
 Photo Frame Market | 2026-2036
Photo Frame Market Size, Share, and Industry Trends Forecast 2026-2036
Photo Frame Market Analysis
CE marking for electronic displays is unwinding competitive access across European distribution channels. Samsung Electronics leverages its semiconductor supply chain to sustain cost advantages in Wi-Fi-enabled digital frames. Aura Home Inc. anchors its position through proprietary cloud-sync software that differentiates user experience from hardware-commoditized rivals.
Photo frames are rigid or flexible display enclosures, typically constructed from engineered wood, extruded aluminum, molded polymer, or tempered glass, designed to protect, present, and enhance visual content for residential, commercial, or institutional display. Wood and metal materials still command premium positioning in gallery and hospitality procurement, though plastic dominates volume production for mass retail. Wall-mounted functionality leads commercial specification, while tabletop and multi-photo configurations concentrate in direct-to-consumer e-commerce channels where assembly and shipping economics favor compact form factors.
FCC certification gates US market entry for digital frames with wireless connectivity, while EU REACH and RoHS frameworks restrict hazardous substances in electronic components and finishes. These regulatory layers elevate compliance costs for smaller manufacturers but simultaneously protect established players with dedicated certification teams. Stakeholders must monitor evolving right-to-repair mandates and extended producer responsibility schemes that could reshape product lifecycle obligations and channel economics.
Market Dynamics
Digital photo frame adoption is compressing replacement cycles for traditional display enclosures while REACH and RoHS frameworks force material transitions across European supply chains. Hospitality procurement teams now specify Wi-Fi-enabled frames as standard in-room amenities, redirecting volume from residential channels.
Growth Catalysts
- EU E-Waste Directives:Extended producer responsibility mandates accelerate frame recycling infrastructure development. Compliance investments by major manufacturers create barrier-to-entry advantages.
- Hospitality Digital Upgrades:Hotels in Germany, France, and Spain deploy cloud-sync displays for guest experience differentiation. In-room technology budgets absorb premium frame specifications.
- Aluminum Extrusion Advances:Precision manufacturing clusters in Guangdong and Zhejiang reduce metal frame production costs. Process improvements enable thinner bezel profiles at mass-market price points.
Market Restraints
- LCD Panel Supply Concentration:Korean and Taiwanese display manufacturers control 85% of small-format screen supply. Digital frame assemblers face allocation volatility during semiconductor cycles.
- Wood Raw Material Costs:Engineered lumber prices fluctuate with construction sector demand swings. Solid wood frame margins compress when resin and veneer input costs spike.
- FCC Certification Burden:Wireless-enabled frames require 6-9 month approval timelines for US market entry. Smaller OEMs lack dedicated regulatory teams to navigate testing protocols.
Strategic Opportunities
- India Mass Retail Expansion:Organized furniture retail chains in Mumbai, Delhi, and Bangalore standardize frame SKUs. Local manufacturing avoids 20-25% import duties on finished goods.
- Healthcare Waiting Room Applications:Hospitals and clinics in Japan adopt digital frames for patient communication. METI energy efficiency standards favor low-power display technologies.
- Subscription Content Models:Cloud platforms bundle curated photography with hardware sales. Recurring revenue offsets hardware commoditization pressure.
Industry Challenges
- Embedded Software Talent Scarcity:Firmware development for cloud-connected frames requires specialized IoT security expertise. Manufacturers compete with automotive and industrial sectors for limited engineering pools.
- Multi-Standard Compliance Complexity:Simultaneous CE marking, FCC Part 15, and GB standard certification extends product launch timelines. Testing costs scale non-linearly with wireless feature integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photo Frame Market |
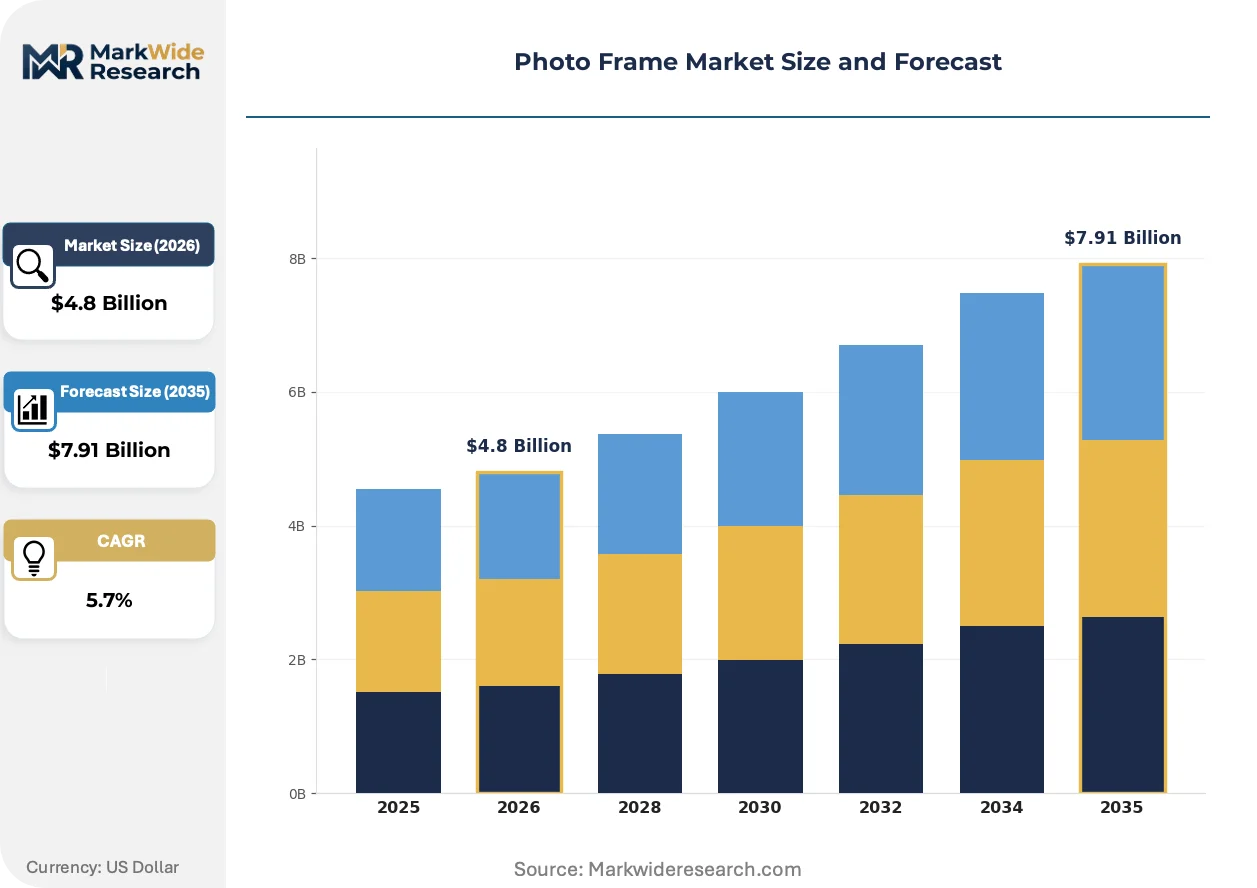
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Wood, Metal, Plastic, Glass Style: Traditional, Modern, Vintage, Rustic Size: 4x6 inches, 5x7 inches, 8x10 inches, 11x14 inches Functionality: Wall-mounted, Tabletop, Multi-photo, Collage |
| Companies Covered | Nixplay, Koninklijke Philips, Samsung Electronics, ViewSonic Corporation, Lenovo Group Ltd., Sony Group Corp., Aura Home Inc., Aluratek Inc., LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photo Frame Market Emerging Trajectories
Edge computing architectures and low-power display drivers are transforming how photo frames process and render visual content. These shifts enable always-on connectivity without tethering to external processing infrastructure.
Micro-LED backlighting is miniaturizing power consumption in digital frames while maintaining daylight visibility. Hospitality procurement teams specify these displays for lobby installations where ambient lighting varies. The technology is compressing total cost of ownership calculations against traditional LCD alternatives.
EU CSRD disclosure requirements now capture scope 3 emissions from frame manufacturers with revenue above threshold limits. Wood sourcing certification and aluminum smelting energy provenance must be documented in sustainability reports. German and French distributors are prioritizing suppliers with verified chain-of-custody documentation.
Direct-to-consumer brands are bypassing wholesale furniture channels through augmented reality preview tools. Buyers in the United States and United Kingdom visualize frame placement via smartphone cameras before purchase. This channel shift is fragmenting traditional retail concentration and compressing brand marketing efficiency ratios.
Photo Frame Market Segmentation
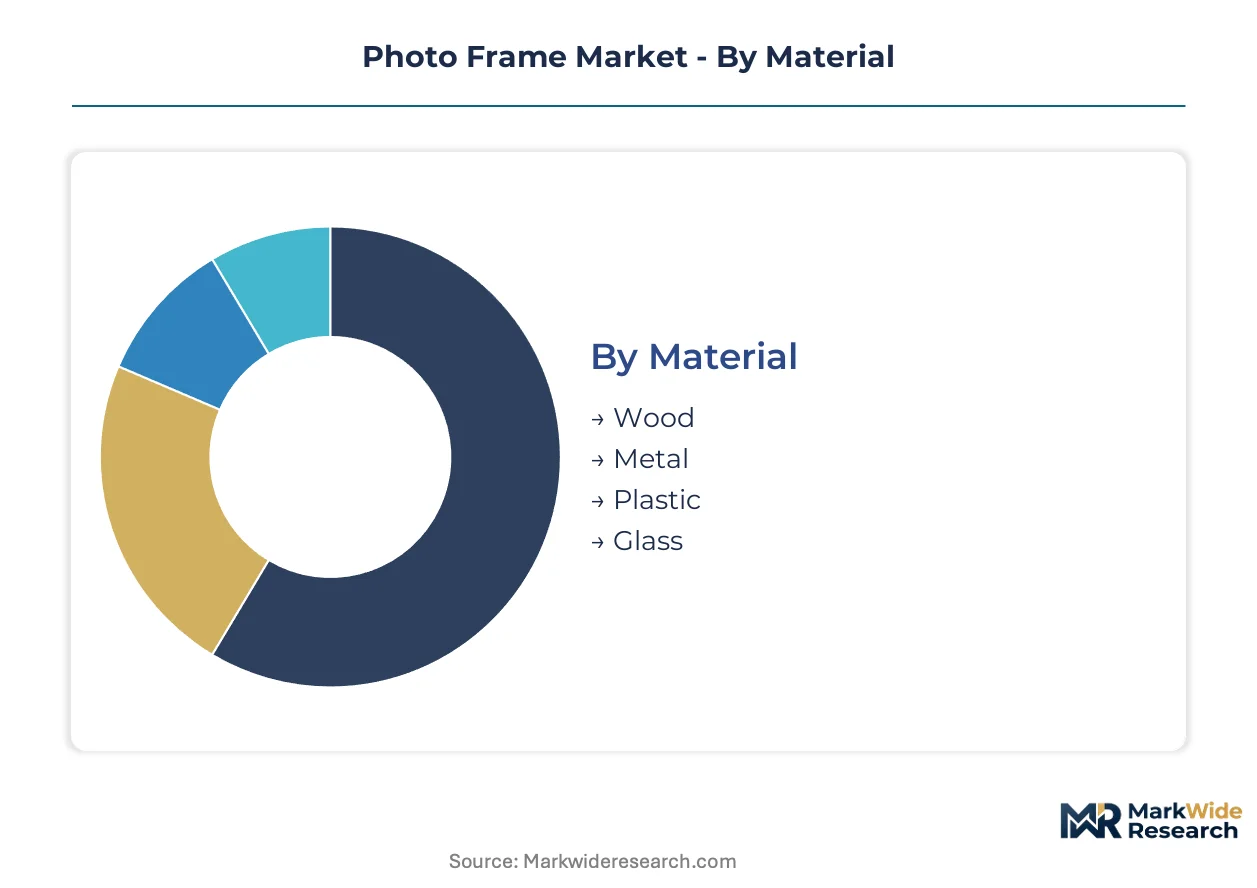
Photo frame segmentation reveals how material specifications, aesthetic positioning, and functional design interact with regulatory frameworks and procurement economics. Manufacturers align production configurations with distinct compliance burdens and end-use durability requirements across residential, commercial, and hospitality channels.
Material:
REACH and RoHS frameworks impose substance restrictions that fragment compliance costs across material categories, with electronic-enabled frames facing layered certification demands that traditional enclosures avoid.
- Wood:Engineered lumber and solid hardwood constructions dominate gallery and premium hospitality procurement. REACH documentation requirements for treated finishes and adhesive resins concentrate demand in FSC-certified supply chains serving German and French distributors.
- Metal:Extruded aluminum and steel frames leverage precision manufacturing clusters in Guangdong and Zhejiang. Thin bezel profiles from these regions penetrate mass retail in India and Brazil, though EU carbon border adjustment mechanisms threaten cost advantages for energy-intensive smelting.
- Plastic:Molded polymer dominates volume production for direct-to-consumer e-commerce. RoHS restrictions on flame retardants and plasticizers elevate testing costs for European-bound shipments.
- Glass:Tempered glass and acrylic glazing protect display contents in high-traffic commercial installations. Shatter-resistance specifications from Japan's METI influence procurement standards for healthcare waiting room applications.
Established volume favors Plastic; emerging adoption favors Metal.
Style:
Style positioning determines margin architecture, with heritage aesthetics commanding wholesale premiums and minimalist designs scaling through digital-native retail channels.
- Traditional:Ornate molding and classic proportions anchor museum and hospitality procurement. Italian and Spanish manufacturers maintain design leadership through artisan finishing techniques that resist offshore replication.
- Modern:Clean lines and neutral palettes align with Scandinavian and Japanese interior design trends. Direct-to-consumer brands in the United Kingdom and United States deploy augmented reality tools to reduce return rates for this category.
- Vintage:Distressed finishes and period-appropriate hardware serve specialty retail and boutique hospitality. Small-batch production in Portugal and Mexico supplies European and North American channels.
- Rustic:Reclaimed wood and industrial metal combinations target cabin and lodge aesthetics in Colorado, Alberta, and the Scottish Highlands. Local sourcing requirements complicate export scaling.
Modern styling gains share fastest in digital channels; Traditional retains procurement dominance in contract specification.
Size:
Dimensional segmentation maps directly to shipping economics and assembly labor, with compact formats concentrating in e-commerce and oversized formats requiring white-glove logistics.
- 4x6 inches:Compact tabletop formats dominate impulse retail and gift market volume. Standardized dimensions enable efficient containerization from Chinese manufacturing clusters to European distribution hubs.
- 5x7 inches:Mid-size configurations balance portability with visual impact. This format leads subscription box and corporate gifting programs in the United States and Canada.
- 8x10 inches:Gallery-standard dimensions command premium positioning in professional photography retail. Framers in Paris, New York, and Tokyo specify conservation-grade mounting for this size tier.
- 11x14 inches:Oversized formats require reinforced backing and specialized glazing. Hospitality procurement in Dubai and Singapore specifies these dimensions for lobby and corridor installations.
4x6 inches captures highest unit volume; 8x10 inches delivers strongest margin per unit.
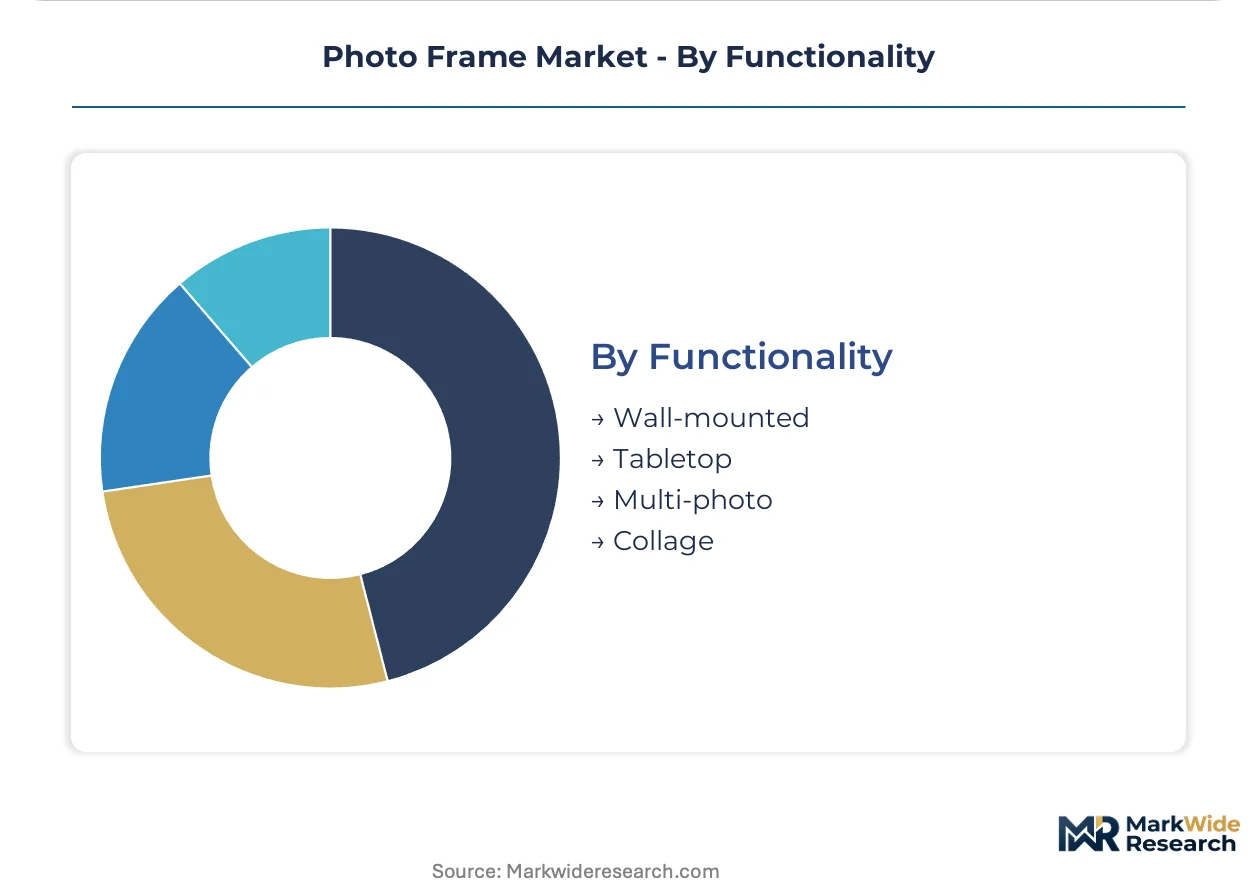
Functionality:
Functional design determines installation labor requirements and technology integration pathways, with wall-mounted and digital-enabled formats diverging in supply chain configuration.
- Wall-mounted:Vertical and horizontal hanging systems dominate commercial specification. German and French distributors require CE-marked hardware kits for liability coverage in public installations.
- Tabletop:Easel-back and freestanding designs concentrate in residential e-commerce. Compact form factors minimize dimensional weight charges for cross-border shipping from Shenzhen to Los Angeles and Rotterdam.
- Multi-photo:Integrated matting and divided glazing serve family portrait and event photography markets. Custom cutting capabilities in Vietnam and Indonesia supply North American seasonal demand peaks.
- Collage:Asymmetrical and grid-based arrangements target younger demographics through social commerce. Rapid style turnover pressures inventory management for dropship models.
Wall-mounted functionality anchors commercial procurement; Tabletop formats scale fastest through direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance and extended producer responsibility mandates are redirecting manufacturing investment toward certified supply chains in Europe and Asia. Digital frame penetration rates diverge sharply between hospitality-heavy urban corridors and residential markets where traditional enclosures retain volume dominance.
United States
Hospitality procurement teams in New York, Los Angeles, and Miami specify Wi-Fi-enabled frames as standard guest amenities. FCC Part 15 certification requirements extend product launch timelines for wireless-enabled imports from Shenzhen and Dongguan clusters. Georgia and Tennessee distribution hubs consolidate inbound container volume for North American wholesale channels.
Germany
Gallery and museum procurement in Berlin, Munich, and Hamburg maintains premium positioning for engineered wood and aluminum constructions. ECHA enforcement of REACH substance restrictions elevates documentation costs for Asian exporters serving Frankfurt and Düsseldorf trade hubs. Bavarian framing cooperatives source FSC-certified hardwoods through verified chain-of-custody networks.
China
Guangdong and Zhejiang manufacturing clusters supply 70% of global aluminum extrusion frame volume through precision processing advances. MIIT energy efficiency standards for electronic displays accelerate domestic adoption of low-power digital alternatives. Shanghai and Beijing hospitality operators deploy cloud-sync frames for guest experience differentiation in premium properties.
Japan
Healthcare waiting room applications in Tokyo, Osaka, and Nagoya drive demand for METI-compliant low-power display technologies. JIS standards for shatter-resistant glazing influence procurement specifications for high-traffic commercial installations. Kyoto and Nara artisan workshops maintain heritage finishing techniques for traditional wooden frame exports.
India
Organized furniture retail chains in Mumbai, Delhi-NCR, and Bangalore standardize frame SKUs for mass-market penetration. BIS certification requirements for imported electronics create compliance barriers for unbranded digital frame entrants. Gujarat and Maharashtra manufacturing zones develop local extrusion capacity to circumvent 20-25% import duties on finished metal goods.
Photo Frame Market Vendor Landscape
Player mix skews toward diversified electronics conglomerates with captive semiconductor supply chains and specialized digital frame pure-plays with cloud-software differentiation. Market structure concentrates around three tiers: premium hospitality specification, mass-market retail volume, and direct-to-consumer subscription bundling. Strategic archetypes include semiconductor-integrated hardware assemblers, proprietary platform operators, and contract manufacturing specialists. Competitive moves center on vertical integration into display panel sourcing and geographic expansion through hospitality channel partnerships.
Within the diversified electronics tier, Samsung Electronics Co., Ltd. and LG Electronics Inc. exemplify semiconductor-captive positioning that sustains cost advantages in Wi-Fi-enabled segments. Aura Home Inc. occupies the pure-play software-differentiation vector through proprietary cloud-sync architecture. Koninklijke Philips N.V. represents legacy brand leverage transitioning toward connected home ecosystems. These three anchors illustrate how competitive positioning fragments across hardware integration depth, software platform ownership, and brand heritage conversion.
| Leading Market Players |
|---|
| Nixplay |
| Koninklijke Philips |
| Samsung Electronics |
| ViewSonic Corporation |
| Lenovo Group Ltd. |
| Sony Group Corp. |
| Aura Home Inc. |
| Aluratek Inc. |
| LG Electronics |
| Others |
Supply Flow & Price Mechanics
Aluminum extrusion replacing engineered wood in mid-tier hospitality procurement simultaneously shifts sourcing toward Guangdong manufacturing clusters and compresses margin premiums previously commanded by solid wood certifications. REACH documentation burdens for treated timber finishes elevate landed costs for European-bound shipments, while precision metal processing advances enable thinner bezel profiles at mass-market price points that undercut traditional frame economics.
Pricing Analysis
Certification level creates the primary spread between premium gallery specification and mass retail volume. CE-marked hardware kits for wall-mounted commercial installations command wholesale premiums over uncertified alternatives, while FCC Part 15 certification for Wi-Fi-enabled digital frames extends approval timelines and elevates compliance costs that concentrate among smaller OEMs. Price differentiation stratifies across FSC-certified wood, extruded aluminum with documented carbon provenance, and RoHS-compliant polymer grades. Cost compression in plastic tabletop formats is intensifying because direct-to-consumer brands bypass wholesale furniture channels through augmented reality preview tools. Hospitality procurement teams demonstrate lowest price sensitivity due to in-room technology budgets, while mass retail buyers in India and Brazil concentrate volume at economy tiers.
Supply Chain Analysis
China anchors global aluminum extrusion frame production through precision manufacturing clusters in Guangdong and Zhejiang that supply 70% of worldwide volume. Taiwan and South Korea control small-format LCD panel supply that digital frame assemblers draw from, creating allocation volatility during semiconductor cycles. Raw material dependencies center on engineered lumber from certified forestry operations, aluminum billet from energy-intensive smelting, and semiconductor-grade display substrates. Single-source vulnerability concentrates in Korean and Taiwanese display manufacturers that command 85% of relevant screen supply. Distribution runs through Georgia and Tennessee hubs for North American wholesale, with Rotterdam and Hamburg consolidating European inbound volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospitality procurement consolidation around cloud-sync frame specifications is shifting buyer power toward chain operators with standardized in-room technology budgets. This concentration fragments negotiating leverage for traditional frame manufacturers dependent on fragmented residential channels.
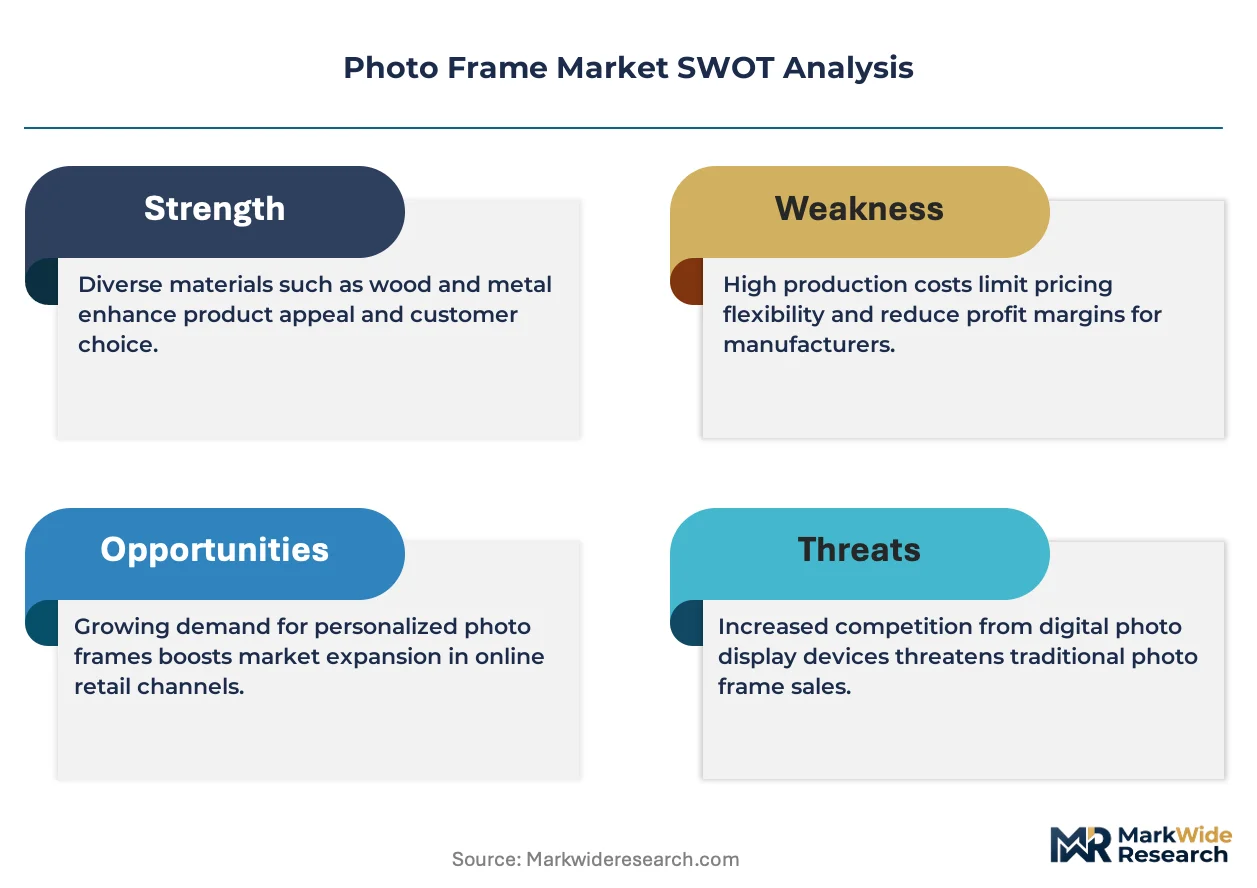
For Market Incumbents: Compound cloud-platform ownership through proprietary sync architecture that differentiates from hardware-commoditized rivals. Samsung Electronics and LG Electronics should deepen captive semiconductor supply advantages against pure-play software competitors. Aura Home Inc. must defend its cloud-sync differentiation through firmware security investments that address embedded software talent scarcity threatening IoT development timelines. Certification team scale creates barrier-to-entry protection against smaller OEMs lacking dedicated regulatory navigation capabilities.
For New Entrants and Emerging Players: Lead with healthcare waiting room applications in Japan where METI energy efficiency standards favor low-power display technologies and procurement specifications remain underpenetrated by established hospitality-focused brands. Target India mass retail expansion through local manufacturing in Gujarat and Maharashtra that circumvents 20-25% import duties on finished metal goods. Deploy subscription content bundling with curated photography to offset hardware commoditization pressure through recurring revenue models.
For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors semiconductor-integrated hardware assemblers with captive display panel sourcing over pure-play software operators vulnerable to platform commoditization. Long-term viability over the next decade hinges on vertical integration depth into cloud infrastructure and hospitality channel partnerships. Acquisition targets should demonstrate established certification teams for multi-standard compliance and proven hospitality procurement relationships. Watch for inflection signals in right-to-repair mandate enforcement that could reshape product lifecycle obligations and channel economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | Proprietary sync software differentiates Aura Home from hardware-commoditized Samsung and LG offerings. |
| Backward Integration into Display Panels | Captive LCD supply from Korean and Taiwanese manufacturers insulates assemblers against allocation volatility. |
| CE Marking Investment | Certification teams protect European market access against REACH and RoHS substance restriction enforcement. |
| Hospitality Channel Partnership | Direct relationships with German, French, and Spanish hotel chains secure premium in-room technology budgets. |
| Local Manufacturing in India | Gujarat and Maharashtra extrusion capacity avoids BIS certification barriers and import duty burdens. |
Methodological Framework
Initial hypotheses were tested against primary input from hospitality procurement managers, gallery framing specialists, electronics manufacturing executives, and retail category buyers, then refined through secondary validation. Primary interviews captured specification trends in Berlin, New York, and Shanghai hospitality markets alongside sourcing decisions in Mumbai and Bangalore organized retail. Secondary sources included FCC equipment authorization databases, ECHA REACH registration dossiers, MIIT energy efficiency filings, and customs records from Guangdong export clusters. Bottom-up volume estimates from manufacturing clusters triangulated against top-down hospitality technology spending analysis.
Variance decomposition across material, style, size, and functionality segments structured the analytical framework over the projection horizon. Modeled dimensions included wood certification grade, metal extrusion precision tier, digital connectivity specification, and regional regulatory cluster. CAGRs derived from segment-level growth trajectories weighted by procurement channel concentration. Industry-specific inputs incorporated LCD panel supply allocation cycles, engineered lumber price correlation with construction sector demand, and cloud-platform subscription attach rates.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor supply normalization, stable REACH enforcement patterns, and continued hospitality digital upgrade budgets would require recalibration. Forecasts reflect documented assumptions regarding certification timeline stability and display technology substitution rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Products & Utilities
Mosquito Screen Doors Market
Home Products & Utilities
Europe Aromatherapy Diffuser Market
Home Products & Utilities
Wine Cabinets Market
Home Products & Utilities
North America Aromatherapy Diffuser Market
Home Products & Utilities
Middle East and Africa Aromatherapy Diffuser Market
Home Products & Utilities
Global Stair Lifts Market
Home Products & Utilities
Netherlands Sustainable Mattress Market
Home Products & Utilities
Storage Basket Rack Market
Home Products & Utilities
Windows Market
Home Products & Utilities
US Aromatherapy Diffusers Market