
 Event Services Market | 2026-2036
Event Services Market Size, Share, and Industry Trends Forecast 2026-2036
Event Services Market Foresight
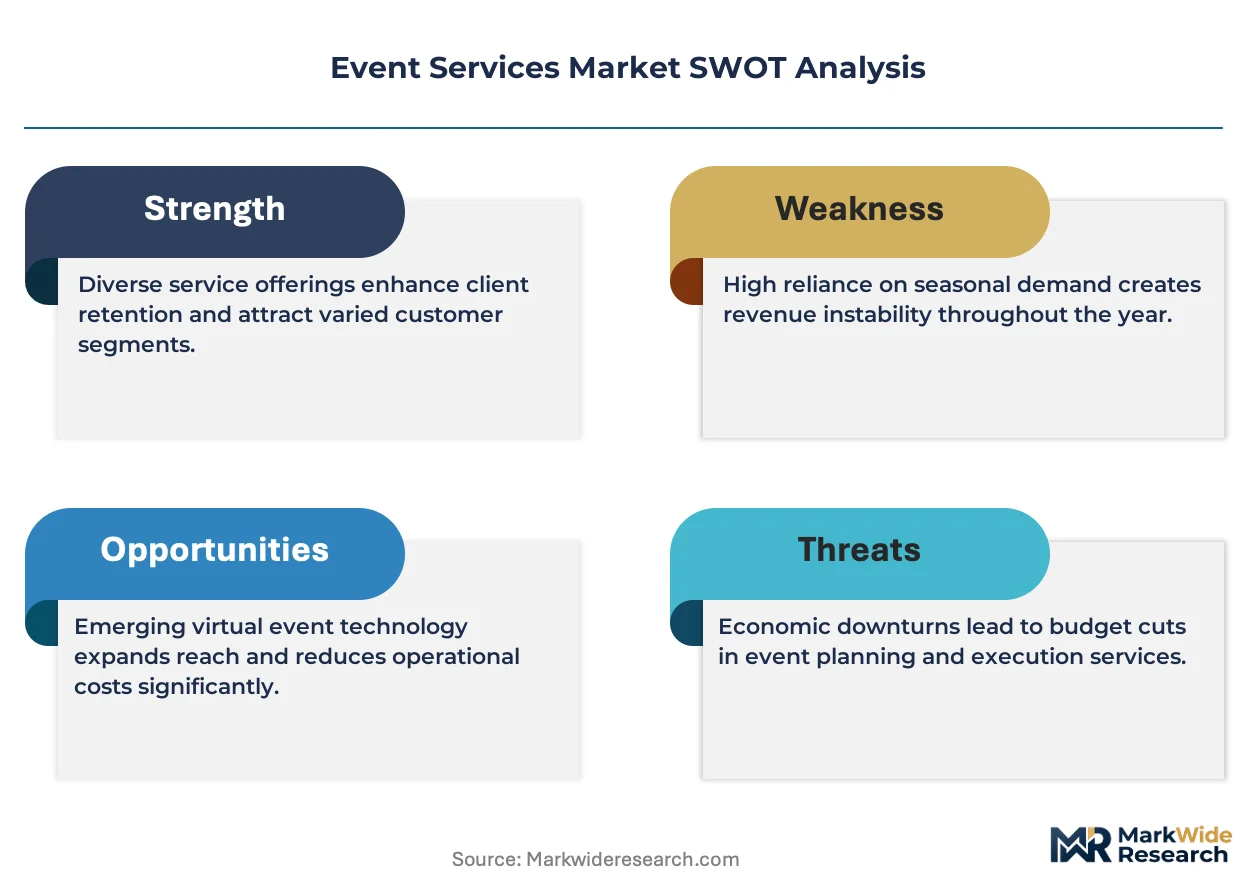
Buyer concentration among Fortune 500 corporations is realigning procurement toward integrated event management partners. Freeman leverages its end-to-end production capabilities to anchor large-scale convention contracts. Cvent competes through proprietary registration and venue-sourcing technology that sustains recurring enterprise relationships.
Event services encompass the strategic design, logistical coordination, and technical execution of live, hybrid, and virtual gatherings, requiring real-time bandwidth allocation above 50 Mbps for seamless streaming and on-site digital interaction. These services drive brand activation, knowledge transfer, and community formation across commercial and institutional contexts. Catering and audio-visual services command the deepest margin pools due to equipment depreciation cycles and perishable supply chains. Virtual platforms within the technology segment represent the fastest-expanding category as organizations retain distributed attendance models.
FDA guidelines on food safety, EPA standards for temporary power generation, and GDPR data-processing requirements collectively elevate compliance costs for multi-jurisdictional programs. Eventbrite navigates these frameworks through automated consent workflows, while Encore Global positions its technical operations to meet varying municipal fire and electrical codes. Stakeholders must weigh capital allocation between physical production assets and cloud-native delivery infrastructure as regulatory fragmentation intensifies.
Market Dynamics
Hybrid event formats are compressing demand for pure-play physical production while expanding requirements for integrated digital-physical service bundles. This structural shift is reallocating capital toward cloud-native delivery infrastructure and real-time bandwidth provisioning.
Growth Catalysts
- GDPR and EU AI Act compliance frameworks:European data governance mandates are driving replacement cycles for legacy attendee management systems. Event operators must deploy consent-automation tools to retain corporate contracts.
- Experiential marketing budgets:Fortune 500 brand activation teams are consolidating spend with end-to-end production partners capable of simultaneous physical and virtual execution.
- India wedding and conference demand:Cultural event density in Mumbai, Delhi, and Bangalore is generating volume concentration unmatched by mature markets.
Market Restraints
- Audio-visual equipment depreciation cycles:LED wall and broadcast camera refresh rates compress margin recovery windows for rental operators.
- Catering supply chain perishability:Food waste liability and FSSAI traceability requirements in India elevate working capital intensity.
- Multi-jurisdictional regulatory fragmentation:EPA temporary power standards, FDA food safety protocols, and municipal fire codes create compliance stacking costs for cross-border programs.
Strategic Opportunities
- Underpenetrated tier-2 Indian cities:Jaipur, Kochi, and Chandigarh lack integrated event infrastructure despite rising corporate and social event density.
- Carbon accounting integration:EU CSRD disclosure requirements are creating demand for emissions-tracking services embedded in event logistics.
- AI-powered personalization engines:Convergence of recommendation algorithms with registration data is enabling dynamic agenda curation for hybrid audiences.
Industry Challenges
- Broadcast engineering talent scarcity:Real-time streaming production requires specialized skills in latency optimization and multi-camera switching that outpace vocational training pipelines.
- Legacy venue integration friction:Historic properties in European capitals lack fiber infrastructure for 50 Mbps+ streaming requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Event Services Market |
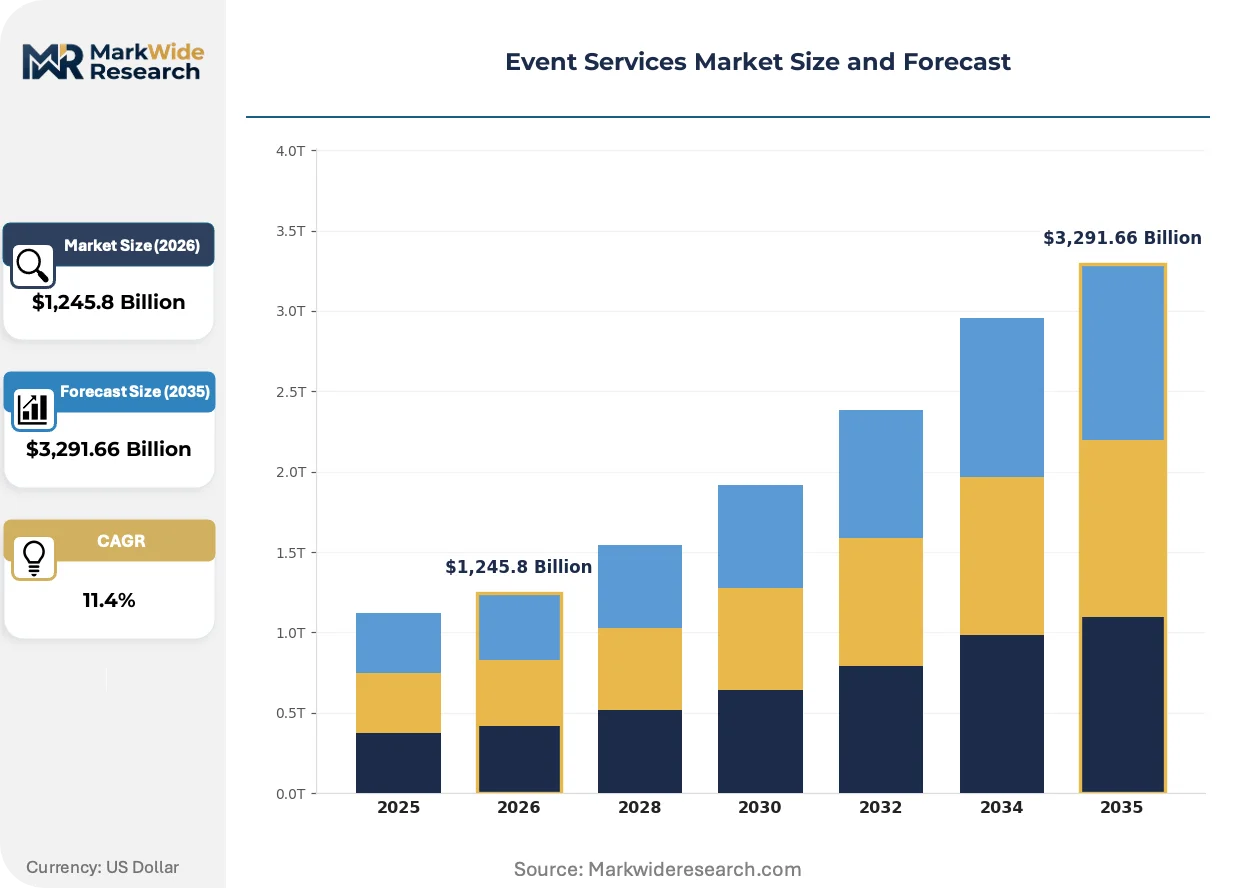
| Market Size in 2026 | $1,245.8 Billion |
| Market Size in 2035 | $3,291.66 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Event Planning, Audio-Visual Services, Catering, Decoration Customer Type: Corporations, Non-Profits, Individuals, Government Event Type: Conferences, Weddings, Trade Shows, Festivals Technology: Virtual Platforms, Registration Software, Streaming Services, Event Apps |
| Companies Covered | Freeman, BCD Meetings & Events, Cvent, GL Events, ATPI Ltd, Jack Morton Worldwide, George P. Johnson Experience Marketing, Encore Global, Eventbrite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Event Services Market Shifts & Advancements
Immersive technologies and sustainability mandates are rewriting service specifications across live, hybrid, and virtual formats. Providers must now synchronize physical production with carbon accounting and AI-driven personalization.
Spatial computing and extended reality platforms are rewriting how corporate clients design brand activations. Pharmaceutical and technology sectors are deploying AR-enabled product demonstrations at medical congresses and developer conferences. This compression of physical footprint requirements is reducing venue rental costs while expanding audience reach through simultaneous virtual access.
EU AI Act risk classification rules are reshaping data handling for attendee facial recognition and sentiment analysis tools. Event technology vendors must now document algorithmic transparency and human oversight protocols. High-stakes pharmaceutical congresses in Frankfurt and Barcelona are delaying AI feature rollouts pending compliance verification.
Enterprise procurement teams are consolidating vendor relationships around integrated service partners rather than specialized subcontractors. Single-source accountability for catering, AV, and digital delivery is displacing fragmented supplier panels. This concentration is most visible in North American technology sector events, where procurement officers prioritize risk transfer over cost optimization.
Event Services Market Segmentation
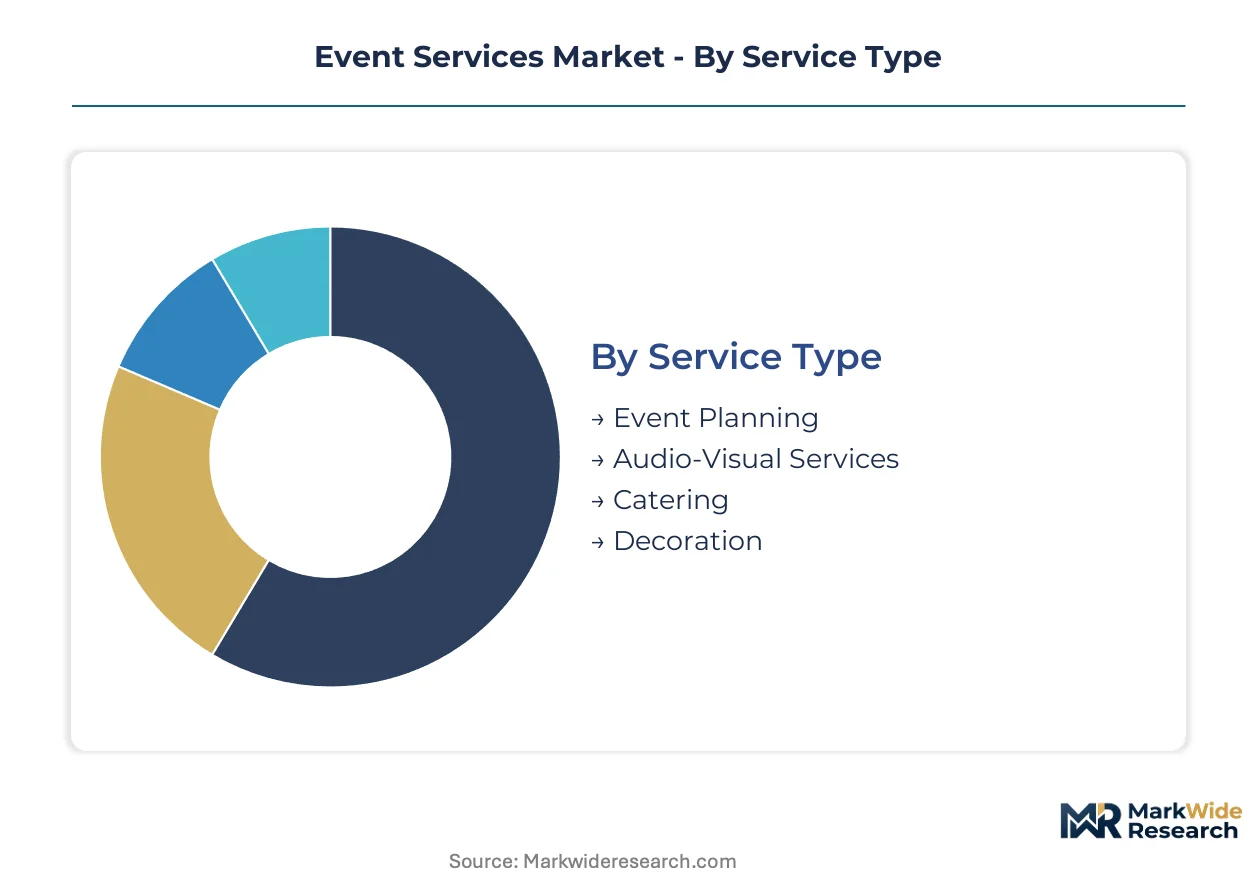
Event services fragmentation demands precise segment targeting. Capital allocation, regulatory exposure, and margin profiles diverge sharply across service lines and customer categories. Procurement teams prioritize integrated partners in high-spend verticals.
Service Type:
Audio-visual services and catering command the heaviest equipment and inventory investments. LED wall depreciation cycles and perishable supply chains compress return windows.
- Audio-Visual Services:LED walls, broadcast cameras, and latency-optimized streaming infrastructure require continuous refresh cycles. Demand concentrates in pharmaceutical congresses across Frankfurt and Barcelona where FDA and EMA compliance documentation drives specification rigor.
- Catering:Perishable inventory and FSSAI traceability mandates in India elevate working capital intensity. Wedding banquets in Mumbai and Delhi generate volume concentration unmatched by corporate accounts.
- Event Planning:Strategic design and vendor orchestration with lower fixed asset requirements.
- Decoration:Floral and scenic fabrication with seasonal demand spikes and compressed setup windows.
Most installed capacity flows through Audio-Visual Services. Expansion is steepest in Catering.
Customer Type:
Corporations and government clients impose the most stringent procurement and compliance standards. Contract duration and payment security vary dramatically by buyer category.
- Corporations:Fortune 500 brand activation teams consolidate spend with end-to-end production partners. Hybrid format requirements in North American technology sector events prioritize risk transfer over cost optimization.
- Government:Municipal and federal programs require adherence to EPA temporary power standards and municipal fire codes across multiple jurisdictions. Procurement cycles run longer but offer payment security.
- Non-Profits:Budget-constrained programming with donor accountability requirements.
- Individuals:Wedding and social event hosts with high personalization demands and fragmented vendor selection.
Contract value peaks with Government accounts. Volume expansion runs fastest among Corporations.
Event Type:
Conferences and weddings generate divergent infrastructure requirements. Technical complexity versus cultural density shapes service provider selection.
- Conferences:Multi-day knowledge transfer programming with simultaneous physical and virtual execution. GDPR consent-automation tools and EU AI Act compliance verification delay feature rollouts in Frankfurt and Barcelona pharmaceutical congresses.
- Weddings:Cultural event density in Mumbai, Delhi, and Bangalore drives substantial volume. FSSAI traceability requirements and perishable supply chain management dominate operational planning.
- Trade Shows:Exhibition floor logistics with compressed build and dismantle schedules.
- Festivals:Outdoor temporary infrastructure with weather contingency and crowd safety protocols.
Revenue concentration sits with Conferences. Share gains are climbing the fastest in Weddings.
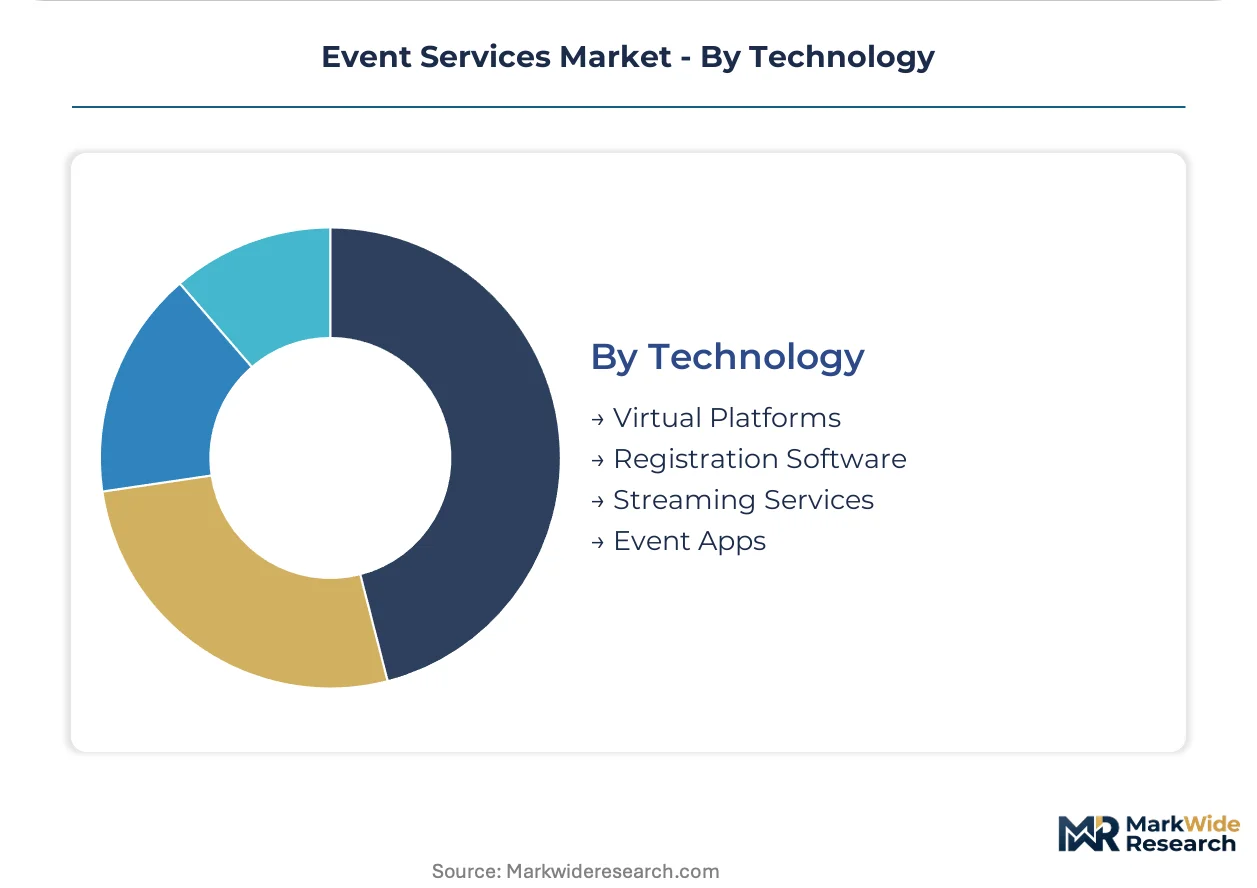
Technology:
Virtual platforms and streaming services require cloud-native infrastructure investment. Legacy venue fiber limitations create deployment friction.
- Virtual Platforms:Cloud-native delivery infrastructure with real-time bandwidth provisioning above 50 Mbps. EU AI Act risk classification rules reshape data handling for facial recognition and sentiment analysis tools.
- Streaming Services:Latency optimization and multi-camera switching with broadcast engineering talent scarcity outpacing vocational training pipelines. Historic European venue properties lack fiber infrastructure for seamless deployment.
- Registration Software:Attendee data management with GDPR consent-automation requirements.
- Event Apps:Mobile-first engagement with AI-powered personalization engine integration.
Deployment scale favors Virtual Platforms. Technology budgets are shifting most aggressively toward Streaming Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's wedding-driven volume concentration contrasts sharply with Germany's compliance-heavy pharmaceutical congress circuit, revealing how cultural density and regulatory stringency shape divergent growth trajectories across national markets.
United States
Fortune 500 technology sector events in Seattle and Austin drive hybrid format adoption with integrated physical-virtual execution requirements. EPA temporary power standards and OSHA workplace safety protocols elevate compliance costs for multi-city programs. Corporate procurement teams in Silicon Valley prioritize risk transfer over cost optimization when selecting end-to-end production partners.
Germany
Frankfurt and Munich anchor Europe's pharmaceutical congress circuit where EMA documentation requirements and EU AI Act risk classification rules delay technology feature rollouts. GDPR consent-automation tools are becoming mandatory for attendee management systems. LED wall and broadcast camera depreciation cycles compress margin recovery windows for Frankfurt-based AV rental operators.
India
Wedding banquets in Mumbai, Delhi, and Bangalore generate volume concentration unmatched by corporate accounts, with FSSAI traceability mandates elevating catering supply chain complexity. Tier-2 cities including Jaipur, Kochi, and Chandigarh lack integrated event infrastructure despite rising corporate event density. The country's central bank regulatory framework shapes payment security expectations for government procurement cycles.
United Kingdom
London's financial services sector drives demand for secure hybrid shareholder meetings and regulatory disclosure events. Historic venue properties in Westminster and the City of London lack fiber infrastructure for 50 Mbps+ streaming requirements. The national data protection authority enforces GDPR-aligned consent protocols for facial recognition deployments at high-profile gatherings.
United Arab Emirates
Dubai's exhibition and conference infrastructure attracts pharmaceutical and luxury brand activations requiring simultaneous regional and virtual audience reach. Municipal fire codes and temporary power standards create compliance stacking costs for cross-border programs originating in European or North American headquarters. Expo City Dubai exemplifies integrated digital-physical venue design for hybrid format execution.
Event Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service categories, producing a bifurcated structure where scale-driven end-to-end providers anchor Fortune 500 contracts while niche operators capture high-margin specialty segments. Audio-visual services and catering command the deepest margin pools due to equipment depreciation cycles and perishable supply chains. Three archetypes dominate: integrated production partners with captive technical infrastructure, cloud-native technology platforms with recurring SaaS revenue, and specialized catering operators with regional culinary expertise. Competitive moves concentrate on strategic partnerships for geographic expansion and portfolio diversification into carbon accounting services.
Within the integrated production tier, Freeman and Encore Global occupy positions exemplifying end-to-end physical-digital execution capabilities. Cvent represents the cloud-native platform archetype with proprietary registration and venue-sourcing technology sustaining enterprise relationships. These three companies illustrate how service bundling and technology integration separate market leaders from fragmented regional subcontractors.
| Leading Market Players |
|---|
| Freeman |
| BCD Meetings & Events |
| Cvent |
| GL Events |
| ATPI Ltd |
| Jack Morton Worldwide |
| George P. Johnson Experience Marketing |
| Encore Global |
| Eventbrite |
| Others |
Supply & Pricing Matrix
LED panel spot prices in South Korea cascade through three-tier pricing structures across premium, standard, and economy levels as event production firms pass component volatility through to corporate procurement teams. Tier-1 AV rental operators in Frankfurt and Mumbai absorb depreciation risk through captive maintenance contracts while tier-3 subcontractors compete on spot-market catering labor.
Pricing Analysis
Capacity additions in India's tier-2 cities are reshaping price floors for integrated wedding packages as Jaipur and Kochi venues undercut Mumbai-Delhi benchmarks. Project-based pricing dominates corporate accounts with Fortune 500 technology sector events in Seattle and Austin prioritizing risk transfer over cost optimization. Price differentiation hinges on GDPR consent-automation certification and real-time bandwidth provisioning above 50 Mbps. Cost compression in standard-tier catering stems from FSSAI traceability compliance overhead, while government procurement cycles in Germany offer payment security at compressed margins.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical congress organizers in Frankfurt and Barcelona mandate qualified backup AV operators for LED wall and broadcast camera fleets. Supply concentrates in Germany, India, and the United Arab Emirates for exhibition infrastructure. Raw material dependencies span South Korean LED components, Dutch floral supply chains for decoration, and Indian perishable catering networks. Single-source vulnerability runs through specialized broadcast engineering talent pools. Distribution runs through venue-embedded service partnerships rather than open subcontractor markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in event services rests on cloud-native infrastructure substitution for depreciating physical assets and premium-tier carbon accounting bundling for EU CSRD compliance.
For Market Incumbents: Lock in multi-year enterprise contracts with GDPR-compliant attendee management systems before EU AI Act risk classification rules harden procurement specifications. Deepen backward integration into LED wall maintenance depots in Frankfurt and Mumbai to compress third-party rental margins. Defend against pure-play virtual platform entrants by embedding AI-powered personalization engines within existing registration software relationships. For New Entrants and Emerging Players: EU AI Act risk classification rules in Germany open a window for algorithmic transparency consulting services attached to pharmaceutical congress technology rollouts. Target tier-2 Indian cities including Chandigarh and Kochi with modular catering and AV bundles that replicate Mumbai infrastructure at lower fixed cost. Lead with carbon accounting integration as the go-to-market wedge for EU-headquartered corporate accounts facing CSRD disclosure mandates. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native registration platforms possessing GDPR consent-automation toolkits and recurring SaaS revenue architecture. Long-term viability favors providers that bridge physical production assets with virtual delivery infrastructure rather than pure-play legacy operators. Watch for inflection signals in pharmaceutical congress AI feature rollout delays as compliance verification bottlenecks clear.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Accounting Integration | EU CSRD disclosure requirements create attach-rate expansion for logistics providers serving Frankfurt pharmaceutical congresses. |
| AI-Powered Personalization Engine | Recommendation algorithm convergence with registration data enables dynamic agenda curation for hybrid audiences in North American technology sector events. |
| Dual-Sourcing Qualification Program | Backup operator certification for LED wall and broadcast camera fleets reduces cancellation risk for high-stakes pharmaceutical congresses in Barcelona. |
| Tier-2 City Infrastructure Deployment | Modular service bundling in Jaipur and Chandigarh captures rising corporate event density without Mumbai-tier fixed asset commitments. |
| GDPR Consent-Automation Tool | Automated data handling protocols secure renewal cycles for legacy attendee management system replacements across European markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with event production executives, corporate procurement officers, venue operations managers, and broadcast engineering specialists with secondary validation against SEC filings from publicly traded service providers, EMA regulatory submission databases, FSSAI compliance records, and customs data for LED panel and broadcast camera imports. Bottom-up segment sizing and top-down macro anchoring were triangulated to constrain variance.
Comparable-period anchoring tied projection assumptions to historical hybrid format adoption curves and experiential marketing budget trajectories across the analysis window. Segmentation dimensions modeled include service type, customer category, event format, technology deployment, and regional regulatory cluster. CAGRs were derived from installed capacity utilization rates and replacement cycle timing for AV equipment. Industry-specific inputs incorporated GDPR consent-automation deployment timelines and FSSAI traceability mandate compliance costs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU AI Act enforcement acceleration or sudden bandwidth infrastructure investment delays in historic European venue properties. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Festivals
Online Event Ticketing Market
Events and Festivals
Asia-Pacific K-Pop Events Market
Events and Festivals
Music Fountain Market
Events and Festivals
Events and Exhibition Market
Events and Festivals
India Event Services Market
Events and Festivals
Professional Speaker Market
Events and Festivals
Photo Booth Market
Events and Festivals
UK Arts Promoter Market
Events and Festivals
Event Photography Service Market
Events and Festivals
Global Escape Room Market
Events and Festivals
Corporate Luxury Events Market
Events and Festivals
Europe K-Pop Events Market
Events and Festivals
Sports Events Tickets Market
Events and Festivals
Global Live Event Ticketing Market
Events and Festivals
Global Family Entertainment Center Market
Events and Festivals
India Event and Exhibition Market