
 Global Exhibition Market | 2026-2036
Global Exhibition Market Size, Share, and Industry Trends Forecast 2026-2036
Global Exhibition Market Analysis
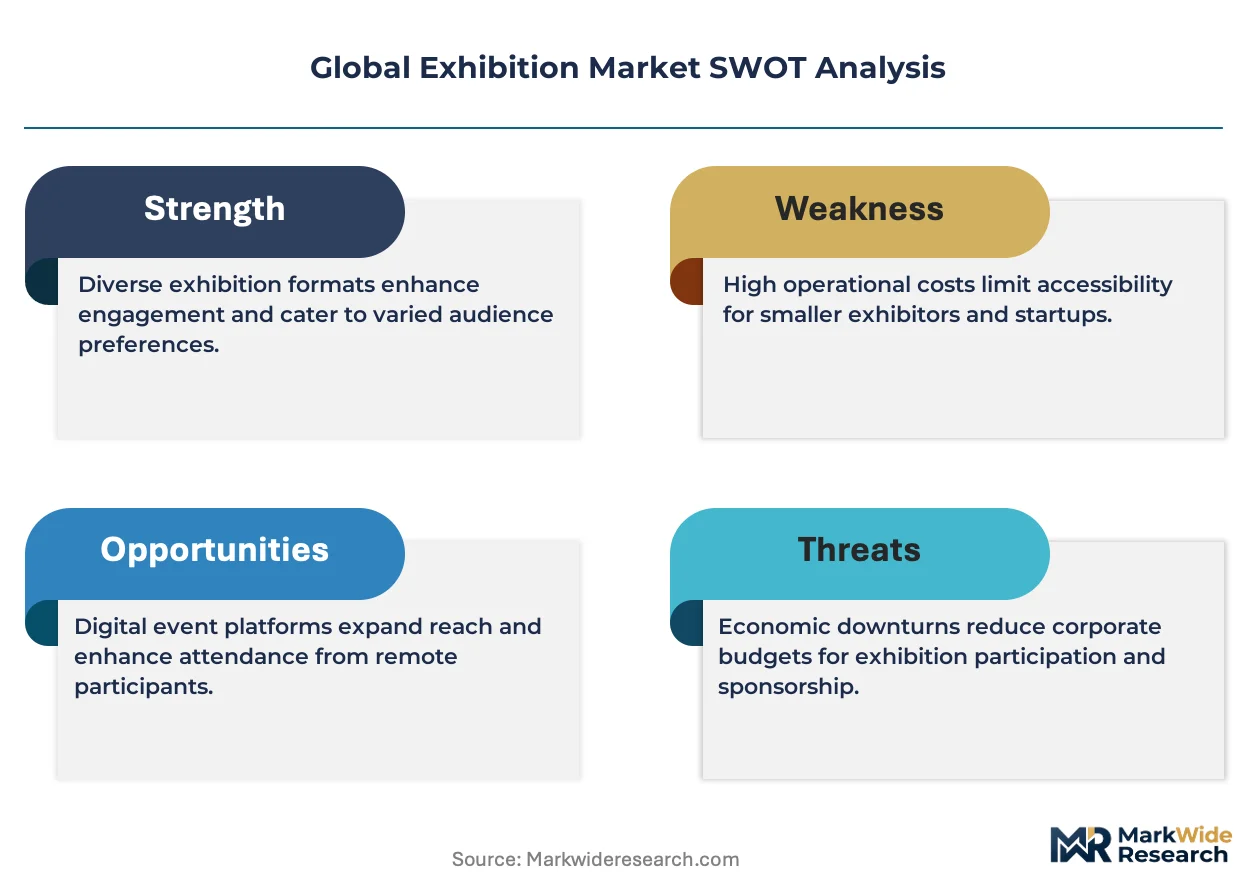
Hybrid event subscription tiers is recalibrating what organizers monetize beyond physical floor space. Informa leverages integrated digital platforms to extend audience reach across year-round engagement cycles. Messe München anchors premium manufacturing expos through its captive venue ownership in Bavaria. RX differentiates via healthcare sector specialization, controlling major medical congress circuits across Asia-Pacific and Middle Eastern host cities.
The global exhibition industry encompasses temporary, purpose-built gatherings where exhibitors deploy physical booths, digital interfaces, and live demonstrations to facilitate B2B commerce, knowledge transfer, and brand visibility within defined venue footprints. Trade shows command the largest revenue pools within event type segmentation, while conferences exhibit the fastest trajectory as knowledge-as-product formats proliferate. Corporations dominate exhibitor type composition, though startup participation is accelerating as incubation-focused pavilions expand. Technology verticals capture disproportionate marketing spend within industry vertical segmentation, reflecting SaaS vendor concentration and product refresh cycles.
FDA guidelines on healthcare congress transparency shape pharmaceutical exhibitor compliance costs and disclosure protocols at US-based medical events. EMA parallel requirements across EU member states create dual-burden registration frameworks for pan-European life sciences exhibitions. ISO 20121 sustainable event management standards increasingly gate venue selection for multinational corporate procurement teams. Stakeholders must monitor how carbon accounting rules reshape location decisions and supplier qualification criteria.
Market Dynamics
Hybrid event infrastructure is reconfiguring revenue architecture across the exhibition value chain, as organizers bundle physical floor space with year-round digital engagement platforms to capture recurring subscription revenue beyond single-event cycles.
Growth Catalysts
- EU Green Deal certification mandates:Sustainability requirements under EU Green Deal frameworks are accelerating venue retrofit investments and green building certifications across German, French, and Italian host cities, creating compliant inventory for multinational corporate procurement teams.
- SaaS vendor concentration:Technology sector exhibitors now commit larger booth footprints and premium sponsorship tiers due to compressed product refresh cycles and competitive positioning needs in crowded software categories.
- Incubation pavilion expansion:Startup participation rates are climbing as purpose-built founder zones with investor matchmaking infrastructure attract venture-backed companies seeking B2B customer acquisition channels.
Market Restraints
- Input cost volatility:Exhibition construction materials including aluminum truss systems and LED display panels face price instability from energy-intensive manufacturing processes and raw material supply fluctuations.
- Venue ownership concentration:Captive venue control by Messe München, Messe Frankfurt, and a limited cohort of municipal operators creates bottleneck pricing power in premium German exhibition corridors.
- Dual-burden compliance:FDA and EMA parallel transparency requirements impose overlapping disclosure protocols and registration costs on pharmaceutical exhibitors operating transatlantic medical congress circuits.
Strategic Opportunities
- Saudi Arabia giga-project pipeline:NEOM and Red Sea Project construction timelines are generating demand for specialized industrial expos targeting construction technology and smart city infrastructure procurement.
- ISO 20121 adoption tailwinds:Sustainable event management standards are gating multinational corporate venue selection, creating first-mover advantage for certified operators in secondary European host cities.
- Healthcare-AI convergence:Medical congress formats are integrating diagnostic artificial intelligence demonstration zones, attracting dual sponsorship from pharmaceutical and health-tech vendors.
Industry Challenges
- Digital-physical integration complexity:Legacy event management systems require substantial middleware investment to synchronize on-site badge scanning, session attendance tracking, and post-event analytics pipelines.
- Carbon accounting skill gaps:Venue operators lack standardized methodologies for Scope 3 emissions measurement across exhibitor freight, attendee travel, and temporary construction waste streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Exhibition Market |
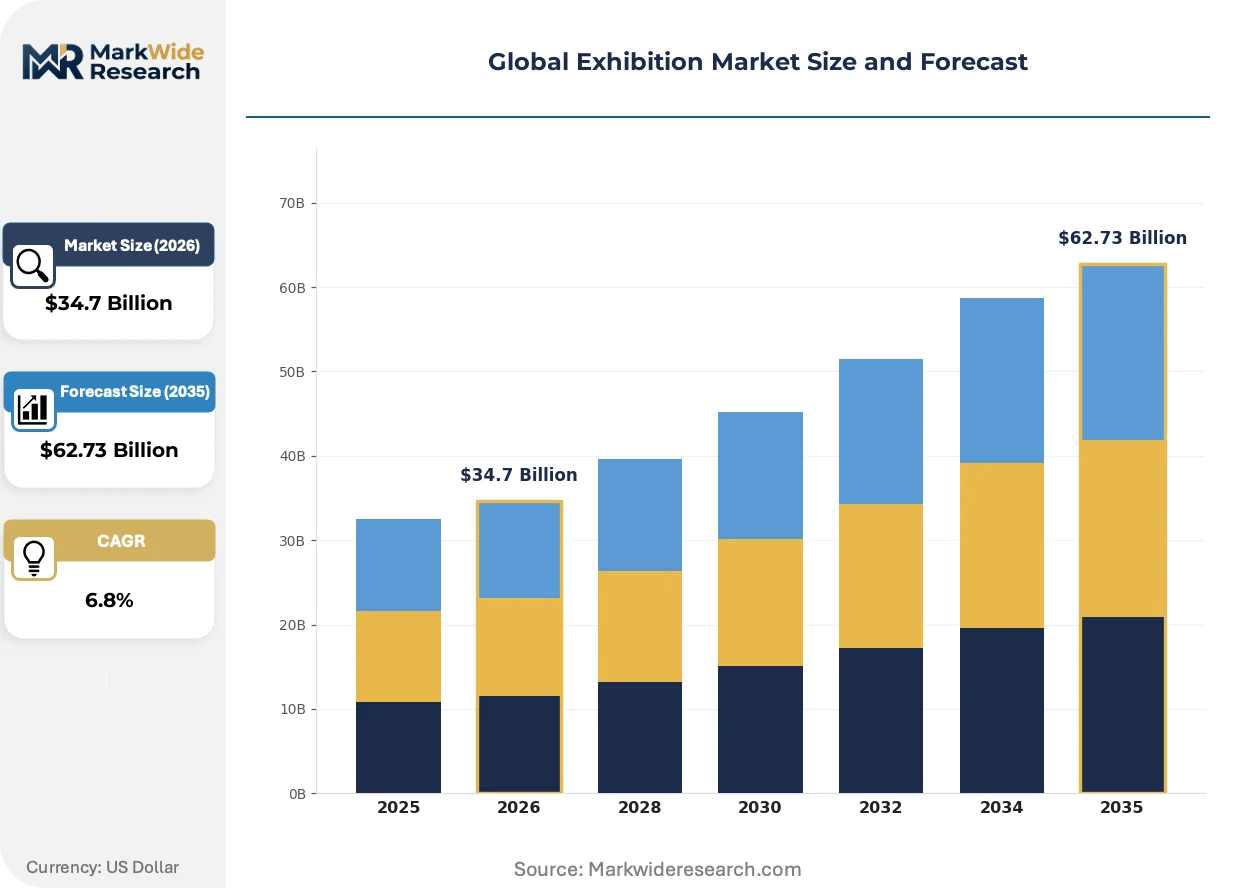
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Event Type: Trade Shows, Expositions, Conferences, Fairs Exhibitor Type: Corporations, Startups, NGOs, Government Agencies Industry Vertical: Technology, Healthcare, Manufacturing, Education Booth Size: Small, Medium, Large, Extra-Large |
| Companies Covered | Clarion Events, dmg Events, Informa, NürnbergMesse, Messe München, RX, Hyve, Easyfairs, Messe Frankfurt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Exhibition Market Emerging Trajectories
Exhibition formats are fragmenting into modular, year-round engagement architectures that decouple content delivery from physical calendar constraints. Organizers now compete on data infrastructure depth rather than square footage alone.
Immersive virtual reality demonstration environments are integrating haptic feedback systems and spatial computing interfaces into premium booth configurations. Industrial machinery and automotive exhibitors are adopting these tools at accelerating rates to simulate equipment operation without freight logistics. The technology is integrating physical product showcases with digital twin visualization, compressing lead qualification timelines from days to minutes.
EU AI Act transparency requirements are reshaping exhibitor disclosure protocols for algorithmic product demonstrations at technology-focused trade shows. Event organizers must now verify documentation of automated decision-making systems displayed on exhibition floors. Medical imaging and diagnostic equipment segments face the steepest compliance burden, with some organizers introducing pre-clearance review processes for AI-enabled product launches.
Corporate procurement teams are unbundling exhibition participation from traditional marketing budget silos, instead routing spend through enterprise SaaS subscription frameworks. Chief Marketing Officers now evaluate exhibition ROI against digital advertising and content marketing alternatives using unified attribution models. This behavioral shift is most pronounced among North American technology vendors, where marketing operations teams demand granular lead-scoring data exports from organizer platforms.
Global Exhibition Market Segmentation
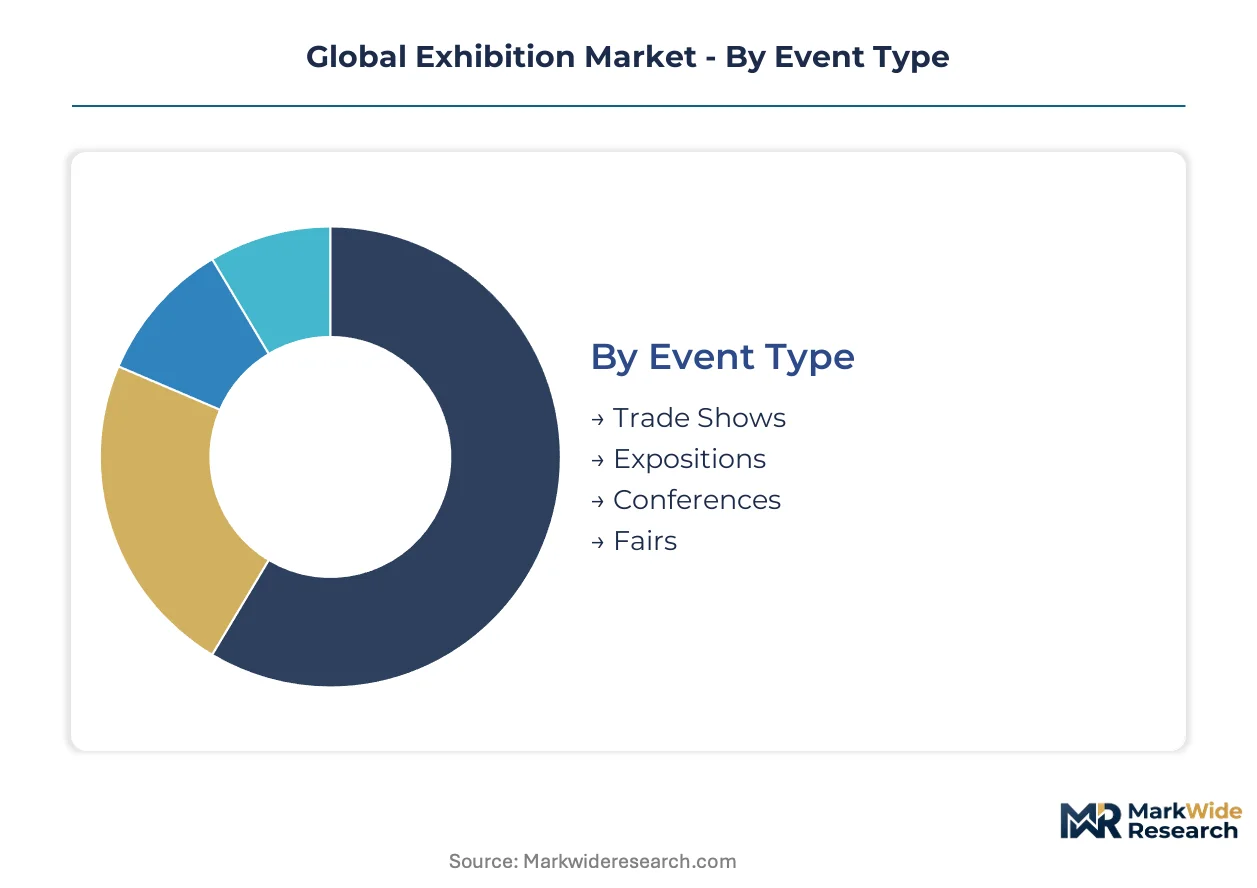
Exhibition organizers calibrate pricing and service bundles across multiple segmentation axes, from event format to booth footprint. Each category reflects distinct procurement behaviors and margin structures that shape venue operator strategy.
Event Type:
Standardization dominates high-volume formats while bespoke programming commands premium tiers in specialized gatherings.
- Trade Shows:Purpose-built temporary marketplaces where exhibitors deploy physical booths, live demonstrations, and sales personnel to facilitate B2B commerce within defined venue footprints. Messe München and Messe Frankfurt anchor global infrastructure for manufacturing and industrial trade shows, with captive venue ownership enabling year-round calendar control.
- Conferences:Knowledge-as-product formats featuring speaker agendas, breakout sessions, and networking infrastructure rather than booth-centric commerce. RX specializes in healthcare congress circuits across Asia-Pacific and Middle Eastern host cities, where pharmaceutical exhibitors navigate FDA and EMA dual-burden compliance requirements.
- Expositions:Large-scale public-facing displays combining commercial exhibition with cultural or educational programming, typically requiring municipal venue partnerships and public safety coordination.
- Fairs:Recurring calendar events with established visitor traditions, often operating on shorter build cycles and standardized booth packages to reduce exhibitor logistics costs.
Most installed capacity flows through Trade Shows. Expansion is steepest in Conferences.
Exhibitor Type:
Procurement sophistication varies sharply across organizational scale and budget authority.
- Corporations:Dominant revenue contributors with centralized marketing procurement teams demanding granular lead-scoring data exports and ISO 20121 sustainability certification from venue operators. Chief Marketing Officers evaluate exhibition ROI against digital advertising alternatives using unified attribution models.
- Startups:Venture-backed companies accelerating participation through incubation-focused pavilions with investor matchmaking infrastructure. Purpose-built founder zones reduce customer acquisition costs in crowded B2B software categories.
- NGOs:Mission-driven organizations prioritizing policy influence and coalition-building over direct sales, typically occupying smaller footprints with advocacy-focused programming.
- Government Agencies:Public sector exhibitors subject to procurement transparency requirements and domestic content preferences, particularly visible at infrastructure and defense-focused events.
Corporations command the largest revenue pools. Startups are gaining share fastest through pavilion expansion.
Industry Vertical:
Technology verticals capture disproportionate marketing spend due to compressed product refresh cycles.
- Technology:SaaS vendors and hardware manufacturers committing larger booth footprints and premium sponsorship tiers. EU AI Act transparency requirements now mandate pre-clearance documentation for algorithmic product demonstrations at technology-focused trade shows.
- Healthcare:Pharmaceutical and medical device exhibitors facing overlapping FDA and EMA disclosure protocols at transatlantic medical congress circuits. Medical imaging segments face steepest compliance burden for AI-enabled product launches.
- Manufacturing:Industrial machinery exhibitors adopting immersive virtual reality demonstration environments with haptic feedback to simulate equipment operation without freight logistics.
- Education:Universities and training providers leveraging exhibition platforms for international student recruitment and research partnership development.
Technology verticals dominate marketing expenditure. Healthcare is expanding most quickly through AI-convergence programming.
Booth Size:
Footprint tier directly correlates with service complexity and construction material requirements.
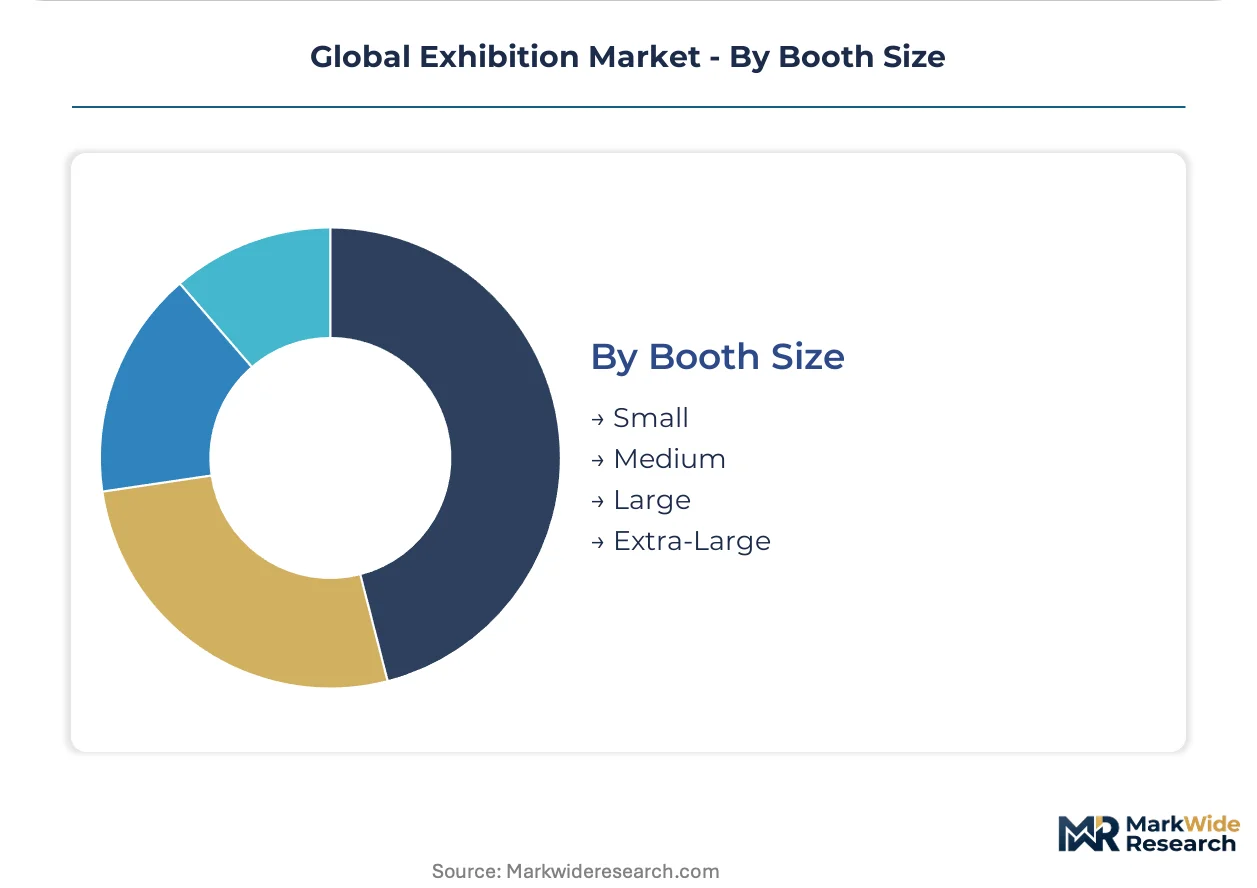
- Small:Standardized shell schemes with basic furniture packages, targeting first-time exhibitors and cost-constrained participants in startup pavilions.
- Medium:Custom-built configurations with branded graphics and meeting room modules, representing the volume tier for established corporate exhibitors.
- Large:Multi-story structures with integrated demonstration areas and hospitality suites, requiring aluminum truss systems and LED display panels facing input cost volatility.
- Extra-Large:Captive hall configurations or dedicated pavilions for anchor exhibitors, negotiated through multi-year commitments with venue operators holding concentrated ownership in German exhibition corridors.
Medium booths represent the volume core. Extra-Large commitments are climbing fastest among technology sector anchors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands larger venue footprints than the United States, while Saudi Arabia's giga-project pipeline is generating faster calendar expansion than mature European markets.
Germany
Messe München and Messe Frankfurt anchor global trade show infrastructure through captive venue ownership in Bavaria and Hesse. EU Green Deal certification mandates are accelerating retrofit investments across Berlin-Brandenburg and Hamburg exhibition complexes. The country's concentrated municipal operator structure creates bottleneck pricing power in premium manufacturing expo corridors.
United States
FDA guidelines on healthcare congress transparency shape pharmaceutical exhibitor compliance costs at medical events concentrated in Boston and San Diego biotech clusters. The IRA's domestic manufacturing incentives are expanding industrial machinery show floors in Chicago and Houston. Corporate procurement teams now route exhibition spend through SaaS subscription frameworks rather than traditional marketing silos.
China
NMPA regulatory requirements for medical device demonstrations are reshaping booth documentation protocols at Shanghai and Shenzhen technology expos. MIIT industrial policy is driving smart manufacturing pavilion expansion in the Yangtze River Delta. The country's dual carbon goals are pressuring venue operators in Beijing-Tianjin-Hebei to accelerate green building certifications.
Saudi Arabia
NEOM and Red Sea Project construction timelines are generating specialized demand for industrial expos targeting smart city infrastructure procurement. SFDA pharmaceutical transparency requirements are converging with international disclosure standards at Riyadh medical congresses. The Eastern Province is emerging as a secondary host city for energy sector exhibitions.
United Kingdom
GDPR compliance costs are elevating data infrastructure requirements for hybrid event platforms serving London's financial services exhibition calendar. MHRA post-Brexit regulatory divergence is creating dual-track certification burdens for medical device exhibitors. Birmingham's NEC complex is capturing manufacturing expo overflow from capacity-constrained German venues.
Global Exhibition Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with venue-owning incumbents controlling premium calendar slots while platform operators capture recurring digital revenue. The market structures around three tiers: captive venue operators with year-round inventory control, hybrid-format specialists bundling physical and digital engagement, and niche segment consolidators targeting vertical compliance requirements. Strategic moves concentrate on M&A for calendar density and ISO 20121 certification acquisition for procurement gatekeeping.
Within the captive venue tier, Messe München GmbH and Messe Frankfurt GmbH exemplify the Bavarian and Hessian operator archetype with integrated hall ownership. Among hybrid-format specialists, Informa occupies a position bridging physical floor space with year-round subscription platforms. RX sits within the vertical specialization vector, anchoring healthcare congress circuits where FDA and EMA dual-burden compliance creates barrier value.
| Leading Market Players |
|---|
| Clarion Events |
| dmg Events |
| Informa |
| NürnbergMesse |
| Messe München |
| RX |
| Hyve |
| Easyfairs |
| Messe Frankfurt |
| Others |
Supply Flow & Price Mechanics
Aluminum truss system costs cascade through exhibition construction tiers, compressing margins on large-format booth configurations while premium digital-physical bundles absorb upstream volatility through recurring subscription architectures. Energy-intensive LED display panel manufacturing in China feeds price instability into German and US venue operator procurement cycles, forcing tiered service unbundling to isolate commodity-exposed legacy formats from software-margin protected hybrid offerings.
Pricing Analysis
Capacity additions in Saudi Arabia and secondary European host cities are reshaping price floors for standard booth packages as new venue inventory loosens Messe München and Messe Frankfurt's bottleneck pricing power. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 20121 certification status and year-round digital platform access, with pharmaceutical exhibitors facing dual-burden compliance costs showing least price sensitivity while startup pavilion participants in incubation zones drive hardest bargain negotiations. Cost compression in medium-format custom builds is intensifying because aluminum and display panel input volatility transfers directly to construction quotes.
Supply Chain Analysis
Domestic-content mandates in China's MIIT industrial policy and US IRA manufacturing incentives are reshaping sourcing patterns for temporary exhibition infrastructure and smart manufacturing demonstration equipment. Supply concentrates in China for LED components and aluminum systems, in Germany for precision-engineered truss and rigging hardware, and in Italy for specialized scenic fabrication. Raw material dependencies span bauxite refining for structural alloys, rare earth elements for display phosphors, and petrochemical feedstocks for synthetic flooring. Single-source vulnerability concentrates in Chinese display panel foundries. Distribution runs through venue-operator captive procurement channels and third-party exhibition service contractors with regional hub structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Exhibition Market functions as a stable compounder anchored by irreplaceable calendar slots at captive-venue operators and the secular shift toward hybrid-format recurring revenue architectures.
For Market Incumbents: Extend digital platform capabilities to capture year-round subscription revenue beyond single-event cycles, insulating against input cost volatility in physical construction materials. Defend against emerging platform-native competitors by accelerating ISO 20121 certification acquisition to gate multinational corporate procurement decisions. Prioritize backward integration into aluminum truss and LED display supply through long-term offtake agreements with Chinese and German manufacturers.
For New Entrants and Emerging Players: Capture white-space in Saudi Arabia's NEOM and Red Sea Project construction timelines through specialized industrial expos targeting smart city infrastructure procurement. Target secondary European host cities where EU Green Deal retrofit investments are creating certified venue inventory ahead of incumbent repositioning. Lead with AI-enabled matchmaking infrastructure for startup pavilion formats to differentiate from legacy organizer relationship databases.
For Investors and Strategic Acquirers: Consolidation pressure builds where venue ownership concentration intersects with hybrid-format capability gaps, favoring targets with captive calendar control and underdeveloped digital infrastructure. Exhibition operators with healthcare vertical specialization offer defensive positioning given FDA and EMA dual-burden compliance barriers. Monitor carbon accounting methodology standardization as the signal to watch for procurement gatekeeping power shifts toward certified operators.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20121 Certification Acquisition | Gates multinational corporate venue selection as EU Green Deal mandates harden procurement criteria. |
| Hybrid Platform Integration | Extends audience reach across year-round engagement cycles beyond physical calendar constraints. |
| Healthcare Vertical Specialization | Captures pharmaceutical exhibitor spend through FDA and EMA dual-burden compliance barrier value. |
| Saudi Arabia Geographic Expansion | Positions for NEOM and Red Sea Project industrial expo demand in construction technology procurement. |
| AI-Enabled Matchmaking Development | Differentiates startup pavilion offerings through investor-founder algorithmic pairing infrastructure. |
Methodological Framework
Coverage spans Germany, United States, China, Saudi Arabia, and United Kingdom, with primary inputs from each market cluster combined with secondary validation. Primary interviews incorporated exhibition organizers, venue operators, corporate marketing procurement managers, pharmaceutical regulatory affairs leads, and startup pavilion coordinators. Secondary sources included SEC filings from listed event operators, EU Green Deal implementation documentation, FDA and EMA transparency guidance, ISO 20121 certification registries, and customs data on aluminum and display panel trade flows. Bottom-up venue capacity and exhibitor spend estimates triangulated against top-down market value reconstructions.
Granularity-level modeling distinguished event format, exhibitor type, industry vertical, and booth size tiers across the projection horizon. Technology sector SaaS vendor concentration and healthcare AI-convergence programming received distinct treatment given their disproportionate marketing spend capture. CAGRs derived from historical growth pattern analysis adjusted for hybrid-format adoption curves and sustainability certification penetration rates. Forecast inputs incorporated EU AI Act transparency requirement implementation timelines and Saudi giga-project construction phase commitments.
Regulatory implementation delays, input cost volatility in energy-intensive manufacturing, and hybrid-format adoption rate divergence are the dominant revision risks to modeled trajectories. Forecasts reflect assumptions on certification mandate enforcement consistency and corporate procurement team behavioral shifts toward SaaS subscription frameworks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Festivals
Portable Photo Booth Market
Events and Festivals
Global Escape Room Market
Events and Festivals
Corporate Luxury Events Market
Events and Festivals
Global Roller Coaster Market
Events and Festivals
Global Family Entertainment Center Market
Events and Festivals
Online Event Ticketing Market
Events and Festivals
US Amusement and Theme Park Market
Events and Festivals
Global Special Effects Fog and Smoke Machines Market
Events and Festivals
India Event Services Market
Events and Festivals
Sports Events Tickets Market
Events and Festivals
Europe K-Pop Events Market
Events and Festivals
India Event and Exhibition Market
Events and Festivals
UK Arts Promoter Market
Events and Festivals
Asia-Pacific K-Pop Events Market
Events and Festivals
Stage and Scenery Equipment Market
Events and Festivals
Asia-Pacific Amusement Parks Market