
 Events Market | 2026-2036
Events Market Size, Share, and Industry Trends Forecast 2026-2036
Events Market Insights
Asset-light venue leasing and project-based event financing is tilting competitive dynamics toward operators with flexible capital structures rather than fixed-asset owners. Live Nation Entertainment leverages its integrated venue-ticketing platform to sustain pricing power across major metropolitan markets. Informa PLC anchors its position through specialized B2B content and exhibition portfolios that dominate niche professional communities. GL events Group competes via its control of municipal and convention center concessions across multiple European countries.
Events constitute temporary, purpose-built gatherings where organizers coordinate spatial design, audiovisual infrastructure, attendee logistics, and programmed content to achieve specific commercial, educational, or ceremonial outcomes, typically measured by attendance volume, sponsor yield, and participant engagement scores. The delivery model dimension shows hybrid formats capturing disproportionate investment as corporations demand simultaneous in-person and virtual participation pathways. Within service type, event planning commands premium margins where agencies embed proprietary technology for real-time attendee analytics, while ticketing services faces margin compression from direct-to-consumer platform disintermediation.
ISO 20121, the EU Green Deal framework, and the US EPA's waste reduction guidelines for large gatherings are converging to mandate carbon accounting, single-use material bans, and energy disclosure for events above defined attendance thresholds. These standards reshape supplier qualification and venue selection criteria. Stakeholders must monitor regulatory divergence between jurisdictions where sustainability mandates accelerate and those where enforcement remains fragmented, as this gap will determine which operators can scale cross-border event portfolios without compliance cost penalties.
Market Dynamics
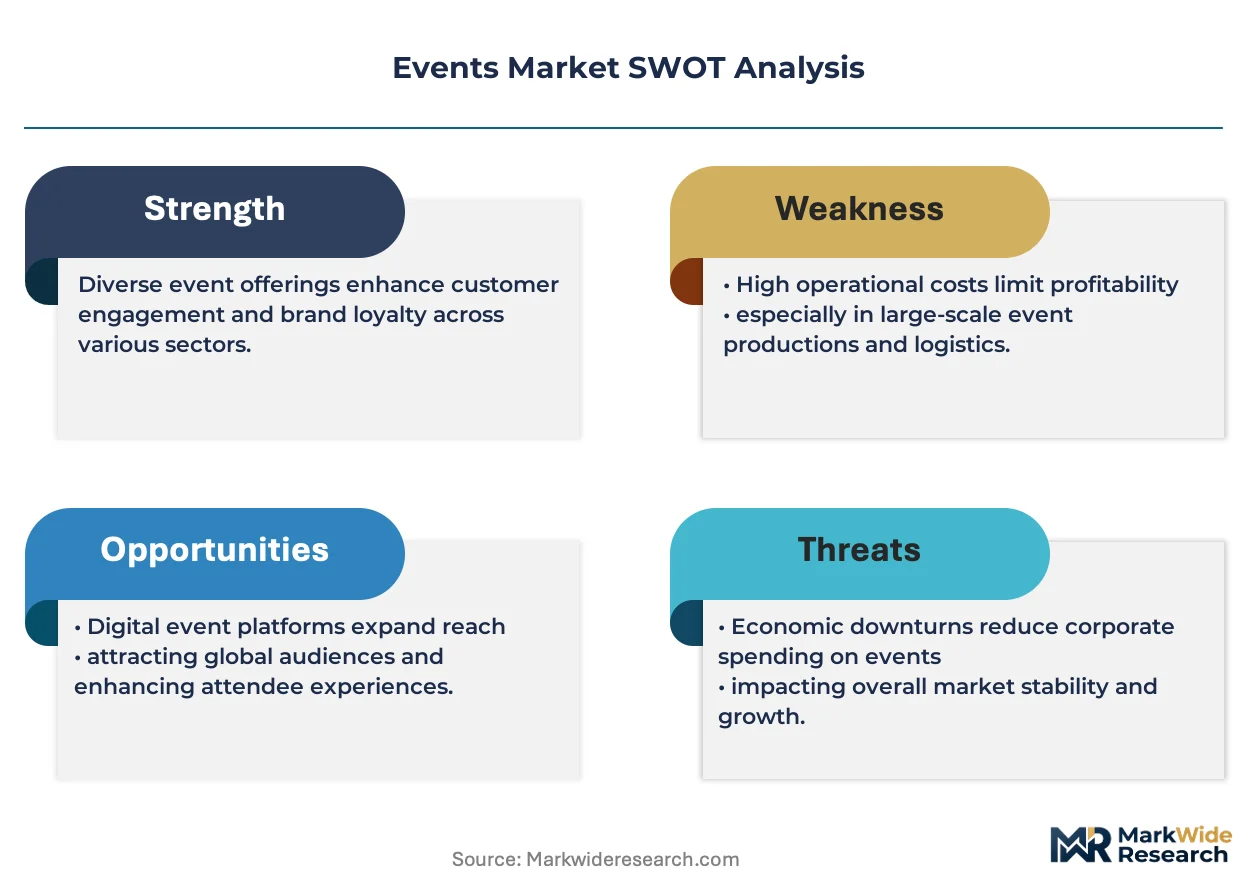
ISO 20121 sustainable event management standards are compressing procurement timelines and disqualifying traditional venue operators who cannot demonstrate carbon accounting capabilities. Corporate technology buyers now mandate hybrid-ready infrastructure as a baseline qualification, forcing asset-heavy incumbents into expensive retrofit cycles while favoring agile, technology-embedded competitors.
Growth Catalysts
- EU Green Deal framework:Mandatory carbon disclosure for large gatherings above defined attendance thresholds is accelerating venue certification upgrades across Germany, France, and the Netherlands.
- Hybrid event technology:Simultaneous in-person and virtual participation infrastructure is capturing disproportionate corporate technology sector investment.
- United States destination concentration:Premium metropolitan markets including New York, Chicago, and Las Vegas are consolidating large-scale conference and trade show demand.
Market Restraints
- Technical labor scarcity:Certified audiovisual engineers and sustainability compliance officers command wage premiums that compress event planning margins.
- Venue supply concentration:Municipal convention center concessions in major European capitals limit independent operator access to prime dates.
- Energy cost volatility:Natural gas and electricity price spikes directly impact temporary infrastructure powering and climate control expenses.
Strategic Opportunities
- Japan inbound expansion:Tokyo and Osaka are underpenetrated relative to their infrastructure capacity for pharmaceutical and medical device congresses.
- Real-time attendee analytics:Proprietary data platforms embedded in event planning services are creating premium pricing power.
- ISO 20121 certification acceleration:Early compliance is opening exclusive supplier relationships with sustainability-mandated Fortune 500 procurement teams.
Industry Challenges
- Legacy venue integration:Retrofitting municipal convention centers with hybrid broadcast infrastructure requires 18-24 month capital cycles.
- Talent pipeline gaps:Universities lack specialized curricula combining event logistics, carbon accounting, and virtual platform management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Events Market |
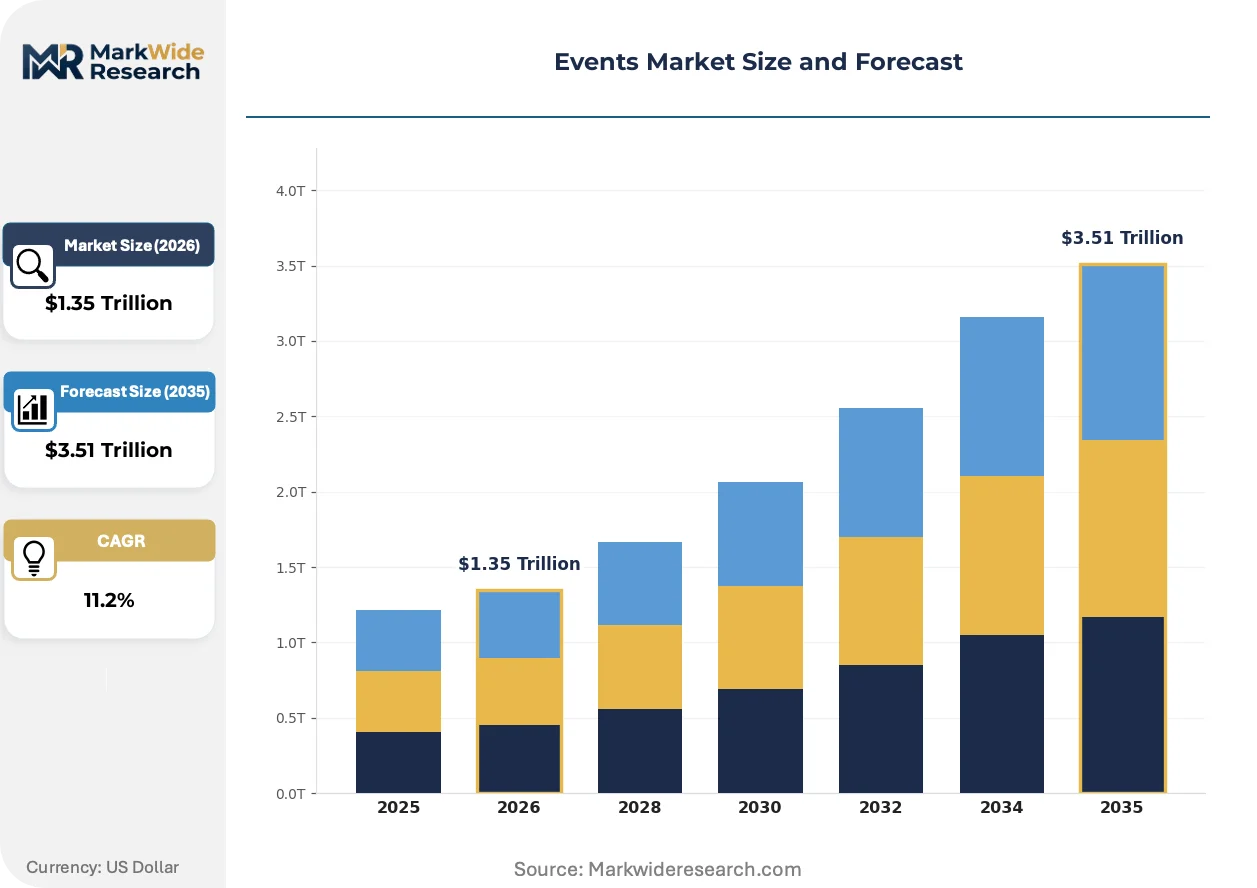
| Market Size in 2026 | $1.35 Trillion |
| Market Size in 2035 | $3.51 Trillion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Event Type: Conferences, Trade Shows, Festivals, Seminars Service Type: Event Planning, Venue Management, Ticketing Services, Event Marketing End User: Corporations, Nonprofits, Educational Institutions, Government Agencies Delivery Model: In-Person, Virtual, Hybrid, Networking Events |
| Companies Covered | Informa PLC, Live Nation Entertainment, ASM Global, Cvent Inc., BCD Meetings & Events, Reed Exhibitions, GL events Group, Anschutz Entertainment Group, ATPI Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Events Market Trends and Innovations
Event delivery models are fragmenting as technology enables simultaneous physical and digital participation pathways. Organizers now compete on real-time data capture and personalized attendee journey orchestration rather than venue scale alone.
Immersive extended reality environments are migrating from experimental pilot programs to standard corporate product launch formats. Pharmaceutical and technology sector buyers now expect virtual exhibition halls with AI-moderated networking as baseline deliverables. This technology compression is eliminating single-channel event agencies and rewarding operators with in-house platform development capabilities.
EPA waste reduction guidelines for large gatherings are mandating single-use material bans and energy disclosure above defined attendance thresholds. US-based venue operators face 90-day compliance windows for new reporting requirements. Trade show segments serving consumer packaged goods and food service verticals are most affected, with organizers accelerating supplier pre-qualification audits.
Corporate procurement teams are consolidating agency relationships around outcome-based engagement metrics rather than per-attendee cost structures. Technology sector buyers now tie payment to measurable lead generation and content consumption analytics. This shift is most visible in the United States, where direct-to-virtual platform disintermediation has compressed traditional ticketing service margins by half.
Events Market Segmentation
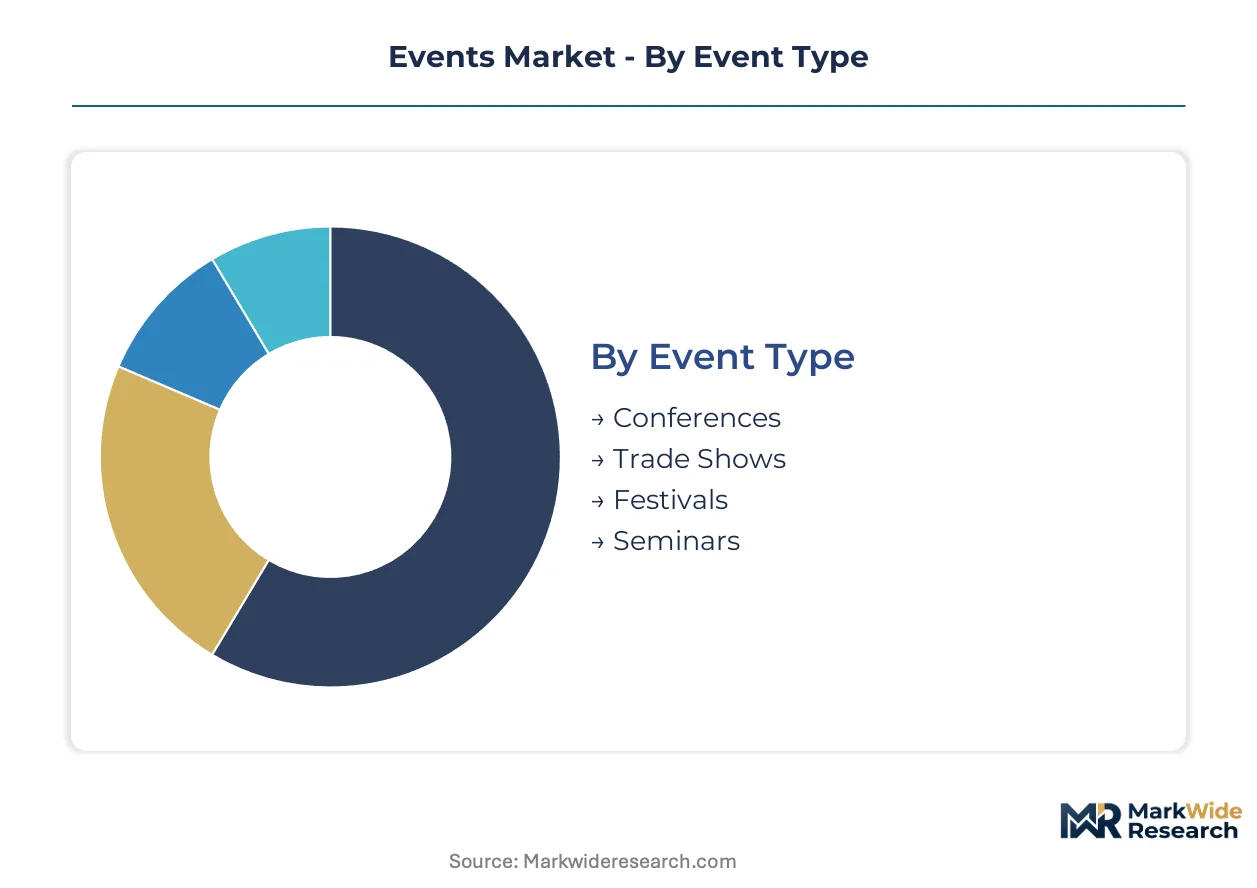
Events Market segmentation reveals distinct operational and investment profiles across event formats, service layers, and participant engagement modes. Procurement patterns diverge sharply between temporary gatherings requiring intensive post-event analytics and recurring formats demanding sustained platform relationships.
Event Type:
After-sales service intensity varies dramatically across event formats, with multi-day programming requiring continuous technical support and single-day formats demanding concentrated pre-event coordination.
- Conferences:Multi-day professional gatherings featuring keynote programming, breakout sessions, and structured networking. Pharmaceutical and technology sector procurement in the United States and Germany concentrates here, driven by compliance documentation requirements and lead generation measurement mandates.
- Trade Shows:Exhibition-centric formats combining vendor booths, product demonstrations, and industry awards. Osaka and Las Vegas venues capture disproportionate investment from medical device and consumer electronics manufacturers seeking concentrated buyer-seller matching.
- Festivals:Entertainment-focused mass gatherings with ticketed admission and sponsor activation zones. Municipal concession agreements in European capitals restrict independent operator access to prime calendar dates.
- Seminars:Education-oriented small-group formats emphasizing skill transfer and certification. Corporate training budgets in Japan and corporate universities in Germany sustain demand for specialized technical programming.
By volume, Conferences leads. By growth pace, Hybrid-enabled Trade Shows is ahead.
Service Type:
Cost tier differentiation separates premium-margin advisory functions from commoditized infrastructure provision, with technology-embedded services commanding pricing power over standardized logistics.
- Event Planning:Strategic coordination of programming, vendor selection, and attendee journey design. Agencies embedding proprietary real-time analytics platforms for pharmaceutical sector clients in the United States capture premium pricing through outcome-based contracts tied to engagement metrics.
- Venue Management:Physical space operations including climate control, security staffing, and accessibility compliance. Municipal convention center operators in France and Germany face margin pressure from ISO 20121 certification costs and energy disclosure mandates.
- Ticketing Services:Admission processing, access control, and secondary market management. Direct-to-consumer platform disintermediation has compressed traditional agency margins by half in North American markets.
- Event Marketing:Pre-event promotion, sponsor acquisition, and post-event content repurposing. B2B technology sector buyers now mandate AI-moderated virtual networking as baseline deliverable.
By revenue concentration, Event Planning dominates. By margin expansion, Technology-embedded Event Marketing is climbing the fastest.
End User:
Customer type determines procurement sophistication, with Fortune 500 technology buyers imposing outcome-based payment structures while public sector clients prioritize compliance documentation.
- Corporations:Commercial entities procuring events for product launches, sales conferences, and employee engagement. Technology sector procurement teams now tie agency payment to measurable lead generation and content consumption analytics.
- Nonprofits:Mission-driven organizations leveraging events for fundraising and stakeholder mobilization. Donor reporting requirements in Germany and the United States drive demand for carbon accounting documentation.
- Educational Institutions:Universities and professional associations delivering credentialing and knowledge transfer. Talent pipeline gaps in combined event logistics, carbon accounting, and virtual platform management constrain service quality.
- Government Agencies:Public sector entities procuring events for policy consultation and international diplomacy. EPA waste reduction guidelines mandate single-use material bans for gatherings above defined attendance thresholds.
By procurement volume, Corporations leads. By compliance complexity acceleration, Government Agencies is gaining share fastest.
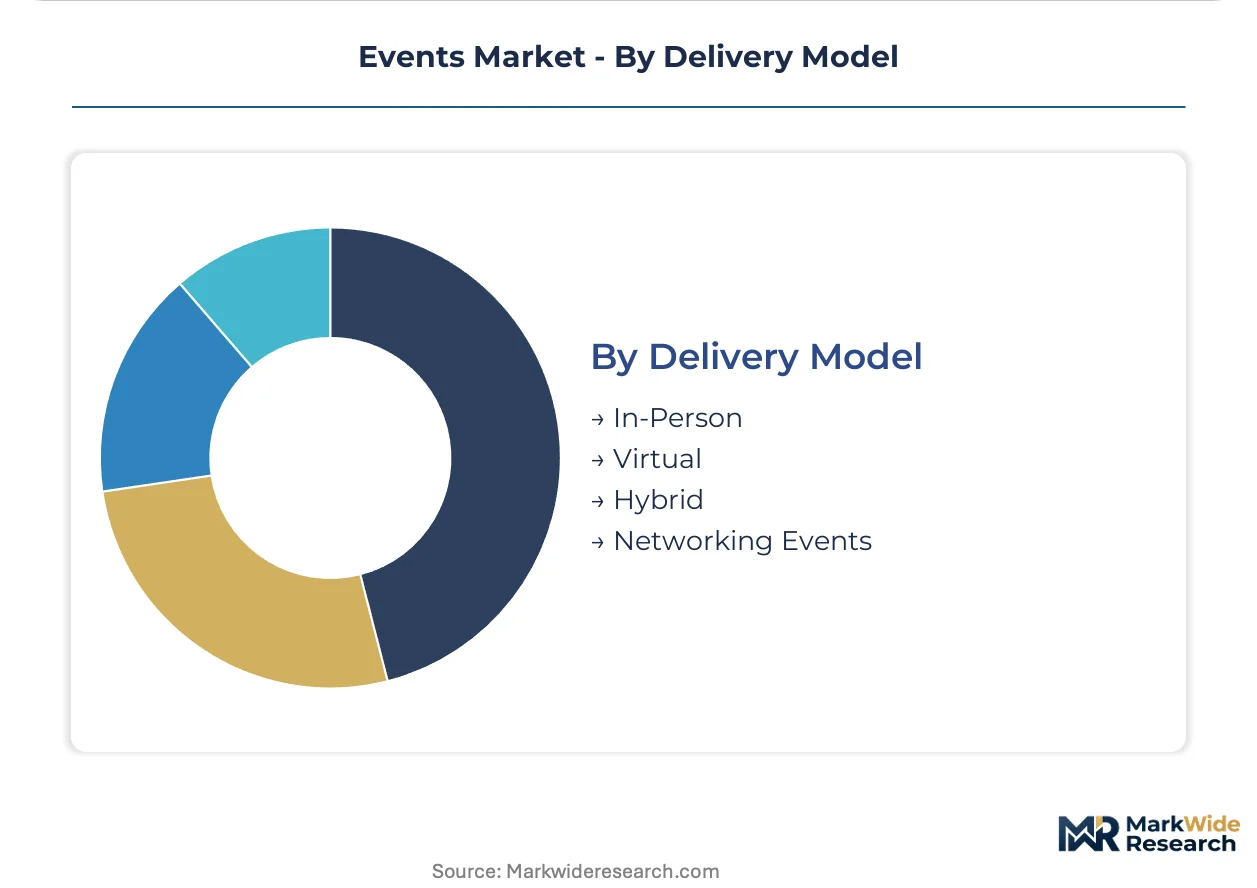
Delivery Model:
Technology maturity separates established in-person infrastructure from experimental virtual formats, with hybrid architectures requiring simultaneous mastery of physical and digital production.
- In-Person:Traditional physical gathering with on-site attendance and localized programming. Legacy venue integration challenges in municipal convention centers require 18-24 month capital cycles for hybrid broadcast retrofit.
- Virtual:Fully digital participation via streaming platforms and virtual exhibition environments. Pharmaceutical sector buyers now expect AI-moderated networking and virtual exhibition halls as standard deliverables.
- Hybrid:Simultaneous in-person and virtual participation pathways with integrated programming. Corporate technology sector procurement mandates hybrid-ready infrastructure as baseline qualification, favoring agile competitors over asset-heavy incumbents.
- Networking Events:Relationship-focused formats emphasizing structured connection over content consumption. Real-time attendee analytics platforms create premium pricing power for operators with proprietary data capabilities.
By installed infrastructure base, In-Person leads. By investment flow, Hybrid shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA waste reduction guidelines and EU Green Deal carbon disclosure mandates are redirecting event investment toward jurisdictions with mature sustainability infrastructure and enforcement capacity.
United States
Corporate technology buyers in New York, Chicago, and Las Vegas drive premium conference demand tied to lead generation analytics. EPA mandates single-use material bans and energy disclosure for gatherings above defined attendance thresholds. Las Vegas convention corridors anchor medical device and consumer electronics trade show concentration.
Germany
ISO 20121 certification requirements compress procurement timelines for pharmaceutical and automotive sector congresses. EU Green Deal frameworks mandate carbon accounting for large gatherings across Frankfurt, Munich, and Berlin. Municipal convention center operators face margin pressure from compliance upgrade cycles.
Japan
Pharmaceutical and medical device manufacturers underutilize Tokyo and Osaka infrastructure relative to capacity. METI guidelines shape corporate sustainability reporting for event procurement. Osaka's exhibition complexes capture disproportionate investment from device manufacturers seeking concentrated buyer-seller matching.
United Kingdom
London's integrated venue-ticketing platforms sustain pricing power across financial services and professional services gatherings. CSRD-aligned disclosure requirements reshape corporate procurement criteria for sustainability documentation. Birmingham and Manchester exhibition centers compete on hybrid broadcast infrastructure certification.
France
Luxury goods and fashion sector buyers concentrate event investment in Paris for product launch formats. EU Green Deal enforcement accelerates venue certification upgrades across Lyon and Nice. GL events Group's municipal concession network controls prime calendar access in multiple metropolitan markets.
Events Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated venue-ticketing operators leverage physical asset networks to capture recurring revenue streams. Specialized B2B content and exhibition portfolios dominate niche professional communities through proprietary data platforms. Agile technology-embedded agencies displace asset-heavy incumbents by meeting hybrid infrastructure mandates without retrofit capital cycles. Dominant competitive moves include municipal concession bidding for prime calendar control and proprietary analytics platform development for outcome-based contracting.
Within the integrated platform tier, Live Nation Entertainment and Informa PLC exemplify divergent scale strategies. Live Nation anchors metropolitan market pricing power through venue-ticketing integration. Informa PLC occupies a position defined by specialized B2B content portfolios dominating professional communities. GL events Group represents the municipal concession archetype, controlling prime calendar access across multiple European jurisdictions. These three patterns illustrate how capital structure flexibility determines competitive positioning under tightening sustainability and hybrid infrastructure mandates.
| Leading Market Players |
|---|
| Informa PLC |
| Live Nation Entertainment |
| ASM Global |
| Cvent Inc. |
| BCD Meetings & Events |
| Reed Exhibitions |
| GL events Group |
| Anschutz Entertainment Group |
| ATPI Ltd |
| Others |
Pricing and Supply Chain Analysis
Municipal convention center concessions in France and Germany concentrate upstream venue control, directing margin pools toward operators with embedded hybrid broadcast infrastructure rather than asset-heavy legacy owners. ISO 20121 certification costs and energy disclosure mandates compress margins for traditional venue operators while technology-embedded agencies capture premium pricing through outcome-based contracts.
Pricing Analysis
Certification level creates the primary spread between premium and standard service tiers, with ISO 20121-compliant operators commanding pricing power over uncertified competitors. Three-tier pricing structure separates sustainability-certified premium services from standard logistics provision and commoditized venue rental. Pricing pressure stems from direct-to-consumer platform disintermediation compressing traditional ticketing margins by half in North American markets. Corporate technology buyers demonstrate lowest price sensitivity due to outcome-based payment structures tied to lead generation analytics, while nonprofit and educational segments face acute budget constraints.
Supply Chain Analysis
Export control regimes on advanced audiovisual broadcast equipment limit technology flows from the United States and Japan into European venue retrofit projects. Supply concentrates in Germany, the United States, and Japan for specialized hybrid event infrastructure, with China dominating lower-tier temporary structure manufacturing. Critical dependencies include LED display panels, streaming encoders, and carbon accounting software platforms. Single-source vulnerability runs through municipal concession agreements controlling prime calendar dates in major metropolitan markets. Distribution runs through integrated venue-ticketing platforms and specialized B2B event agencies serving corporate procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The events market is crossing a platform-economics inflection where hybrid infrastructure interoperability determines competitive survival, with corporate procurement teams consolidating around operators delivering seamless physical-digital integration.
For Market Incumbents: Harden market position by accelerating proprietary real-time analytics platform development to meet outcome-based contracting demands from pharmaceutical and technology sector buyers. Deepen backward integration into hybrid broadcast infrastructure to reduce dependency on municipal venue retrofit cycles. Defend against agile technology-embedded competitors by securing exclusive supplier relationships with Fortune 500 procurement teams mandating ISO 20121 certification.
For New Entrants and Emerging Players: Pursue white-space opportunities in Japan's underpenetrated pharmaceutical congress infrastructure, where Tokyo and Osaka exhibition capacity exceeds current utilization rates. Target corporate training and medical device verticals with specialized hybrid event offerings combining AI-moderated networking and virtual exhibition halls. Establish go-to-market positioning through sustainability certification acceleration, opening exclusive access to EU Green Deal-mandated procurement channels.
For Investors and Strategic Acquirers: Capital is best deployed toward technology-embedded event agencies with in-house platform development capabilities and established ISO 20121 compliance. Long-term viability across the projection horizon favors operators with asset-light structures capable of scaling hybrid infrastructure without fixed-venue retrofit capital cycles. Monitor regulatory divergence between jurisdictions where sustainability mandates accelerate and those with fragmented enforcement as the critical inflection signal determining cross-border portfolio scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Infrastructure Certification | ISO 20121 compliance opens exclusive Fortune 500 procurement channels in Germany and the United States. |
| Proprietary Analytics Platform Development | Real-time attendee data capabilities command premium pricing from pharmaceutical sector buyers. |
| Municipal Concession Bidding | Prime calendar control in Paris and Frankfurt secures recurring revenue from trade show verticals. |
| Backward Integration into Broadcast Technology | In-house hybrid production reduces dependency on 18-24 month venue retrofit cycles. |
| Geographic Expansion into Japan | Tokyo and Osaka infrastructure capacity exceeds current pharmaceutical congress penetration rates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with event agency executives, venue operations directors, corporate procurement managers, and sustainability compliance officers; and secondary validation against SEC filings, municipal concession contract disclosures, ISO certification registries, and EU regulatory frameworks. Bottom-up triangulation across service type and delivery model segments was cross-checked against top-down market sizing from participant volume and sponsor yield indicators.
Forecast inputs incorporated event format segmentation, service layer differentiation, end-user procurement sophistication, and delivery model technology maturity across the projection horizon. CAGRs were derived from attendance volume trajectories, sponsor yield evolution, and hybrid infrastructure investment flows. Industry-specific inputs included ISO 20121 certification adoption curves, municipal venue retrofit capital cycles, and corporate technology sector hybrid procurement mandates.
Sensitivities concentrate around regulatory enforcement divergence, energy cost volatility impacts on temporary infrastructure, and technical labor scarcity in certified audiovisual engineering. Forecasts reflect documented assumptions on sustainability mandate acceleration and hybrid technology adoption rates. Material shifts in EU Green Deal implementation timelines or EPA waste reduction guideline enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Festivals
Indoor Entertainment Center Market
Events and Festivals
US Amusement and Theme Park Market
Events and Festivals
Asia-Pacific Amusement Parks Market
Events and Festivals
Global Live Event Ticketing Market
Events and Festivals
North America K-Pop Events Market
Events and Festivals
Europe K-Pop Events Market
Events and Festivals
Corporate Luxury Events Market
Events and Festivals
Sports Events Tickets Market
Events and Festivals
Global Exhibition Market
Events and Festivals
Stage and Scenery Equipment Market
Events and Festivals
Professional Speaker Market
Events and Festivals
Global Escape Room Market
Events and Festivals
Event Photography Service Market
Events and Festivals
India Event Services Market
Events and Festivals
Photo Booth Market
Events and Festivals
Global Roller Coaster Market