
 Poultry Farming Equipment Market | 2026-2036
Poultry Farming Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Farming Equipment Market Outlook
The capital-intensity gap between turnkey system providers and component specialists is collapsing as mid-scale farms demand integrated climate-feeding-biosecurity packages rather than point solutions. Big Dutchman leverages its vertical manufacturing footprint to control cost structures across feeder and ventilation lines. Roxell competes through specialized drinker engineering that reduces water waste in high-density broiler houses. Vencomatic Group anchors European demand with automated egg collection systems that cut labor inputs.
Poultry farming equipment encompasses mechanized housing, feeding, drinking, climate regulation, and waste management systems engineered for controlled-environment bird production, typically operating at stocking densities of 15–25 kg per square meter in broiler facilities. Its primary purpose is to optimize feed conversion ratios, mortality rates, and labor productivity across integrated protein supply chains. Incubators and climate control equipment capture disproportionate margin pools as hatcheries prioritize precision temperature-humidity management for genetic stock. IoT Solutions within automation segments are expanding fastest where farm operators deploy sensor networks for real-time ammonia and mortality alerts.
The US Department of Agriculture and FDA jointly enforce pathogen reduction and veterinary feed directive rules that mandate equipment sanitation protocols and antibiotic-use documentation systems. EU Green Deal farm-to-fork targets and REACH chemical safety standards compel European producers to retrofit housing with lower-emission ventilation and non-toxic coating materials. Stakeholders must weigh capital deployment timing between incremental automation upgrades and full-system replacements as regulatory compliance thresholds tighten without grandfathering existing installations.
Market Dynamics
The convergence of EU Green Deal emission targets with ASEAN veterinary drug residue standards is compressing equipment replacement cycles, forcing producers to choose between modular retrofits and full-system overhauls before compliance grandfathering expires.
Growth Catalysts
- EU Green Deal farm-to-fork mandates:European producers must install lower-emission ventilation and non-toxic housing coatings, accelerating capital deployment into climate-control infrastructure.
- IoT-enabled flock monitoring:Southeast Asian integrators deploy sensor networks for real-time ammonia and mortality tracking to satisfy tightening sanitary export protocols.
- Brazilian export-grade egg safety alignment:Commercial layer operations scale automated feeding systems to meet EU-aligned sanitary requirements for premium market access.
Market Restraints
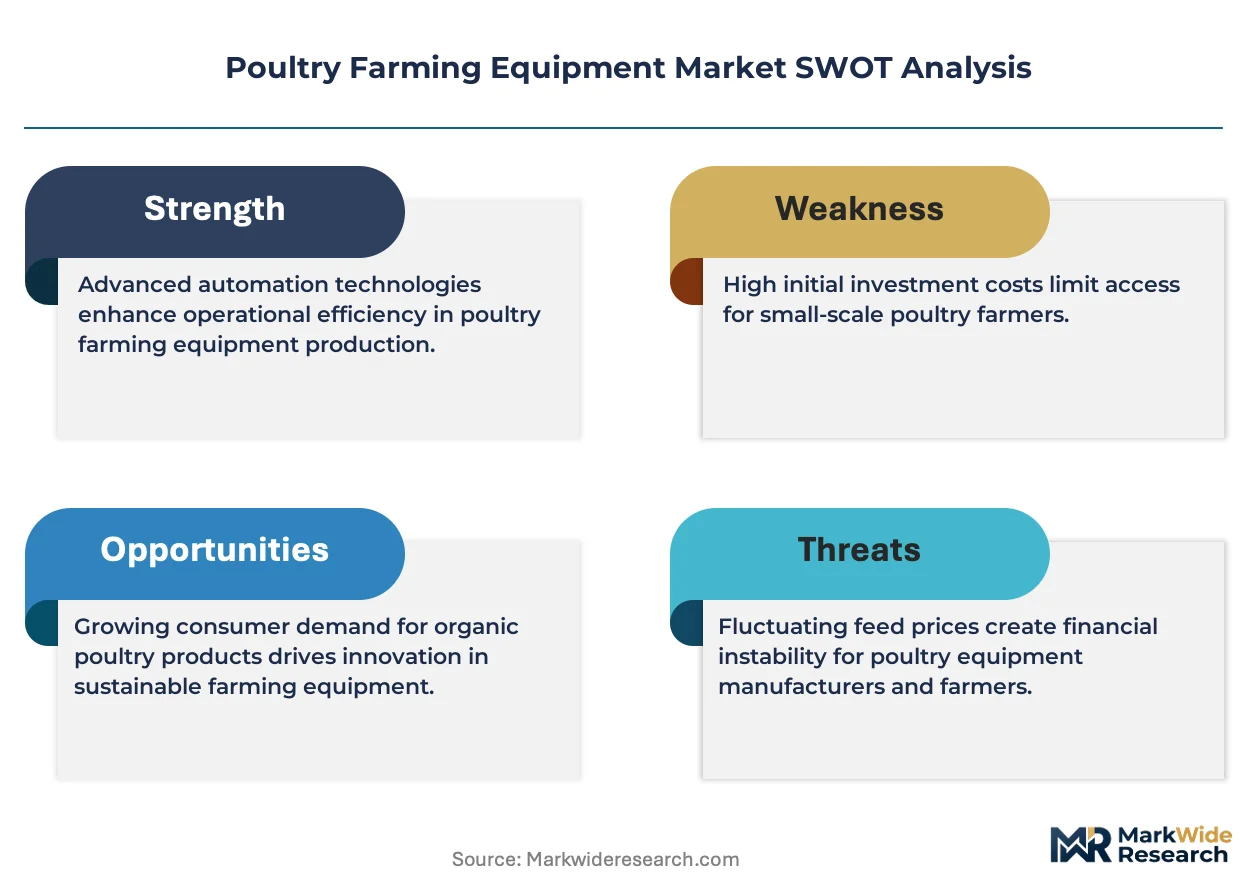
- Steel and aluminum input volatility:Climate-control housing and feeder fabrication costs swing with commodity markets, squeezing margins for equipment fabricators.
- Component supply concentration:Precision sensors and variable-frequency drives for automated systems concentrate in East Asian manufacturing clusters, creating single-source vulnerability.
- REACH chemical compliance friction:Coating material substitutions for housing equipment face extended ECHA approval timelines, delaying product launches.
Strategic Opportunities
- Indian broiler modernization:Mid-scale farms under PLI scheme incentives seek integrated climate-feeding-biosecurity packages rather than point solutions.
- Precision incubation-as-a-service:Hatcheries outsource temperature-humidity management to equipment vendors, shifting revenue from hardware to recurring monitoring contracts.
- EU F-Gas Regulation phase-down:Heat pump and evaporative cooling retrofits capture subsidy pools as hydrofluorocarbon-based systems face mandatory replacement.
Industry Challenges
- Automation technician scarcity:Farms struggle to hire personnel capable of calibrating IoT sensor networks and troubleshooting variable-frequency drive faults.
- Legacy system integration complexity:Retrofitting automated egg collection and climate control into existing housing requires custom mechanical interfaces and control software bridging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Farming Equipment Market |
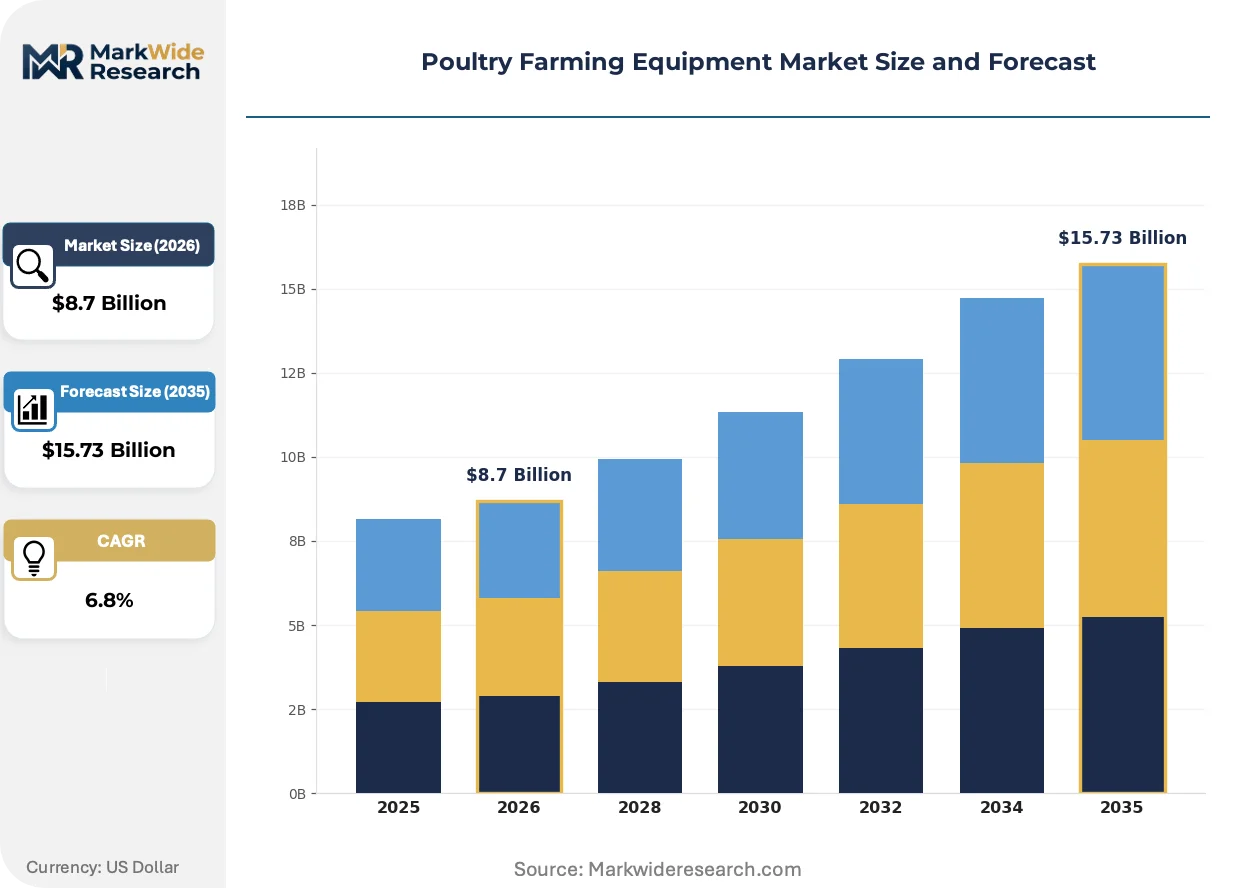
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Feeders, Drinkers, Brooders, Incubators Technology: Automation, IoT Solutions, Climate Control, Biosecurity Systems End User: Poultry Farms, Hatcheries, Feed Manufacturers, Equipment Suppliers Size: Small Scale, Medium Scale, Large Scale, Commercial |
| Companies Covered | Big Dutchman, Roxell, SKA, Tecno Poultry Equipment, Texha, Valco Industries, Officine Facco, Vencomatic Group, Hellmann Poultry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Farming Equipment Market Strategic Shifts
Equipment vendors are repositioning around data monetization and energy efficiency as protein integrators demand measurable feed conversion and labor productivity gains rather than hardware specifications alone.
Edge-computing sensor arrays for ammonia, humidity, and bird weight is fragmenting the market for centralized climate controllers. Mid-scale broiler operators in Vietnam and Thailand install distributed monitoring nodes that bypass legacy PLC-based systems. This architecture compresses margin pools for traditional ventilation OEMs while opening subscription revenue for analytics platforms.
REACH chemical safety standards and EU Green Deal emission targets are forcing coating and ventilation material substitutions. Housing manufacturers reformulate surface treatments to eliminate restricted substances. German and Dutch producers face the tightest compliance windows, accelerating partnerships with specialty chemical suppliers.
Buyer consolidation among Southeast Asian protein integrators is compressing vendor negotiation cycles. Large-scale operators in Indonesia and the Philippines now mandate five-year total cost of ownership guarantees rather than upfront equipment pricing. This shift pressures component suppliers to absorb performance risk through outcome-based service agreements.
Poultry Farming Equipment Market Segmentation
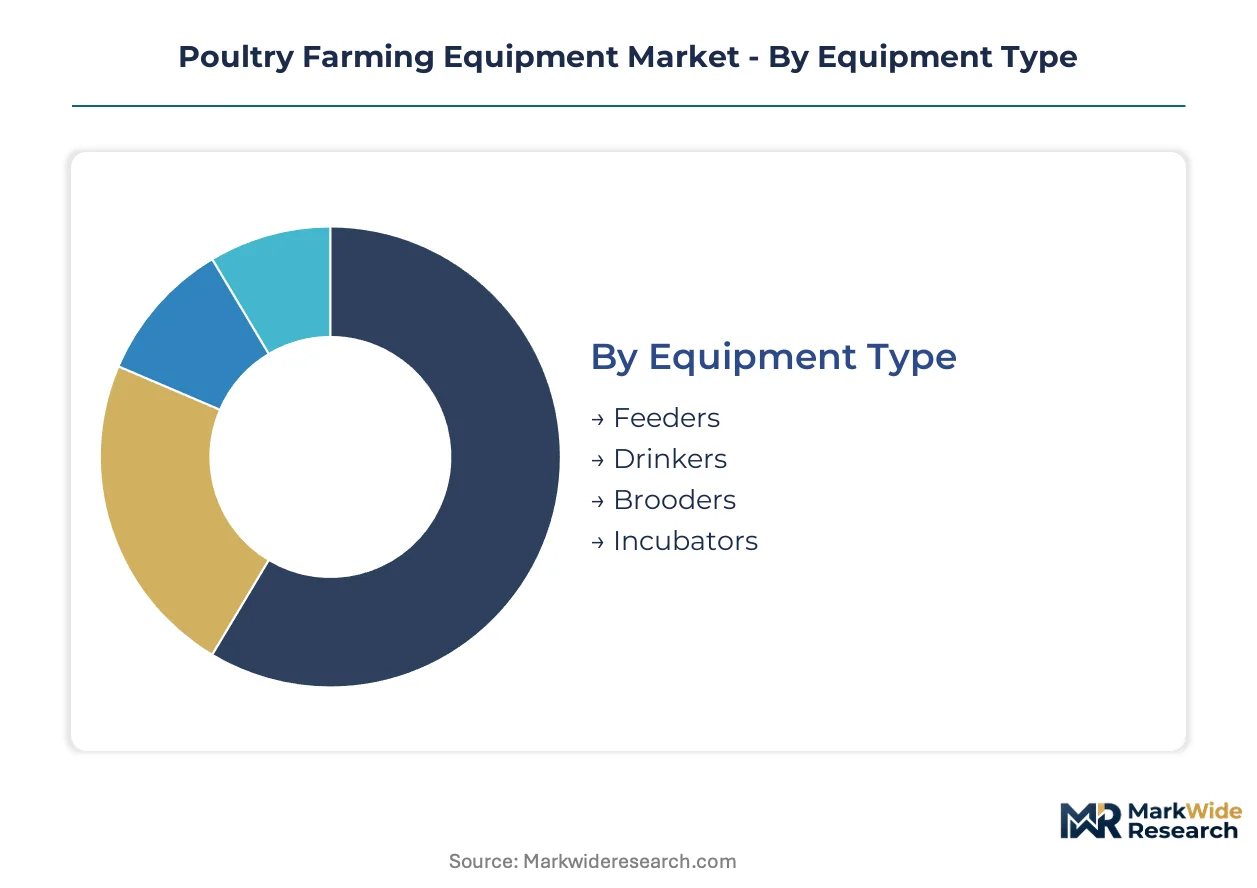
Equipment segmentation in poultry farming tracks how capital flows shift between precision hardware and connected systems. Channel strategies diverge sharply: component specialists sell through agricultural distributors, while integrated platform vendors pursue direct contracting with protein integrators.
Equipment Type:
Feeder and drinker hardware moves through regional agricultural supply chains, whereas climate systems and incubators flow via specialized HVAC and life-science distribution channels.
- Feeders:Automated chain and pan systems deliver precise rationing across broiler and layer houses. Brazilian commercial layer operations scale these systems to meet EU-aligned sanitary protocols for export-grade egg production.
- Drinkers:Nipple and cup systems engineered for minimal water waste dominate high-density broiler facilities. Southeast Asian integrators prioritize drinker precision to reduce litter moisture and ammonia emissions under tightening ASEAN veterinary standards.
- Brooders:Radiant and forced-air heating units maintain chick comfort zones during brooding phases. Small-scale operators in India source these through PLI scheme-linked equipment financing.
- Incubators:Single-stage and multi-stage setter-hatcher combinations control temperature, humidity, and turning precision for genetic stock. Hatcheries outsource temperature-humidity management to vendors under emerging incubation-as-a-service models.
By volume, feeders lead equipment shipments. By growth pace, incubators are expanding most quickly as genetic stock precision becomes a competitive differentiator.
Technology:
Technology tiering follows customer sophistication: basic automation for cost-conscious mid-scale farms, full IoT integration for export-oriented integrators, and biosecurity systems for regulatory-heavy European markets.
- Automation:Programmable feeding, egg collection, and manure removal systems reduce labor inputs. German and Dutch producers automate fastest to comply with EU Green Deal labor efficiency targets.
- IoT Solutions:Edge-computing sensor arrays for ammonia, humidity, and bird weight bypass legacy PLC architectures. Vietnamese and Thai broiler operators deploy distributed monitoring nodes that fragment traditional ventilation OEM margin pools.
- Climate Control:Ventilation, heating, and cooling systems maintain thermal comfort across stocking densities of 15–25 kg per square meter. EU F-Gas Regulation phase-down accelerates heat pump and evaporative cooling retrofits.
- Biosecurity Systems:Entry protocols, air filtration, and surface disinfection equipment protect flock health. European housing manufacturers reformulate coatings to eliminate REACH-restricted substances.
By installed base, automation dominates. By revenue momentum, IoT Solutions gain share fastest as subscription analytics replace hardware-only transactions.
End User:
End-user segmentation reveals procurement consolidation: poultry farms and hatcheries increasingly demand integrated packages, while feed manufacturers and equipment suppliers serve as channel intermediaries for component sales.
- Poultry Farms:Broiler and layer operations seeking feed conversion optimization and labor productivity. Indian mid-scale farms under PLI incentives favor climate-feeding-biosecurity packages over point solutions.
- Hatcheries:Genetic stock producers prioritizing precision temperature-humidity management. These operators shift capital expenditure toward recurring monitoring contracts with equipment vendors.
- Feed Manufacturers:Mill operators integrating on-farm feeding equipment with ration formulation software. They specify feeder compatibility during equipment procurement for integrated protein supply chains.
- Equipment Suppliers:Distributors and dealers stocking component inventory for aftermarket service. They face margin compression as direct vendor relationships with large integrators bypass traditional channels.
By contract value, poultry farms lead procurement. By contract sophistication, hatcheries show the steepest expansion trajectory toward outcome-based service agreements.
Size:
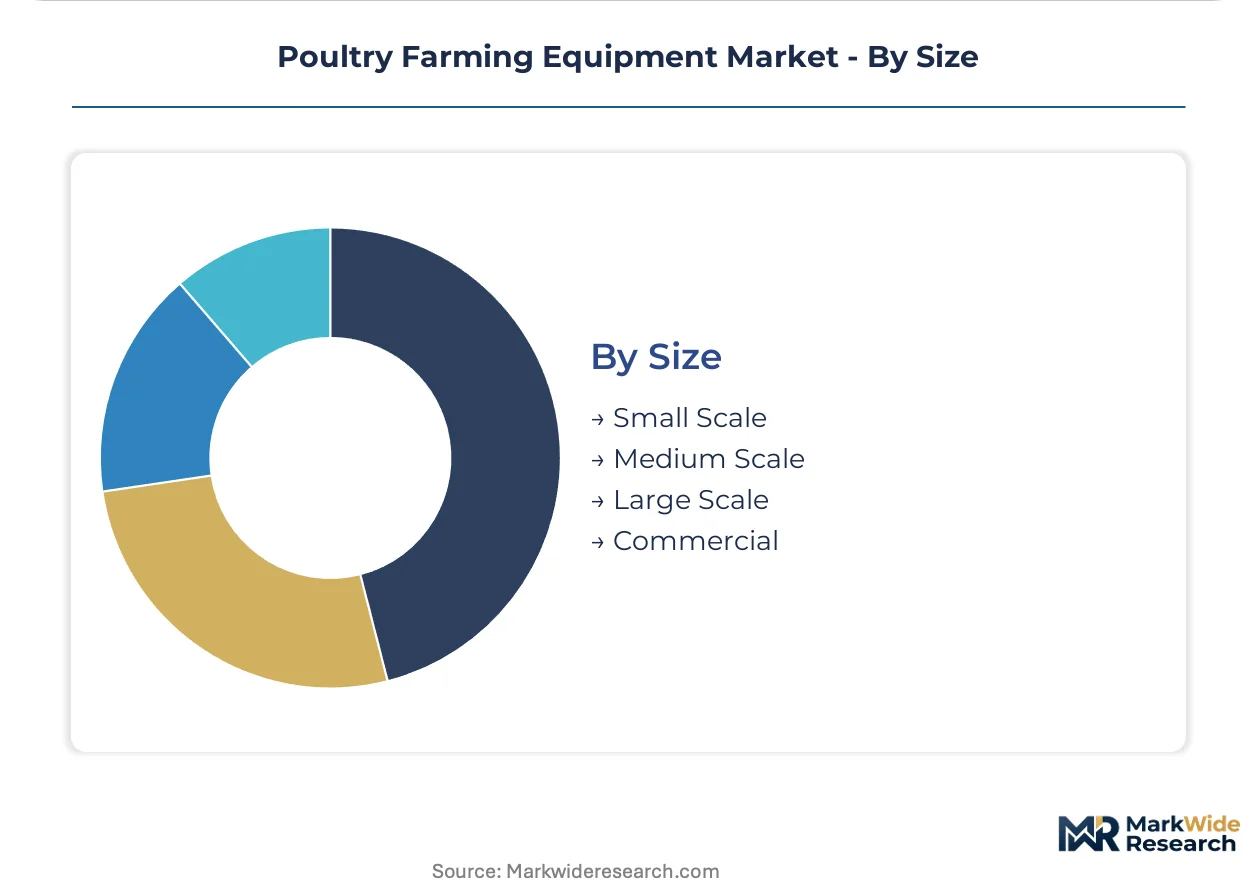
Size tiering determines system architecture: small-scale operators buy modular point solutions, while commercial integrators specify enterprise-grade integrated platforms with five-year total cost of ownership guarantees.
- Small Scale:Family farms and backyard operations with manual or semi-automated equipment. These buyers prioritize upfront affordability over precision specifications.
- Medium Scale:Regional farms modernizing under government incentive schemes. Indian PLI beneficiaries in this tier drive demand for integrated climate-feeding-biosecurity packages.
- Large Scale:Multi-house operations with dedicated technical staff. Indonesian and Philippine integrators in this segment mandate performance guarantees rather than equipment pricing alone.
- Commercial:Vertically integrated protein producers with centralized procurement and data analytics capabilities. Brazilian export-oriented layer operations in this tier scale automated systems for EU market access.
By unit shipments, medium scale leads. By technology intensity, commercial operations set the pace for IoT and automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment vendors command premium pricing in Germany and the Netherlands while Brazilian producers absorb cost compression to secure EU export access, creating a transatlantic pricing-power asymmetry that shapes regional investment patterns.
Germany
Lower-emission ventilation retrofits dominate capital deployment as producers face compressed EU Green Deal compliance windows. ECHA approval timelines for non-toxic housing coatings extend product launch cycles. The Lower Saxony poultry cluster around Oldenburg accelerates automated climate-control installations to meet farm-to-fork emission targets.
Brazil
Commercial layer operations scale automated feeding systems to align with EU-aligned sanitary protocols for premium egg export markets. ANVISA veterinary drug residue documentation requirements drive biosecurity equipment procurement. The São Paulo state integrator corridor concentrates investment in IoT-enabled flock monitoring for traceability compliance.
India
Mid-scale broiler farms under PLI scheme incentives seek integrated climate-feeding-biosecurity packages rather than point solutions. BIS equipment certification standards tighten import specifications for automated systems. The Haryana-Punjab poultry belt modernizes housing infrastructure through government-linked equipment financing schemes.
Vietnam
Edge-computing sensor arrays for ammonia and mortality tracking bypass legacy PLC architectures as integrators deploy distributed monitoring nodes. ASEAN veterinary drug residue standards tighten export compliance requirements. The Mekong Delta broiler concentration adopts modular IoT solutions to satisfy premium market access protocols.
United States
Hatcheries prioritize precision temperature-humidity management for genetic stock differentiation in concentrated production regions. USDA-FDA joint pathogen reduction rules mandate equipment sanitation documentation systems. The Georgia-Alabama poultry corridor invests in incubator upgrades to optimize feed conversion ratios across integrated supply chains.
Poultry Farming Equipment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the poultry equipment sector. European specialists dominate precision climate-control and automated egg collection segments through engineering-intensive product development. Asian fabricators compete on modular system cost structures for mid-scale farm modernization. Three archetypes define competitive positioning: integrated platform vendors supplying turnkey housing-feeding-climate packages, component specialists engineering single-function precision equipment, and regional fabricators serving price-sensitive replacement demand. Consolidation pressure intensifies as protein integrators mandate outcome-based service agreements and five-year total cost of ownership guarantees.
Within the European engineering-intensive tier, Big Dutchman and Vencomatic Group exemplify platform-scale competitors with vertical manufacturing control over multiple equipment lines. Roxell occupies a specialist position focused on precision drinking systems. These named entities anchor the competitive structure without exhausting the vendor landscape, as regional fabricators across Asia and Latin America fill volume tiers below the premium-technology threshold.
| Leading Market Players |
|---|
| Big Dutchman |
| Roxell |
| SKA |
| Tecno Poultry Equipment |
| Texha |
| Valco Industries |
| Officine Facco |
| Vencomatic Group |
| Hellmann Poultry |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal farm-to-fork mandates gate both supplier qualification and price differentiation simultaneously, as coating reformulations and ventilation retrofits force tiered certification premiums that separate compliant European producers from cost-optimized Brazilian exporters seeking EU market access.
Pricing Analysis
Configured-to-order pricing for integrated climate-feeding-biosecurity packages commands substantial premiums over standard pan-feeder and nipple-drinker hardware. Price differentiation hinges on CE marking tier and volume scale, with large Indonesian and Philippine integrators extracting performance guarantees that compress margins for component suppliers. Cost compression in standard equipment tiers intensifies as Asian fabricators absorb commodity steel volatility. Small-scale Indian farms under PLI financing show highest price sensitivity, while German commercial operators prioritize compliance-grade specifications regardless of premium.
Supply Chain Analysis
Strategic stockpiling of precision sensors and variable-frequency drives dominates inventory strategy as East Asian manufacturing concentration creates single-source vulnerability for climate-control automation. Supply draws from China, Germany, and the Netherlands for core components, with steel and aluminum inputs tethered to volatile commodity markets. Tariff exposure on precision electronics fragments margin pools for ventilation OEMs. Distribution runs through agricultural distributors for feeder hardware and specialized HVAC channels for climate systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IoT-enabled flock monitoring is reshaping competitive positioning as Southeast Asian integrators modernize facilities under tightening ASEAN veterinary drug residue standards, creating a high-growth disruption window for connected equipment platforms.
For Market Incumbents: Shield installed base relationships by embedding outcome-based service agreements that absorb performance risk from protein integrators demanding five-year total cost of ownership guarantees. Deepen backward integration into precision sensor manufacturing to reduce East Asian single-source exposure. Prioritize certification investment for EU Green Deal coating compliance to defend premium positioning against Asian cost competitors. For New Entrants and Emerging Players: CE marking fast-track for climate-control retrofits opens white-space entry into German and Dutch compliance windows where ECHA approval timelines delay incumbent product launches. Target mid-scale Indian broiler farms under PLI scheme incentives with modular IoT sensor arrays that bypass legacy PLC architectures. Pursue direct contracting with Vietnamese integrators adopting distributed monitoring nodes for ammonia tracking. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down reshapes the acquisition landscape toward heat pump and evaporative cooling specialists positioned for mandatory hydrofluorocarbon replacement subsidy pools. Long-term viability centers on platform vendors with recurring monitoring contract revenue rather than hardware-only transactions. Monitor ANVISA veterinary documentation requirements as the signal to watch for Brazilian equipment procurement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive supply of precision ammonia and humidity sensors reduces East Asian single-source vulnerability for climate OEMs. |
| Outcome-Based Service Agreement Rollout | Performance guarantees align vendor incentives with Indonesian integrator demands for feed conversion optimization. |
| CE Marking Fast-Track Investment | Accelerated certification timelines exploit ECHA approval delays to penetrate German Green Deal compliance windows. |
| Incubation-as-a-Service Platform Launch | Recurring monitoring contracts shift hatchery revenue from capital expenditure to subscription analytics. |
| PLI Scheme Partnership in India | Government-linked financing access opens mid-scale farm modernization demand for integrated equipment packages. |
Study Parameters
The analysis maps feeding equipment, climate systems, IoT automation, and biosecurity infrastructure, each validated through equipment procurement managers at protein integrators, plant engineers at hatcheries, aftermarket service heads at distributors, and regulatory compliance officers. Primary interviews combined with secondary validation from EU Green Deal policy documents, ANVISA veterinary residue guidelines, ASEAN sanitary protocol filings, and BIS equipment certification standards. Bottom-up equipment shipment data triangulates against top-down protein production forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include equipment type, technology tier, end-user category, and farm scale. CAGRs derived from regression analysis of capital expenditure patterns correlated with regulatory compliance timelines and government incentive scheme disbursements. Industry-specific inputs incorporate PLI scheme uptake rates and EU F-Gas phase-down schedules.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory tightening without grandfathering provisions; material deviation would warrant model refresh. Forecasts reflect assumptions of continued steel and aluminum commodity volatility and ASEAN veterinary standard harmonization. Revision becomes warranted when REACH chemical approval timelines or PLI scheme funding allocations cross thresholds that alter equipment replacement cycle economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poultry Farming Equipment
Poultry Brooder Market
Poultry Farming Equipment
Commercial Chicken Plucker Market
Poultry Farming Equipment
Poultry Plucker Market
Poultry Farming Equipment
Automated Poultry Farm Market
Poultry Farming Equipment
Egg Grading Machines Market
Poultry Farming Equipment
Rabbit Cages Market
Poultry Farming Equipment
Duck Plucker Machine Market
Poultry Farming Equipment
Poultry House Ventilation System Market
Poultry Farming Equipment
Multi-Layer Poultry Cage Market
Poultry Farming Equipment
Poultry Keeping Machinery Market
Poultry Farming Equipment
Asia Pacific Poultry Market
Poultry Farming Equipment
Poultry Incubator Market
Poultry Farming Equipment
Poultry Brooders, Feeders, and Waterers Market
Poultry Farming Equipment
Egg Breaking Machine Market
Poultry Farming Equipment
Turkey Poultry Market