
 Poultry Brooders, Feeders, and Waterers Market | 2026-2036
Poultry Brooders, Feeders, and Waterers Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Brooders, Feeders, and Waterers Market Analysis
Contract growers and integrated poultry operations is redrawing procurement patterns across the equipment supply base. Big Dutchman International GmbH leverages its vertical manufacturing footprint to serve large-scale barn installations across multiple continents. Roxell BVBA anchors its position through specialized feeding systems engineered for high-density layer operations. TEXHA PA LLC competes on automated climate-controlled brooder lines that reduce manual intervention.
Poultry brooders, feeders, and waterers comprise climate-controlled heating units, feed distribution mechanisms, and hydration systems constructed from galvanized steel, UV-stabilized polyethylene, or fiberglass-reinforced composites, designed to maintain biosecurity and optimize feed conversion ratios in confined animal feeding operations. Plastic dominates material selection for waterers and feeders due to corrosion resistance and ease of sanitation, though metal persists in high-wear brooder frames. Automated technology leads product development as sensor-integrated systems reduce mortality rates and labor dependency, while manual equipment retains share among backyard poultry keepers and smaller agricultural cooperatives with limited capital budgets.
USDA biosecurity guidelines and EPA waste management standards shape equipment design specifications for American producers, while EFSA hygiene mandates and CE marking requirements govern European market access. Brazil's national agricultural regulator enforces sanitary protocols that favor equipment with smooth surfaces and minimal pathogen harborage points. Stakeholders must weigh automation investment cycles against evolving veterinary drug residue rules that alter flock management protocols.
Market Dynamics
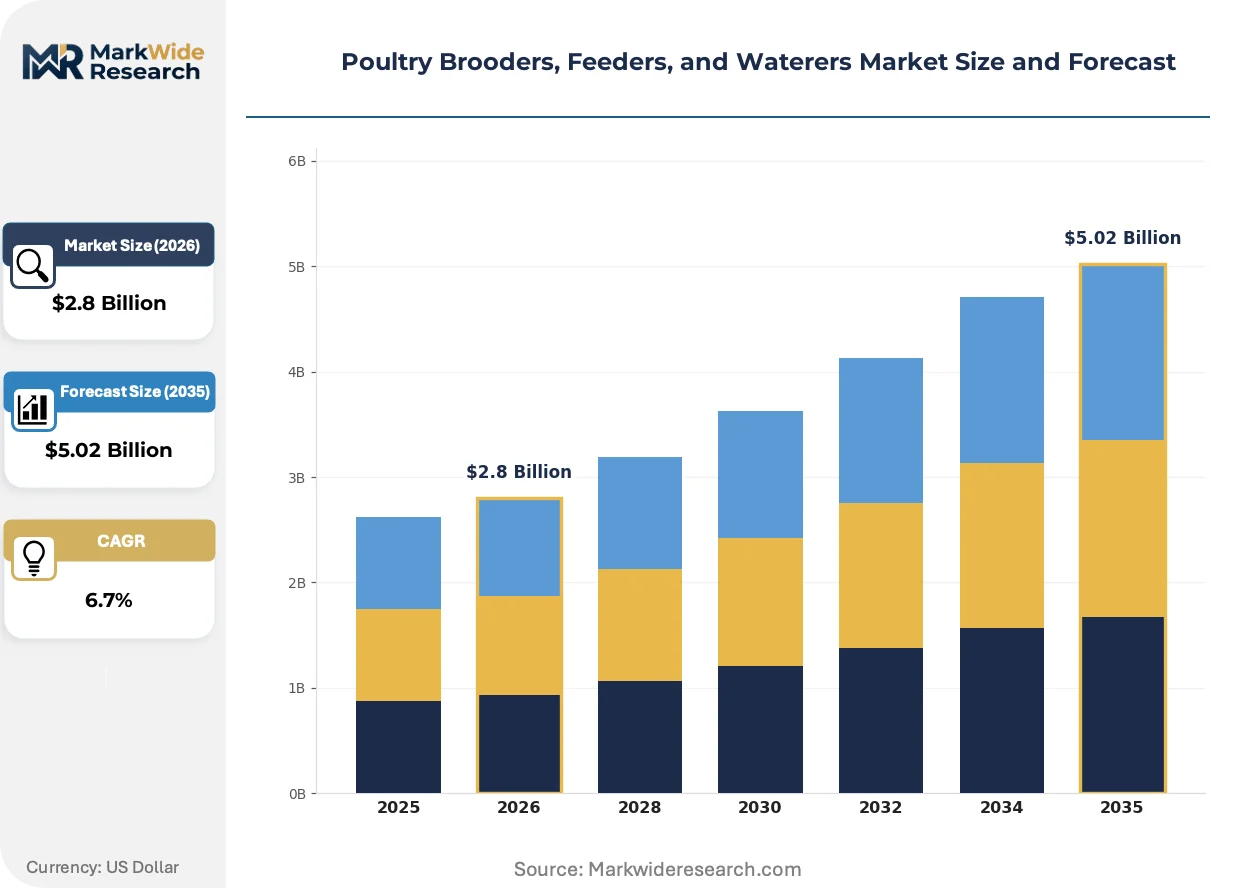
Automated feeding and climate control systems are compressing procurement cycles as commercial poultry operations consolidate supplier relationships around integrated equipment suites that reduce labor dependency and mortality rates.
Growth Catalysts
- EFSA Hygiene Mandates:European Union directives on equipment sanitation are forcing upgrades to smooth-surface, pathogen-resistant designs across broiler and layer operations.
- Sensor-Integrated Climate Control:IoT-enabled brooder systems reduce manual intervention and mortality through real-time temperature and humidity monitoring.
- Brazil's Southern Poultry Belt:Integrated producers in Paraná and Santa Catarina are modernizing infrastructure, driving concentrated demand for automated feeding lines.
Market Restraints
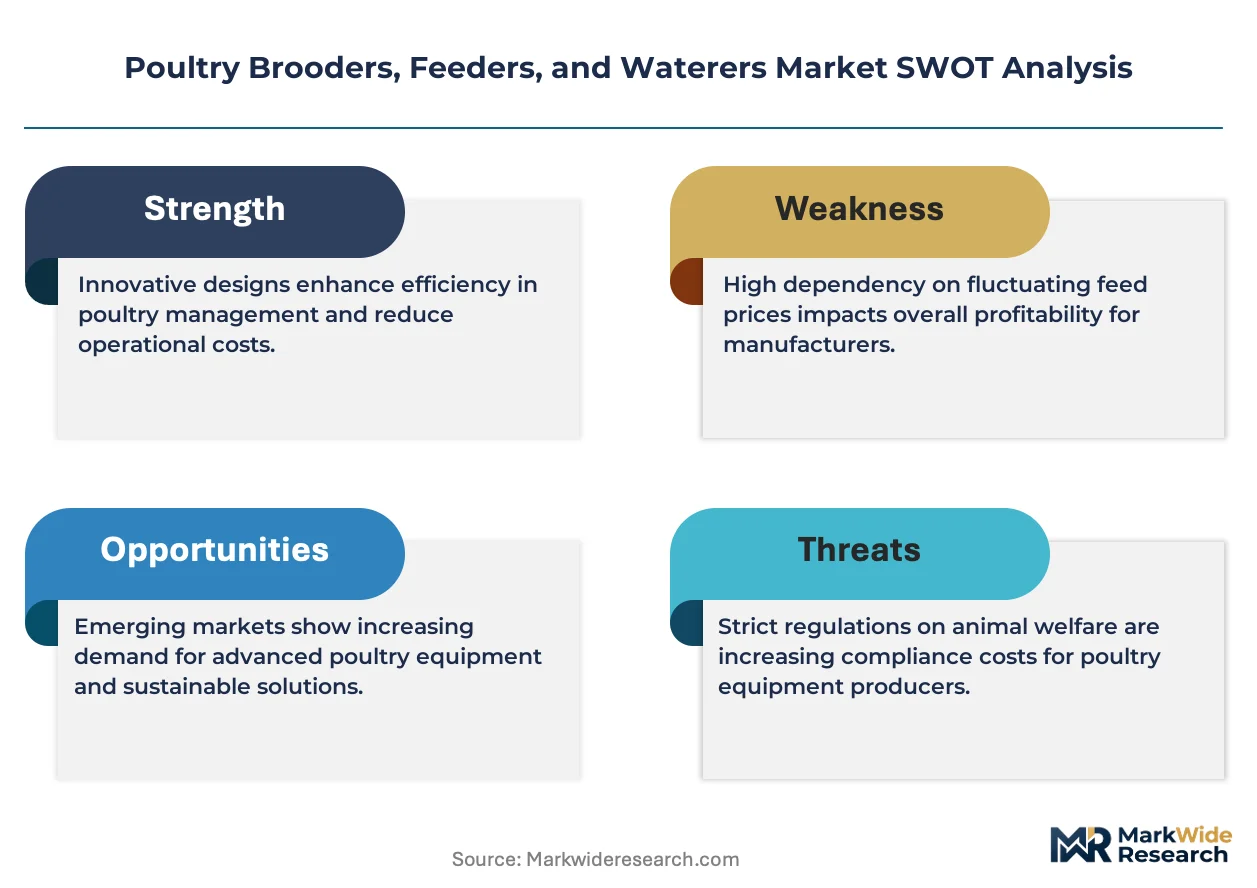
- Galvanized Steel Price Volatility:Input cost swings for metal brooder frames squeeze margins for equipment manufacturers dependent on commodity supply chains.
- High Capex for Automation:Smallholder cooperatives and backyard poultry keepers lack capital budgets for sensor-integrated systems, capping addressable market expansion.
- Sanitary Protocol Complexity:Divergent national veterinary directives across export markets force redundant certification cycles that extend product launch timelines.
Strategic Opportunities
- India's Contract Growing Expansion:Untapped penetration in integrated poultry operations offers white space for automated feeder and waterer deployment.
- USDA Biosecurity Alignment:Equipment designed to meet federal guidelines gains preferential access to large-scale American producers seeking audit compliance.
- UV-Stabilized Polyethylene Convergence:Advanced plastics meeting both corrosion resistance and pathogen control requirements open premium positioning in high-density operations.
Industry Challenges
- Electromechanical Technician Scarcity:Automated climate control systems require specialized maintenance skills that rural poultry regions struggle to source.
- Legacy Barn Retrofit Complexity:Older facilities face structural constraints when integrating modern feeding lines, forcing costly infrastructure overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Brooders, Feeders, and Waterers Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brooders, Feeders, Waterers, Automatic Systems End User: Poultry Farms, Commercial Breeders, Backyard Poultry Keepers, Agricultural Cooperatives Material: Plastic, Metal, Wood, Composite Technology: Manual, Automated, Solar-Powered, Smart Technology |
| Companies Covered | Farmer Automatic GmbH & Co. KG, Roxell BVBA, Big Dutchman International GmbH, TEXHA PA LLC, VAL-CO Companies, Inc., GQF Manufacturing Company, Ziggity Systems, Inc., Officine Facco & C. S.p.A., Cumberland Poultry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Brooders, Feeders, and Waterers Market Emerging Trajectories
Equipment architecture is splitting between premium automated suites for industrial operations and simplified manual systems for capital-constrained producers, reshaping how manufacturers structure product portfolios and channel strategies.
Sensor-integrated feeding systems is bifurcating the supplier landscape. These platforms combine weight-based dispensers with cloud-connected analytics to optimize feed conversion ratios. Large-scale integrated operations in Brazil and the United States are adopting them at accelerated rates. The technology is bifurcating procurement patterns, as buyers consolidate around full-system vendors rather than assembling components from fragmented suppliers.
EPA waste management standards are tightening design specifications for American producers. Rules on effluent and nutrient runoff now govern material selection and drainage geometry in waterer systems. Broiler operations in the Southeastern United States are responding by specifying equipment with integrated waste separation features that preempt regulatory enforcement.
Integrated service contracts are displacing transactional equipment sales in commercial poultry. Buyers now expect suppliers to bundle installation, calibration, and mortality-rate guarantees with hardware purchases. This shift concentrates purchasing authority at the corporate level of integrated producers, reducing autonomy among individual contract growers in Brazil's southern states.
Poultry Brooders, Feeders, and Waterers Market Segmentation
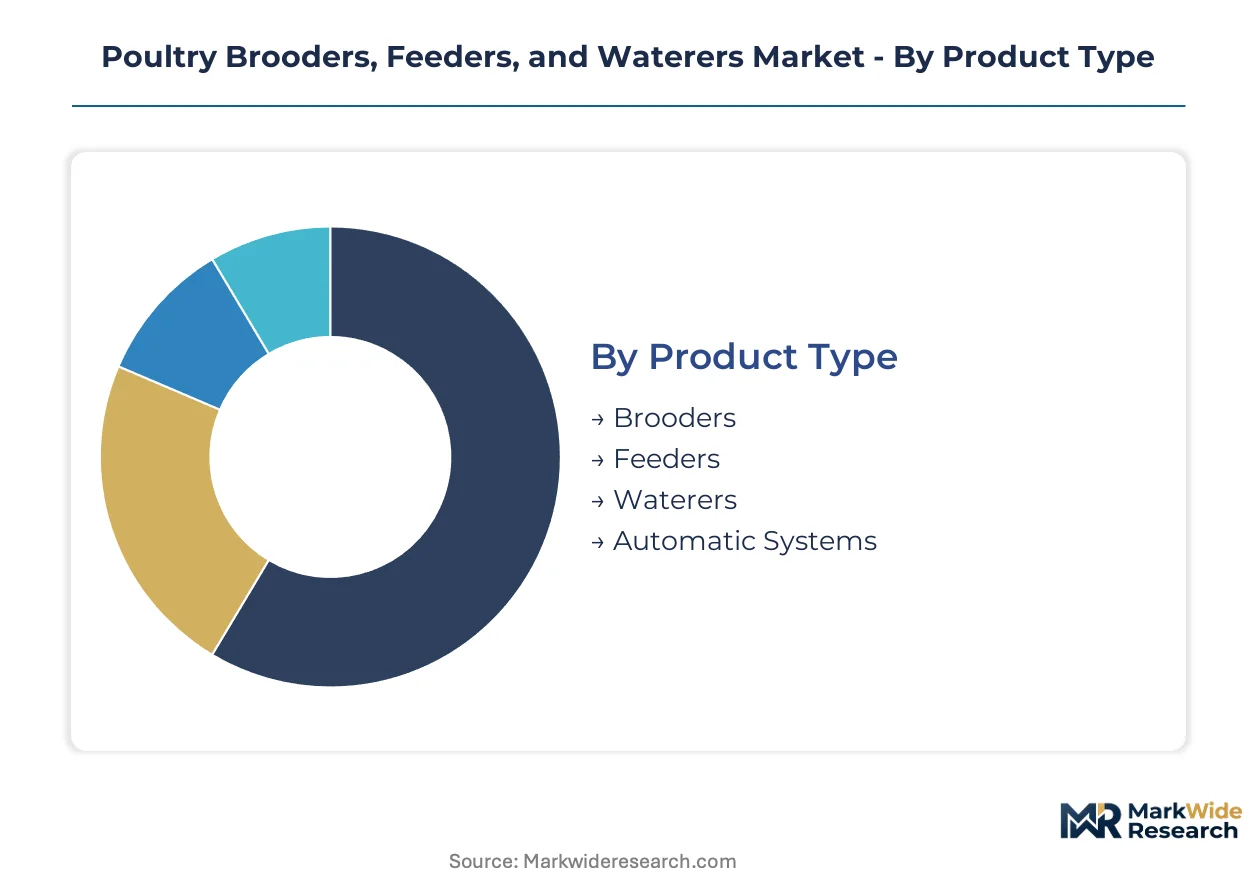
Equipment suppliers must align product portfolios with divergent capital capacities and biosecurity requirements across poultry operation scales. Channel strategies differ sharply between integrated commercial systems and decentralized smallholder markets.
Product Type:
Brooders and climate systems flow through specialized agricultural distributors serving large barn installations, while feeders and waterers reach backyard keepers through farm supply retailers and online channels.
- Brooders:Climate-controlled heating units constructed from galvanized steel or fiberglass-reinforced composites maintain precise temperature zones for chick development. Demand concentrates in Brazil's southern poultry belt where integrated producers modernize broiler house infrastructure to reduce mortality rates.
- Automatic Systems:Sensor-integrated platforms combining climate control, feed distribution, and hydration monitoring through cloud-connected analytics optimize feed conversion ratios. Commercial breeders across multiple continents adopt these suites to compress labor dependency and meet tightening veterinary drug residue protocols.
- Feeders:Gravity-fed and mechanized distribution mechanisms constructed from UV-stabilized polyethylene or metal serve high-density layer operations with corrosion-resistant surfaces that ease EFSA-mandated sanitation cycles.
- Waterers:Nipple drinkers, bell drinkers, and cup systems engineered for minimal pathogen harborage points comply with Brazilian national agricultural regulator sanitary protocols favoring smooth-surface designs.
Brooders dominate installed base through replacement cycles tied to barn infrastructure lifespan. Automatic systems are where expansion concentrates as labor costs rise and mortality guarantees become procurement requirements.
End User:
Cost tier stratification separates capital-intensive integrated operations from equipment categories accessible to limited-budget producers.
- Commercial Breeders:Large-scale integrated operations procure full-system suites through direct manufacturer relationships, bundling installation and calibration with mortality-rate guarantees. These buyers consolidate supplier relationships around vendors capable of multi-continent barn installation support.
- Poultry Farms:Mid-scale operations balance automation investment against flock size, often selecting semi-automated feeding lines that reduce manual intervention without requiring specialized electromechanical technician maintenance.
- Agricultural Cooperatives:Capital-pooled purchasing enables shared access to automated climate control systems that individual members could not finance independently, particularly in India's expanding contract growing regions.
- Backyard Poultry Keepers:Manual equipment dominates this price-sensitive segment where simplified feeders and waterers serve small flocks with minimal biosecurity infrastructure.
Commercial breeders command premium pricing through integrated service contracts. Agricultural cooperatives are gaining share fastest as contract growing models spread into underpenetrated markets.
Material:
Application environment dictates material selection between corrosion resistance, durability, and sanitation compliance requirements.
- Plastic:UV-stabilized polyethylene dominates waterer and feeder construction due to corrosion resistance, lightweight handling, and ease of sanitation meeting EFSA hygiene mandates. The material's smooth surfaces minimize pathogen harborage points required by Brazilian sanitary protocols.
- Metal:Galvanized steel persists in high-wear brooder frames and structural components where mechanical stress exceeds plastic tolerance, though price volatility squeezes manufacturer margins.
- Composite:Fiberglass-reinforced materials serve premium climate-controlled units combining thermal insulation with structural rigidity in high-density operations.
- Wood:Limited to manual systems in backyard and small cooperative settings where capital constraints override durability and biosecurity considerations.
Plastic commands volume leadership across automated and manual equipment lines. Composite materials are climbing the fastest as premium positioning aligns with integrated producer procurement consolidation.
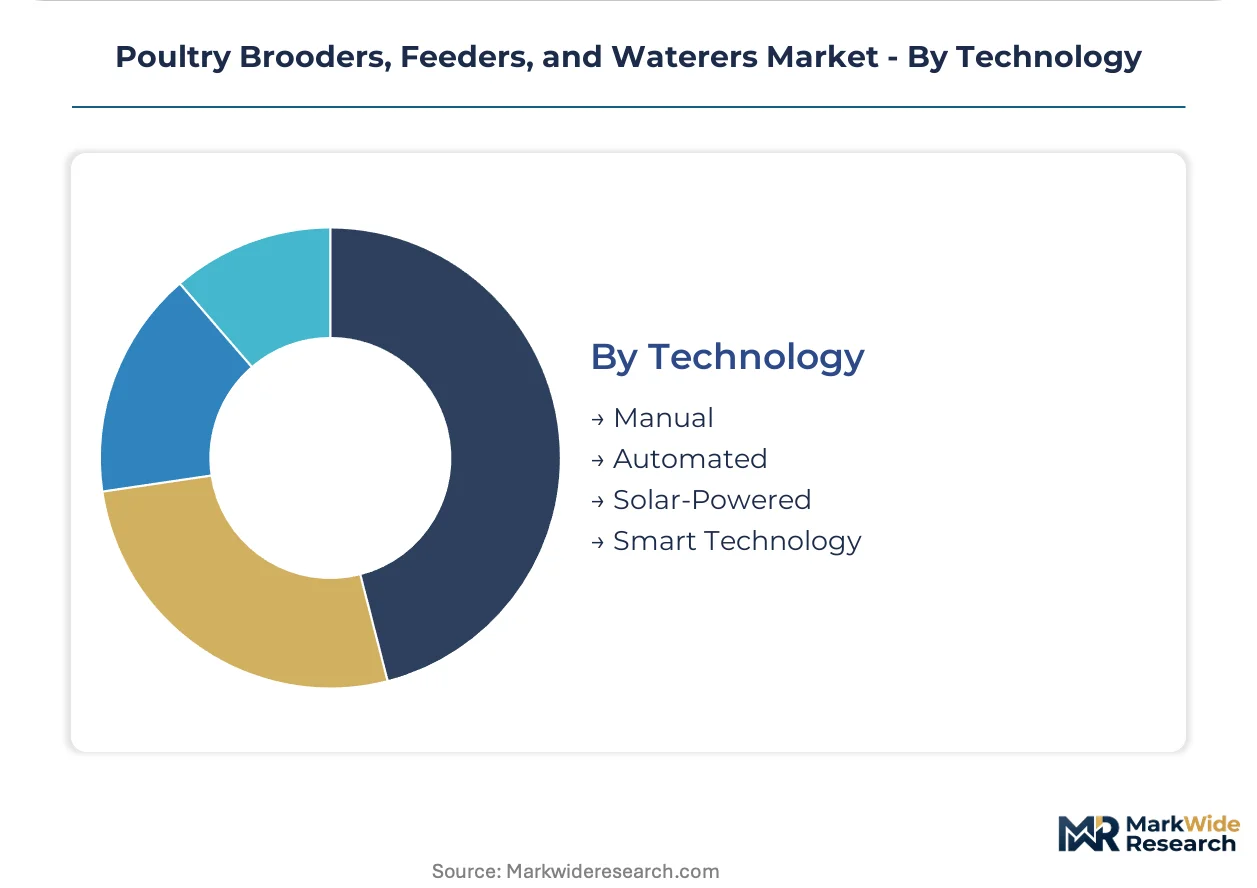
Technology:
Customer type and operational scale determine technology tier penetration, with rural infrastructure constraints limiting advanced system deployment.
- Automated:IoT-enabled platforms integrating weight-based dispensers, climate sensors, and cloud analytics reduce manual intervention and mortality through real-time monitoring. These systems concentrate in Brazil's southern states and large-scale US operations where corporate purchasing authority overrides individual grower autonomy.
- Manual:Gravity-fed and mechanically simple equipment retains substantial share among backyard poultry keepers and smaller agricultural cooperatives with limited capital budgets and minimal biosecurity infrastructure.
- Smart Technology:AI-enhanced systems with predictive analytics for feed optimization and disease early warning represent emerging deployment in most technologically advanced integrated operations.
- Solar-Powered:Off-grid climate control and feeding systems address electromechanical technician scarcity in rural poultry regions with unreliable electrical infrastructure.
Manual technology retains installed base dominance across developing market smallholders. Automated systems are expanding most quickly as labor costs rise and mortality guarantees reshape procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian equipment manufacturers export automated climate-control systems to integrated poultry operations across the United States and European Union markets. These trade corridors channel premium brooder technology toward large-scale barn installations while manual equipment flows to smallholder markets in India and Southeast Asia.
United States
USDA biosecurity guidelines and EPA waste management standards drive equipment upgrades across the Southeastern broiler belt. Large-scale operations in Georgia and Arkansas specify sensor-integrated feeding lines that meet federal audit compliance requirements. Corporate procurement consolidation concentrates purchasing authority at headquarters in Springdale, Arkansas and other poultry industry hubs.
Brazil
Integrated producers in Paraná and Santa Catarina modernize broiler house infrastructure to reduce mortality rates and labor dependency. ANVISA sanitary protocols favor equipment with smooth surfaces and minimal pathogen harborage points. The southern poultry belt around Chapecó and Cascavel anchors concentrated demand for automated climate-controlled brooder lines.
Germany
EFSA hygiene mandates and CE marking requirements govern equipment design for layer operations across Lower Saxony and Bavaria. Manufacturers adapt feeding systems to meet REACH-compliant material specifications and corrosion-resistant sanitation cycles. The Oldenburg Münsterland region hosts dense layer farm clusters adopting premium automated suites.
India
Contract growing expansion in Telangana and Andhra Pradesh creates white space for automated feeder deployment among capital-pooled agricultural cooperatives. FSSAI sanitary protocols and state-level veterinary directives shape equipment specifications for integrated operations. The Coimbatore-Salem corridor in Tamil Nadu concentrates small-scale poultry equipment fabrication serving regional cooperatives.
China
GB standards and MIIT industrial policies accelerate automated system adoption in Shandong and Jiangsu poultry belts. Domestic manufacturers supply climate-controlled brooders to large-scale operations facing rising rural labor costs. The Weifang cluster in Shandong Province anchors concentrated feed equipment production serving both domestic and export markets.
Poultry Brooders, Feeders, and Waterers Market Vendor Landscape
Listed leaders compete with private specialists across automation depth and geographic reach, creating a tiered structure where scale-driven multinationals serve integrated producers while regional fabricators capture smallholder segments. Strategic archetypes separate full-system integrators, specialized component manufacturers, and regional equipment assemblers. Competitive moves concentrate on backward integration into galvanized steel and polymer supply chains alongside geographic expansion through distributor partnerships in underpenetrated contract growing regions.
Among German-based full-system integrators, Big Dutchman International GmbH exemplifies the multinational archetype serving multi-continent barn installations, while Roxell BVBA represents specialized feeding system engineering for high-density operations. TEXHA PA LLC occupies a position among automated climate-control specialists reducing manual intervention through sensor-integrated brooder lines. These three anchors illustrate how competitive positioning splits between comprehensive platform vendors and focused technology specialists.
| Leading Market Players |
|---|
| Farmer Automatic GmbH & Co. KG |
| Roxell BVBA |
| Big Dutchman International GmbH |
| TEXHA PA LLC |
| VAL-CO Companies, Inc. |
| GQF Manufacturing Company |
| Ziggity Systems, Inc. |
| Officine Facco & C. S.p.A. |
| Cumberland Poultry |
| Others |
Supply Flow & Price Mechanics
EFSA hygiene mandates and CE marking requirements gate both supplier qualification and price differentiation in European markets, forcing equipment manufacturers to absorb certification costs that stratify offerings across regulatory tiers while compressing margins for non-compliant fabricators.
Pricing Analysis
Current-generation automated climate-control suites command substantial premiums over prior-generation mechanized systems and economy-tier manual equipment. Three-tier pricing structure across premium sensor-integrated, standard semi-automated, and economy manual levels reflects divergence in mortality-rate guarantees and after-sales service bundling. Price differentiation hinges on certification grade—CE-marked and EFSA-compliant equipment fetches premiums—and volume scale from integrated producers. Pricing pressure stems from galvanized steel cost volatility squeezing metal-frame manufacturers. Backyard poultry keepers exhibit highest price sensitivity, while commercial breeders prioritize total cost of ownership over unit price.
Supply Chain Analysis
Strategic stockpiling of UV-stabilized polyethylene and galvanized steel dominates inventory strategy among large equipment manufacturers, buffering against commodity price swings that would disrupt just-in-time assembly schedules. Supply concentrates in China for polymer feedstock and precision electronics, Germany for engineered climate-control components, and Brazil for regional metal fabrication serving South American markets. Raw material dependencies include petroleum-derived plastics, zinc-coated steel, and IoT sensor modules. Single-source vulnerability in semiconductor components for automated systems poses structural risk. Distribution runs through specialized agricultural equipment distributors for commercial operations and farm supply retailers for smallholder segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting as integrated producers consolidate procurement around full-system vendors capable of bundling hardware, installation, and mortality guarantees, mirroring ecosystem shifts seen in precision agriculture equipment markets.
For Market Incumbents: Secure captive supply of galvanized steel and UV-stabilized polyethylene through backward integration or long-term offtake agreements to defend margins against commodity volatility. Deepen firmware and cloud-analytics capabilities to raise switching costs as sensor-integrated platforms become procurement requirements among Brazilian and American integrated producers.
For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany or the Netherlands accelerates European market access ahead of capital-intensive certification cycles that deter regional fabricators. Target India's contract growing cooperatives in Telangana and Andhra Pradesh with solar-powered climate-control systems addressing electromechanical technician scarcity and unreliable grid infrastructure.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated brooder and feeding system manufacturing as IoT development and multi-continent service networks require sustained R&D deployment. Acquisition targets should exhibit established distributor relationships in Brazil's southern poultry belt or proprietary climate-control algorithms. Watch for inflection when mortality-rate guarantee clauses become standard in procurement specifications, signaling tipping point toward full-system vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Supply | Captive UV-stabilized polyethylene production insulates margins from petrochemical volatility and EFSA compliance costs. |
| Sensor-Integrated Platform Launch | IoT-enabled climate and feeding systems command premium positioning among Brazilian integrated producers modernizing infrastructure. |
| CE Marking Fast-Track Investment | Accelerated European regulatory approval opens premium tier before competitors complete multi-cycle certification. |
| Service Contract Bundling | Integrated installation and mortality guarantees concentrate purchasing authority at corporate headquarters of large operations. |
| Solar-Powered System Development | Off-grid climate control addresses technician scarcity and infrastructure gaps in India's expanding contract growing regions. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of USDA biosecurity guidelines, EFSA hygiene mandates, ANVISA sanitary protocols, and trade data from agricultural equipment customs classifications. Primary interviews incorporated perspectives from commercial breeder procurement directors, agricultural cooperative managers, electromechanical maintenance technicians, and farm supply retail buyers. Secondary sources included equipment manufacturer technical specifications, veterinary directive filings, and commodity price indices for galvanized steel and petroleum-derived plastics. Bottom-up demand modeling from flock size and replacement cycles triangulated against top-down market sizing from equipment shipment values.
Segmentation dimensions modeled span product type, end-user scale, material composition, and technology tier across the projection horizon. The analytical framework incorporated capital expenditure cycles of integrated producers, labor cost trajectories in major poultry-producing regions, and regulatory compliance timelines. CAGRs derived from equipment replacement rates, barn infrastructure investment patterns, and automation penetration curves. Industry-specific inputs included mortality-rate guarantee adoption thresholds and electromechanical technician availability indices.
Decision-makers should treat outputs as directional under assumptions of continued labor cost escalation and stable regulatory enforcement intensity; material deviation would warrant model refresh. Specific risks include abrupt shifts in veterinary drug residue protocols altering flock management equipment specifications, trade policy changes affecting steel and polymer input costs, and electrification infrastructure delays in rural poultry regions. Revision becomes warranted when integrated producer consolidation crosses thresholds that fundamentally reshape procurement authority structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poultry Farming Equipment
Automated Poultry Farm Market
Poultry Farming Equipment
Poultry Plucker Market
Poultry Farming Equipment
Rabbit Cages Market
Poultry Farming Equipment
Multi-Layer Poultry Cage Market
Poultry Farming Equipment
Poultry Keeping Machinery Market
Poultry Farming Equipment
Poultry Incubator Market
Poultry Farming Equipment
Poultry Brooder Market
Poultry Farming Equipment
Egg Grading Machines Market
Poultry Farming Equipment
Asia Pacific Poultry Market
Poultry Farming Equipment
Commercial Chicken Plucker Market
Poultry Farming Equipment
Turkey Poultry Market
Poultry Farming Equipment
Poultry Farming Equipment Market
Poultry Farming Equipment
Duck Plucker Machine Market
Poultry Farming Equipment
Egg Breaking Machine Market
Poultry Farming Equipment
Poultry House Ventilation System Market