
 Commercial Chicken Plucker Market | 2026-2036
Commercial Chicken Plucker Market Size, Share, and Industry Trends Forecast 2026-2036
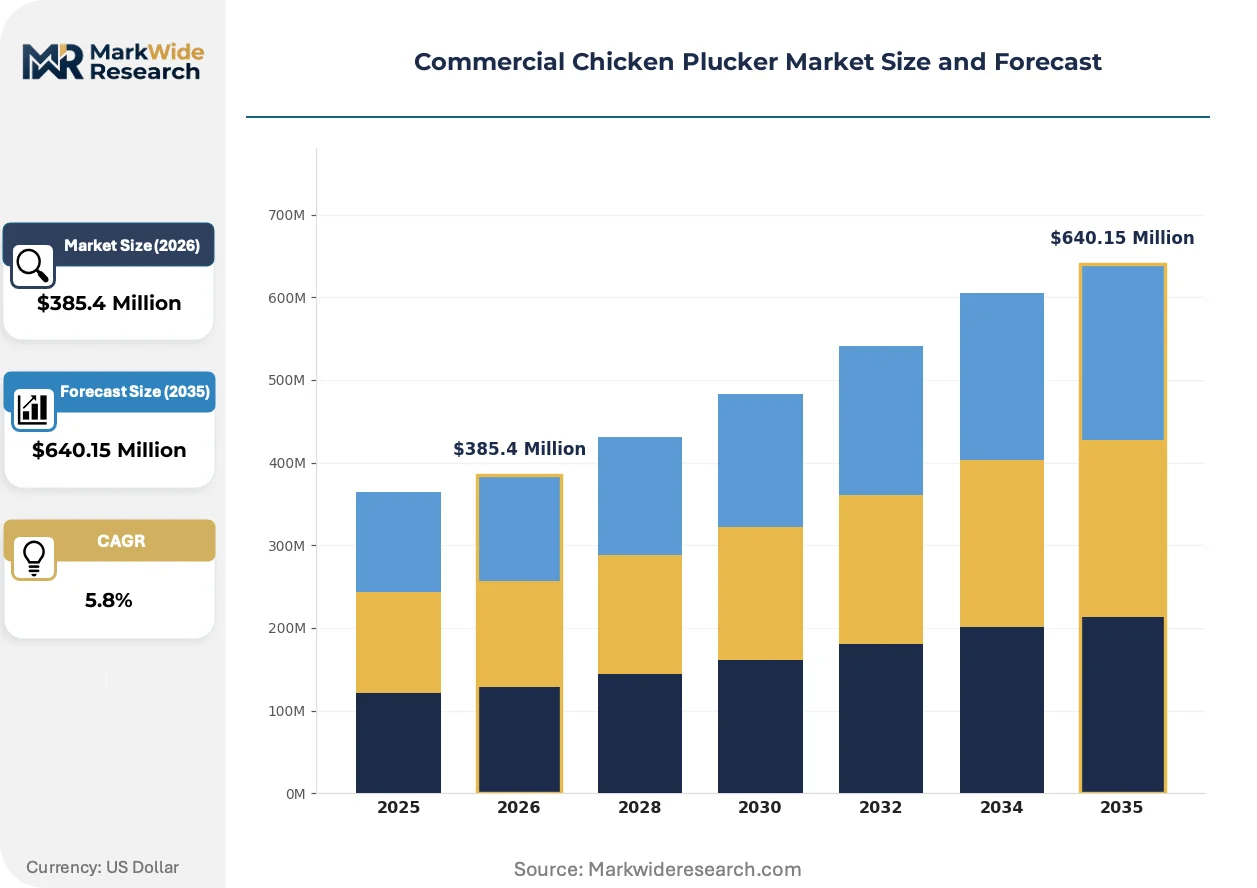
Commercial Chicken Plucker Market Outlook
The dealer-direct channel is narrowing as e-commerce platforms and manufacturer portals capture mid-size poultry farm orders. Meyn Food Processing Technology B.V. leverages its European engineering base to sustain premium positioning in automated lines. Marel anchors North American supply through integrated processing system bundles. Zhucheng Xinhaoyun Machinery Co., Ltd. competes on cost-engineered units for emerging markets.
A commercial chicken plucker is a motorized or hand-operated device with rubber fingers mounted on a rotating drum or disk, designed to remove feathers from slaughtered birds through abrasive contact at 150-300 RPM. The equipment serves poultry processing operations by reducing labor hours and improving hygiene consistency over manual plucking. Electric plucker units lead volume sales due to throughput advantages in mid-scale facilities, while industrial plucker configurations command margin pools from meat processing plants requiring continuous-line integration. Rotary mechanism technology dominates installed bases, though hybrid systems incorporating pneumatic assist are gaining traction where water conservation regulations tighten.
USDA poultry inspection standards and FDA Hazard Analysis Critical Control Point rules shape equipment sanitation design, mandating stainless steel contact surfaces and clean-in-place compatibility. OSHA workplace safety directives influence guarding and noise specifications for plant installations. Stakeholders must weigh capital intensity against labor arbitrage as automation thresholds shift with minimum wage trajectories and processing volume consolidation.
Market Dynamics
Water conservation mandates are compressing plucker design specifications as processors face effluent discharge limits and rising utility tariffs across poultry-producing regions.
Growth Catalysts
- USDA Sanitation Mandates:Stainless steel contact surface requirements are forcing equipment upgrades at mid-scale facilities, expanding replacement demand for compliant rotary drum systems.
- Labor Arbitrage Collapse:Rising minimum wage trajectories in processing-heavy states are accelerating payback calculations for automated plucking lines versus manual labor pools.
- Continuous-Line Integration:Meat processing plants are standardizing on industrial plucker configurations that feed directly into evisceration and chilling tunnels, reducing handling contamination risks.
Market Restraints
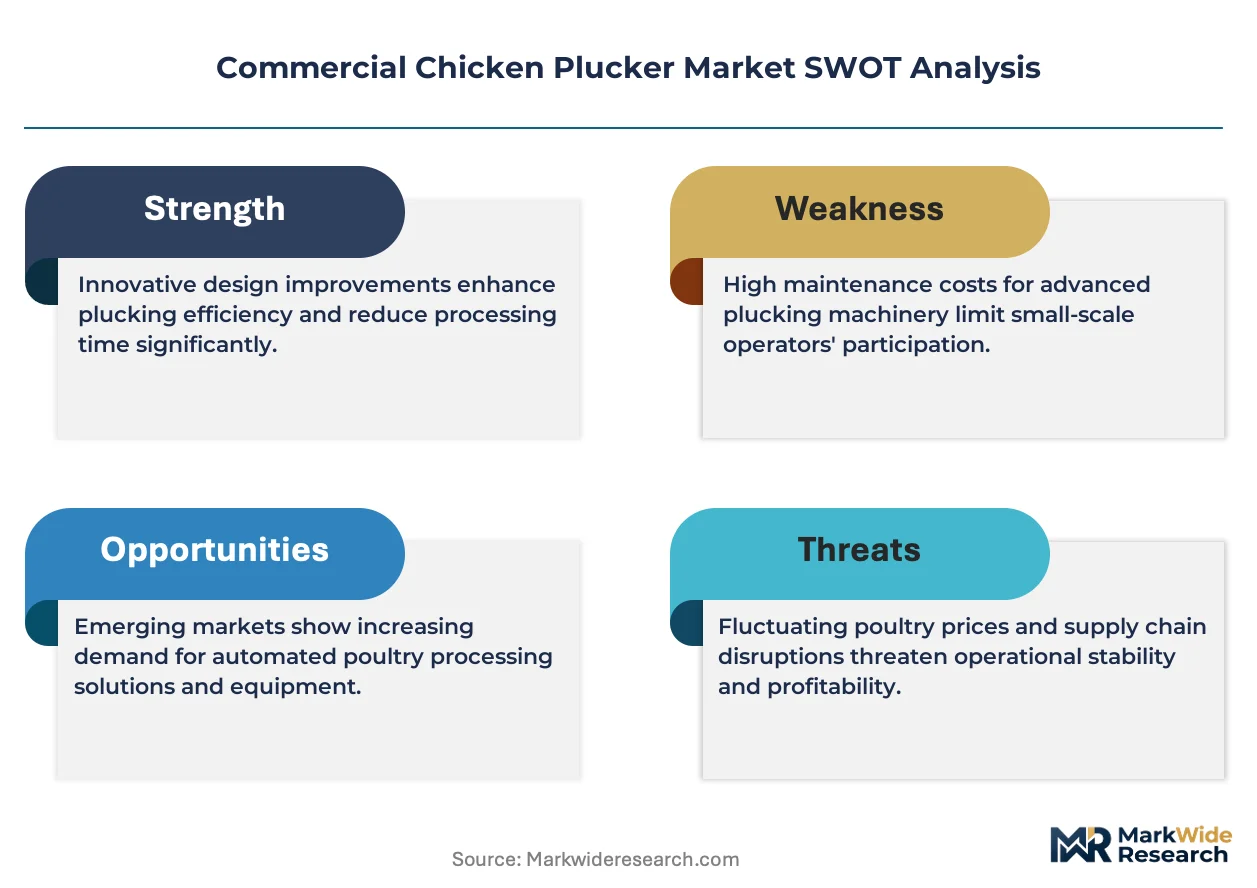
- Stainless Steel Input Volatility:Grade 304 and 316 price swings directly compress equipment margins, forcing manufacturers to absorb costs or pass through to price-sensitive buyers.
- European Component Concentration:Precision drive motors and sealed bearing assemblies source predominantly from German and Italian suppliers, creating lead time vulnerability.
- Manual Plucking Substitution:Small-scale farms and specialty poultry operations retain hand-processing for heritage breeds and direct-to-consumer channels, capping mechanization penetration.
Strategic Opportunities
- Brazilian Export Processing Expansion:Integrated poultry exporters are modernizing facilities to meet EU and Saudi import standards, opening demand for automated defeathering systems with HACCP documentation.
- Pneumatic-Assist Hybrid Systems:Convergence of rotary drum mechanics with compressed air feather ejection addresses water-scarce regions while maintaining throughput benchmarks.
- Manufacturer Portal Direct Sales:Bypassing dealer networks for mid-size farm orders captures margin and builds service relationship data for predictive maintenance offerings.
Industry Challenges
- Sanitation Engineering Talent Gap:Clean-in-place system design and USDA-compliant welding certification lag demand, extending commissioning timelines for new installations.
- Legacy Equipment Integration:Retrofitting pneumatic-assist modules onto existing rotary bases requires custom fabrication, complicating upgrade paths for budget-constrained processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Chicken Plucker Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Plucker, Electric Plucker, Portable Plucker, Industrial Plucker End User: Restaurants, Poultry Farms, Meat Processing Plants, Catering Services Capacity: Small Scale, Medium Scale, Large Scale, Custom Size Technology: Rotary Mechanism, Pneumatic System, Vibrating System, Hybrid System |
| Companies Covered | KITCHENER, Featherman Equipment, Meyn Food Processing Technology B.V., Zhucheng Xinhaoyun Machinery Co., Ltd., Marel, LEM Products, VEVOR, Zhucheng Xincheng Mingshun Machinery Co., Ltd., Yardbird, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Chicken Plucker Market Strategic Shifts
Equipment intelligence and regulatory compliance automation are displacing purely mechanical specifications as primary purchase criteria among volume processors.
Sensor-integrated plucker units are digitizing operational monitoring through drum speed optimization, feather load detection, and predictive bearing failure alerts. Large-scale meat processing plants are deploying these systems fastest, with multi-line facilities requiring centralized dashboard visibility. This digitizing capability is compressing maintenance response windows and enabling outcome-based service contracts that shift vendor revenue from hardware to uptime guarantees.
EPA effluent discharge rules are tightening allowable biological oxygen demand in poultry processing wastewater, forcing equipment redesigns around closed-loop water recycling. Manufacturers are responding with integrated filtration modules that reduce freshwater intake per bird. Mid-scale facilities in water-stressed regions of Texas and California face the steepest compliance curves, driving regional sales concentration for conservation-optimized configurations.
Buyer consolidation among integrated poultry processors is compressing vendor negotiation cycles and unbundling after-sales service from equipment purchases. Third-party maintenance providers are capturing service contracts previously held by original manufacturers, particularly in the southeastern United States where processor concentration is highest. This unbundling pressures equipment margins while opening recurring revenue streams for specialized sanitation and parts logistics firms.
Commercial Chicken Plucker Market Segmentation
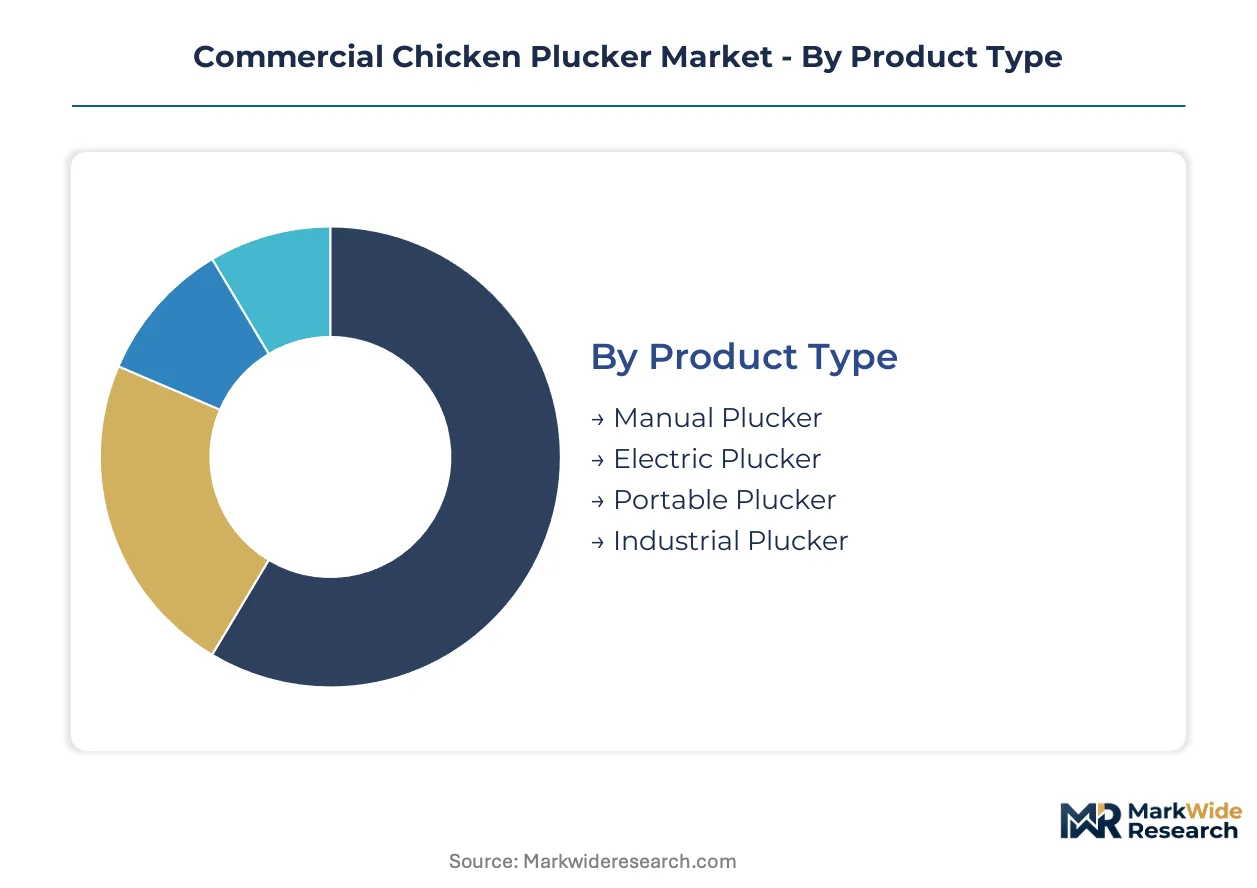
Equipment turnover cycles vary dramatically across commercial chicken plucker segments, with portable units replacing every 3-5 years while industrial lines operate on 15-year depreciation schedules. Procurement patterns track these replacement rhythms, concentrating vendor sales efforts on high-velocity categories while building long-term service contracts around capital-intensive installations.
Product Type:
Cycle times compress toward the portable end of the spectrum, where smaller farms cycle equipment faster than integrated processors amortizing industrial assets over decades.
- Electric Plucker:Motorized units with 150-300 RPM drum speeds dominate mid-scale poultry farm procurement due to throughput advantages over manual alternatives. USDA-compliant stainless steel configurations command premium positioning as facilities face sanitation mandate deadlines.
- Industrial Plucker:Continuous-line systems integrate directly into evisceration and chilling tunnels, serving meat processing plants with 10,000+ bird-per-hour throughput requirements. Capital intensity restricts adoption to volume operators with consolidated procurement authority.
- Manual Plucker:Hand-cranked or foot-pedal devices serve heritage breed operations and direct-to-consumer farms where mechanization conflicts with artisanal positioning.
- Portable Plucker:Compact electric units with wheeled bases target mobile processing services and small farms with seasonal slaughter volumes.
Electric plucker configurations anchor the volume base while industrial plucker systems gain share at the steepest rate as processing consolidation accelerates.
End User:
Customer scale determines specification complexity, with integrated processors demanding continuous-line integration while foodservice operators prioritize footprint minimization.
- Poultry Farms:Mid-scale operations with 10,000-100,000 bird annual throughput drive electric plucker replacement cycles, particularly in southeastern United States clusters where labor arbitrage has collapsed. These facilities balance capital constraints against USDA compliance deadlines.
- Meat Processing Plants:Integrated poultry processors standardize on industrial configurations with clean-in-place compatibility and centralized dashboard monitoring. Multi-line facilities require vendor uptime guarantees and predictive maintenance contracts.
- Restaurants:On-premise slaughter operations in farm-to-table concepts specify compact electric units with minimal water consumption for urban utility cost management.
- Catering Services:Mobile foodservice operators prioritize portable units with rapid setup capabilities for event-based poultry processing.
Poultry farms anchor the volume base while meat processing plants expand their share most aggressively through facility modernization programs.
Capacity:
Scale thresholds align with regulatory inspection categories, driving specification divergence between exempt small operations and USDA-inspected facilities.
- Medium Scale:Units processing 500-2,000 birds daily capture the largest addressable market, serving regional poultry farms and independent processing cooperatives. These configurations balance throughput against water conservation compliance in Texas and California water-stressed regions.
- Large Scale:Continuous-feed systems exceeding 5,000 birds per hour require custom foundation work and utility infrastructure, limiting adoption to integrated processors with captive engineering resources.
- Small Scale:Sub-500 bird daily capacity serves exempt operations under federal inspection thresholds, retaining manual methods or basic electric units.
- Custom Size:Engineered-to-order configurations address specialty poultry processors handling duck, turkey, or game bird species with non-standard carcass dimensions.
Medium scale configurations anchor the volume base while large scale systems climb the fastest as processor consolidation concentrates procurement authority.
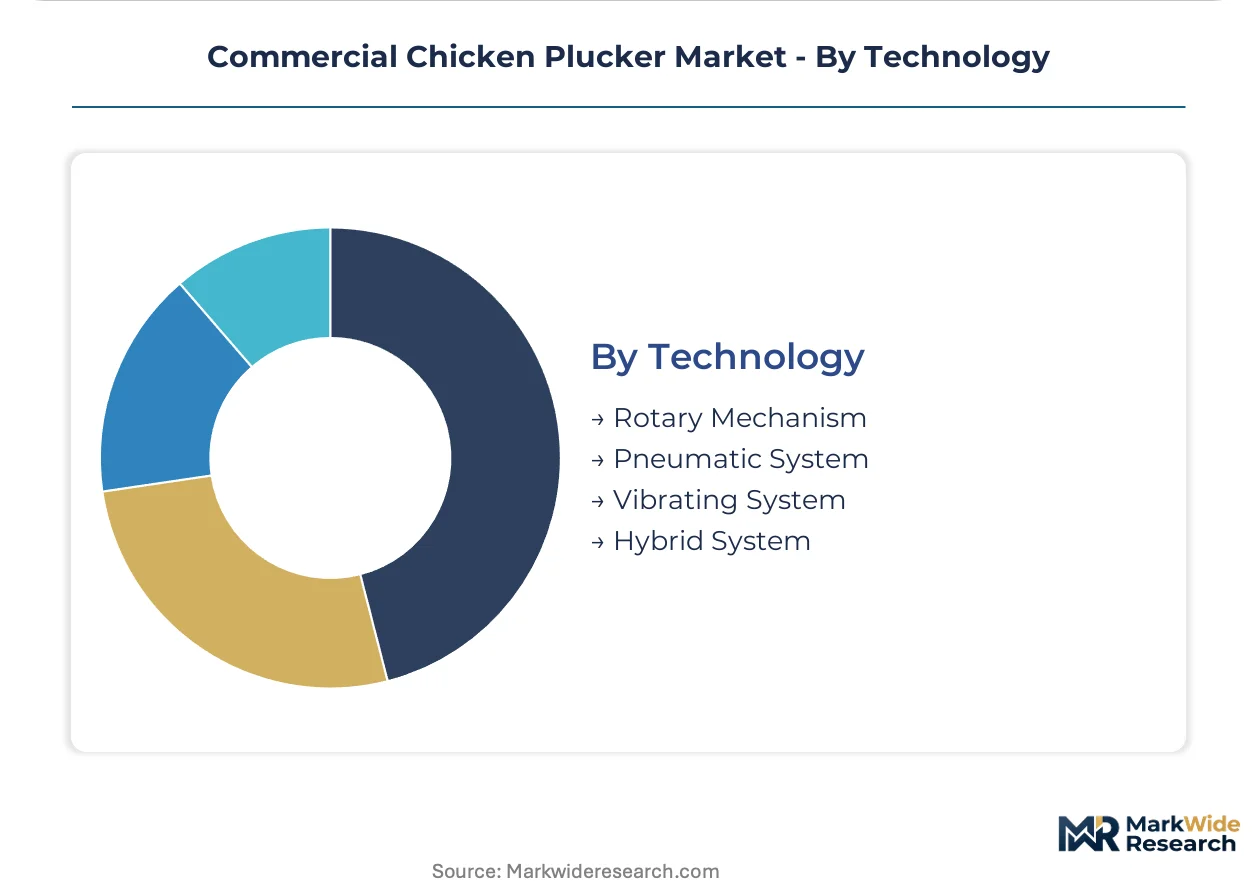
Technology:
Mechanical sophistication correlates with water efficiency mandates, pushing adoption toward hybrid architectures in regulated watersheds.
- Rotary Mechanism:Drum-based systems with rubber finger arrays dominate installed bases due to proven reliability and lower capital requirements. These units face retrofit pressure as EPA effluent rules tighten biological oxygen demand limits in poultry processing wastewater.
- Hybrid System:Convergence of rotary mechanics with pneumatic feather ejection addresses water-scarce regions while maintaining throughput benchmarks. Saudi Arabian and Brazilian export processors specify these configurations for EU import standard compliance.
- Pneumatic System:Compressed-air-based feather removal serves niche applications requiring minimal water contact, particularly in kosher and halal processing protocols.
- Vibrating System:Oscillating plate alternatives target delicate-skinned poultry varieties where rotary drum contact causes carcass damage.
Rotary mechanism technology anchors the volume base while hybrid systems expand most quickly as water conservation mandates proliferate across poultry-producing regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA inspection mandates and EPA effluent regulations anchor North American demand, while Brazilian export modernization and Chinese mechanization programs reshape procurement patterns across distinct regulatory environments.
United States
Integrated poultry processors in Georgia and Arkansas drive industrial plucker procurement as labor costs compress manual processing margins. USDA Hazard Analysis Critical Control Point rules mandate stainless steel contact surfaces and clean-in-place compatibility, forcing mid-scale facility upgrades. The Delmarva Peninsula cluster concentrates broiler processing operations where water conservation regulations from the EPA tighten biological oxygen demand limits in effluent discharge.
Brazil
Export-oriented integrators in Santa Catarina and Paraná modernize defeathering lines to meet EU and Saudi import standards. ANVISA sanitation protocols align equipment specifications with destination market requirements, driving automated system adoption. The Seara and BRF processing corridors anchor demand for continuous-line configurations with HACCP documentation capabilities.
China
Provincial poultry conglomerates in Shandong and Henan accelerate mechanization as rural labor pools contract and wage arbitrage erodes. GB food safety standards and provincial environmental regulations tighten wastewater discharge parameters, favoring water-recycling plucker designs. The Weifang processing cluster exemplifies regional consolidation trends where multi-line facilities standardize on integrated equipment bundles.
Germany
Engineering-intensive fabricators in North Rhine-Westphalia and Bavaria supply precision drive components to global plucker manufacturers, creating upstream supply concentration. REACH chemical compliance and CE machinery directives shape material specifications for export-bound equipment. The Ruhr industrial corridor hosts specialized motor and sealed bearing suppliers whose lead times create vulnerability for downstream assemblers.
India
Contract poultry farming expansion in Telangana and Andhra Pradesh generates demand for electric plucker units as processing cooperatives formalize operations. FSSAI hygiene regulations and state-level pollution control board mandates reshape equipment procurement specifications for mid-scale facilities. The Hyderabad-Vijayawada corridor concentrates emerging poultry processing infrastructure where mechanization replaces manual defeathering.
Commercial Chicken Plucker Market Competitive Environment
European engineering specialists and Asian cost-optimized fabricators split the market along capability-versus-price vectors. The vendor base stratifies across three tiers: integrated processing system bundlers, standalone equipment specialists, and component-focused regional suppliers. Consolidation pressures intensify as mid-scale farm procurement shifts toward direct manufacturer portals, compressing dealer network relevance. Dominant competitive moves include backward integration into precision drive manufacturing and geographic expansion through distributor partnerships in Brazilian and Southeast Asian markets.
Among Dutch and Icelandic system integrators, Meyn Food Processing Technology B.V. and Marel exemplify the premium-tier archetype through integrated processing line positioning. Chinese fabricators including Zhucheng Xinhaoyun Machinery Co., Ltd. occupy the cost-engineered segment, supplying standardized units for emerging market price sensitivity. Featherman Equipment represents the mid-scale specialist archetype, serving regional poultry farms with configurable electric plucker configurations. These strategic groupings reflect divergent capital intensity tolerance and regulatory compliance depth across customer segments.
| Leading Market Players |
|---|
| KITCHENER |
| Featherman Equipment |
| Meyn Food Processing Technology B.V. |
| Zhucheng Xinhaoyun Machinery Co., Ltd. |
| Marel |
| LEM Products |
| VEVOR |
| Zhucheng Xincheng Mingshun Machinery Co., Ltd. |
| Yardbird |
| Others |
Value Chain & Pricing Dynamics
The Hamburg-Rotterdam freight corridor's container rate volatility feeds directly into landed cost spreads between German-engineered precision components and Asian-fabricated standard units, compressing margin pools for mid-tier assemblers while amplifying price differentiation between stainless steel Grade 304 configurations and cost-optimized alternatives.
Pricing Analysis
The customization-premium spread spans roughly 40-60 percent between configured-to-order industrial lines and standard electric plucker units, with pricing stratifying across premium USDA-compliant stainless steel, standard carbon steel with sanitary coatings, and economy-grade galvanized configurations. Price differentiation hinges on certification depth — HACCP documentation and clean-in-place compatibility command substantial premiums — and volume scale, where integrated processors extract fleet discounts unavailable to independent farms. Cost compression in the economy tier is intensifying because Chinese fabricators are absorbing stainless steel input volatility to defend export share. Independent poultry farms exhibit highest price sensitivity, while meat processing plants prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Contract manufacturing concentration sits with precision drive specialists in Germany's Ruhr corridor and bearing assembly houses in northern Italy, with secondary metal fabrication capacity clustering in Shandong Province, China and Gujarat, India. Raw material dependencies center on Grade 304/316 stainless steel from Indonesian nickel smelters, food-grade rubber compounds from Malaysian plantations, and precision motors from German suppliers. Single-source vulnerability in sealed bearing assemblies creates lead time exposure for downstream assemblers. Distribution runs through dealer networks for small-farm segments and direct manufacturer portals for mid-scale operations, with integrated processors negotiating enterprise service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity because predictive maintenance contracts and uptime guarantee arrangements are expanding faster than hardware shipments as buyer consolidation shifts procurement criteria toward operational expenditure models.
For Market Incumbents: Entrench through backward integration into precision drive manufacturing to neutralize German supplier lead time vulnerability, while expanding captive sanitation engineering certification programs to capture commissioning revenue streams previously lost to third-party specialists. The unbundling of after-sales service by independent maintenance providers threatens OEM margin pools. Vertical control over critical component supply secures delivery reliability for large-scale installations. For New Entrants and Emerging Players: Build out pneumatic-assist hybrid system capabilities to exploit water conservation mandate proliferation across Texas, California, and emerging export markets like Saudi Arabia. The most penetrable white space sits with mid-scale poultry farms in India's Telangana-Andhra Pradesh corridor, where contract farming formalization is outpacing local equipment supply. A direct-to-farm digital sales portal with regional language configuration support bypasses entrenched dealer networks. For Investors and Strategic Acquirers: EPA effluent discharge rule tightening reshapes the acquisition landscape toward water-recycling technology stacks and clean-in-place engineering talent pools. Long-term viability favors targets with installed base data streams enabling predictive maintenance subscription conversion. The signal to watch is regional water stress index movements, which accelerate compliance-driven replacement cycles ahead of published regulatory deadlines. Quarterly review of state-level pollution control board enforcement intensity is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Converts hardware margins into recurring uptime guarantee revenue from meat processing plants. |
| Backward Integration into Drive Manufacturing | Captures German motor supplier margins while securing lead time resilience for industrial lines. |
| Pneumatic-Assist Hybrid System Development | Addresses EPA biological oxygen demand limits in Texas and California water-stressed regions. |
| Direct Manufacturer Portal Expansion | Bypasses dealer networks to capture mid-scale farm margin and build service relationship data. |
| Sanitation Engineering Certification Program | Monetizes clean-in-place design expertise as USDA compliance deadlines compress commissioning timelines. |
Study Parameters
A spread of perspectives from plant engineers at integrated poultry processors, aftermarket service heads at OEMs, procurement leads at mid-scale farms, and regulatory compliance officers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against USDA enforcement bulletins, EPA effluent discharge databases, state-level water conservation mandate filings, and customs records tracking stainless steel equipment imports. Bottom-up unit economics from facility-level procurement patterns triangulated against top-down capacity estimates from major processing clusters.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, end-user scale, capacity tier, and technology architecture. Modeled outputs incorporated poultry farm mechanization trajectories, minimum wage compression curves in processing-heavy states, and water tariff escalation patterns. CAGRs were derived from replacement cycle analysis and consolidation-driven procurement authority concentration.
Practitioners should monitor stainless steel input price volatility, EPA regional enforcement variance, and Brazilian export certification requirement shifts for early signals of forecast revision. Forecasts reflect documented assumptions about labor arbitrage collapse timing and regulatory compliance deadline adherence. Quarterly review of state-level water stress indices and USDA inspection backlog data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poultry Farming Equipment
Duck Plucker Machine Market
Poultry Farming Equipment
Multi-Layer Poultry Cage Market
Poultry Farming Equipment
Poultry Farming Equipment Market
Poultry Farming Equipment
Turkey Poultry Market
Poultry Farming Equipment
Egg Grading Machines Market
Poultry Farming Equipment
Asia Pacific Poultry Market
Poultry Farming Equipment
Poultry Keeping Machinery Market
Poultry Farming Equipment
Automated Poultry Farm Market
Poultry Farming Equipment
Poultry Brooders, Feeders, and Waterers Market
Poultry Farming Equipment
Poultry Incubator Market
Poultry Farming Equipment
Poultry House Ventilation System Market
Poultry Farming Equipment
Poultry Brooder Market
Poultry Farming Equipment
Poultry Plucker Market
Poultry Farming Equipment
Egg Breaking Machine Market
Poultry Farming Equipment
Rabbit Cages Market