
 Automated Poultry Farm Market | 2026-2036
Automated Poultry Farm Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Poultry Farm Market Outlook
The Netherlands is reconfiguring its position as a design and export hub for poultry automation engineering. Big Dutchman International leverages decades of European market presence to sustain specification leadership in climate control and feeding infrastructure. Fancom B.V. anchors precision livestock farming through sensor-integrated house management platforms. SKOV A/S competes on ventilation and cooling system specialization across Nordic and Central European installations.
Automated poultry farms integrate electromechanical systems, environmental sensors, and software platforms to manage feeding, climate, egg collection, and flock health with minimal labor intervention. These installations typically operate within temperature bands of 18–24°C for layers and achieve feed conversion ratios below 1.7 for broilers through algorithmic optimization. Feeding systems and climate control systems occupy the largest installed base segments, reflecting their foundational role in every commercial house build-out. IoT solutions and artificial intelligence represent the fastest-expanding technology categories, as farms replace standalone controllers with connected platforms that enable remote diagnostics and predictive mortality alerts.
Europe's F-Gas Regulation and REACH framework constrain refrigerant and material choices in climate system manufacturing, pushing vendors toward low-global-warming-potential alternatives. The USDA and FDA in the United States enforce pathogen monitoring and antibiotic residue rules that elevate demand for automated traceability and biosecurity gating systems. Stakeholders must weigh regulatory divergence between jurisdictions when configuring platform architectures for multi-country deployment.
Market Dynamics
Algorithmic flock management is compressing labor dependency across commercial layer and broiler operations, forcing capital reallocation from manual husbandry toward sensor-integrated house control systems.
Growth Catalysts
- GB Standards Certification:China's tightening equipment import rules are filtering out non-compliant vendors, creating specification advantages for engineered systems that meet dual carbon and biosecurity protocols.
- Layer House Automation:Brazilian commercial farms facing wage inflation are retrofitting climate-controlled facilities with electromechanical feeding and egg collection infrastructure.
- REACH-Driven Material Substitution:Europe's chemical framework is accelerating refrigerant and insulation material transitions, pulling demand toward low-global-warming-potential climate system designs.
Market Restraints
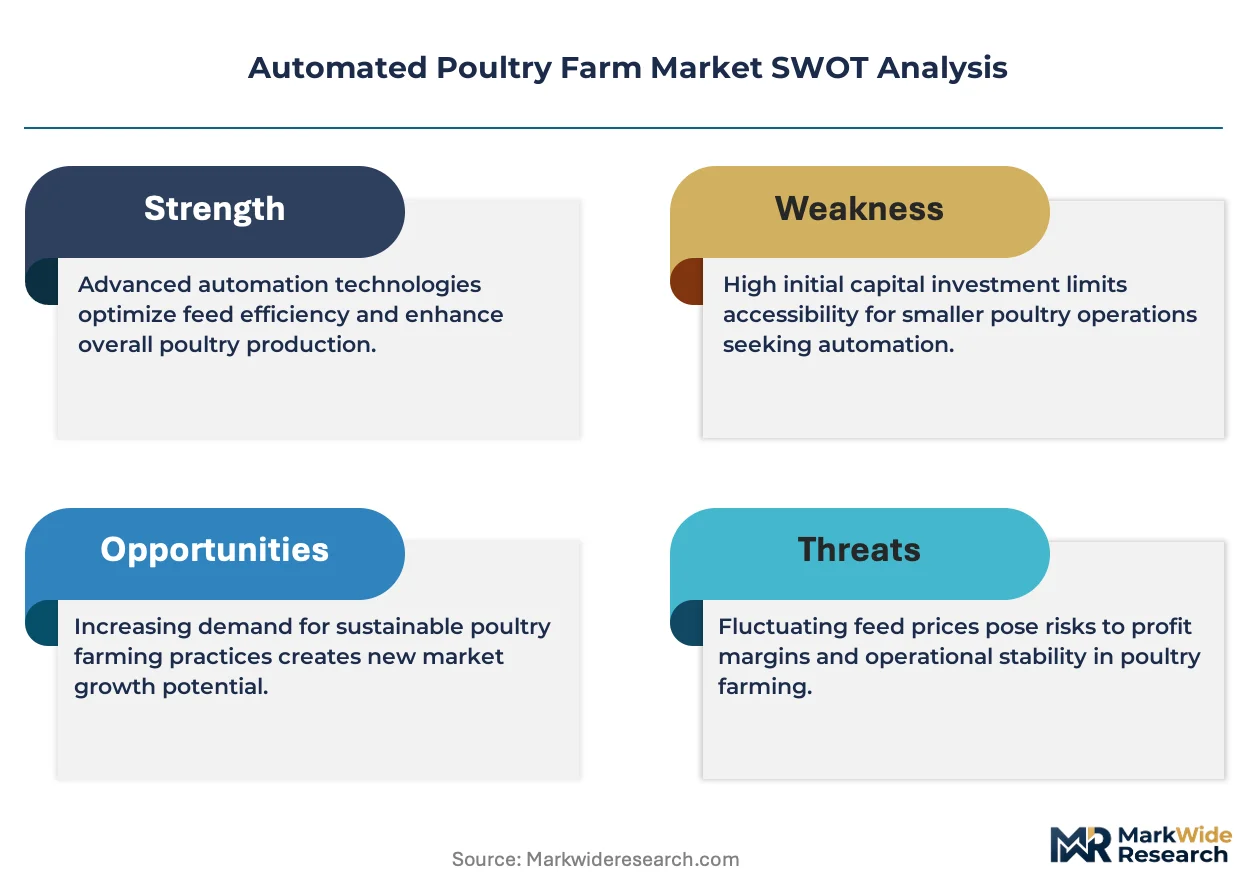
- Steel and Aluminum Input Volatility:Climate system housings and feeding infrastructure face margin pressure from base metal price swings, constraining project financing predictability for farm operators.
- Component Supply Concentration:Precision sensors and variable-frequency drives concentrate among East Asian contract manufacturers, exposing European and Latin American integrators to lead-time fragility.
- Interoperability Limitations:Proprietary communication protocols between feeding, climate, and health monitoring subsystems force expensive middleware development or single-vendor lock-in.
Strategic Opportunities
- Sub-Saharan Africa Greenfield Builds:Underpenetrated poultry markets in Nigeria and Kenya present first-mover advantages for fully automated house configurations without legacy infrastructure displacement costs.
- AI-IoT Convergence:Predictive mortality algorithms layered onto environmental sensor networks enable remote diagnostics that reduce on-site veterinary labor requirements.
- USDA Biosecurity Mandates:Pathogen traceability rules are elevating automated gating and quarantine zone management from optional to specification-critical in US commercial operations.
Industry Challenges
- Mechatronics Skill Scarcity:Maintenance of precision feeding augers and sensor-calibrated ventilation demands technicians cross-trained in mechanical, electrical, and software diagnostics, a profile rare in rural agricultural labor pools.
- Multi-System Integration Complexity:Synchronizing climate controllers with third-party egg grading and packing equipment requires custom API development that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Poultry Farm Market |
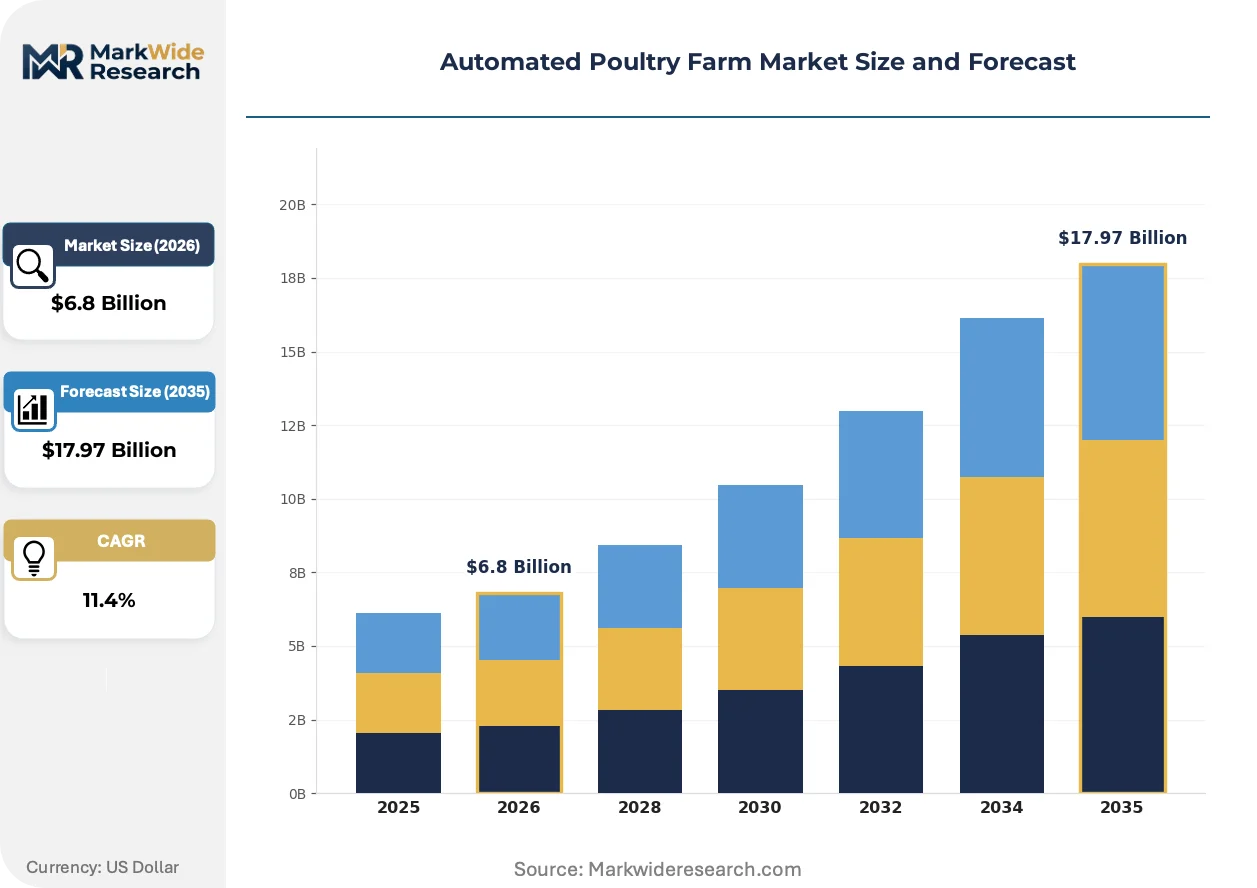
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
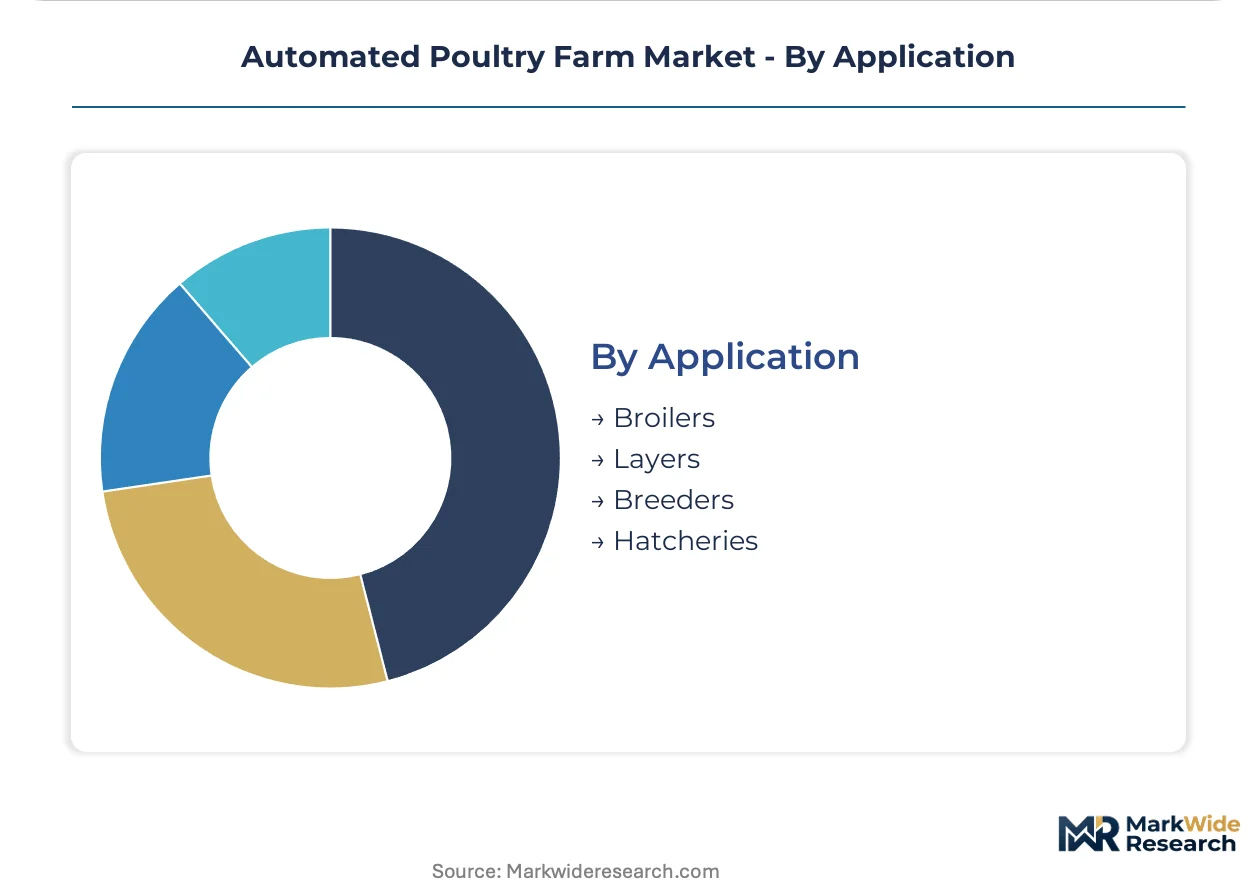
| Segmentation | Product Type: Feeding Systems, Monitoring Equipment, Climate Control Systems, Egg Handling Equipment Technology: IoT Solutions, Artificial Intelligence, Robotics, Automation Software End User: Commercial Farms, Organic Farmers, Integrated Poultry Companies, Research Institutions Application: Broilers, Layers, Breeders, Hatcheries |
| Companies Covered | Fancom B.V., SKOV A/S, CTB, Inc., LiVi Machinery, Val-Co, LLC, Big Dutchman International GmbH, Nedap, Porphyrio, Vencomatic Group B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Poultry Farm Market Strategic Shifts
Connected platform architectures are displacing standalone house controllers, compressing the operational data loop from sensor capture to algorithmic response from hours to minutes.
Precision livestock farming is digitizing flock behavior monitoring through computer vision and acoustic analysis, converting feeding patterns and vocal stress indicators into real-time health scoring. Mid-scale broiler operations in the Netherlands and Denmark are deploying these systems at commercial pace, replacing periodic manual inspection with continuous automated surveillance. The technology is digitizing mortality risk prediction, enabling intervention before clinical symptoms manifest.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in climate control systems, forcing manufacturers toward CO2 and ammonia-based cooling architectures. This industrial consequence elevates capital costs for new house builds but creates specification differentiation for vendors with certified low-global-warming-potential portfolios. Nordic installation markets are responding fastest, with Denmark and Sweden already specifying natural refrigerant systems in public procurement tenders.
Integrated service contracts are displacing equipment-only sales, binding climate and feeding system vendors to performance-based uptime guarantees. Brazilian and Mexican commercial farm operators are leading this shift, preferring vendors who absorb maintenance complexity in exchange for per-bird fees. The model is most visible in Latin America, where currency volatility makes fixed operational expenditures preferable to lumpy capital outlays.
Automated Poultry Farm Market Segmentation
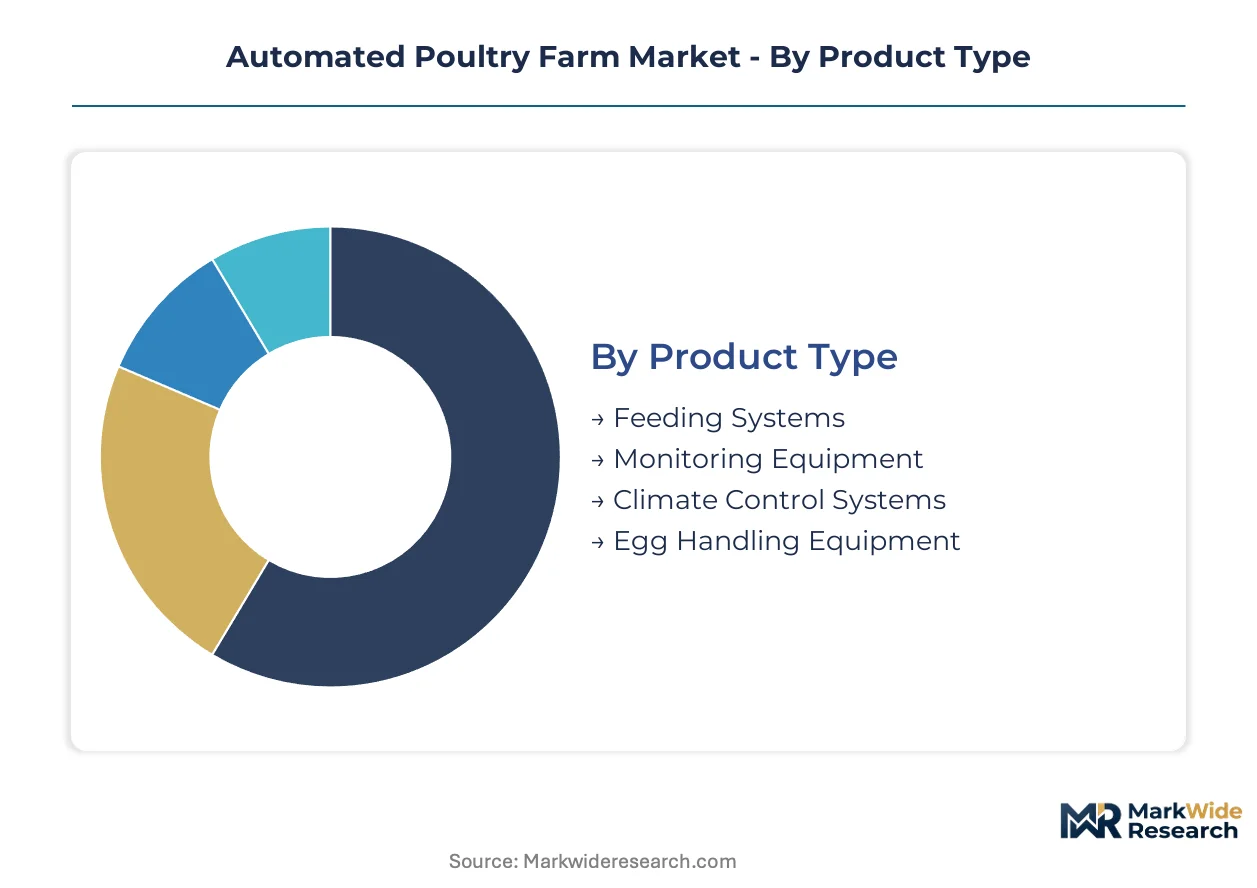
Segmentation in automated poultry farming reveals distinct service intensity profiles. Feeding and climate systems demand continuous calibration support, while software platforms shift revenue toward subscription maintenance. Equipment buyers prioritize vendors with localized technical presence over pure hardware specifications.
Product Type:
After-sales service intensity varies sharply across hardware categories. Climate systems require seasonal recalibration and refrigerant monitoring, while feeding infrastructure needs auger alignment and motor replacement programs.
- Feeding Systems:Electromechanical augers, chain feeders, and pan distribution networks deliver precise ration control across house zones. Brazilian commercial farms retrofit these systems most aggressively as labor costs climb, prioritizing vendors with spare parts depots in São Paulo state. By volume, Feeding Systems leads. By growth pace, Climate Control Systems is ahead.
- Climate Control Systems:Ventilation, cooling, and heating modules maintain 18–24°C bands for layers through variable-frequency fan arrays and evaporative cooling pads. REACH-driven refrigerant transitions in Europe are pulling specification toward CO2-based architectures from Dutch and Danish engineering clusters. These systems carry the highest lifetime service contract attachment rates of any hardware category.
- Monitoring Equipment:Environmental sensors, ammonia detectors, and light intensity meters feed data to house controllers.
- Egg Handling Equipment:Automated collection belts, grading machinery, and packing robotics reduce manual touchpoints in layer operations.
Climate and feeding infrastructure together command the largest installed base, reflecting their non-negotiable role in every commercial house configuration.
Technology:
Cost tier separation distinguishes technology adoption patterns. Premium deployments integrate full AI-IoT stacks, while mid-market farms deploy standalone automation software with limited sensor networks.
- IoT Solutions:Connected sensor networks transmit temperature, humidity, and ammonia readings to cloud platforms for remote monitoring. Netherlands-based layer operations deploy these at commercial scale, replacing hourly manual house checks with continuous data streams. IoT platforms are expanding most quickly as farms retrofit standalone controllers with connectivity modules.
- Artificial Intelligence:Predictive mortality algorithms and computer vision systems for flock behavior analysis enable pre-symptomatic health intervention. Danish broiler integrators lead commercial deployment, using acoustic stress detection to flag respiratory distress before clinical signs appear. AI carries the highest R&D intensity and vendor margin profile of all technology categories.
- Robotics:Autonomous floor cleaning, egg collection, and carcass removal systems reduce human entry frequency.
- Automation Software:House management platforms coordinate feeding, climate, and lighting schedules through centralized controllers.
IoT Solutions dominate current deployment volume. AI commands the steepest expansion trajectory as precision livestock farming matures.
End User:
Customer type determines procurement sophistication and contract structure. Integrated poultry companies negotiate enterprise-wide performance guarantees, while organic farmers prioritize antibiotic-free compliance documentation.
- Commercial Farms:Large-scale layer and broiler operations with 100,000+ bird capacities drive bulk equipment procurement. These buyers in Brazil and Mexico increasingly favor integrated service contracts with uptime guarantees over equipment-only purchases. Commercial Farms represent the deepest installed base and most concentrated vendor relationship intensity.
- Integrated Poultry Companies:Vertically coordinated operations spanning breeding, hatchery, grow-out, and processing demand unified data platforms across facilities. USDA biosecurity mandates for pathogen traceability elevate automated gating systems from optional to specification-critical for US-based integrators. These buyers command the largest per-facility technology budgets.
- Organic Farmers:Smaller-scale operations with strict antibiotic-free and outdoor access requirements.
- Research Institutions:University and government experimental stations testing genetics, nutrition, and welfare protocols.
Commercial Farms anchor equipment volume. Integrated Poultry Companies are climbing fastest as biosecurity regulations tighten.
Application:
Application maturity shapes technology penetration depth. Broiler operations lead algorithmic feed conversion optimization, while layer houses concentrate automation investment in egg handling robotics.
- Broilers:Grow-out operations for meat production prioritize feed conversion ratio optimization through climate-controlled environments and precision rationing. Algorithmic flock management has compressed labor dependency most dramatically here, with automated mortality detection replacing twice-daily manual house walks. Brazil's expanding commercial farm base drives regional demand concentration.
- Layers:Egg production facilities require specialized climate bands, automated collection systems, and grading infrastructure. Netherlands and Denmark operations deploy computer vision for continuous welfare monitoring, converting feeding patterns and vocal indicators into health scores. Layer automation carries the highest per-bird capital intensity due to extended production cycles.
- Breeders:Parent stock operations with specialized lighting and nutrition protocols for hatching egg production.
- Hatcheries:Incubation facilities with precise temperature, humidity, and turning automation for embryonic development.
Broilers dominate unit volume. Layers are gaining share fastest as welfare monitoring technology commercializes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering clusters in the Netherlands and Denmark concentrate climate system design and precision livestock farming platforms, while Brazil and China anchor installation volume through distinct regulatory and cost pressures.
Netherlands
Wageningen University corridors and Eindhoven industrial zones generate precision farming technology exports. The ECHA REACH framework restricts refrigerant chemistry in climate systems, forcing Dutch manufacturers toward CO2-based cooling architectures. Vencomatic Group and Fancom B.V. anchor a dense cluster of poultry automation engineering in North Brabant province.
Brazil
Commercial layer operations in São Paulo state retrofit climate-controlled houses as agricultural wages climb. ANVISA biosecurity protocols mandate pathogen traceability systems for integrated poultry companies. Campinas and Sorocaba industrial zones host Brazilian assembly operations for European feeding and climate system vendors.
China
GB standards for automated livestock equipment tighten certification requirements for imported climate and feeding systems. The MIIT dual carbon policy pushes domestic manufacturers toward energy-efficient house controllers. Shandong and Jiangsu provinces concentrate contract manufacturing for precision sensors and variable-frequency drives.
Denmark
Broiler integrators deploy acoustic stress detection and computer vision for mortality prediction ahead of clinical symptoms. The F-Gas Regulation phases down hydrofluorocarbon refrigerants, accelerating natural refrigerant adoption in new house builds. Aarhus and Odense engineering clusters specialize in sensor-integrated house management platforms.
United States
USDA biosecurity mandates elevate automated gating and quarantine zone management from optional to specification-critical in commercial operations. The FDA enforces antibiotic residue rules that pull demand toward automated traceability infrastructure. Georgia and Arkansas poultry belts concentrate integrated company procurement for algorithmic flock management systems.
Automated Poultry Farm Market Competitive Environment
Specialist engineering houses and diversified agricultural equipment conglomerates split the market along technology depth versus scale breadth. Dutch and Danish clusters concentrate climate and feeding system design, while North American and Chinese players compete on installation volume and cost-optimized fabrication. Three archetypes dominate: precision livestock farming specialists, integrated climate-feeding system vendors, and contract manufacturing assemblers. Competitive moves center on integrated service contract expansion and AI-IoT platform licensing.
Among precision livestock farming specialists, Fancom B.V. and SKOV A/S occupy positions exemplifying sensor-integrated house management and ventilation system specialization respectively. Big Dutchman International GmbH represents the integrated-system archetype with decades of European market presence in climate control and feeding infrastructure. These three anchors span the strategic spectrum from pure-play precision technology to full-stack house system integration.
| Leading Market Players |
|---|
| Fancom B.V. |
| SKOV A/S |
| CTB, Inc. |
| LiVi Machinery |
| Val-Co, LLC |
| Big Dutchman International GmbH |
| Nedap |
| Porphyrio |
| Vencomatic Group B.V. |
| Others |
Value Chain & Pricing Dynamics
Shandong and Jiangsu provinces concentrate contract manufacturing for precision sensors and variable-frequency drives, concentrating upstream capacity in East Asian electronics corridors that filter through to European and Latin American integrators with limited alternative sourcing. This geographic clustering amplifies pricing power for component vendors while exposing downstream automation assemblers to lead-time volatility that compresses margin predictability across project financing cycles.
Pricing Analysis
Europe's F-Gas Regulation dictates the pricing tier structure for climate control systems, forcing specification toward CO2-based cooling architectures that carry 15-25% capital cost premiums over legacy hydrofluorocarbon designs. Three-tier pricing structure across premium, standard, and economy levels separates vendors with certified low-global-warming-potential portfolios from commodity competitors, with REACH compliance and dual carbon certification anchoring the premium tier. Cost compression in mid-market feeding systems is intensifying because Brazilian and Mexican farm operators increasingly prefer integrated service contracts with uptime guarantees over equipment-only purchases. Commercial farms with 100,000+ bird capacities demonstrate highest price sensitivity due to currency volatility exposure, while integrated poultry companies prioritize performance specifications over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from East Asian contract manufacturers have become critical liquidity instruments for European climate system assemblers facing steel and aluminum input volatility. Component sourcing draws from China for precision sensors, South Korea for variable-frequency drives, and Germany for specialized refrigerant compressors. Raw material dependencies center on cold-rolled steel for housing fabrication, copper windings for motor assemblies, and specialized polymers for sensor encapsulation. Single-source vulnerability concentrates in ammonia sensor microcontrollers and evaporative cooling pad substrates, where qualified alternative suppliers require 12-18 month certification cycles. Distribution runs through authorized integrator networks in São Paulo state, North Brabant province, and Georgia-Arkansas poultry belts, with direct-to-farm commissioning replacing traditional equipment wholesaling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated poultry farming is crossing a platform-economics inflection where proprietary communication protocols between feeding, climate, and health monitoring subsystems force expensive middleware development or single-vendor lock-in, reshaping competitive positioning around interoperability rather than standalone hardware performance.
For Market Incumbents: Harden specification leadership in climate control and feeding infrastructure through captive supply of precision sensors and backward integration into refrigerant compressor manufacturing, defending against emerging Chinese domestic champions with MIIT dual carbon policy alignment. Prioritize certification investment for GB standards compliance to maintain access to China's tightening import equipment market, while building API development capabilities that reduce commissioning timelines for multi-system integration complexity. For New Entrants and Emerging Players: Sub-Saharan Africa greenfield builds in Nigeria and Kenya present first-mover advantages for fully automated house configurations without legacy infrastructure displacement costs, with local currency service contracting mitigating capital expenditure barriers for mid-scale commercial farms. Target poultry integrators seeking USDA biosecurity mandate compliance through automated gating and quarantine zone management systems, deploying cloud-native IoT platforms that bypass proprietary controller ecosystems. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision livestock farming specialists with computer vision and acoustic stress detection capabilities, as algorithmic flock management compresses labor dependency and elevates R&D intensity toward predictive mortality algorithms. Long-term viability hinges on AI-IoT convergence maturity, with acquisition targets showing commercial deployment traction in Danish broiler integrators or Netherlands layer operations. Watch for F-Gas Regulation enforcement acceleration as inflection indicator, as natural refrigerant system specification would rapidly consolidate vendor tiers around certified low-global-warming-potential portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| API Development for Multi-System Integration | Reduces commissioning timelines by enabling climate controller synchronization with third-party egg grading equipment. |
| Natural Refrigerant System Certification | Creates specification differentiation under Europe's F-Gas Regulation phase-down of hydrofluorocarbon cooling architectures. |
| Integrated Service Contract Expansion | Binds vendors to performance-based uptime guarantees preferred by Brazilian operators facing currency volatility. |
| GB Standards Compliance Investment | Maintains market access as China's MIIT dual carbon policy tightens equipment import certification requirements. |
| AI-IoT Platform Licensing | Captures recurring revenue from predictive mortality algorithms layered onto environmental sensor networks. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and equipment vendor technical documentation, combining interviews with farm operations managers, poultry integrator procurement directors, climate system design engineers, and aftermarket service technicians. Bottom-up triangulation validates installation volume estimates against top-down market sizing from agricultural equipment trade associations and veterinary pharmaceutical distribution records.
Forecast inputs span feeding system retrofit intensity, climate control refrigerant transition timelines, and AI-IoT platform adoption curves across commercial farms and integrated poultry companies. Segmentation dimensions modeled include product type hardware categories, technology deployment tiers, end-user procurement sophistication levels, and application-specific capital intensity patterns. CAGRs derive from regression analysis of historical equipment shipment data against macroeconomic indicators including agricultural wage indices and protein commodity prices.
Practitioners should monitor steel and aluminum futures volatility, REACH framework enforcement acceleration, and Chinese GB standards certification timeline shifts for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poultry Farming Equipment
Multi-Layer Poultry Cage Market
Poultry Farming Equipment
Asia Pacific Poultry Market
Poultry Farming Equipment
Commercial Chicken Plucker Market
Poultry Farming Equipment
Rabbit Cages Market
Poultry Farming Equipment
Poultry Plucker Market
Poultry Farming Equipment
Egg Grading Machines Market
Poultry Farming Equipment
Poultry Farming Equipment Market
Poultry Farming Equipment
Turkey Poultry Market
Poultry Farming Equipment
Poultry House Ventilation System Market
Poultry Farming Equipment
Duck Plucker Machine Market
Poultry Farming Equipment
Poultry Incubator Market
Poultry Farming Equipment
Egg Breaking Machine Market
Poultry Farming Equipment
Poultry Brooders, Feeders, and Waterers Market
Poultry Farming Equipment
Poultry Brooder Market
Poultry Farming Equipment
Poultry Keeping Machinery Market