
 Poultry Incubator Market | 2026-2036
Poultry Incubator Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Incubator Market Insights
Chinese incubator manufacturing clusters is expanding output of large-scale electric units for integrated poultry operations. Petersime NV leverages its Belgian engineering base to sustain premium positioning in climate-controlled hatchery systems across European markets. Pas Reform Hatchery Technologies anchors its competitiveness through in-house development of embryo monitoring sensors. Jamesway Incubator Company dominates the North American replacement cycle for industrial-grade installations.
A poultry incubator is a thermostatically controlled enclosure that maintains precise temperature, humidity, and ventilation parameters to artificially hatch fertilized eggs, typically operating within 37.5-37.8°C and 50-65% relative humidity ranges depending on species. The device serves commercial agriculture by decoupling hatch timing from broody hen availability and enabling standardized survival rates for chicks destined for meat or layer flocks. Automatic incubators command the highest margin pools due to embedded control systems and reduced labor dependency, while solar-powered units represent the fastest-expanding operation mode in off-grid rural poultry zones. Small-scale tabletop incubators occupy a mature niche serving backyard farmers and educational institutions with limited capital budgets.
The USDA enforces biosecurity protocols through the National Poultry Improvement Plan that dictate sanitation standards for hatchery equipment crossing state lines, while EU F-Gas Regulation pressures manufacturers to eliminate hydrofluorocarbon-based cooling from climate control circuits. China's GB standards for agricultural machinery establish minimum energy efficiency thresholds that filter low-cost imports from Southeast Asian suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border equipment sales.
Market Dynamics
EU F-Gas Regulation is forcing a wholesale redesign of cooling circuits in climate-controlled hatchery systems, compressing margins for manufacturers reliant on hydrofluorocarbon-based components while advantaging forced-air engineering specialists.
Growth Catalysts
- Protein demand surge:Commercial hatcheries in Brazil are scaling capacity to serve domestic meat production and export markets, driving orders for large-scale electric incubators with automated turning mechanisms.
- GB standards enforcement:China's energy efficiency thresholds for agricultural machinery are filtering low-cost Southeast Asian imports, creating protected demand for domestic and premium-tier equipment.
- Embryo monitoring sensors:In-house development of real-time viability tracking is reducing mortality rates and labor intensity in integrated poultry operations.
Market Restraints
- Refrigerant transition costs:Elimination of HFC-based cooling under EU F-Gas Regulation requires complete retooling of climate control circuits, elevating R&D burdens for European manufacturers.
- Steel and copper volatility:Cabinet fabrication and heating element production face input cost instability from commodity markets, squeezing margin pools on economy-tier units.
- Biosecurity compliance friction:USDA National Poultry Improvement Plan sanitation standards for interstate equipment movement create certification bottlenecks for smaller hatchery suppliers.
Strategic Opportunities
- Off-grid rural zones:Solar-powered incubators represent unpenetrated demand in sub-Saharan African and South Asian poultry operations lacking reliable grid access.
- Educational institution channel:Tabletop units for vocational training and STEM programs offer recurring replacement cycles distinct from commercial agriculture procurement patterns.
- Dual carbon alignment:China's national carbon neutrality targets are accelerating subsidies for energy-efficient agricultural machinery, favoring inverter-driven forced-air designs over resistive heating systems.
Industry Challenges
- Control systems integration:Legacy hatcheries face technical debt when retrofitting automated humidity and ventilation modules onto mechanically simple existing infrastructure.
- Embryology technician scarcity:Specialized expertise in candling, calibration, and mortality diagnostics is concentrating in integrated operations, leaving independent hatcheries dependent on vendor field service.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Incubator Market |
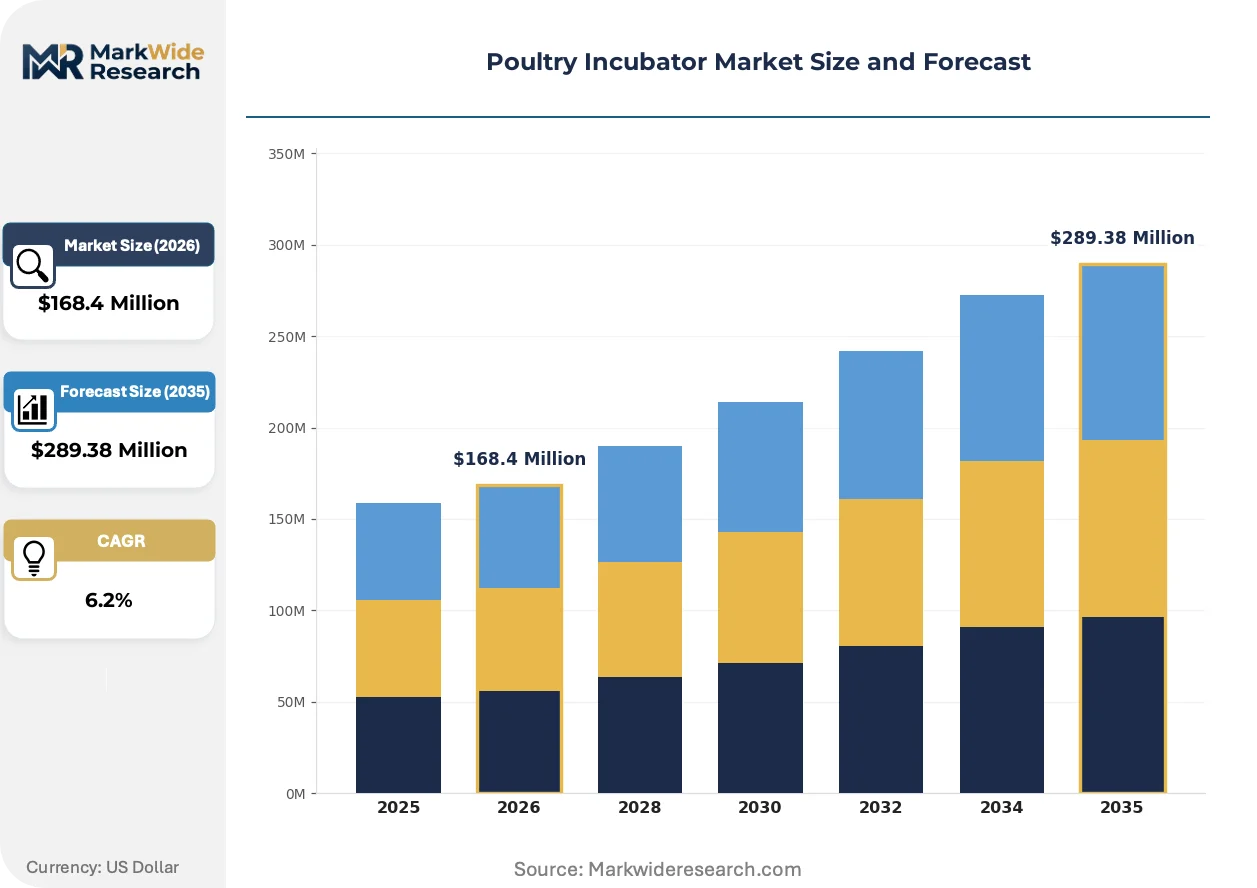
| Market Size in 2026 | $168.4 Million |
| Market Size in 2035 | $289.38 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Incubators, Forced Air Incubators, Tabletop Incubators, Still Air Incubators End User: Commercial Hatcheries, Backyard Farmers, Research Institutions, Poultry Breeders Operation Mode: Electric Incubators, Solar-Powered Incubators, Manual Incubators, Hybrid Incubators Capacity: Small-Scale, Medium-Scale, Large-Scale, Industrial |
| Companies Covered | Petersime NV, Pas Reform Hatchery Technologies, Jamesway Incubator Company, Brinsea Products, HatchTech, Chore-Time, Jansen Poultry, HEKA-Brutgeräte, GQF Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Incubator Market Trends and Innovations
Sensor fusion and predictive analytics are compressing the skill gap required for commercial hatchery operations, enabling centralized monitoring of distributed incubator banks from remote facilities.
IoT-enabled environmental controllers are unifying temperature, humidity, and CO2 management into single-platform dashboards. Large integrated poultry operations in the Netherlands and Denmark are adopting these systems fastest, consolidating oversight of multi-site hatcheries under centralized agronomy teams. This unification is compressing the competitive advantage of traditional field-service-dependent vendors.
EU F-Gas Regulation is prohibiting hydrofluorocarbon refrigerants in new climate-controlled incubators from 2025. Manufacturers serving European hatcheries are pivoting to hydrocarbon and CO2-based cooling circuits, with premium-tier suppliers absorbing retooling costs faster than economy competitors. German and Belgian engineering bases are capturing specification authority as regulatory complexity escalates.
Integrated poultry operations are consolidating procurement authority at headquarters level, displacing distributed purchasing by individual farm managers. Equipment vendors now face consolidated tender processes with extended evaluation cycles and unbundled after-sales service negotiations. This concentration is most visible in China's Shandong and Guangdong provinces where domestic protein giants are standardizing incubator fleets across acquired subsidiaries.
Poultry Incubator Market Segmentation
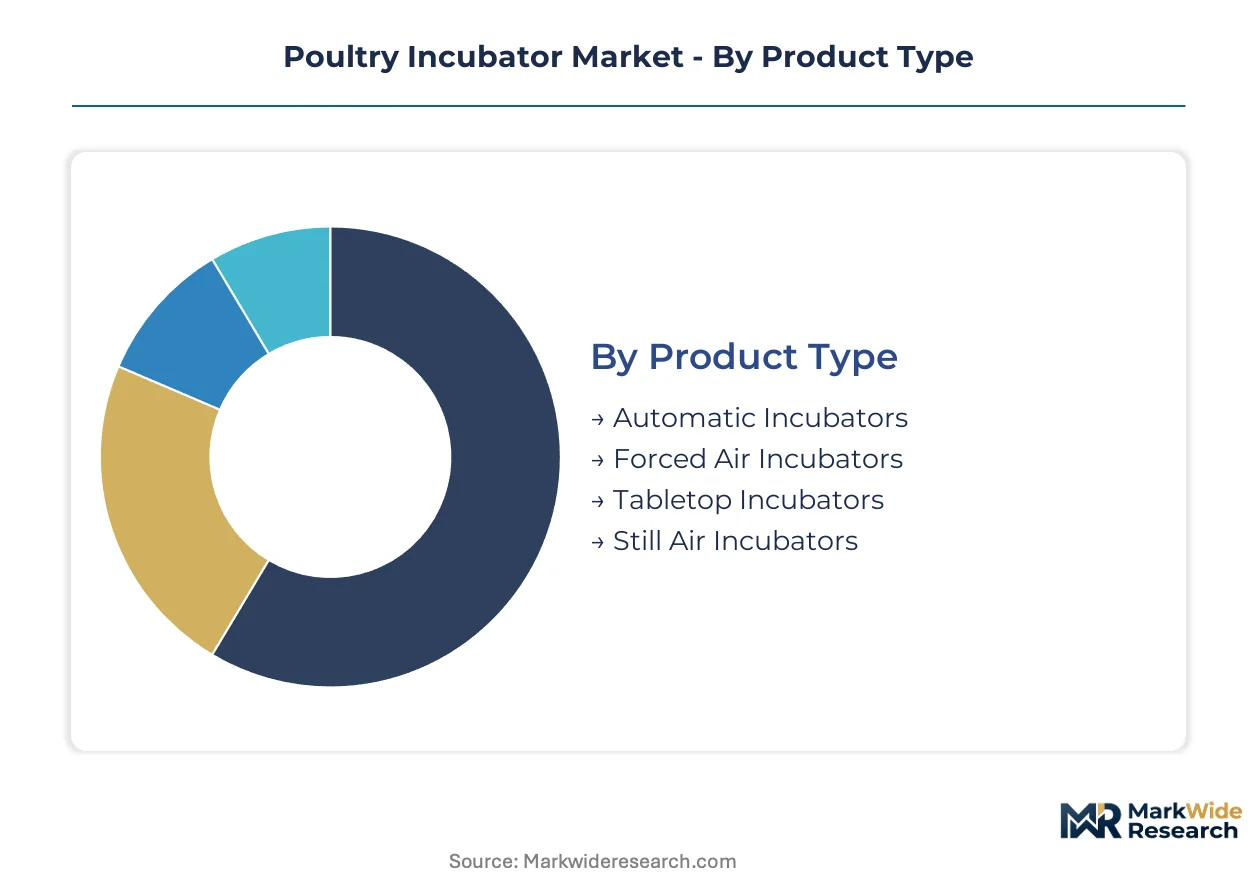
Poultry incubator segmentation reflects divergent capital intensity, automation requirements, and energy access across production scales. Equipment specifications vary sharply between integrated commercial operations and dispersed rural holdings, creating distinct margin pools and replacement-cycle dynamics for manufacturers.
Product Type:
Equipment replacement cycles accelerate where automated environmental control reduces labor dependency and mortality variance.
- Automatic Incubators:Embedded microprocessor systems manage temperature, humidity, and egg-turning intervals without manual intervention. Demand concentrates in Brazil's commercial hatcheries serving export-oriented meat production, driven by labor cost escalation and batch consistency requirements.
- Forced Air Incubators:Circulation fans distribute heat uniformly across cabinet volumes, enabling higher egg densities per unit floor space. EU F-Gas Regulation is compressing margins for manufacturers reliant on hydrofluorocarbon cooling circuits while advantaging engineering specialists with hydrocarbon transition capabilities.
- Tabletop Incubators:Compact units serve educational demonstration and hobbyist breeding with limited capital outlay.
- Still Air Incubators:Passive convection designs persist in price-sensitive rural markets with unreliable electricity.
Volume placements concentrate in Forced Air Incubators; the faster expansion belongs to Automatic Incubators.
End User:
Customer procurement authority is consolidating at headquarters level across integrated operations, extending tender cycles and unbundling service negotiations.
- Commercial Hatcheries:Industrial-scale facilities operate continuous-batch systems with centralized monitoring infrastructure. China's Shandong and Guangdong protein giants are standardizing incubator fleets across acquired subsidiaries, filtering procurement toward premium-tier suppliers with national service networks.
- Backyard Farmers:Small-holding operations prioritize capital efficiency over automation depth. Sub-Saharan African and South Asian poultry zones lacking grid reliability drive demand for manual and solar-compatible units.
- Research Institutions:Controlled-environment specifications for genetic and veterinary studies require precision calibration capabilities.
- Poultry Breeders:Specialist genetic stock operations balance batch size flexibility with pedigree documentation requirements.
Procurement value pools concentrate in Commercial Hatcheries; Research Institutions show the steepest expansion trajectory for sensor-integrated climate systems.
Operation Mode:
Energy infrastructure gaps across rural poultry belts are fragmenting technology adoption by geography.
- Electric Incubators:Grid-dependent systems dominate integrated operations with reliable power supply. Brazil's commercial hatchery expansion and China's domestic production scaling sustain replacement demand for large-scale electric units with automated turning mechanisms.
- Solar-Powered Incubators:Photovoltaic-battery configurations enable off-grid operation in sub-Saharan African and South Asian zones lacking distribution infrastructure. Unit economics improve as panel costs decline and rural electrification programs lag poultry investment timelines.
- Manual Incubators:Hand-turned designs persist where capital constraints exceed energy access limitations.
- Hybrid Incubators:Dual-source systems combine grid and solar inputs for transitional reliability.
Shipment volumes concentrate in Electric Incubators; Solar-Powered Incubators are gaining share fastest in emerging-market rural corridors.
Capacity:
Scale-tier pricing stratifies across capital intensity, control system sophistication, and service bundling depth.
- Large-Scale:Cabinet systems accommodate thousands of eggs per batch with centralized environmental monitoring. China's GB standards for agricultural machinery energy efficiency are filtering low-cost imports, protecting domestic and premium-tier suppliers in this segment.
- Industrial:Walk-in chamber configurations serve mega-hatcheries with continuous throughput requirements. Netherlands and Denmark integrated operations are adopting IoT-enabled controllers fastest, consolidating multi-site oversight under centralized agronomy teams.
- Small-Scale:Countertop and cabinet units serve educational and hobbyist markets with limited batch sizes.
- Medium-Scale:Intermediate capacities bridge commercial entry and full industrial integration.
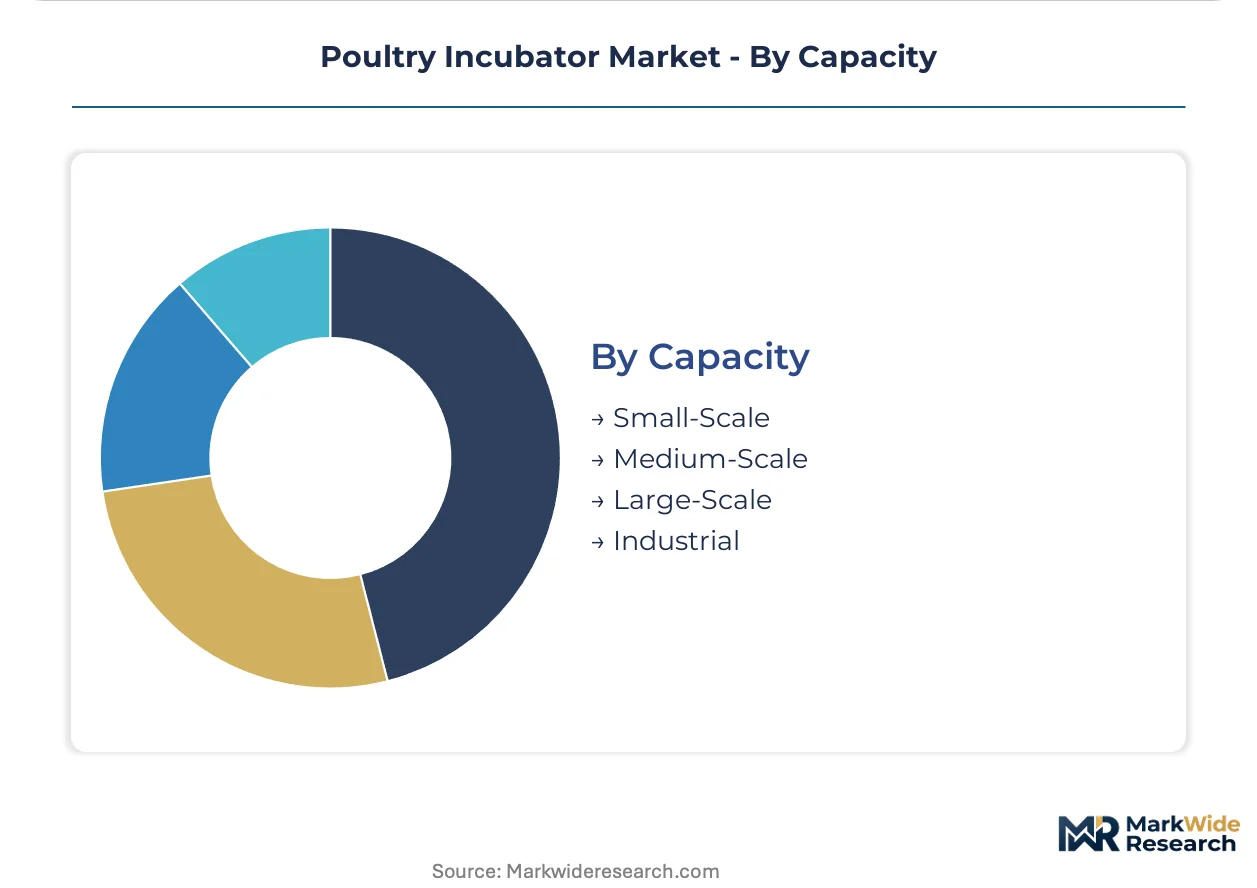
Revenue concentration sits with Large-Scale units; Industrial capacity is climbing the fastest as procurement authority consolidates in integrated protein operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soybean meal availability in Brazil's Cerrado region underpins feedstock economics for integrated poultry operations driving incubator procurement decisions. Steel and copper price volatility across Chinese manufacturing hubs reshapes equipment cost structures for export markets. Regulatory divergence between Brussels, Beijing, and Washington fragments certification requirements for climate-control components.
China
Domestic protein production scaling reduces import dependency for chicken meat and eggs. GB standards for agricultural machinery establish minimum energy efficiency thresholds filtering low-cost Southeast Asian equipment imports. Shandong and Guangdong provinces concentrate procurement authority as domestic giants standardize incubator fleets across acquired subsidiaries.
Brazil
Commercial hatcheries expand capacity to serve domestic meat consumption and export markets to Middle Eastern buyers. ANVISA biosecurity protocols govern interstate equipment movement and sanitation certification for hatchery infrastructure. São Paulo state anchors manufacturing clusters for large-scale electric units with automated turning mechanisms.
United States
Industrial-grade replacement cycles sustain demand for precision climate-controlled systems in Midwest poultry belts. USDA National Poultry Improvement Plan enforces sanitation standards for hatchery equipment crossing state lines. Georgia and Arkansas concentrate integrated operations consolidating procurement at headquarters level.
Germany
Engineering-intensive forced-air designs capture specification authority amid refrigerant transition complexity. EU F-Gas Regulation prohibits hydrofluorocarbon cooling in new climate-controlled incubators from 2025. Bavaria and North Rhine-Westphalia host premium-tier suppliers absorbing retooling costs faster than economy competitors.
Netherlands
IoT-enabled environmental controllers unify multi-site hatchery oversight under centralized agronomy teams. EU Green Deal agricultural machinery incentives accelerate adoption of inverter-driven forced-air designs over resistive heating. Gelderland province concentrates integrated operations adopting sensor-fusion platforms fastest.
Poultry Incubator Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solar-compatible configurations for off-grid rural zones. The vendor base stratifies across three capability tiers: premium engineering specialists with hydrocarbon cooling transition capabilities, mid-scale fabricators serving regional replacement cycles, and price-point competitors concentrated in manual and small-capacity segments. Two dominant competitive moves define current positioning: backward integration into control system firmware development, and geographic expansion through distributor partnerships in sub-Saharan African corridors.
Within the premium engineering tier, Petersime NV and Pas Reform Hatchery Technologies exemplify European specialists leveraging Belgian and Dutch engineering bases for climate-controlled hatchery systems. Jamesway Incubator Company anchors North American industrial-grade replacement demand. These three occupy positions distinguished by service network depth and regulatory compliance authority rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Petersime NV |
| Pas Reform Hatchery Technologies |
| Jamesway Incubator Company |
| Brinsea Products |
| HatchTech |
| Chore-Time |
| Jansen Poultry |
| HEKA-Brutgeräte |
| GQF Manufacturing Company |
| Others |
Pricing and Supply Chain Analysis
Integrated protein giants in China's Shandong and Guangdong provinces concentrate procurement authority at headquarters level, compressing vendor margins through consolidated tender processes that unbundle after-sales service from equipment pricing. This buyer concentration forces manufacturers toward three-tier pricing structures that separate premium climate-controlled systems from standard forced-air units and economy manual designs.
Pricing Analysis
Warranty and field-service bundling now separates premium-tier suppliers from mid-scale competitors, with Petersime NV and Pas Reform Hatchery Technologies commanding price premiums through multi-year maintenance contracts while economy fabricators compete on unbundled equipment-only transactions. Pricing stratifies across premium, standard, and economy tiers based on certification grade for EU F-Gas compliance and control system sophistication. Cost compression in the economy tier is intensifying as steel and copper volatility squeezes cabinet fabrication margins. Backyard farmers and educational institutions exhibit highest price sensitivity, while commercial hatcheries prioritize batch consistency over capital outlay.
Supply Chain Analysis
Regional distribution centers in Belgium, the Netherlands, and Germany anchor hub-and-spoke patterns serving European hatchery clusters, while São Paulo state and China's Zhejiang province concentrate manufacturing for export markets. Steel sheet and copper heating element supplies draw from Chinese and Brazilian metalworking hubs. Single-source vulnerability in microprocessor-based control systems creates exposure to semiconductor foundry concentration. Distribution runs through authorized dealer networks for premium-tier equipment and direct-to-farm channels for manual and small-capacity units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory compliance capabilities, with EU F-Gas refrigerant transition costs forcing smaller fabricators toward exit or acquisition by engineering specialists with hydrocarbon cooling expertise.
For Market Incumbents: Anticipate margin compression in economy-tier segments as Chinese GB standards filter low-cost imports and elevate R&D burdens for refrigerant transition. Defensive moves center on backward integration into embryo monitoring sensor firmware and captive service network expansion across Brazil's Cerrado hatchery corridor. The priority lever sits with hydrocarbon cooling circuit certification to capture specification authority in European procurement cycles. For New Entrants and Emerging Players: E-commerce and agricultural extension channels offer lowest-friction routes to sub-Saharan African and South Asian backyard farmer segments, where solar-powered configurations face limited incumbent penetration. White-space targets include off-grid rural zones lacking distribution infrastructure and educational institution replacement cycles distinct from commercial agriculture patterns. Go-to-market execution should emphasize photovoltaic-battery unit economics and vocational training partnerships. For Investors and Strategic Acquirers: The window for entry favors mid-scale European fabricators with F-Gas transition capabilities and established service networks in protein production clusters. Long-term viability hinges on consolidation of procurement authority at integrated operation headquarters level, favoring targets with national-scale maintenance infrastructure. The signal to watch is subsidy acceleration under China's dual carbon targets for inverter-driven forced-air designs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Firmware | In-house embryo monitoring development reduces mortality variance and vendor dependency for Pas Reform Hatchery Technologies. |
| Hydrocarbon Cooling Transition | EU F-Gas compliance investment separates premium engineering specialists from economy competitors in climate-controlled segments. |
| Solar-Compatible Product Line Expansion | Photovoltaic-battery configurations capture unpenetrated demand in sub-Saharan African and South Asian off-grid corridors. |
| Headquarters-Level Service Contracting | Unbundled after-sales negotiations with Shandong and Guangdong protein giants secure recurring revenue streams independent of equipment sales. |
| Educational Institution Channel Development | Vocational training and STEM program partnerships establish replacement cycles distinct from commercial hatchery procurement patterns. |
Research Methodology
Trade association filings, customs export records, and agricultural machinery registration databases formed the secondary backbone for demand quantification. Primary interviews with hatchery operations managers, OEM procurement leads at integrated poultry companies, agricultural extension officers, and aftermarket service heads validated equipment replacement cycle assumptions and pricing tier boundaries. Bottom-up and top-down triangulation cross-checked volume estimates against protein production scaling trajectories in Brazil and China.
Bottom-up modeling built from unit shipment data by capacity tier and operation mode, while top-down verification anchored against national poultry flock statistics and hatchery capacity utilization rates. Segmentation dimensions included product type, end-user category, operation mode, and capacity scale across the projection horizon. CAGRs derived from regression analysis of historical replacement patterns and regulatory compliance investment cycles, with specific inputs from EU F-Gas implementation timelines and China's GB standards enforcement trajectories.
The model holds under stable commodity price regimes and gradual electrification progress in rural poultry belts; deviation in steel-copper volatility or accelerated solar subsidy programs would shift equipment mix assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poultry Farming Equipment
Rabbit Cages Market
Poultry Farming Equipment
Poultry Keeping Machinery Market
Poultry Farming Equipment
Automated Poultry Farm Market
Poultry Farming Equipment
Egg Grading Machines Market
Poultry Farming Equipment
Turkey Poultry Market
Poultry Farming Equipment
Poultry House Ventilation System Market
Poultry Farming Equipment
Multi-Layer Poultry Cage Market
Poultry Farming Equipment
Poultry Brooder Market
Poultry Farming Equipment
Poultry Brooders, Feeders, and Waterers Market
Poultry Farming Equipment
Duck Plucker Machine Market
Poultry Farming Equipment
Poultry Plucker Market
Poultry Farming Equipment
Egg Breaking Machine Market
Poultry Farming Equipment
Commercial Chicken Plucker Market
Poultry Farming Equipment
Asia Pacific Poultry Market
Poultry Farming Equipment
Poultry Farming Equipment Market