
 North America Wedding Services Market | 2026-2036
North America Wedding Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wedding Services Market Insights
ASTD Certified Wedding Planner designation is bifurcating the competitive landscape between credentialed full-service firms and unlicensed operators. David's Bridal anchors bridal retail through vertically integrated gown design and alteration networks across the United States. The Knot Worldwide dominates digital vendor discovery through proprietary review algorithms and registry technology. Zola competes in the same digital space by extending its platform into honeymoon planning and guest management tools.
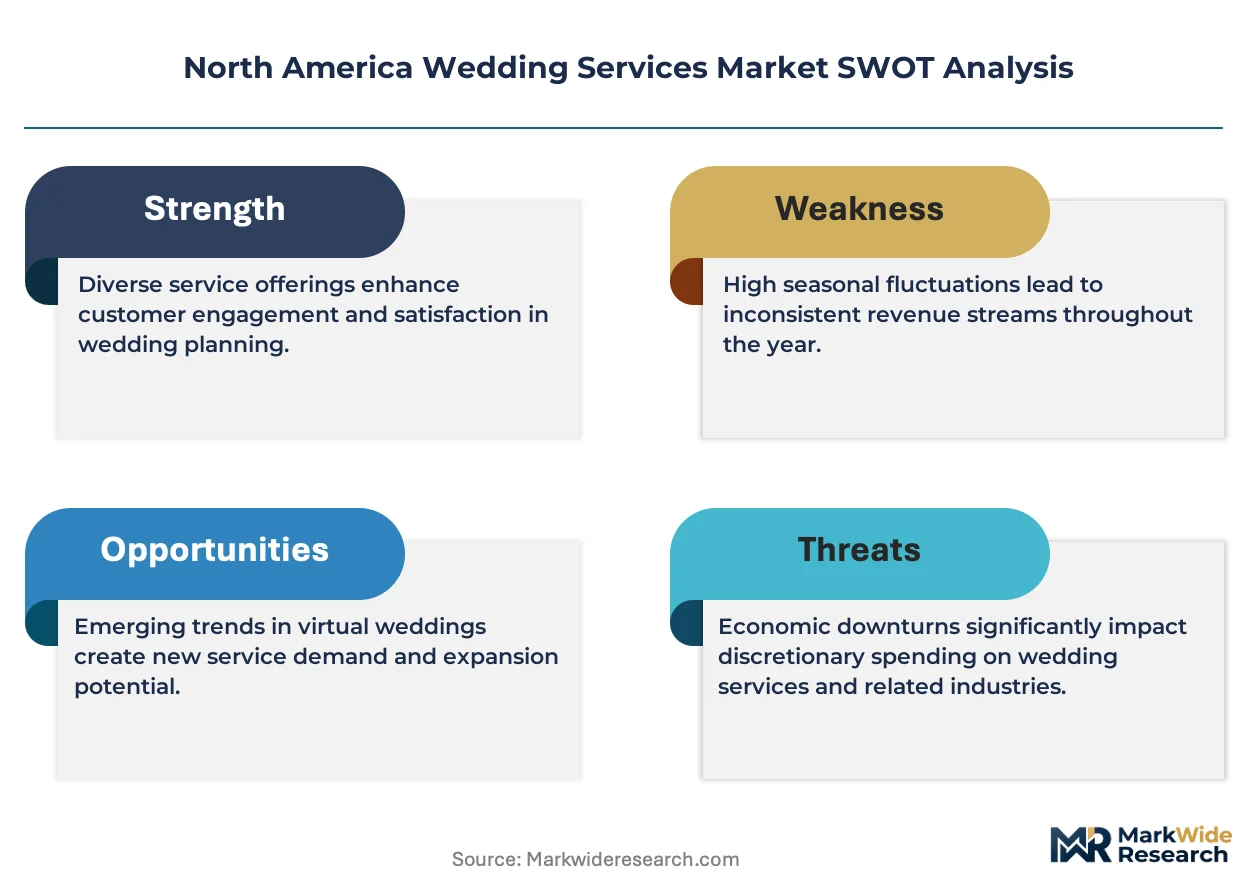
Wedding services encompass the coordinated provision of ceremonial and reception support including catering logistics, photographic documentation, floral installation, and venue procurement. Technical execution requires adherence to food safety protocols, liability insurance thresholds, and acoustic permitting for outdoor amplification. Venue rental and catering together represent the mature revenue core where margin compression is most acute. Photography and floral design occupy faster-growing positions as couples prioritize experiential differentiation and social media documentation. Luxury and premium price tiers command disproportionate margin pools despite representing smaller volume shares.
The U.S. Food and Drug Administration and state health departments govern catering safety standards, while the Occupational Safety and Health Administration regulates temporary event structure installation. Canadian couples fall under Health Canada guidelines for food service at private events, with provincial liquor boards controlling beverage licensing. Stakeholders must monitor evolving short-term rental regulations in major metropolitan zones and decide whether to build compliance infrastructure in-house or absorb third-party coordination costs.
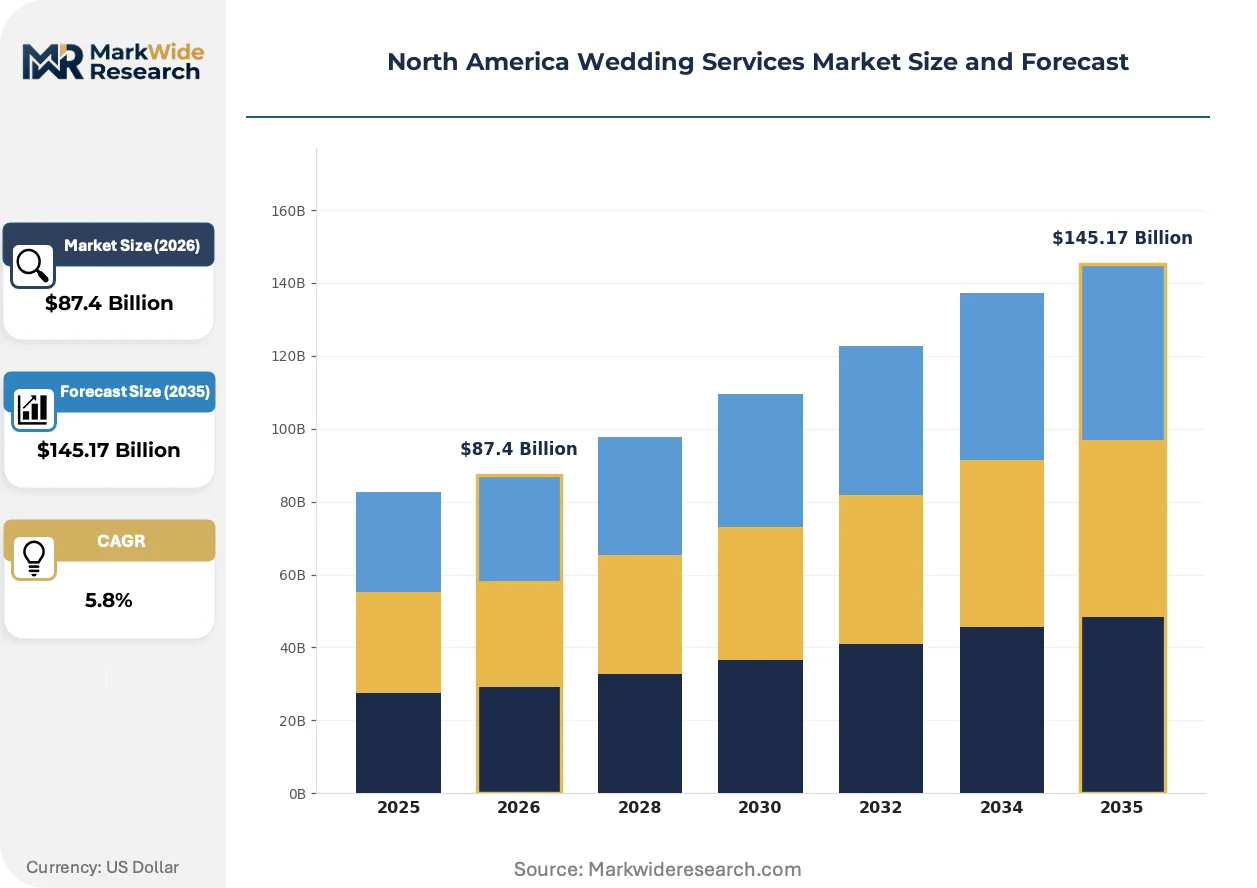
Market Dynamics
The North America wedding services sector is experiencing structural pressure from state-level event insurance mandates and the U.S. Small Business Administration's lending programs, which are forcing vendor compliance infrastructure upgrades and reshaping competitive entry barriers.
Growth Catalysts
- Destination Wedding Demand:Millennial and Gen-Z couples are driving cross-border bookings toward climate-diverse venues in California, Texas, and Florida, expanding addressable revenue pools for regional operators.
- OSHA Temporary Structure Standards:Federal workplace safety protocols for outdoor event installations are professionalizing vendor capabilities and creating differentiation for certified installation crews.
- Social Media Documentation Priority:Couples now allocate disproportionate budgets toward photography and floral design for experiential differentiation, accelerating service premiumization.
Market Restraints
- Labor Cost Volatility:Catering and floral installation depend on seasonal wage fluctuation in metropolitan zones, compressing margin predictability for full-service firms.
- Venue Supply Concentration:Premium indoor and outdoor locations cluster in three U.S. states, creating booking bottlenecks and price inelasticity during peak seasons.
- Short-Term Rental Regulation Friction:Evolving municipal restrictions on non-traditional venues in major metropolitan zones limit expansion options for boutique operators.
Strategic Opportunities
- ASTD Certification Tailwind:The certified wedding planner designation creates margin separation between credentialed full-service firms and unlicensed competitors, rewarding compliance investment.
- Honeymoon Integration:Digital platforms are converging wedding planning with travel booking, opening ancillary revenue streams for vendors extending into guest management tools.
- Canadian Regulatory Alignment:Health Canada food service guidelines for private events present standardization advantages for U.S. caterers expanding cross-border operations.
Industry Challenges
- Food Safety Compliance Timeline:FDA and state health department catering protocols require continuous staff certification updates, draining administrative bandwidth from smaller operators.
- Acoustic Permitting Complexity:Outdoor amplification licensing varies by municipality, forcing event producers to maintain jurisdiction-specific compliance databases or absorb third-party coordination costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wedding Services Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $145.17 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Catering, Photography, Floral Design, Venue Rental Customer Type: Brides, Grooms, Wedding Planners, Families Price Tier: Budget, Mid-Range, Luxury, Premium Package Type: All-Inclusive, Custom, Elopement, Partial |
| Companies Covered | David's Bridal, BBJ Linen, The Knot Worldwide, Calluna Events, Generation Tux, WeddingWire, Minted, ROQUE Events, Zola, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wedding Services Market Trends and Innovations
Digital vendor discovery platforms and proprietary registry technology are restructuring how couples allocate wedding budgets, compressing traditional intermediary roles while elevating data-driven personalization.
AI-powered guest management tools are displacing manual RSVP tracking and seating chart workflows. Destination wedding planners and luxury-tier couples are adopting these systems fastest, typically within 12-18 month refresh cycles. This automation is displacing traditional coordinator hours toward higher-margin design consultation and day-of execution roles.
Health Canada and provincial liquor boards are tightening beverage licensing enforcement at private events, particularly for cross-border destination weddings. Canadian operators now face mandatory server certification and liability documentation. Ontario and British Columbia venues are responding by bundling licensed bar service into base packages rather than allowing BYOB arrangements.
Couples are unbundling all-inclusive venue packages into à la carte vendor selection, prioritizing vendor-specific social media portfolios over venue-preferred lists. This fragmentation is most visible in California and Florida, where independent photographers and floral designers now capture 40-60% of bookings directly through Instagram and TikTok discovery rather than venue referrals.
North America Wedding Services Market Segmentation
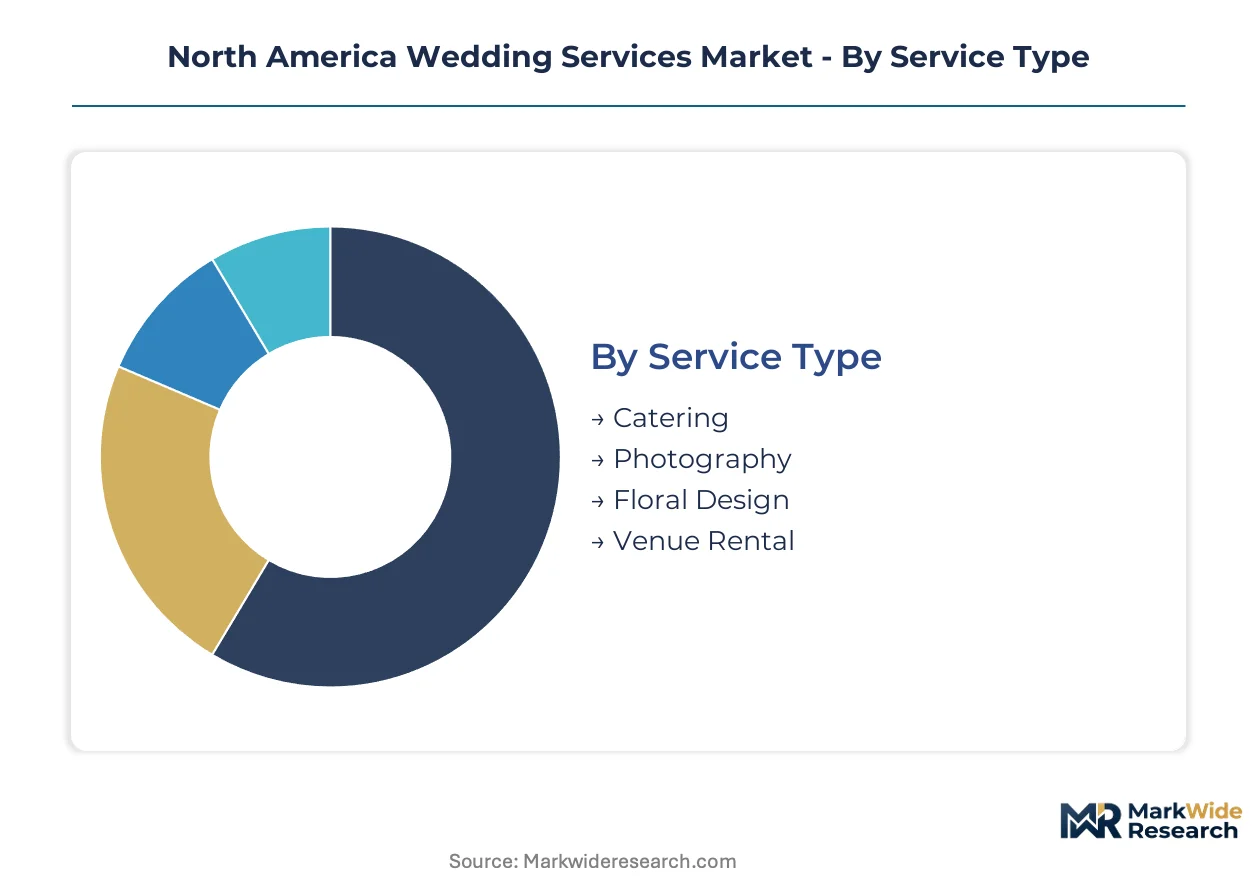
Wedding services segment along four intersecting dimensions that determine vendor selection workflows and margin structures. Service type and price tier drive procurement patterns, while customer type and package configuration shape platform monetization models.
Service Type:
Domestic demand concentrates in California, Texas, and Florida venues, while cross-border Canadian bookings favor photographic documentation and floral design for destination events.
- Catering:Food safety protocols under FDA and state health departments govern menu execution, with liability insurance thresholds rising under new mandates. Demand clusters in metropolitan zones with established vendor networks, though labor cost volatility compresses margin predictability for full-service operators.
- Photography:Social media documentation priorities have elevated this segment's budget allocation, with couples prioritizing experiential differentiation and platform-ready content. California and Florida independent photographers now capture direct bookings through Instagram and TikTok discovery rather than venue referrals.
- Floral Design:Installation crews face OSHA temporary structure standards for outdoor amplification and tent mounting, professionalizing vendor capabilities.
- Venue Rental:Premium locations cluster in three U.S. states, creating booking bottlenecks and price inelasticity during peak seasons.
Venue rental holds the largest share; momentum sits with photography.
Customer Type:
Procurement authority varies sharply by budget tier, with wedding planners commanding premium service access while families drive volume in mid-range markets.
- Brides:Primary decision-makers for aesthetic and experiential elements, with digital platform engagement highest among millennial and Gen-Z demographics. The Knot Worldwide and Zola capture this cohort through proprietary review algorithms and registry technology.
- Grooms:Expanding influence in vendor selection, particularly for catering logistics and acoustic permitting for outdoor amplification. This segment shows faster adoption of AI-powered guest management tools.
- Wedding Planners:ASTD certification is bifurcating this field between credentialed full-service firms and unlicensed operators, with certified planners commanding margin separation.
- Families:Budget authority concentrates here for traditional ceremonies, with multi-generational input extending decision timelines and favoring all-inclusive packages.
Families hold the largest share; wedding planners are climbing the fastest.
Price Tier:
Cost structures align with regulatory compliance burdens, as luxury and premium tiers absorb certification and insurance infrastructure more readily than budget operators.
- Budget:Price-sensitive couples unbundle all-inclusive packages into à la carte vendor selection, prioritizing independent operators with strong social media portfolios over venue-preferred lists.
- Mid-Range:Represents the volume core where margin compression is most acute, with couples balancing experiential priorities against venue supply concentration in California, Texas, and Florida.
- Luxury:Command disproportionate margin pools despite smaller volume shares, with destination wedding demand rising among affluent millennial and Gen-Z couples toward climate-diverse venues.
- Premium:Full-service firms with ASTD certification capture this tier, leveraging compliance investment to separate from unlicensed competitors.
Mid-range holds the largest share; luxury shows the steepest expansion trajectory.
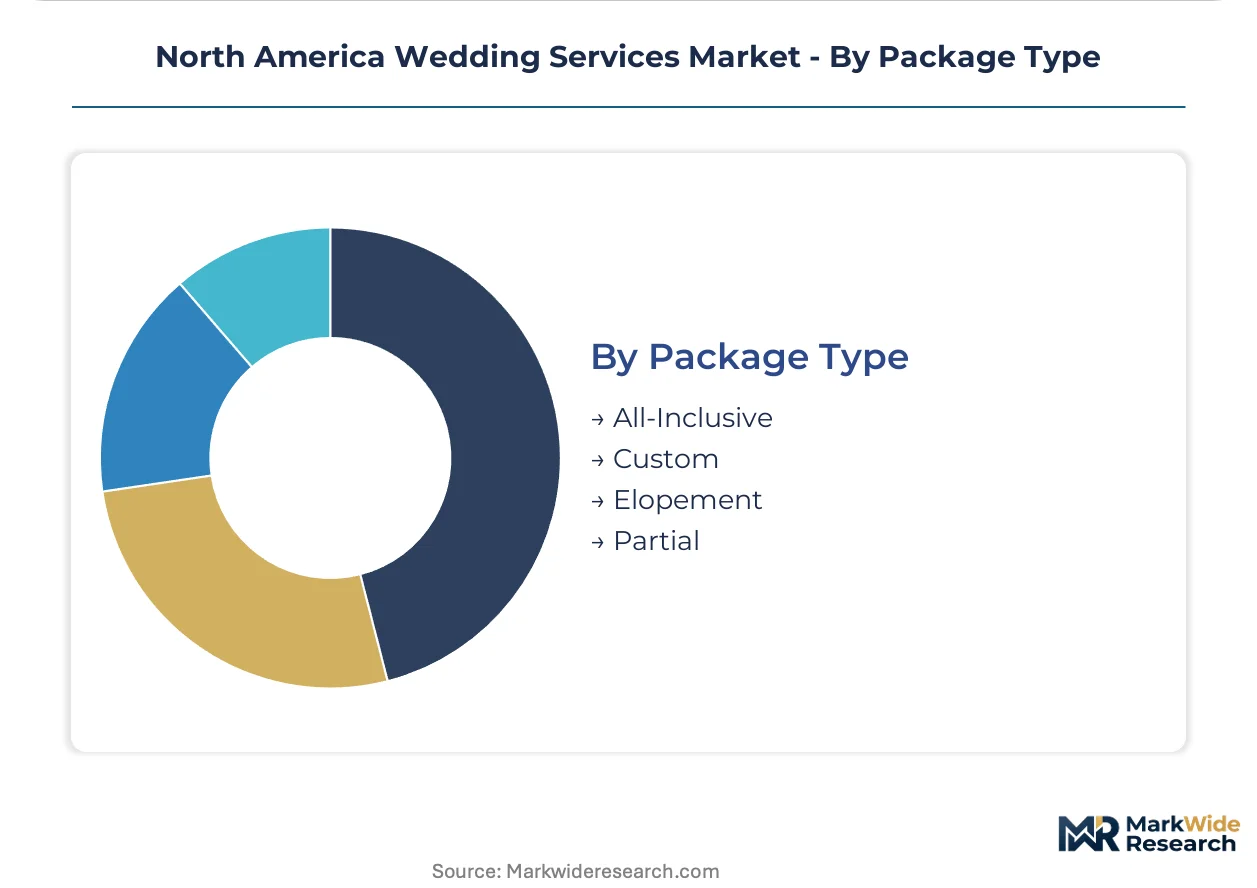
Package Type:
Configuration preferences reflect regulatory complexity tolerance, with all-inclusive offerings absorbing compliance coordination costs that fragment under custom arrangements.
- All-Inclusive:Venue-preferred vendor lists are losing share as couples prioritize vendor-specific discovery, though this model retains strength where Health Canada and provincial liquor boards mandate bundled licensed bar service.
- Custom:Unbundling trend is most visible in California and Florida, where independent photographers and floral designers capture 40-60% of bookings directly through social media platforms.
- Elopement:Simplified regulatory footprint appeals to cross-border destination weddings, particularly where short-term rental regulation friction limits boutique operator expansion in major metropolitan zones.
- Partial:Hybrid approach combining venue procurement with à la carte service selection, requiring couples to maintain jurisdiction-specific compliance databases for acoustic permitting and food safety protocols.
All-inclusive holds the largest share; custom configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Small Business Administration's lending programs and state-level event insurance mandates are reshaping vendor operating requirements across North America. Destination wedding demand concentrates in California, Texas, and Florida, where climate diversity and venue density attract both domestic and cross-border couples.
United States
California, Texas, and Florida dominate venue procurement and catering logistics, with metropolitan zones in Los Angeles, Houston, and Miami commanding premium booking rates. The U.S. Food and Drug Administration governs food safety protocols for private event catering, while OSHA regulates temporary structure installation for outdoor ceremonies. Independent photographers and floral designers in California and Florida now capture 40-60% of bookings directly through Instagram and TikTok discovery rather than venue referrals.
Canada
Cross-border destination wedding demand from U.S. couples is accelerating bookings in Ontario and British Columbia, particularly for photographic documentation and floral design services. Health Canada guidelines govern food service at private events, with provincial liquor boards tightening beverage licensing enforcement and mandating server certification. Ontario and British Columbia venues are responding by bundling licensed bar service into base packages rather than allowing BYOB arrangements.
Mexico
Riviera Maya and Los Cabos beach destinations are capturing premium-tier destination wedding volume from North American couples seeking climate-advantaged outdoor ceremonies. Mexican federal tourism promotion programs and state-level hospitality incentives are professionalizing vendor certification standards in Quintana Roo and Baja California Sur. Cancún and Cabo San Lucas hospitality clusters are investing in acoustic permitting infrastructure and liability insurance coordination to compete with U.S. domestic venues.
North America Wedding Services Market Competitive Landscape
Player mix skews toward vertically integrated bridal retailers and digital platform operators with proprietary discovery algorithms. Market structure bifurcates between credentialed full-service planning firms and unlicensed independent operators, with ASTD certification creating margin separation. Two strategic archetypes dominate: bridal retail chains with captive alteration networks, and digital aggregators monetizing vendor discovery through registry technology and review algorithms. Competitive moves center on platform extension into honeymoon planning and guest management tools, plus certification infrastructure investment to capture premium-tier procurement.
Within the bridal retail archetype, David's Bridal anchors physical gown distribution through vertically integrated design and alteration networks. The Knot Worldwide and Zola occupy the digital platform tier, with The Knot Worldwide exemplifying vendor discovery monetization through proprietary review algorithms and Zola representing platform extension into honeymoon booking and AI-powered guest management workflows. These three companies illustrate the competitive tension between physical retail scale and digital aggregation efficiency.
| Leading Market Players |
|---|
| David's Bridal |
| BBJ Linen |
| The Knot Worldwide |
| Calluna Events |
| Generation Tux |
| WeddingWire |
| Minted |
| ROQUE Events |
| Zola |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day floral procurement lead times concentrate margin pressure among California and Florida operators, binding pricing power to climate-dependent inventory cycles and forcing tiered service structures that separate ASTD-certified planners from unlicensed competitors.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ASTD-credentialed planners commanding margin separation through compliance infrastructure that unlicensed operators cannot replicate. Project-based pricing dominates catering and venue rental, while photography and floral design shift toward value-based models tied to social media portfolio strength. Cost compression in mid-range catering intensifies because labor wage volatility in metropolitan zones erodes predictability. Budget-tier couples exhibit highest price sensitivity, unbundling packages to prioritize independent vendors with platform-discoverable portfolios; luxury-tier buyers absorb certification premiums without volume trade-offs.
Supply Chain Analysis
Just-in-time floral sourcing from Ecuador, Colombia, and domestic California growers dominates inventory strategy, though peak-season demand surges force strategic stockpiling of hard goods and linens. Raw material dependencies center on imported blooms, specialty textiles, and temporary structure components. Single-source vulnerability concentrates in South American flower corridors exposed to climate disruption and logistics chokepoints at Miami customs. Distribution runs through regional hub-and-spoke networks anchored in Los Angeles, Houston, and Miami, with final-mile coordination handled by venue-staffed receiving teams or certified installation crews.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as couples unbundle all-inclusive packages and prioritize vendor-specific discovery over venue-preferred lists, creating niche entry points for certified specialists and platform-native operators.
For Market Incumbents: Compound certification advantages by embedding ASTD standards into proprietary training pipelines, locking in margin separation from unlicensed competitors. Vertical integration into captive floral sourcing from Ecuadorian growers insulates against climate-driven price spikes. Channel control through exclusive venue partnerships defends against platform disintermediation threatening traditional referral economics. For New Entrants and Emerging Players: Differentiate on AI-powered guest management tools, where adoption cycles among luxury-tier couples lag platform capabilities. White-space targets cluster in Canadian cross-border destination weddings, where Health Canada beverage licensing complexity repels under-resourced operators. Go-to-market through TikTok and Instagram portfolio discovery bypasses venue gatekeeper fees dominant in California and Florida. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned regional caterers with established FDA compliance infrastructure but absent digital platform presence. Long-term viability favors operators with dual certification and technology stacks capable of serving both domestic and cross-border destination demand. Watch OSHA temporary structure enforcement intensity as inflection indicator for installation crew specialization premiums.| Strategic Initiative | Industry Significance |
|---|---|
| ASTD Certification Investment | Creates margin separation from unlicensed competitors in premium procurement tiers. |
| Platform Integration | Zola and The Knot Worldwide monetize vendor discovery through registry technology lock-in. |
| Backward Integration into Floral Sourcing | Captive Ecuadorian supply chains insulate California operators from climate-driven price volatility. |
| AI Guest Management Deployment | Automated RSVP workflows displace coordinator hours toward higher-margin design consultation. |
| Canadian Regulatory Alignment | Health Canada standardization advantages reward U.S. caterers expanding cross-border operations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA food safety filings, OSHA temporary structure guidance, state health department catering protocols, and Health Canada private event guidelines. Interviews with ASTD-certified wedding planners, venue procurement directors, floral installation crew supervisors, and catering operations managers informed demand-side segmentation. Bottom-up vendor revenue estimates triangulated against top-down addressable market calculations derived from regional marriage license data and average expenditure surveys.
Segmentation dimensions modeled include service type, customer type, price tier, and package configuration across the analysis window. CAGRs were derived from regression analysis of historical expenditure patterns and forward projection of millennial and Gen-Z demographic cohort entry. Industry-specific forecast inputs incorporated OSHA regulatory enforcement timelines and short-term rental regulation friction indices for metropolitan zones.
Material uncertainties — labor cost volatility, climate-driven floral supply disruption, and municipal acoustic permitting variability — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification adoption rates and platform penetration curves. Revision becomes warranted when OSHA enforcement intensity or Health Canada liquor board mandates cross thresholds that reshape vendor compliance economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Conferences
GCC Event Management Market
Events and Conferences
Corporate Event Planner Market
Events and Conferences
MICE Market
Events and Conferences
Event Tourism Market
Events and Conferences
Germany Event Services Market
Events and Conferences
UAE Event Management Market
Events and Conferences
Canada Wedding Services Market
Events and Conferences
Vietnam MICE Market
Events and Conferences
Asia-Pacific MICE Industry Market
Events and Conferences
Global Event Management Service Market
Events and Conferences
North America Event Services Market
Events and Conferences
Canada Event Services Market
Events and Conferences
India Wedding Services Market
Events and Conferences
Thailand MICE and Mega Event Market
Events and Conferences
Event Management Solutions Market
Events and Conferences
Exhibition, Convention & Meeting Market