
 Global Event Management Service Market | 2026-2036
Global Event Management Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Event Management Service Market Foresight
A widening capability gap between full-service operators and boutique coordinators is reorganizing competitive dynamics in event management. Freeman leverages its integrated production network to control large-scale corporate activations. Live Nation Entertainment anchors live entertainment portfolios through venue ownership and talent relationships. BCD Meetings & Events differentiates via embedded travel logistics and multinational account structures.
Event management services encompass the strategic planning, logistical coordination, technical production, and post-event analytics required to execute gatherings ranging from ten-person board retreats to fifty-thousand-attendee trade shows, with core deliverables including venue sourcing, vendor contracting, attendee registration systems, audiovisual staging, and real-time crowd flow management. The primary commercial purpose centers on converting organizational objectives—brand awareness, lead generation, stakeholder alignment, or revenue extraction—into structured temporal experiences with measurable outcomes. Corporate Event Planning dominates value capture as enterprises consolidate dispersed meetings budgets under single-source contracts, while Hybrid Event Solutions represents the fastest-expanding delivery model as clients demand simultaneous physical and digital audience pathways without duplicate production costs. Virtual Event Management has matured into a margin-compressed baseline offering rather than a premium tier.
FDA guidelines on food safety at public gatherings, OSHA crowd safety standards for temporary structures, and GDPR data handling rules for attendee information collectively elevate compliance costs and disqualify undercapitalized regional operators from multinational contracts. The EU AI Act's transparency requirements for automated recommendation engines used in event matchmaking platforms will further reshape vendor qualification criteria. Stakeholders must evaluate whether their technology stacks can pass regulatory audit without wholesale platform replacement.
Market Dynamics
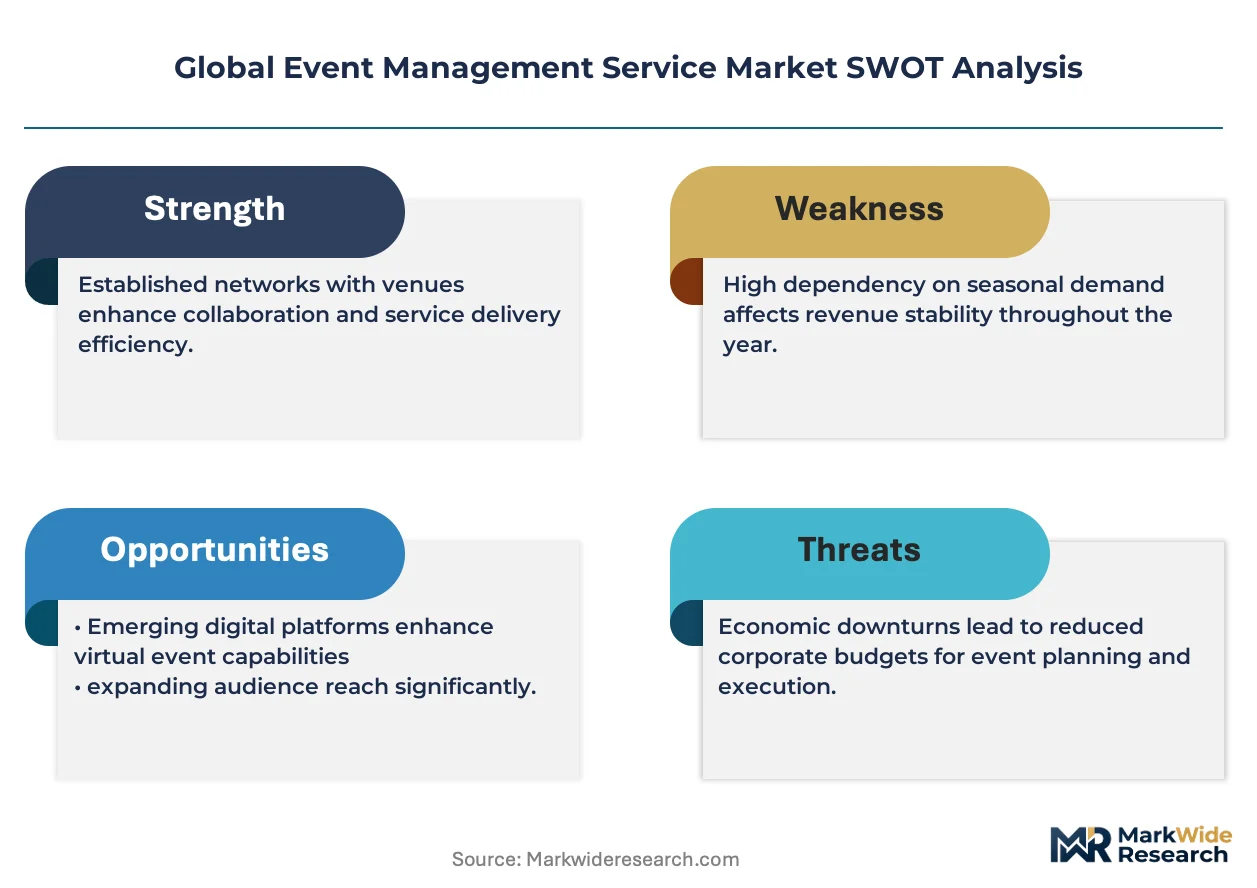
GDPR and the EU AI Act are forcing event management providers to rebuild technology stacks for compliance, redirecting procurement toward managed service providers with certified data governance and automated decision-making transparency.
Growth Catalysts
- Hybrid Event Infrastructure:Corporate clients now mandate simultaneous physical and digital audience pathways without duplicate production costs, expanding addressable market per engagement.
- GDPR Data Governance:European enterprises face escalating penalties for attendee data mishandling, creating pull for certified event technology platforms with built-in consent management and breach notification protocols.
- United Arab Emirates Tourism Investment:Dubai and Abu Dhabi government-backed destination marketing organizations are underwriting mega-event infrastructure, drawing multinational corporate activations and incentive travel programs.
Market Restraints
- Technical Talent Scarcity:Broadcast-quality virtual production and real-time audience analytics require specialized skill sets concentrated in Los Angeles, London, and Singapore, inflating labor costs for regional operators.
- EU AI Act Compliance Burden:Automated attendee matchmaking and recommendation engines face mandatory transparency documentation and human oversight requirements, extending platform development timelines.
- Venue Ownership Concentration:Live Nation Entertainment and ASM Global control premium arena and convention center inventory in major metropolitan markets, constraining independent event producers' negotiating leverage.
Strategic Opportunities
- Saudi Arabia Giga-Project Pipeline:NEOM, Qiddiya, and Red Sea Project developments are commissioning permanent event infrastructure, creating first-mover advantage for operators establishing local production capabilities.
- Carbon Accounting Integration:CSRD-mandated emissions disclosure for large European enterprises is creating demand for event-specific carbon footprint measurement and offset bundling as a differentiated service layer.
- AI-Generated Content Workflows:Convergence of generative AI with real-time rendering engines enables personalized attendee experiences at scale, reducing per-head creative production costs.
Industry Challenges
- Cybersecurity Certification Complexity:ISO 27001 and SOC 2 Type II audits for event registration and payment platforms require 12-18 month implementation cycles, delaying market entry for new technology vendors.
- Legacy AV Integration Friction:Corporate clients' installed base of proprietary video conferencing and collaboration tools resists seamless interoperability with third-party event management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Event Management Service Market |
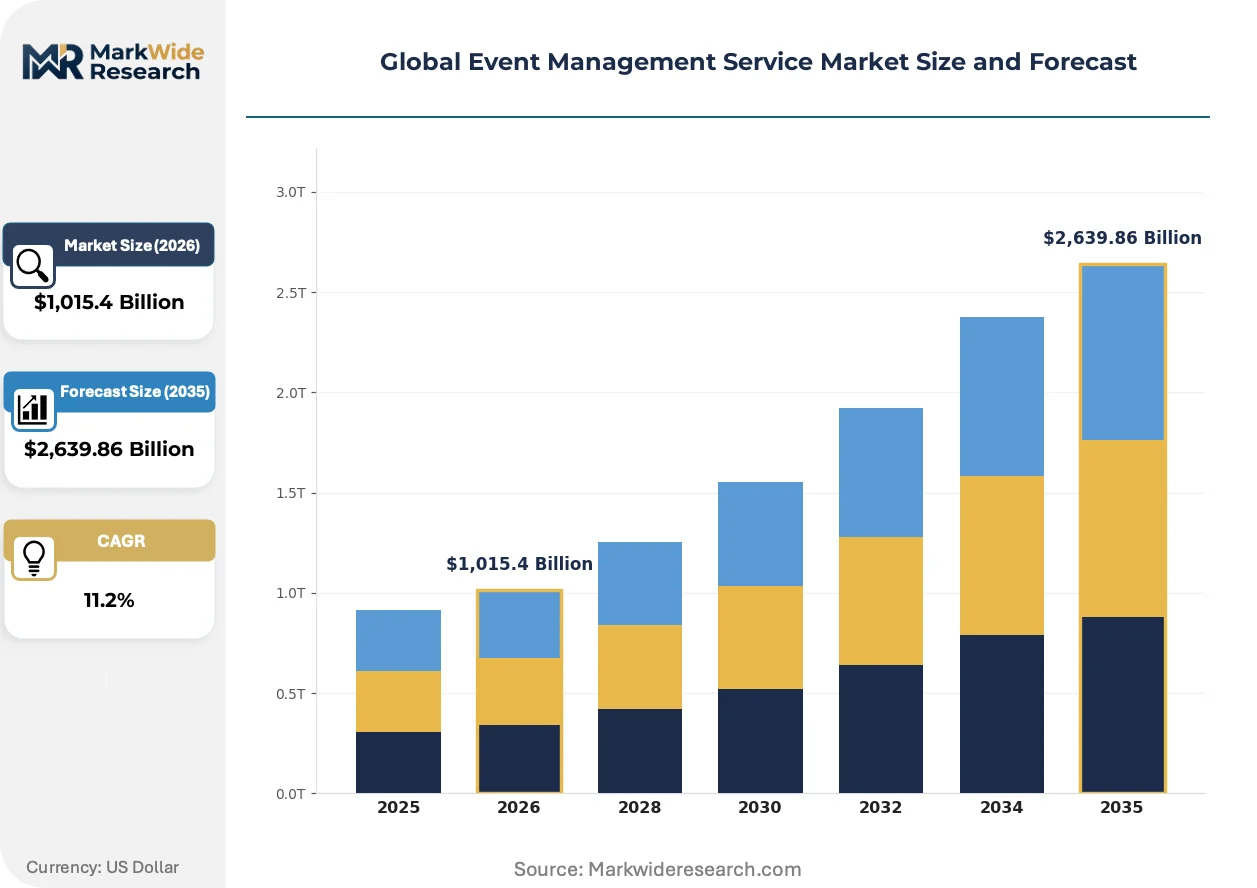
| Market Size in 2026 | $1,015.4 Billion |
| Market Size in 2035 | $2,639.86 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corporate Event Planning, Social Event Coordination, Virtual Event Management, Trade Show Organizing, Entertainment Event Production Application: Product Launches, Conferences, Exhibitions, Team Building Activities, Award Ceremonies Client Type: Multinational Corporations, Small & Medium Enterprises, Nonprofit Organizations, Educational Institutions, Government Agencies Delivery Model: Onsite Management, Remote Coordination, Hybrid Event Solutions, Automated Platforms, Managed Services |
| Companies Covered | Freeman, Informa Markets, Reed Exhibitions, Live Nation Entertainment, BCD Meetings & Events, MCI Group, Clarion Events, ASM Global, George P. Johnson Experience Marketing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Event Management Service Market Shifts & Advancements
Real-time spatial computing and AI-powered audience analytics are compressing the planning-to-execution cycle for complex multi-venue programs. These technologies are redistributing value from traditional logistics coordination toward data-driven experience design and predictive crowd management.
Immersive extended reality staging is supplanting conventional LED wall and projection-mapped environments in high-budget corporate activations. Fortune 500 marketing departments are mandating XR-capable production partners for product launches and annual meetings. This capability threshold is consolidating procurement around full-service operators with in-house virtual production studios, marginalizing equipment-rental-dependent regional coordinators.
The EU AI Act's transparency requirements for automated decision-making systems are reshaping vendor qualification criteria for European enterprise contracts. Event matchmaking platforms must now document algorithmic logic and maintain human oversight protocols. German and French procurement departments are inserting AI governance clauses into multi-year managed service agreements, disqualifying black-box recommendation engines from consideration.
Enterprise buyers are consolidating dispersed meetings and events budgets under single-source contracts with outcome-based performance metrics. Marketing procurement teams at technology and pharmaceutical companies are replacing transactional venue sourcing with multi-year partnerships tying fees to attendee engagement scores and lead generation targets. This shift is most advanced in the United States, where procurement organizations have matured their events category management capabilities.
Global Event Management Service Market Segmentation
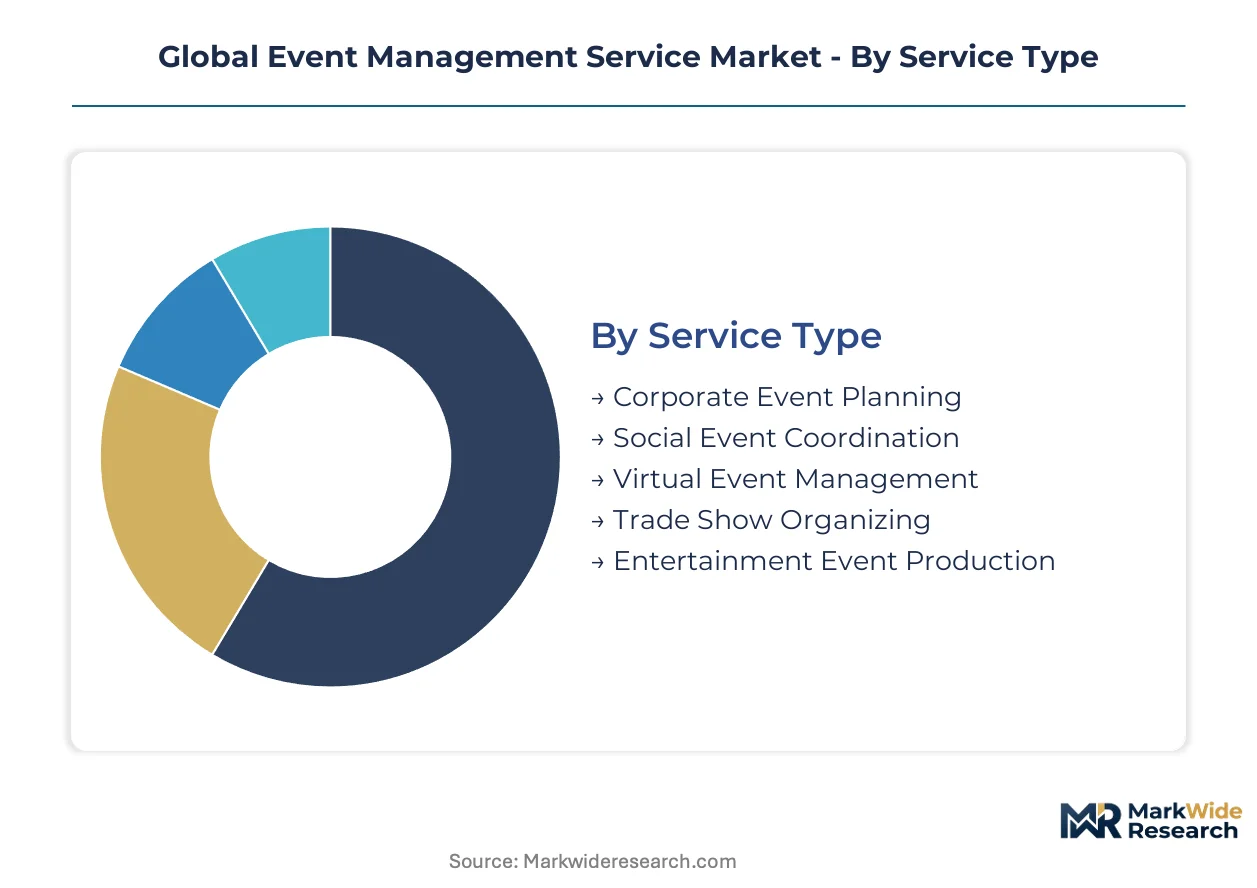
Event management services fragment across four intersecting dimensions that determine procurement patterns and margin structures. Service type and delivery model combinations create distinct competitive arenas, while client type and application pairings dictate pricing power and contract duration.
Service Type:
Geographic demand varies sharply by service type, with Corporate Event Planning and Trade Show Organizing concentrated in export-led multinational contracts while Social Event Coordination remains predominantly domestic.
- Corporate Event Planning:Encompasses strategic program design, stakeholder alignment workshops, and executive retreat logistics for enterprise clients. Demand concentrates in the United States, Germany, and the United Arab Emirates where procurement teams consolidate dispersed meetings budgets under single-source contracts with outcome-based performance metrics. GDPR and EU AI Act compliance costs are redirecting spend toward providers with certified data governance frameworks.
- Hybrid Event Solutions:Represents the fastest-expanding delivery model as clients mandate simultaneous physical and digital audience pathways without duplicate production costs. Corporate marketing departments at technology and pharmaceutical companies now require broadcast-quality virtual production capabilities as a baseline qualification, compressing margins for equipment-rental-dependent regional operators.
- Social Event Coordination:Covers weddings, milestone celebrations, and private gatherings requiring aesthetic design and vendor curation. Domestic demand dominates with limited cross-border procurement.
- Virtual Event Management:Has matured into a margin-compressed baseline offering rather than a premium tier, with standardized platform features and reduced differentiation.
- Trade Show Organizing:Involves exhibitor sales, floor plan optimization, and sponsor activation management for industry-specific gatherings. Live Nation Entertainment and ASM Global's venue ownership concentration constrains independent producers' negotiating leverage in major metropolitan markets.
- Entertainment Event Production:Encompasses concert logistics, talent contracting, and crowd safety compliance for live audience experiences. OSHA crowd safety standards for temporary structures elevate compliance costs and disqualify undercapitalized regional operators from large-scale contracts.
Corporate Event Planning holds the largest share; momentum sits with Hybrid Event Solutions.
Application:
Cost tier stratification separates high-budget Product Launches and Award Ceremonies from volume-driven Conferences and Team Building Activities.
- Product Launches:Demands immersive extended reality staging and real-time spatial computing for Fortune 500 marketing departments. German and French procurement teams are inserting AI governance clauses into multi-year managed service agreements, disqualifying black-box recommendation engines from consideration.
- Award Ceremonies:Requires broadcast-quality production values, celebrity talent coordination, and sponsor integration at scale. Dubai and Abu Dhabi government-backed destination marketing organizations are underwriting mega-event infrastructure, drawing multinational corporate activations.
- Conferences:Standardized agenda management, speaker logistics, and attendee registration systems with compressed differentiation.
- Exhibitions:Floor space monetization, lead retrieval systems, and exhibitor services with venue-dependent economics.
- Team Building Activities:Experience design and group facilitation with localized delivery and limited technology integration.
Product Launches command premium pricing; Award Ceremonies are climbing the fastest as experiential marketing budgets expand.
Client Type:
Volume concentration sits with Multinational Corporations, while margin expansion opportunities concentrate in Small & Medium Enterprises seeking outsourced expertise.
- Multinational Corporations:Require embedded travel logistics, multinational account structures, and centralized procurement with multi-year partnerships. CSRD-mandated emissions disclosure for large European enterprises is creating demand for event-specific carbon footprint measurement and offset bundling as a differentiated service layer.
- Government Agencies:Mandate strict compliance with FDA food safety guidelines at public gatherings and OSHA crowd safety standards for temporary structures. Saudi Arabia's NEOM, Qiddiya, and Red Sea Project developments are commissioning permanent event infrastructure, creating first-mover advantage for operators establishing local production capabilities.
- Small & Medium Enterprises:Transactional procurement with price sensitivity and limited contract duration.
- Nonprofit Organizations:Budget-constrained programming with donor accountability requirements and volunteer coordination complexity.
- Educational Institutions:Academic calendar constraints and procurement bureaucracy with extended sales cycles.
Multinational Corporations dominate contract value; Small & Medium Enterprises represent the steepest expansion trajectory as managed service penetration deepens.
Delivery Model:
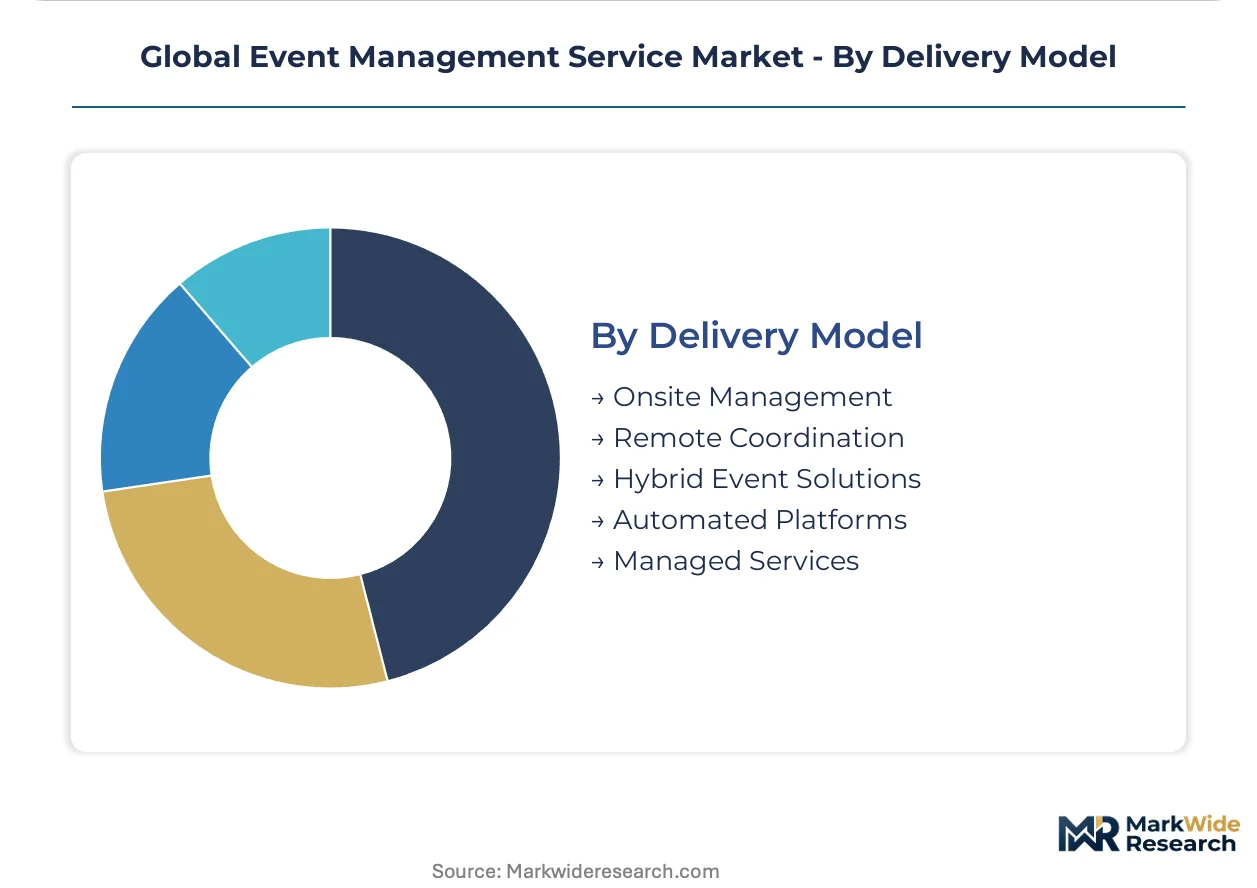
Supply concentration favors Managed Services and Automated Platforms with certified compliance infrastructure, while Onsite Management remains fragmented across regional operators.
- Managed Services:Encompasses end-to-end program ownership with outcome-based fees tied to attendee engagement scores and lead generation targets. ISO 27001 and SOC 2 Type II audits for event registration and payment platforms require 12-18 month implementation cycles, creating barriers for new technology vendors.
- Hybrid Event Solutions:Combines physical venue logistics with virtual audience platforms and real-time analytics. The EU AI Act's transparency requirements for automated attendee matchmaking are reshaping vendor qualification criteria, extending platform development timelines.
- Onsite Management:Day-of coordination and vendor supervision with labor-intensive economics and limited scalability.
- Remote Coordination:Distributed team management with reduced travel costs and timezone complexity.
- Automated Platforms:Self-service registration, scheduling, and analytics with AI-generated content workflows enabling personalized attendee experiences at scale.
Managed Services capture the largest share; Hybrid Event Solutions are gaining share fastest as corporate procurement matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States and Germany exceeds that in emerging Middle Eastern markets by substantial margins, reflecting procurement maturity and compliance infrastructure depth. This asymmetry redirects investment toward certified operators capable of capturing premium contracts.
United States
Corporate procurement teams consolidate dispersed meetings budgets under single-source contracts with outcome-based performance metrics. OSHA crowd safety standards for temporary structures elevate compliance costs and disqualify undercapitalized regional operators from large-scale contracts. New York and Los Angeles anchor broadcast-quality virtual production capabilities, concentrating specialized technical talent.
Germany
CSRD-mandated emissions disclosure for large enterprises creates demand for event-specific carbon footprint measurement and offset bundling. GDPR data governance requirements redirect procurement toward managed service providers with certified compliance frameworks. Frankfurt and Munich host multinational account headquarters for embedded travel logistics and centralized procurement.
United Arab Emirates
Dubai and Abu Dhabi government-backed destination marketing organizations underwrite mega-event infrastructure, drawing multinational corporate activations and incentive travel programs. MOHAP regulations govern public health at large gatherings, shaping vendor qualification criteria. The emirates concentrate premium arena and convention center inventory through state-linked venue operators.
Saudi Arabia
NEOM, Qiddiya, and Red Sea Project developments commission permanent event infrastructure, creating first-mover advantage for operators establishing local production capabilities. SFDA guidelines intersect with event food safety protocols at public gatherings. Riyadh anchors government agency procurement for large-scale national programs.
United Kingdom
Enterprise buyers replace transactional venue sourcing with multi-year partnerships tying fees to attendee engagement scores and lead generation targets. GDPR and emerging AI governance requirements reshape vendor qualification for European enterprise contracts. London concentrates financial services and pharmaceutical corporate event spending.
Global Event Management Service Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the event management service market, creating tiered competitive dynamics. Full-service operators with integrated production networks capture premium corporate activations, while equipment-rental-dependent regional coordinators compete on price for standardized programs. Two strategic archetypes dominate: multinational managed service providers with certified compliance infrastructure, and venue-owning entertainment conglomerates controlling premium inventory. Competitive moves concentrate on M&A for geographic expansion and strategic partnerships for technology licensing.
Among the full-service operator tier, Freeman and BCD Meetings & Events exemplify archetypes with embedded travel logistics and multinational account structures. Live Nation Entertainment occupies a position representing venue ownership concentration, controlling premium arena and convention center inventory in major metropolitan markets. These three companies anchor the competitive structure, with Freeman representing integrated production network capabilities, BCD Meetings & Events exemplifying procurement consolidation capture, and Live Nation Entertainment anchoring live entertainment portfolio control through venue-talent relationships.
| Leading Market Players |
|---|
| Freeman |
| Informa Markets |
| Reed Exhibitions |
| Live Nation Entertainment |
| BCD Meetings & Events |
| MCI Group |
| Clarion Events |
| ASM Global |
| George P. Johnson Experience Marketing |
| Others |
Supply & Pricing Matrix
Broadcast-quality virtual production replacing conventional AV equipment is redrawing supply geography toward Los Angeles, London, and Singapore while compressing margins for equipment-rental-dependent regional operators unable to absorb fixed-cost investments. This substitution simultaneously elevates pricing power for certified full-service operators and eliminates price-competitive positioning for undifferentiated coordinators.
Pricing Analysis
The customization-premium spread separates outcome-based managed service contracts from transactional per-event sourcing, with three-tier pricing structure across premium, standard, and economy levels tied to certification grade and geographic delivery complexity. Price differentiation hinges on GDPR/EU AI Act compliance infrastructure and broadcast-quality virtual production capabilities. Pricing pressure stems from margin compression in standardized virtual event platforms as features commoditize. Small and medium enterprises exhibit highest price sensitivity, while multinational corporations accept premium positioning for centralized procurement efficiency.
Supply Chain Analysis
The United States, Germany, and the United Arab Emirates anchor high-value corporate event delivery, with China and Vietnam supplying LED hardware and staging components at scale. Production draws from specialized technical talent pools, proprietary venue inventory controlled by entertainment conglomerates, and certified data governance platforms. Single-source vulnerability concentrates in broadcast-quality virtual production skill sets. Distribution runs through multinational account structures with embedded travel logistics and centralized procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in real-time spatial computing and AI-powered audience analytics is scarce relative to demand, creating asymmetric returns for operators who develop these capabilities before procurement departments fully specify them in vendor qualification criteria.
For Market Incumbents: Shield premium positioning by accelerating ISO 27001 and SOC 2 Type II certification completion ahead of EU AI Act enforcement timelines. Deepen backward integration into virtual production studios to reduce dependency on Los Angeles and London talent concentration. Control venue inventory through long-term operator agreements where ASM Global and Live Nation Entertainment concentration threatens negotiating leverage. For New Entrants and Emerging Players: Lead with carbon accounting integration and CSRD-compliant emissions measurement services targeting German and French enterprise procurement departments. Saudi Arabia's NEOM and Qiddiya developments represent the most penetrable geography for establishing local production capabilities before permanent infrastructure commissioning completes. Position as certified compliance specialists rather than generalist coordinators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional operators possessing venue relationships but lacking virtual production capabilities. Long-term viability favors platforms with automated decision-making transparency documentation and human oversight protocols already operational. Watch for EU AI Act audit failures disqualifying black-box recommendation engines as the inflection signal for accelerated consolidation toward certified providers.| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Production Studio Acquisition | Captures broadcast-quality capabilities that pharmaceutical and technology marketing departments now mandate as baseline qualification. |
| GDPR/EU AI Act Compliance Certification | Unlocks German and French enterprise procurement contracts inserting algorithmic transparency clauses into multi-year agreements. |
| Saudi Arabia Local Production Buildout | Establishes first-mover positioning before NEOM, Qiddiya, and Red Sea Project infrastructure commissions complete. |
| Carbon Accounting Service Integration | Addresses CSRD-mandated emissions disclosure requirements for large European enterprise events procurement. |
| Strategic Venue Partnership | Counterbalances Live Nation Entertainment and ASM Global inventory concentration constraining independent producer leverage. |
Research Methodology
The analysis maps corporate event planning, hybrid event solutions, virtual event management, and trade show organizing segments, each validated through event technology procurement officers, corporate marketing executives, venue operations directors, and managed service account directors. Primary interviews with these stakeholders combined with secondary validation against SEC filings, EU regulatory disclosure databases, destination marketing organization infrastructure reports, and corporate events industry association benchmarks. Bottom-up service provider revenue aggregation and top-down enterprise events spend allocation triangulate market sizing.
Consistency checks validated volume and value outputs against external procurement spend surveys and venue capacity utilization data across the analysis window. The analytical framework modeled delivery model, client type, service type, and application dimensions alongside regional regulatory cluster variations. CAGRs derived from segment-level growth rate reconciliation with macroeconomic indicators and technology adoption curves. Forecast inputs incorporated hybrid event infrastructure investment cycles and compliance cost pass-through assumptions.
The analysis sits within stated boundaries; outcomes outside sustained corporate travel recovery and regulatory enforcement intensity would require recalibration. Forecasts reflect documented assumptions regarding procurement consolidation velocity and virtual production talent supply expansion. Specific risks that could revise projections include accelerated EU AI Act implementation timelines and cybersecurity certification delays for new platform entrants. Recalibration cycles align with material shifts in regulatory enforcement patterns and corporate procurement policy updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Conferences
North America Wedding Services Market
Events and Conferences
India B2B Events Market
Events and Conferences
China Wedding Services Market
Events and Conferences
Exhibition, Convention & Meeting Market
Events and Conferences
Thailand MICE and Mega Event Market
Events and Conferences
Global Exhibition Organizing Market
Events and Conferences
Saudi Arabia Event Management Market
Events and Conferences
Mexico Event Services Market
Events and Conferences
France Event Services Market
Events and Conferences
Japan Wedding Services Market
Events and Conferences
Canada Wedding Services Market
Events and Conferences
Wedding Services Market
Events and Conferences
Asia-Pacific Wedding Services Market
Events and Conferences
Corporate Event Planner Market
Events and Conferences
GCC Event Management Market
Events and Conferences
Event Management Solutions Market