
 Asia-Pacific Amusement Parks Market | 2026-2036
Asia-Pacific Amusement Parks Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Amusement Parks Market Analysis
Steel-track roller coasters are pivoting toward lighter composite materials that cut maintenance cycles and foundation loads. Chimelong Group leverages its integrated resort model to anchor visitor dwell time across multiple properties. Fantawild Holdings sustains dominance in intellectual property-driven attractions through its animated character portfolio. Universal Studios Japan competes by controlling premium licensing partnerships with major film studios.
Asia-Pacific amusement parks constitute large-scale entertainment complexes combining mechanical rides, themed environments, live performance venues, and hospitality services, typically requiring minimum site areas of fifty hectares and daily throughput capacities exceeding twenty thousand visitors to achieve operational viability. Theme parks command the largest revenue pool among amusement types due to their capital-intensive immersive storytelling infrastructure, while trampoline parks represent the fastest-expanding segment as urban consumers seek compact, repeatable experiences. Within service types, annual passes generate recurring revenue streams that stabilize cash flow across seasonal demand cycles, whereas VIP packages capture the highest per-capita margin contribution.
China's SAMR enforces safety certification protocols for large amusement devices under GB standards, while Japan's METI oversees operational inspection regimes that mandate annual structural audits of steel coaster assemblies. Australia's TGA-equivalent state-level regulators impose noise and environmental impact thresholds that constrain expansion near residential zones. Stakeholders must monitor evolving carbon accounting requirements across multiple national frameworks as energy disclosure rules tighten for high-consumption entertainment infrastructure.
Market Dynamics
China's dual carbon goals are compressing capital planning cycles as operators retrofit legacy ride systems with energy-efficient drive technologies and on-site solar generation to preempt tightening MEE disclosure mandates.
Growth Catalysts
- Composite track materials:Lighter carbon-fiber reinforced polymer rails reduce foundation loads and extend inspection intervals for steel coaster assemblies.
- Annual pass penetration:Recurring revenue models stabilize cash flow across seasonal demand troughs in Japan's Greater Tokyo metropolitan cluster.
- GB standards compliance:China's SAMR certification protocols for large amusement devices create barrier-to-entry protection for certified domestic operators.
Market Restraints
- Steel price volatility:Raw material input swings compress margin predictability for track fabrication contracts.
- Site scarcity in tier-one cities:Land availability constraints in Shanghai, Beijing, and Shenzhen limit greenfield expansion.
- Residential proximity restrictions:Australia's state-level noise and environmental impact thresholds block development near population centers.
Strategic Opportunities
- Southeast Asia underpenetration:Vietnam, Indonesia, and the Philippines lack integrated resort-scale properties relative to per-capita income growth.
- Renewable integration incentives:China's dual carbon goals subsidize on-site photovoltaic and kinetic energy recovery systems for ride motors.
- Character IP licensing:Animated portfolio holders can verticalize into captive merchandise and media distribution channels.
Industry Challenges
- Structural engineer scarcity:Specialized coaster dynamics expertise concentrates in Japan and China, creating recruitment bottlenecks for new market entrants.
- Multi-jurisdiction certification lag:Operators face sequential GB standards, METI inspection, and Australian state-level approvals for cross-border equipment deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Amusement Parks Market |
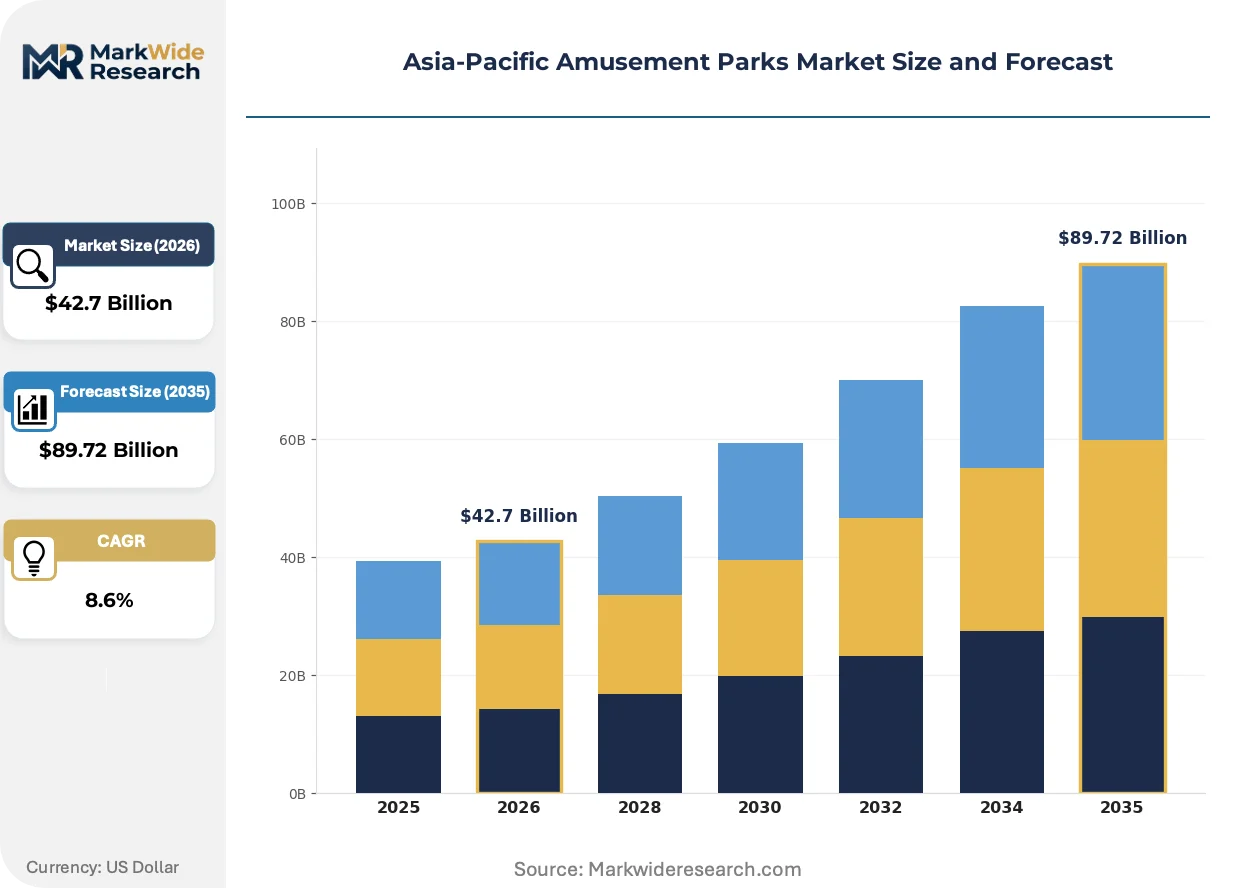
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $89.72 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Amusement Type: Theme Parks, Water Parks, Amusement Arcades, Trampoline Parks Customer Segment: Families, School Groups, Tourists, Corporate Events Service Type: Admission Tickets, Annual Passes, VIP Packages, Food & Beverage Attraction Type: Roller Coasters, Ferris Wheels, Games, Live Shows |
| Companies Covered | Shanghai Disneyland, Everland, Chimelong Group, Fantawild Holdings, Nagashima Spa Land, OCT Group, Universal Studios Japan, Haichang Ocean Park Holdings, Tokyo Disneyland, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Amusement Parks Market Emerging Trajectories
Kinetic energy recovery and predictive maintenance systems are compressing operational expenditure profiles across high-throughput properties. Operators now prioritize technologies that reduce per-ride energy intensity while extending mechanical asset life.
Magnetic braking and linear motor launch systems are unifying acceleration control with regenerative power capture. Tier-one Chinese operators deploy these configurations at scale to meet dual carbon disclosure thresholds. The technology is unifying ride performance specifications with energy accounting requirements in capital procurement decisions.
METI's annual structural audit mandates for steel coaster assemblies are tightening documentation standards for weld inspection and fatigue testing. Japanese operators now embed sensor networks to generate continuous compliance records. Premium properties in Osaka and Nagoya are responding by consolidating maintenance vendor relationships to ensure traceability.
Visitor purchasing is fragmenting across mobile-enabled micro-transaction platforms that displace traditional gate-plus-concession bundling. Younger demographics in South Korea and urban China prefer per-attraction payment and dynamic pricing tiers. This pattern is most visible in compact urban entertainment zones where repeat visitation frequency exceeds destination resort models.
Asia-Pacific Amusement Parks Market Segmentation
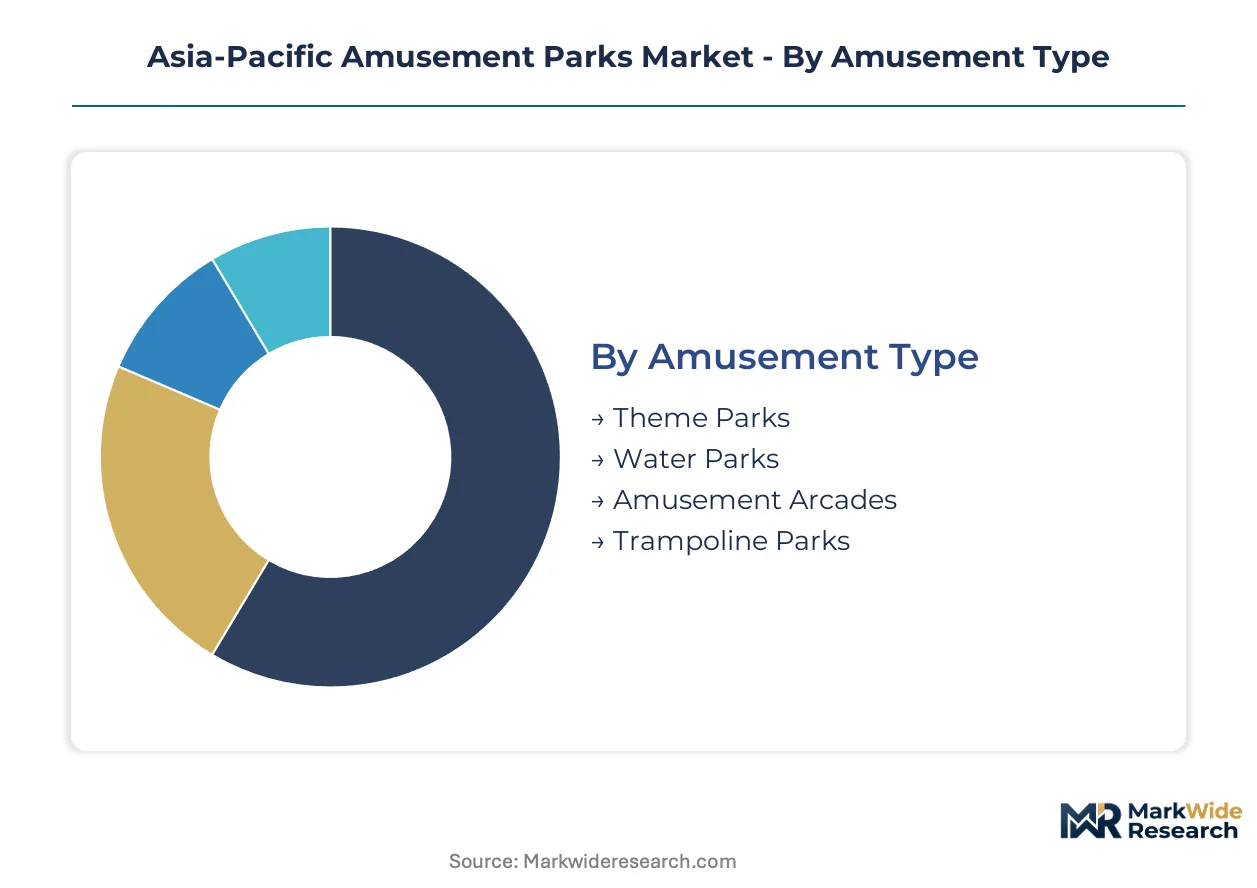
Asia-Pacific amusement parks operate across four distinct segmentation dimensions that shape capital deployment, operational complexity, and revenue architecture. Each category reflects divergent site requirements, regulatory exposure, and customer lifetime value profiles that determine competitive positioning.
Amusement Type:
Capital intensity varies dramatically across property formats, with immersive infrastructure demanding the heaviest upfront investment.
- Theme Parks:Large-scale complexes integrating mechanical rides, themed environments, and hospitality services require minimum fifty-hectare footprints and daily throughput exceeding twenty thousand visitors. China's tier-one cities and Japan's Greater Tokyo metropolitan cluster concentrate demand for these capital-intensive properties.
- Water Parks:Seasonal operations with lower per-ride mechanical complexity but significant water treatment and filtration infrastructure. Australia's state-level environmental impact thresholds constrain expansion near residential zones for this segment.
- Amusement Arcades:Compact urban formats with rapid equipment refresh cycles and minimal land requirements.
- Trampoline Parks:Repeatable micro-experiences targeting urban consumers seeking compact entertainment; expansion is steepest in this segment across Southeast Asian metropolitan zones.
Most installed capacity flows through Theme Parks. Expansion is steepest in Trampoline Parks.
Customer Segment:
Visitor composition directly determines pricing power, dwell time, and ancillary spend capture across operating calendars.
- Families:Core demand driver with multi-generational visitation patterns and highest per-capita merchandise attachment rates. Chimelong Group and Fantawild Holdings optimize property layouts for family unit circulation across China's tier-one cities.
- Tourists:Destination visitors generating premium accommodation and dining spend; concentrated in integrated resort properties with on-site lodging.
- School Groups:Structured educational programming with weekday demand smoothing and volume-based contracting.
- Corporate Events:Private hire and team-building formats with off-peak calendar utilization and customized service tiers.
Families account for the dominant visitor share. Tourists deliver the highest per-visit revenue yield.
Service Type:
Revenue model selection shapes cash flow stability and margin architecture across seasonal demand cycles.
- Annual Passes:Recurring revenue instruments that stabilize cash flow across Japan's seasonal demand troughs and China's holiday concentration. METI inspection mandates and SAMR GB standards compliance create retention value for certified operators.
- VIP Packages:Premium tiered experiences capturing the highest per-capita margin contribution through priority access and dedicated concierge services.
- Admission Tickets:Single-entry gate revenue with peak-day yield management and dynamic pricing sensitivity.
- Food & Beverage:Captive catering with location-based pricing power and throughput-constrained capacity planning.
Annual Passes anchor recurring revenue stability. VIP Packages scale fastest in premium Japanese and Chinese metropolitan properties.
Attraction Type:
Mechanical asset selection determines energy intensity, maintenance liability, and regulatory inspection exposure.
- Roller Coasters:Steel-track assemblies with carbon-fiber reinforced polymer rails reducing foundation loads and extending inspection intervals. SAMR GB standards and METI annual structural audit mandates govern certification and operational compliance across China and Japan.
- Live Shows:Performance-based entertainment with lower capital depreciation but higher labor intensity and intellectual property licensing requirements.
- Ferris Wheels:Observation infrastructure with extended asset life and lower per-ride energy consumption.
- Games:Skill-based and redemption formats with rapid technology refresh cycles and minimal site preparation.
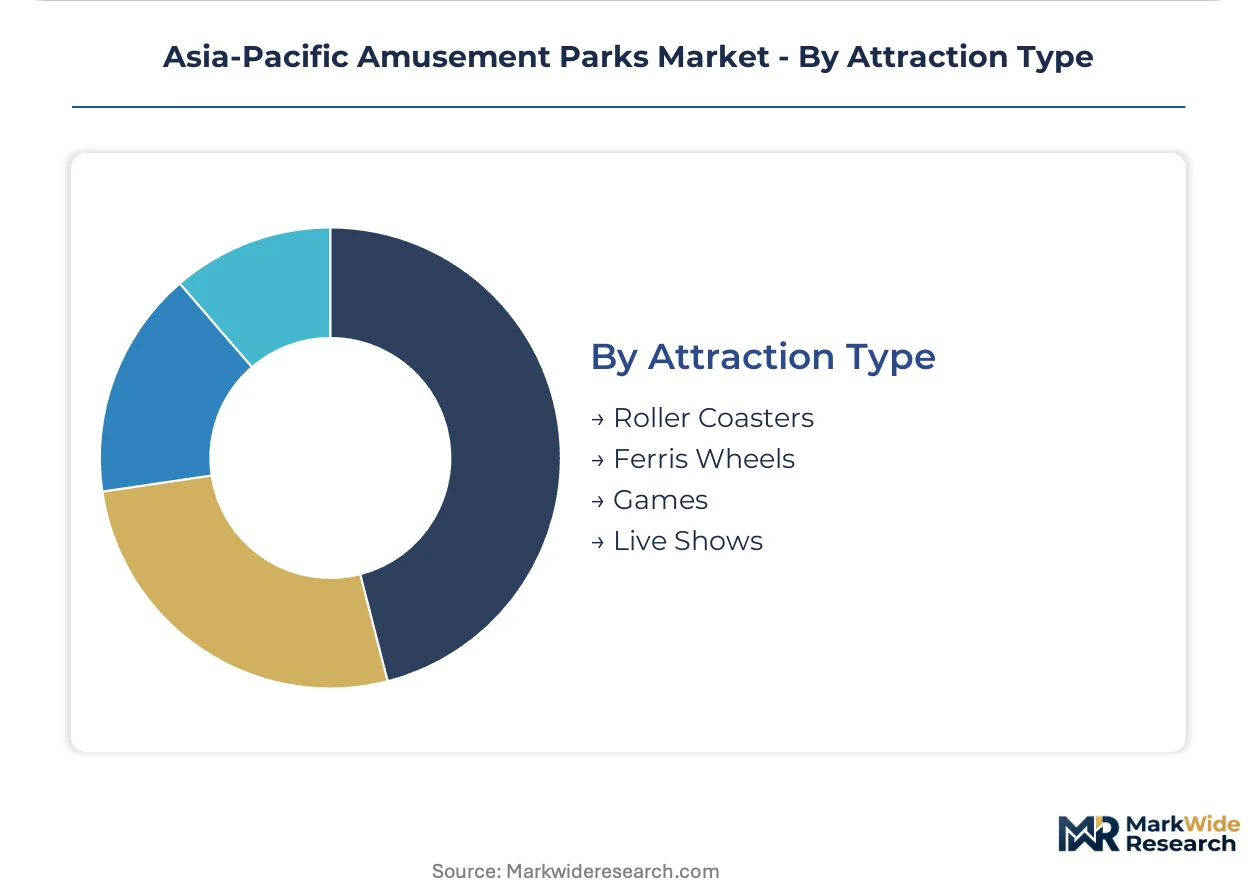
Roller Coasters represent the dominant capital deployment category. Live Shows are gaining share fastest in properties pursuing IP differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Tokyo metropolitan cluster anchors regional demand through integrated resort-scale properties with multi-day dwell time capture. China's tier-one cities concentrate capital deployment for immersive themed entertainment. Southeast Asian markets present expansion vectors as per-capita income growth outpaces installed capacity.
China
Shanghai and Beijing drive family entertainment spending through destination resort complexes with on-site hospitality. SAMR enforces GB standards certification for large amusement devices, creating compliance barriers for uncertified equipment imports. The Pearl River Delta hosts Chimelong Group's integrated properties where renewable energy retrofits align with MEE disclosure mandates.
Japan
Osaka and Nagoya metropolitan zones sustain premium per-capita spending through annual pass retention models. METI mandates annual structural audits of steel coaster assemblies, tightening documentation for weld inspection and fatigue testing. Universal Studios Japan leverages licensed film partnerships to differentiate within the Kansai entertainment corridor.
South Korea
Seoul Capital Area consumers fragment purchasing across mobile-enabled micro-transaction platforms with per-attraction payment preferences. The national safety regulator imposes operational inspection protocols for mechanical ride systems. Everland anchors the Yongin cluster with seasonal programming optimized for repeat visitation frequency.
Australia
Sydney and Melbourne metropolitan markets face site scarcity from state-level noise and environmental impact thresholds near residential zones. TGA-equivalent state regulators constrain water park expansion through water treatment discharge standards. Gold Coast properties concentrate tourist destination demand with extended-stay accommodation bundling.
Vietnam
Ho Chi Minh City and Hanoi metropolitan areas exhibit underpenetration relative to income growth trajectories. The Ministry of Construction oversees safety standards for large-scale entertainment infrastructure with evolving certification frameworks. Da Nang emerges as a coastal resort development corridor with integrated hospitality-entertainment proposals.
Asia-Pacific Amusement Parks Market Vendor Landscape
Strategic partnerships dominate the current landscape as operators secure licensed intellectual property and technology transfer agreements. The market structures around three tiers: integrated resort conglomerates with hospitality verticals, IP-driven animation studios with captive character portfolios, and single-property destination operators. Two archetypes prevail—scale-driven integrated resort developers and specialization-focused regional entertainment complexes. Competitive moves concentrate on portfolio diversification into adjacent hospitality services and geographic expansion through management contracts.
Within the integrated resort tier, Chimelong Group and OCT Group exemplify conglomerate structures with multi-property networks across Chinese metropolitan clusters. Fantawild Holdings occupies a distinct position as an IP-anchored operator leveraging animated character portfolios for vertical merchandise and media distribution. Universal Studios Japan represents the premium licensing model through major film studio partnerships that differentiate destination properties in saturated metropolitan markets.
| Leading Market Players |
|---|
| Shanghai Disneyland |
| Everland |
| Chimelong Group |
| Fantawild Holdings |
| Nagashima Spa Land |
| OCT Group |
| Universal Studios Japan |
| Haichang Ocean Park Holdings |
| Tokyo Disneyland |
| Others |
Supply Flow & Price Mechanics
Carbon-fiber reinforced polymer rail costs cascade through three-tier pricing structures across premium, standard, and economy levels as Chinese fabricators consolidate supply positions for steel coaster assemblies destined for tier-one metropolitan clusters in China and Japan.
Pricing Analysis
Input-cost pass-through from steel price volatility compresses margin predictability for track fabrication contracts, with carbon-fiber composite premiums widening against conventional steel assemblies. Price differentiation hinges on SAMR GB standards certification tier and annual throughput volume commitments, with certified operators commanding sustained premiums. Pricing pressure stems from residential proximity restrictions in Australian state-level markets that constrain greenfield expansion near population centers. Corporate event buyers exhibit highest price sensitivity due to off-peak calendar utilization negotiations, while tourist segments anchored in integrated resort properties demonstrate lowest sensitivity through accommodation bundling capture.
Supply Chain Analysis
Reverse-logistics flows for steel coaster refurbishment concentrate maintenance vendor relationships in Osaka and Nagoya metropolitan zones where METI audit mandates require continuous weld inspection documentation. Manufacturing gravity centers on China, Japan, and South Korea for precision mechanical drive systems and magnetic braking assemblies. Raw material dependencies span high-grade structural steel, rare-earth magnetic components, and carbon-fiber reinforced polymers. Single-source vulnerability concentrates in specialized structural engineering expertise for coaster dynamics simulation. Distribution runs through direct equipment procurement contracts between operators and certified fabrication facilities, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific amusement parks function as a regulatory compounder where China's dual carbon goals and METI structural audit mandates continuously elevate compliance investment thresholds that certified operators convert into pricing power.
For Market Incumbents: Extend annual pass retention models across Japan's Greater Tokyo metropolitan cluster to stabilize cash flow through seasonal demand troughs while retrofitting legacy ride systems with kinetic energy recovery technologies to preempt MEE disclosure tightening. Threat substitution emerges from mobile-enabled micro-transaction platforms fragmenting visitor purchasing in South Korea's Seoul Capital Area. Vertical integration into captive merchandise channels anchored by animated character portfolios reinforces margin architecture against per-attraction payment erosion. For New Entrants and Emerging Players: SAMR GB standards certification in China opens a window for equipment import partnerships that bypass sequential approval bottlenecks facing cross-border deployment. White-space targets concentrate in Vietnam's Ho Chi Minh City and Hanoi metropolitan areas where income growth outpaces installed capacity, and in trampoline park formats across Southeast Asian urban zones seeking compact repeatable experiences. Go-to-market positioning should emphasize renewable integration incentives for on-site photovoltaic and kinetic energy recovery systems that align with dual carbon subsidy frameworks. For Investors and Strategic Acquirers: Consolidation pressure builds where structural engineer scarcity for coaster dynamics expertise concentrates recruitment bottlenecks in Japan and China, favoring acquisition of certified maintenance vendors with traceability documentation systems. Long-term viability over the next decade rests on IP-anchored operators with verticalized merchandise and media distribution channels. Acquisition target archetype: integrated resort conglomerates with multi-property networks and renewable energy retrofit completion. Signal to monitor: sequential multi-jurisdiction certification lag duration for cross-border equipment deployment as barrier-to-entry indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Retrofit | On-site photovoltaic integration aligns with MEE disclosure mandates in China's Pearl River Delta. |
| Annual Pass Retention Model | Recurring revenue instruments stabilize cash flow across Japan's seasonal demand troughs. |
| Character IP Licensing Expansion | Vertical merchandise channels capture ancillary spend from family unit circulation patterns. |
| Sensor Network Compliance Embedding | Continuous weld inspection records satisfy METI structural audit documentation tightening. |
| Southeast Asian Management Contracts | Underpenetrated Vietnam and Indonesia markets offer expansion vectors relative to income growth. |
Methodological Framework
Coverage spans China, Japan, South Korea, Australia, and Vietnam, with primary inputs from each market combining interviews with ride system procurement directors, theme park operations executives, structural engineering consultants, and SAMR compliance officers with secondary validation against METI inspection protocols, MEE disclosure frameworks, Australian state-level environmental impact thresholds, and customs data for amusement device imports. Bottom-up property-level throughput estimates triangulate against top-down regional entertainment spending aggregates.
Rate-of-change decomposition separates volume expansion from yield improvement across the projection horizon, with segmentation dimensions spanning amusement type, customer segment, service type, and attraction type plus energy intensity tier as an industry-specific overlay. CAGRs derive from regression against per-capita income trajectories, regulatory compliance cost curves, and installed capacity saturation thresholds. Forecast inputs incorporate dual carbon subsidy allocation patterns and mobile payment penetration rates for micro-transaction platform adoption.
Revisions become necessary when steel price volatility exceeds historical bands, when residential proximity restrictions tighten in Australian state-level jurisdictions, or when METI extends structural audit mandates to additional ride categories. Practitioners should monitor sequential multi-jurisdiction certification lag duration and renewable integration incentive program modifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Festivals
K-Pop Events Market
Events and Festivals
Events and Exhibition Market
Events and Festivals
North America K-Pop Events Market
Events and Festivals
Global Escape Room Market
Events and Festivals
Asia-Pacific K-Pop Events Market
Events and Festivals
Events Market
Events and Festivals
Sports Events Tickets Market
Events and Festivals
Global Special Effects Fog and Smoke Machines Market
Events and Festivals
Corporate Luxury Events Market
Events and Festivals
Portable Photo Booth Market
Events and Festivals
Global Live Event Ticketing Market
Events and Festivals
Global Roller Coaster Market
Events and Festivals
Virtual Events Market
Events and Festivals
Europe K-Pop Events Market
Events and Festivals
Europe Event Pro-Av Services Market
Events and Festivals
Music Fountain Market