
 Europe Handicrafts Market | 2026-2036
Europe Handicrafts Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Handicrafts Market Intelligence
Premium heritage-grade certification is unwinding price ceilings across the European handicrafts sector. Gangamani Fashions leverages vertical integration from artisan cooperatives to finished textile exports. KALYS anchors its position through specialized embroidery ateliers in Eastern Europe. Ten Thousand Villages differentiates via fair-trade channel control across Nordic retail networks.
European handicrafts encompass artisan-produced goods using traditional techniques, natural fibers, and hand-processed raw materials with batch sizes typically under fifty units. These items serve decorative, functional, and collectible purposes across residential, hospitality, and gallery contexts. Textiles lead volume flows through established weaving and embroidery clusters, while pottery commands margin concentration in limited-edition studio ceramics. Woodwork occupies a mature position in Scandinavian markets, whereas metal crafts from Iberian smithies are gaining traction among architectural specification buyers.
REACH compliance and CE marking requirements govern chemical safety in dyed textiles and glazed ceramics sold across EU member states. The EU Green Deal's circular economy action plan is forcing reformulation of finishes and adhesives in traditional craft processes. France's national craft heritage registry and Italy's artisan quality seals create dual-track market access standards. Stakeholders must monitor evolving ECHA substance restrictions and national intangible cultural heritage designations that will determine which production methods retain commercial viability.
Market Dynamics
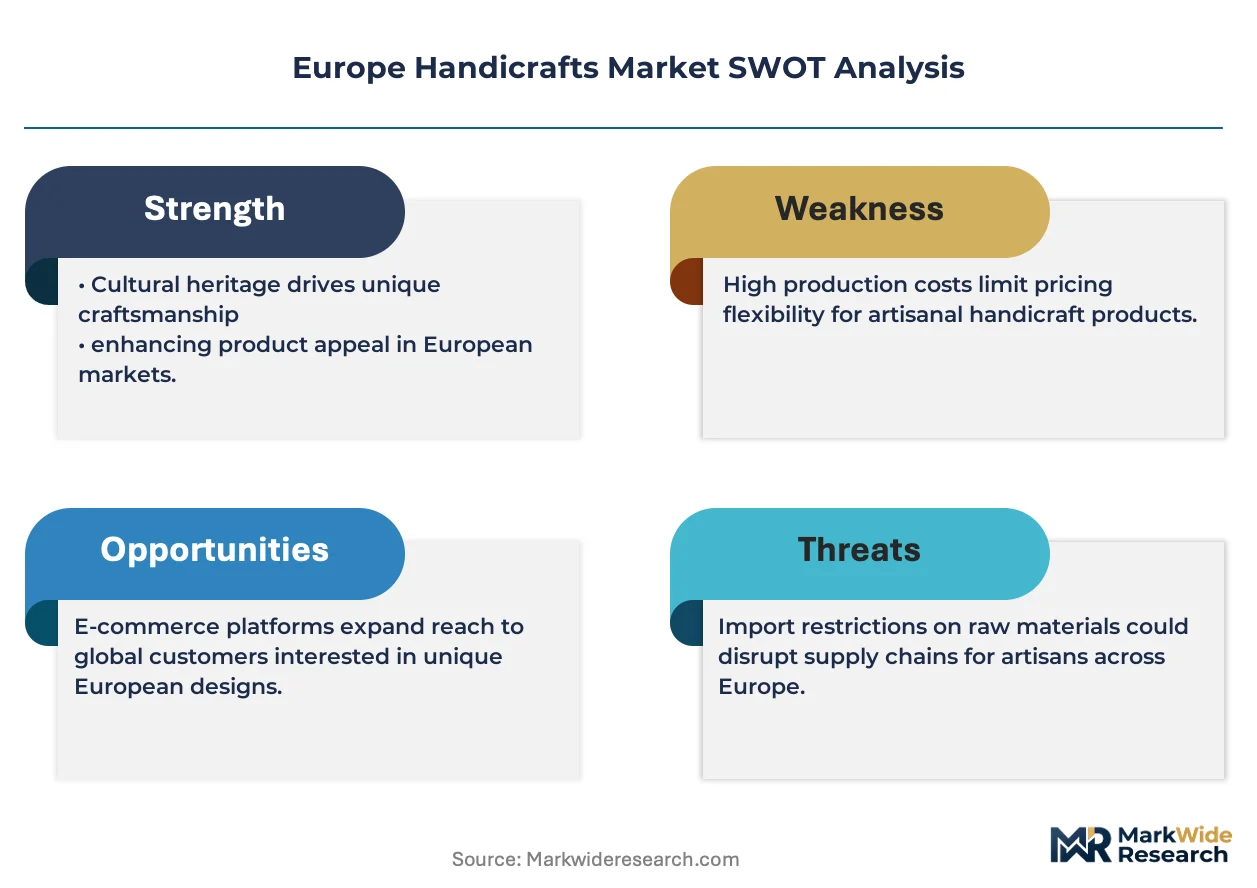
The EU Green Deal's circular economy mandates are compressing traditional craft supply chains, forcing dyers, weavers, and ceramicists to reformulate centuries-old material recipes or face market exclusion. Heritage protection statutes in France and Italy simultaneously create protected status tiers that fragment competitive access.
Growth Catalysts
- REACH chemical reformulation:ECHA substance restrictions on azo dyes and heavy-metal glazes are accelerating adoption of bio-based colorants among Tuscan textile clusters, opening premium export channels to German and Nordic retailers.
- Boutique hospitality procurement:Design-forward hotel operators in Portugal and Greece are contracting directly with regional pottery cooperatives for site-specific tableware and architectural ceramics, bypassing wholesale intermediaries.
- Artisan certification digitization:Blockchain-tracked provenance systems are enabling Umbrian weaving ateliers to command price premiums through verifiable hand-process documentation.
Market Restraints
- Raw material concentration:Organic linen fiber supply concentrates in Belgian and French flax belt, exposing weavers to weather-driven harvest volatility and single-source dependency.
- CE marking compliance costs:Small-batch ceramic studios face disproportionate testing burdens for lead leaching and thermal shock, compressing margins on sub-hundred-unit production runs.
- Substitute displacement:Machine-woven "hand-finished" textiles from Turkish industrial producers are capturing mid-market hospitality specification at 40-60% cost differentials.
Strategic Opportunities
- Eastern European embroidery revival:Romanian and Bulgarian needlework traditions remain undercommercialized, offering first-mover positioning for heritage-grade certification before EU cohesion funding saturates capacity.
- Architectural metalcraft specification:Iberian blacksmithing clusters in Catalonia and Basque Country are pivoting toward bespoke railing and fixture contracts for luxury residential developers.
- France's national craft heritage registry:Entrants to the Inventaire du Patrimoine Culturel Immatériel gain automatic eligibility for public procurement preference and export promotion subsidies.
Industry Challenges
- Master craftsperson succession gaps:Traditional bobbin lace and hand-thrown pottery techniques face attrition as aging practitioners retire without trained apprentices in Abruzzo and Galicia.
- Dual certification timelines:Producers seeking both EU organic textile labeling and national artisan quality seals must navigate sequential audit processes stretching 14-22 months.
- Supply chain reconfiguration friction:Shifting from petroleum-based sizing agents to bio-alternatives requires loom recalibration and retraining that idle small ateliers cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Handicrafts Market |
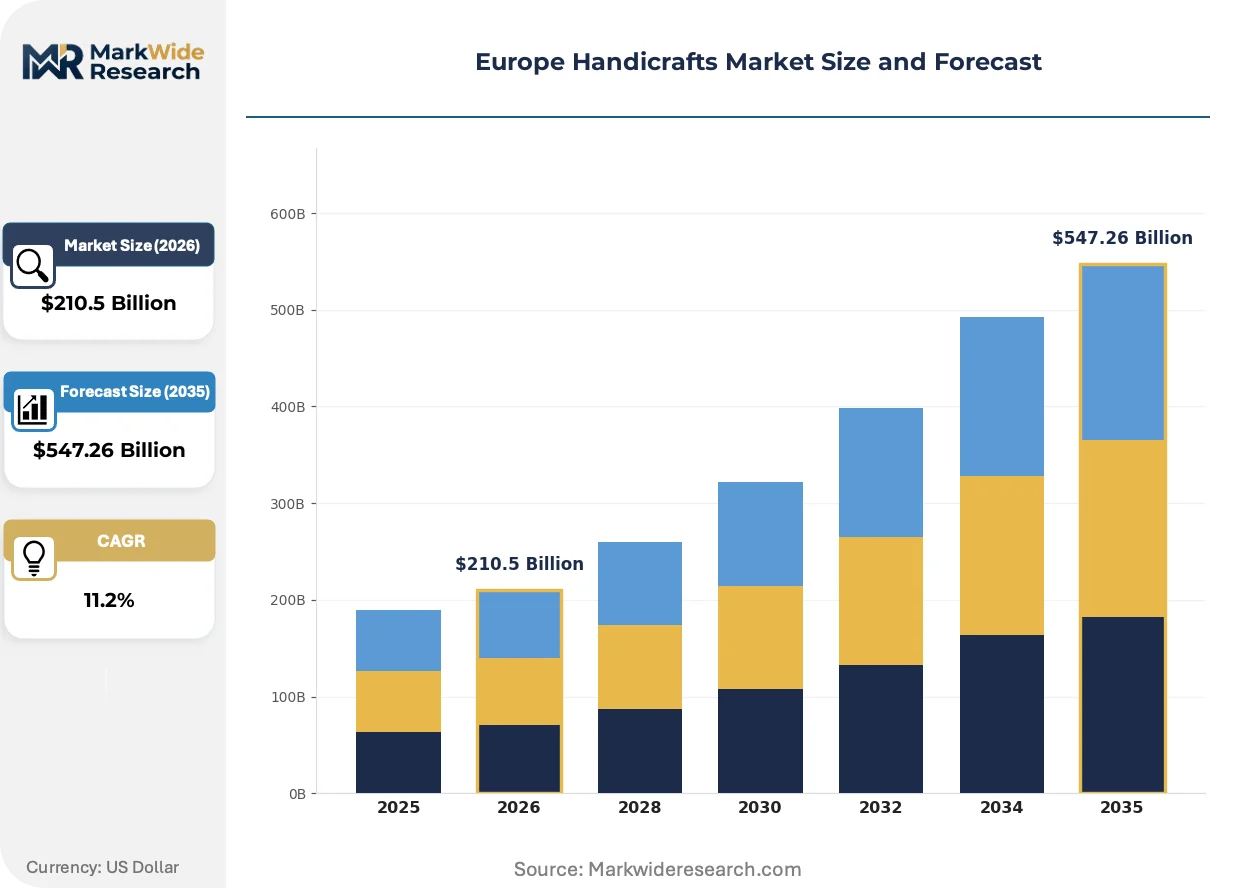
| Market Size in 2026 | $210.5 Billion |
| Market Size in 2035 | $547.26 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textiles, Pottery, Woodwork, Metal Crafts End User: Households, Artisans, Retailers, Collectors Distribution Channel: Online, Crafts Fairs, Retail Outlets, Direct Sales Creative Technique: Embroidery, Weaving, Carving, Pottery Making |
| Companies Covered | Gangamani Fashions, KALYS, Fakih Group of Companies, Ten Thousand Villages, It's Roni, Dezaro, AMOURRINA, Handverk og hönnun, Handicrafts Town, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Handicrafts Market Strategic Shifts & Innovations
Digital traceability infrastructure and bio-material science are converging to redefine authenticity verification and production chemistry across European craft sectors. These shifts are compressing traditional quality assurance timelines while opening new specification channels.
Blockchain-based provenance platforms are displacing paper-based artisan certificates that dominated gallery and collector sales for decades. High-end interior designers in Milan and Copenhagen are now requiring cryptographic ownership records for commissioned tapestries and studio ceramics. This displacement is compressing authentication costs while expanding resale royalty capture for living artists.
France's intensifying enforcement of REACH Annex XVII restrictions on nickel release in metal alloys is forcing Iberian smithies to reformulate traditional forge recipes. The industrial consequence is a split production base: export-oriented workshops invest in spectrometry testing, while domestic-market artisans face exclusion from cross-border e-commerce. Architectural specification buyers in Germany and Switzerland are now requiring batch-level compliance documentation that was previously voluntary.
Collector and hospitality buyer preferences are rotating toward repairable and modular craft objects that extend serviceable lifespan. Scandinavian contract furniture dealers are unbundling after-sales restoration services from initial purchase, creating recurring revenue relationships with regional woodwork ateliers. This pattern is most visible in Denmark and Sweden, where extended producer responsibility frameworks for furniture are tightening disposal cost accountability.
Europe Handicrafts Market Segmentation
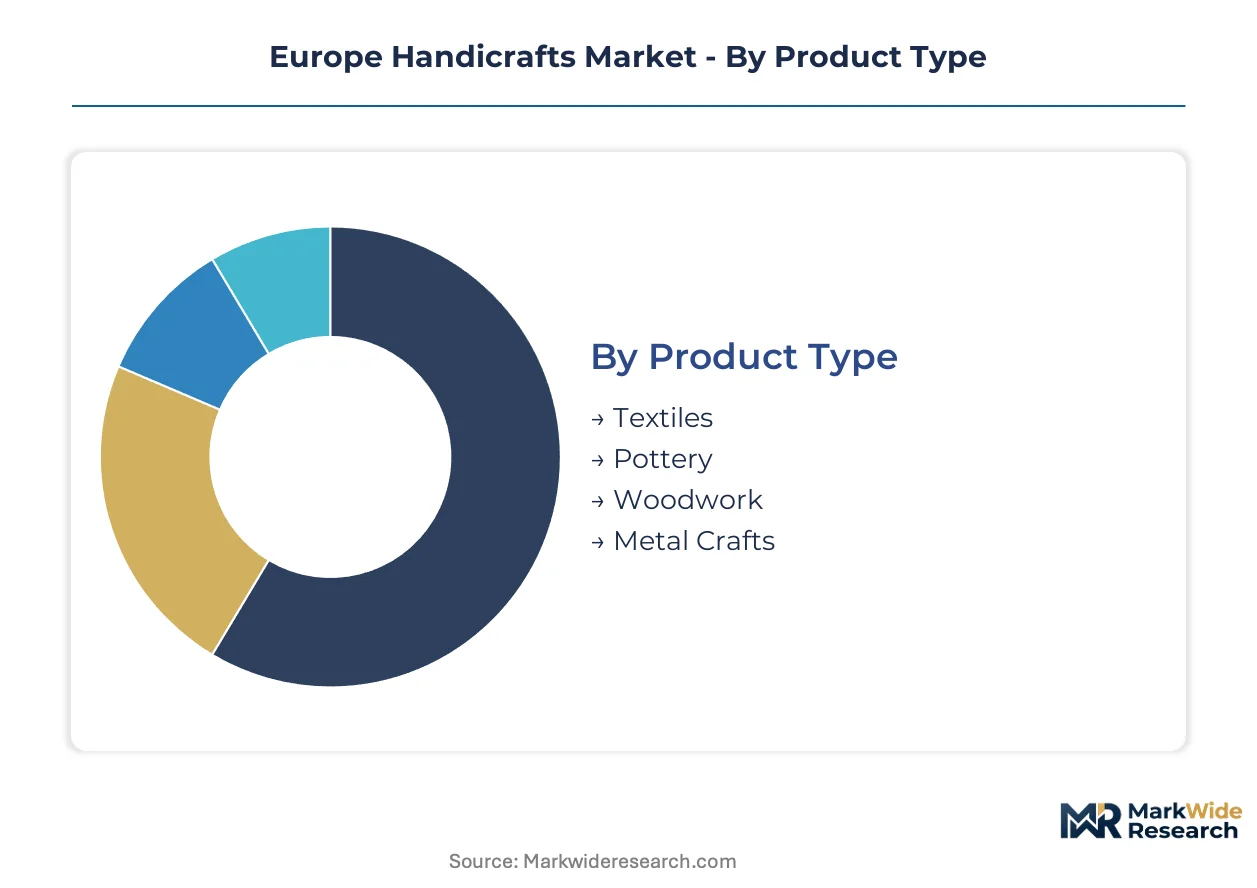
European handicrafts segment along four intersecting dimensions that determine pricing power, certification requirements, and channel access. Product type and creative technique govern material compliance burdens under REACH and national heritage statutes. End user and distribution channel configurations dictate whether producers capture retail margin or remain captive to wholesale intermediaries.
Product Type:
Domestic consumption concentrates in Italian and French clusters, while export-led growth flows through German and Nordic retail networks. Geographic spread varies sharply by material compliance intensity and shipping fragility.
- Textiles:Hand-woven linens, embroidered tapestries, and artisan scarves dominate volume flows through Tuscan and Umbrian cooperatives. REACH-compliant natural dyes command price premiums in German boutique retail, though Belgian flax supply volatility constrains batch consistency for premium hospitality contracts.
- Pottery:Studio ceramics and architectural tableware from Portuguese and Greek cooperatives bypass wholesale channels through direct hospitality procurement. CE marking for lead leaching and thermal shock testing compresses margins on sub-hundred-unit production runs, fragmenting the competitive base between export-capable workshops and domestic-only artisans.
- Woodwork:Scandinavian ateliers in Denmark and Sweden anchor mature demand through repairable furniture specifications under extended producer responsibility frameworks.
- Metal Crafts:Iberian smithies in Catalonia and Basque Country pivot toward architectural railing and fixture contracts for luxury residential developers, with France's nickel release enforcement under REACH Annex XVII forcing spectrometry investment for cross-border e-commerce eligibility.
Textiles command the established base. The steepest expansion runs through pottery as boutique hospitality procurement accelerates direct cooperative contracts.
End User:
Customer type determines certification depth and pricing tier, with institutional buyers imposing traceability requirements that individual consumers rarely demand.
- Households:Residential buyers in Italy and France drive heritage-grade demand through regional craft fairs and gallery channels, prioritizing aesthetic distinction over compliance documentation.
- Artisans:Peer-to-peer supply relationships within Eastern European embroidery revival clusters enable skill transmission and raw material pooling before commercial scaling.
- Retailers:Nordic fair-trade networks and German boutique chains require blockchain-tracked provenance systems that compress authentication costs while expanding resale royalty capture.
- Collectors:Milan and Copenhagen interior designers now mandate cryptographic ownership records for commissioned tapestries, displacing paper-based certificates that dominated gallery sales for decades.
Retailers anchor volume concentration. Collectors generate the steepest margin expansion through provenance-digitization premiums.
Distribution Channel:
Channel selection dictates margin capture and regulatory exposure, with digital platforms accelerating cross-border compliance complexity.
- Online:Cross-border e-commerce platforms expose Iberian metal crafters to France's intensifying REACH enforcement, requiring batch-level compliance documentation previously voluntary for domestic sales.
- Crafts Fairs:Regional events in Tuscany and Umbria sustain artisan-direct relationships that bypass wholesale markups while enabling tactile quality verification resistant to digital substitution.
- Retail Outlets:German and Nordic boutique networks consolidate procurement of REACH-compliant textiles, concentrating demand among vertically integrated cooperatives with captive dyeing capacity.
- Direct Sales:Portuguese and Greek pottery cooperatives contract directly with hospitality operators, eliminating intermediary margins while absorbing site-specific specification and logistics burdens.
Retail outlets maintain the established volume base. Direct sales channels are climbing the fastest as boutique hospitality procurement bypasses wholesale intermediaries.
Creative Technique:
Technique heritage governs certification eligibility and succession risk, with digitization opening new verification channels for hand-process documentation.
- Embroidery:Romanian and Bulgarian needlework traditions remain undercommercialized, offering first-mover positioning for heritage-grade certification before EU cohesion funding saturates regional capacity.
- Weaving:Tuscan and Umbrian ateliers deploy blockchain-tracked provenance systems to command price premiums through verifiable hand-process documentation, with bobbin lace techniques facing attrition as aging practitioners retire without trained apprentices.
- Carving:Scandinavian woodwork ateliers unbundle after-sales restoration services from initial purchase, creating recurring revenue relationships under tightening extended producer responsibility frameworks.
- Pottery Making:Hand-thrown techniques in Abruzzo and Galicia confront master craftsperson succession gaps, while CE marking compliance costs disproportionately burden small-batch studios.
Weaving anchors the established production base. Embroidery is gaining share fastest as Eastern European heritage revival attracts pre-saturation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian collectors demonstrate the lowest price elasticity, absorbing 40-60% premiums for blockchain-verified provenance, while German mass-market buyers compress margins through consolidated procurement of REACH-compliant textiles. French heritage registry entrants capture automatic public procurement preference, widening the bid-ask spread between certified and uncertified production.
Italy
Tuscan weaving cooperatives and Umbrian embroidery ateliers drive heritage-grade volume through direct gallery and hospitality channels. The national artisan quality seal (Marchio di Qualità Artigiana) creates dual-track market access that fragments competitive positioning between export-capable and domestic-only producers. Florence anchors premium textile clusters where blockchain-tracked provenance systems command price premiums from Milan interior designers.
France
Parisian gallery networks and Provence hospitality operators sustain demand for certified studio ceramics and metalwork. Entrants to the Inventaire du Patrimoine Culturel Immatériel gain automatic eligibility for public procurement preference and export promotion subsidies. Lyon and Limoges concentrate enamel and metalcraft production where REACH Annex XVII nickel release enforcement is forcing spectrometry investment for cross-border e-commerce eligibility.
Germany
Nordic and domestic boutique retail chains consolidate procurement of REACH-compliant natural-dye textiles, concentrating demand among vertically integrated cooperatives with captive dyeing capacity. ECHA substance restrictions on azo dyes accelerate adoption of bio-based colorants among supplier networks. Berlin and Hamburg anchor fair-trade distribution networks that require cryptographic ownership records for resale royalty capture.
Portugal
Alentejo and Algarve pottery cooperatives bypass wholesale intermediaries through direct contracts with boutique hospitality operators for site-specific tableware and architectural ceramics. CE marking compliance costs for lead leaching and thermal shock testing compress margins on sub-hundred-unit production runs. Lisbon galleries mediate collector access to limited-edition studio ceramics with repairable and modular design specifications.
Greece
Cycladic island cooperatives and Peloponnese weaving ateliers supply design-forward hotel operators with site-specific commissions that absorb logistics burdens in exchange for eliminated intermediary margins. EU Green Deal circular economy mandates force reformulation of traditional finishes and adhesives in ceramic and textile processes. Athens design studios broker direct relationships between regional artisans and German specification buyers seeking Mediterranean aesthetic differentiation.
Europe Handicrafts Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the European handicrafts sector. Digitally integrated cooperatives with blockchain provenance systems command premium positioning, while traditional ateliers without certification infrastructure compete on price in saturated domestic channels. Three archetypes dominate: vertically integrated heritage clusters with captive dyeing and weaving capacity, specialized embroidery ateliers leveraging Eastern European labor cost advantages, and fair-trade networks controlling Nordic retail distribution. Competitive moves concentrate on certification digitization and direct hospitality procurement contracts that eliminate wholesale markups.
Within the heritage-tier cluster, Gangamani Fashions and KALYS exemplify divergent geographic and structural positioning. Gangamani Fashions represents the vertically integrated cooperative model with artisan-to-export control spanning South Asian supply bases and European distribution. KALYS occupies a position among specialized Eastern European embroidery ateliers leveraging Romanian and Bulgarian needlework traditions before EU cohesion funding saturates regional capacity. Ten Thousand Villages anchors the fair-trade network archetype through channel control across Nordic retail networks, demonstrating how certification-driven distribution can displace traditional wholesale intermediaries.
| Leading Market Players |
|---|
| Gangamani Fashions |
| KALYS |
| Fakih Group of Companies |
| Ten Thousand Villages |
| It's Roni |
| Dezaro |
| AMOURRINA |
| Handverk og hönnun |
| Handicrafts Town |
| Others |
Cost & Logistics Intelligence
Bio-based colorant substitution for azo dyes is redrawing supply geography across Tuscan textile clusters while compressing premium pricing spreads between REACH-compliant and legacy production. This input shift simultaneously fragments dye sourcing toward Belgian bio-refineries and elevates compliance costs that filter through to German retail procurement.
Pricing Analysis
After-sales restoration services now anchor lifetime value capture for Scandinavian woodwork ateliers unbundling repair contracts from initial furniture sales. Three-tier pricing structure across heritage-certified, standard artisan, and uncertified production levels stratifies buyer access, with blockchain-verified provenance commanding the widest premiums from Milan interior designers. Cost compression in mid-market textiles is intensifying because Turkish machine-woven substitutes capture hospitality specification at steep discounts. German mass-market buyers exhibit the highest price sensitivity, while Italian collectors absorb substantial premiums for digitized provenance documentation.
Supply Chain Analysis
Belgium and France anchor organic linen fiber supply through the established flax belt, while Portugal and Greece concentrate pottery production for direct hospitality contracting. Raw material dependencies center on Belgian flax harvests, Tuscan bio-dye formulations, and Iberian nickel-compliant metal alloys. Single-source vulnerability in organic fiber supply exposes weavers to weather-driven harvest volatility that disrupts batch consistency. Distribution runs through Nordic fair-trade retail networks for standardized textiles and direct cooperative contracts for site-specific hospitality ceramics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine-woven "hand-finished" substitutes from Turkish industrial producers threaten mid-market positioning, forcing incumbents to defend through certification differentiation and channel control.
For Market Incumbents: Secure blockchain provenance infrastructure to authenticate hand-process documentation and capture resale royalty streams from collector markets. Deepen captive dyeing capacity within Tuscan cooperatives to insulate margin from Belgian flax supply volatility and REACH reformulation costs. For New Entrants and Emerging Players: After-sales restoration service gaps in Scandinavian furniture markets offer white-space entry before extended producer responsibility frameworks tighten disposal accountability. Target Romanian and Bulgarian embroidery clusters for heritage-grade certification ahead of EU cohesion funding saturation, deploying direct e-commerce to bypass wholesale intermediaries. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vertically integrated heritage clusters lacking digitized provenance capabilities. Five-to-ten year viability hinges on certification infrastructure depth rather than production scale alone. Monitor ECHA substance restriction announcements as inflection indicators for compliance-cost revaluation across dye-dependent segments.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Certification Digitization | Blockchain-tracked provenance systems enable Umbrian weavers to command authentication premiums from Copenhagen collectors. |
| Backward Integration into Bio-Dye Production | Captive natural colorant capacity insulates Tuscan cooperatives from ECHA azo dye restrictions and supply disruption. |
| Direct Hospitality Procurement Contracts | Portuguese pottery cooperatives bypass wholesale markups through site-specific architectural ceramics agreements. |
| Eastern European Embroidery Capacity Buildout | Romanian and Bulgarian ateliers attract pre-saturation investment before EU cohesion funding normalizes regional labor costs. |
| After-Sales Restoration Service Launch | Danish woodwork specialists capture recurring revenue under tightening extended producer responsibility disposal frameworks. |
Research Approach
Operator-level perspectives from weaving cooperative managers, pottery studio owners, hospitality procurement directors, and fair-trade retail buyers anchored the qualitative base. Primary field engagement combined with secondary validation against ECHA regulatory filings, EU Green Deal implementation documents, national heritage registry records, and customs trade data for textile and ceramic flows. Bottom-up artisan production estimates triangulated against top-down retail channel absorption metrics.
Sensitivity analysis tested forecast robustness across alternative REACH enforcement timelines and bio-material adoption curves over the projection horizon. Segmentation dimensions modeled include product type, creative technique heritage, end-user category, and distribution channel configuration. CAGRs derived from fitted growth curves incorporating artisan succession rates, certification penetration trajectories, and hospitality procurement shift assumptions.
Underlying assumptions cover REACH substance restriction schedules, EU cohesion funding disbursement patterns, and boutique hospitality expansion rates, with deviation risk concentrated in flax harvest volatility and master craftsperson attrition. Recalibration cycles align with material shifts in ECHA regulatory announcements and national heritage registry designation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crafts & Hobbies
Ironing Beads Market
Crafts & Hobbies
Global Personalized Gifts Market
Crafts & Hobbies
North America Handicrafts Market
Crafts & Hobbies
United States Handicrafts Market
Crafts & Hobbies
Water Color Palette Market
Crafts & Hobbies
Art and Craft Tools Market
Crafts & Hobbies
Dibber Market
Crafts & Hobbies
Needlecraft Patterns Market
Crafts & Hobbies
Macrame Products Market
Crafts & Hobbies
Daughter Craft Market
Crafts & Hobbies
Craft Supplies Market
Crafts & Hobbies
Handicrafts Market
Crafts & Hobbies
Art Supplies Market
Crafts & Hobbies
Global K-12 Arts and Crafts Material Market