
 Clip-On Headphones Market | 2026-2036
Clip-On Headphones Market Size, Share, and Industry Trends Forecast 2026-2036
Clip-On Headphones Market Outlook
Bluetooth Low Energy 5.3 is reconfiguring power architecture across clip-on headphone engineering, enabling manufacturers to shrink battery cells without sacrificing playback duration. Shokz leverages bone-conduction heritage to anchor its open-ear positioning in athletic channels. Bose competes through acoustic research depth, sustaining premium pricing authority across North American retail. Anker Soundcore dominates value-tier distribution through aggressive channel control in e-commerce marketplaces.
Clip-on headphones attach over the outer ear without inserting into the ear canal, typically employing ear hooks or spring-loaded clamps to secure drivers adjacent to the auricle while maintaining ambient sound awareness. Most contemporary units integrate 10-16mm dynamic drivers with IPX4-IPX7 moisture protection for active-use durability. The Bluetooth product type leads volume shipments as cord-free mobility becomes standard among athletes and commuters. Premium offerings capture disproportionate margin pools where high-fidelity tuning and extended battery life command price premiums above mid-range alternatives.
The FCC governs radio frequency emissions for wireless audio devices in the United States, while the EU Radio Equipment Directive mandates interoperability and safety standards across European markets. RoHS and REACH compliance in Europe restricts hazardous substances in driver assemblies and cable insulation, elevating material costs for budget-tier manufacturers. Stakeholders must monitor evolving battery transport regulations and right-to-repair mandates that could reshape modular design requirements and aftermarket service economics.
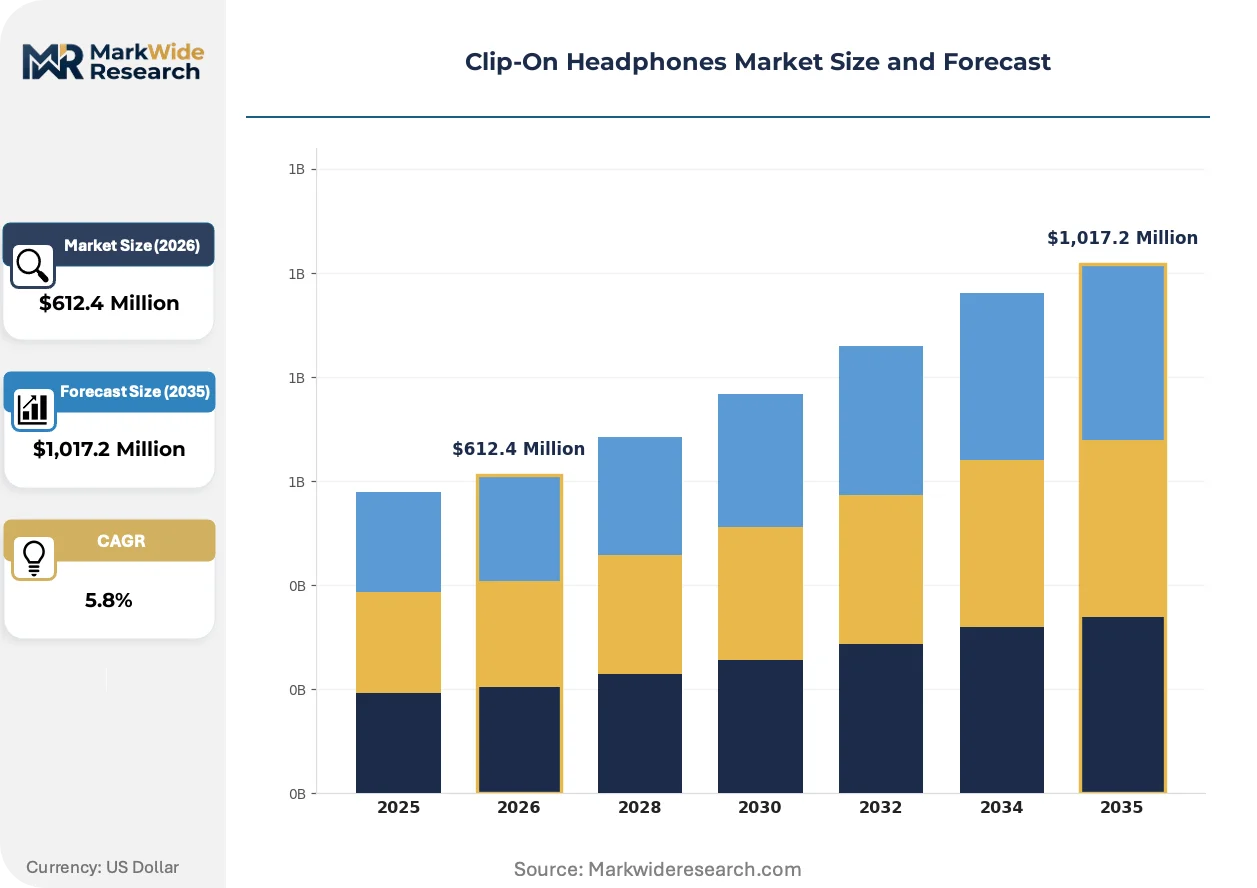
Market Dynamics
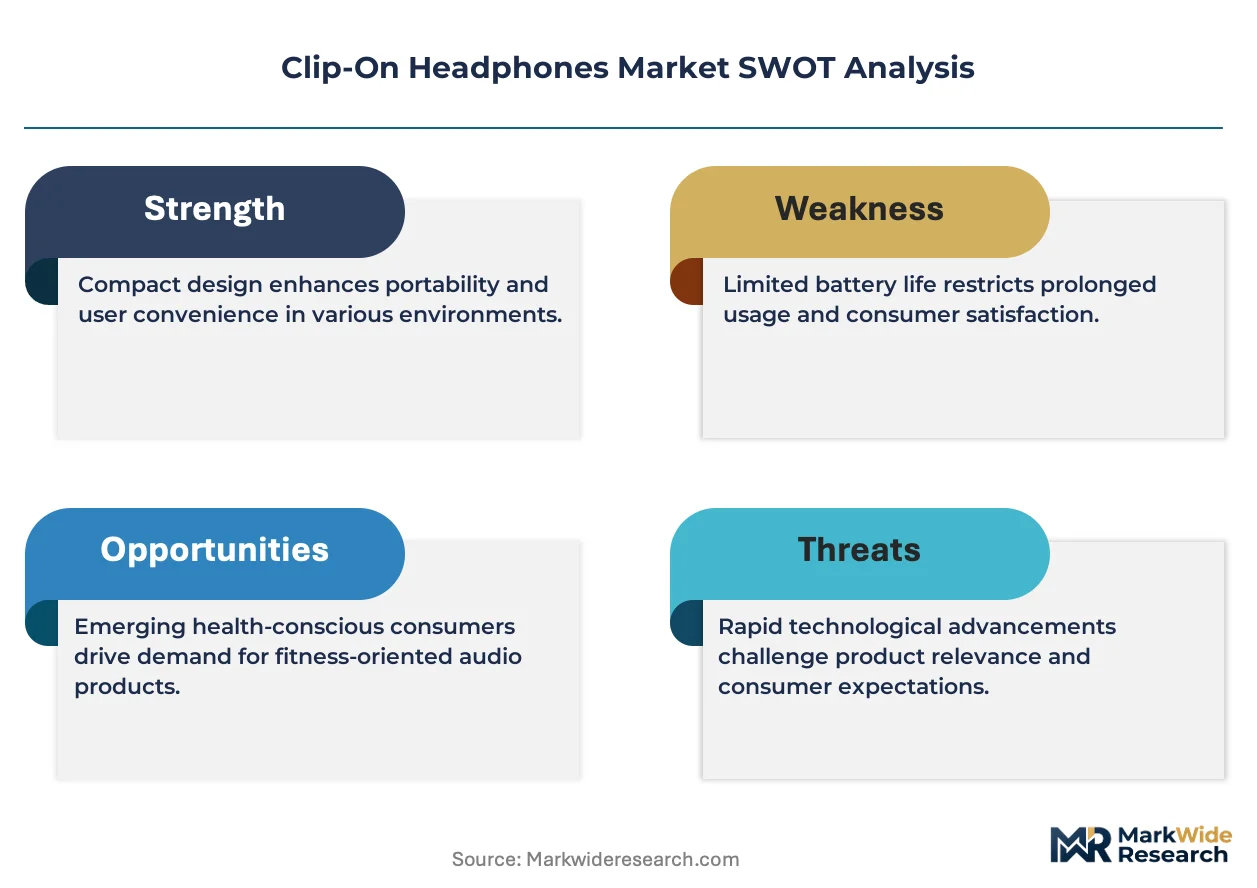
Bluetooth Low Energy 5.3 is compressing power architecture timelines, forcing manufacturers to redesign battery subsystems around milliamp-hour efficiency targets while maintaining playback duration parity with legacy 5.0 implementations.
Growth Catalysts
- Open-ear athletic adoption:Runners and cyclists in the United States favor ambient sound awareness during outdoor training, expanding the addressable user base beyond traditional sealed-earphone markets.
- RoHS material compliance:European REACH restrictions on hazardous substances in driver assemblies are accelerating substitution toward halogen-free cable insulation and lead-free solder joints.
- IPX7 moisture protection:Sweat-resistant sealing technologies enable all-weather usage scenarios that extend product replacement cycles and justify premium positioning.
Market Restraints
- Lithium-polymer cell volatility:Battery raw material cost swings compress margin predictability for mid-tier manufacturers lacking long-term cathode supply contracts.
- Driver supplier concentration:Precision 10-16mm dynamic driver production clusters in East Asian contract manufacturers create single-source vulnerability for Western brands.
- Bone-conduction frequency ceiling:Physical vibration transmission limits sub-bass reproduction below 200Hz, restricting audiophile market penetration regardless of price tier.
Strategic Opportunities
- India fitness infrastructure expansion:Government PLI scheme incentives for electronics manufacturing are lowering import duty exposure for brands establishing local assembly operations.
- Telehealth audio integration:Clip-on form factors enabling simultaneous environmental awareness and clear voice capture suit remote clinical consultation workflows.
- Right-to-repair mandate alignment:Modular battery and driver architectures compliant with emerging EU serviceability requirements create differentiation against sealed disposable competitors.
Industry Challenges
- RF certification timeline compression:FCC Part 15 and EU RED testing queues for 2.4GHz spectrum compliance are extending product launch windows by eight to fourteen weeks.
- Acoustic tuning talent scarcity:Finite pools of engineers capable of optimizing open-ear frequency response without canal coupling are commanding compensation premiums that inflate R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clip-On Headphones Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bluetooth, Wired, Noise-Cancelling, Sports End User: Athletes, Commuters, Students, Audio Professionals Technology: Active Noise Control, Wireless Charging, Touch Control, Voice Assistant Offering: Budget, Mid-Range, Premium, High-Fidelity |
| Companies Covered | Anker Soundcore, SoundPeats, Shokz, Klipsch, Acefast, JBL, Oladance, Fender, Bose, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clip-On Headphones Market Strategic Shifts
Audio transmission protocols and power management semiconductors are converging to redefine minimum viable product specifications, compressing the feature gap between flagship and entry-tier offerings.
Multipoint Bluetooth pairing is migrating from enterprise headset portfolios into consumer clip-on designs, enabling seamless switching between laptop video calls and smartphone audio streams. Remote workers adopting hybrid schedules demand this workflow continuity without manual re-pairing friction. The capability is compressing price-band differentiation as sub-premium SKUs incorporate previously flagship-exclusive controller firmware.
EU battery passport requirements under the Ecodesign for Sustainable Products Regulation are mandating digital traceability for lithium cell origin, chemistry, and cycle life data. Manufacturers must retrofit supply chain data infrastructure to capture mining source documentation and assembly facility carbon footprints. Premium-tier brands with existing ESG audit systems are responding fastest, while value-tier competitors face compliance cost barriers.
Urban commuters in dense metropolitan corridors are prioritizing situational awareness over isolation, rotating demand toward open-ear clip designs that preserve pedestrian and traffic audio cues. This preference shift is displacing active noise cancellation as the default purchase criterion in cycling and running retail channels. United States coastal cities with high bicycle infrastructure investment exhibit the most pronounced behavioral pivot.
Clip-On Headphones Market Segmentation
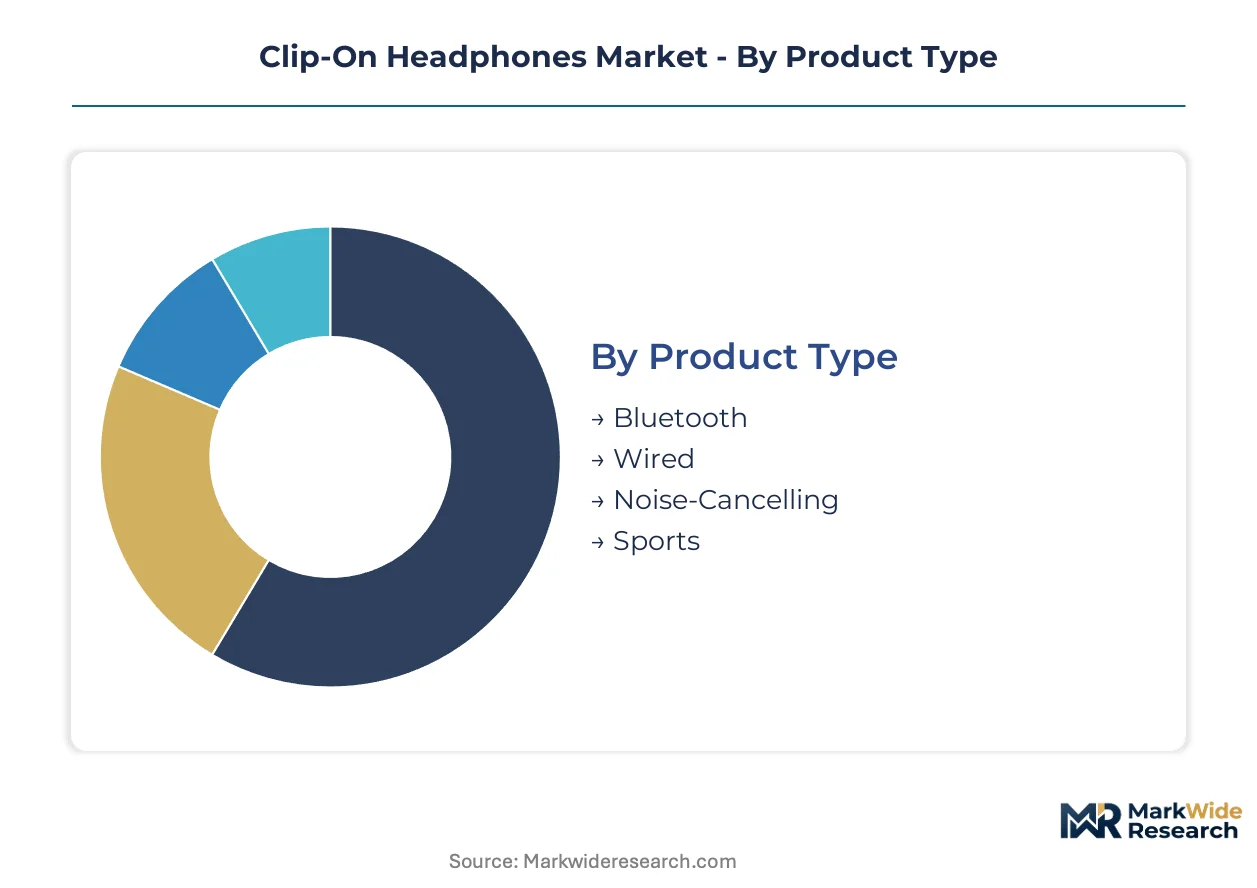
Clip-on headphone purchasing patterns diverge sharply across use-case intensity, with athletic and commuter segments demanding ruggedized moisture sealing while professional users prioritize acoustic precision. Manufacturers must align warranty terms and service network density to each segment's replacement cycle expectations and failure mode profiles.
Product Type:
After-sales-service intensity varies dramatically by connectivity architecture, with wireless designs requiring firmware update infrastructure and battery replacement programs that wired alternatives seldom need.
- Bluetooth:Cord-free implementations integrate BLE 5.3 controllers with lithium-polymer cells requiring periodic replacement. Demand clusters among runners in United States metropolitan corridors where smartphone tethering eliminates cable snag risks during outdoor training.
- Sports:Sweat-optimized variants employ hydrophobic driver membranes and titanium alloy frames rated for IPX7 submersion. Cyclists in coastal California and Florida favor these for salt-air corrosion resistance during year-round outdoor mileage.
- Wired:Analog connectivity persists in institutional procurement for schools and call centers where IT departments restrict Bluetooth spectrum usage. These units carry minimal service overhead beyond driver replacement.
- Noise-Cancelling:Hybrid designs combining open-ear clip mechanics with feedforward microphones remain technically constrained; limited adoption concentrates among air travelers seeking partial isolation without complete canal occlusion.
Bluetooth holds the largest share; momentum sits with Sports as fitness infrastructure investment accelerates across North American and European urban centers.
End User:
Cost tier stratification separates disposable procurement for education budgets from premium expenditure by performance-focused athletes.
- Athletes:Marathoners and triathletes in Germany's Rhine-Ruhr region and Australia's Gold Coast drive demand for sub-30-gram designs with eight-hour-plus playback. These users accept premium pricing for biometric integration and training platform compatibility.
- Commuters:Urban rail and bicycle commuters in Tokyo, London, and New York prioritize situational awareness over isolation. Open-ear clip designs displace sealed earbuds in these corridors where traffic hazard perception outweighs audio fidelity preferences.
- Students:Educational institutions in South Korea and Taiwan procure volume-tier wired units for classroom language labs and standardized testing environments. Price sensitivity dominates with average transaction values below mid-range consumer thresholds.
- Audio Professionals:Broadcast field producers and video editors require flat frequency response for monitoring accuracy. Limited clip-on penetration here reflects bone-conduction and open-air physics constraints against studio-grade reference standards.
Commuters generate the highest unit volume; Athletes deliver the steepest expansion trajectory as endurance sport participation climbs post-pandemic.
Technology:
Application-specific integration determines which feature bundles justify bill-of-materials cost increments across consumer versus enterprise deployment contexts.
- Active Noise Control:Feedforward microphone arrays process ambient sound for selective suppression without canal sealing. Implementation concentrates in premium commuter SKUs targeting United States Northeast Corridor rail riders.
- Wireless Charging:Qi-compatible coil integration adds enclosure volume and cost; adoption remains limited to flagship tier products where convenience premiums offset efficiency losses versus contact charging.
- Touch Control:Capacitive sensor strips on ear-hook surfaces enable gesture-based volume and track navigation. Manufacturing yield challenges from moisture ingress during athletic use constrain reliability ratings.
- Voice Assistant:Wake-word processing requires dedicated DSP silicon and cloud connectivity; battery drain penalties limit deployment to mid-range and above SKUs with sufficient cell capacity.
Active Noise Control commands the widest installed base; Voice Assistant integration is climbing fastest as natural language interfaces mature across smartphone ecosystems.
Offering:
Margin structure and channel economics diverge across four price bands with distinct material specifications and retail placement strategies.
- Premium:Aircraft-grade aluminum housings, custom-tuned 16mm beryllium drivers, and 24-month warranty terms define this tier. Distribution concentrates through specialty audio retailers in Paris, Munich, and Manhattan where demonstration-driven purchase decisions dominate.
- Mid-Range:Polycarbonate enclosures with IPX5 ratings and 12-hour battery life hit the specification threshold for mainstream athletic adoption. E-commerce marketplaces in the United States and United Kingdom capture disproportionate volume here.
- Budget:ABS plastic construction with basic Bluetooth 5.0 and 6-hour playback targets price-sensitive emerging market consumers. India and Southeast Asian urban centers drive procurement through value-tier electronics chains.
- High-Fidelity:Audiophile-grade open-back clip designs with planar magnetic drivers occupy a niche where acoustic purity overrides portability. Japanese and South Korean enthusiast communities sustain limited production runs through direct-to-consumer channels.
Premium captures the highest revenue concentration; Mid-Range is expanding most quickly as feature migration from flagship tier compresses differentiation windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban commuters and endurance athletes concentrate purchasing power across four distinct national markets, each governed by divergent RF emission standards and fitness infrastructure investment cycles.
United States
FCC Part 15 certification timelines stretch product launches by eight to fourteen weeks as 2.4GHz spectrum testing queues lengthen. Runners in Austin and Boulder drive open-ear adoption where trail safety awareness outweighs audio fidelity preferences. The National Park Service's expanding trail network in Colorado and Utah sustains year-round outdoor training demand.
Germany
REACH compliance on halogen-free cable insulation elevates material costs for import-dependent brands. Triathletes in the Rhine-Ruhr metropolitan region prioritize sub-30-gram designs with eight-hour playback for Ironman training blocks. Bavaria's cycling infrastructure investment around Munich accelerates commuter adoption of ambient-aware form factors.
Japan
METI efficiency standards for wireless audio devices mandate standby power thresholds below 0.5 watts. Tokyo's dense rail corridors concentrate commuter volume where situational awareness prevents platform accidents. Osaka-based specialty retailers sustain audiophile-grade open-back clip production for enthusiast communities.
Australia
The Gold Coast's year-round triathlon training culture sustains premium moisture-sealed product demand. TGA device registration requirements for Bluetooth medical-adjacent applications create compliance overhead for telehealth-integrated designs. Sydney's harbor-side cycling infrastructure drives coastal commuter adoption.
India
PLI scheme incentives for electronics manufacturing lower import duty exposure for brands establishing local assembly. Bangalore's marathon running clubs expand addressable demand for biometric-integrated training tools. Mumbai's suburban rail network concentrates commuter volume where open-ear designs address theft and awareness concerns simultaneously.
Clip-On Headphones Market Competitive Environment
Channel-controlling players compete with product-specialist players across three distinct tiers. The market structure consolidates around audio heritage brands, consumer electronics conglomerates, and athletic-specialist entrants. Strategic archetypes include acoustic research laboratories, e-commerce-native value brands, and bone-conduction technology originators. Dominant competitive moves encompass portfolio diversification into adjacent wearable categories and geographic expansion through local assembly partnerships.
Among acoustic heritage anchors, Bose and Klipsch occupy positions where demonstration-driven retail sustains premium pricing authority. Shokz exemplifies the athletic-specialist archetype, leveraging bone-conduction lineage to anchor open-ear positioning in endurance sport channels. Anker Soundcore represents the e-commerce-native value tier, dominating marketplace distribution through aggressive channel control and firmware feature migration from flagship tier.
| Leading Market Players |
|---|
| Anker Soundcore |
| SoundPeats |
| Shokz |
| Klipsch |
| Acefast |
| JBL |
| Oladance |
| Fender |
| Bose |
| Others |
Value Chain & Pricing Dynamics
Lithium-polymer cell production clusters in Chinese and South Korean contract manufacturers concentrate upstream cost leverage, directing margin pools toward brands with long-term cathode supply contracts and captive battery assembly partnerships.
Pricing Analysis
Cost-plus contracts with quarterly lithium carbonate indexation dominate procurement between tier-one brands and cell suppliers. Three-tier pricing structure across premium, mid-range, and budget levels separates aircraft-grade aluminum enclosures with beryllium drivers from polycarbonate IPX5 alternatives. Pricing pressure stems from raw material volatility in cathode chemistry inputs. Educational institutions exhibit highest price sensitivity, while endurance athletes accept premium positioning for biometric integration.
Supply Chain Analysis
Neodymium magnet feedstock and beryllium copper driver diaphragms draw from Chinese rare earth processors and Japanese precision metal suppliers. Dynamic driver assembly concentrates in Dongguan, Shenzhen, and Tainan manufacturing corridors. Single-source vulnerability persists in 10-16mm precision driver tooling. Distribution runs through Amazon marketplace nodes and specialty audio retailers in metropolitan demonstration corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clip-on headphone market structure favors incumbents through regulatory entrenchment, where FCC Part 15 and EU RED certification timelines create eight-to-fourteen-week barriers that capital-constrained challengers cannot absorb.
For Market Incumbents: Pre-empt emerging value-tier challengers by securing exclusive BLE 5.3 controller allocation from Taiwan semiconductor foundries. Deepen backward integration into driver diaphragm stamping to offset East Asian supplier concentration risk. Anchor retail shelf space through demonstration infrastructure investment in specialty audio channels. For New Entrants and Emerging Players: Build out telehealth-integrated clip-on portfolios targeting remote clinical consultation workflows, where simultaneous environmental awareness and voice capture create unmet demand. India's PLI scheme electronics manufacturing incentives offer the most penetrable geography for local assembly cost parity. Pursue direct-to-consumer launch through fitness platform partnership integrations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed consumer audio conglomerates seeking portfolio rationalization. Five-to-ten-year viability hinges on modular design architectures compliant with emerging EU right-to-repair mandates. Monitor EU battery passport implementation timelines as inflection signal for compliance cost barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Battery Architecture Development | Positions brands ahead of EU Ecodesign serviceability requirements. |
| Fitness Platform API Integration | Enables training data synchronization with Strava and Garmin ecosystems. |
| Local Assembly Partnership in India | Reduces import duty exposure under PLI scheme electronics incentives. |
| Telehealth Audio Certification Pathway | Opens clinical consultation workflows through TGA and FDA device registration. |
| Halogen-Free Cable Insulation Transition | Ensures REACH compliance for European market access continuity. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with product managers at audio heritage brands, athletic-specialist entrants, and e-commerce-native value manufacturers; and secondary validation through FCC equipment authorization databases, EU RED compliance filings, and customs trade records for lithium-polymer cell imports. Primary fieldwork encompassed discussions with specialty audio retailers in Manhattan, Munich, and Tokyo, plus procurement leads at educational institutions and telehealth platform operators. Bottom-up shipment estimates triangulated against top-down consumer electronics spending patterns.
Forecast inputs span product type segmentation across Bluetooth, sports-optimized, wired, and noise-cancelling architectures; end-user categories including athletes, commuters, students, and audio professionals; and technology integration levels from basic wireless to voice assistant-enabled designs. CAGRs were derived through regression analysis of historical adoption curves in wearable audio categories, adjusted for BLE 5.3 power efficiency migration and fitness infrastructure investment cycles across target metropolitan corridors.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated semiconductor conglomerates entering audio would shift outcomes. Quarterly review of FCC Part 15 certification queue lengths and EU battery passport regulatory drafts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Audio Equipment
Wireless Audio Devices Market
Audio Equipment
Radio Headset Market
Audio Equipment
Asia-Pacific Wireless Audio Market
Audio Equipment
Commercial Microphone Market
Audio Equipment
India Wireless Audio Market
Audio Equipment
Audio Kits Market
Audio Equipment
Hi-Fi Cartridges Market
Audio Equipment
In Car Audio System Market
Audio Equipment
India Gaming Headset Market
Audio Equipment
Amps & Effects Market
Audio Equipment
Global Networked Audio Products Market
Audio Equipment
Europe Audio Products Market
Audio Equipment
Japan Gaming Headset Market
Audio Equipment
Motorcycle Audio Systems Market
Audio Equipment
United Kingdom Gaming Headset Market
Audio Equipment
Digital a/V Decoder Market