
 United Kingdom Gaming Headset Market | 2026-2036
United Kingdom Gaming Headset Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Gaming Headset Market Insights
Casual gamers is bifurcating from professional players and streamers as the dominant volume segment while esports teams command disproportionate margin pools. Corsair Gaming Inc anchors its position through in-house production of high-fidelity drivers and proprietary wireless protocols. Razer Inc differentiates via RGB-integrated designs and software ecosystems that lock in repeat purchases. SteelSeries competes aggressively on tournament sponsorships and team partnerships that reinforce brand credibility among competitive users.
A gaming headset is an audio peripheral engineered with circumaural or supra-aural earcups, typically housing 40–53mm dynamic drivers, low-latency wireless chipsets or braided analog cables, and unidirectional or bidirectional microphones for voice communication during multiplayer sessions. Its primary purpose is to deliver positional audio cues and clear voice transmission that competitive gameplay demands. Wireless configurations capture the fastest expansion as latency compression and battery endurance improvements eliminate performance gaps with wired alternatives. Premium and luxury price tiers concentrate margin pools where audiophile-grade components and broadcast-quality microphone arrays justify substantial price premiums over budget and mid-range offerings.
OFCOM governs wireless spectrum allocation and electromagnetic compatibility certification for radio-enabled headsets sold in the United Kingdom. The UK's Product Safety and Metrology regulations, aligned with retained EU CE marking requirements, mandate acoustic output limits and material safety standards for prolonged skin contact. Stakeholders must monitor impending revisions to e-waste directives and right-to-repair frameworks that could mandate modular designs and extended software support obligations.
Market Dynamics
The United Kingdom gaming headset market is bifurcating into two distinct procurement ecosystems: casual gamers driving volume through mass retail channels while esports organizations and professional streamers command premium pricing through direct B2B relationships with broadcast-grade audio vendors.
Growth Catalysts
- Esports infrastructure investment:Professional gaming leagues and tournament organizers in England are mandating standardized audio equipment, creating institutional demand for certified headsets across London, Manchester, and Birmingham competitive venues.
- OFCOM spectrum modernization:Revised wireless allocation rules are enabling sub-6GHz low-latency protocols that eliminate performance gaps between wireless and wired configurations, accelerating replacement cycles among competitive users.
- Retained EU CE marking alignment:The UK's Product Safety and Metrology regime maintains electromagnetic compatibility certification continuity, reducing friction for manufacturers distributing across Northern Ireland and Great Britain.
Market Restraints
- Driver component concentration:High-fidelity 50mm dynamic driver production concentrates among East Asian suppliers, exposing UK distributors to shipping volatility and currency fluctuation risks.
- Acoustic output limits:The UK's retained EU sound exposure regulations cap maximum decibel output, constraining differentiation opportunities for vendors competing on raw volume specifications.
- Right-to-repair uncertainty:Pending e-waste directive revisions may mandate modular designs and extended software support obligations, compressing margins for vendors with integrated, non-serviceable architectures.
Strategic Opportunities
- Scotland and Wales penetration:Peripheral demand outside England's gaming corridor remains underdeveloped, presenting first-mover advantages for vendors establishing distribution partnerships in Edinburgh, Glasgow, and Cardiff retail networks.
- Cloud gaming audio optimization:Emerging low-latency streaming platforms are creating demand for headsets with adaptive bitrate audio processing, a specification category where incumbent vendors have not established dominance.
- Sustainability certification differentiation:Anticipated carbon footprint disclosure requirements under the UK's evolving environmental regulations will reward vendors with transparent supply chain documentation and recyclable material sourcing.
Industry Challenges
- RF engineering talent scarcity:Wireless protocol optimization for gaming-grade latency requires specialized firmware expertise that competes with broader consumer electronics and telecommunications sectors for limited UK engineering graduates.
- Multi-platform certification complexity:Headsets must simultaneously satisfy Sony PlayStation, Microsoft Xbox, and Nintendo Switch audio authentication standards, extending product development timelines and testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Gaming Headset Market |
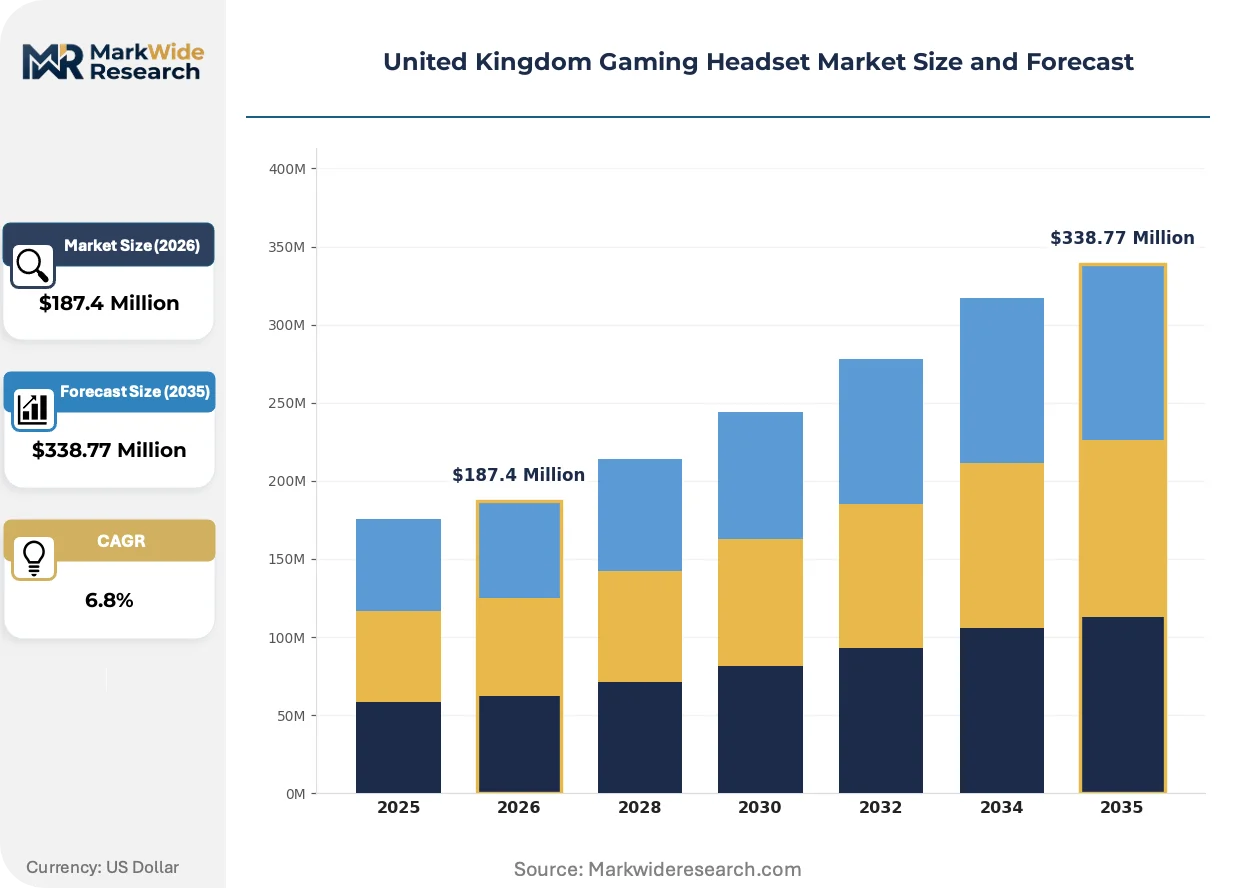
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Noise-Canceling, Surround Sound End User: Casual Gamers, Professional Players, Streamers, Esports Teams Brand: Logitech, SteelSeries, Razer, HyperX Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Logitech International S.A., Corsair Gaming Inc, Razer Inc, SteelSeries, Turtle Beach Corporation, HyperX, EPOS, Astro Gaming, Sony, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Gaming Headset Market Trends and Innovations
Wireless audio architectures are decomposing the traditional wired-dominant competitive gaming segment, while regulatory pressure on electromagnetic emissions and material safety is accelerating design standardization across the United Kingdom.
Spatial audio processing with head-tracking sensors is decomposing conventional stereo positioning in competitive gaming. Professional esports organizations in England are adopting this technology for training facilities, compressing the performance advantage previously held by conventional surround-sound virtualization. Tournament broadcasters are now mandating compatible equipment for participant uniformity.
OFCOM's updated wireless equipment authorization framework is tightening electromagnetic compatibility testing requirements for radio-enabled peripherals. Manufacturers must now submit expanded documentation on spurious emission profiles, extending certification timelines by several months. Premium-tier vendors with established compliance departments are absorbing these costs more readily than budget competitors, reinforcing tier stratification.
Subscription-based hardware access models are emerging among UK gaming cafes and esports training facilities. These venues are replacing outright headset purchases with monthly equipment refresh programs, transferring obsolescence risk to distributors. Manchester and Birmingham gaming hubs are piloting this arrangement most aggressively, pressuring traditional retail channels to develop corresponding financing structures.
United Kingdom Gaming Headset Market Segmentation
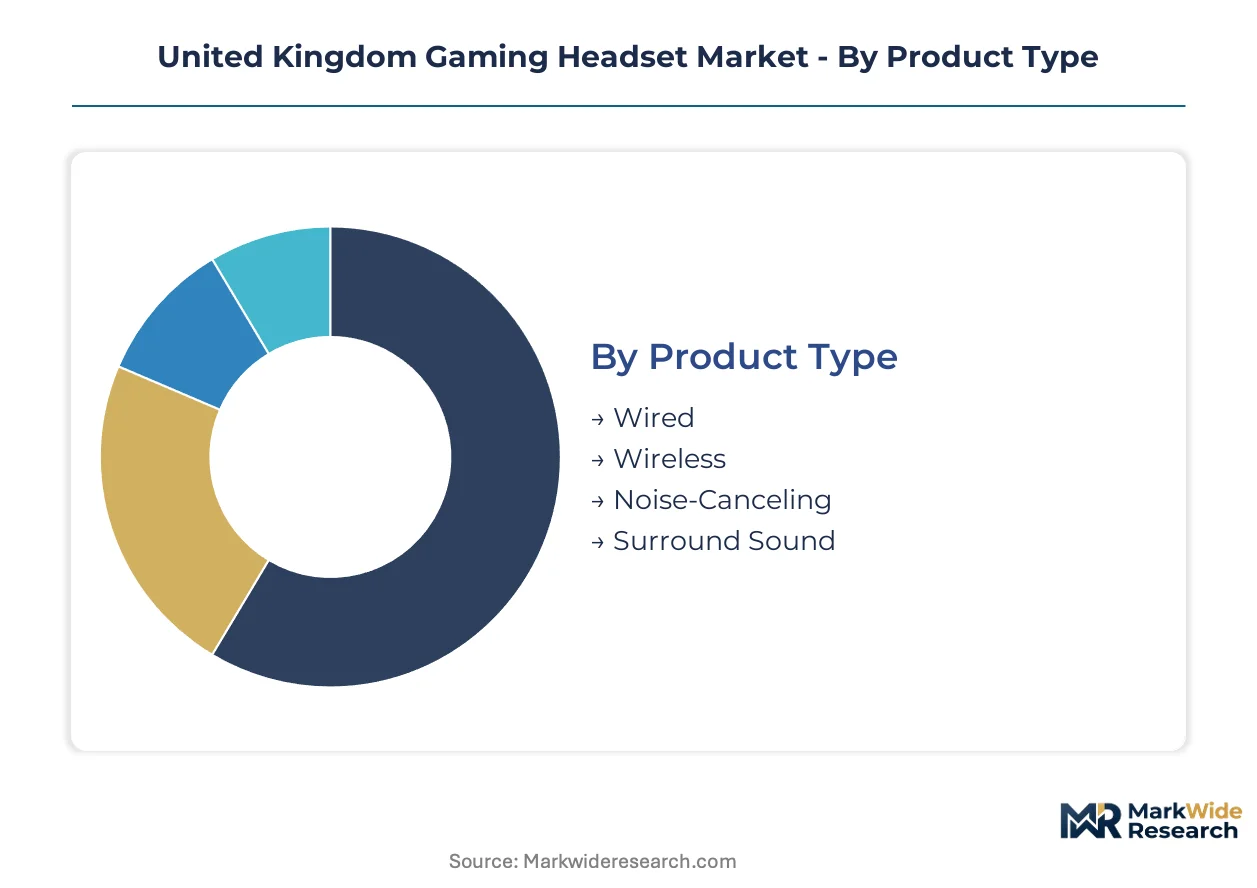
Segmentation in the United Kingdom gaming headset market reveals how procurement patterns split between mass-market volume and specialized performance requirements. Understanding these divides exposes where margin pools concentrate and which technical specifications command price premiums across England's gaming corridor and beyond.
Product Type:
OFCOM's wireless spectrum modernization has eliminated the performance gap between radio-enabled and cabled configurations, reshaping competitive dynamics across all four product categories.
- Wired:Braided analog cables with USB-C or 3.5mm termination deliver uncompressed audio streams and zero-latency transmission for tournament play. Demand concentrates among esports organizations in London and Manchester competitive venues where OFCOM electromagnetic certification adds procurement friction to wireless alternatives.
- Wireless:Sub-6GHz low-latency chipsets with 40-hour battery endurance now match wired response times. Adoption climbs fastest among professional streamers across Birmingham gaming hubs who require unrestricted movement during broadcast sessions.
- Noise-Canceling:Hybrid ANC circuits with feedforward and feedback microphones isolate environmental interference. Home-based casual gamers in dense urban England locations prioritize this specification for immersive single-player experiences.
- Surround Sound:Virtual 7.1 channel processing through 50mm dynamic drivers creates positional audio cues. Competitive players seeking directional accuracy in first-person titles drive replacement cycles here.
Established volume favors wired configurations; emerging adoption favors wireless architectures.
End User:
Procurement economics diverge sharply between individual purchasers optimizing for price-performance and institutional buyers mandating broadcast-grade uniformity.
- Casual Gamers:Individual consumers purchasing through mass retail channels in London, Manchester, and Birmingham. Volume concentration here absorbs budget and mid-range inventory, though per-unit margins remain compressed.
- Professional Players:Individual competitors requiring tournament-certified equipment with standardized latency specifications. Direct B2B relationships with audio vendors dominate this segment's procurement pattern.
- Streamers:Content creators prioritizing microphone array quality and RGB aesthetic integration for audience engagement. Scotland and Wales penetration remains underdeveloped for this user type.
- Esports Teams:Institutional purchasers mandating equipment uniformity across training facilities and competitive venues. Disproportionate margin pools concentrate here due to bulk procurement and replacement guarantees.
Volume gravity centers on casual gamers; margin extraction targets esports teams.
Brand:
Vendor positioning reflects differentiated supply chain strategies and proprietary technology investments rather than interchangeable commodity competition.
- Logitech:In-house driver manufacturing and LIGHTSPEED wireless protocol development anchor premium positioning. Distribution partnerships span major UK electronics retailers and direct-to-consumer channels.
- SteelSeries:Tournament sponsorship density and team partnership networks reinforce competitive credibility. Esports organization procurement favors this brand for institutional standardization.
- Razer:RGB-integrated industrial design and Synapse software ecosystem create switching costs. Repeat purchase loyalty concentrates among streamers and aesthetic-conscious casual users.
- HyperX:Memory heritage translates to comfort-engineered earcup design and cloud gaming optimization. Value positioning captures price-sensitive entrants in the gaming peripheral category.
Software ecosystem lock-in favors Razer; tournament certification favors SteelSeries.
Price Tier:
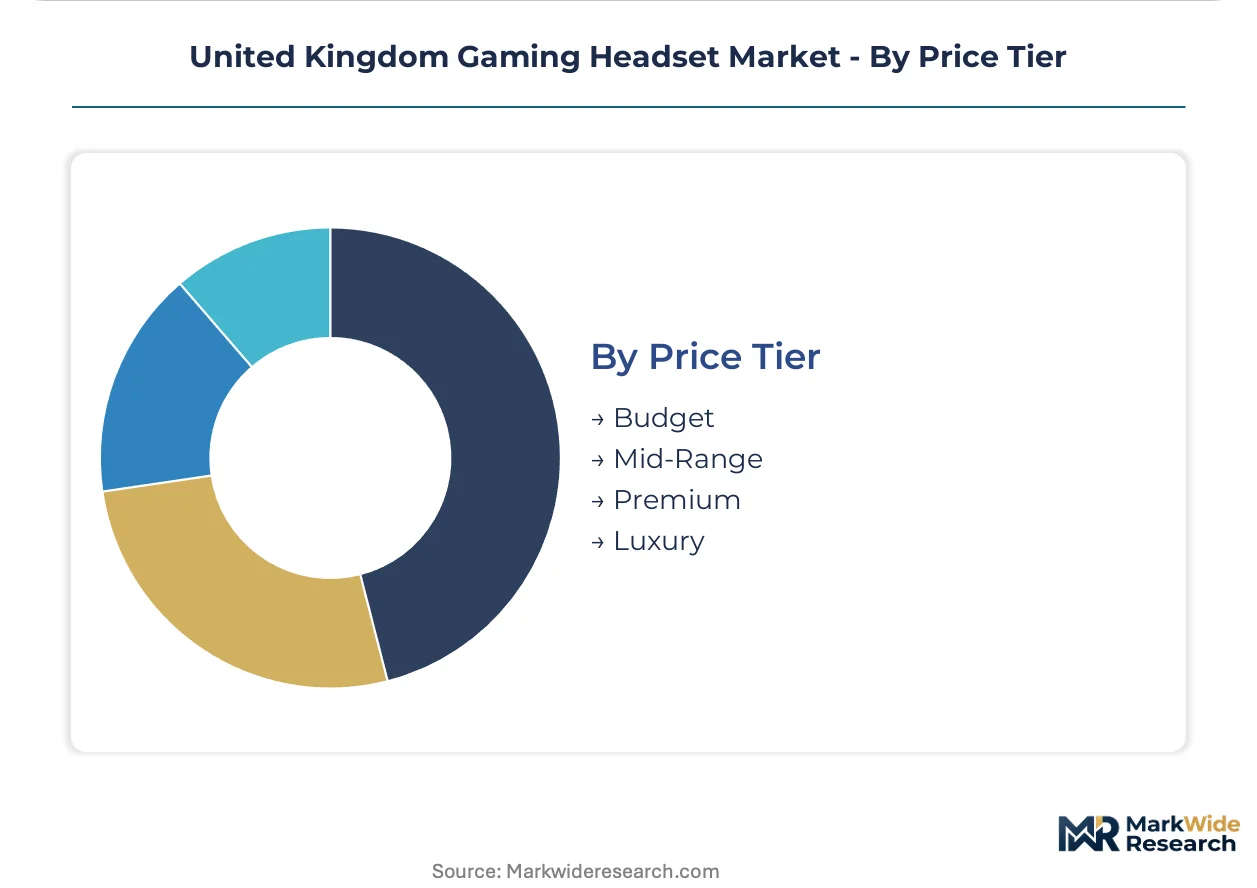
Cost stratification aligns with component grade, acoustic certification, and microphone array specifications rather than brand premium alone.
- Budget:40mm dynamic drivers and basic electret microphones serve entry-level multiplayer participation. Mass retail channels in England's gaming corridor move this inventory at high velocity with minimal margin.
- Mid-Range:50mm drivers with virtual surround processing and detachable boom microphones. The largest volume segment absorbs mainstream casual gamer demand across UK high-street and online retailers.
- Premium:Audiophile-grade driver materials, broadcast-quality microphone arrays, and dual-wireless connectivity. Professional players and serious streamers in Manchester and Birmingham gaming hubs drive replacement cycles here.
- Luxury:Beryllium or planar magnetic drivers, active noise cancellation, and extended warranty programs. Margins concentrate where esports teams standardize equipment across entire rosters.
Mid-range captures volume leadership; premium and luxury tiers command margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement gravity concentrates in England's gaming corridor while institutional buyers in Scotland and Wales remain underserved. Professional esports organizations drive disproportionate margin extraction through direct B2B relationships.
London and the Southeast
Esports tournament organizers and streaming studios anchor demand for broadcast-grade audio equipment. OFCOM's electromagnetic compatibility certification requirements filter wireless headset distribution through authorized channels. The M25 gaming hub corridor hosts training facilities for professional teams mandating standardized equipment procurement.
Midlands
Birmingham's emerging gaming cafe networks pilot subscription-based hardware refresh programs. The UK's Product Safety and Metrology regulations enforce acoustic output limits that constrain raw volume specifications. Manufacturing logistics clusters around Coventry distribute inventory across central England retail networks.
North England
Manchester's competitive gaming venues institutionalize certified headset requirements for tournament participation. Retained EU CE marking alignment reduces friction for manufacturers distributing across Northern England and Northern Ireland. Sheffield and Leeds retail corridors absorb mid-range volume from casual gamer segments.
Scotland
Edinburgh and Glasgow gaming communities show underpenetrated demand for premium-tier peripherals. The Scottish government's digital economy initiatives support esports infrastructure development without specific audio equipment mandates. Local distributors face longer lead times from England-based logistics hubs.
Wales
Cardiff's peripheral retail networks remain dependent on cross-border supply chains from Bristol and Birmingham. Welsh gaming cafes represent nascent demand for institutional procurement relationships. Right-to-repair directive uncertainty complicates inventory planning for vendors with integrated product architectures.
United Kingdom Gaming Headset Market Competitive Landscape
Player mix skews toward diversified consumer electronics conglomerates with captive audio engineering divisions. Market structure shows moderate consolidation where three to five vendors extract disproportionate margin from esports institutional procurement. Strategic archetypes include in-house driver manufacturers, software-ecosystem integrators, and tournament-sponsorship specialists. Dominant competitive moves encompass backward integration into high-fidelity component production and exclusive partnership arrangements with professional gaming organizations.
Within the software-ecosystem tier, Razer Inc exemplifies RGB-integrated design differentiation and repeat-purchase loyalty engineering. Corsair Gaming Inc represents in-house manufacturing control over driver production and proprietary wireless protocol development. SteelSeries occupies a position emphasizing competitive credibility through team partnership density. These three vendors anchor distinct competitive vectors without interchangeable substitution.
| Leading Market Players |
|---|
| Logitech International S.A. |
| Corsair Gaming Inc |
| Razer Inc |
| SteelSeries |
| Turtle Beach Corporation |
| HyperX |
| EPOS |
| Astro Gaming |
| Sony |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation contracts with East Asian driver manufacturers lock in supply access and price visibility for UK distributors navigating OFCOM certification timelines and currency fluctuation exposure. These arrangements tether procurement economics to semiconductor foundry output schedules while insulating premium-tier vendors from spot-market volatility in neodymium magnet and copper voice coil inputs.
Pricing Analysis
Cost-plus contracts with raw material indexation to copper and rare earth oxide benchmarks dominate procurement between UK distributors and East Asian component suppliers. Three-tier pricing structure across premium, standard, and economy levels separates broadcast-grade microphone arrays from basic electret configurations. Price differentiation hinges on OFCOM electromagnetic certification tier and driver diameter specifications. Cost compression in budget tiers is intensifying because retained EU CE marking alignment has flattened compliance cost advantages among mid-market competitors. Casual gamers in England's retail corridor exhibit highest price sensitivity; esports teams mandate uniformity regardless of per-unit cost.
Supply Chain Analysis
Port congestion along Shenzhen-Hong Kong trade lanes and container availability constraints at Felixstowe and Southampton anchor inbound logistics costs for UK distributors sourcing finished headsets and discrete components. Manufacturing concentration in China, Taiwan, and Vietnam feeds driver production, PCB assembly, and final packaging stages. Raw material dependencies center on neodymium magnets, copper voice coils, and ABS polymer housings. Single-source vulnerability concentrates in 50mm dynamic driver fabrication, where three Taiwanese suppliers control majority output. Distribution runs through Birmingham and Coventry logistics hubs serving England's gaming corridor, with cross-border replenishment to Scotland and Wales adding lead time exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OFCOM's sub-6GHz spectrum modernization constitutes a technological inflection accelerating wireless adoption and compressing replacement cycles across professional and casual segments alike. This regulatory shift disrupts incumbent positioning while opening margin pools for vendors with proprietary low-latency protocols.
For Market Incumbents: Consolidate tournament certification relationships and in-house driver manufacturing capacity to defend against emerging entrants with software-centric positioning. Prioritize backward integration into high-fidelity component production to offset East Asian supplier concentration. Channel control through direct B2B esports team partnerships remains the critical lever for margin extraction. For New Entrants and Emerging Players: Lead with cloud gaming audio optimization specifications where incumbent vendors have not established protocol dominance. Scotland and Wales retail networks present the most penetrable geography, with Edinburgh and Glasgow showing underdeveloped premium-tier peripheral demand. A direct-to-streamer go-to-market angle emphasizing RGB aesthetic integration and microphone array quality bypasses established tournament sponsorship barriers. For Investors and Strategic Acquirers: Firmware engineering boutiques with wireless latency compression expertise represent the priority acquisition archetype, given RF talent scarcity across UK engineering graduate pools. Long-term viability over the analysis window favors vendors with modular architectures positioned for impending right-to-repair mandate compliance. Watch OFCOM equipment authorization framework revisions as the signal indicating regulatory cost acceleration and tier stratification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Wireless Protocol Development | OFCOM sub-6GHz authorization enables latency parity with wired configurations for competitive users. |
| Esports Team Exclusive Partnership | Institutional procurement standardization across London and Manchester venues locks in replacement revenue. |
| Modular Design Architecture Transition | Anticipated UK right-to-repair mandates favor serviceable driver and battery configurations. |
| Scotland and Wales Distribution Expansion | First-mover positioning in Edinburgh and Glasgow retail networks captures underpenetrated premium demand. |
| Sustainability Certification Investment | Carbon footprint disclosure requirements reward transparent supply chain documentation and recyclable sourcing. |
Research Methodology
Desk research of customs trade records, OFCOM equipment authorization filings, and SEC 10-K peripheral segment disclosures preceded structured interviews with esports organization procurement directors, UK electronics retailer category managers, and wireless audio firmware engineers. Primary fieldwork with tournament organizers in London, Manchester, and Birmingham competitive venues combined with secondary validation from retained EU CE marking technical documentation. Bottom-up unit shipment estimates across price tiers and top-down value reconciliation anchored market size triangulation.
Variance decomposition across product type, end user archetype, and regional adoption patterns structured the analytical framework throughout the forecast period. Segmentation modeling incorporated connectivity configuration, microphone array specification, and brand ecosystem lock-in intensity as discrete dimensions. CAGRs derived from replacement cycle analysis and esports infrastructure investment trajectories, with cross-reference to professional streamer equipment refresh rates and casual gamer upgrade propensity surveys.
Forecasts assume regulatory continuity in OFCOM wireless allocation rules and UK Product Safety and Metrology regimes; material policy shifts would require re-modeling. Model boundaries exclude non-gaming audio peripheral categories and enterprise conferencing equipment markets. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Audio Equipment
Europe Audio Products Market
Audio Equipment
Global Wireless Audio Market
Audio Equipment
Mixing Console Market
Audio Equipment
Amps & Effects Market
Audio Equipment
Clip-On Headphones Market
Audio Equipment
Asia-Pacific Wireless Audio Market
Audio Equipment
Japan Gaming Headset Market
Audio Equipment
Hi-Fi Cartridges Market
Audio Equipment
Wireless Audio Products Market
Audio Equipment
Gaming Headsets and Gaming Headphones Market
Audio Equipment
Soundbar Market
Audio Equipment
Speaker Driver Market
Audio Equipment
Electronic Drums Market
Audio Equipment
Global Networked Audio Products Market
Audio Equipment
Wireless Audio Devices Market
Audio Equipment
Consumer Audio Market