
 Spain Do-It-Yourself (DIY) Home Improvement Retailing Market | 2026-2036
Spain Do-It-Yourself (DIY) Home Improvement Retailing Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Do-It-Yourself (DIY) Home Improvement Retailing Market Insights
Specialist hypermarket formats is reconfiguring how Spaniards source building materials and decorative finishes. Leroy Merlin leverages its nationwide big-box network to anchor category management across power tools and garden equipment. Bricomart competes through concentrated industrial-zone locations that target trade professionals with bulk pricing on construction supplies. Bauhaus differentiates via its German-origin technical assortment, sustaining loyalty among precision-oriented renovators in the Basque Country and Catalonia.
Spain Do-It-Yourself Home Improvement Retailing encompasses the organized sale of building materials, decorative products, installation equipment, and home maintenance supplies through retail channels serving non-professional consumers and light trade buyers. Product specifications span solvent-free interior paints meeting VOC thresholds, laminate flooring with AC4 abrasion ratings, and LED luminaires carrying CE marking under EU ecodesign rules. Tools and paints command the deepest margin pools as repeat-purchase categories with strong private-label penetration, while lighting is accelerating fastest as efficiency regulations phase out legacy halogen stock. The homeowner segment dominates transaction volume, though contractors represent the highest average ticket and drive wholesale channel development.
Spain's Ministry for the Ecological Transition enforces building energy certification mandates that redirect renovation spending toward insulation and efficient systems, while the national consumer protection authority monitors product safety claims under EU GPSD transposition. BIS-equivalent Spanish standards body AENOR certifies structural timber and electrical accessories, creating compliance gateways for imported merchandise. Stakeholders must track how EU Ecodesign Working Plan expansions and national recovery fund disbursement timelines reshape category prioritization across autonomous communities.
Market Dynamics
Spain's transposition of EU building energy performance directives is redirecting renovation expenditure toward thermal insulation and efficient heating systems, compressing demand cycles for traditional decorative categories while expanding specialized building material requirements.
Growth Catalysts
- Certification mandates:Spain's Ministry for the Ecological Transition enforces energy performance certificates that compel homeowners to upgrade insulation and install efficient systems before resale.
- Coastal second-home refurbishment:Mediterranean provinces including Alicante and Málaga exhibit accelerated renovation cycles as international owners modernize aging vacation properties.
- LED technology penetration:EU ecodesign rules phasing out halogen luminaires are forcing stock rotation toward LED fixtures with integrated smart controls.
Market Restraints
- Timber supply concentration:Structural softwood imports depend heavily on Nordic and Baltic suppliers, exposing retailers to freight cost volatility and currency fluctuation.
- Technical skills shortage:Installation of heat-pump systems and advanced insulation requires certified technicians that remain scarce in rural Castilla-La Mancha and Extremadura.
- Substitution by professional services:Turnkey renovation contractors capturing complex projects reduce addressable market for pure material suppliers serving DIY segments.
Strategic Opportunities
- Basque Country technical segment:Industrial heritage and higher disposable income create demand for precision tools and German-origin technical assortments that command premium positioning.
- Recovery fund disbursement:Spain's national recovery plan allocates subsidies for residential energy efficiency that expand eligible product categories for participating retailers.
- Digital-physical channel fusion:Click-and-collect integration with in-store project consultation addresses time-constrained urban professionals in Madrid and Barcelona metropolitan zones.
Industry Challenges
- AENOR certification timelines:Electrical accessories and structural timber require third-party testing that delays product launches and ties working capital in compliance documentation.
- Inventory reconfiguration costs:Shifting category mix toward bulky insulation materials demands warehouse reorganization and expanded last-mile delivery capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Do-It-Yourself (DIY) Home Improvement Retailing Market |
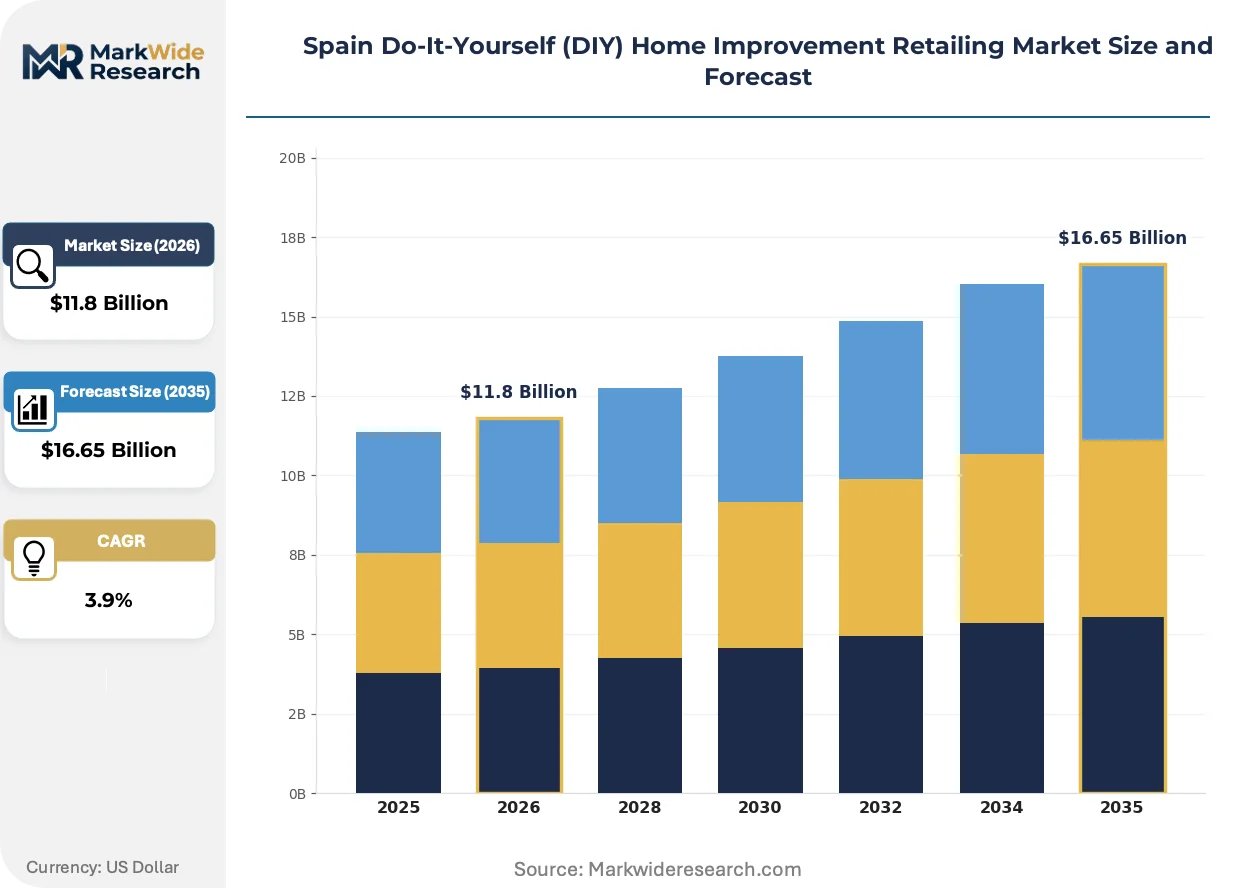
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $16.65 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tools, Paints, Flooring, Lighting Customer Type: Homeowners, Contractors, Renters, Designers Distribution Channel: Online Retail, Physical Stores, Wholesale, Catalog Sales Price Tier: Premium, Mid-range, Discount, Value |
| Companies Covered | Leroy Merlin, Bricomart, Bricor, Brico Depot, Bauhaus, Adeo Group, Kingfisher, Pinturas Andalucía, Hoffman Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Do-It-Yourself (DIY) Home Improvement Retailing Market Trends and Innovations
Digital tools and connected home systems are reshaping how Spanish consumers plan, purchase, and execute renovation projects, compressing the traditional research-to-purchase timeline while elevating technical support expectations.
Smart home integration platforms that coordinate lighting, climate, and security through unified mobile interfaces are rendering obsolete standalone device categories that previously dominated electrical aisles. Younger homeowners in Barcelona and Madrid metropolitan areas adopt these systems at pace, treating home automation as standard infrastructure rather than premium add-on. Retailers must now stock compatible ecosystems and train floor staff on interoperability protocols, compressing margins on legacy electrical accessories.
Spain's national transposition of EU Ecodesign Working Plan expansions is tightening permissible energy consumption thresholds for residential heating and cooling equipment. The industrial consequence mandates inventory clearance of non-compliant boiler and air-conditioning stock before prohibition dates. Basque Country and Navarre retailers face compressed timelines due to earlier regional enforcement, accelerating promotional activity on affected product lines.
Project-based purchasing is displacing single-item transactions as homeowners approach renovation through comprehensive room overhauls rather than incremental repairs. This pattern concentrates demand in full-kitchen and bathroom solutions, pressuring retailers to offer design consultation and installation coordination. The shift is most visible in Valencia and Seville where younger demographics favor turnkey aesthetic coherence over functional replacement.
Spain Do-It-Yourself (DIY) Home Improvement Retailing Market Segmentation
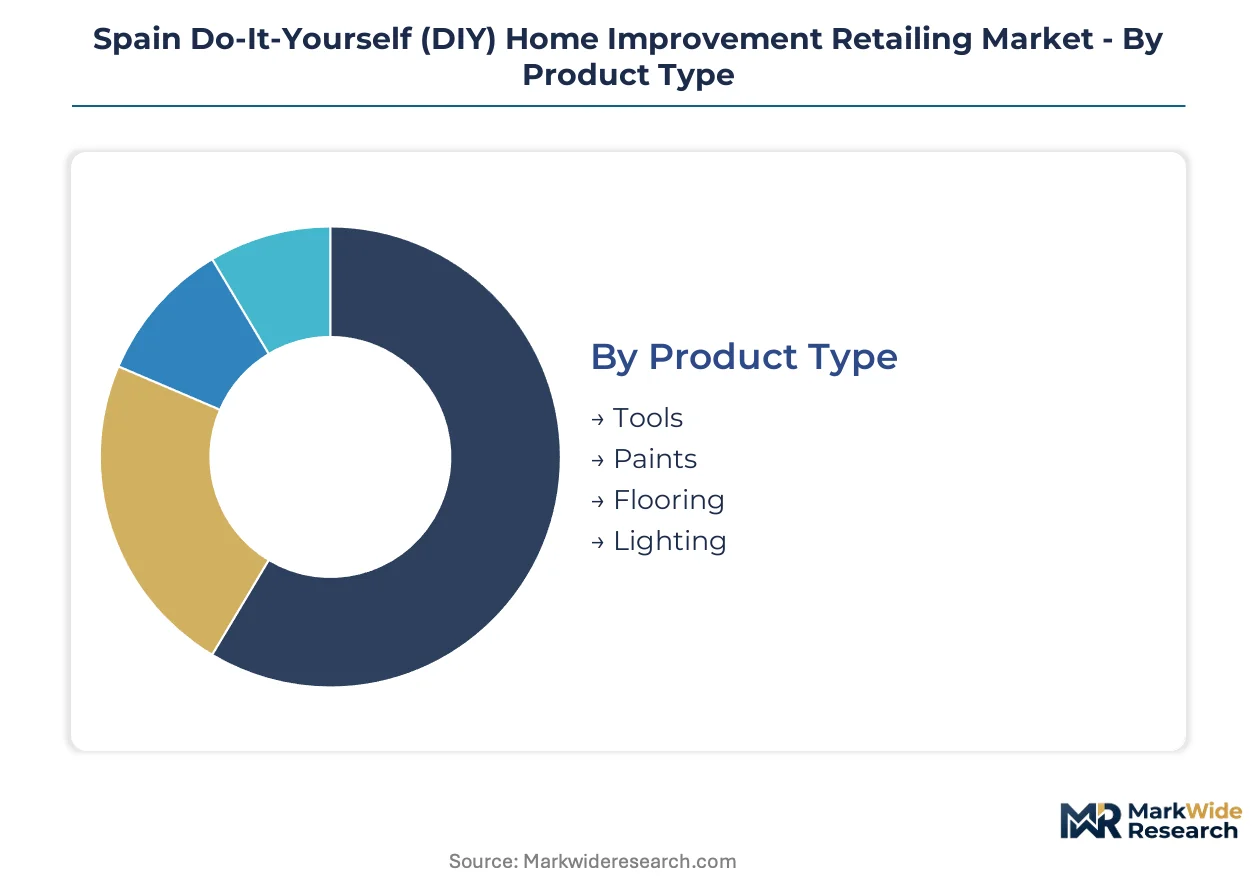
Segmentation in Spain's DIY home improvement retailing reveals how distinct buyer motivations and project scopes reshape category priorities across autonomous communities. Understanding these divides allows retailers to calibrate inventory depth, service intensity, and pricing architecture to specific demand clusters.
Product Type:
The use-case spectrum spans functional repair through aesthetic transformation, with each category carrying distinct margin profiles and purchase frequency rhythms.
- Tools:Cordless power tools and hand tool assortments dominate repeat-purchase frequency among Madrid and Barcelona homeowners executing seasonal maintenance. Professional-grade lithium-ion platforms command premium positioning in Basque Country industrial zones where technical precision drives specification.
- Paints:Solvent-free interior coatings meeting EU VOC thresholds concentrate demand in coastal Mediterranean provinces where second-home refurbishment cycles accelerate. Pigment technology and durability ratings differentiate premium architectural lines from economy coverage solutions.
- Flooring:Laminate surfaces with AC4 abrasion ratings and engineered wood alternatives address moisture-sensitive applications in humid Atlantic climates.
- Lighting:LED luminaires carrying CE marking under EU ecodesign rules are displacing legacy halogen stock as efficiency mandates tighten.
Established volume favors tools; emerging adoption favors lighting.
Customer Type:
Cost tier stratification separates transactional material buyers from relationship-dependent project orchestrators seeking bundled services.
- Homeowners:Owner-occupiers in urban Madrid and Barcelona metropolitan zones drive transaction volume through room-scale renovation projects requiring design consultation and installation coordination. Energy efficiency subsidies under Spain's national recovery plan redirect their spending toward insulation and heating system upgrades.
- Contractors:Trade professionals generate the highest average ticket values through bulk procurement of construction supplies concentrated in industrial-zone Bricomart locations. Their demand for certified electrical accessories and structural timber creates AENOR compliance gateways that delay product launches.
- Renters:Temporary occupants favor portable solutions and reversible modifications with minimal structural impact.
- Designers:Specification professionals curate aesthetic coherence across full-kitchen and bathroom solutions in Valencia and Seville markets.
Contractor relationships anchor margin stability; homeowner digital engagement is climbing the fastest.
Distribution Channel:
Application context determines whether buyers prioritize immediate physical verification or remote convenience with deferred fulfillment.
- Online Retail:E-commerce platforms capture growing share among time-constrained urban professionals seeking click-and-collect integration with in-store project consultation. Product visualization tools and compatibility configurators reduce return rates on technical electrical and lighting categories.
- Physical Stores:Big-box hypermarket formats sustain category management dominance across power tools and garden equipment through tactile evaluation and staff technical guidance. Leroy Merlin's nationwide network anchors this channel's geographic coverage.
- Wholesale:Bulk pricing structures serve contractor segments with consolidated delivery logistics for construction sites.
- Catalog Sales:Remaining print-direct operations target rural Castilla-La Mancha and Extremadura regions with limited broadband infrastructure.
Physical presence retains tool category dominance; online penetration is expanding most quickly in lighting and decorative finishes.
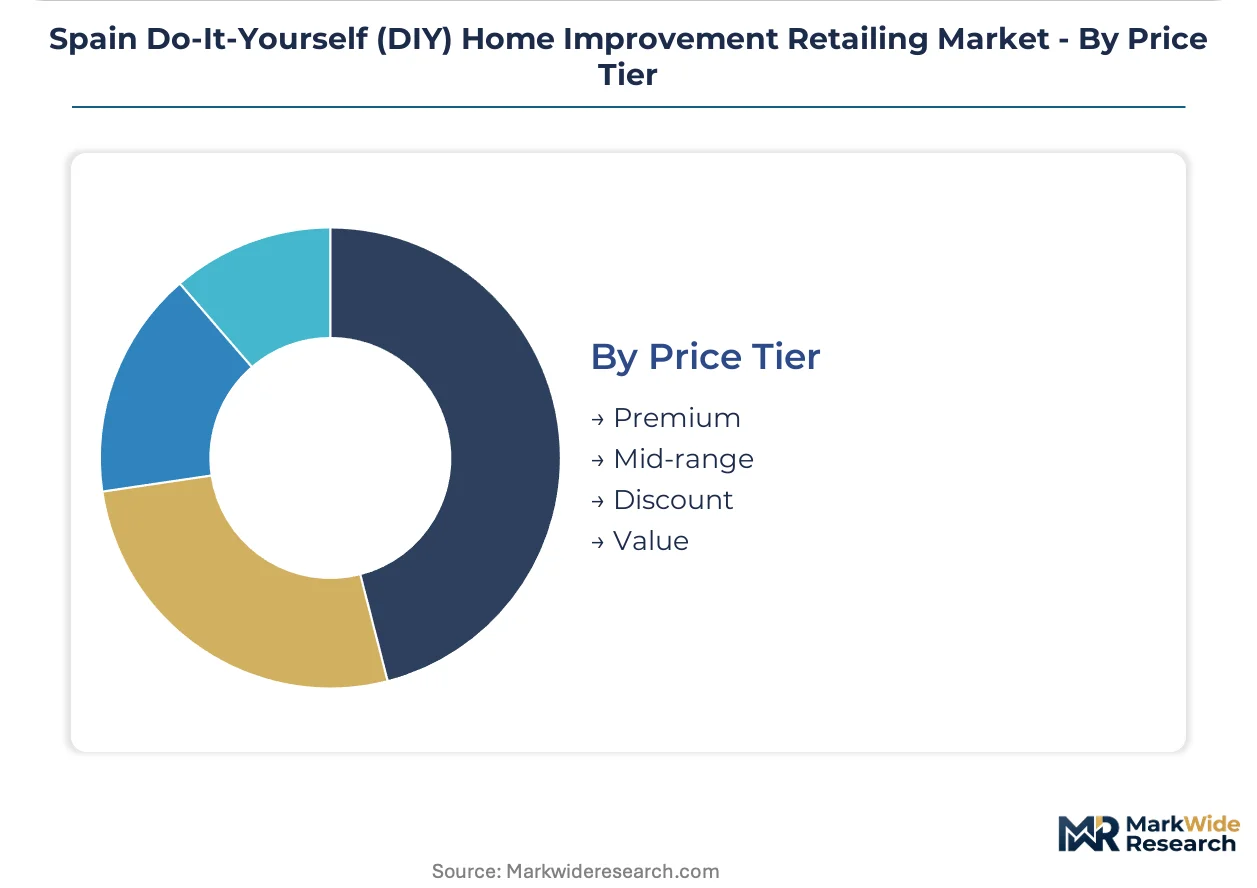
Price Tier:
Margin architecture stratifies across certification grade, performance specification, and brand provenance rather than simple quality ladders.
- Premium:German-origin technical assortments and professional-grade equipment command positioning among precision-oriented renovators in Catalonia and the Basque Country. Bauhaus sustains loyalty in this tier through engineering heritage and extended warranty terms.
- Mid-range:Balanced specification-to-price positioning captures the majority homeowner segment seeking durable solutions without specialist-grade features.
- Discount:Entry-level private-label penetration concentrates in high-frequency consumables where repeat purchase minimizes perceived risk.
- Value:Promotional and clearance stock rotation addresses price-sensitive segments during inventory transitions for EU ecodesign compliance deadlines.
Mid-range SKUs absorb volume concentration; premium positioning is gaining share fastest in connected home and automation categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catalonia commands premium pricing for German-origin technical assortments while Andalusia operates on compressed margins driven by high-volume coastal refurbishment cycles. This pricing-power asymmetry reflects divergent buyer sophistication, certification stringency, and proximity to industrial supply corridors across Spain's autonomous communities.
Madrid
Urban homeowners in the capital metropolitan zone drive transaction volume through room-scale renovation projects requiring design consultation. Spain's Ministry for the Ecological Transition enforces energy performance certificates that compel insulation upgrades before resale. The Madrid corridor concentrates demand for LED luminaires and smart home integration platforms as younger demographics treat automation as standard infrastructure.
Catalonia
Precision-oriented renovators in Barcelona sustain loyalty toward engineering-grade tools and technical assortments. Regional enforcement of EU Ecodesign Working Plan expansions accelerates inventory clearance timelines for non-compliant heating equipment. Basque Country-adjacent industrial heritage influences specification preferences, with German-origin retailers capturing premium positioning through extended warranty terms.
Basque Country
Higher disposable income and manufacturing legacy create demand for professional-grade lithium-ion platforms and certified electrical accessories. AENOR certification requirements for structural timber and electrical components delay product launches and tie working capital in compliance documentation. Bilbao and San Sebastián anchor this technical segment where precision drives specification over price.
Andalusia
Mediterranean coastal provinces exhibit accelerated renovation cycles as international owners modernize aging vacation properties in Alicante and Málaga. EU ecodesign rules phasing out halogen luminaires force stock rotation toward LED fixtures with integrated controls. The region's dependence on second-home refurbishment compresses margin pools as owners prioritize cost containment over premium specification.
Valencia
Younger demographics favor turnkey aesthetic coherence over functional replacement, concentrating demand in full-kitchen and bathroom solutions. Project-based purchasing displaces single-item transactions as homeowners approach renovation through comprehensive room overhauls. The metropolitan zone pressures retailers to offer design consultation and installation coordination services.
Spain Do-It-Yourself (DIY) Home Improvement Retailing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in category-specific niches. Spain's DIY retailing structure consolidates around big-box hypermarket networks that anchor geographic coverage through tactile evaluation and staff technical guidance. Three archetypes dominate: nationwide format operators with private-label depth, industrial-zone bulk suppliers targeting trade professionals, and technical-assortment specialists leveraging origin-brand heritage. Competitive intensity manifests through warehouse reconfiguration for bulky insulation materials and click-and-collect integration with in-store project consultation.
Within the nationwide format tier, Leroy Merlin anchors category management across power tools and garden equipment through its extensive big-box network. Bricomart occupies a position among industrial-zone operators, concentrating locations to capture trade professionals with bulk pricing structures. Bauhaus exemplifies the technical-assortment archetype, sustaining loyalty among precision-oriented renovators through German-origin engineering heritage and premium positioning in Catalonia and the Basque Country.
| Leading Market Players |
|---|
| Leroy Merlin |
| Bricomart |
| Bricor |
| Brico Depot |
| Bauhaus |
| Adeo Group |
| Kingfisher |
| Pinturas Andalucía |
| Hoffman Group |
| Others |
Pricing and Supply Chain Analysis
Nordic timber supply concentration determines both pricing tier spreads and supply chain shape across Spanish DIY retailing. Structural softwood imports from Sweden and Finland expose retailers to freight cost volatility and Baltic currency fluctuation, compressing margins on economy-grade lumber while premium certified grades absorb volatility through specification premiums.
Pricing Analysis
Configured-to-order pricing for certified electrical accessories and AENOR-tested structural timber commands spreads of 15-25 percent above standard SKUs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with contractor bulk procurement accessing tiered rebates unavailable to homeowner segments. Cost compression in economy paints and basic hand tools is intensifying because private-label penetration concentrates repeat-purchase categories. Trade professionals show lowest price sensitivity due to project-billing pass-through, while coastal second-home owners exhibit highest elasticity on decorative finishes.
Supply Chain Analysis
EU ecodesign restrictions on halogen luminaires and non-compliant heating equipment limit stock rotation flows into Spanish distribution. Germany, China, and Poland anchor supply for power tools, LED fixtures, and laminate flooring respectively. Raw material dependencies span lithium-ion cells, engineered wood substrates, and solvent-free pigment bases. Single-source vulnerability concentrates in Nordic structural timber, where mill capacity constraints create allocation risk during peak renovation seasons. Distribution runs through big-box hypermarket networks for tactile evaluation, with click-and-collect layering for urban convenience.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's DIY retailing market tracks a cyclical recovery pattern tied to EU recovery fund disbursement timelines for residential energy efficiency. Subsidy activation windows create demand surges that outpace inventory reconfiguration capacity.
For Market Incumbents: Insulate margin pools by deepening private-label penetration in paints and hand tools where repeat purchase minimizes brand switching. Secure AENOR certification pipelines for electrical accessories to preempt compliance delays that advantage German-origin competitors. Vertical integration into insulation material warehousing addresses bulky inventory reconfiguration costs threatening last-mile economics.
For New Entrants and Emerging Players: Build out digital-physical fusion capabilities targeting time-constrained Madrid and Barcelona professionals underserved by legacy big-box consultation models. Basque Country technical segments offer penetrable white space where precision-oriented renovators reward engineering-grade specification. Go-to-market leverage rests on smart home ecosystem bundling that compresses legacy electrical accessory margins.
For Investors and Strategic Acquirers: Spain's national transposition of EU Ecodesign Working Plan expansions reshapes the acquisition landscape toward compliance-capable distributors with certified product pipelines. Long-term viability favors platform integrators over component specialists as connected home systems render standalone categories obsolete. Target mid-cap retailers with AENOR testing relationships and industrial-zone logistics footprints. The signal to watch is regional enforcement acceleration in Navarre and Basque Country compressing clearance timelines for non-compliant stock.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pipeline Investment | AENOR pre-approval for electrical accessories accelerates product launch velocity against compliance-delayed imports. |
| Insulation Material Warehousing Expansion | Bulky thermal product handling capacity captures recovery fund subsidy flows into renovation spending. |
| Smart Home Ecosystem Partnership | Interoperability platform bundling displaces legacy electrical accessory margins in Barcelona and Madrid. |
| Industrial-Zone Bulk Pricing Structure | Contractor loyalty programs at Bricomart-type locations anchor highest-average-ticket trade segment. |
| Click-and-Collect Integration | Digital-physical channel fusion addresses time-constrained urban professional convenience requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with category managers at Leroy Merlin and Bricomart, procurement leads at Basque Country contractor firms, AENOR certification officers, and Madrid metropolitan homeowner focus groups. Secondary validation drew from Spain's Ministry for the Ecological Transition energy performance filings, EU Ecodesign Working Plan documentation, customs records for Nordic timber imports, and SEC disclosures from Adeo Group and Kingfisher. Bottom-up transaction modeling triangulated against top-down macroeconomic renovation spend projections.
Calibration against historical subsidy disbursement patterns and energy certificate issuance rates anchored volume assumptions across the projection horizon. Segmentation dimensions modeled include product type, customer archetype, distribution channel, and autonomous community regulatory cluster. CAGRs derived from regression analysis of renovation spend elasticity to GDP and housing transaction velocity. Industry-specific inputs encompass EU recovery fund allocation timelines and regional enforcement acceleration schedules for ecodesign compliance.
The forecast holds incumbent behavior within observed patterns; aggressive moves by German-origin technical specialists or platform-integrator new entrants would shift outcomes. Material shifts in EU timber tariff structures or Basque Country regional enforcement timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
DIY Home Improvement Products
Germany DIY Home Improvement Market
DIY Home Improvement Products
Japan Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Netherlands DIY Home Improvement Market
DIY Home Improvement Products
Sweden DIY Home Improvement Market
DIY Home Improvement Products
Asia-Pacific DIY Home Improvement Market
DIY Home Improvement Products
Saudi Arabia Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
France Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Do-It-Yourself (DIY) Home Improvement Retailing Market