
 Do-It-Yourself (DIY) Home Improvement Retailing Market | 2026-2036
Do-It-Yourself (DIY) Home Improvement Retailing Market Size, Share, and Industry Trends Forecast 2026-2036
Do-It-Yourself (DIY) Home Improvement Retailing Market Analysis
North American big-box retail capacity is decoupling from traditional lumberyard networks as fulfillment models shift toward omnichannel integration. The Home Depot leverages its Pro customer ecosystem to sustain contractor loyalty through dedicated inventory and credit programs. Lowe's Companies Inc anchors its position in suburban renovation markets with localized merchandising and installation service bundling. Kingfisher plc competes across European home improvement markets with format-adapted store concepts and private-label tool development.
Do-It-Yourself (DIY) Home Improvement Retailing encompasses the sale of tools, paint, lighting, flooring, and related materials to consumers and small contractors for self-executed residential renovation, repair, and maintenance projects, typically involving products with standardized dimensions, safety ratings, and installation compatibility. The category serves both functional property upkeep and aesthetic upgrade needs across single-family, multi-family, and rental housing stock. Tools and paint currently occupy the largest margin pools within product type segmentation, driven by repeat purchase frequency and private-label penetration. Online retail is expanding fastest among distribution channels as click-and-collect and same-day delivery reshape convenience expectations. DIY Enthusiasts represent a concentrated growth segment, exhibiting higher basket sizes and stronger engagement with workshop and consultancy service offerings.
EPA lead-safe certification requirements govern renovation product sales in pre-1978 housing markets, while CE marking under EU construction product regulations shapes import and private-label sourcing standards for European retailers. OSHA workplace safety standards additionally influence tool design specifications and retailer liability exposure for contractor-grade merchandise. Stakeholders must monitor how building code stringency and energy performance labeling evolve to anticipate inventory mix adjustments and supplier compliance investments.
Market Dynamics
Omnichannel fulfillment infrastructure is compressing traditional lumberyard networks as same-day delivery expectations reshape inventory placement and last-mile logistics for home improvement retailers.
Growth Catalysts
- Suburban Housing Turnover:First-time millennial homebuyers in United States exurban markets are accelerating tool and paint purchase frequency as renovation activity concentrates in single-family housing stock.
- EPA Lead-Safe Certification Mandate:Renovation product sales in pre-1978 housing markets require certified retailer inventory and trained contractor networks, creating compliance-driven demand for compliant merchandise.
- Private-Label Tool Development:Retailers are expanding margin capture through in-house design and direct sourcing of power tools and hand tools, bypassing traditional brand intermediaries.
Market Restraints
- Lumber Price Volatility:Structural wood product input costs fluctuate with Canadian softwood supply quotas and domestic mill capacity constraints, compressing gross margins on framing and decking categories.
- CE Marking Compliance Burden:European retailers face elevated testing and documentation costs for construction product regulations, slowing private-label expansion into power tool categories.
- Contractor-Grade Substitution:Professional tool rental services and equipment-sharing platforms are displacing ownership models among occasional-use DIY consumers in urban density markets.
Strategic Opportunities
- Installation Service Bundling:Flooring and lighting retailers can capture incremental revenue by embedding certified contractor networks into e-commerce checkout flows, converting product sales into project contracts.
- Energy Efficiency Retrofit Incentives:United States Inflation Reduction Act rebates for heat pump and insulation upgrades are creating demand pull for weatherization product categories and associated tool purchases.
- Augmented Reality Measurement Tools:Smartphone-based spatial computing applications are reducing return rates for dimensional products by enabling accurate pre-purchase visualization of paint colors and flooring layouts.
Industry Challenges
- Skilled Installer Scarcity:Certified trade labor shortages in electrical and plumbing specialties are extending project timelines and increasing customer service costs for retailers offering installation referrals.
- Legacy Inventory System Integration:Real-time stock visibility across warehouse, store, and delivery fleet requires capital-intensive ERP upgrades that strain mid-tier retailer technology budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Do-It-Yourself (DIY) Home Improvement Retailing Market |
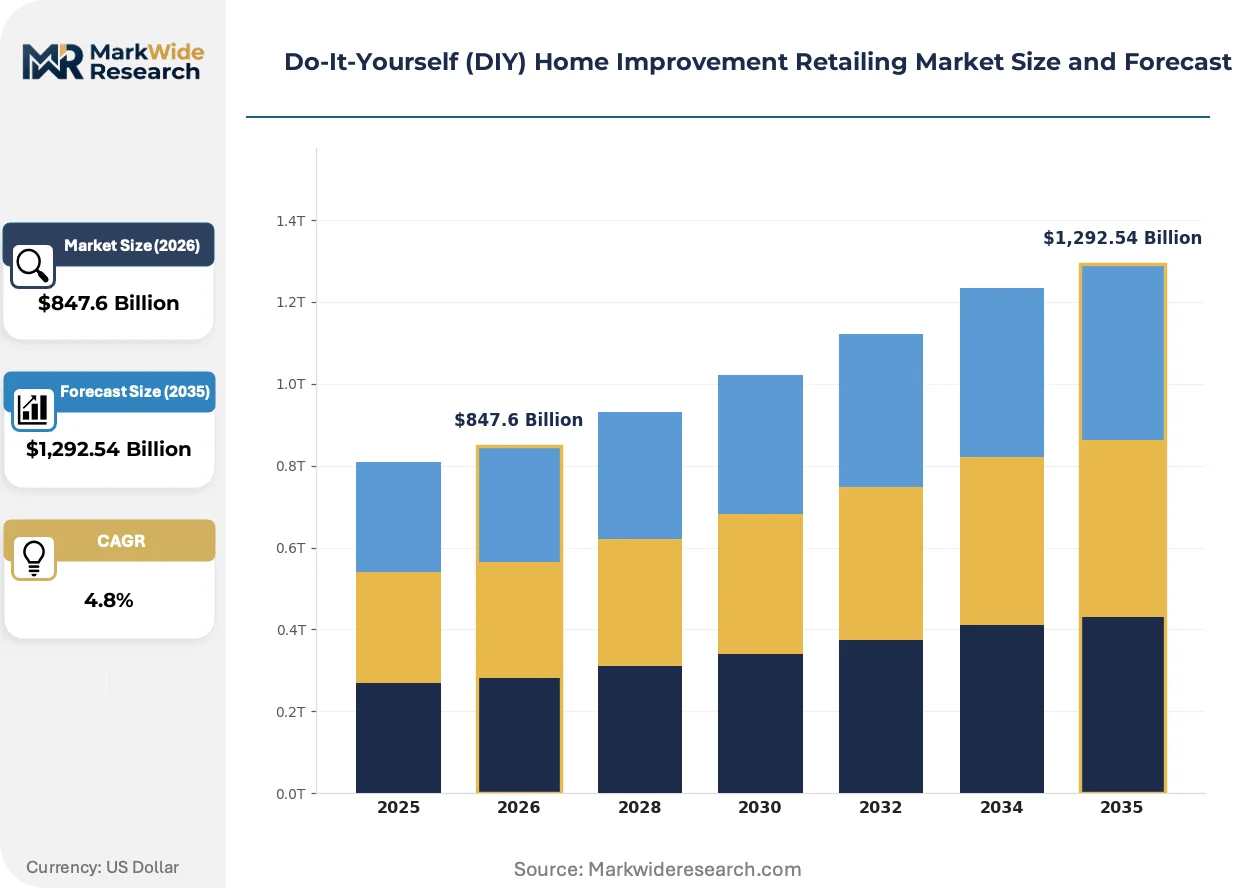
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $1,292.54 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tools, Paint, Lighting, Flooring Customer Type: Homeowners, Renters, Contractors, DIY Enthusiasts Distribution Channel: Online Retail, Brick-and-Mortar, Wholesale, Direct Sales Service Type: Installation Services, Consultancy, Delivery, Workshops |
| Companies Covered | The Home Depot, Lowe's Companies Inc, ADEO Group, Kingfisher plc, Menards Inc, Ace Hardware Corporation, Bunnings Warehouse, Travis Perkins plc, 84 Lumber Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Do-It-Yourself (DIY) Home Improvement Retailing Market Emerging Trajectories
Battery chemistry advances and connectivity modules are redefining tool functionality and retailer merchandising strategies across cordless power equipment categories.
Cordless lithium-ion power tools are electrifying jobsite mobility by eliminating generator dependency and cord management. Pro-sumers and small contractors in United States suburban markets are adopting 18V and 40V platforms at accelerated replacement cycles. This shift is compressing corded tool shelf space and forcing retailers to allocate floor space to battery ecosystem displays and charging station infrastructure.
OSHA silica dust exposure standards are mandating integrated vacuum systems and wet-cutting methods for concrete and masonry work. Tool manufacturers are embedding compliance features into grinder and drill designs to reduce employer liability. United States rental departments and pro-focused retailers are prioritizing compliant SKUs and training materials to avoid enforcement penalties.
Click-and-collect order consolidation is displacing traditional aisle browsing as the dominant pre-purchase behavior among time-constrained DIY consumers. Mobile app inventory accuracy and curbside pickup logistics are becoming primary competitive differentiators against pure-play e-commerce platforms. This pattern is most visible in United States metropolitan markets where same-day fulfillment expectations have normalized across big-box and specialty retailers.
Do-It-Yourself (DIY) Home Improvement Retailing Market Segmentation
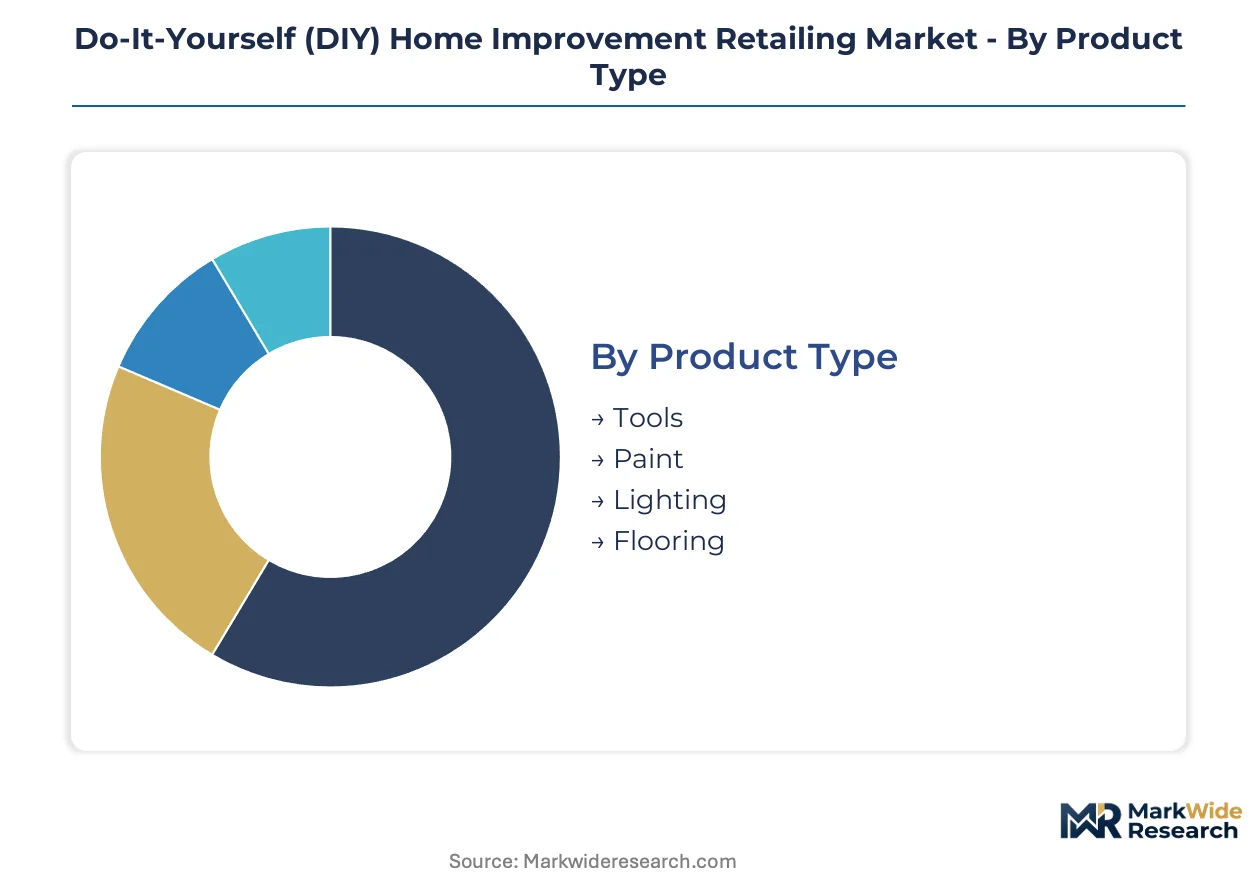
Segmentation in DIY home improvement retailing reveals how capital deployment, customer behavior, and fulfillment economics diverge across product and service categories. Retailers optimize inventory mix and margin capture by aligning shelf space and digital infrastructure with the distinct purchase patterns of each segment cluster.
Product Type:
Capital intensity varies sharply across product categories, with power tools and flooring requiring the heaviest inventory investment and specialized storage infrastructure.
- Tools:Cordless lithium-ion platforms dominate shelf allocation as battery ecosystem compatibility drives replacement cycles. United States suburban markets concentrate demand for 18V and 40V systems among pro-sumer homeowners tackling deck and fence projects. OSHA silica compliance features are now standard in grinder and rotary hammer SKUs.
- Paint:Water-based acrylic and zero-VOC formulations command premium positioning as EPA indoor air quality standards tighten. Millennial first-time buyers in exurban United States markets are accelerating purchase frequency for accent wall and cabinet refinishing projects. Tinting machine infrastructure represents significant fixed capital per store location.
- Lighting:LED retrofit kits and smart fixture bundles are displacing incandescent inventory in electrical aisles.
- Flooring:Luxury vinyl plank and engineered hardwood SKUs require climate-controlled warehousing and specialized delivery fleets.
Most installed capacity flows through Tools. Expansion is steepest in Paint.
Customer Type:
Revenue concentration and basket composition diverge dramatically across customer types, with contractors and DIY enthusiasts generating disproportionate margin contribution relative to transaction volume.
- Homeowners:Single-family property upkeep drives seasonal demand spikes for exterior paint and lawn equipment. United States suburban markets concentrate renovation spending among households aged 30-45 with recent mortgage originations. Credit program enrollment and project financing attachment rates exceed other customer types.
- DIY Enthusiasts:Workshop participation and tool rental subscriptions characterize this high-engagement segment with above-average basket sizes. United States metropolitan markets host the densest concentrations of maker-space affiliates and advanced project skill levels. Consultancy service uptake runs triple the rate of casual purchasers.
- Contractors:Pro-focused credit lines and dedicated inventory access sustain loyalty among small electrical and plumbing trades.
- Renters:Removable adhesive products and temporary lighting solutions dominate this price-sensitive, low-commitment segment.
Contractors anchor volume throughput. DIY Enthusiasts are climbing the fastest.
Distribution Channel:
Fulfillment infrastructure requirements scale unevenly across channels, with same-day delivery networks demanding the most capital-intensive last-mile investments.
- Online Retail:Click-and-collect and direct-to-door fulfillment are capturing share from traditional aisle browsing as inventory accuracy and curbside logistics improve. United States metropolitan markets normalize same-day expectations for paint and small tools. Mobile app engagement metrics now drive merchandising algorithm development.
- Brick-and-Mortar:Showroom experiences for flooring and lighting retain importance where tactile evaluation influences purchase decisions. United States exurban locations concentrate foot traffic among first-time millennial buyers seeking project guidance. In-store workshop programming builds repeat visitation patterns.
- Wholesale:Bulk framing lumber and drywall supply to small builders operates on thin margins with high inventory turns.
- Direct Sales:Manufacturer-owned channels for premium power tools bypass retailer markups in contractor segments.
Brick-and-Mortar holds the largest physical footprint. Online Retail is gaining share fastest.
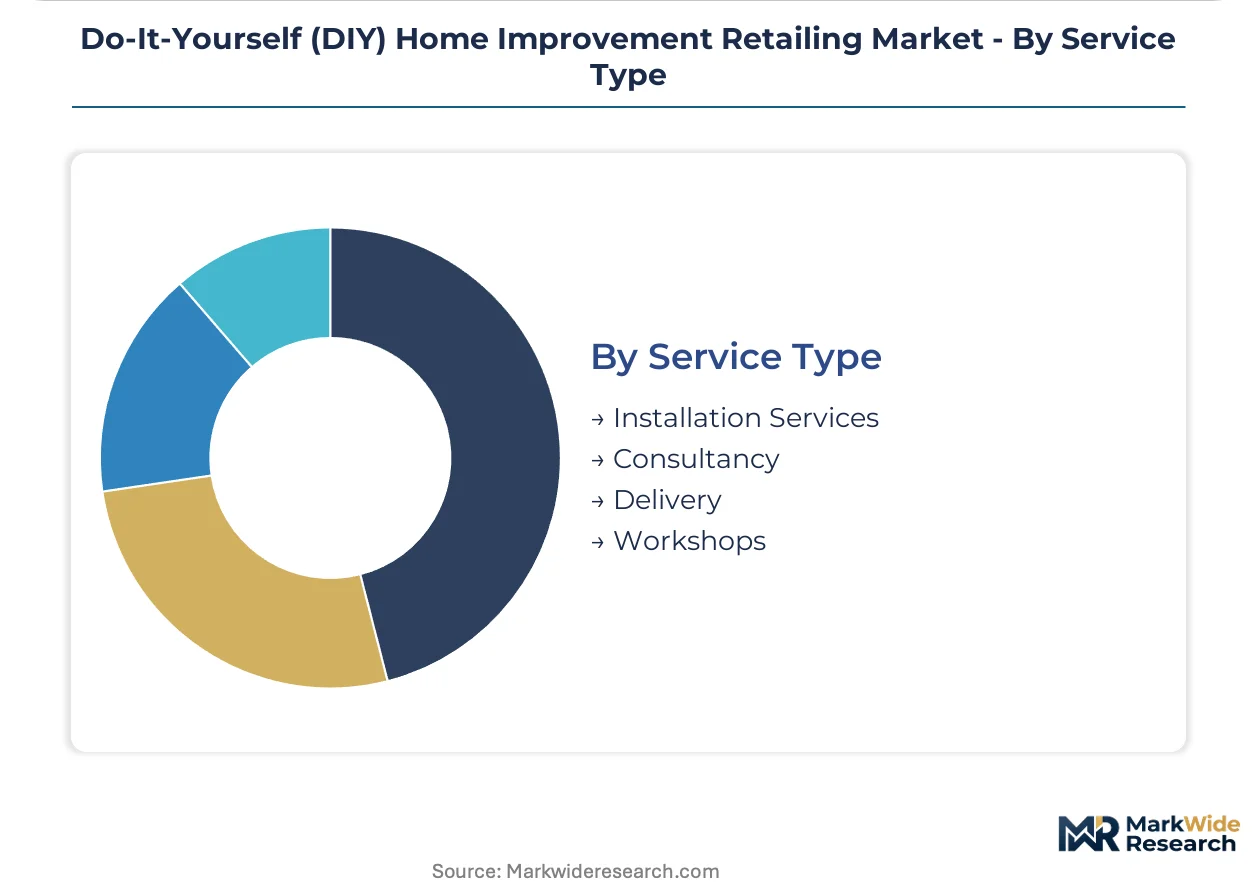
Service Type:
Margin accretion potential and labor coordination complexity separate service categories, with installation networks requiring the most sophisticated contractor relationship management.
- Installation Services:Certified contractor embedding at e-commerce checkout converts product sales into project contracts with substantially higher revenue per transaction. United States markets face skilled installer scarcity in electrical and plumbing specialties that extends timelines and elevates customer service costs. Retailers are building captive referral networks to capture this margin pool.
- Workshops:In-store skill-building sessions drive tool category attachment and build loyalty among novice DIY participants. United States suburban locations report highest enrollment for power tool safety and tile installation basics. Content libraries from these sessions feed digital marketing pipelines.
- Consultancy:Virtual and in-person project planning assistance reduces return rates for dimensional products.
- Delivery:Same-day and scheduled white-glove options for appliances and bulky materials complete the fulfillment stack.
Installation Services carries the highest revenue per project. Workshops show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States suburban renovation spending outpaces Canadian per-capita tool purchases, while European markets concentrate demand in format-adapted retail networks rather than big-box formats.
United States
Millennial first-time homebuyers in exurban markets accelerate paint and power tool replacement cycles as housing turnover concentrates in single-family stock. EPA lead-safe certification mandates govern renovation product sales in pre-1978 housing markets, requiring retailer inventory compliance and trained contractor networks. Dallas-Fort Worth and Atlanta metropolitan clusters anchor Pro customer ecosystems through dedicated credit programs and same-day fulfillment infrastructure.
Germany
Energy efficiency retrofit incentives drive heat pump and insulation upgrade demand among owner-occupied housing stock. CE marking under EU construction product regulations shapes import standards and private-label sourcing requirements for power tool categories. The Rhine-Ruhr industrial corridor concentrates specialized retail formats serving dense urban renovation markets with localized contractor service bundling.
United Kingdom
Suburban property improvement projects sustain demand for lighting and flooring categories among aging housing stock. Building regulations under the UK Building Safety Regulator influence fire-rated product certification and retailer liability exposure. Greater Manchester and West Midlands metropolitan areas host dense concentrations of click-and-collect fulfillment nodes competing with London's showroom-centric retail footprint.
France
Private-label tool development accelerates margin capture as retailers bypass traditional brand intermediaries in cordless power equipment. REACH chemical regulations and EU Green Deal targets reshape paint formulation standards and zero-VOC product positioning. The Île-de-France region anchors national distribution networks while Lyon and Marseille clusters drive regional format adaptation for urban density markets.
Canada
Canadian softwood supply quotas and domestic mill capacity constraints compress gross margins on structural wood products for framing and decking categories. Health Canada and PMRA govern treated lumber and wood preservative standards affecting outdoor renovation merchandise. Toronto and Vancouver metropolitan markets concentrate omnichannel fulfillment investments as same-day delivery expectations normalize across suburban renovation corridors.
Do-It-Yourself (DIY) Home Improvement Retailing Market Vendor Landscape
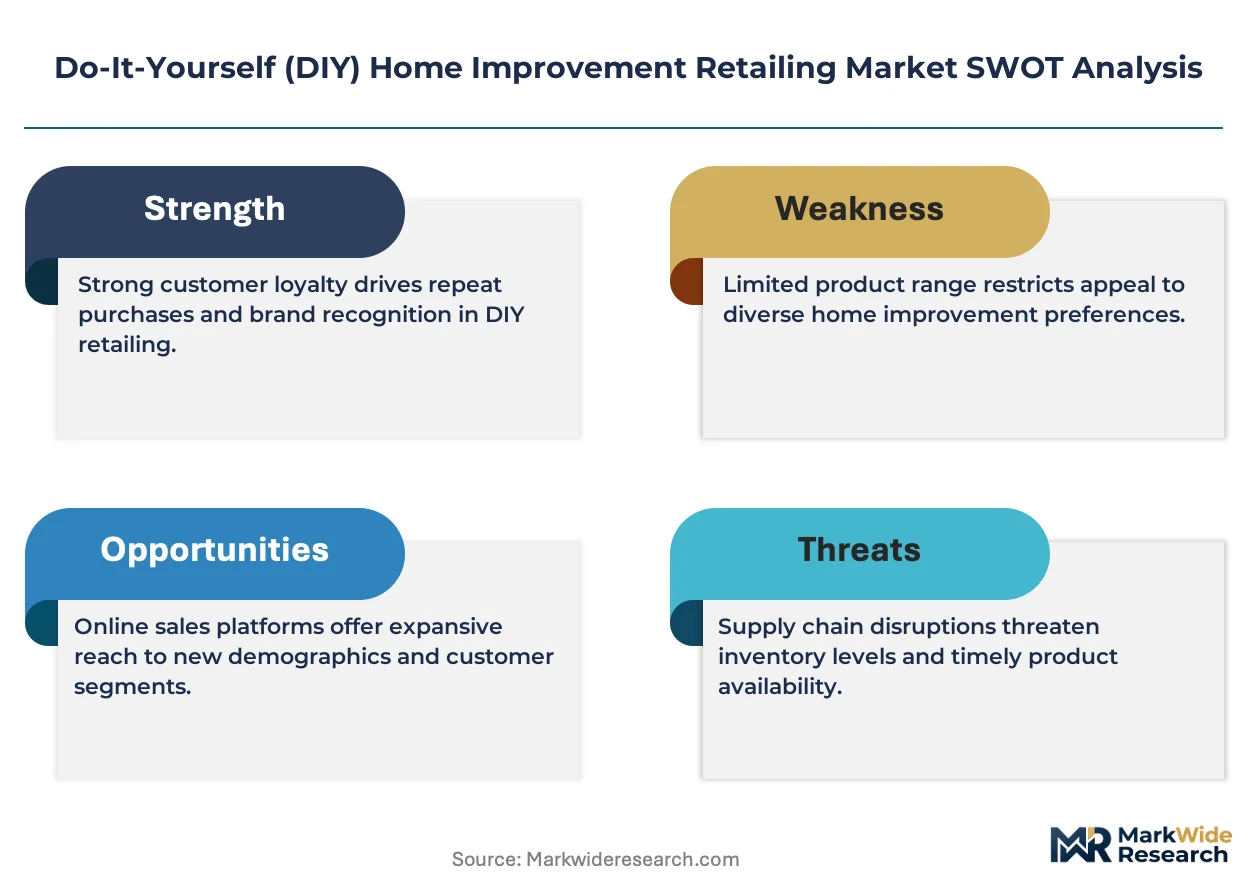
United States big-box chains anchor one tier; European format-adapted specialists hold differentiated positions through private-label development. The vendor base concentrates around consolidated national networks with regional specialists capturing residual share in contractor-grade segments. Two strategic archetypes dominate: scale-driven omnichannel platforms and service-integrated specialty retailers. Competitive moves center on installation service bundling and battery ecosystem lock-in through proprietary cordless platforms.
Among North American big-box operators, The Home Depot and Lowe's Companies Inc exemplify scale-driven omnichannel archetypes with Pro customer ecosystems and fulfillment infrastructure. Kingfisher plc occupies a position representing European format adaptation through market-specific store concepts and private-label tool development. These three entities anchor competitive positioning across their respective geographies without overlapping operational footprints.
| Leading Market Players |
|---|
| The Home Depot |
| Lowe's Companies Inc |
| ADEO Group |
| Kingfisher plc |
| Menards Inc |
| Ace Hardware Corporation |
| Bunnings Warehouse |
| Travis Perkins plc |
| 84 Lumber Company |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap retailers in Germany and France anchor supply discipline through multi-generational supplier relationships that buffer price volatility in cordless power tool categories. Their ownership structure enables patient capital allocation toward private-label development, insulating margin pools from branded manufacturer pricing power while compressing working capital cycles.
Pricing Analysis
Capacity additions in China are reshaping price floors for lithium-ion battery packs and brushless motor assemblies, forcing incumbent brands to reposition 18V and 40V platforms. Three-tier pricing structure across premium pro-grade, standard DIY, and economy entry-level segments stratifies by battery ecosystem compatibility and OSHA silica compliance certification. Pricing pressure stems from direct-to-consumer entrants bypassing traditional retail markups. Renters and occasional-use homeowners exhibit highest price sensitivity; pro-sumer contractors show lowest, prioritizing warranty terms and service network density.
Supply Chain Analysis
Returns of defective power tools and paint tinting errors flow through dedicated refurbishment centers in Poland and Mexico, recovering margin from quality failures. Manufacturing concentrates in China for cordless platforms, Vietnam for hand tool forging, and Germany for precision components. Raw material dependencies span rare earth elements for magnet motors, petrochemical feedstocks for plastic housings, and titanium dioxide for paint formulations. Single-source vulnerability runs through Chinese battery cell production. Distribution runs through regional distribution centers serving click-and-collect nodes and last-mile delivery fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DIY home improvement retailing has entered a late-cycle quality phase where millennial first-time buyers prioritize zero-VOC paint certifications and OSHA-compliant tool features over price minimization, rewarding retailers with differentiated private-label positioning.
For Market Incumbents: Deploy installation service bundling as the primary defensive lever. Embed certified contractor networks at e-commerce checkout to capture project-contract margins threatened by pure-play service marketplaces. Accelerate backward integration into cordless battery platform development to reduce dependence on branded manufacturer pricing power and lock in pro-sumer replacement cycles. For New Entrants and Emerging Players: Augmented reality visualization tools offer the most penetrable white-space entry point. Target United States metropolitan markets where smartphone-based spatial computing reduces return rates for dimensional products like flooring and lighting. Launch through direct-to-consumer channels with virtual project planning assistance to bypass big-box shelf space barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialty retailers with underutilized private-label infrastructure. Five-to-ten year viability hinges on energy efficiency retrofit positioning as IRA incentives reshape demand. Monitor EPA lead-safe certification training completion rates among retailer contractor networks as an inflection signal for compliance-driven market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Private-Label Tool Development | Bypasses branded manufacturer markups while capturing margin from lithium-ion battery ecosystem lock-in. |
| Installation Service Bundling | Converts product sales into project contracts, capturing revenue pools threatened by service marketplaces. |
| Augmented Reality Deployment | Reduces return rates for dimensional products through smartphone-based spatial computing visualization. |
| Energy Efficiency Positioning | Aligns inventory mix with IRA rebate flows for heat pump and weatherization upgrade demand. |
| Omnichannel Fulfillment Investment | Same-day delivery infrastructure defends against pure-play e-commerce platforms in metropolitan markets. |
Methodological Framework
Coverage spans United States, Germany, United Kingdom, France, and Canada, with primary inputs from each market's retail operations executives, category buyers, contractor network managers, and supply chain directors. Secondary validation draws from EPA enforcement data, EU construction product regulation filings, customs trade records, and SEC retail sector disclosures. Bottom-up store-level revenue modeling triangulates against top-down national renovation spending estimates.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions include product type, customer archetype, distribution channel, and service attachment level. CAGRs derive from housing turnover velocity, tool replacement cycle compression, and online penetration trajectory. Forecast inputs incorporate battery chemistry adoption curves and energy efficiency incentive program enrollment.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for cordless platform replacement cycles. Forecasts embed assumptions regarding regulatory enforcement intensity and lumber supply quota stability. Practitioners should monitor EPA lead-safe certification audit results and IRA rebate program utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
DIY Home Improvement Products
Sweden DIY Home Improvement Market
DIY Home Improvement Products
Germany DIY Home Improvement Market
DIY Home Improvement Products
France Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Asia-Pacific DIY Home Improvement Market
DIY Home Improvement Products
Netherlands DIY Home Improvement Market
DIY Home Improvement Products
Japan Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Spain Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Saudi Arabia Do-It-Yourself (DIY) Home Improvement Retailing Market