
 Sweden DIY Home Improvement Market | 2026-2036
Sweden DIY Home Improvement Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden DIY Home Improvement Market Analytics
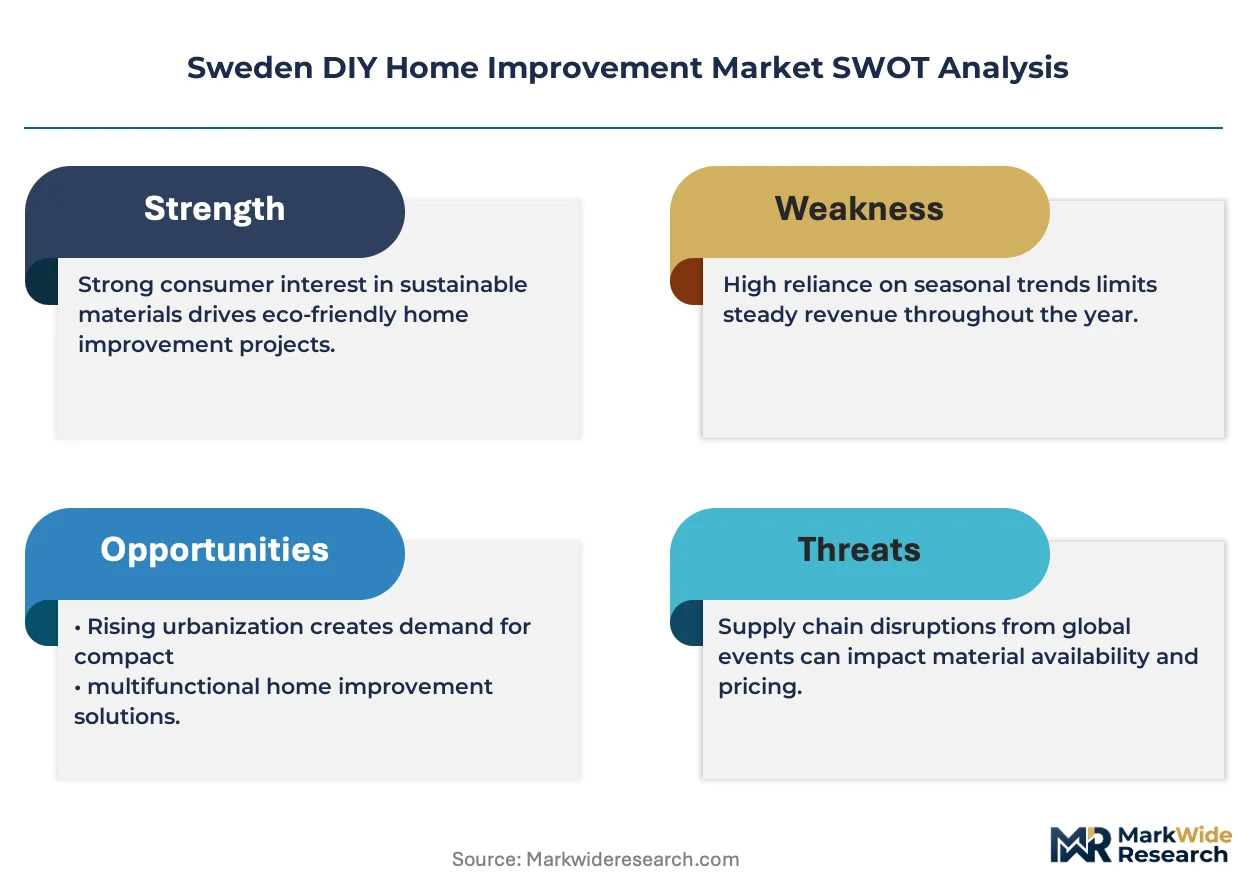
Professional installation services revenue is fragmenting across self-directed tool purchases and modular system kits. Byggmax Group leverages its out-of-town warehouse format to sustain low-cost lumber volumes in secondary Swedish cities. Jula Holding competes through private-label tool specialization that anchors its position among price-sensitive rural DIYers. Clas Ohlson differentiates via compact urban store footprints and digital integration that controls Stockholm's convenience-oriented segment.
DIY home improvement encompasses self-executed residential modification using handheld power tools, water-based acrylic coatings, pressure-treated softwood lumber, and click-lock engineered flooring systems to alter dwelling function, efficiency, or aesthetics without contracted labor. The Swedish market structures around four product pillars: tools capture repeat purchase frequency from enthusiast segments; paint and lumber dominate project value; flooring commands premium positioning through moisture-resistant laminates suited to Nordic climate conditions. Customer segmentation reveals homeowners as the stable volume base while DIY enthusiasts generate higher per-visit basket values through specialized tool acquisitions. Distribution channels show online retail gaining transaction share for standardized repeat purchases, whereas brick-and-mortar stores retain project-planning missions where tactile material assessment drives conversion.
Boverket's building regulations mandate energy performance certificates that shape demand toward insulation-grade lumber and low-VOC paint formulations. The Swedish Chemicals Agency (Kemi) enforces REACH-aligned restrictions on solvent content that filter available product assortments. The EU Green Deal's embodied carbon tracking requirements are extending upstream to pressure-treated wood sourcing disclosures. Stakeholders must monitor how forthcoming circular economy reporting obligations under CSRD reshape supplier qualification criteria and private-label sourcing strategies.
Market Dynamics
Sweden's DIY home improvement sector is restructuring around Boverket's tightening energy performance mandates that force systematic insulation retrofits across Stockholm's aging multifamily housing stock. Professional labor shortages are accelerating self-directed renovation adoption as homeowners absorb installation tasks previously outsourced to contractors.
Growth Catalysts
- Boverket Energy Code Enforcement:Mandatory energy performance certificates for residential sales trigger insulation-grade lumber and low-VOC coating demand across metropolitan renovation projects.
- Stockholm Housing Stock Age:Systematic multifamily unit upgrades in Sweden's capital concentrate project volume and sustain tool replacement cycles among owner-occupiers.
- REACH-Aligned Chemical Restrictions:Kemi's solvent-content limits filter product assortments toward water-based acrylic formulations that DIYers favor for indoor air quality compliance.
Market Restraints
- Nordic Softwood Supply Concentration:Pressure-treated lumber sourcing depends on concentrated Swedish and Finnish sawmill capacity, exposing project timelines to regional weather disruptions.
- CSRD Upstream Disclosure Requirements:EU circular economy reporting obligations reshape supplier qualification criteria and complicate private-label sourcing strategies for mid-scale retailers.
- Professional Skill Substitution Limits:Electrical and plumbing code compliance barriers prevent DIY penetration into high-value renovation segments regardless of tool accessibility.
Strategic Opportunities
- Secondary City Warehouse Expansion:Out-of-town retail formats in Gothenburg, Malmö, and Uppsala capture underserved rural DIYers with bulk lumber volumes and parking accessibility.
- Digital-Physical Integration:Click-and-collect services for standardized repeat purchases merge online transaction efficiency with tactile material assessment for project-planning missions.
- EU Green Deal Carbon Tracking:Embodied carbon disclosure mandates create first-mover advantage for retailers with verified pressure-treated wood chain-of-custody documentation.
Industry Challenges
- Retrofit Technical Assessment Gaps:Homeowners lack standardized protocols for evaluating existing insulation performance, causing project scope uncertainty and material waste.
- Modular System Integration Complexity:Click-lock engineered flooring and prefabricated wall systems require precision subfloor preparation that exceeds amateur skill thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden DIY Home Improvement Market |
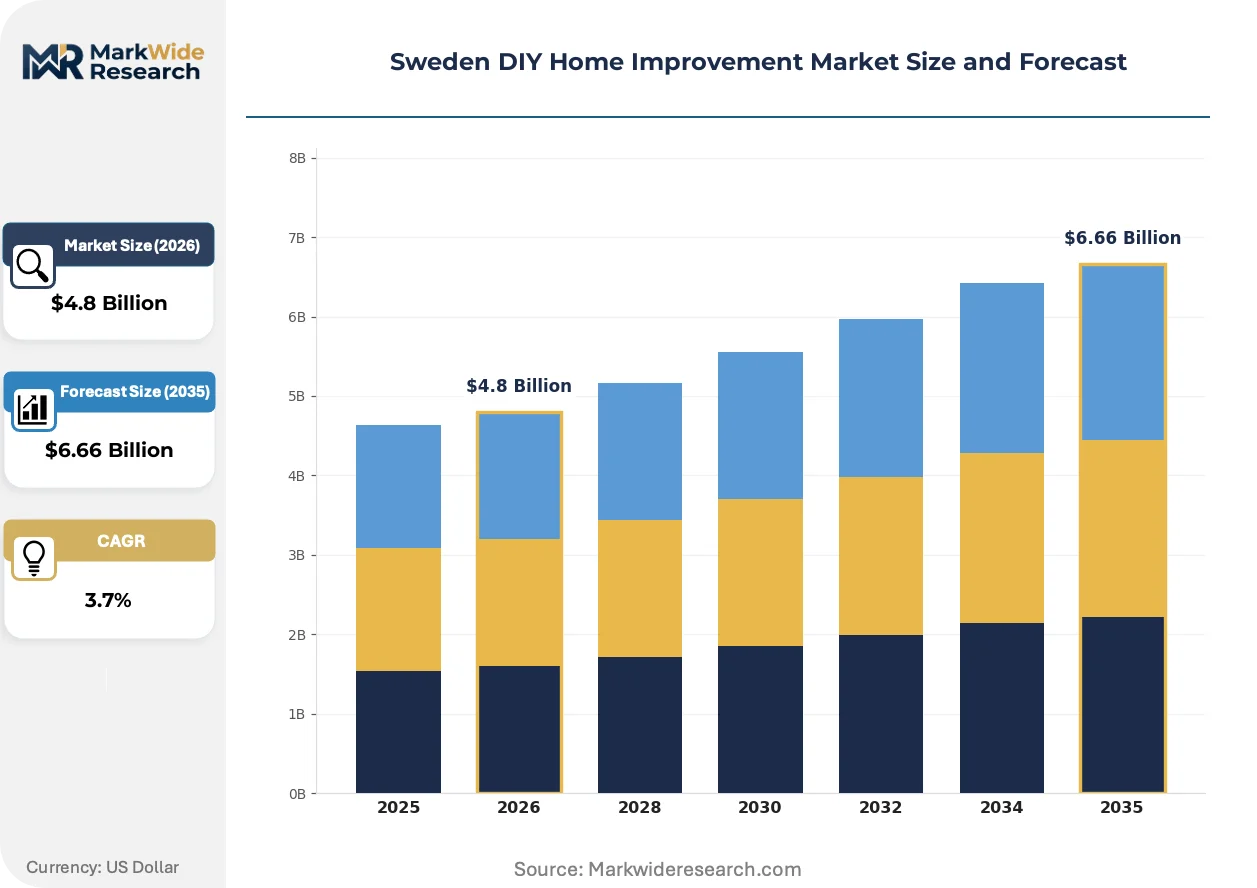
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tools, Paint, Lumber, Flooring Customer Type: Homeowners, Renters, Contractors, DIY Enthusiasts Distribution Channel: Online Retail, Brick-and-Mortar Stores, Wholesalers, Marketplaces End Use: Interior Remodeling, Exterior Renovation, Garden Enhancement, Maintenance |
| Companies Covered | Hornbach Sverige, Jula Holding, Bauhaus Sverige, IKEA Group, Rusta, Byggmax Group, Beijer Byggmaterial, K-Rauta, Clas Ohlson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden DIY Home Improvement Market Evolving Landscape
Swedish DIY retail is converging around three force lines: cordless power tool battery platform consolidation, regulatory chemical reformulation mandates, and channel fragmentation between project-planning physical missions and transactional digital efficiency.
Brushless motor lithium-ion platforms are rendering obsolete corded tool dependence in Swedish residential renovation. Enthusiast segments adopt Milwaukee M18 and DeWalt 20V Max ecosystems for sustained torque delivery. Corded circular saw and drill inventory is compressing at Byggmax and Jula as battery interchangeability becomes the decisive purchase criterion.
EU Green Deal embodied carbon tracking requirements extend upstream to pressure-treated wood sourcing disclosures. Swedish retailers must document chain-of-custody from Baltic and Nordic sawmills through treatment facilities. Flooring and lumber categories face the steepest compliance reconfiguration as CSRD reporting obligations phase in across supplier tiers.
Stockholm metropolitan homeowners now separate project-planning missions from transactional replenishment. Tactile material assessment drives brick-and-mortar conversion for paint and flooring selections. Standardized repeat purchases of fasteners, sandpaper, and consumables migrate to mobile-optimized digital channels with next-day locker collection.
Sweden DIY Home Improvement Market Segmentation
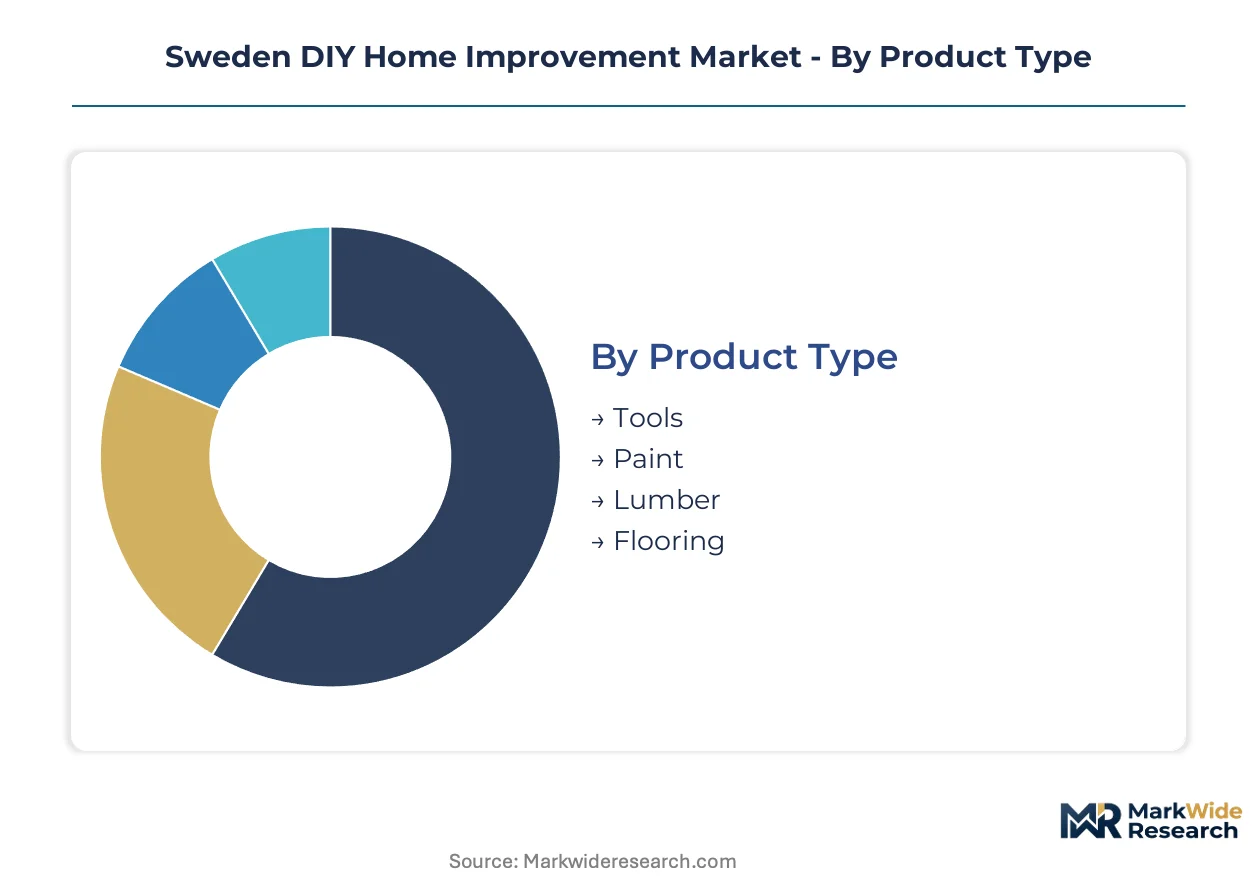
Swedish DIY home improvement segments reflect divergent maturity profiles across product categories and customer bases. Understanding where established demand concentrates versus where emerging behaviors reshape purchasing patterns enables precise resource allocation for retailers navigating Boverket regulatory pressures and channel fragmentation.
Product Type:
Mature categories dominate transaction volume while emerging segments capture renovation-driven project value expansion.
- Tools:Cordless lithium-ion platforms with brushless motor technology deliver sustained torque for repetitive residential tasks. Stockholm's metropolitan homeowners drive replacement cycles as battery interchangeability becomes the decisive purchase criterion amid professional labor shortages.
- Paint:Water-based acrylic formulations with low-VOC compliance anchor interior project specifications under Kemi's REACH-aligned restrictions. Aging multifamily units in Sweden's capital concentrate demand for coating systems that satisfy indoor air quality mandates during systematic energy retrofits.
- Lumber:Pressure-treated softwood grades meeting Boverket insulation standards supply structural and thermal upgrade projects.
- Flooring:Moisture-resistant click-lock engineered laminates suited to Nordic climate conditions command premium positioning in renovation baskets.
Paint handles the majority of throughput in project value terms; flooring is expanding most quickly as moisture-resistant technology penetrates Stockholm's upgrade cycle.
Customer Type:
Volume concentration sits with stable repeat purchasers while specialized acquisition patterns concentrate among technically engaged segments.
- Homeowners:Owner-occupiers of aging Stockholm multifamily stock execute systematic insulation retrofits triggered by mandatory energy performance certificates. This segment sustains baseline tool replacement and bulk material purchasing across project planning missions at brick-and-mortar locations.
- DIY Enthusiasts:Technically proficient self-directed renovators generate elevated per-visit basket values through specialized cordless platform acquisitions and precision tool investments. Enthusiast demand clusters in metropolitan corridors where digital-physical integration supports complex project planning.
- Contractors:Small-scale professional installers purchasing through wholesale channels for client renovation projects.
- Renters:Limited-scope modification participants constrained by lease terms and temporary occupancy horizons.
Homeowners anchor absolute volume throughput; DIY enthusiasts are climbing the fastest on per-transaction value contribution.
Distribution Channel:
Channel configuration separates tactile-dependent project planning from standardized replenishment efficiency.
- Brick-and-Mortar Stores:Physical retail formats enable material assessment for paint color matching, flooring texture evaluation, and lumber grade verification. Byggmax's out-of-town warehouse positioning and Clas Ohlson's compact urban footprints compete for project-planning missions through differentiated accessibility models.
- Online Retail:Mobile-optimized platforms with next-day locker collection capture standardized repeat purchases of fasteners, sandpaper, and consumables. Digital efficiency concentrates among Stockholm homeowners executing maintenance replenishment between major renovation cycles.
- Wholesalers:Volume-oriented supply relationships serving contractor and small professional installer procurement.
- Marketplaces:Third-party platforms aggregating specialized tool and discontinued product availability for enthusiast segments.
Brick-and-mortar handles the majority of project-planning throughput; online retail is gaining share fastest in standardized consumables.
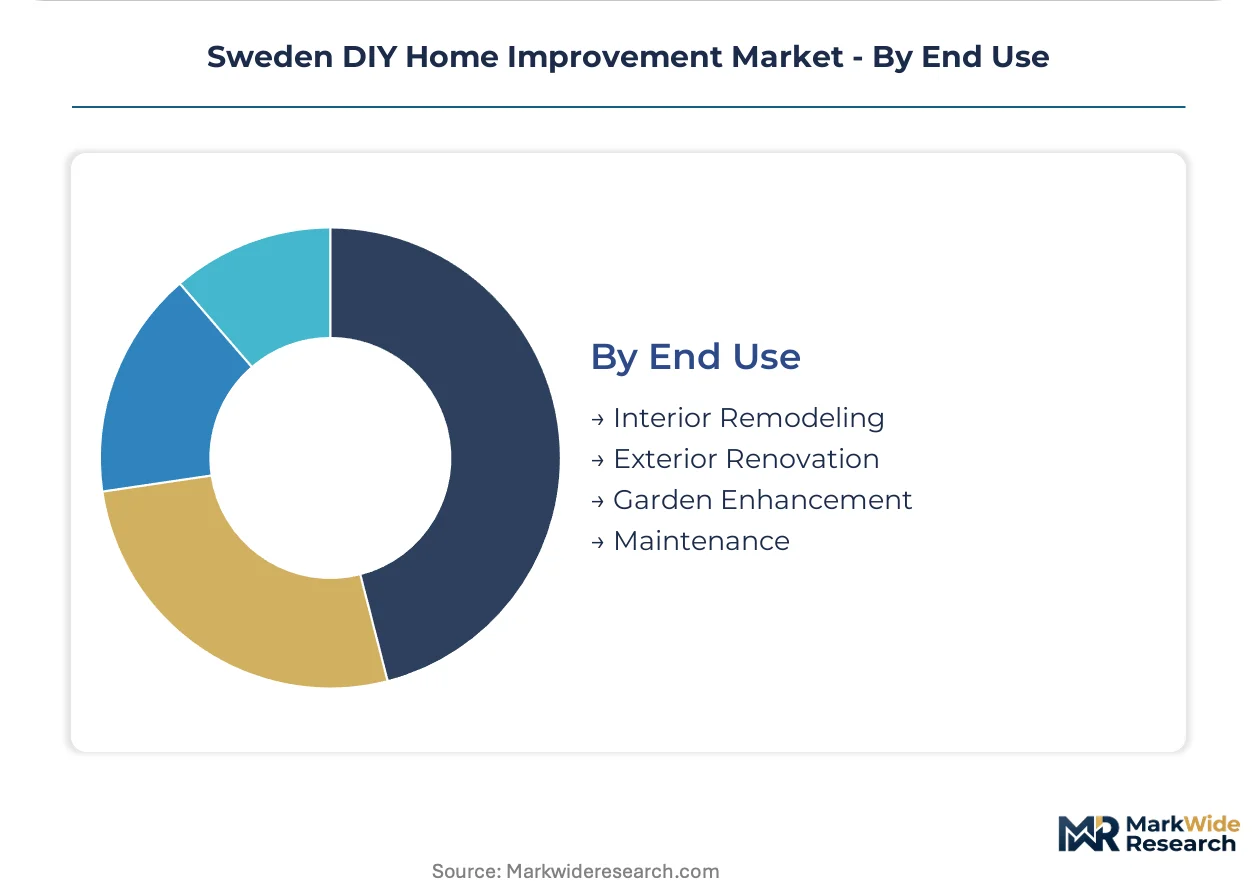
End Use:
Application segmentation tracks regulatory pressure concentration versus discretionary enhancement demand.
- Interior Remodeling:Systematic multifamily unit upgrades encompassing insulation retrofit, flooring replacement, and coating renewal dominate project value. Boverket energy code enforcement channels demand toward thermally efficient materials and low-emission finishes across Stockholm's aging housing stock.
- Exterior Renovation:Façade insulation, cladding replacement, and weatherproofing projects respond to tightening building envelope standards. Pressure-treated lumber sourcing disclosures under EU Green Deal requirements reshape material specification protocols for exterior applications.
- Garden Enhancement:Outdoor living space modifications including decking, fencing, and landscape construction.
- Maintenance:Routine repair and preservation activities sustaining dwelling condition without structural modification.
Interior remodeling handles the majority of project value throughput; exterior renovation is advancing fastest on regulatory compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish DIY consumption patterns diverge sharply from neighboring Nordic markets through Boverket-driven energy retrofit intensity rather than new-build expansion. Stockholm's aging multifamily concentration creates project-planning missions distinct from Denmark's single-family renovation culture or Norway's cabin-focused seasonal demand.
Stockholm Metropolitan Area
Systematic insulation upgrades across 1960s-era multifamily housing stock concentrate project value in pressure-treated lumber and low-VOC coating systems. Boverket energy performance certificates trigger mandatory pre-sale renovations that sustain tool replacement cycles among owner-occupiers. Stockholm's compact urban fabric favors Clas Ohlson's convenience-oriented store footprints and click-and-collect integration for standardized consumables.
Gothenburg and Western Sweden
Industrial heritage housing in Sweden's second city drives exterior façade renovation demand alongside interior energy retrofits. The Swedish Chemicals Agency enforces REACH-aligned solvent restrictions that filter paint assortments toward water-based acrylic formulations. Gothenburg's port proximity anchors pressure-treated lumber distribution from Baltic sawmills serving western regional project timelines.
Malmö and Southern Sweden
Cross-border price sensitivity from Copenhagen proximity shapes competitive dynamics in Skåne County's DIY retail landscape. EU Green Deal embodied carbon tracking requirements extend to Swedish pressure-treated wood sourcing disclosures that complicate private-label qualification. Malmö's densifying housing stock concentrates demand for moisture-resistant click-lock flooring suited to Nordic climate conditions.
Uppsala and Mälardalen Corridor
University city demographics blend student rental modifications with established homeowner renovation cycles in Sweden's fastest-growing regional economy. Kemi's chemical restrictions on VOC content filter interior coating specifications across Uppsala's mixed housing tenure patterns. The Mälardalen logistics corridor enables Byggmax's out-of-town warehouse format to capture bulk lumber volumes with parking accessibility.
Norrland and Northern Sweden
Remote geography and dispersed population patterns concentrate DIY demand in seasonal bulk purchasing from out-of-town retail formats. Boverket building codes apply uniformly but enforcement capacity varies across northern municipalities with limited inspection resources. Umeå and Luleå anchor regional tool replacement cycles while rural DIYers favor Jula Holding's private-label price positioning.
Sweden DIY Home Improvement Market Competitive Landscape
Capability concentration sits with specialist retailers commanding project-planning missions; scale advantage sits with diversified groups leveraging cross-category purchasing power. The Swedish DIY sector structures around three archetypes: out-of-town warehouse operators capturing bulk lumber volumes, compact urban format specialists controlling convenience-oriented segments, and diversified generalists spanning home improvement with adjacent categories. Competitive moves center on digital-physical integration investments and private-label expansion to defend margin position against price-transparent online channels.
Within the out-of-town warehouse tier, Byggmax Group and Bauhaus Sverige exemplify format specialization through bulk lumber accessibility and parking-optimized locations. Jula Holding occupies a position among price-sensitive rural segments through private-label tool concentration. Clas Ohlson anchors the compact urban specialist archetype with Stockholm-centric convenience positioning. Hornbach Sverige and Beijer Byggmaterial sit within the professional-adjacent tier serving small-scale installers alongside committed DIY enthusiasts. IKEA Group represents the diversified generalist model integrating home improvement with interior furnishings across overlapping customer missions.
| Leading Market Players |
|---|
| Hornbach Sverige |
| Jula Holding |
| Bauhaus Sverige |
| IKEA Group |
| Rusta |
| Byggmax Group |
| Beijer Byggmaterial |
| K-Rauta |
| Clas Ohlson |
| Others |
Value Network & Pricing Analysis
Baltic sawmill supply concentration determines both lumber pricing tier spreads and inventory positioning strategies across Swedish retail formats. Kemi's REACH-aligned solvent restrictions on paint formulations compress margin structures for water-based acrylic coatings while forcing private-label reformulation investments.
Pricing Analysis
Long-term offtake contracts with Nordic and Finnish sawmills anchor bulk lumber pricing for out-of-town warehouse operators, while spot market exposure concentrates in seasonal project-based purchasing for smaller retailers. Price differentiation separates moisture-resistant click-lock flooring grades from standard laminates, with certification tier premiums widening as Boverket energy code enforcement intensifies. Cost compression in mid-grade paint runs through raw material substitution toward bio-based acrylic resins. Rural DIYers exhibit highest price sensitivity, driving Jula Holding's private-label tool concentration, whereas Stockholm metropolitan homeowners prioritize convenience premiums over absolute cost minimization.
Supply Chain Analysis
Contract manufacturing concentration in Swedish and Finnish sawmill networks controls pressure-treated lumber capacity feeding the Nordic renovation market. Geographic supply concentration centers on Baltic states, Poland, and domestic Swedish forestry for softwood feedstock. Raw material dependencies encompass spruce and pine timber grades, copper-based wood preservatives, and titanium dioxide pigment stocks for coating formulations. Single-source vulnerability persists in brushless motor lithium-ion cell supply from East Asian battery manufacturers. Distribution runs through out-of-town warehouse formats for bulk lumber volumes and compact urban footprints for project-planning consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sweden's DIY home improvement market represents an early-cycle expansion story as Boverket energy retrofit mandates penetrate secondary cities beyond Stockholm's saturated upgrade cycle.
For Market Incumbents: Insulate margin position through backward integration into pressure-treated lumber treatment facilities and certified chain-of-custody documentation ahead of CSRD disclosure requirements. Expand digital-physical integration investments to defend project-planning mission capture against pure-play online entrants. Prioritize moisture-resistant flooring SKU depth as regulatory compliance accelerates exterior renovation demand. For New Entrants and Emerging Players: Norrland's dispersed rural geography offers underpenetrated white-space for out-of-town warehouse formats with seasonal bulk purchasing programs. Secondary city corridors around Uppsala and western Sweden present project-planning mission opportunities where incumbent footprint density remains thin. Pursue private-label tool specialization targeting price-sensitive rural segments through direct sourcing from Baltic manufacturing networks. For Investors and Strategic Acquirers: The market sits at a regulatory acceleration phase that favors vertically integrated specialists with verified carbon disclosure capabilities. Long-term viability hinges on CSRD-compliant supplier qualification infrastructure and digital channel integration depth. Acquisition target archetypes include regional lumber treaters with FSC chain-of-custody certification and mobile-optimized consumables platforms. Monitor Boverket inspection capacity expansion in northern municipalities as inflection signal for enforcement-driven demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Private-Label Tool Expansion | Jula Holding's rural price positioning demonstrates margin defense against transparent online channels. |
| Click-and-Collect Integration | Clas Ohlson's Stockholm-centric convenience model merges digital efficiency with tactile material assessment. |
| CSRD-Compliant Sourcing | Verified pressure-treated wood chain-of-custody documentation creates first-mover qualification advantage. |
| Secondary City Warehouse Buildout | Byggmax's Gothenburg and Malmö expansion captures underserved bulk lumber demand outside capital region. |
| Moisture-Resistant Flooring SKU Depth | Nordic climate-specific laminate technology commands premium positioning in systematic retrofit projects. |
Research Methodology
Operator-level perspectives from category buyers at DIY retail chains, procurement directors at Nordic sawmill groups, and Boverket building inspection officers anchored the qualitative base. Primary interview findings combined with secondary validation from Swedish Chemicals Agency regulatory filings, EU Timber Regulation enforcement reports, and Nordic forestry trade statistics. Bottom-up store-level transaction modeling and top-down housing stock renovation rate projections enabled triangulation across independent estimation paths.
Scenario-bracketing around Boverket enforcement intensity and professional labor shortage persistence shaped volume projections across the analysis window. Segmentation dimensions encompassed product type, customer archetype, distribution channel, and regional housing tenure patterns. CAGRs derived from housing stock age distribution analysis and energy certificate transaction velocity. Industry-specific forecast inputs included multifamily unit renovation permit data and cordless tool battery platform replacement cycle surveys.
Practitioners should monitor CSRD implementation timelines and Baltic sawmill capacity utilization rates for early signals of supply constraint or pricing inflection. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and Nordic softwood harvest levels. Quarterly review of Boverket inspection staffing announcements and Kemi chemical restriction amendments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
DIY Home Improvement Products
Germany DIY Home Improvement Market
DIY Home Improvement Products
Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Saudi Arabia Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Netherlands DIY Home Improvement Market
DIY Home Improvement Products
Asia-Pacific DIY Home Improvement Market
DIY Home Improvement Products
Spain Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
France Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Japan Do-It-Yourself (DIY) Home Improvement Retailing Market