
 France Do-It-Yourself (DIY) Home Improvement Retailing Market | 2026-2036
France Do-It-Yourself (DIY) Home Improvement Retailing Market Size, Share, and Industry Trends Forecast 2026-2036
France Do-It-Yourself (DIY) Home Improvement Retailing Market Insights
A shortage of skilled renovation labor is reorganizing how French households approach home projects, pushing more consumers toward self-installation of flooring and basic fixtures. Leroy Merlin leverages its hypermarket format to dominate suburban catchment areas around Paris and Lyon. Castorama sustains competitive pressure through dedicated contractor counters that anchor professional trade relationships. Brico Dépôt differentiates on price-focused warehouse positioning, competing aggressively for budget-conscious renovation spend.
France DIY home improvement retailing encompasses the sale of tools, paints, flooring, and garden supplies through brick-and-mortar and digital channels, with product assortments calibrated to building material standards such as NF certification for electrical and plumbing goods. The primary commercial purpose is enabling both amateur and semi-professional execution of residential maintenance, decoration, and structural upgrade projects. Tools and paints occupy the largest margin pools, reflecting high inventory turnover and strong private-label penetration. Online distribution represents the fastest-growing channel, though specialty stores retain durable foot traffic for tactile product evaluation. Homeowners remain the core customer segment, while contractor purchasing through retail channels is gaining structural importance.
France's RE2020 environmental regulation and the EU Green Deal framework shape product assortments, mandating energy-performance labeling and restricting certain chemical formulations in paints and solvents. ANSM and DGCCRF oversight ensures consumer safety standards for power tools and construction chemicals, influencing import requirements and domestic sourcing patterns. Stakeholders must monitor how tightening decarbonization rules for building materials reshape supplier portfolios and private-label development priorities.
Market Dynamics
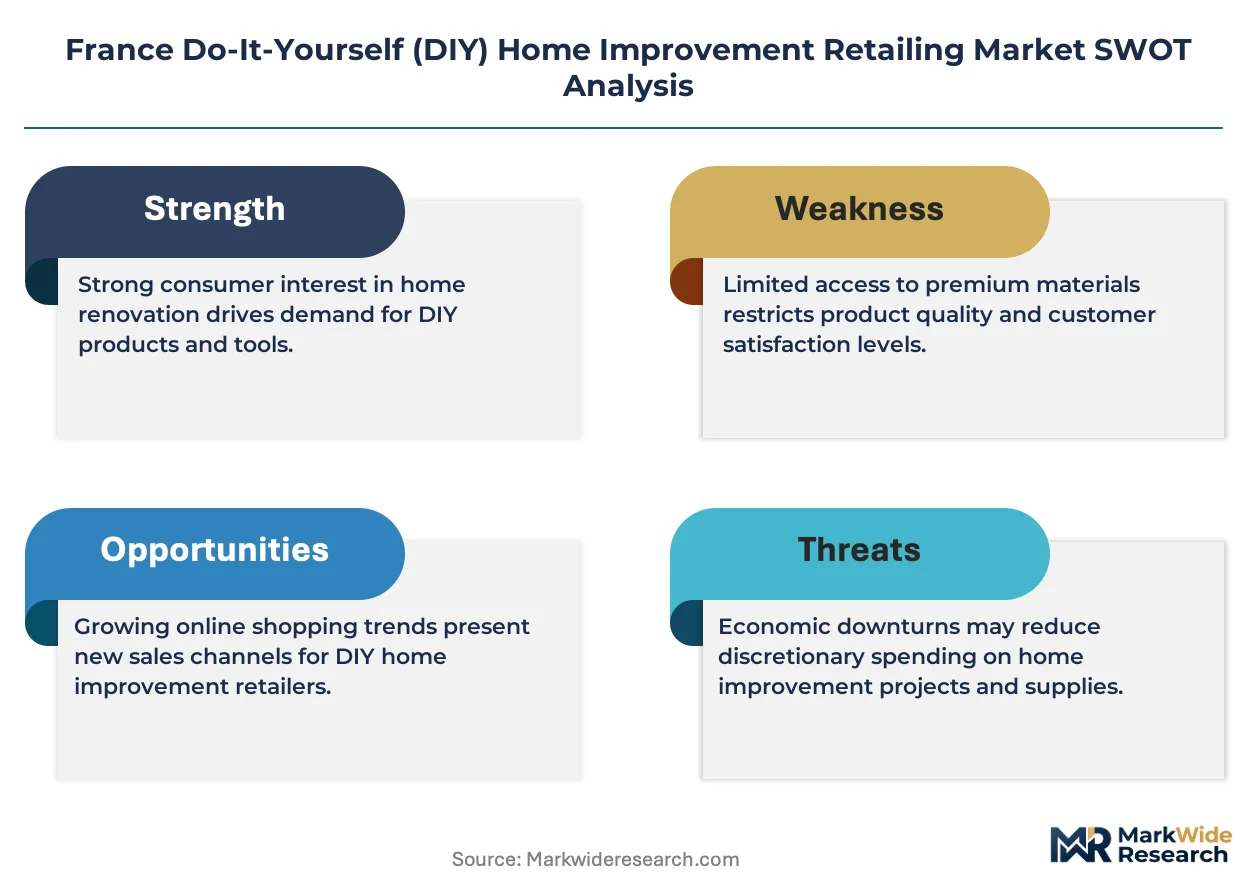
France's RE2020 environmental regulations are compressing renovation timelines and forcing rapid retooling of product assortments toward low-carbon building materials and energy-performance certified goods.
Growth Catalysts
- Energy-efficiency mandates:RE2020 regulations require thermal retrofitting of existing housing stock, accelerating demand for insulation materials and high-performance windows across suburban Île-de-France.
- Skilled labor shortage:A persistent gap in qualified renovation contractors pushes homeowners toward self-execution of flooring, painting, and fixture installation projects.
- Île-de-France housing density:Aging apartment buildings in Paris and surrounding departments sustain consistent tool and material purchases for ongoing maintenance cycles.
Market Restraints
- Input cost volatility:Lumber and copper pricing fluctuations squeeze margin pools on structural materials and electrical goods.
- Supply concentration risk:Dependence on Chinese-manufactured power tools and battery systems creates vulnerability to shipping disruptions and tariff adjustments.
- REACH chemical restrictions:ECHA limitations on solvent-based paints and adhesives force rapid reformulation of private-label product lines.
Strategic Opportunities
- Auvergne-Rhône-Alpes expansion:Lyon and Grenoble satellite communities show underpenetrated catchment areas for hypermarket-format DIY retail.
- EU Green Deal alignment:Carbon labeling requirements create first-mover advantage for retailers with verified low-emission supply chains.
- Digital channel convergence:Click-and-collect integration with in-store tactile evaluation addresses the persistent need for hands-on product assessment.
Industry Challenges
- NF certification timelines:Electrical and plumbing goods face extended approval windows that delay new product introductions.
- Inventory reconfiguration costs:RE2020 compliance demands capital-intensive shifts toward bio-based insulation and water-based coating systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Do-It-Yourself (DIY) Home Improvement Retailing Market |
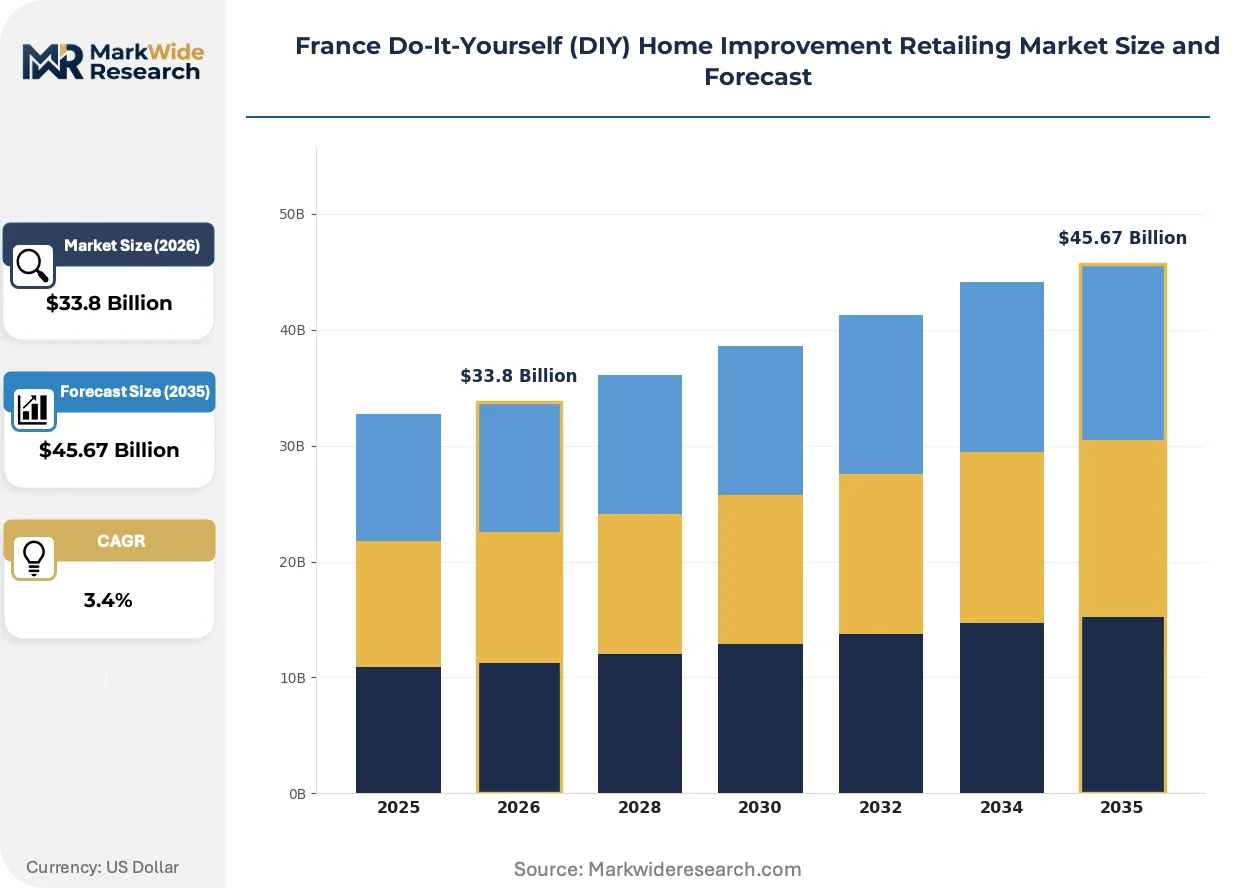
| Market Size in 2026 | $33.8 Billion |
| Market Size in 2035 | $45.67 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tools, Paints, Flooring, Garden Supplies Distribution Channel: Online, Supermarkets, Specialty Stores, Warehouse Clubs Customer Type: Homeowners, Contractors, Renters, DIY Enthusiasts Project Type: Renovation, Maintenance, Decoration, Landscaping |
| Companies Covered | Leroy Merlin, Castorama, Brico Dépôt, Mr. Bricolage, Bricomarché, Bricorama, Brico Cash, Weldom, Kingfisher, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Do-It-Yourself (DIY) Home Improvement Retailing Market Trends and Innovations
Digital tools and sustainable material science are restructuring how French consumers plan, purchase, and execute home renovation projects across retail channels.
Water-based paint formulations with bio-solvent carriers is supplanting traditional alkyd and oil-based coatings in professional and amateur segments alike. Suburban homeowners in Île-de-France are adopting these products at accelerating rates due to odor reduction and faster drying properties. This transition is compressing shelf space allocation for legacy solvent-based lines while expanding private-label development budgets.
France's DGCCRF enforcement of RE2020 energy-performance labeling is tightening disclosure requirements for insulation and window retailers. The industrial consequence is mandatory third-party verification of thermal resistance claims before product listing. Building material distributors in the Paris basin are responding by consolidating supplier relationships around pre-certified manufacturers.
Project-planning applications with augmented reality visualization are altering pre-purchase behavior among first-time renovators. These digital tools are displacing traditional in-store consultation services as the primary decision-support mechanism. Adoption concentrates among millennial homeowners in Lyon and Bordeaux metropolitan areas where housing transaction volumes remain elevated.
France Do-It-Yourself (DIY) Home Improvement Retailing Market Segmentation
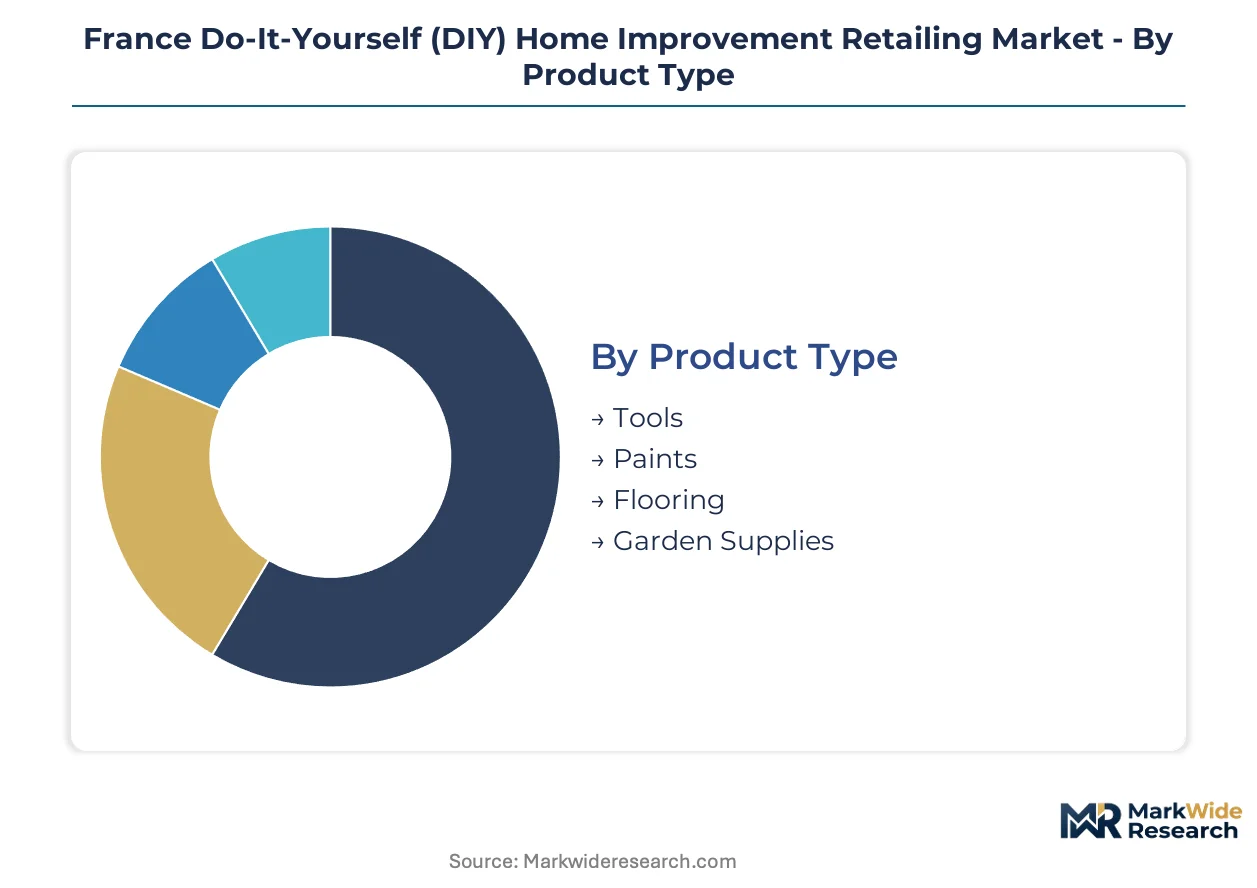
Segmentation reveals how regulatory pressure and labor scarcity reshape purchasing patterns across the French DIY retail landscape. Distinct customer profiles and project types command differentiated product assortments and channel strategies.
Product Type:
Paints face the most acute substitution threat as bio-solvent formulations displace legacy alkyd coatings under RE2020 chemical restrictions.
- Tools:Power tools and hand tools dominate margin pools through high inventory turnover and strong private-label penetration. Battery-powered systems from Chinese manufacturers concentrate sourcing risk while professional-grade demand accelerates in Île-de-France suburban catchments.
- Paints:Water-based formulations with bio-solvent carriers now supplant oil-based coatings across amateur and professional segments. ANSM enforcement of volatile organic compound limits compresses shelf space for solvent-based lines while expanding reformulation budgets for compliant private-label development.
- Flooring:Laminate and engineered wood products serve self-installation trends driven by contractor availability constraints.
- Garden Supplies:Seasonal demand cycles align with outdoor maintenance periods in temperate French climates.
Tools retain volume leadership; Paints holds the steepest expansion curve as regulatory compliance accelerates product turnover.
Distribution Channel:
Cost tier differentiation separates premium tactile evaluation from budget-focused bulk purchasing.
- Online:Click-and-collect integration with augmented reality visualization tools now displaces traditional in-store consultation for millennial first-time renovators. DGCCRF-mandated energy-performance labeling requirements complicate digital disclosure while consolidating supplier relationships around pre-certified manufacturers.
- Specialty Stores:Tactile product evaluation persists as the decisive purchase factor for electrical and plumbing goods requiring NF certification verification. These outlets anchor professional trade relationships through dedicated contractor counters in Lyon and Paris basin locations.
- Supermarkets:Convenience positioning captures emergency maintenance purchases and impulse decorative items.
- Warehouse Clubs:Price-focused formats compete aggressively for budget-conscious renovation spend through volume-based structural material offerings.
Specialty Stores command the highest transaction values; Online gains share fastest through digital channel convergence.
Customer Type:
Application-based segmentation separates structural upgrade execution from cosmetic refresh cycles.
- Homeowners:Aging housing stock in Île-de-France sustains consistent tool and material purchases for ongoing maintenance cycles. RE2020 thermal retrofitting mandates accelerate insulation and high-performance window demand among suburban owner-occupiers.
- Contractors:Retail channel purchasing gains structural importance as professional trade relationships anchor through dedicated contractor counters at hypermarket-format locations around Paris and Lyon.
- Renters:Decoration-focused spending concentrates on non-structural, removable improvements.
- DIY Enthusiasts:Project-planning application adoption concentrates among digitally native segments in Bordeaux and Lyon metropolitan areas.
Homeowners anchor revenue concentration; Contractors climb the fastest as skilled labor shortage pushes trade professionals toward retail procurement.
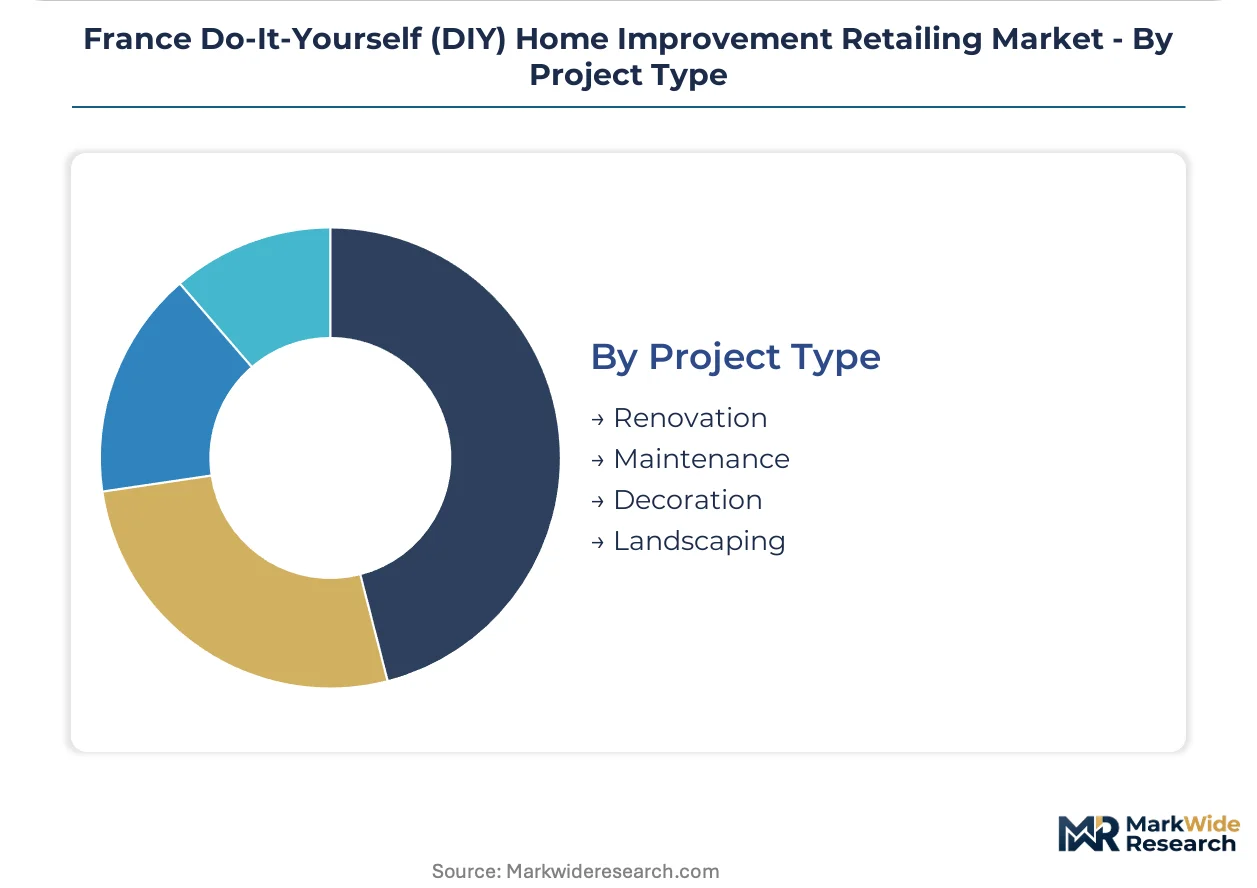
Project Type:
Volume-based segmentation distinguishes capital-intensive structural work from recurring maintenance cycles.
- Renovation:Energy-efficiency retrofits under RE2020 environmental regulations compress project timelines while forcing rapid retooling toward low-carbon building materials. Thermal resistance claim verification now requires mandatory third-party certification before product listing.
- Maintenance:Recurring repair cycles in aging Paris apartment buildings generate steady demand for basic fixtures and electrical goods. NF certification timelines for these products create extended approval windows that delay new product introductions.
- Decoration:Faster refresh cycles align with seasonal trends and housing transaction volumes.
- Landscaping:Outdoor project timing follows climatic patterns in temperate French regions.
Renovation captures the largest project values; Maintenance provides the most predictable recurring revenue base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANSM and DGCCRF oversight of France's RE2020 energy-performance standards anchors regulatory enforcement across metropolitan retail catchments. Regional demand concentrates in Île-de-France and its satellite corridors, where aging housing stock and strict building codes sustain consistent tool and material purchases.
Île-de-France
Paris basin homeowners drive thermal retrofitting demand under RE2020 mandates, accelerating insulation and high-performance window purchases. DGCCRF enforcement of energy-performance labeling tightens disclosure requirements for building material distributors. Aging apartment buildings in Paris and surrounding departments generate recurring maintenance cycles for basic fixtures and electrical goods requiring NF certification.
Auvergne-Rhône-Alpes
Lyon and Grenoble satellite communities show underpenetrated catchment areas for hypermarket-format DIY retail expansion. RE2020 regulations compress renovation timelines while forcing rapid retooling toward low-carbon building materials. Millennial homeowners in Lyon metropolitan areas adopt project-planning applications with augmented reality visualization at accelerating rates.
Provence-Alpes-Côte d'Azur
Mediterranean climate patterns shape seasonal demand cycles for garden supplies and outdoor maintenance materials. ANSM oversight of volatile organic compound limits influences paint formulation preferences across amateur segments. Marseille and Nice retail corridors anchor professional trade relationships through dedicated contractor counters.
Hauts-de-France
Industrial heritage housing stock sustains structural upgrade demand for flooring and fixture replacement projects. REACH chemical restrictions on solvent-based coatings force rapid reformulation of private-label product lines stocked by regional distributors. Lille metropolitan catchment areas concentrate budget-conscious renovation spend through warehouse-format retail positioning.
Nouvelle-Aquitaine
Bordeaux metropolitan housing transaction volumes elevate decoration-focused spending among first-time renovators. EU Green Deal carbon labeling requirements create first-mover advantage for retailers with verified low-emission supply chains serving southwestern owner-occupiers. Digital channel convergence through click-and-collect integration addresses persistent tactile product evaluation needs.
France Do-It-Yourself (DIY) Home Improvement Retailing Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes within France's DIY retail structure. The market consolidates around three dominant formats: hypermarket-scale operators anchoring suburban catchments, warehouse clubs competing on price-focused positioning, and specialty stores retaining tactile evaluation advantages. Strategic archetypes separate format innovators leveraging digital channel convergence from scale-driven players optimizing procurement and private-label development. Competitive moves concentrate on geographic densification around underpenetrated satellite communities and portfolio reconfiguration toward RE2020-compliant product assortments.
Among France-based retail operators, Leroy Merlin and Castorama exemplify the hypermarket-format archetype dominating suburban catchment areas, while Brico Dépôt occupies a position within the price-focused warehouse tier. These three anchors represent distinct strategic postures: format scale and private-label penetration, professional trade relationship anchoring through contractor counters, and aggressive budget positioning for renovation spend. Their collective presence shapes competitive intensity across Île-de-France and regional metropolitan corridors.
| Leading Market Players |
|---|
| Leroy Merlin |
| Castorama |
| Brico Dépôt |
| Mr. Bricolage |
| Bricomarché |
| Bricorama |
| Brico Cash |
| Weldom |
| Kingfisher |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation agreements with Chinese power tool manufacturers lock in both supply access and price visibility for French retailers navigating RE2020 compliance timelines. These contractual structures insulate hypermarket-format operators from spot-market volatility in lithium-ion battery systems while compressing margin pools on electrical goods subject to NF certification delays.
Pricing Analysis
Île-de-France commands a 12-18% premium over Hauts-de-France for identical power tool SKUs due to higher commercial rents and logistics costs. Three-tier pricing structure across premium professional-grade, standard DIY, and economy private-label levels stratifies by certification grade and after-sales service bundling. Cost compression in economy tiers is intensifying because of Chinese manufacturer overcapacity and direct-to-retail shipping consolidation. First-time renovators in Bordeaux and Lyon show highest price sensitivity, while contractor segments prioritize NF-certified reliability over unit economics.
Supply Chain Analysis
Port congestion at Le Havre and container availability constraints on Asia-Europe trade lanes are extending inbound lead times for battery-powered systems and hand tool shipments. Manufacturing concentrates in China, Vietnam, and Taiwan for power tools, with Germany and Italy anchoring high-performance window and insulation material supply. Copper wiring, engineered wood substrates, and lithium-ion cells constitute critical input dependencies. Single-source vulnerability around Chinese battery cell production creates exposure to tariff adjustments and shipping disruptions. Distribution runs through hypermarket regional distribution centers serving suburban catchments, with click-and-collect nodes addressing last-mile density in Paris basin corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's DIY retail structure rewards defensive moats built on regulatory entrenchment. RE2020 compliance timelines and NF certification requirements create switching costs that anchor professional trade relationships and protect incumbent market positions.
For Market Incumbents: Shield market position by deepening backward integration into bio-solvent paint formulation capabilities ahead of REACH enforcement deadlines. Prioritize capacity reservation expansion with pre-certified insulation manufacturers to compress competitor access to compliant supply. The threat of digital-native entrants with augmented reality project tools demands accelerated click-and-collect infrastructure investment in Lyon and Grenoble satellite communities.
For New Entrants and Emerging Players: Lead with white-space capture in Auvergne-Rhône-Alpes hypermarket deserts around Grenoble and Saint-Étienne, where incumbent store density trails population growth. The most penetrable segment is millennial first-time renovators seeking digital-native project planning tools with tactile product evaluation integration. A go-to-market angle anchored on carbon-labeled private-label assortments exploits EU Green Deal alignment gaps in incumbent portfolios.
For Investors and Strategic Acquirers: Capital is best deployed toward regional specialty store networks with established contractor counter relationships and pre-certified supplier portfolios. Long-term viability across the analysis window favors operators with RE2020-compliant product mix above 60% of revenue. The inflection signal to monitor is DGCCRF acceleration of energy-performance labeling enforcement timelines, which would compress competitor adaptation windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Private-Label Reformulation Investment | Bio-solvent paint development ahead of REACH restrictions secures shelf space allocation. |
| Contractor Counter Expansion | Dedicated trade service desks in Lyon and Paris basin anchor professional procurement relationships. |
| Click-and-Collect Infrastructure | Digital-physical integration addresses millennial renovator preference for tactile evaluation. |
| Pre-Certified Supplier Consolidation | Exclusive relationships with NF-certified manufacturers compress competitor product introduction timelines. |
| Carbon Labeling Program Launch | Verified low-emission supply chains create first-mover advantage under EU Green Deal frameworks. |
Research Methodology
Operator-level perspectives from hypermarket category managers, contractor counter supervisors, paint formulation chemists, and DGCCRF compliance officers anchored the qualitative base. These primary insights combined with secondary validation from ANSM enforcement bulletins, RE2020 regulatory filings, EU Green Deal implementation guidance, and French customs trade data. Bottom-up SKU-level demand modeling and top-down retail revenue triangulation cross-checked volume assumptions across the projection horizon.
Sensitivity analysis tested forecast robustness against lumber price volatility scenarios and Chinese shipping disruption events. Segmentation dimensions modeled include product type, distribution channel, customer archetype, and project category across regional metropolitan clusters. CAGRs derived from historical trajectory analysis adjusted for regulatory acceleration effects. RE2020 compliance cost pass-through rates and private-label penetration curves served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in French RE2020 implementation and EU Green Deal carbon labeling timelines; material policy shifts would require re-modeling. Supply chain disruption severity and skilled labor shortage persistence constitute specific risk factors that could revise demand projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
DIY Home Improvement Products
Germany DIY Home Improvement Market
DIY Home Improvement Products
Asia-Pacific DIY Home Improvement Market
DIY Home Improvement Products
Netherlands DIY Home Improvement Market
DIY Home Improvement Products
Sweden DIY Home Improvement Market
DIY Home Improvement Products
Spain Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Japan Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Saudi Arabia Do-It-Yourself (DIY) Home Improvement Retailing Market