
 Netherlands DIY Home Improvement Market | 2026-2036
Netherlands DIY Home Improvement Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands DIY Home Improvement Market Foresight
Specialist home improvement store networks is tilting toward experiential retail formats that blend showroom displays with contractor service desks. Gamma leverages its dense Dutch store footprint to sustain local brand recognition across provincial markets. Hornbach anchors its position through large-format destinations emphasizing project-based shopping journeys. Praxis competes via integrated online-to-store fulfillment that reduces delivery friction for bulky building materials.
DIY home improvement encompasses self-directed residential renovation, repair, and decoration activities utilizing hand tools, power equipment, surface coatings, floor coverings, and illumination systems manufactured to EN safety and performance specifications. The category serves homeowners, landlords, and contractors seeking cost-controlled property maintenance or value-enhancing upgrades without professional trade dependency. Tools and paints occupy the largest revenue pools, reflecting repetitive purchase cycles and broad household penetration across all price tiers. Flooring and lighting segments attract premium positioning, as Dutch consumers prioritize sustainable timber certifications and LED efficiency ratings that command margin premiums over standard alternatives.
Dutch Building Decree standards enforced by the Ministry of the Interior and Kingdom Relations mandate thermal performance minimums that shape insulation product specifications and window replacement demand. CE marking under EU construction product regulation governs market access for structural building materials sold through retail channels. Stakeholders must monitor tightening energy performance requirements and evolving digital commerce compliance obligations as the market transitions toward omnichannel service models.
Market Dynamics
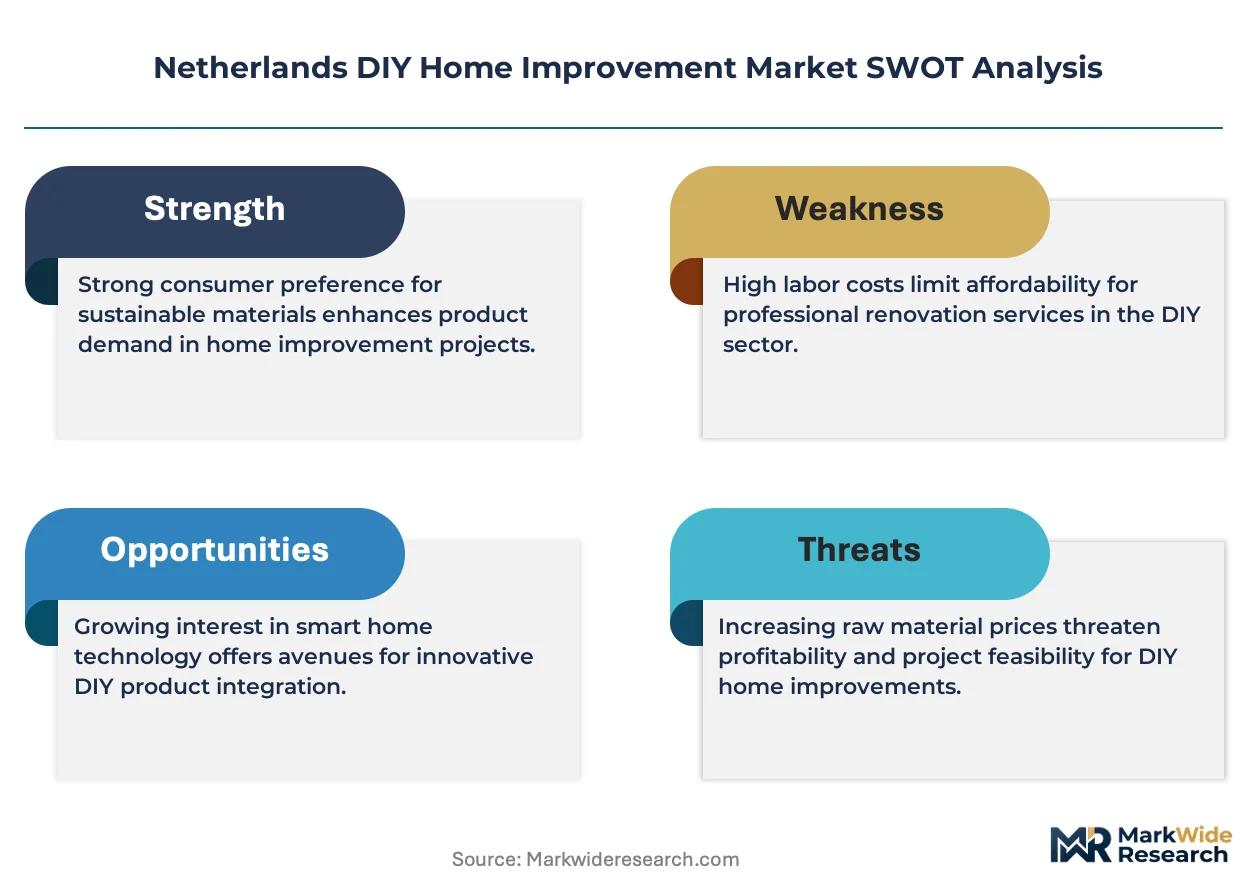
The Dutch DIY home improvement sector faces structural pressure from mandatory energy performance mandates that redirect renovation spending toward insulation and window replacement, compressing traditional decorative categories while elevating building envelope materials.
Growth Catalysts
- Dutch Building Decree thermal standards:The Ministry of the Interior mandates minimum thermal performance for residential structures, forcing landlords and homeowners to prioritize insulation retrofits and high-efficiency glazing systems.
- Randstad housing density:Concentrated property values across Amsterdam, Rotterdam, The Hague and Utrecht corridors support sustained investment in premium fixtures and professional-grade tools among owner-occupiers.
- CE marking harmonization:EU construction product regulation streamlines cross-border material sourcing, enabling Dutch retailers to expand certified product assortments without redundant national testing protocols.
Market Restraints
- Aluminum and timber input volatility:Window frames and sustainable flooring materials face raw material price swings that compress retail margins on fixed-price installation contracts.
- German manufacturing concentration:Power tool and coating supply chains cluster in Baden-Württemberg and Bavaria, exposing Dutch distributors to single-source disruption risks during cross-border logistics constraints.
- Skilled installer scarcity:Energy label upgrade deadlines outpace certified contractor availability, creating execution bottlenecks for rental property compliance projects.
Strategic Opportunities
- Gelderland and North Brabant aging housing stock:Suburban provinces host elevated concentrations of pre-1990 dwellings requiring comprehensive envelope modernization, opening secondary market penetration beyond Randstad saturation.
- Online-to-store fulfillment integration:Bulky building material logistics favor hybrid commerce models that merge digital specification tools with physical collection points, reducing last-mile delivery costs for insulation batts and timber lengths.
- EU Green Deal renovation wave funding:National subsidy schemes for residential energy efficiency create financed demand pools that lower homeowner upfront barriers to window and insulation investments.
Industry Challenges
- EN standard compliance timelines:Evolving safety and performance specifications for power equipment require continuous product re-certification, straining R&D resources and inventory transition management.
- Omnichannel inventory synchronization:Real-time stock visibility across showroom floors, regional warehouses and digital platforms demands capital-intensive systems integration without guaranteed conversion lift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands DIY Home Improvement Market |
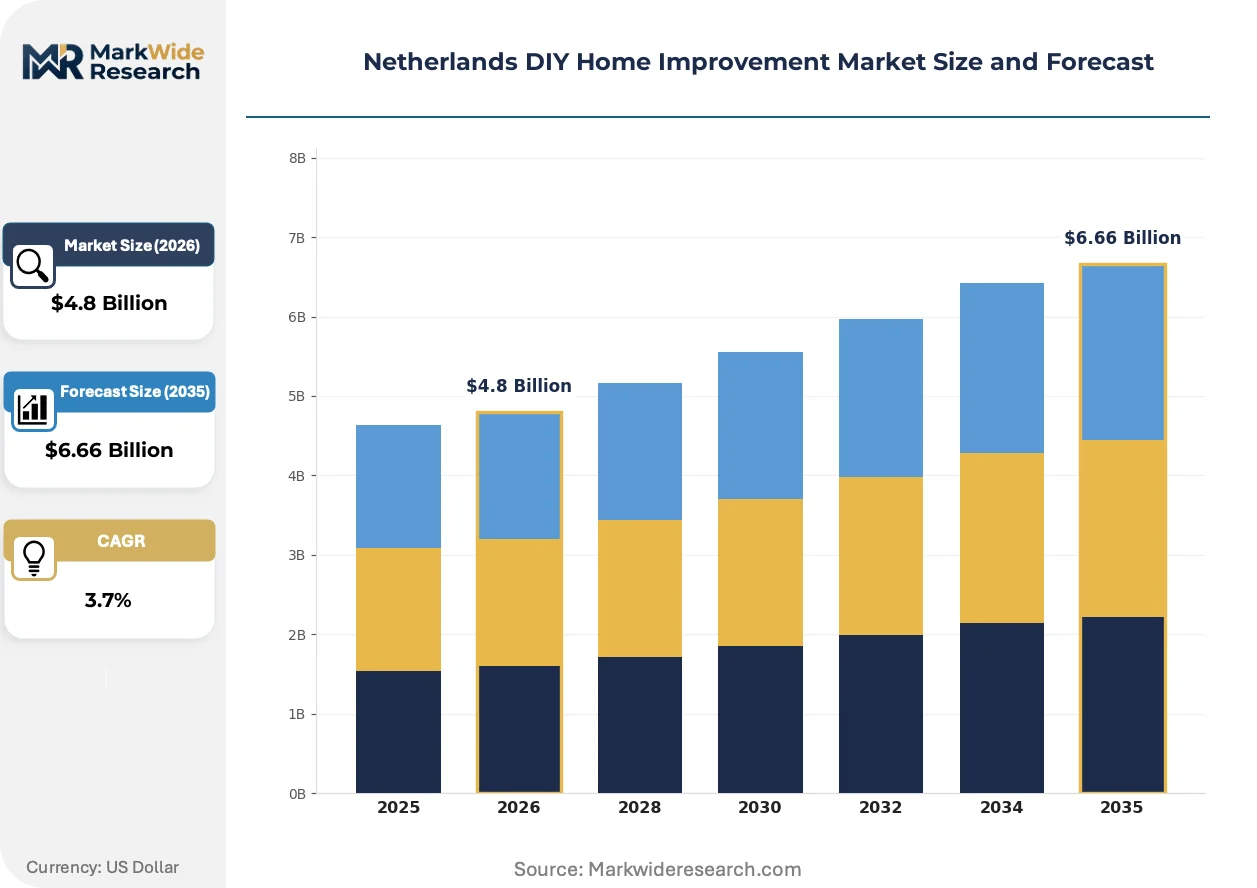
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tools, Paints, Flooring, Lighting End User: Homeowners, Contractors, Renters, Interior Designers Distribution Channel: Online Retail, Home Improvement Stores, Wholesale, Supermarkets Price Tier: Affordable, Mid-Range, Premium, Luxury |
| Companies Covered | Gamma, Vorwerk, Groupe Adeo SA, Karwei, Bauhaus, Hornbach, IKEA, Hubo, Praxis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands DIY Home Improvement Market Shifts & Advancements
Digital specification tools and connected jobsite equipment are restructuring how Dutch homeowners and contractors plan, procure and execute residential renovation projects.
Smart home energy management systems with integrated thermal monitoring capabilities are rendering obsolete standalone thermostat and manual radiator valve installations. Owner-occupiers in Amsterdam and Utrecht corridors adopt these systems fastest, compressing demand for conventional heating controls and shifting electrical contractor skill requirements toward IoT configuration.
The EU F-Gas Regulation phase-down mandates accelerate adoption of natural refrigerant heat pumps and low-global-warming-potential insulation blowing agents. Dutch HVAC and envelope contractors must retool equipment and certification portfolios to handle propane and CO2 systems, with rural Gelderland installations showing earliest compliance-driven equipment turnover.
Project-based buying patterns now dominate suburban renovation planning, with homeowners researching complete kitchen or bathroom specifications online before entering physical stores. This behavior concentrates purchasing authority in digital research phases, forcing retailers to deploy augmented reality visualization tools and contractor matching services to capture consideration-stage engagement before price comparison commoditization sets in.
Netherlands DIY Home Improvement Market Segmentation
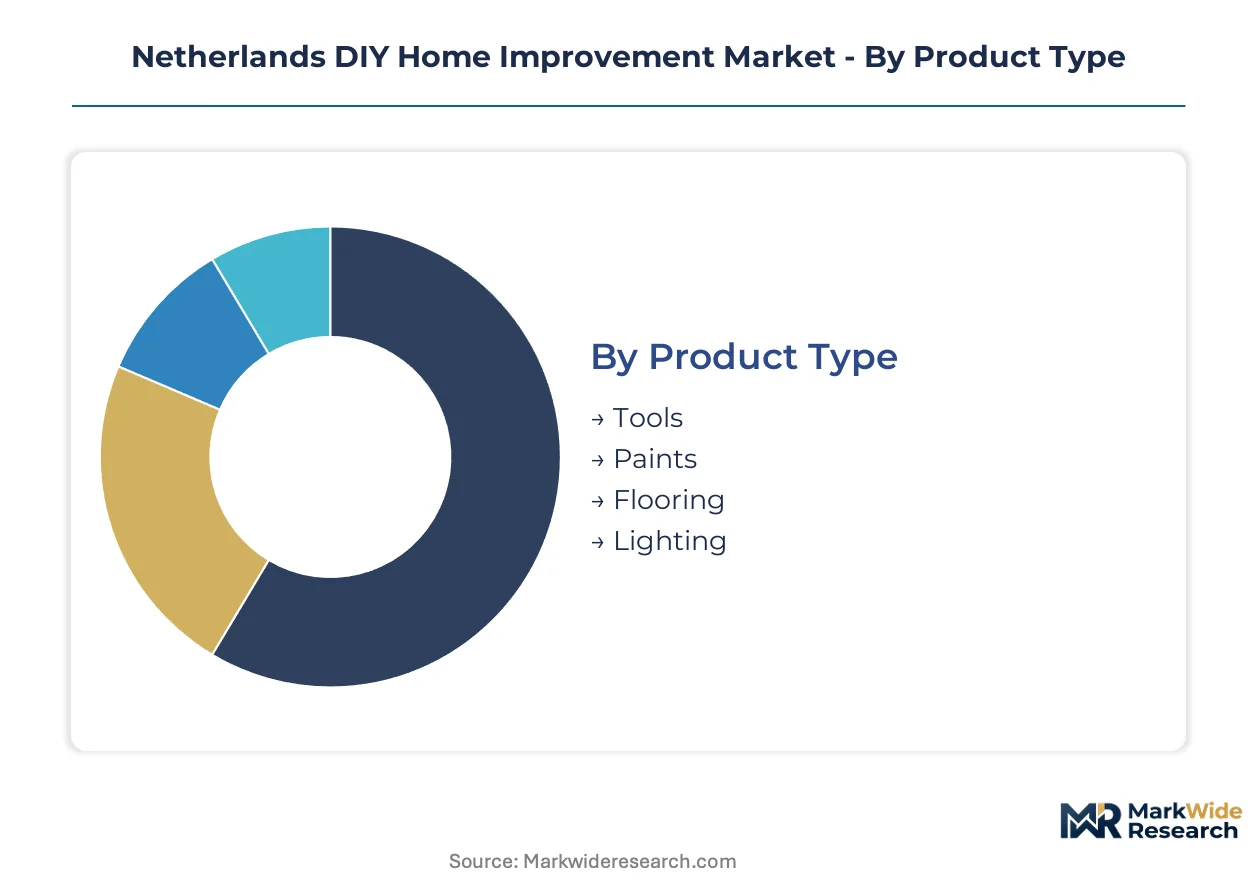
Segmentation in the Dutch DIY market reveals how energy efficiency mandates and Randstad property economics reshape purchasing patterns across product categories and customer types. Understanding these divides exposes where insulation-driven spending concentrates versus where traditional decorative categories retain relevance.
Product Type:
After-sales service intensity varies sharply across product categories, with power equipment demanding repair networks and technical support while coatings require minimal post-purchase engagement.
- Tools:Power equipment and hand tool assortments span corded drills, cordless drivers, and precision measuring devices built to EN 60745 safety specifications. Demand clusters among aging homeowners in North Brabant executing envelope retrofits, driven by contractor scarcity that forces self-directed installation of insulation and window systems. Tools holds the largest share; momentum sits with Lighting.
- Paints:Decorative and protective coatings encompass interior emulsions, exterior masonry finishes, and specialist moisture-resistant formulations. Randstad apartment renovations sustain volume, though Dutch Building Decree thermal standards redirect spending toward functional envelope materials rather than aesthetic refresh cycles.
- Flooring:Surface coverings include engineered timber, laminate, vinyl plank, and ceramic tile systems certified for residential load-bearing performance. Gelderland suburban dwellings drive sustainable timber demand, with FSC certification commanding margin premiums over standard alternatives.
- Lighting:Illumination systems comprise LED retrofit lamps, integrated fixtures, and smart control modules meeting EU ecodesign efficiency tiers. Amsterdam and Utrecht corridors show fastest adoption of connected thermal management systems, displacing conventional radiator valves and standalone thermostats.
Tools and Paints retain volume dominance through repeat purchase cycles; Lighting gains share fastest on smart home integration and energy label compliance requirements.
End User:
Application context determines specification authority, with rental property landlords facing mandatory upgrade deadlines that compress decision timelines versus discretionary homeowner renovations.
- Homeowners:Owner-occupiers across Randstad provinces and suburban Gelderland execute discretionary kitchen, bathroom, and envelope upgrades. Project-based buying patterns concentrate research online before physical store entry, forcing retailers to deploy visualization tools early in consideration phases.
- Contractors:Professional installers handle energy label compliance projects for rental portfolios and high-value residential retrofits. Scarcity of certified envelope specialists creates execution bottlenecks, extending project timelines and elevating labor cost components relative to materials.
- Renters:Tenants in regulated rental stock contribute limited direct spending, though 2030 energy label mandates indirectly shape their housing quality through landlord capital deployment.
- Interior Designers:Specification professionals influence premium fixture and finish selection in high-value Amsterdam and The Hague renovations, bridging homeowner preferences with technical compliance requirements.
Homeowners command the largest expenditure pool; Contractors show steepest expansion trajectory on regulatory-driven rental property compliance volumes.
Distribution Channel:
Volume throughput and margin structure diverge across channels, with bulky building materials favoring physical collection points while standardized consumables migrate toward digital fulfillment.
- Online Retail:Digital platforms capture standardized tools, coatings, and lighting consumables through direct-to-consumer fulfillment. Project-based research behavior concentrates purchasing authority in digital consideration phases before price comparison commoditization.
- Home Improvement Stores:Large-format destinations anchor project-based shopping journeys with showroom displays, contractor service desks, and bulk material collection points. Dense provincial footprints sustain local brand recognition across non-Randstad markets.
- Wholesale:Trade-focused distribution serves contractor accounts with volume pricing, technical specification support, and delivery coordination for envelope retrofit projects. Procurement patterns favor integrated online-to-store fulfillment that reduces last-mile friction for insulation batts and timber lengths.
- Supermarkets:Mass retail channels capture emergency replacement and entry-level consumables through convenience positioning, though assortment depth remains limited relative to specialist competitors.
Home Improvement Stores retain the dominant channel position; Online Retail climbs the fastest on hybrid fulfillment integration and digital specification tool adoption.
Price Tier:
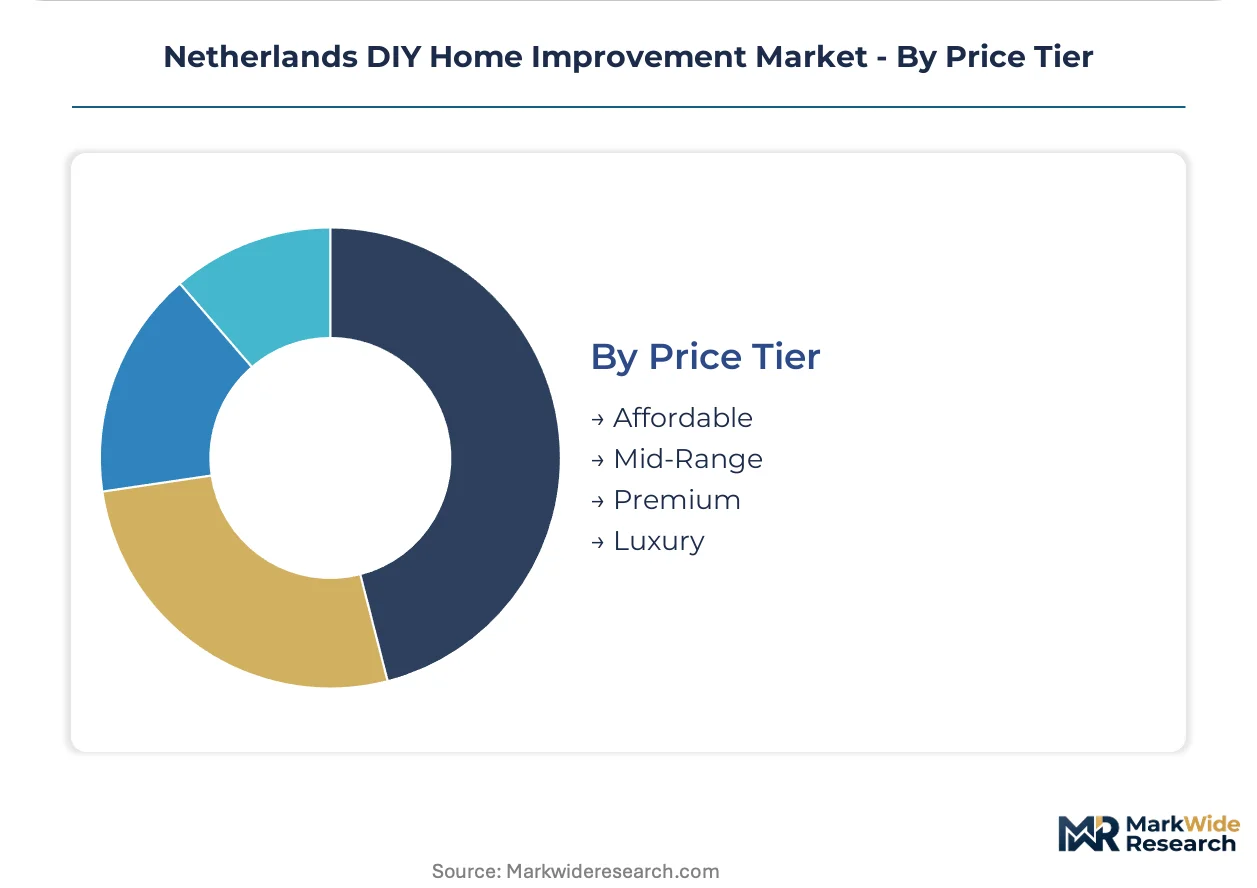
Customer type and application context stratify across price tiers, with rental compliance projects prioritizing functional mid-range specifications while discretionary renovations support premium positioning.
- Affordable:Entry-level tools, basic coatings, and standard lighting modules serve cost-constrained maintenance and emergency replacement needs. Supermarket and mass-market online channels dominate distribution.
- Mid-Range:Professional-grade power equipment, certified insulation materials, and efficient LED systems align with rental property upgrade mandates and pragmatic homeowner renovations. This tier captures regulatory-driven volume.
- Premium:Advanced power tools, sustainable timber flooring, and integrated smart home systems command margin premiums in Randstad owner-occupied properties where housing values justify investment recovery.
- Luxury:Bespoke fixtures, designer finishes, and professional-grade equipment serve high-value Amsterdam and The Hague renovations with specification authority concentrated among interior designers and affluent homeowners.
Mid-Range commands the largest revenue share; Premium gains share fastest on sustainability certification premiums and smart home integration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam anchors Dutch building material distribution, handling bulk insulation imports and timber flows that supply renovation clusters across the Randstad and southern provinces.
North Brabant
Aging suburban housing stock and contractor scarcity drive self-directed envelope retrofits among homeowners. The Dutch Building Decree thermal standards mandate insulation upgrades for pre-1990 dwellings. Eindhoven and surrounding municipalities concentrate demand for power tools and certified window systems.
Gelderland
Sustainable timber flooring and envelope materials attract premium positioning among owner-occupiers. EU Green Deal renovation wave subsidies lower upfront barriers for rural property modernization. Arnhem-Nijmegen corridor shows fastest adoption of FSC-certified products and natural refrigerant heat pumps.
Randstad Corridor
Amsterdam, Rotterdam, The Hague and Utrecht sustain premium fixture investments through concentrated property values. Mandatory energy label upgrade requirements for rental properties by 2030 redirect spending toward high-efficiency glazing and smart thermal management systems.
Northern Netherlands
Lower housing density moderates absolute spending volumes compared to southern provinces. Online-to-store fulfillment integration reduces delivery friction for bulky insulation materials in dispersed markets. Groningen and Friesland lag Randstad adoption curves for connected home energy systems.
Zeeland and Limburg
Cross-border commuter flows and German manufacturing proximity shape procurement patterns for power equipment. CE marking harmonization enables seamless sourcing from Baden-Württemberg suppliers. Maastricht and regional hubs serve as collection points for project-based building material purchases.
Netherlands DIY Home Improvement Market Competitive Landscape
On the supply side, the industry is consolidating around large-format destination retail and hybrid fulfillment platforms that merge physical collection points with digital specification tools. Specialist networks compete through experiential showroom formats and contractor service integration. Two strategic archetypes dominate: dense provincial footprint operators and integrated online-to-store fulfillment specialists. Competitive moves center on regional warehouse expansion and augmented reality visualization tool deployment to capture consideration-stage engagement.
Among Dutch and German-based retailers, Gamma, Hornbach and Praxis anchor distinct positioning vectors. Gamma exemplifies the dense provincial footprint archetype through sustained local brand recognition across non-Randstad markets. Hornbach occupies the large-format destination position, emphasizing project-based shopping journeys with contractor service desks. Praxis represents integrated online-to-store fulfillment, reducing last-mile friction for bulky building materials through hybrid commerce infrastructure.
| Leading Market Players |
|---|
| Gamma |
| Vorwerk |
| Groupe Adeo SA |
| Karwei |
| Bauhaus |
| Hornbach |
| IKEA |
| Hubo |
| Praxis |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp freight corridors channel aluminum extrusions and engineered timber from German manufacturing clusters into Dutch distribution networks, where cross-border logistics costs amplify price differentiation between Randstad premium tiers and provincial mid-market positioning.
Pricing Analysis
Volume-discount tiering structures separate project-based contractor procurement from retail consumer purchases, with CE-certified insulation materials commanding margin premiums over standard alternatives. Price differentiation rests on FSC timber certification and EN thermal performance ratings, while aluminum input volatility compresses margins on fixed-price window installation contracts. Pricing pressure stems from German manufacturing concentration in Baden-Württemberg power tool supply chains. Contractors show lowest price sensitivity due to pass-through rental compliance mandates; supermarket channel consumers exhibit highest elasticity on entry-level consumables.
Supply Chain Analysis
Upstream feedstock flows of aluminum billets, sustainable timber, and LED chipsets draw from German, Belgian, and Chinese production bases respectively. Raw material dependencies center on Baden-Württemberg power equipment, Austrian engineered timber, and Asian semiconductor components for smart lighting systems. Single-source vulnerability concentrates in cross-border logistics chokepoints through North Rhine-Westphalia. Distribution runs through Rotterdam port warehousing into regional home improvement store networks and integrated online-to-store fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dutch DIY home improvement market represents a high-growth disruption as mandatory energy label upgrades by 2030 force capital redeployment from decorative categories toward building envelope materials.
For Market Incumbents: Insulate core profitability by securing captive supply agreements for certified insulation materials before EU Green Deal subsidy pools deplete. Backward integration into FSC-certified timber sourcing in Gelderland reduces exposure to sustainable flooring margin compression. Channel control through contractor service desk expansion defends against pure-play digital entrants capturing specification-stage engagement. For New Entrants and Emerging Players: Rural Gelderland and North Brabant aging housing stocks represent the most penetrable entry points beyond Randstad saturation, where contractor scarcity forces self-directed envelope retrofits. Online-to-store fulfillment infrastructure for bulky insulation batts offers differentiation against established store networks. Digital specification tools with augmented reality visualization capture consideration-phase authority before price commoditization. For Investors and Strategic Acquirers: Regional warehouse operators with integrated last-mile capabilities for building materials offer acquisition exposure to omnichannel transition tailwinds. Long-term viability hinges on subsidy scheme continuity and installer certification pipeline expansion. Monitor Dutch Building Decree enforcement intensity as the primary inflection signal for compliance-driven demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Timber | FSC supply control secures margin premiums in Gelderland sustainable flooring demand. |
| Contractor Service Desk Expansion | Technical support infrastructure captures rental compliance project volumes. |
| Online-to-Store Fulfillment Infrastructure | Hybrid commerce reduces last-mile costs for bulky insulation and timber lengths. |
| Augmented Reality Specification Tools | Digital visualization captures homeowner consideration-phase purchasing authority. |
| Regional Warehouse Network Densification | Provincial footprint expansion serves North Brabant self-directed retrofit demand. |
Research Methodology
A spread of perspectives from home improvement retail executives, envelope installation contractors, building materials procurement managers, and Dutch Ministry of Interior policy officials converged on the working assumptions driving this analysis. Primary field engagement combined with secondary validation against EU construction product regulation filings, Dutch customs trade data, CE marking certification databases, and retailer SEC disclosures established foundational inputs. Bottom-up store-level volume estimates and top-down sector expenditure flows underwent iterative reconciliation.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across product type, end user archetype, distribution channel, and price tier dimensions. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection timing and subsidy scheme uptake curves. Forecast inputs incorporated EN standard compliance timelines, installer certification pipeline constraints, and cross-border logistics cost indices.
Practitioners should monitor Dutch Building Decree enforcement acceleration, EU Green Deal subsidy pool depletion rates, and German manufacturing input cost indices for early signals requiring forecast revision. Cross-checking against national construction sector output statistics and housing transaction velocity benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
DIY Home Improvement Products
Japan Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Saudi Arabia Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Spain Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Germany DIY Home Improvement Market
DIY Home Improvement Products
France Do-It-Yourself (DIY) Home Improvement Retailing Market
DIY Home Improvement Products
Asia-Pacific DIY Home Improvement Market
DIY Home Improvement Products
Sweden DIY Home Improvement Market