
 Lemongrass Oil Market | 2026-2036
Lemongrass Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Lemongrass Oil Market Intelligence
Asset-light contract distillation and third-party leasing of extraction equipment is narrowing the capital barrier for mid-tier entrants in lemongrass oil supply. NOW Foods leverages vertical integration from sourcing to bottling to sustain margin control across volatile raw material cycles. AG Organica anchors its position through deep backward integration into organic lemongrass farms in India's primary growing belts. Mountain Rose Herbs differentiates via certified organic and fair-trade supply chains that command premium positioning in specialty retail channels.
Lemongrass oil is an essential oil obtained primarily from Cymbopogon flexuosus or Cymbopogon citratus through steam distillation, yielding a pale yellow to amber liquid containing citral as its dominant constituent at 70-85% concentration, valued for its antimicrobial, antifungal, and aromatic properties across industrial and consumer applications. Steam distillation dominates production volume due to its cost efficiency and scalability for commercial citral recovery, while cold pressing occupies a niche in premium cosmetic formulations where heat-sensitive terpene preservation commands higher unit economics. Cosmetics and aromatherapy represent the most contested application battlegrounds, with personal care brands and spa centers driving formulation innovation toward natural preservative systems.
India's BIS standards for essential oil purity and the EU REACH framework governing chemical substance registration collectively elevate compliance costs for export-oriented distillers, filtering out informal producers from formal supply chains. The USDA organic certification and FDA oversight of cosmetic ingredient safety in the United States further fragment market access requirements across destination geographies. Stakeholders must monitor regulatory convergence on natural claim substantiation and traceability mandates as decisive factors in supplier selection and geographic market prioritization.
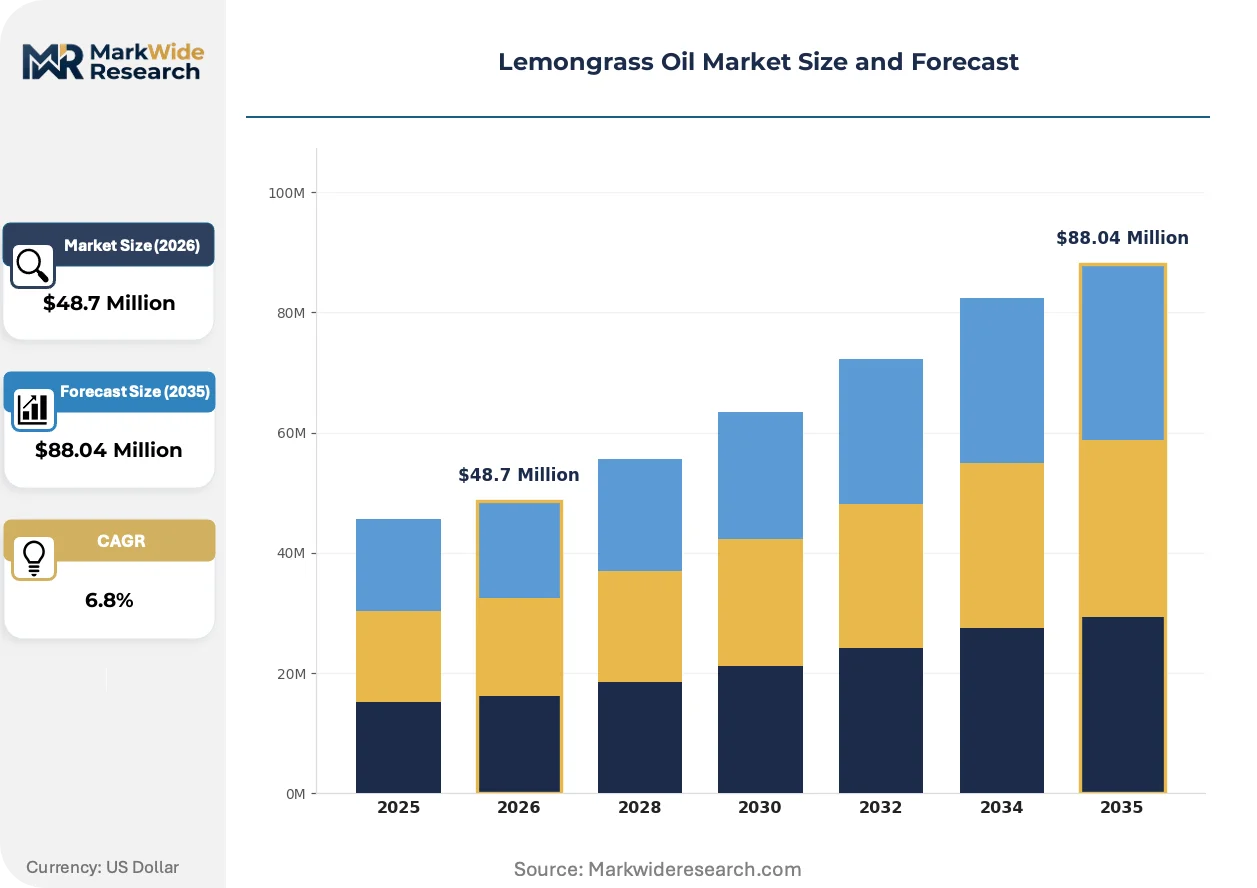
Market Dynamics
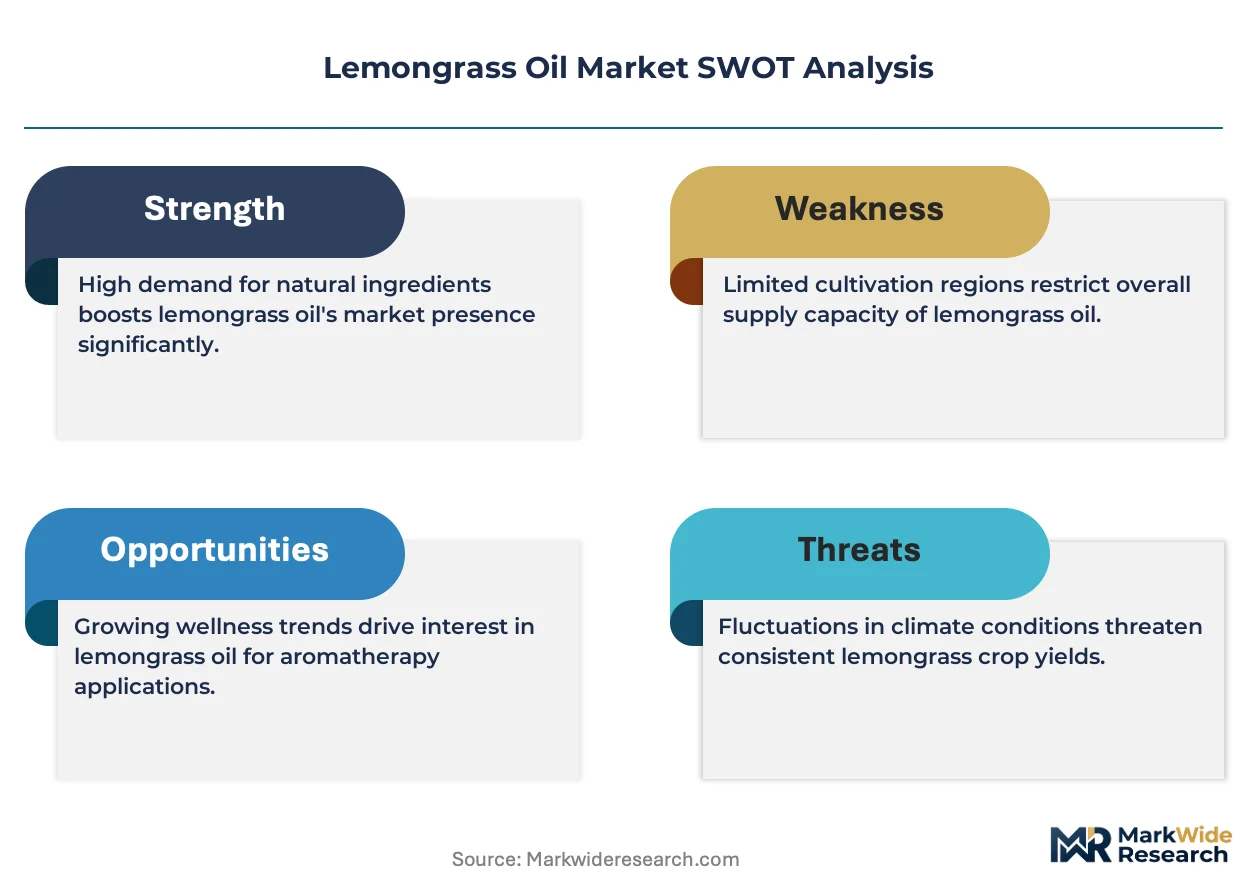
Steam distillation economics and REACH compliance burdens are bifurcating the supplier base, concentrating formal supply chains around certified organic producers while informal distillers face exclusion from export markets.
Growth Catalysts
- EU REACH framework:Chemical substance registration requirements in Europe are filtering out uncertified competitors, expanding market share for compliant distillers with traceable supply chains.
- Natural preservative systems:Personal care formulators are substituting synthetic antimicrobials with lemongrass oil citral in skincare and haircare products.
- Kerala-Tamil Nadu cultivation clusters:Traditional growing belts in southern India supply dominant global volumes with established agronomic expertise.
Market Restraints
- Monsoon-dependent biomass yields:Rainfall volatility in Indian growing regions creates raw material supply instability and price spikes.
- Steam distillation energy costs:Thermal processing requires sustained fuel inputs that compress margins during energy price cycles.
- Synthetic citral substitution:Petrochemical-derived citral from BASF and other manufacturers competes on cost for industrial fragrance applications.
Strategic Opportunities
- USDA organic certification tailwind:Premium positioning in United States specialty retail channels commands price multiples over conventional grades.
- Spa center channel expansion:Aromatherapy service providers are building direct procurement relationships with distillers, bypassing traditional distributors.
- Cold pressing technology convergence:Heat-sensitive terpene recovery methods are penetrating premium cosmetic formulations where thermal degradation is unacceptable.
Industry Challenges
- Organic certification timeline compression:Three-year transition periods for farmland conversion strain working capital for smallholder cooperatives.
- Batch-to-batch citral standardization:Natural variation in essential oil composition complicates contract fulfillment for pharmaceutical-grade buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lemongrass Oil Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Distillation, Cold Pressing, Solvent Extraction, Others Application: Cosmetics, Food & Beverage, Aromatherapy, Pharmaceuticals End User: Personal Care Brands, Food Manufacturers, Spa Centers, Health Clinics Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Edens Garden, NOW Foods, AG Organica, Plant Therapy Essential Oils, Phoenix Aromas & Essential Oils, Aura Cacia, Mountain Rose Herbs, Young Living Essential Oils, doTERRA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lemongrass Oil Market Strategic Shifts & Innovations
Formulation science advances and regulatory claim substantiation requirements are elevating analytical chemistry capabilities across the value chain, separating specification-grade suppliers from commodity traders.
Supercritical CO2 extraction is hybridizing with conventional steam distillation in mid-scale facilities, enabling selective terpene fractionation for cosmetic houses demanding precise citral-to-geraniol ratios. Fragrance compounders in France and Switzerland are adopting hybrid extraction trains to serve luxury skincare brands. This technology convergence is compressing the addressable market for standardized steam-distilled grades while expanding premium tier capacity.
REACH authorization requirements for chemical substances are forcing downstream cosmetic manufacturers to document full supply chain substance volumes. ECHA compliance deadlines are compressing procurement qualification cycles. Distillers serving European personal care brands are investing in third-party analytical certification to maintain market access.
Direct farm-to-brand contracting is displacing spot market purchasing among mid-sized personal care manufacturers seeking traceability documentation. Specialty retailers are auditing supplier agronomic practices. This procurement model evolution is most visible in German and French natural cosmetics markets where clean label claims require verified cultivation inputs.
Lemongrass Oil Market Segmentation
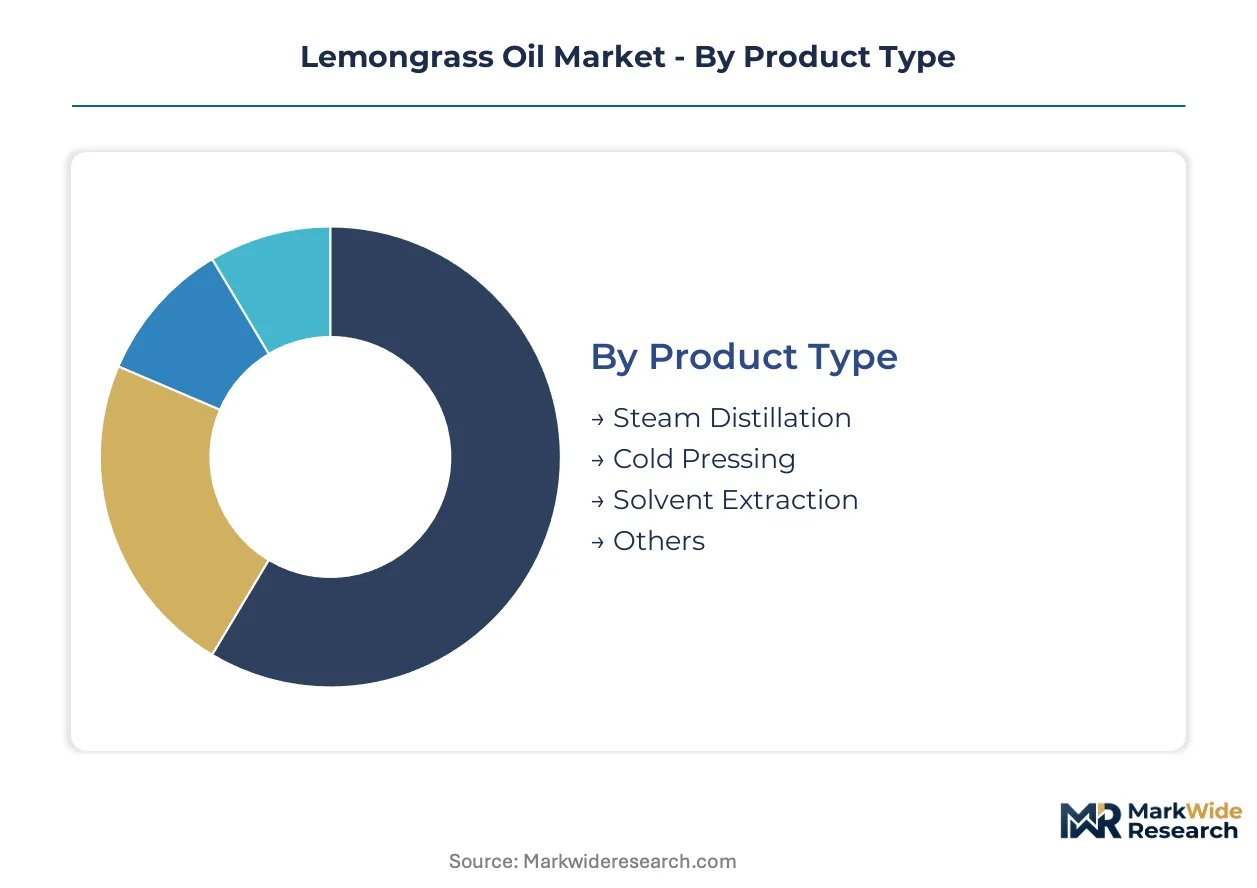
Segmentation in lemongrass oil separates commodity-grade distillers from specification-driven suppliers. Product type and application boundaries determine margin capture, regulatory exposure, and customer loyalty across fragmented demand pools.
Product Type:
Use-case spectrum spans industrial citral recovery to heat-sensitive cosmetic preservation, with extraction method directly governing specification grade and end-market access.
- Steam Distillation:Thermal processing of Cymbopogon biomass yields citral concentrations of 70-85% at commercial scale. Cost efficiency dominates fragrance compounder procurement in Grasse and Geneva, though energy price volatility compresses processor margins during fuel cost cycles.
- Cold Pressing:Mechanical expression without thermal degradation preserves heat-labile terpenes for premium skincare formulations. Luxury cosmetic houses in France and Switzerland command precise citral-to-geraniol ratios that this method delivers, expanding most quickly among clean-label personal care brands.
- Solvent Extraction:Organic solvent recovery of non-volatile compounds serves flavoring applications in food manufacturing.
- Others:Supercritical CO2 and hybrid extraction trains serve niche pharmaceutical-grade specifications.
Established volume favors steam distillation; emerging adoption favors cold pressing.
Application:
Margin structure varies sharply across application tiers, with pharmaceutical-grade specifications commanding analytical certification premiums unavailable to commodity fragrance suppliers.
- Cosmetics:Natural preservative systems in skincare and haircare drive citral substitution for synthetic antimicrobials. Personal care formulators in Germany and France require REACH-compliant traceability documentation, filtering out uncertified distillers from premium supply chains.
- Aromatherapy:Spa centers and wellness service providers build direct procurement relationships with Kerala-based distillers, bypassing traditional distribution. This channel climbs the fastest as experiential wellness services expand in urban India and Southeast Asian metros.
- Food & Beverage:Flavoring applications in beverages and confectionery demand FSSAI and FDA compliance for ingestible-grade oil.
- Pharmaceuticals:Antimicrobial and antifungal therapeutic applications require batch-to-batch citral standardization that strains smallholder cooperative capacity.
Cosmetics anchors current revenue; aromatherapy gains share fastest.
End User:
Procurement sophistication divides end users between spot-market purchasers and contract-integrated buyers with agronomic audit requirements.
- Personal Care Brands:Mid-sized natural cosmetics manufacturers displace spot purchasing with direct farm contracting for clean-label claim substantiation. German and French specialty retailers audit supplier cultivation practices, compressing qualification cycles for export-oriented Indian distillers.
- Spa Centers:Aromatherapy service providers source directly from Tamil Nadu and Kerala cultivation belts, eliminating distributor markups. This segment shows steepest expansion trajectory as wellness tourism infrastructure develops in Kerala and Goa.
- Food Manufacturers:Beverage and flavoring houses prioritize cost-competitive citral sourcing over organic certification.
- Health Clinics:Ayurvedic and integrative medicine practitioners require therapeutic-grade specifications with documented heavy metal and pesticide screening.
Personal care brands dominate formal procurement; spa centers drive channel innovation.
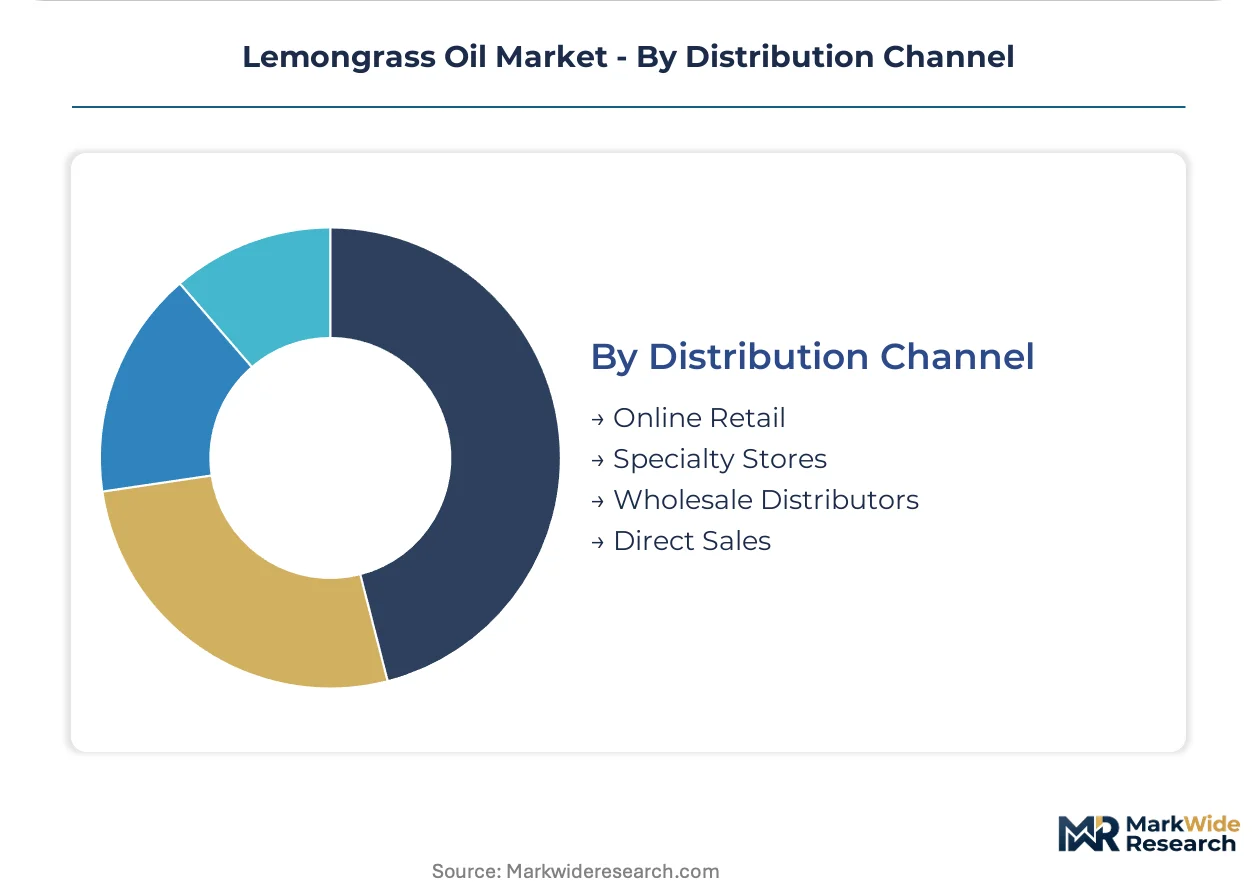
Distribution Channel:
Channel selection determines margin retention and customer data access, with direct models capturing traceability premiums unavailable to wholesale intermediaries.
- Direct Sales:Farm-to-brand contracting enables cultivation practice documentation for clean-label claims. Specialty retailers in German and French natural cosmetics markets require verified agronomic inputs that direct relationships provide.
- Online Retail:E-commerce platforms serve small-batch aromatherapy and DIY cosmetic formulators with certified organic grades. This channel expands most quickly among United States specialty consumers seeking USDA organic verification.
- Wholesale Distributors:Aggregated volume sales to fragrance compounders and industrial buyers prioritize specification consistency over traceability.
- Specialty Stores:Brick-and-mortar natural products retailers curate certified organic and fair-trade assortments for premium positioning.
Wholesale distributors retain volume leadership; direct sales and online retail capture margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian distillers capture 35-40% price premiums over Southeast Asian competitors through organic certification and BIS compliance, while United States buyers absorb transport costs to secure Kerala-origin supply with USDA verification.
India
Kerala and Tamil Nadu cultivation belts supply dominant global volumes through traditional steam distillation clusters. BIS standards for essential oil purity and FSSAI oversight of food-grade extracts filter informal producers from formal export channels. Coimbatore and Kochi processing hubs concentrate backward-integrated distillers serving European and North American personal care brands.
United States
Specialty retailers and personal care formulators drive demand for USDA organic and fair-trade certified grades. FDA oversight of cosmetic ingredient safety and FTC natural claim substantiation requirements elevate documentation burdens on importers. California-based natural products distributors and Utah Valley essential oil processors anchor domestic formulation activity.
Germany
Fragrance compounders in Grasse and natural cosmetics manufacturers prioritize REACH-compliant traceability documentation. ECHA authorization deadlines compress procurement qualification cycles for Indian distillers. Hamburg and Frankfurt trading houses mediate bulk sourcing for industrial citral recovery applications.
France
Luxury skincare houses command precise citral-to-geraniol ratios through cold pressing and hybrid extraction specifications. ANSM cosmetic safety assessments and EU Green Deal sustainability mandates shape supplier selection criteria. Grasse fragrance cluster concentrates premium-tier formulation demand.
Switzerland
Geneva-based fragrance compounders and pharmaceutical-grade buyers impose batch-to-batch citral standardization requirements. Swissmedic therapeutic-grade specifications strain smallholder cooperative capacity. Basel chemical trading corridor anchors industrial citral procurement for synthetic substitution comparison.
Lemongrass Oil Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in cultivation and distillation. The supplier base concentrates around certified organic producers with traceable supply chains, while informal distillers face exclusion from REACH and FDA-regulated markets. Three archetypes dominate: backward-integrated farm-to-bottle operators, contract distillation service providers, and specialty retail channel curators. Competitive moves center on direct farm contracting for traceability documentation and supercritical CO2 technology licensing for premium cosmetic specifications.
Among United States-based platform operators, NOW Foods exemplifies captive supply chain control from sourcing through bottling. AG Organica occupies a position representing deep backward integration into Indian organic cultivation belts. Mountain Rose Herbs anchors the specialty retail curator archetype through certified organic and fair-trade supply chain positioning in premium channels.
| Leading Market Players |
|---|
| Edens Garden |
| NOW Foods |
| AG Organica |
| Plant Therapy Essential Oils |
| Phoenix Aromas & Essential Oils |
| Aura Cacia |
| Mountain Rose Herbs |
| Young Living Essential Oils |
| doTERRA |
| Others |
Cost & Logistics Intelligence
Overcapacity in Kerala-Tamil Nadu steam distillation clusters compresses spot-market margins while concentrating pricing power among BIS-compliant exporters serving REACH-regulated European buyers. This utilization asymmetry forces informal distillers toward domestic offtake or contract manufacturing, reshaping tier boundaries across the value chain.
Pricing Analysis
The customization-premium spread separates cold-pressed cosmetic grades from commodity steam-distilled volumes, with citral-to-geraniol ratio precision commanding substantial markups from Grasse fragrance houses. Three-tier pricing structure across premium organic-certified, standard BIS-compliant, and economy spot-market grades reflects certification depth and traceability documentation. Pricing pressure stems from synthetic citral substitution by BASF and petrochemical compounders in industrial fragrance applications. Food manufacturers exhibit highest price sensitivity, while Swiss pharmaceutical-grade buyers absorb premiums for batch-to-batch standardization.
Supply Chain Analysis
Monsoon exposure across Kerala and Tamil Nadu cultivation belts dominates supply chain risk, with rainfall volatility triggering raw material price spikes that propagate through Coimbatore and Kochi processing hubs. Geographic concentration in southern India draws from Cymbopogon flexuosus biomass, fuel oil for thermal processing, and analytical certification services. Single-source vulnerability concentrates in Kerala-origin organic supply chains serving USDA-verified United States buyers. Distribution runs through direct farm-to-brand contracting for traceability documentation, alongside wholesale fragrance compounder channels prioritizing volume over provenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in mid-tier personal care brands abandoning spot procurement for verified agronomic partnerships, creating niches for specification-grade suppliers with analytical certification capabilities.
For Market Incumbents: Build traceability moats through captive organic farmland conversion and third-party analytical certification investment. Secure BIS and REACH compliance documentation ahead of ECHA authorization deadlines to filter uncertified competitors. Deepen backward integration into Tamil Nadu cultivation cooperatives to defend margin position against energy cost cycles and monsoon volatility. For New Entrants and Emerging Players: Pursue asset-light contract distillation services for mid-tier United States personal care brands seeking Kerala-origin supply with USDA organic verification. Target German and French natural cosmetics markets where clean-label claim substantiation requirements compress incumbent qualification cycles. Leverage supercritical CO2 technology licensing to penetrate premium cosmetic specifications demanding precise terpene fractionation. For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated farm-to-bottle operators with established BIS compliance and European market access. Long-term viability hinges on regulatory convergence around natural claim substantiation and traceability mandates. Monitor REACH authorization timeline compression as inflection signal for compliant distiller valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | Three-year farmland conversion timelines strain smallholder working capital, filtering informal producers from premium channels. |
| Supercritical CO2 Technology Licensing | Hybrid extraction trains enable selective terpene fractionation for Grasse luxury skincare houses demanding precise citral ratios. |
| Direct Farm-to-Brand Contracting | Specialty retailers in German and French markets audit supplier agronomic practices, compressing qualification cycles for export-oriented distillers. |
| Third-Party Analytical Certification | ECHA compliance deadlines force downstream cosmetic manufacturers to document full supply chain substance volumes for REACH authorization. |
| Spa Center Channel Expansion | Wellness tourism infrastructure development in Kerala and Goa enables aromatherapy service providers to bypass traditional distribution markups. |
Research Approach
A standing panel of Kerala-based distillation plant managers, European fragrance compounder procurement leads, United States natural products category buyers, and FSSAI regulatory affairs specialists provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders alongside secondary validation through BIS essential oil standards documentation, ECHA REACH substance registration databases, USDA organic certification records, and United States customs import filings. Bottom-up volume triangulation from cultivation belt surveys converged with top-down demand estimation from personal care brand procurement disclosures.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling spanning extraction method tiers, application-grade specifications, end-user procurement sophistication levels, and regional regulatory clusters. CAGRs derived from historical price-volume elasticity analysis and forward-looking capacity expansion announcements in Coimbatore and Kochi processing hubs. Industry-specific forecast inputs incorporated monsoon variability indices and energy cost cycle assumptions for steam distillation economics.
Sensitivities concentrate around REACH authorization timeline extensions, synthetic citral substitution rates in industrial fragrance applications, and organic certification conversion success rates among Tamil Nadu smallholder cooperatives. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Cassia Seed Extract Market
Extracts
Global Rose Oils Market
Extracts
Asia-Pacific Spirulina Extract Market
Extracts
Global Azadirachtin Market
Extracts
Chamomile Oil Market
Extracts
Salvia Miltiorrhiza Extract Market
Extracts
Eucommia Extract Market
Extracts
Natural Rosemarine Extract Market
Extracts
Lavender Oil Market
Extracts
Botanical CO2 Extracts Market
Extracts
Ovalbumin Powder Market
Extracts
Nootkatone Market
Extracts
Gelatin Hydrolysates Market
Extracts
Cassia Extract Market
Extracts
Pectin Powder Market
Extracts
Industrial Extractor Market