
 Home Audio Equipment Market | 2026-2036
Home Audio Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Home Audio Equipment Market Analysis
The capability gap between mass-market assemblers and vertically integrated acoustic engineering houses is collapsing as semiconductor commoditization erodes historical moats. Samsung Electronics leverages captive display-audio bundling to sustain living-room dominance across multiple price tiers. Harman International anchors its position through automotive-to-home brand extension, while Sonos differentiates via proprietary mesh networking that locks households into ecosystem upgrades.
Home audio equipment encompasses electroacoustic transducers, signal amplification circuits, and enclosure systems engineered to reproduce recorded sound within residential environments, with frequency response, total harmonic distortion, and driver array configuration serving as critical performance parameters. Soundbars now occupy the largest revenue pool as consumers prioritize space-efficient cinematic audio over discrete component systems. Wireless and Wi-Fi segments are expanding fastest as streaming-native households abandon physical interconnects, while wired configurations retain entrenched demand among audiophile subsegments seeking uncompressed signal integrity.
The FCC governs radio-frequency emissions for wireless audio devices in the United States, while the EU's RoHS and REACH frameworks restrict hazardous substances in driver magnets and circuit board substrates, elevating compliance costs for imported equipment. China's SAMR enforces GB standards for electromagnetic compatibility that manufacturers must satisfy for market access. Stakeholders must monitor regulatory divergence around right-to-repair mandates and emerging energy-efficiency labeling requirements that could reshape product design priorities and regional competitive dynamics.
Market Dynamics
Semiconductor commoditization is collapsing the traditional capability gap between mass-market assemblers and vertically integrated acoustic engineering houses, forcing incumbents to defend positions through ecosystem lock-in and captive bundling strategies.
Growth Catalysts
- Wireless Protocol Maturation:Wi-Fi 6E and Matter compatibility eliminate interoperability friction for streaming-native households. United States residential consumers upgrade living-room configurations at accelerating replacement cycles.
- REACH and RoHS Compliance:European hazardous substance frameworks elevate design standards for driver magnets and circuit substrates. Premium manufacturers capture margin premiums through certified sustainable supply chains.
- Spatial Audio Processing:Dolby Atmos and MPEG-H decoding hardware penetrates mid-tier soundbar configurations. Content streaming platforms mandate immersive audio for original programming.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings destabilize driver unit economics. Chinese mining concentration creates single-source vulnerability for enclosure manufacturers.
- GB Standard Certification Burden:China's SAMR electromagnetic compatibility testing extends product launch timelines. Imported equipment faces mandatory retesting for market access.
- Smart Speaker Substitution:Voice-activated assistants satisfy casual listening needs without dedicated audio investment. Amazon Alexa and Google Assistant ecosystems capture ambient audio demand.
Strategic Opportunities
- India Residential Penetration:Urban middle-class expansion creates first-time buyer pools for compact wireless systems. Local assembly incentives under PLI schemes reduce landed cost structures.
- Automotive-to-Home Brand Extension:Harman, Bose, and Bowers & Wilkins leverage cabin audio credibility for residential premium positioning. Shared acoustic engineering reduces R&D duplication.
- Right-to-Repair Mandates:Emerging European and US state-level legislation requires modular driver replacement and firmware longevity. Serviceable designs differentiate against sealed disposable competitors.
Industry Challenges
- Acoustic Engineering Talent Scarcity:DSP algorithm development and enclosure simulation expertise concentrates in legacy audio hubs. Compensation inflation strains mid-tier manufacturer R&D budgets.
- Multi-Protocol Integration Complexity:Simultaneous support for AirPlay 2, Chromecast, Spotify Connect, and proprietary mesh networks expands firmware validation matrices. Quality assurance timelines extend proportionally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Audio Equipment Market |
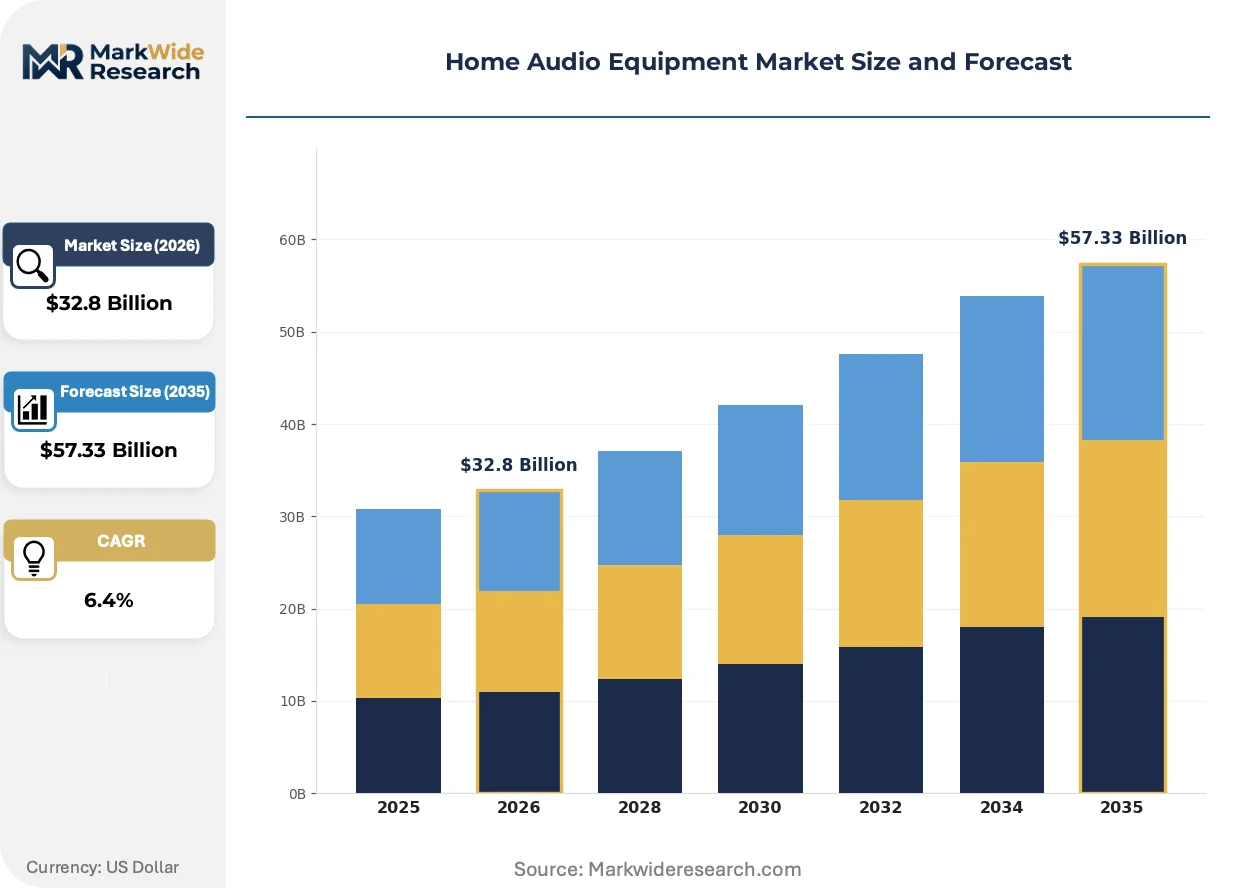
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Speakers, Amplifiers, Soundbars, Subwoofers Technology: Wired, Wireless, Bluetooth, Wi-Fi End User: Consumers, Audiophiles, Professionals, Retailers Distribution Channel: Online, Offline, Direct Sales, Resellers |
| Companies Covered | Samsung Electronics, Harman International, Sonos, Yamaha Corporation, Bowers & Wilkins, Sony, Panasonic, LG Electronics, Bose, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Audio Equipment Market Emerging Trajectories
Active acoustic processing and wireless connectivity standards are fragmenting historical product categories while regulatory pressure on materials and energy efficiency rewrites design priorities.
Beamforming and adaptive room-correction DSP is bifurcating the performance tier structure. Entry-level soundbars now ship with microphone-array calibration previously reserved for flagship configurations. This compression collapses premium positioning for standalone acoustic processors.
EU energy-efficiency labeling requirements under the Ecodesign for Energy-related Products framework now cover networked audio equipment. Manufacturers must disclose standby power consumption and networked standby modes. Germany and France lead enforcement, with retailers delisting non-compliant SKUs from autumn compliance deadlines.
Direct-to-consumer subscription bundling disrupts traditional electronics retail channels. Sonos and Bluesound integrate hardware financing with streaming service trials. United States urban millennials demonstrate highest attachment to unbundled purchase journeys, bypassing big-box showroom validation.
Home Audio Equipment Market Segmentation
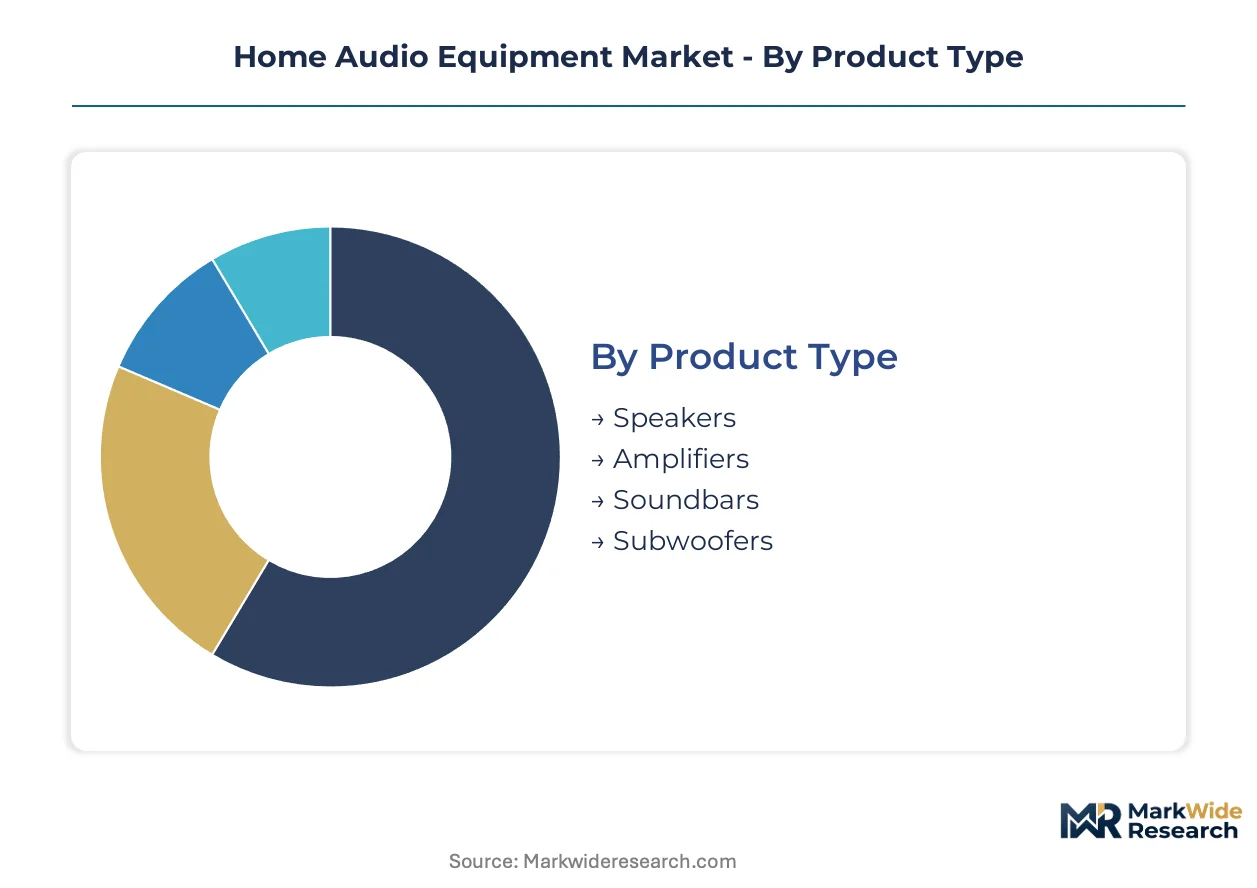
Home audio equipment segmentation reveals how acoustic engineering investments concentrate differently across product architectures, connectivity protocols, and buyer sophistication tiers. Manufacturers calibrate R&D allocation by tracking which configurations capture margin premiums versus volume throughput.
Product Type:
Margin pools concentrate in integrated systems that bundle amplification with acoustic output, reducing consumer assembly complexity.
- Soundbars:Integrated amplification and driver arrays in linear enclosures dominate living-room installations. United States residential consumers prioritize space-efficient cinematic audio, driving replacement cycles shorter than traditional component systems.
- Speakers:Discrete electroacoustic transducers range from bookshelf to floor-standing configurations. Audiophile subsegments in Germany sustain demand for passive driver systems requiring external amplification.
- Amplifiers:Signal amplification circuits span Class D efficiency-focused designs to Class A/B linear topologies. Vinyl resurgence sustains niche demand for phono preamplification stages.
- Subwoofers:Dedicated low-frequency enclosures extend bass response below 80Hz. Home theater configurations in China increasingly specify dual-subwoofer setups for spatial uniformity.
Soundbars hold installed capacity. Subwoofers are rotating up the share rankings.
Technology:
Volume leadership has shifted toward protocols eliminating physical interconnects, though signal integrity requirements sustain wired demand in specific applications.
- Wi-Fi:IEEE 802.11-based streaming enables whole-home audio synchronization with lossless codec support. United States households with streaming-native consumption patterns drive multi-room system adoption.
- Wireless:Proprietary RF protocols and mesh networking architectures create ecosystem lock-in. Sonos and Bluesound leverage proprietary implementations to sustain recurring hardware upgrade cycles.
- Bluetooth:Short-range codec transmission dominates portable and entry-level stationary applications. Codec limitations at range extremes constrain audiophile acceptance.
- Wired:Analog and digital physical interconnects preserve uncompressed signal paths. Germany and Japan sustain entrenched demand among measurement-focused enthusiasts.
Wi-Fi configurations are climbing the fastest. Bluetooth retains volume leadership in entry-tier price bands.
End User:
Buyer sophistication stratifies purchasing criteria from convenience-driven casual listening to measurement-verified acoustic performance.
- Consumers:General residential purchasers prioritize installation simplicity and streaming service integration. United States mass-market retail channels capture this volume tier.
- Audiophiles:Performance-focused buyers evaluate frequency response linearity and distortion specifications. Germany and Japan host concentrated communities driving premium component demand.
- Professionals:Content creators and studio engineers require reference-grade monitoring accuracy. Post-production facilities in Los Angeles and London specify calibrated nearfield systems.
- Retailers:Commercial audio installers and custom integration specialists specify distributed systems. High-end residential projects in Dubai and Singapore drive multi-zone architectural audio.
Consumer tier holds installed capacity. Audiophile segment is rotating up the share rankings.
Distribution Channel:
Channel selection determines margin capture versus customer acquisition cost tradeoffs, with direct models gaining efficiency in digitally native buyer segments.
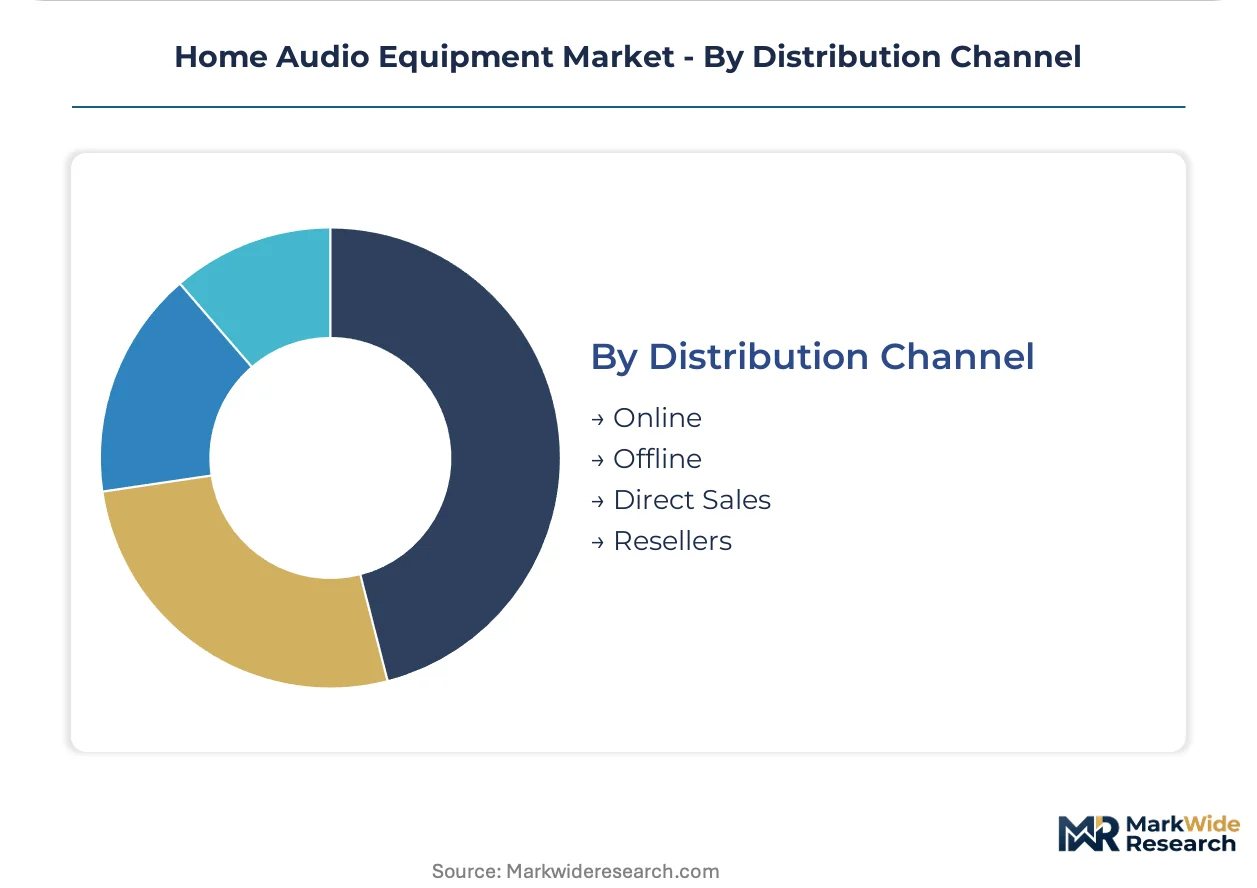
- Online:E-commerce platforms and brand-direct storefronts bypass retail markup layers. United States urban millennials demonstrate highest attachment to unbundled purchase journeys.
- Direct Sales:Manufacturer-owned channels enable subscription bundling with streaming services. Sonos integrates hardware financing with service trials.
- Offline:Big-box electronics retailers and specialty audio salons provide tactile evaluation environments. Germany's MediaMarkt Saturn and Japan's Bic Camera sustain showroom traffic.
- Resellers:Third-party distributors and value-added resellers serve commercial integration projects. Custom installation firms in California and Florida specify through regional distribution.
Offline channels hold installed capacity. Online is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium audio equipment commands pricing power in Germany that mass-market configurations in India cannot replicate, creating a regional margin asymmetry that shapes manufacturer portfolio allocation. This divergence concentrates R&D investment toward Western European and North American specifications while compressing entry-tier margins elsewhere.
United States
Residential consumers upgrade living-room soundbars at accelerating replacement cycles driven by streaming-native consumption patterns. The FCC governs radio-frequency emissions for wireless audio devices, mandating certification for Wi-Fi and Bluetooth implementations. Los Angeles hosts concentrated post-production facilities specifying calibrated nearfield monitoring systems for content creators.
Germany
Audiophile subsegments sustain entrenched demand for passive driver systems requiring external amplification and measurement-verified performance. The EU's Ecodesign for Energy-related Products framework imposes standby power disclosure requirements on networked audio equipment. Berlin-Brandenburg clusters specialty audio engineering talent for DSP algorithm development.
China
Urban middle-class expansion drives home theater configurations specifying dual-subwoofer setups for spatial uniformity. SAMR enforces GB standards for electromagnetic compatibility that extend product launch timelines for imported equipment. The Pearl River Delta concentrates enclosure manufacturing capacity facing rare earth magnet price volatility.
Japan
Measurement-focused enthusiasts preserve demand for wired analog and digital interconnects preserving uncompressed signal paths. METI oversees industrial standards coordination affecting audio equipment efficiency labeling. Tokyo anchors legacy acoustic engineering hubs where DSP and enclosure simulation expertise concentrates.
India
Urban middle-class expansion creates first-time buyer pools for compact wireless systems bypassing discrete component traditions. PLI schemes for local assembly reduce landed cost structures for multinational brands. Maharashtra and Karnataka host emerging electronics manufacturing clusters serving domestic consumption.
Home Audio Equipment Market Vendor Landscape
Concentration sits with diversified electronics conglomerates and specialized acoustic engineering houses. Samsung Electronics leverages captive display-audio bundling across multiple price tiers, while Harman International anchors position through automotive-to-home brand extension. Three archetypes dominate: vertically integrated conglomerates with captive semiconductor supply, specialized acoustic engineering houses with heritage transducer expertise, and streaming-native ecosystem builders with proprietary mesh networking. Competitive moves center on ecosystem lock-in through proprietary wireless protocols and automotive audio credibility extension into residential markets.
Among diversified electronics conglomerates, Samsung Electronics and LG Electronics occupy positions sustained by captive supply chain integration and living-room bundling power. Sony and Panasonic represent Japanese heritage players with transducer engineering depth spanning professional and consumer applications. Sonos exemplifies the streaming-native ecosystem archetype, locking households into proprietary mesh networking architectures that drive recurring hardware upgrade cycles.
| Leading Market Players |
|---|
| Samsung Electronics |
| Harman International |
| Sonos |
| Yamaha Corporation |
| Bowers & Wilkins |
| Sony |
| Panasonic |
| LG Electronics |
| Bose |
| Others |
Supply Flow & Price Mechanics
Enclosure manufacturing scale in China's Pearl River Delta compresses unit economics for mass-market soundbar producers while elevating price floors for boutique acoustic engineering houses in Germany and Japan. This divergence concentrates margin capture among vertically integrated conglomerates with captive driver production, forcing specialized brands to defend premium positioning through certification investments and configured-to-order fulfillment.
Pricing Analysis
Configured-to-order pricing for reference-grade passive speaker systems commands spreads exceeding standard soundbar SKUs by factors reflecting driver array complexity and enclosure material selection. Three-tier pricing structure across premium, standard, and economy levels stratifies by amplification topology and wireless protocol support, with Class D efficiency designs facing compression from semiconductor commoditization. Cost compression in entry-tier Wi-Fi configurations is intensifying because streaming-native households prioritize ecosystem compatibility over acoustic specifications. Consumer-tier mass-market buyers exhibit highest price sensitivity, while German and Japanese audiophile segments demonstrate inelastic demand for measurement-verified performance.
Supply Chain Analysis
Rare earth magnet processing concentration in China's Inner Mongolia and Jiangxi provinces creates single-source vulnerability for neodymium-dysprosium alloys essential to high-excursion driver motors. Driver magnet assemblies, Class D amplifier chipsets, and MDF enclosure substrates draw from geographically dispersed supplier bases spanning Malaysia, Vietnam, and Taiwan. Tariff exposure on finished electronics imports into the United States and European Union elevates landed cost structures for non-localized assembly. Distribution runs through a hybrid model combining direct-to-consumer brand storefronts with big-box retail partnerships in North America and specialty audio salons in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DSP algorithm development and enclosure simulation expertise concentrates in legacy audio hubs, creating acquisition premiums for engineering talent pools that mid-tier manufacturers cannot replicate internally. This scarcity elevates strategic value for firms with captive acoustic R&D capabilities.
For Market Incumbents: Consolidate ecosystem lock-in through proprietary mesh networking architectures that increase household switching costs, while acquiring specialized DSP engineering teams in Berlin-Brandenburg and Tokyo to offset talent scarcity. Smart speaker substitution from Amazon Alexa and Google Assistant ecosystems threatens ambient audio demand, requiring defensive bundling with streaming service trials to sustain replacement cycles. For New Entrants and Emerging Players: After-sales firmware longevity and modular driver replacement services represent underserved white-space where sealed disposable competitors face emerging right-to-repair mandates in European and select US state jurisdictions. India's urban middle-class expansion offers the most penetrable geography for compact wireless systems, with local assembly incentives under PLI schemes enabling cost-competitive entry. Direct-to-consumer subscription bundling with regional streaming platforms provides differentiated go-to-market positioning against established retail-channel incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors streaming-native ecosystem builders with proprietary wireless protocols over legacy component manufacturers dependent on discrete system sales. Long-term viability across the analysis window rests on recurring hardware upgrade cycles rather than transactional replacement demand. Acquisition targets should demonstrate captive acoustic engineering depth and automotive audio credibility extension potential. The signal to monitor is Matter protocol adoption velocity, which could erode proprietary mesh networking moats if interoperability friction collapses.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-to-Home Brand Extension | Harman, Bose, and Bowers & Wilkins leverage cabin audio credibility for residential premium positioning. |
| Proprietary Mesh Networking Investment | Sonos locks households into ecosystem architectures that drive recurring hardware upgrade cycles. |
| Right-to-Repair Modular Design | Serviceable driver replacement and firmware longevity differentiate against sealed disposable competitors. |
| Local Assembly Under PLI Schemes | Maharashtra and Karnataka manufacturing clusters reduce landed cost structures for India market entry. |
| Spatial Audio Processing Integration | Dolby Atmos and MPEG-H decoding hardware penetration into mid-tier soundbar configurations captures streaming platform mandates. |
Methodological Framework
Operator-level perspectives from acoustic engineering directors, consumer electronics procurement leads, specialty audio retail buyers, and streaming platform hardware partnership managers anchored the qualitative base for this study. Primary interview insights combined with secondary validation against FCC equipment authorization databases, EU Ecodesign regulatory filings, SAMR GB standard certification records, and SEC 10-K disclosures from listed electronics conglomerates. Bottom-up demand modeling across product type, connectivity protocol, and buyer sophistication tiers triangulated with top-down market sizing from trade flow analysis.
Sensitivity analysis around rare earth magnet price volatility, Wi-Fi protocol adoption curves, and regulatory enforcement timelines shaped scenario boundaries across the projection horizon. Segmentation dimensions modeled include product architecture, wireless connectivity standard, end-user sophistication tier, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis, installed base penetration rates, and premium tier mix shift assumptions. Forecast inputs incorporated streaming-native household formation patterns and spatial audio content availability expansion.
Forecasts assume regulatory continuity in FCC emissions governance, EU RoHS and REACH hazardous substance frameworks, and China's SAMR electromagnetic compatibility enforcement; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as right-to-repair mandate expansion and energy-efficiency labeling enforcement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Audio Equipment
India Consumer Speaker Market
Audio Equipment
Professional Audio-Visual Systems Market
Audio Equipment
India Gaming Headset Market
Audio Equipment
Audio Equipment Market
Audio Equipment
Global Automotive Premium Audio System Market
Audio Equipment
High-End Audiophile Speakers Market
Audio Equipment
Europe Audio Products Market
Audio Equipment
In Car Audio System Market
Audio Equipment
India Wireless Audio Market
Audio Equipment
Global Networked Audio Products Market
Audio Equipment
India Wireless Speaker Market
Audio Equipment
Portable Audio Amplifier Market
Audio Equipment
United States Gaming Headsets Market
Audio Equipment
Wireless Audio Devices Market
Audio Equipment
Soundbar Market
Audio Equipment
Germany Radio Headset Market