
 Sports Trading Card Market | 2026-2036
Sports Trading Card Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Trading Card Market Outlook
US print houses and licensed manufacturers is repositioning supply chains toward direct-to-consumer authentication bundles. Topps leverages exclusive league licenses to sustain premium release calendars. Panini anchors European football card production through centralized Italian printing operations. Upper Deck competes in hockey memorabilia with proprietary foil-stamping technology.
Sports trading cards are rectangular cardstock collectibles, typically measuring 2.5 by 3.5 inches, featuring athlete imagery, statistical data, and serialized numbering, produced through offset lithography or digital presses with UV coating for archival preservation. Their commercial purpose centers on fan engagement, speculative investment, and secondary market arbitrage. Vintage cards command the deepest liquidity pools among product type segments as scarcity-driven auction volumes concentrate in high-grade specimens. Online marketplaces within distribution channel segments are capturing incremental transaction flow from legacy retail stores as real-time price discovery tools proliferate.
FDA guidelines on ink and adhesive materials influence card manufacturing safety standards for youth-oriented products, while FTC regulations on collectible investment claims constrain dealer marketing practices. ISO 9001 quality management protocols shape third-party grading laboratory accreditation criteria. Stakeholders must monitor evolving authentication technology standards and grading consistency benchmarks as counterfeiting sophistication escalates.
Market Dynamics
Authentication infrastructure investments are restructuring competitive advantage in sports trading cards, as grading laboratory capacity and blockchain verification protocols determine which platforms capture secondary market liquidity.
Growth Catalysts
- Third-party grading standardization:ISO 9001 protocols are expanding laboratory accreditation across collector investment platforms, reducing information asymmetry in high-value transactions.
- Direct-to-consumer authentication bundles:US print houses are integrating UV coating verification with serialized digital registries, compressing arbitrage windows for counterfeit specimens.
- Fan engagement platform convergence:Real-time price discovery tools embedded in online marketplaces are accelerating transaction velocity beyond legacy retail channels.
Market Restraints
- Specialized substrate concentration:Archival-grade cardstock supply concentrates among North American specialty paper mills, exposing manufacturers to input cost volatility.
- Counterfeiting sophistication escalation:High-resolution digital reproduction technologies are degrading visual authentication reliability for vintage specimens.
- FTC investment claim constraints:Dealer marketing practices face heightened scrutiny under collectible investment disclosure rules, limiting speculative positioning language.
Strategic Opportunities
- EU cross-border resale transparency:The Consumer Rights Directive is creating compliant infrastructure for pan-European auction liquidity pools.
- Blockchain-physical convergence:Non-fungible token registries paired with smart contract escrow are emerging as verification layers for high-grade inventory.
- Youth product safety tailwinds:FDA guidelines on ink and adhesive materials are prompting certified manufacturing line investments that differentiate compliant producers.
Industry Challenges
- Grading consistency talent scarcity:Condition assessment expertise concentrates among veteran examiners, constraining laboratory throughput scaling.
- Legacy inventory digitization friction:Pre-digital era card databases require manual reconciliation with emerging authentication platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Trading Card Market |
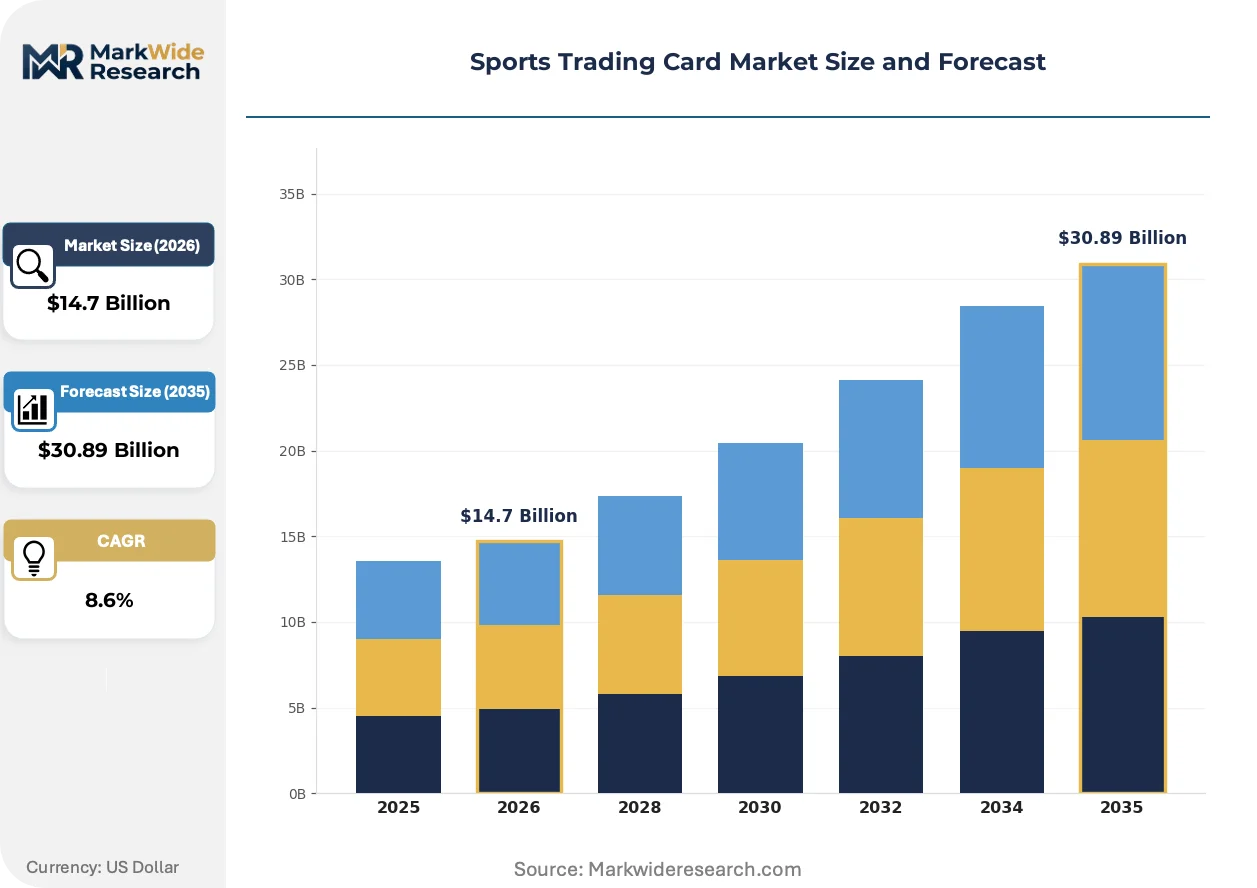
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Sport Cards, Vintage Cards, Autographed Cards, Inserts Condition: Mint, Near Mint, Good, Poor Distribution Channel: Retail Stores, Online Marketplaces, Auctions, Trade Shows End User: Collectors, Investors, Hobbyists, Dealers |
| Companies Covered | Topps, Panini, Upper Deck, Fanatics, Leaf Trading Cards, Donruss, Goldin Auctions, Market Movers, Trading Card Market, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Trading Card Market Strategic Shifts
Digital verification protocols are displacing manual provenance tracking across the sports trading card value chain, while regulatory frameworks on investment disclosures and material safety reshape operational compliance burdens.
Machine vision grading systems are automating condition assessment workflows previously requiring human examiner consensus. Major auction houses and authentication laboratories are deploying high-resolution imaging arrays with defect-pattern recognition algorithms. This compression of subjective evaluation timelines is automating throughput bottlenecks that historically constrained laboratory capacity expansion.
FTC regulations on collectible investment claims are tightening dealer marketing compliance requirements. The framework mandates specific disclosure protocols for speculative value projections and historical performance representations. High-volume resale platforms targeting US collectors are restructuring listing templates and educational content to preempt enforcement exposure.
Collector procurement patterns are fragmenting across specialized vertical platforms rather than consolidating through generalist marketplaces. Dedicated sports card applications with integrated price indexing and community verification are displacing legacy classified listings and informal trading forums. This channel disintermediation is most pronounced among millennial and Generation Z demographics in North American urban markets.
Sports Trading Card Market Segmentation
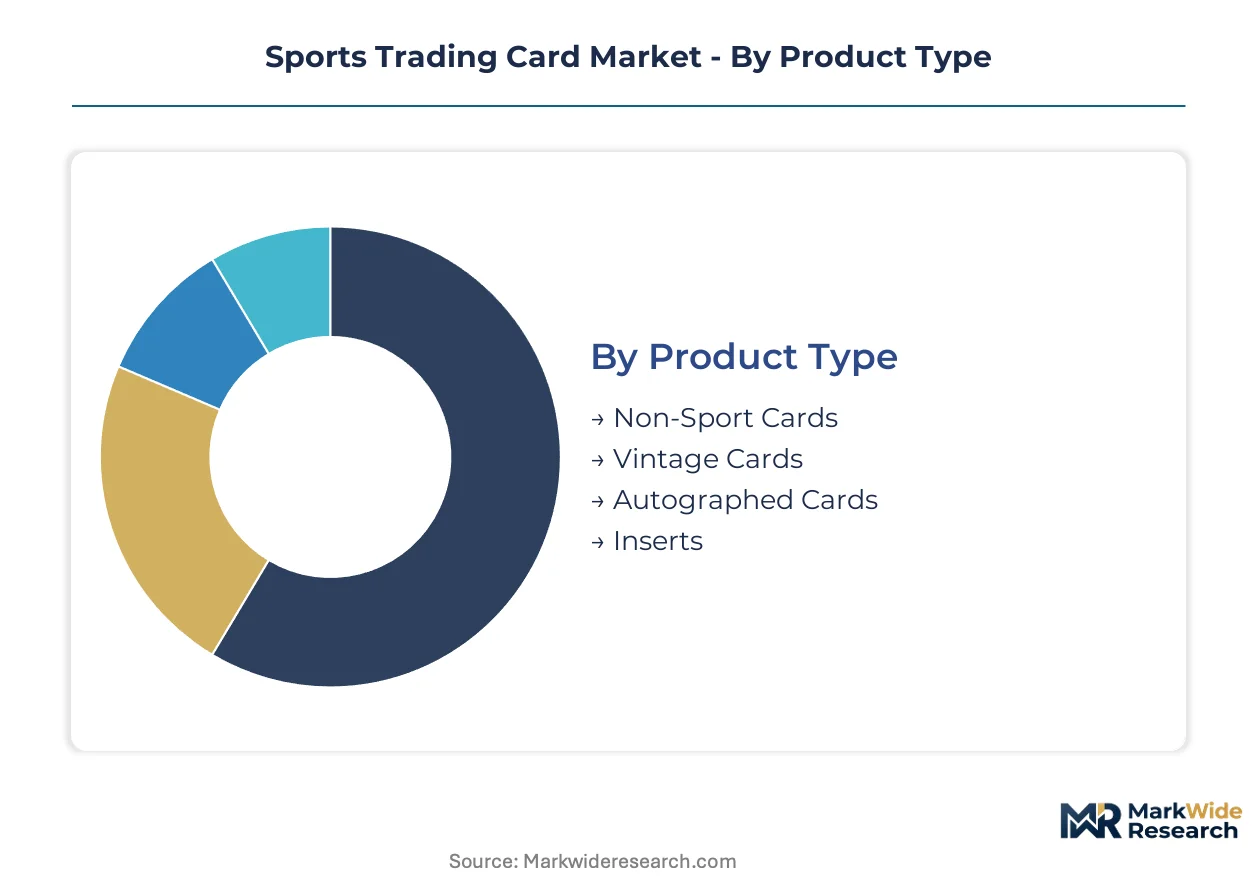
Sports trading card segmentation reveals how authentication infrastructure, liquidity mechanisms, and buyer sophistication stratify across distinct product tiers and transaction channels. Condition grading and distribution format selection determine price discovery efficiency and investment-grade accessibility for different collector profiles.
Product Type:
The customization-to-standardization spectrum runs from mass-produced contemporary inserts to individually authenticated vintage specimens with documented provenance chains.
- Vintage Cards:Pre-1980 cardstock issues with established scarcity metrics and population reports from third-party grading laboratories. Auction liquidity concentrates in specimens graded Mint 9 or higher, where condition premiums exceed raw card multiples by the widest margins.
- Autographed Cards:Hand-signed specimens requiring dual authentication of both the underlying card and the signature itself through witnessed signing protocols or forensic handwriting analysis. Demand clusters in rookie-year signatures of Hall of Fame inductees where on-card autographs command substantial premiums over sticker-applied alternatives.
- Inserts:Limited-run parallel designs embedded within base product releases, typically serial-numbered to establish artificial scarcity. These chase elements drive pack-ripping velocity for manufacturers.
- Non-Sport Cards:Entertainment and pop culture issues featuring film, television, or gaming intellectual property rather than athletic subjects. This segment attracts crossover collectors from adjacent hobby verticals.
Most installed capacity flows through Inserts as manufacturers embed scarcity mechanics within high-volume base releases. Expansion is steepest in Autographed Cards as witnessed signing protocols and blockchain verification layers extend authentication trust.
Condition:
Grading tier selection maps directly to investment intent, with cost thresholds filtering casual collectors from institutional-grade inventory accumulation.
- Mint:Flawless specimens exhibiting perfect centering, sharp corners, and surface integrity under 10x magnification. These population-scarce grades anchor seven-figure auction transactions and collateralized lending pools.
- Near Mint:Minor imperfections visible only upon close inspection, representing the optimal entry point for appreciation-seeking collectors balancing condition with acquisition cost. Volume concentrates here as grading standards tighten and borderline submissions face downgrades.
- Good:Moderate wear acceptable to completionists prioritizing set registry participation over investment returns. Pricing reflects substantial discounts to higher grades.
- Poor:Heavy creasing, paper loss, or staining that nonetheless preserves card identity for historical documentation purposes. Demand is limited to pre-war rarities where any surviving example carries scarcity value.
Grading submission volume clusters in Near Mint as collectors speculate on upgrade potential. Mint population growth is constrained by examiner throughput and tightening standards.
Distribution Channel:
Channel selection determines price transparency, authentication integration, and buyer-seller counterparty risk exposure.
- Online Marketplaces:Platform-mediated transactions with integrated price indexing, escrow services, and seller rating systems. Real-time comparables accelerate price discovery beyond legacy retail formats.
- Auctions:Scheduled sales events with third-party condition verification, extended bidding windows, and buyer premium structures. High-value vintage liquidation concentrates here.
- Retail Stores:Brick-and-mortar hobby shops offering immediate inventory inspection and community trading events. Foot traffic is declining as digital channels capture transaction flow.
- Trade Shows:Convention-floor dealer aggregation with on-site grading submission and bulk purchase negotiation. These events anchor the social infrastructure of collector communities.
Transaction velocity is shifting fastest toward Online Marketplaces as mobile applications embed authentication verification and payment protection. Auctions retain dominance for six-figure vintage liquidation.
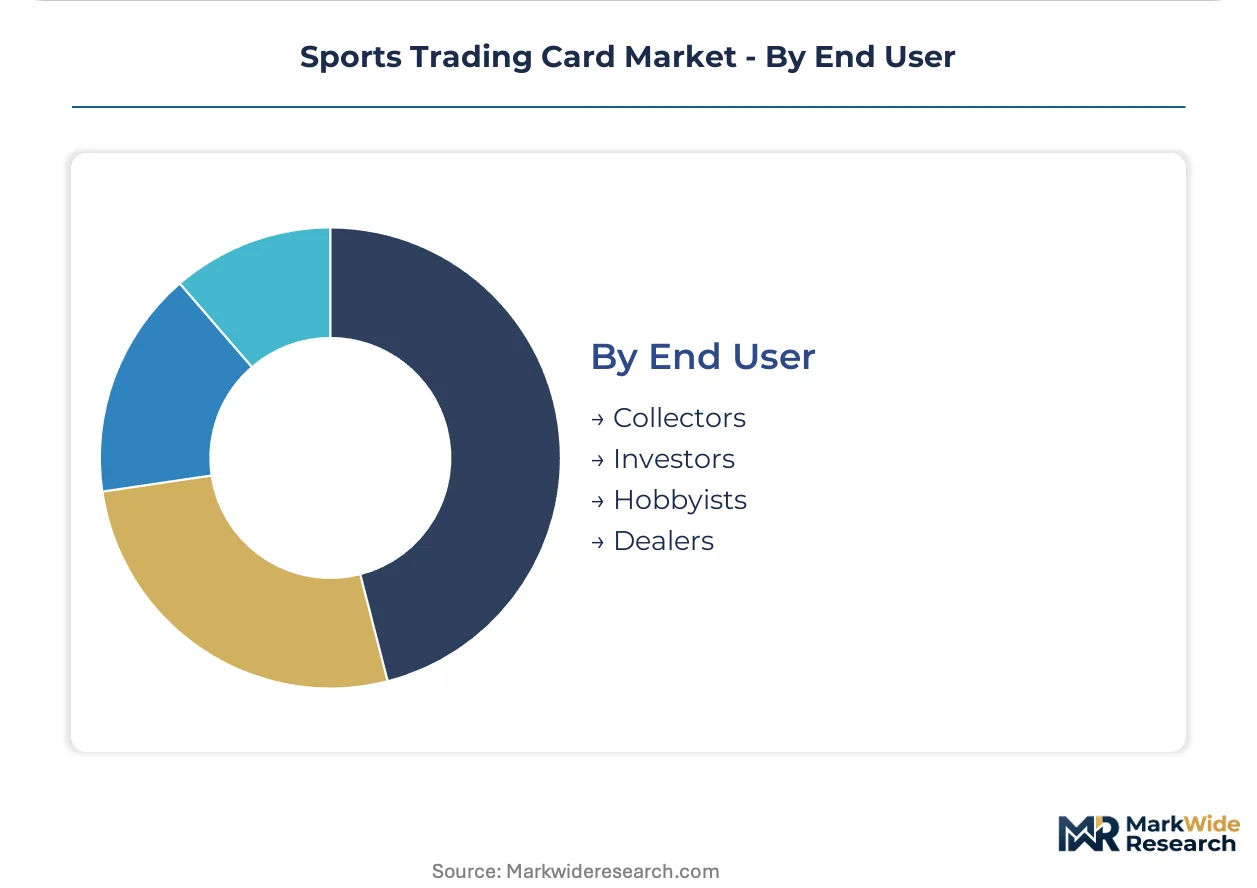
End User:
Buyer taxonomy separates consumption-oriented hobbyists from financialized collectors treating cards as alternative assets.
- Investors:Portfolio allocators employing grading population data, price appreciation metrics, and liquidity depth analysis to construct diversified positions. These participants drive premium pricing for high-grade vintage.
- Collectors:Completion-focused enthusiasts pursuing set registry achievement and aesthetic display objectives. Their demand concentrates in specific athletes, teams, or eras rather than pure financial returns.
- Dealers:Inventory-accumulating intermediaries exploiting bid-ask spreads through rapid turnover and grading arbitrage. Their procurement patterns signal emerging scarcity dynamics.
- Hobbyists:Casual participants engaging in pack-ripping, trading, and community participation without systematic investment frameworks. Volume here supports manufacturer release calendars.
Investor capital inflows are compressing yields in liquid vintage grades. Hobbyist engagement sustains primary market pack sales and manufacturer release velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing sports trading card production capacity toward jurisdictions with streamlined authentication compliance and favorable duty structures for collectible imports.
United States
Grading laboratory expansion and auction liquidity depth attract institutional capital flows. The FTC enforces collectible investment disclosure rules that constrain dealer marketing language. Dallas and New York City host the densest concentrations of third-party authentication facilities and high-value auction houses.
Germany
European football card demand and cross-border collector platforms drive transaction velocity. The EU Consumer Rights Directive mandates resale transparency protocols for pan-European marketplaces. Frankfurt anchors centralized distribution infrastructure for licensed product releases across German-speaking markets.
Japan
Baseball card heritage and otaku crossover collecting sustain premium pricing for vintage NPB issues. METI guidelines on consumer protection shape authentication service advertising standards. Tokyo's Shibuya and Akihabara districts concentrate specialty retailers and grading submission centers.
United Kingdom
Premier League licensing and Premier Rugby memorabilia attract speculative investment from domestic collectors. Trading Standards regulations govern collectible investment claims and return policies. London's Camden Market and Birmingham's NEC host recurring trade shows with on-site authentication services.
Italy
Panini's centralized printing operations and Serie A licensing dominance anchor European production capacity. CE marking requirements apply to imported cardstock materials for youth-oriented products. Modena hosts the primary manufacturing complex for continental football card distribution.
Sports Trading Card Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue authentication-technology convergence and direct-to-consumer platform development. The vendor base stratifies across three functional layers: licensed manufacturers with exclusive league agreements, third-party grading laboratories, and auction-mediated liquidity providers. Competitive positioning depends on authentication infrastructure depth and exclusive intellectual property access. Consolidation pressures intensify as Fanatics acquires legacy licensing rights and integrates vertical control over production-to-marketplace value chains.
Within the licensed-manufacturer tier, Topps and Panini exemplify divergent geographic anchoring strategies—Topps leveraging North American league exclusivity, Panini commanding European football licensing. Upper Deck occupies a specialist position in hockey memorabilia with proprietary production techniques. These three entities represent distinct archetypes: league-exclusive licensors, multi-sport portfolio holders, and single-vertical specialists.
| Leading Market Players |
|---|
| Topps |
| Panini |
| Upper Deck |
| Fanatics |
| Leaf Trading Cards |
| Donruss |
| Goldin Auctions |
| Market Movers |
| Trading Card Market |
| Others |
Value Chain & Pricing Dynamics
FDA guidelines on youth-product material safety gate both qualified supply and premium-tier pricing access, as archival-grade cardstock mills and UV-coating vendors must certify compliance before serving licensed manufacturers. This regulatory filter concentrates production among North American and Italian facilities that have absorbed certification costs, embedding compliance premiums into manufacturer pricing to collectors and auction houses.
Pricing Analysis
Direct-to-consumer authentication bundles compress traditional distributor margins as US print houses integrate grading laboratory partnerships into serialized release calendars. Three-tier pricing structure across premium, standard, and economy levels stratifies by condition grade and witnessed-autograph verification, with Mint 9-plus specimens commanding substantial premiums over raw alternatives. Cost compression in mass-produced contemporary inserts intensifies as digital reproduction technologies democratize scarcity mechanics. Hobbyists exhibit highest price sensitivity, while institutional investors absorb premiums for population-scarce vintage inventory.
Supply Chain Analysis
Specialized examiner talent availability in Dallas and New York City constrains grading laboratory throughput scaling. Archival-grade cardstock supply concentrates among North American specialty paper mills and Panini's centralized Italian printing operations, with UV coating chemicals and holographic foil substrates sourced from German and Japanese specialty chemical producers. Single-source vulnerability runs through witnessed-autograph logistics chains where exclusive athlete signing contracts limit authentication protocol expansion. Distribution runs through online marketplaces with integrated escrow, displacing legacy retail hobby shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sports trading cards function as a stable compounder anchored by generational wealth transfer into tangible alternative assets and sustained fan engagement platform convergence.
For Market Incumbents: Anchor authentication infrastructure superiority through machine vision grading system deployment and examiner training pipeline investments. Counter Fanatics' vertical control over production-to-marketplace value chains by deepening exclusive league license renewal terms and integrating blockchain verification layers into direct-to-consumer release bundles.
For New Entrants and Emerging Players: Capture EU cross-border resale transparency infrastructure as the Consumer Rights Directive mandates compliant pan-European auction liquidity pools. Penetrate the autographed card verification segment where witnessed signing protocol fragmentation creates white-space for blockchain-physical convergence platforms targeting millennial collector demographics.
For Investors and Strategic Acquirers: Valuations sit cheapest among third-party grading laboratories facing examiner throughput constraints but possessing irreplaceable condition assessment expertise and population report databases. Long-term viability centers on authentication technology moats rather than manufacturing scale. Monitor grading consistency benchmark divergence across major laboratories as the inflection indicator for quality control reputational risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Authentication Technology Integration | Machine vision grading systems from Goldin Auctions compress examiner consensus timelines and laboratory capacity bottlenecks. |
| Exclusive License Renewal | Topps leverages MLB and NBA exclusivity to sustain premium release calendar pricing power against Fanatics encroachment. |
| Blockchain Verification Deployment | Non-fungible token registries paired with smart contract escrow extend authentication trust layers for high-grade inventory. |
| EU Compliance Infrastructure Buildout | Panini anchors pan-European auction liquidity through Frankfurt distribution hubs meeting Consumer Rights Directive transparency mandates. |
| Youth Product Safety Certification | FDA-compliant manufacturing line investments differentiate producers in the hobbyist segment driving pack-ripping velocity. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with grading laboratory directors, auction house authentication specialists, licensed manufacturer product managers, and collector investment platform executives. Secondary validation drew from FTC collectible investment disclosure filings, FDA youth product safety guidelines, ISO 9001 accreditation databases, and population report aggregations from major grading services. Bottom-up transaction volume estimates triangulated against top-down manufacturer release calendar projections.
Segment-weighting approaches modeled product type stratification across vintage, autographed, and insert categories, condition tier distribution from Poor through Mint, and channel migration from retail stores toward online marketplaces. CAGR derivation incorporated authentication infrastructure investment cycles, fan engagement platform user acquisition trajectories, and regulatory compliance cost absorption timelines. Forecast inputs included examiner throughput scaling constraints and blockchain verification protocol adoption curves.
Counterfeiting technology escalation, grading consistency benchmark divergence, and exclusive license reallocation are the dominant revision risks to projection assumptions. Material deviation in these triggers warrants pause and re-evaluation of authentication infrastructure valuation premiums.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hobbies & Collectibles
Toys and Hobby Stores Market
Hobbies & Collectibles
Plastic Model Kit Market
Hobbies & Collectibles
Foosball Table Market
Hobbies & Collectibles
Spiritual and Devotional Products Market
Hobbies & Collectibles
Coin Collection Market
Hobbies & Collectibles
Animation Collectibles Market
Hobbies & Collectibles
Mannequins Market
Hobbies & Collectibles
Stamp Collecting Market