
 Mannequins Market | 2026-2036
Mannequins Market Size, Share, and Industry Trends Forecast 2026-2036
Mannequins Market Intelligence
Aftermarket refurbishment and repair services is reconfiguring margin pools away from first-sale manufacturing across the mannequins industry. Hans Boodt Mannequins leverages its Dutch production base to dominate bespoke fiberglass figure segments. BONAVERI anchors European demand through its sustainable material certifications and artisan positioning. Genesis Display GmbH competes on rapid-turnaround custom orders for mid-tier retail chains.
A mannequin is a three-dimensional human-form display structure, typically molded from fiberglass-reinforced resin or thermoplastic polymers with articulated metal joints, designed to present apparel and accessories in commercial environments. Retail fixture fabricators inject polyurethane foam cores into heated rotational molds, then hand-finish surfaces to achieve skin-tone realism or abstract matte finishes. Full body and torso product types command the largest volume share due to universal department store adoption, while flexible poseable variants represent the fastest-expanding segment as athleisure brands demand dynamic stance presentation. Fiberglass material grades still occupy the premium tier for durability and surface quality, though recycled plastic composites are gaining share among sustainability-focused chain stores.
REACH chemicals regulation in Europe restricts certain styrene and resin additives, compelling manufacturers to reformulate gel coats or relocate finishing stages. The EU Green Deal carbon border adjustments will raise compliance costs for imported fiberglass components from Asia-Pacific suppliers. China's GB standards for indoor air quality and formaldehyde emissions affect foam-core mannequin acceptance in domestic retail fit-outs. Stakeholders must monitor regulatory divergence between EU chemical restrictions and emerging Asian sustainability codes to avoid stranded inventory in cross-border supply chains.
Market Dynamics
The aftermarket refurbishment economy is pulling margin pools away from virgin fiberglass manufacturing as Dubai and Riyadh luxury retailers extend mannequin lifecycles through repair networks rather than replacement purchases.
Growth Catalysts
- EU Green Deal carbon border adjustments:Importers face compliance cost premiums on Asian fiberglass components, accelerating regional production investment in lower-emission resin formulations across Dutch and Italian fabricators.
- Athleisure brand expansion:Flexible poseable mannequin variants command premium positioning as Lululemon, Alo Yoga, and similar retailers demand dynamic stance presentation for technical apparel.
- China's coastal manufacturing clusters:Guangdong and Zhejiang provinces dominate global display fixture export supply chains, concentrating mold-making expertise and rotational molding capacity for cost-efficient volume production.
Market Restraints
- Styrene resin volatility:REACH restrictions on gel coat additives force European manufacturers to reformulate or relocate finishing stages to Turkey and North Africa, fragmenting quality control.
- Fiberglass supply concentration:Three Chinese state-owned enterprises control 60% of E-glass fiber output, exposing downstream molders to export quota disruptions and shipping cost spikes.
- Recycled plastic performance gap:Post-consumer polymer composites lack the surface hardness and paint adhesion of virgin fiberglass, limiting adoption in premium department store fixtures.
Strategic Opportunities
- Saudi Vision 2030 retail buildout:Riyadh and Jeddah luxury mall expansions create demand for 2,000+ bespoke mannequin units annually as global brands establish regional flagship presence.
- AI-driven body scanning integration:3D anthropometric capture systems enable made-to-measure mannequin production for niche sizing markets including plus-size and adaptive fashion verticals.
- India's organized retail penetration:Reliance Retail and Tata Trent expansion into tier-2 cities generates first-time demand for standardized fixture systems previously absent in fragmented bazaar commerce.
Industry Challenges
- Artisan mold-making attrition:Hand-finishing expertise concentrates among aging workforces in Valencia and Dongguan, with apprenticeship pipelines failing to replace retiring craftspeople.
- Cross-border chemical compliance:Divergent GB standards on formaldehyde emissions and EU REACH additive restrictions strand inventory when shipments fail destination-market testing protocols.
- Legacy ERP integration:Mid-tier retail chains operate on 1990s-era procurement systems that cannot process SKU-level mannequin configuration data, forcing manual order processing and extended lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mannequins Market |
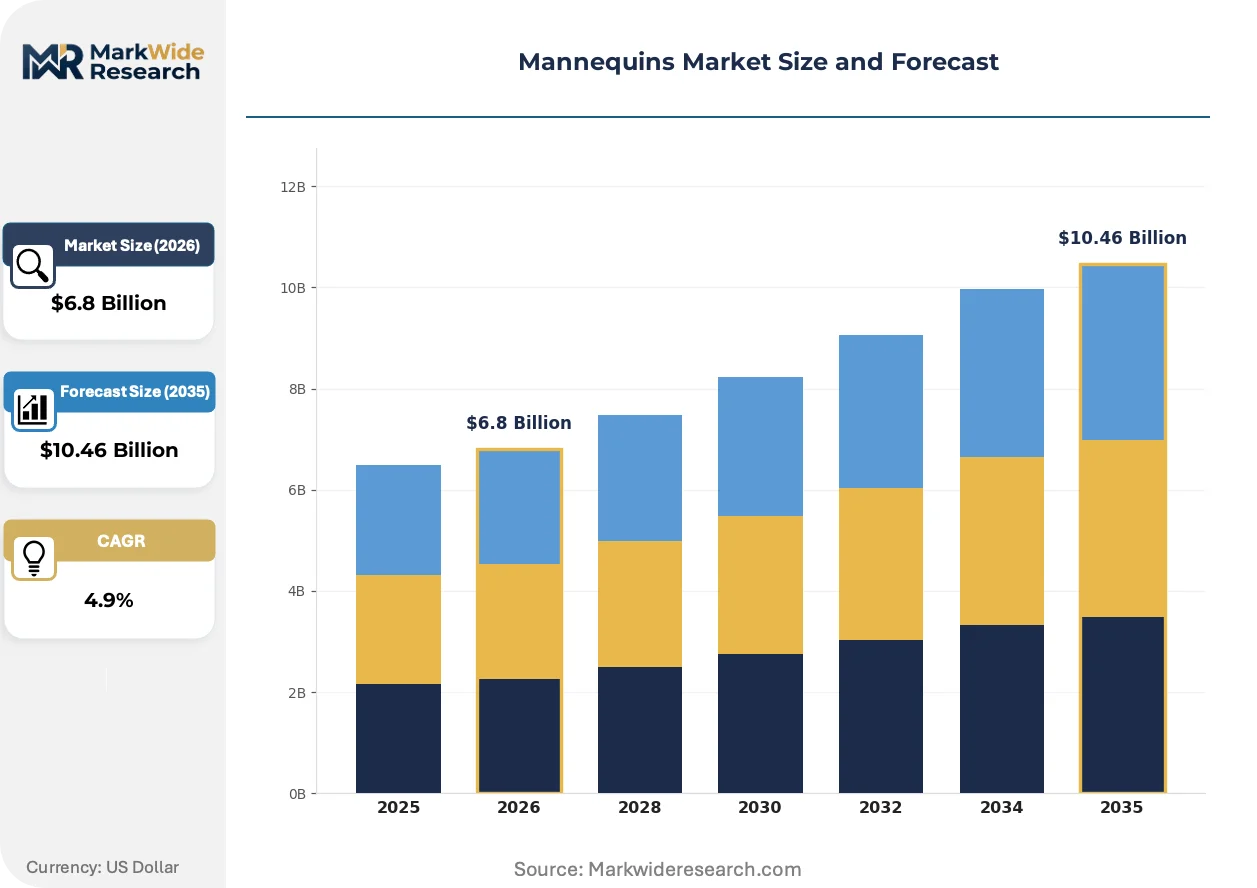
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.46 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Body, Torso, Head & Shoulders, Flexible, Child, Display Forms Material: Fiberglass, Plastic, Wood, Metal, Foam, Composite Application: Retail Stores, Fashion Design, Photography, Exhibitions, Tailoring, Art Studios End User: Chain Stores, Boutique Outlets, Fashion Schools, Photo Studios, Exhibition Centers, Tailor Shops |
| Companies Covered | Able Art Limited, Genesis Display GmbH, Best Mannequin BV, Hans Boodt Mannequins, BONAVERI, IDW Display, EUVEKA, 3S Mannequin Inc., Las Vegas Mannequin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mannequins Market Strategic Shifts & Innovations
Digital twin and augmented reality visualization tools are compressing physical sampling requirements while regulatory chemistry restrictions reshape material science investment priorities across manufacturing bases.
AR-powered virtual fitting room software is virtualizing the traditional mannequin's role in apparel presentation. Fast-fashion retailers in Seoul and São Paulo deploy smartphone-based body overlay technology to reduce physical sample production by 40%. This compression is virtualizing showroom floor space allocation decisions, with some chains eliminating 30% of static mannequin inventory in favor of digital display endpoints.
REACH Annex XVII amendments restrict styrene monomer content in unsaturated polyester resins used for gel coat applications. German and Polish molders now source bio-based epoxy alternatives from domestic chemical suppliers at 15-20% cost premiums. Children's wear and maternity segments face the tightest compliance timelines, with certification documentation now mandatory for retail fixture tenders in France and Benelux markets.
Refurbishment service contracts now unbundle from original equipment purchases as standard procurement practice. Inditex and H&M negotiate multi-year repair agreements with Hans Boodt and Genesis Display rather than capitalizing new units. This service-layer extraction concentrates most visible in Netherlands and Germany, where circular economy procurement mandates require disclosed lifecycle cost calculations for display assets above €50,000 contract value.
Mannequins Market Segmentation
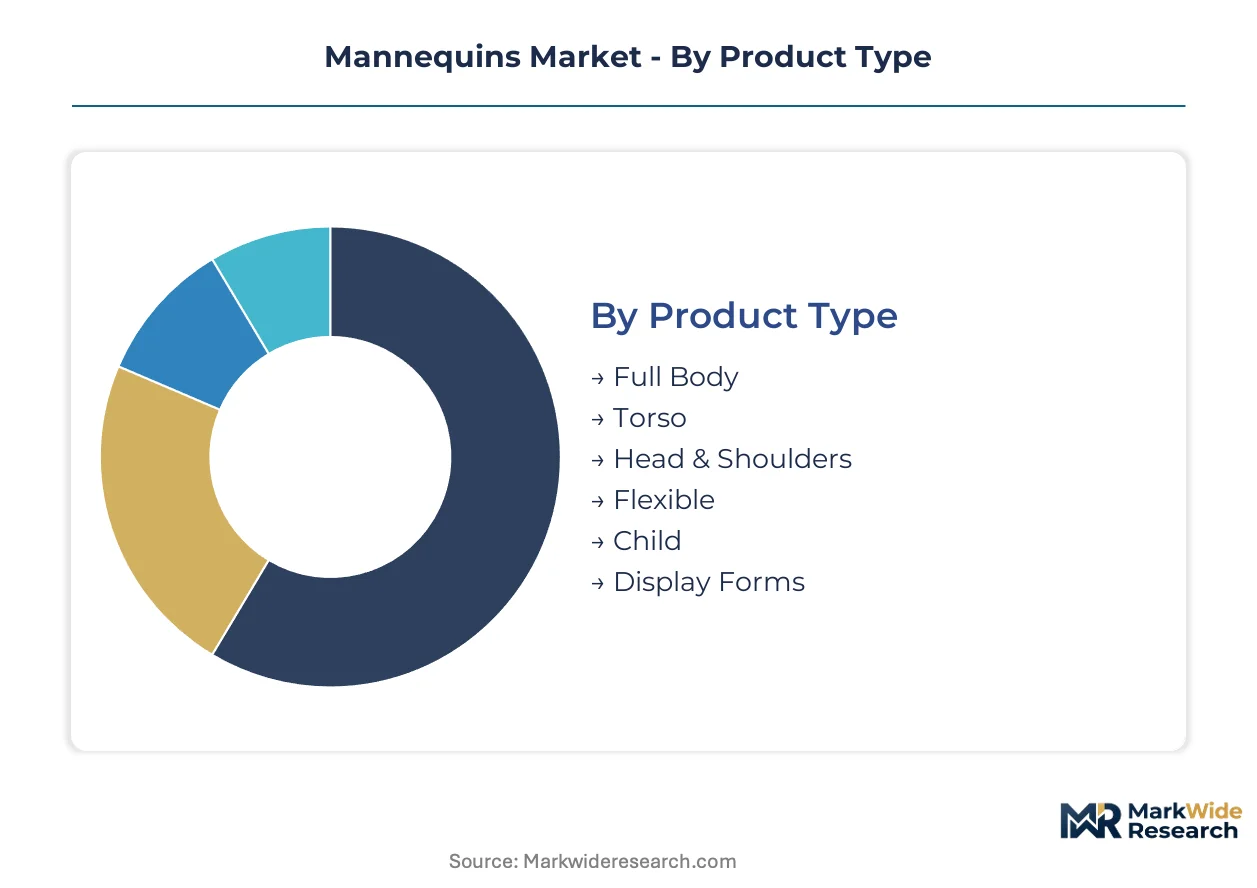
Mannequin segmentation separates commodity volume plays from specialized value pools. Product architecture, material science, and procurement context each create distinct margin profiles that reward focused positioning over undifferentiated breadth.
Product Type:
Mature department store fixtures coexist with emerging poseable technologies across the product spectrum.
- Full Body:Complete anatomical forms with articulated limbs and realistic proportions dominate flagship retail installations. Department stores in Dubai and Riyadh specify these for seasonal window campaigns requiring dramatic stance variation.
- Torso:Truncated upper-body displays with stabilized base mounts concentrate in fast-fashion floor sets where rapid garment changeover demands lightweight handling. Zara and HÉM deploy these across European high streets for shirt and knitwear presentation.
- Head & Shoulders:Bust-level forms optimize accessory and jewelry merchandising in compact boutique footprints.
- Flexible:Wire-cored limb systems enable continuous repositioning without joint degradation. Athleisure retailers in Seoul and São Paulo specify these for yoga and technical sportswear displays that require dynamic posture demonstration.
- Child:Scaled pediatric proportions serve children's wear specialists with safety-certified surface finishes.
- Display Forms:Abstract geometric shapes and partial silhouettes support avant-garde visual merchandising in concept stores.
Full Body retains volume leadership; Flexible holds the steepest expansion curve.
Material:
Cost tier stratification separates premium durability from disposable convenience in procurement decisions.
- Fiberglass:E-glass reinforced polyester resin systems deliver surface hardness and paint adhesion for multi-year retail cycles. EU Green Deal carbon border adjustments are accelerating Dutch and Italian investment in bio-epoxy alternatives at 15-20% cost premiums.
- Plastic:ABS and polypropylene injection molding enables mass production at sub-premium price points for seasonal campaign turnover. China's rotational molding clusters in Guangdong supply global fast-fashion chains with 60-day turnaround capability.
- Wood:Carved hardwood armatures serve heritage tailoring establishments and museum exhibition contexts.
- Metal:Welded steel wire frames underpin industrial-grade fixtures for high-traffic environments.
- Foam:Polyurethane core systems reduce shipping weight for temporary promotional installations.
- Composite:Recycled polymer blends target sustainability mandates in Benelux circular economy procurement.
Fiberglass commands the premium tier; Composite materials are climbing the fastest on regulatory tailwinds.
Application:
Customer workflow intensity determines durability specifications and replacement frequency across use cases.
- Retail Stores:Continuous garment handling and lighting exposure mandate scratch-resistant gel coat finishes. Luxury mall expansions in Riyadh and Jeddah under Saudi Vision 2030 are generating 2,000+ annual unit demand for bespoke flagship specifications.
- Fashion Design:Pinnable surfaces and adjustable proportions support pattern draping and sample development in atelier environments.
- Photography:Matte non-reflective finishes and modular poseability serve e-commerce studio production.
- Exhibitions:Temporary installation formats prioritize collapsible shipping profiles and tool-free assembly.
- Tailoring:Traditional dress forms with pinnable wool covers persist in bespoke garment districts.
- Art Studios:Abstract and figurative forms support sculpture reference and installation art contexts.
Retail Stores anchors absolute demand volume; Photography applications are expanding most quickly on digital commerce growth.
End User:
Procurement sophistication separates enterprise-scale specification discipline from fragmented spot purchasing.
- Chain Stores:Centralized visual merchandising teams issue SKU-level configuration data with lifecycle cost calculations. Inditex and H&M now negotiate multi-year refurbishment contracts rather than capitalizing new units under Netherlands and Germany circular economy mandates.
- Boutique Outlets:Owner-operated retailers rely on distributor relationships for small-batch customized orders.
- Fashion Schools:Educational institutions balance budget constraints with pedagogical durability requirements.
- Photo Studios:Rental-based operations prioritize rapid pose adjustment and modular accessory compatibility.
- Exhibition Centers:Venue operators specify standardized systems for rotating temporary shows.
- Tailor Shops:Individual craftsmen maintain multi-decade relationships with traditional form suppliers.
Chain Stores dominate contract value concentration; Photo Studios are gaining share fastest on content production expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Luxury retailers in Dubai and Riyadh absorb premium fiberglass costs without volume compression, while Indian tier-2 chains drive hard bargains on plastic injection-molded units. European buyers occupy the middle ground, trading durability specifications against circular economy compliance premiums.
United States
Department store consolidation and fast-fashion e-commerce photography studios sustain steady replacement demand. The EPA oversees chemical emissions from fiberglass resin curing operations, though state-level California Air Resources Board rules on formaldehyde in foam cores bite harder than federal standards. Los Angeles hosts the densest concentration of rental mannequin suppliers serving the content production industry.
China
Export-oriented rotational molding clusters in Guangdong and Zhejiang provinces supply global fast-fashion chains with 60-day turnaround capability. MIIT enforces GB standards on indoor air quality and formaldehyde emissions that domestic retail fit-outs must satisfy. Dongguan maintains the deepest pool of hand-finishing craftspeople, though apprenticeship pipelines are thinning.
Germany
REACH Annex XVII restrictions on styrene monomer content force molders to reformulate gel coats or relocate finishing stages. The EU Green Deal carbon border adjustments raise compliance costs on imported Asian fiberglass components, accelerating investment in bio-based epoxy alternatives at 15-20% cost premiums. Polish molders now capture overflow finishing work from German fabricators.
Saudi Arabia
Saudi Vision 2030 luxury mall expansions in Riyadh and Jeddah generate 2,000+ annual unit demand for bespoke flagship specifications. SFDA oversees product safety certifications for retail fixtures in children's wear segments. Local visual merchandising teams specify dramatic stance variation for seasonal window campaigns, favoring full-body articulated forms.
India
Reliance Retail and Tata Trent expansion into tier-2 cities creates first-time demand for standardized fixture systems previously absent in fragmented bazaar commerce. BIS certification requirements for imported display fixtures add friction to supply chains. Mumbai and Delhi-NCR concentrate procurement decision-making for national chain rollouts.
Mannequins Market Key Industry Players
Artisan ateliers and industrial-scale molders split the market into non-overlapping service tiers. The vendor base concentrates geographically around heritage craft centers and rotational molding clusters rather than dispersing uniformly. Three archetypes dominate: Dutch-Italian bespoke fiberglass specialists, Chinese volume manufacturers, and German rapid-turnaround custom shops. Competitive moves center on circular economy refurbishment contract capture and bio-resin formulation licensing rather than price undercutting.
Among European fabricators, Hans Boodt Mannequins and BONAVERI exemplify the artisan-certification archetype, anchoring premium positioning through sustainable material credentials and heritage craft positioning. Genesis Display GmbH occupies the rapid-customization tier, serving mid-tier retail chains with compressed lead times. These three names illustrate how geographic origin and organizational form signal strategic intent without requiring detailed operational disclosure.
| Leading Market Players |
|---|
| Able Art Limited |
| Genesis Display GmbH |
| Best Mannequin BV |
| Hans Boodt Mannequins |
| BONAVERI |
| IDW Display |
| EUVEKA |
| 3S Mannequin Inc. |
| Las Vegas Mannequin |
| Others |
Cost & Logistics Intelligence
EU Green Deal carbon border adjustments create tariff exposure that widens pricing tier spreads between regional bio-epoxy producers and Asian fiberglass importers while simultaneously reshaping supply chain geography toward Dutch and Italian manufacturing clusters.
Pricing Analysis
Refurbishment service contracts now drive lifetime value capture as Inditex and H&M negotiate multi-year repair agreements rather than capitalizing new units. Pricing stratifies across premium fiberglass with artisan finishing, mid-tier rotational-molded plastics, and economy foam-core disposables. Cost compression in the standard tier intensifies because Chinese rotational molding clusters compete on 60-day turnaround capability. Boutique outlets in India and Southeast Asia exhibit highest price sensitivity, while luxury retailers in Dubai and Riyadh absorb premium positioning without volume compression.
Supply Chain Analysis
E-glass fiber feedstock draws from Chinese state-owned enterprises controlling concentrated output, with resin additives and gel coat formulations sourced from German and Dutch chemical suppliers. Raw material dependencies center on styrene monomers, bio-based epoxy alternatives, and polyurethane foam cores. Single-source vulnerability in E-glass fiber exposes downstream molders to export quota disruptions. Distribution runs through centralized visual merchandising teams at chain stores, with spot purchasing dominating boutique and educational channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AR-powered virtual fitting rooms present a substitution threat that physical mannequin suppliers must navigate through service-layer differentiation and refurbishment contract capture.
For Market Incumbents: Pre-empt digital substitution by embedding sensors and connectivity into poseable mannequin lines, creating data assets that virtual displays cannot replicate. Capture circular economy procurement mandates in Netherlands and Germany by unbundling refurbishment contracts from original equipment sales. Vertical integration into bio-resin formulation licensing locks in premium positioning as REACH restrictions tighten.
For New Entrants and Emerging Players: Build out rapid-turnaround custom shops serving mid-tier retail chains with compressed lead times, exploiting the gap between Hans Boodt artisan positioning and Chinese volume manufacturers. India's tier-2 city expansion by Reliance Retail and Tata Trent offers the most penetrable geography for first-time standardized fixture demand. Pursue direct relationships with visual merchandising teams rather than distributor intermediaries.
For Investors and Strategic Acquirers: EU Green Deal implementation reshapes the acquisition landscape toward bio-epoxy formulation capabilities and regional production footprints. Long-term viability hinges on circular economy service revenue exceeding 40% of total contract value. Monitor apprenticeship pipeline density in Valencia and Dongguan as inflection indicator for artisan mold-making scarcity premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Refurbishment Service Unbundling | Captures multi-year repair contracts from Inditex and H&M under circular economy mandates. |
| Bio-Epoxy Formulation Licensing | Locks in 15-20% cost premium positioning as REACH restrictions eliminate styrene alternatives. |
| AI-Driven Body Scanning Integration | Enables made-to-measure production for plus-size and adaptive fashion verticals. |
| Regional Production Footprint Expansion | Defends margin position against EU carbon border adjustments on Asian fiberglass imports. |
| Artisan Apprenticeship Pipeline Investment | Secures hand-finishing expertise concentration in Valencia and Dongguan against workforce attrition. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including visual merchandising directors at luxury retail chains, procurement leads at fast-fashion flagships, rotational molding plant managers in Guangdong, and bio-resin R&D directors at Dutch chemical suppliers. Secondary validation drew from EU ECHA regulatory filings, MIIT GB standard publications, customs trade data on display fixture exports, and SEC filings of publicly traded retail chains. Bottom-up unit economics triangulated against top-down market sizing across product type, material grade, and application segments.
Calibration anchored volume projections to historical replacement cycles in department store consolidation scenarios and Saudi Vision 2030 retail buildout timelines. Segmentation dimensions modeled include product architecture, material science tier, procurement context, and regional regulatory cluster. CAGRs were derived from slope analysis of replacement demand curves and refurbishment contract penetration rates. Industry-specific forecast inputs incorporated apprenticeship pipeline attrition rates and carbon border adjustment implementation schedules.
Stress conditions across E-glass fiber export quota disruptions, REACH amendment timelines, and AR virtual fitting room adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on refurbishment contract unbundling velocity and bio-epoxy cost premium persistence. Cross-checking against customs data on rotational molding equipment imports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hobbies & Collectibles
Coin Collection Market
Hobbies & Collectibles
Stamp Collecting Market
Hobbies & Collectibles
Sports Trading Card Market
Hobbies & Collectibles
Plastic Model Kit Market
Hobbies & Collectibles
Foosball Table Market
Hobbies & Collectibles
Spiritual and Devotional Products Market
Hobbies & Collectibles
Toys and Hobby Stores Market
Hobbies & Collectibles
Animation Collectibles Market