
 Plastic Model Kit Market | 2026-2036
Plastic Model Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Model Kit Market Analytics
ISO 8124 toy safety certification is rotating toward stricter chemical migration thresholds for polystyrene-based kits, effectively filtering smaller suppliers from premium retail channels. Bandai Co., Ltd. leverages its Gundam intellectual property to dominate sci-fi themed releases across Asian markets. Tamiya Inc. sustains engineering-grade fidelity in military vehicle replicas that anchor its reputation among advanced modelers. Revell competes through broad distribution partnerships with mass-market hobby retailers in North America and Europe.
Plastic model kits comprise injection-molded polystyrene or resin components requiring solvent-based adhesives and acrylic lacquer finishes, primarily serving recreational assembly, historical education, and collectible display purposes. Aircraft and military vehicle kits occupy the largest volume share within product type segmentation, reflecting enduring consumer interest in aviation history and armored warfare aesthetics. Sci-Fi themed releases represent the fastest-growing theme category, driven by streaming media franchises and cross-licensing opportunities. The 1:35 scale segment leads margin pools due to its optimal balance of detail density and shelf footprint for serious hobbyists.
REACH restrictions on styrene monomer content and the EU's F-Gas Regulation governing propellants in spray finishing products shape material choices and aftermarket accessory demand across European markets. The US Consumer Product Safety Commission enforces age-grading standards that directly influence assembly complexity labeling and beginner kit packaging requirements. China's SAMR monitors GB standards compliance for imported model kits, creating certification barriers for non-domestic manufacturers. Stakeholders must monitor evolving chemical substance restrictions and streaming-media licensing windows to align product development cycles with regulatory compliance deadlines and entertainment franchise peaks.
Market Dynamics
REACH restrictions on styrene monomer migration and the EU's F-Gas Regulation governing spray propellants are forcing manufacturers to reformulate polystyrene resins and solvent-based finishing products, compressing margins for smaller suppliers while advantaging integrated compounders with in-house polymer labs.
Growth Catalysts
- Digital detox behavioral shift:Adult hobbyists aged 35-55 are allocating discretionary hours toward tactile assembly activities, expanding the addressable base beyond traditional youth segments.
- REACH compliance differentiation:Premium retailers in Germany and France now gate shelf access to kits certified under ECHA's evolving substance restrictions, filtering non-compliant imports.
- Streaming-media licensing cycles:Sci-fi franchise windows from major entertainment studios generate predictable demand spikes for themed kit releases.
Market Restraints
- Styrene price volatility:Petrochemical feedstock fluctuations directly impact polystyrene pellet costs, squeezing margin stability for injection-molders without long-term supply contracts.
- Specialty retailer concentration:Japan's hobby shop ecosystem remains dominated by established chains in Akihabara and Osaka, creating entry barriers for direct-to-consumer entrants.
- Water-based finish performance gap:Acrylic alternatives to solvent lacquers still fail to match durability and gloss depth, limiting regulatory-driven product transitions.
Strategic Opportunities
- India's emerging collector base:Metro cities including Mumbai and Bangalore show rising kit imports through e-commerce platforms, with limited domestic manufacturing presence.
- Educational curriculum integration:STEM programs in South Korea and Taiwan are incorporating scale-model assembly for engineering visualization training.
- Recycled-content polystyrene:Post-industrial regrind formulations meeting ISO 8124 safety thresholds open circular-economy positioning in European markets.
Industry Challenges
- Master mold-maker scarcity:Precision tooling design for 1:35 scale detail fidelity requires skills concentrated among aging specialists in Japan and Germany.
- Dual certification timelines:Simultaneous GB standards review by China's SAMR and REACH updates by ECHA create staggered compliance deadlines that fragment production batches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Model Kit Market |
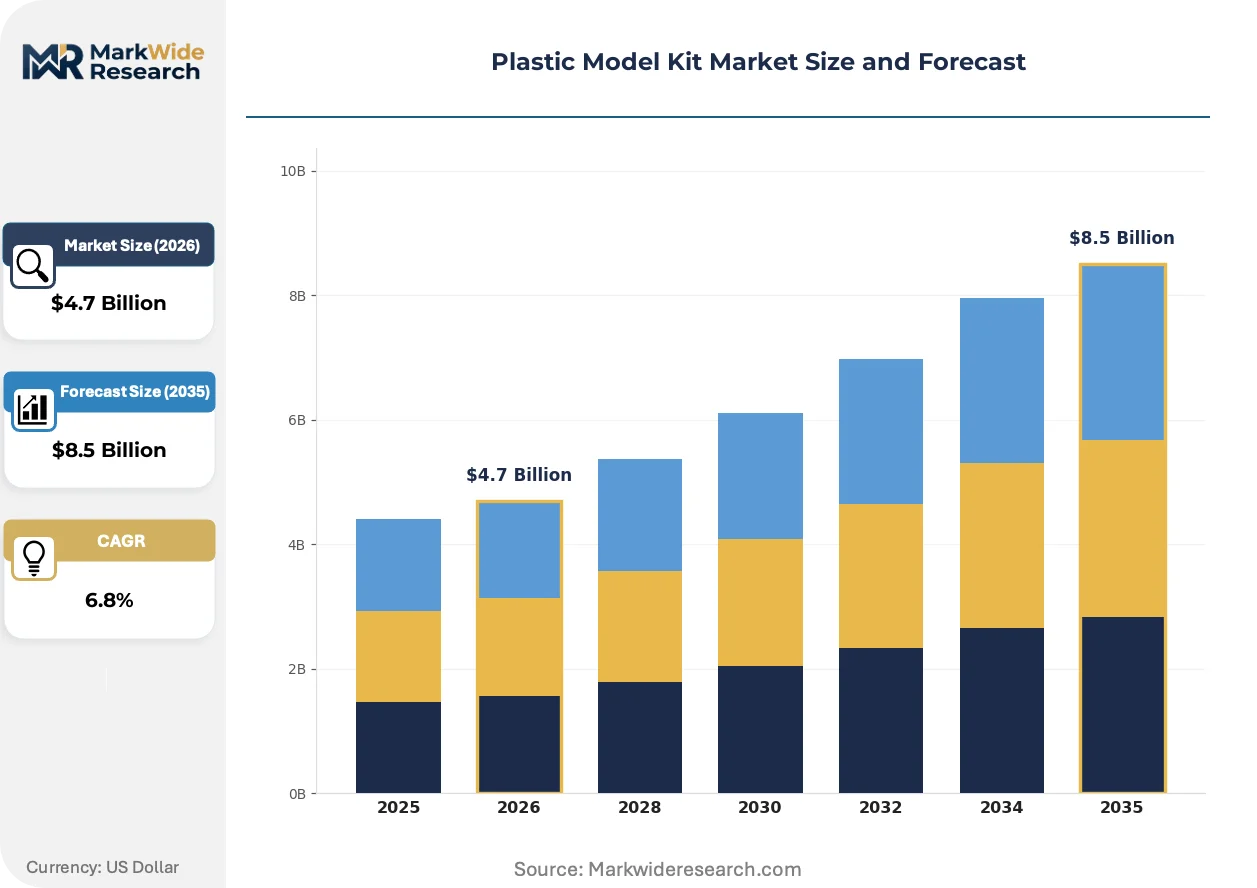
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aircraft, Tanks, Ships, Automobiles Scale: 1:72, 1:48, 1:35, 1:24 Assembly Complexity: Beginner, Intermediate, Advanced, Expert Theme: Military, Civilian, Sci-Fi, Fantasy |
| Companies Covered | Airfix, Dragon Models Limited, Bandai Co., Ltd., Academy Plastic Model, Italeri, Tamiya Inc., Hasegawa Corporation, ICM Holding, Revell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Model Kit Market Evolving Landscape
Photopolymer resin formulations and digital light processing workflows are compressing prototyping cycles for limited-run kits, while regulatory pressure on volatile organic compounds accelerates material substitution across finishing product lines.
Water-washable photopolymer resins are displacing traditional solvent-cleaned formulations in garage-kit and limited-production segments. Boutique manufacturers in Osaka and Seoul are adopting desktop-scale DLP printers for short-run figure releases. This shift is displacing the economics of aluminum mold investment for batches under five hundred units, fragmenting volume concentration among established injection-molders.
The EU's F-Gas Regulation phase-down schedules for hydrofluorocarbon propellants are forcing reformulation of spray lacquers and primers. German and Italian finish suppliers are accelerating water-based acrylic development programs. Military vehicle kit builders represent the most affected segment, as their weathering techniques historically relied on solvent-based washes and filters now facing retail restrictions.
Subscription box curation is consolidating demand discovery for novice hobbyists. Services targeting North American and British buyers are displacing traditional hobby shop browsing as the primary entry path for first-time assemblers. This pattern is most visible among millennials entering the hobby through sci-fi franchise tie-ins rather than aviation or armor subjects.
Plastic Model Kit Market Segmentation
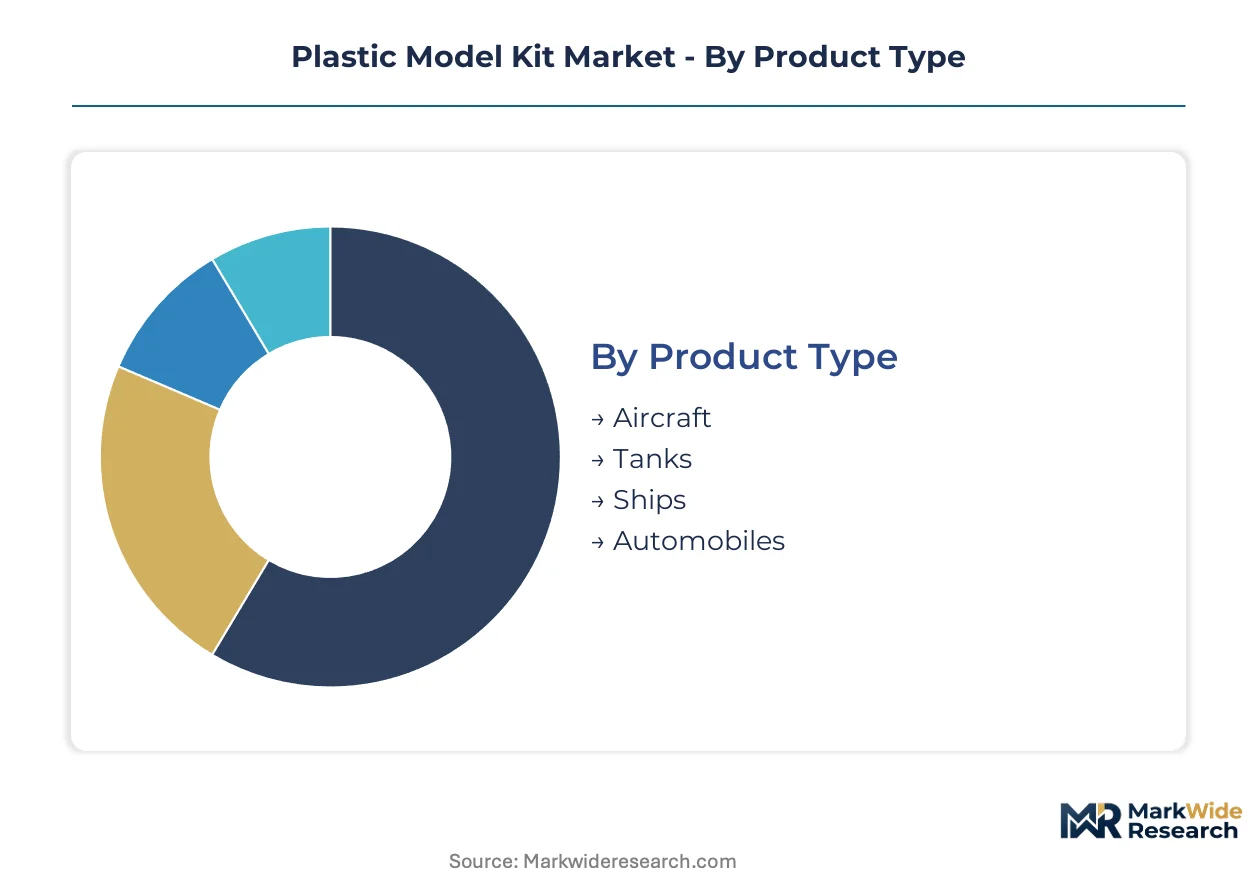
Segmentation in plastic model kits determines tooling investment priorities, distribution channel selection, and regional go-to-market strategies. Manufacturers align mold complexity and material specifications with identifiable buyer skill profiles and display preferences.
Product Type:
Photopolymer resin printers and 3D-printed aftermarket accessories threaten injection-molded kit economics most acutely in low-volume historical subjects.
- Aircraft:Aviation subjects dominate shelf space at specialty retailers across Germany and Japan. Demand concentrates among collectors aged 45-60 pursuing World War II and Cold War era subjects, with aftermarket decal manufacturers extending kit lifecycles through alternate marking options.
- Tanks:Armored vehicle kits anchor the premium 1:35 scale segment. Russian and Israeli armor variants gain share fastest among Eastern European and Middle Eastern buyers, while Western European collectors sustain demand for German and Allied subjects.
- Ships:Naval subjects occupy niche positioning due to large box dimensions and extended assembly times.
- Automobiles:Road car and racing subjects attract younger entrants through motorsport licensing tie-ins.
Aircraft retains volume leadership; Sci-Fi themed releases across all product types hold the steepest expansion curve.
Scale:
Display case dimensions and storage constraints in urban apartments reshape collector preferences toward compact formats.
- 1:35:Military vehicle builders favor this scale for optimal detail-to-size ratio. German and Czech manufacturers command premium pricing through slide-molded hull components and individual track links that satisfy advanced modelers.
- 1:72:Aviation collectors prioritize this scale for squadron-building projects. Japanese and British manufacturers dominate through efficient sprue layouts that minimize part count without sacrificing accuracy.
- 1:48:Aircraft subjects in this scale balance cockpit detail with manageable wingspan.
- 1:24:Automobile kits occupy this scale exclusively, requiring dedicated display space.
1:35 scale commands margin leadership; 1:72 scale delivers the broadest geographic penetration.
Assembly Complexity:
Retailer return rates and customer satisfaction scores vary most dramatically across complexity tiers, driving packaging and instruction investment differentiation.
- Beginner:Snap-fit engineering and pre-painted components reduce barrier to entry. North American mass-market hobby chains prioritize this tier for gift purchase occasions and youth market cultivation.
- Advanced:Multi-media kits incorporating photo-etched brass and resin castings target experienced builders. Japanese manufacturers lead through integrated accessory bundling that eliminates aftermarket sourcing friction.
- Intermediate:Glue-required polystyrene kits with 50-100 parts represent the volume transition tier.
- Expert:Limited-run resin kits and full-detail interior sets serve competition-oriented builders.
Intermediate kits sustain volume throughput; Advanced complexity tier gains share fastest among re-entering adult hobbyists.
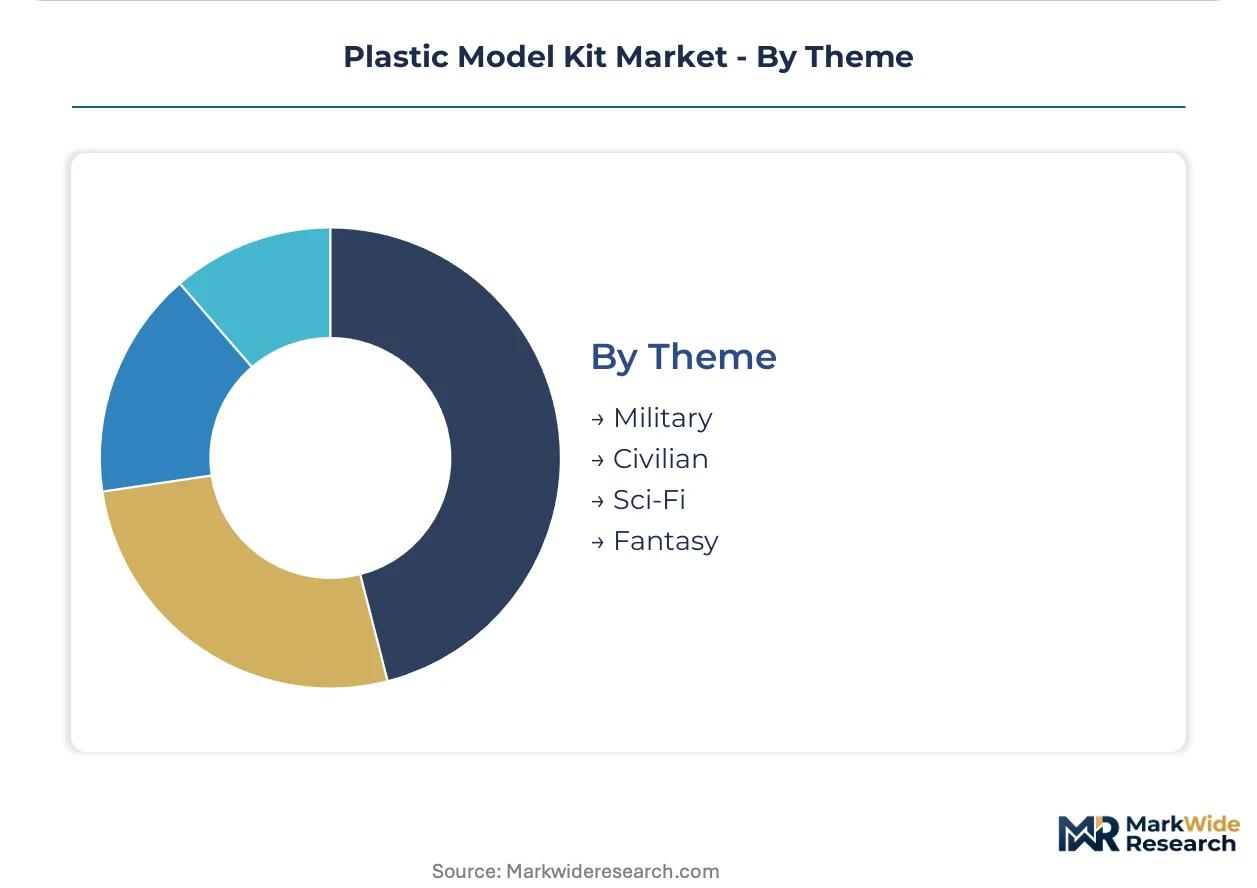
Theme:
Intellectual property licensing windows and streaming content cycles create demand predictability gaps that favor diversified theme portfolios.
- Military:Historical warfare subjects anchor collector retention through documentary and museum tie-ins. European manufacturers sustain authenticity partnerships with tank museums at Bovington and Munster.
- Sci-Fi:Space opera and mecha franchises generate pre-order spikes aligned with streaming release schedules. Japanese licensors enforce strict quality tiers that filter unauthorized kit producers from premium channels.
- Civilian:Commercial aviation and classic automobiles serve display-oriented collectors.
- Fantasy:Figure and diorama subjects occupy boutique production economics.
Military theme retains collector lifetime value leadership; Sci-Fi theme expands most quickly through cross-media licensing velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance deadlines and Japan's mature hobby retail infrastructure are redistributing manufacturing footprints and retail access premiums across key national markets.
Japan
Akiba culture and dedicated hobby shop districts sustain the world's densest collector ecosystem. METI monitors chemical substance reporting for polystyrene formulations under existing industrial safety frameworks. Osaka and Nagoya host precision mold-making clusters where multi-generational tooling expertise concentrates among specialist suppliers.
Germany
ECHA's evolving substance restrictions filter non-compliant imports from premium retail channels. The F-Gas Regulation phase-down forces lacquer reformulation among domestic finish suppliers. Munich and Nuremberg anchor distribution networks serving Central European collectors through museum-adjacent specialty retailers.
United States
Subscription box curation displaces traditional hobby shop browsing among millennial entrants. The Consumer Product Safety Commission enforces age-grading standards that shape packaging and complexity labeling. California and Texas concentrate e-commerce fulfillment infrastructure for direct-to-consumer kit distribution.
China
SAMR's GB standards compliance creates certification barriers for imported kits while domestic manufacturers scale production. Dual carbon goals pressure polystyrene resin sourcing toward recycled-content formulations. Shenzhen and Dongguan clusters supply precision injection-molding equipment to regional kit producers.
United Kingdom
Aviation history documentation sustains demand for World War II and Cold War era subjects among aging collector demographics. Post-Brexit regulatory divergence from REACH creates parallel compliance obligations for importers. London and Birmingham retain specialty retail presence despite broader high-street contraction.
Plastic Model Kit Market Competitive Landscape
Listed leaders compete with private specialists across intellectual property licensing and mold-making capability dimensions. The vendor base stratifies into three tiers: integrated entertainment conglomerates with captive IP, precision engineering houses with multi-decade tooling libraries, and boutique resin-casting operations serving garage-kit segments. Two dominant competitive moves define current positioning: exclusive licensing negotiations with streaming franchises and backward integration into captive polystyrene compounding.
Within the engineering-grade fidelity tier, Tamiya Inc. and Hasegawa Corporation exemplify Japanese precision manufacturing archetypes, while Revell occupies a position representing broad distribution partnerships with mass-market hobby chains. Bandai Co., Ltd. anchors the intellectual property-driven segment through entertainment franchise integration.
| Leading Market Players |
|---|
| Airfix |
| Dragon Models Limited |
| Bandai Co., Ltd. |
| Academy Plastic Model |
| Italeri |
| Tamiya Inc. |
| Hasegawa Corporation |
| ICM Holding |
| Revell |
| Others |
Value Network & Pricing Analysis
Ninety-day mold fabrication lead times in Osaka and Nagoya concentrate pricing power among Japanese tooling houses, while REACH-compliant resin premiums compress margins for European distributors without captive compounding capacity. Inventory velocity at specialty retailers in Akihabara and Nuremberg directly shapes manufacturer pricing flexibility across complexity tiers.
Pricing Analysis
Certification level under ISO 8124 and REACH substance restrictions creates the primary spread between premium and economy kit tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by mold complexity and aftermarket accessory bundling. Cost compression in intermediate-tier injection-molded kits is intensifying because styrene feedstock volatility passes through to contract manufacturers without long-term supply agreements. Beginner snap-fit segments show highest price sensitivity among gift purchasers, while advanced multi-media kit buyers demonstrate inelastic demand for limited-run releases.
Supply Chain Analysis
Strategic stockpiling of polystyrene pellets dominates inventory strategy among German and Japanese compounders facing monomer price swings, while just-in-time resin delivery prevails in Shenzhen assembly clusters serving domestic Chinese brands. Manufacturing gravity centers on Japan, China, and Germany for precision injection molding and mold fabrication. Supply chains draw from petrochemical feedstocks, aluminum tooling stock, and photopolymer resin formulations. Single-source vulnerability concentrates in master mold-maker expertise pools aging out in Osaka and Nagoya. Distribution runs through specialty hobby retailers in dense urban districts and curated subscription services for North American entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from desktop photopolymer printing economics disrupting low-volume historical subject kits, requiring defensive repositioning around IP exclusivity and mold-making capability depth.
For Market Incumbents: Consolidate master mold-maker relationships through apprenticeship partnerships in Nagoya and Osaka tooling clusters before demographic attrition accelerates. Secure backward integration into REACH-compliant polystyrene compounding to defend margin position against ECHA substance restriction updates. Channel control through exclusive specialty retailer arrangements in Akihabara and Nuremberg limits direct-to-consumer entrant access.
For New Entrants and Emerging Players: Fast-track ISO 8124 certification through third-party testing laboratories in Hong Kong and Singapore to unlock premium European retail placement. India's metro collector base through Mumbai and Bangalore e-commerce channels represents the most penetrable geography with limited domestic manufacturing presence. Motorsport licensing tie-ins for automobile subjects offer differentiated go-to-market positioning against established aviation and armor incumbents.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across photopolymer resin formulation segments as water-washable chemistry R&D demands specialized polymer labs. Long-term viability favors targets with captive entertainment IP or multi-decade tooling libraries rather than pure manufacturing scale. Watch streaming franchise licensing windows as inflection indicators for sci-fi themed kit demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Polystyrene Compounding | REACH compliance premiums flow to integrated manufacturers with in-house polymer laboratories. |
| Master Mold-Maker Apprenticeship Programs | Osaka and Nagoya tooling expertise pools require generational transfer before specialist attrition. |
| Streaming Franchise Licensing | Sci-fi kit demand spikes align with entertainment release windows requiring precise timing. |
| Photopolymer Resin Formulation | Water-washable chemistry displaces solvent-cleaned garage-kit economics for limited runs. |
| Subscription Box Curation | Curated entry paths displace traditional hobby shop browsing among millennial first-time buyers. |
Research Methodology
Desk research of customs trade databases, specialty retail inventory audits, and entertainment licensing registries preceded structured interviews with injection-molding plant managers, hobby shop proprietors in Akihabara and Nuremberg, aftermarket decal manufacturers, and polymer R&D directors. Primary fieldwork combined with secondary validation against ECHA substance restriction filings and SAMR GB standards documentation. Bottom-up kit shipment tallies triangulated against top-down polystyrene resin consumption patterns across identified manufacturing clusters.
Variance decomposition across product type, scale tier, assembly complexity, and theme licensing status shaped the analytical framework. Modeled segmentation captured aircraft, armor, naval, and automotive subjects alongside sci-fi and military thematic splits. CAGRs derived from trend-line extrapolation of adult hobbyist demographic expansion and digital detox behavioral survey data, cross-referenced with injection-molding capacity expansion announcements in Shenzhen and Dongguan.
Underlying assumptions cover stable petrochemical feedstock availability and streaming franchise licensing continuity, with deviation risk concentrated in REACH substance restriction acceleration and master mold-maker retirement waves. Forecasts reflect these conditions without scenario-weighting. Revision becomes warranted when photopolymer print resolution thresholds cross injection-molded surface quality parity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hobbies & Collectibles
Spiritual and Devotional Products Market
Hobbies & Collectibles
Stamp Collecting Market
Hobbies & Collectibles
Animation Collectibles Market
Hobbies & Collectibles
Sports Trading Card Market
Hobbies & Collectibles
Coin Collection Market
Hobbies & Collectibles
Mannequins Market
Hobbies & Collectibles
Foosball Table Market
Hobbies & Collectibles
Toys and Hobby Stores Market