
 Toys and Hobby Stores Market | 2026-2036
Toys and Hobby Stores Market Size, Share, and Industry Trends Forecast 2026-2036
Toys and Hobby Stores Market Analysis
REACH chemical standards is consolidating material compliance costs for toy importers entering European markets. LEGO Group anchors its position through captive manufacturing of ABS plastic bricks across Denmark, Mexico, and China. Hobby Lobby Stores Inc. differentiates via vertical craft supply chains that span fabric, art materials, and seasonal décor. Michaels Companies, Inc. competes through specialized workshop programming that drives repeat visits from dedicated hobbyists.
Toys and hobby stores constitute retail establishments selling play products, craft materials, and recreational merchandise, typically featuring inventory with ASTM F963 mechanical safety specifications and phthalate-free polymer compositions designed for developmental engagement and leisure activity. Action figures and craft kits command the strongest margin pools, with craft kits benefiting from adult hobbyist expansion and action figures riding collector-driven premium pricing. Specialty shops within the distribution channel segment sustain higher per-square-foot productivity than big-box alternatives due to curated assortments and staff expertise.
The Consumer Product Safety Commission enforces ASTM F963 in the United States, while the EU Toy Safety Directive governs mechanical and chemical standards across member states; China's GB standards regime adds a third compliance layer for manufacturers sourcing from Asia. These frameworks elevate testing expenditures but simultaneously filter out low-cost competitors lacking laboratory infrastructure. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation will determine which suppliers retain shelf access across multiple markets.
Market Dynamics
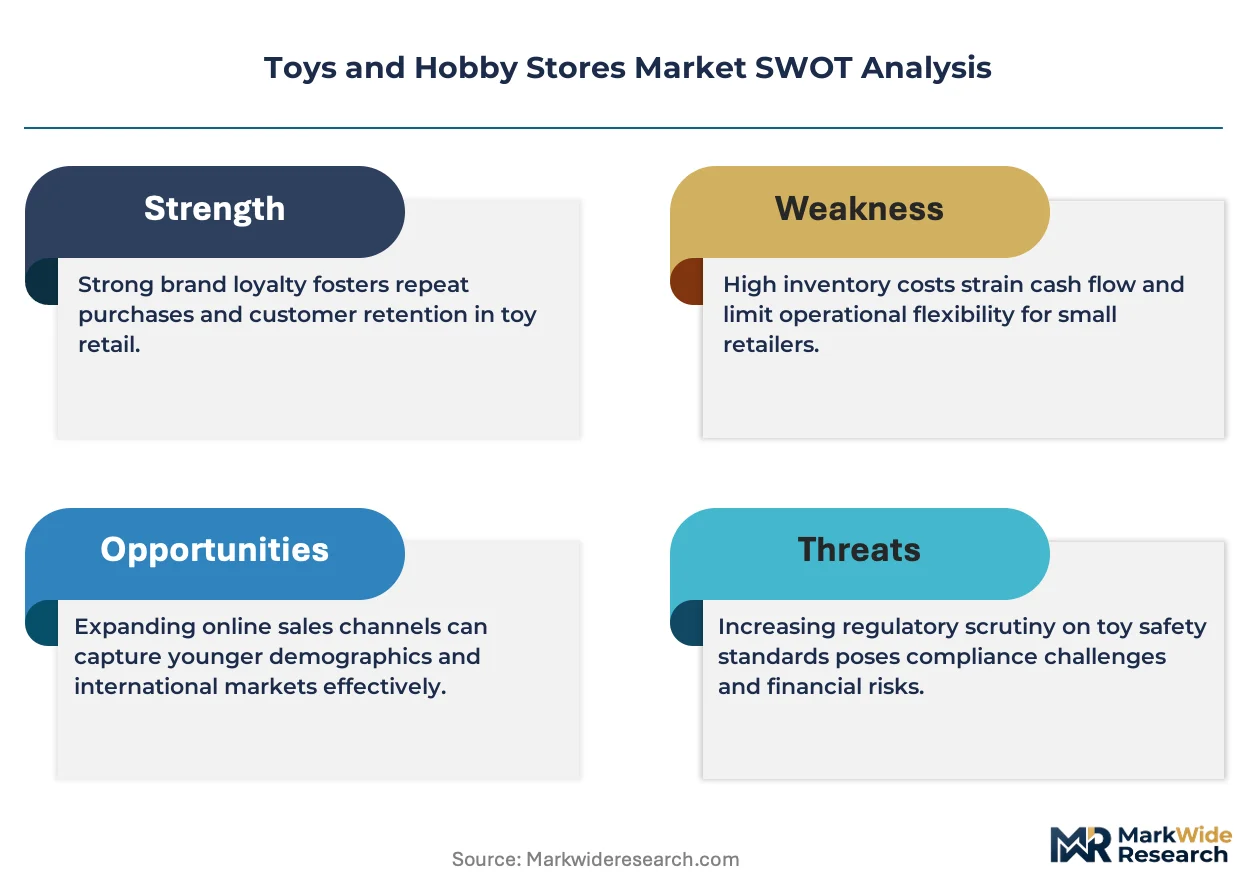
The toys and hobby stores market is experiencing structural pressure from regulatory fragmentation across major trade jurisdictions, where divergent chemical safety standards are forcing importers to maintain parallel testing protocols for shelf access in the United States, European Union, and China.
Growth Catalysts
- EU REACH chemical standards:These regulations are consolidating material compliance costs for toy importers, filtering out low-cost competitors lacking laboratory infrastructure and creating protected market space for certified suppliers.
- Adult hobbyist expansion:Craft kit demand from mature consumers is commanding premium pricing pools, with specialized workshop programming driving repeat visits and higher per-square-foot productivity than conventional toy categories.
- Collector community concentration:Action figure segments in the United States, Germany, and China are sustaining volume through premium pricing dynamics and dedicated retail footprints that anchor category stability.
Market Restraints
- ABS plastic supply concentration:Captive manufacturing of polymer bricks in Denmark, Mexico, and China creates geographic dependency risks for construction toy supply chains.
- Phthalate-free polymer transition costs:Reformulation of soft plastics to eliminate restricted plasticizers requires capital-intensive material science investment without immediate price recovery mechanisms.
- ASTM F963 testing expenditure escalation:The Consumer Product Safety Commission's mechanical safety enforcement elevates laboratory certification burdens that disproportionately impact smaller import distributors.
Strategic Opportunities
- Vertical craft supply chain integration:Fabric, art materials, and seasonal décor sourcing under unified procurement creates margin expansion potential through backward integration into raw material suppliers.
- Curated specialty shop formats:Staff expertise and assortment curation in dedicated hobby retail is capturing collector and enthusiast segments that abandon big-box alternatives.
- China GB standards harmonization:Alignment opportunities between Chinese national standards and Western safety frameworks could reduce dual-certification overhead for Asia-sourced manufacturers.
Industry Challenges
- Multi-jurisdiction compliance synchronization:Maintaining simultaneous adherence to ASTM F963, EU Toy Safety Directive, and GB standards requires dedicated regulatory affairs functions that strain mid-tier distributor resources.
- Seasonal demand volatility management:Inventory positioning for holiday-driven purchase spikes demands working capital intensity that compresses margins during off-peak periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toys and Hobby Stores Market |
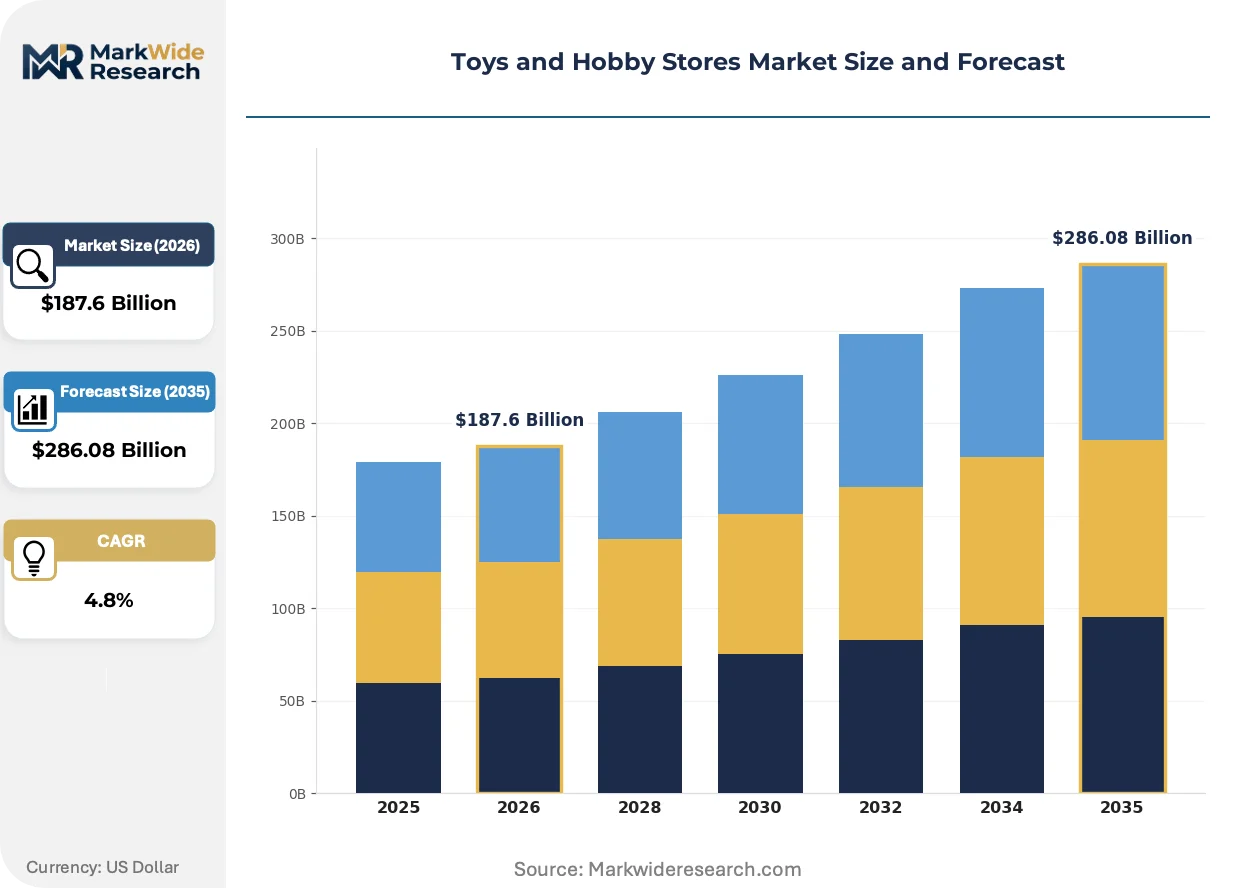
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $286.08 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Action Figures, Dolls, Puzzles, Craft Kits Customer Type: Parents, Collectors, Hobbyists, Gift Buyers Distribution Channel: Online Retail, Physical Stores, Specialty Shops, Wholesale Age Group: Infants, Toddlers, Preschoolers, Teens |
| Companies Covered | Toys 'R' Us (WHP Global), Hamleys, Michaels Companies, Inc., Target Corporation, Città del Sole, Hobby Lobby Stores Inc., LEGO Group, Walmart Inc., GameStop Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toys and Hobby Stores Market Emerging Trajectories
Digital fabrication tools and direct-to-consumer platforms are redistributing manufacturing proximity and purchase pathways across the toys and hobby sector, compressing traditional wholesale-retail hierarchies.
Desktop 3D printing systems using PLA and resin formulations are decentralizing prototype development and limited-run production for action figure accessories and model components. Independent designers and small collectives are adopting these systems at accelerating rates, bypassing conventional mold-based manufacturing minimums. This capability is decentralizing design ownership from major licensors toward creator-led microbrands that capture niche enthusiast segments through crowdfunding pre-orders.
ECHA's expanding REACH substance restrictions are tightening permissible chemical thresholds in polymer formulations and surface coatings across European member states. Manufacturers are reformulating product lines to eliminate newly classified substances of very high concern, often ahead of mandatory deadlines to maintain distribution continuity. Small-batch craft suppliers with flexible material sourcing are adapting faster than mass-market producers locked into legacy compound specifications.
Enthusiast buyers are migrating toward subscription-based kit deliveries and membership workshop access that replace transactional retail encounters with ongoing engagement models. Specialty retailers are responding with tiered loyalty programs that bundle exclusive product access, event participation, and educational content. This behavioral shift is most pronounced in Germany and the United States, where established hobbyist communities demonstrate willingness to commit recurring expenditure for curated experiences.
Toys and Hobby Stores Market Segmentation
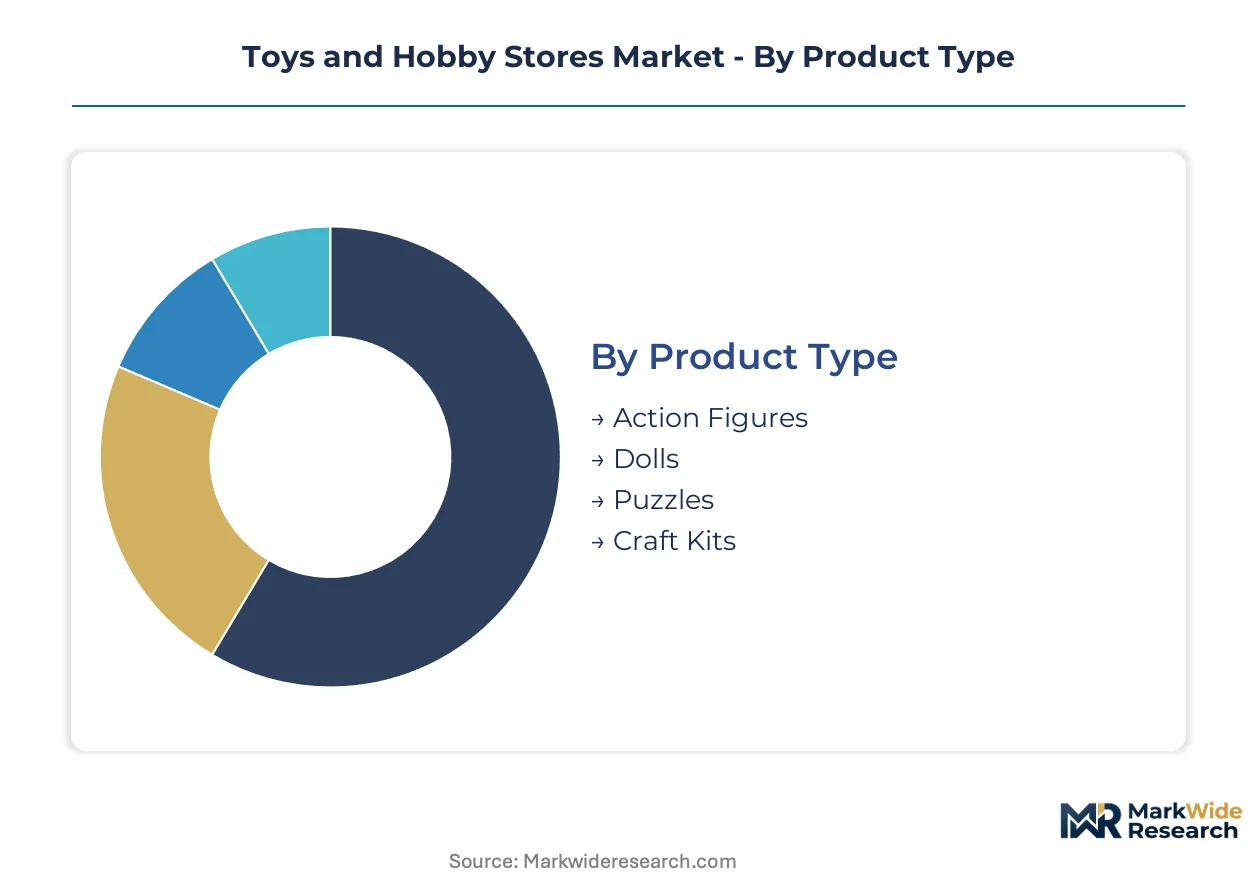
Product differentiation across the toys and hobby stores market determines margin capture and inventory velocity. Segmentation reveals how regulatory compliance costs, collector pricing power, and channel specialization create divergent profitability pools across buyer categories.
Product Type:
Volume concentration sits in construction and basic play categories, while premium pricing accrues to licensed and collectible formats.
- Action Figures:Articulated character models utilizing ABS polymer chassis with painted detail applications. Collector communities in the United States and Germany sustain premium pricing through limited-edition releases and aftermarket arbitrage.
- Craft Kits:Bundled material sets spanning textiles, paper crafts, and mixed-media applications. Adult hobbyist expansion in Germany and the United States commands repeat purchase frequency and workshop-driven loyalty.
- Dolls:Fashion and character dolls with rooted hair and textile clothing assemblies targeting developmental role-play segments.
- Puzzles:Die-cut cardboard and wooden interlocking piece sets ranging from infant floor formats to adult collector art reproductions.
Today's leader: Craft Kits. Tomorrow's challenger: Action Figures.
Customer Type:
Purchase motivation splits between developmental utility for children and emotional investment for mature enthusiasts.
- Parents:Primary decision-makers evaluating ASTM F963 compliance markers and phthalate-free material certifications for child safety assurance.
- Collectors:Speculative buyers concentrating in the United States, Germany, and China who anchor category stability through premium pricing and dedicated retail footprint loyalty.
- Hobbyists:Skill-practitioners seeking workshop programming and material quality tiers that support technique progression.
- Gift Buyers:Occasional purchasers driven by seasonal occasion clustering with lower repeat frequency but higher average transaction values.
Collectors extract the highest per-unit margins. Hobbyists deliver the strongest lifetime value through recurring engagement.
Distribution Channel:
Channel selection determines assortment depth, staff expertise access, and fulfillment speed trade-offs.
- Specialty Shops:Curated inventory formats with trained staff expertise capturing enthusiast segments that abandon big-box alternatives for technical guidance and community programming.
- Online Retail:Direct-to-consumer platforms compressing wholesale-retail hierarchies and enabling crowdfunding pre-orders for microbrand designers using desktop fabrication tools.
- Physical Stores:Mass-market retail footprints with seasonal inventory surges and impulse purchase placement strategies.
- Wholesale:Volume aggregation channels supplying institutional buyers and secondary retail tiers with standardized assortment configurations.
Specialty Shops sustain superior per-square-foot productivity. Online Retail is gaining share fastest through creator-led microbrand proliferation.
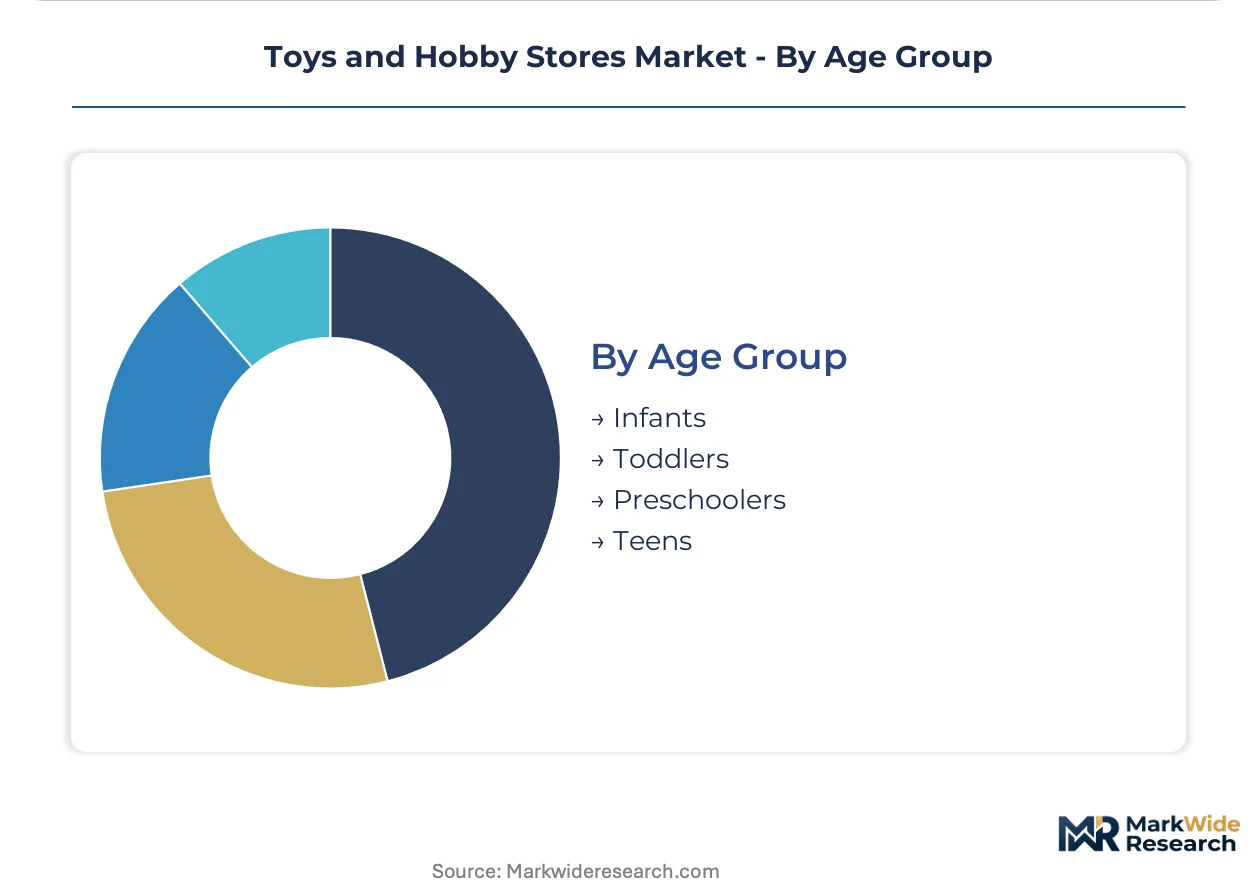
Age Group:
Safety specification intensity and price point elasticity vary sharply across developmental stages.
- Preschoolers:Large-format products with rounded edges and non-toxic material mandates dominating parental purchase frequency expansion.
- Teens:Complex assembly kits and collector-grade items with premium positioning and social signaling value.
- Infants:Sensory-focused formats with stringent choke hazard prevention and sterilizable surface requirements.
- Toddlers:Gross motor development tools with durability specifications for active manipulation and environmental exposure.
Preschoolers anchor volume throughput. Teens concentrate margin extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered modern hobby retail through model railway and craft traditions dating to the early twentieth century. The United States scaled mass-market toy distribution through post-war suburban expansion. China now anchors manufacturing concentration while cultivating domestic collector communities.
United States
Collector-driven premium pricing and adult hobbyist workshop programming sustain category momentum. ASTM F963 mechanical safety enforcement by the Consumer Product Safety Commission elevates compliance expenditure for import distributors. California and Texas host the densest specialty retail footprints, with Los Angeles and Dallas-Fort Worth anchoring action figure aftermarket arbitrage clusters.
Germany
Subscription-based kit deliveries and membership workshop access command recurring expenditure from established hobbyist communities. EU REACH chemical standards administered by ECHA tighten permissible polymer formulation thresholds. Bavaria and North Rhine-Westphalia concentrate craft supply manufacturing, with Nuremberg maintaining its historical position in model production.
China
Domestic collector community expansion and captive ABS plastic brick manufacturing anchor construction toy supply chains. GB standards regime administered by SAMR adds compliance layering for exporters. Guangdong Province and Yangtze River Delta clusters dominate fabrication capacity, with Shenzhen emerging as a hub for desktop 3D printing accessory microbrands.
United Kingdom
Heritage toy retail formats and curated specialty shop expertise capture enthusiast segments abandoning big-box alternatives. CE marking requirements under EU Toy Safety Directive govern mechanical and chemical specifications for cross-border trade. London and Southeast England sustain the highest per-square-foot productivity in specialty hobby retail.
Japan
Complex assembly kit demand and premium collector-grade positioning drive margin extraction from mature enthusiasts. METI industrial standards coordinate with international safety frameworks. Tokyo and Osaka metropolitan areas anchor the densest concentration of dedicated hobby retail and limited-edition release distribution.
Toys and Hobby Stores Market Vendor Landscape
The competitive structure tilts toward vertically integrated manufacturers with captive production assets and specialty retailers with curated assortment depth. Scale-driven mass merchants and digital-native direct-to-consumer platforms occupy secondary tiers. Strategic moves concentrate on backward integration into raw material supply and workshop programming investments that drive repeat visitation frequency.
Among Denmark-based manufacturers with captive polymer production, LEGO Group exemplifies vertical integration archetypes. Within specialty retail, Michaels Companies, Inc. and Hobby Lobby Stores Inc. occupy positions emphasizing curated inventory and vertical craft supply chain control. These three anchors represent divergent competitive vectors: manufacturing-centric consolidation versus retail-centric experience differentiation.
| Leading Market Players |
|---|
| Toys 'R' Us (WHP Global) |
| Hamleys |
| Michaels Companies, Inc. |
| Target Corporation |
| Città del Sole |
| Hobby Lobby Stores Inc. |
| LEGO Group |
| Walmart Inc. |
| GameStop Corp. |
| Others |
Supply Flow & Price Mechanics
Model-making artisans concentrated in Bavaria and North Rhine-Westphalia command wage premiums that compress margin spreads between premium collector-grade kits and mass-market alternatives, widening the pricing gap between German-engineered hobby products and Asian-manufactured entry-level equivalents.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and brand heritage. Premium collector-grade action figures from licensed manufacturers command substantial markups based on limited-edition scarcity and aftermarket arbitrage potential. Cost compression in economy-tier polymer play products is intensifying because phthalate-free reformulation expenses cannot be passed through to price-sensitive parents. Gift buyers demonstrate the highest price sensitivity, while dedicated collectors exhibit inelastic demand for authenticated limited releases.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and China operate hub-and-spoke patterns that consolidate inventory positioning ahead of seasonal demand spikes. Manufacturing concentration in Guangdong Province and Denmark feeds from ABS polymer resin, textile components, and specialized paint formulations. Single-source vulnerability in Danish captive brick production creates geographic dependency risks for construction toy supply chains. Distribution runs through a hybrid model blending direct-to-consumer platforms with specialty retail footprints that emphasize staff expertise and community programming.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU REACH compliance costs and Chinese manufacturing scale creates margin capture opportunities for operators with dual-hemisphere regulatory affairs capabilities.
For Market Incumbents: Anchor market position through backward integration into raw material suppliers for craft textiles and polymer compounds, insulating margin pools from phthalate-free transition cost escalation. Defend against creator-led microbrand displacement by expanding proprietary workshop programming that builds switching costs among hobbyist communities. Prioritize certification investment in ASTM F963 and EU Toy Safety Directive harmonization to maintain shelf access across North American and European markets. For New Entrants and Emerging Players: Specialty retailers with curated inventory expertise represent the most accessible channel partnership pathway for desktop fabrication microbrands seeking physical footprint validation. Target adult hobbyist segments in Germany and the United States where subscription-based engagement models demonstrate recurring revenue potential and lower customer acquisition costs. Pursue direct-to-consumer crowdfunding pre-orders as the primary go-to-market angle, bypassing wholesale-retail margin compression. For Investors and Strategic Acquirers: Vertically integrated craft supply manufacturers are the most active acquirer in this space, seeking distribution footprint expansion through specialty retail consolidation. Long-term viability hinges on regulatory compliance infrastructure that filters smaller competitors while preserving premium pricing power for certified suppliers. Monitor ECHA substance restriction announcements as the critical inflection signal for reformulation cost waves that will reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Supply | Captive sourcing of ABS polymer and textile components insulates margin pools from REACH-driven reformulation cost spikes. |
| Subscription-Based Membership Programming | Tiered loyalty structures in German and US markets convert transactional retail encounters into recurring revenue streams. |
| Dual-Jurisdiction Certification Harmonization | Simultaneous ASTM F963 and EU Toy Safety Directive compliance preserves shelf access across North American and European retail networks. |
| Desktop Fabrication Microbrand Launch | Crowdfunding pre-orders for creator-led action figure accessories bypass conventional mold-based manufacturing minimums. |
| Specialty Retail Footprint Expansion | Curated shop formats with trained staff expertise capture enthusiast segments abandoning big-box alternatives for technical guidance. |
Methodological Framework
Bottom-up hobbyist demand modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with specialty retail buyers, craft supply procurement managers, toy safety compliance officers, and independent designer collectives were validated against secondary sources including CPSC enforcement databases, ECHA substance restriction registers, customs trade records, and retail audit data from Nielsen and Circana. This dual-layer approach triangulates volume estimates across construction toys, craft kits, action figures, and collector-grade merchandise categories.
Historical trendline analysis of parental purchase frequency, collector aftermarket arbitrage volumes, and workshop program enrollment rates informed the projection framework. Segmentation modeling spanned product type, customer archetype, distribution channel, and age group dimensions across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating regulatory compliance cost pass-through assumptions and seasonal demand volatility patterns specific to holiday-driven purchase clustering.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance restriction expansion, ABS polymer supply concentration disruptions, and migration of enthusiast buyers toward digital fabrication alternatives. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hobbies & Collectibles
Foosball Table Market
Hobbies & Collectibles
Stamp Collecting Market
Hobbies & Collectibles
Spiritual and Devotional Products Market
Hobbies & Collectibles
Mannequins Market
Hobbies & Collectibles
Plastic Model Kit Market
Hobbies & Collectibles
Animation Collectibles Market
Hobbies & Collectibles
Sports Trading Card Market
Hobbies & Collectibles
Coin Collection Market