
 Animation Collectibles Market | 2026-2036
Animation Collectibles Market Size, Share, and Industry Trends Forecast 2026-2036
Animation Collectibles Market Analysis
Capital-intensity divergence between mass-market vinyl producers and artisan resin studios is redrawing competitive boundaries. Funko leverages automated molding at scale to dominate budget-tier figure distribution. Bandai anchors premium mecha and anime statue lines through captive Japanese manufacturing. LEGO Group extends its brick-based animation IP partnerships into collectible display sets for adult fans.
Animation collectibles comprise licensed physical merchandise reproducing characters from film, television, gaming, and comic properties, typically manufactured through injection-molded vinyl, cold-cast resin, or machined polystone with hand-painted finishing and serialized certificates of authenticity. These items serve dual commercial purposes: mass-market toy retail for children and speculative investment-grade assets for adult collectors seeking appreciation and community status. Figures and statues capture the dominant margin pools as high-ASP categories with strong aftermarket liquidity, while trading cards experience accelerating velocity among crossover gaming audiences. Plush toys occupy a mature volume position sustained by gift-market cyclicality rather than collector premiums.
The US Consumer Product Safety Commission governs material safety and small-part labeling for collectibles marketed to children under fourteen, while the EU REACH regulation restricts phthalate and heavy-metal content in imported vinyl and painted finishes. Japan's Ministry of Economy, Trade and Industry coordinates intellectual property export frameworks that facilitate licensed merchandise trade. Stakeholders must monitor evolving digital ownership verification standards and secondary-market platform compliance obligations as authentication technology matures.
Market Dynamics
Digital authentication infrastructure is restructuring how provenance and ownership transfer occur in animation collectibles, compressing information asymmetry between buyers and sellers while elevating trust premiums for verified pieces.
Growth Catalysts
- Adult Collector Demographics:Speculative asset-seeking behavior among 25-45 year-old buyers is elevating average selling prices for limited-edition resin statues and serialized vinyl figures. This cohort treats physical collectibles as alternative store-of-value instruments alongside traditional investments.
- EU REACH Compliance:Stricter phthalate and heavy-metal restrictions on imported painted finishes are filtering out low-quality manufacturers, creating quality-tier separation that benefits compliant producers with certified supply chains.
- NFC and Blockchain Integration:Embedded near-field communication chips paired with distributed ledger verification are enabling instantaneous authenticity checks at point-of-sale and secondary market transfer.
Market Restraints
- Petroleum-Derived Vinyl Volatility:Injection-molded figure production depends on PVC resin pricing indexed to crude oil markets, exposing mass-market producers to input cost swings without pricing power to pass through.
- Japanese Manufacturing Concentration:Premium polystone and cold-cast resin statue fabrication clusters in Osaka and Tokyo prefectures, creating geographic single-point-of-failure risk for Western licensors.
- Hand-Painting Bottleneck:Artisan finishing capacity scales linearly with skilled labor hours, capping output velocity for limited-edition releases regardless of mold production speed.
Strategic Opportunities
- Southeast Asian Expansion:Indonesia, Vietnam, and Thailand exhibit rising disposable income among urban millennials with limited local access to licensed anime merchandise, creating first-mover retail and distribution openings.
- Gaming Crossover Formats:Physical collectibles tied to blockchain-verified in-game assets are attracting hybrid digital-physical collectors from esports and gacha gaming communities.
- Carbon Border Adjustment Mechanism:EU importers of Chinese and Southeast Asian manufactured goods face phased carbon intensity reporting requirements, rewarding early adopters of low-emission production methods with competitive positioning.
Industry Challenges
- Sculptor Talent Pipeline:Digital sculpting proficiency in ZBrush and Blender combined with traditional anatomy knowledge is scarce, extending product development timelines and inflating freelance rates.
- Licensing Agreement Complexity:Multi-territory IP rights fragmentation across film studios, streaming platforms, and original creators creates legal clearance bottlenecks for international product releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animation Collectibles Market |
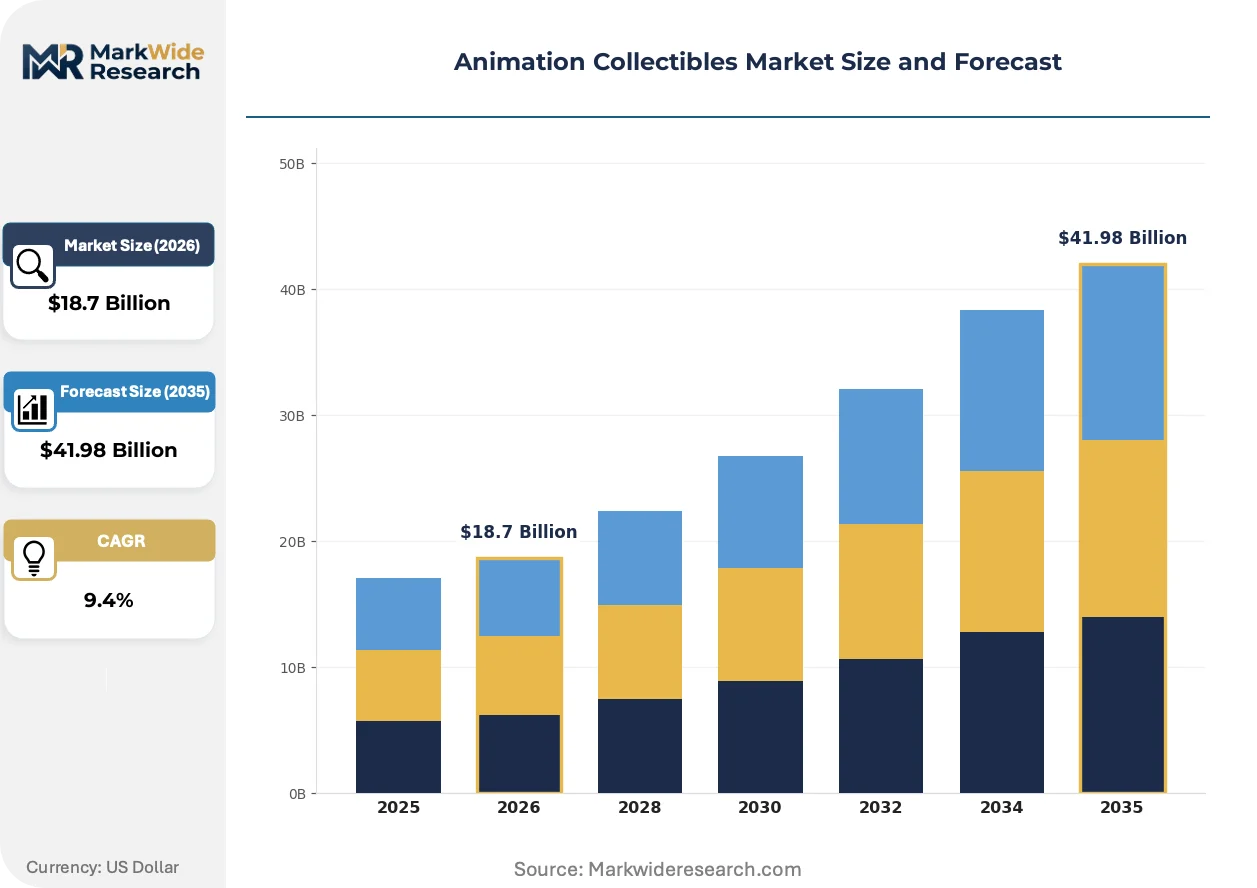
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Figures, Statues, Plush Toys, Trading Cards End User: Children, Teens, Collectors, Adult Fans Sales Channel: Online Retail, Brick-and-Mortar, Auctions, Conventions Price Tier: Budget, Mid-Range, Premium, Limited Edition |
| Companies Covered | Ravensburger, Funko, Hasbro, Bandai, MGA Entertainment, LEGO Group, TOMY, JAKKS Pacific, Mattel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animation Collectibles Market Emerging Trajectories
Authentication technology and manufacturing automation are converging to separate premium collectible tiers from mass-market commodity production, reshaping how value accrues across the product pyramid.
Blockchain-based provenance tracking is supplanting paper certificates of authenticity in the premium statue and figure segment. High-value collectors in Japan and the United States now expect immutable ownership records transferable across secondary market platforms. This shift is compressing fraud incidence and elevating price transparency for liquid resale.
EU REACH enforcement on phthalate content in painted vinyl surfaces is tightening import inspection protocols at Rotterdam and Hamburg ports. Manufacturers without certified laboratory testing partnerships face detention and destruction risk. Japanese exporters with pre-submitted conformity documentation are capturing shelf space from slower-adapting competitors.
Collector purchasing has migrated toward direct-to-manufacturer pre-order models, bypassing traditional hobby shop distribution. Crowdfunding platforms and brand-owned e-commerce portals in China and South Korea now capture first-allocation rights for limited pieces. This channel compression is marginalizing wholesale distributors and accelerating sell-out velocity for hyped releases.
Animation Collectibles Market Segmentation
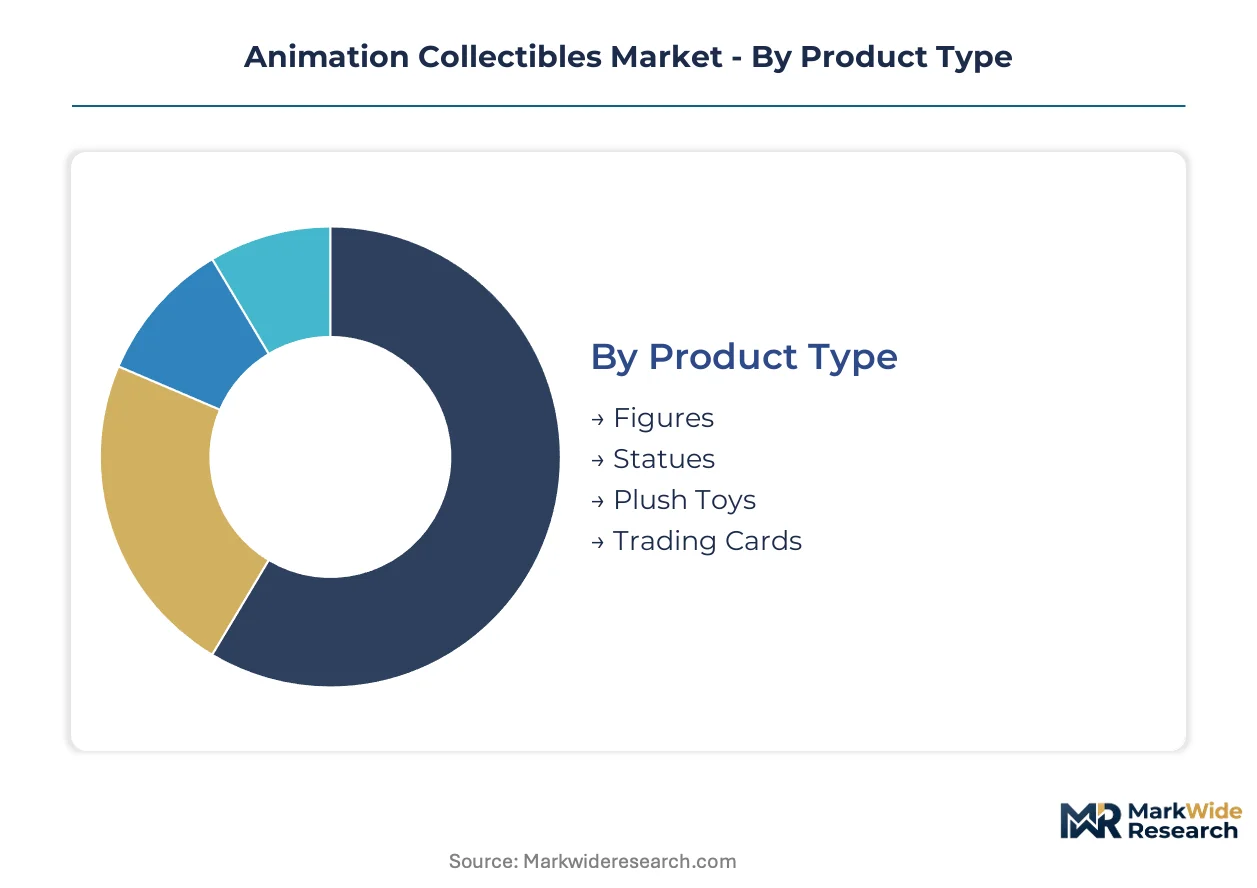
Animation collectibles segment along four distinct dimensions that shape manufacturing investment, distribution strategy, and margin capture. Product type and price tier determine production complexity and authentication requirements, while end user demographics and sales channel preferences dictate marketing spend allocation and inventory positioning.
Product Type:
Figures and statues dominate export-heavy premium manufacturing from Japan and China, while plush toys and trading cards serve more domestic-oriented gift and gaming markets.
- Figures:Injection-molded vinyl or ABS constructions with hand-painted details and serialized bases. Demand concentrates among adult collectors in Japan and the United States seeking appreciation potential from limited production runs. This segment captures the deepest margin pools through direct-to-consumer pre-order models.
- Statues:Cold-cast resin or polystone compositions requiring artisan finishing and substantial shipping protection. Osaka and Tokyo prefectures anchor global supply, with Western licensors dependent on this geographic concentration for premium releases. Hand-painting bottlenecks constrain output velocity regardless of mold capacity.
- Plush Toys:Textile-based soft goods manufactured at scale in Vietnam and Indonesia for mass retail distribution. Gift-market cyclicality sustains volume without collector premiums.
- Trading Cards:Paper or cardstock collectibles with holographic or embossed security features, accelerating among crossover gaming audiences in South Korea and the United States. Secondary market liquidity lags behind figures and statues.
Figures hold the largest share; momentum sits with statues as authentication technology elevates provenance premiums.
End User:
Collector and adult fan segments drive premium pricing power, while children and teens anchor volume through mass-market retail channels with lower per-unit margins.
- Children:Safety-regulated play products governed by US Consumer Product Safety Commission small-part labeling and EU REACH material restrictions. Mass retail distribution through big-box chains dominates procurement.
- Teens:Entry-level collectible purchasing with social media-influenced brand preferences. Online retail and convention attendance shape discovery patterns.
- Collectors:Speculative asset-seeking behavior among 25-45 year-olds treating physical pieces as alternative store-of-value instruments. Blockchain-verified provenance and NFC authentication are becoming baseline expectations.
- Adult Fans:Display-oriented purchasing of premium and limited-edition pieces with substantial discretionary income. Direct-to-manufacturer pre-order participation is highest in this cohort.
Collectors generate the highest revenue per capita; adult fans are climbing the fastest as channel compression accelerates sell-out velocity.
Sales Channel:
Channel compression is marginalizing wholesale distributors, with online retail and manufacturer-direct platforms capturing first-allocation rights previously held by brick-and-mortar hobby shops.
- Online Retail:Brand-owned e-commerce portals and marketplace platforms enabling global reach without physical inventory commitment. Crowdfunding integration allows production-scale validation before manufacturing commitment.
- Brick-and-Mortar:Hobby shops and specialty retailers facing margin pressure from channel compression. Geographic concentration in urban Japan and United States coastal cities sustains surviving operators.
- Auctions:Secondary market liquidity venues for authenticated premium pieces, with blockchain-verified ownership records compressing information asymmetry between buyers and sellers.
- Conventions:Event-based exclusive releases and direct fan engagement driving hype cycles and sell-out velocity. Comic-Con and anime expo circuits anchor the global calendar.
Online retail commands the largest share; conventions are expanding most quickly as experiential marketing investments intensify.
Price Tier:
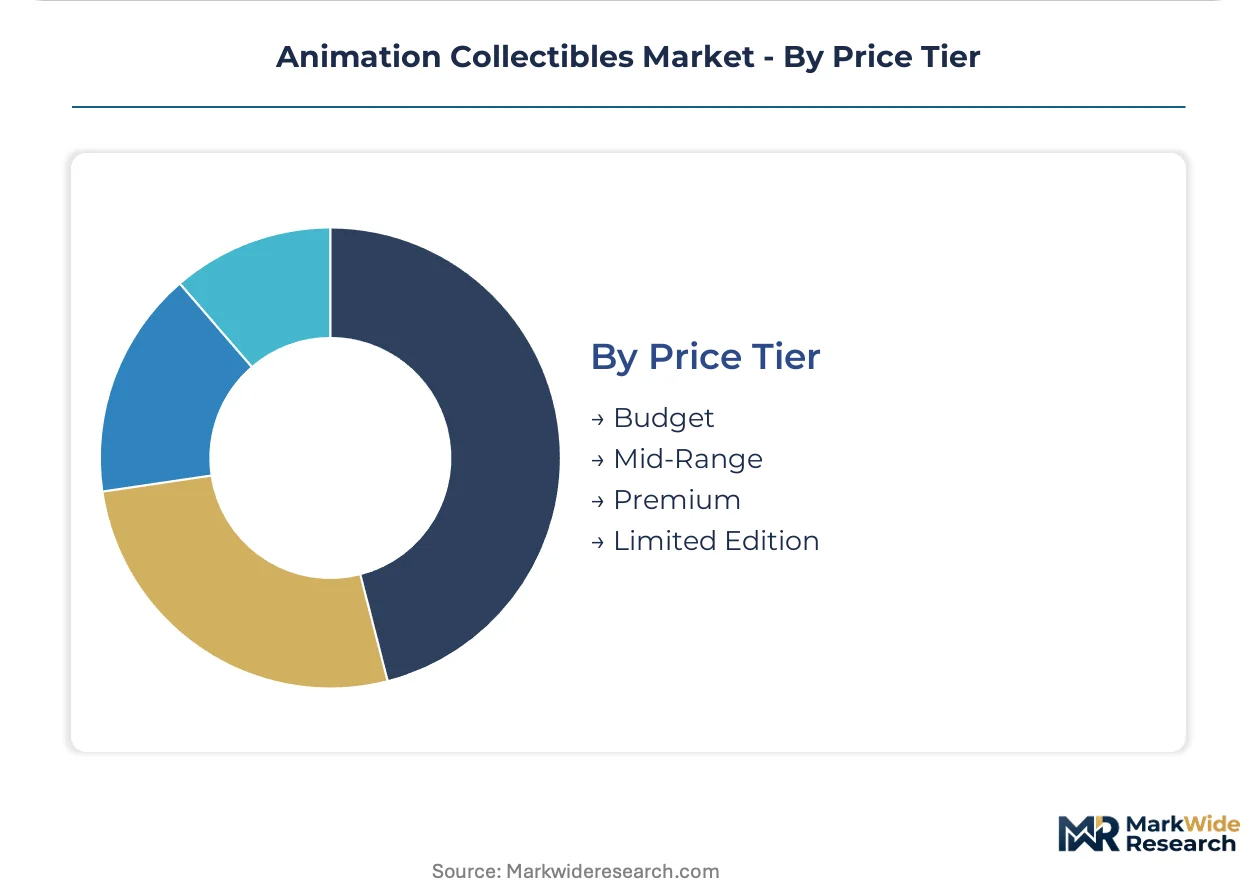
Manufacturing automation separates budget-tier commodity production from artisan-limited premium and limited-edition categories with steep price appreciation curves.
- Budget:Mass-market vinyl figures produced through automated molding at scale. Funko dominates this tier through distribution breadth and IP licensing velocity.
- Mid-Range:Enhanced detailing and larger scale without serialized scarcity. This tier faces the greatest pressure from adjacent category encroachment.
- Premium:Polystone and cold-cast resin constructions with hand-painted finishing and certificates of authenticity. Bandai and Japanese captive manufacturers anchor supply.
- Limited Edition:Serialized releases with absolute production caps, often paired with NFC chips and blockchain registration. Speculative demand from investment-oriented collectors drives aftermarket premiums.
Premium captures the deepest margins; limited edition is gaining share fastest as authentication infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese collectors demonstrate the lowest price elasticity, absorbing premiums for serialized resin statues, while Southeast Asian buyers remain highly sensitive to mid-range figure pricing. Demand concentration in Tokyo, Osaka, and Nagoya sustains artisan manufacturing clusters. Regulatory fragmentation across import markets is reshaping competitive access.
United States
Adult collectors aged 25-45 drive speculative demand for blockchain-verified limited editions. The US Consumer Product Safety Commission enforces small-part labeling and phthalate limits on vinyl imports. Los Angeles and New York City host the densest specialty retailer networks, with direct-to-consumer pre-orders bypassing traditional distribution.
Japan
Domestic otaku culture sustains the world's deepest market for premium polystone statues and artisan-finished figures. METI coordinates intellectual property export frameworks that facilitate licensed merchandise trade. Osaka and Tokyo prefectures concentrate global cold-cast resin fabrication, with hand-painting bottlenecks constraining output regardless of mold capacity.
China
Crossover gaming audiences fuel trading card velocity and gacha-style figure demand among urban millennials. SAMR enforces product safety standards and counterfeit enforcement on e-commerce platforms. Guangdong and Zhejiang provinces anchor mass-market vinyl molding at scale, with Shenzhen emerging as a crowdfunding platform hub for direct-to-consumer releases.
Germany
EU REACH compliance on phthalate and heavy-metal content filters import quality tiers, benefiting certified supply chains. ECHA enforcement at Rotterdam and Hamburg ports detains non-conforming painted finishes. Berlin and Munich sustain boutique hobby shop networks, though channel compression is marginalizing wholesale distributors.
South Korea
Esports and webtoon IP crossovers attract hybrid digital-physical collectors with substantial disposable income. The national consumer protection regulator enforces labeling standards on youth-targeted collectibles. Seoul's Gangnam and Hongdae districts concentrate pop-up retail and convention circuits, with brand-owned e-commerce capturing first-allocation rights.
Animation Collectibles Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale-driven vinyl molders commanding budget-tier distribution and captive Japanese manufacturers anchoring premium resin production. The market structure rewards IP licensing velocity and authentication infrastructure investment. Three archetypes dominate: automated mass-market producers, artisan-limited premium fabricators, and hybrid digital-physical platform operators. Competitive moves center on direct-to-consumer channel compression and blockchain provenance integration.
Among scale-driven vinyl specialists, Funko exemplifies automated molding dominance through distribution breadth. Bandai occupies a position within the captive Japanese manufacturing tier, representing artisan-limited premium production. LEGO Group sits within the brick-based IP extension archetype, anchoring collectible display sets for adult fans. These three companies illustrate how divergent capital intensity separates mass-market commodity production from investment-grade collectible tiers.
| Leading Market Players |
|---|
| Ravensburger |
| Funko |
| Hasbro |
| Bandai |
| MGA Entertainment |
| LEGO Group |
| TOMY |
| JAKKS Pacific |
| Mattel |
| Others |
Supply Flow & Price Mechanics
Direct-to-manufacturer pre-order contracts lock in both resin statue allocation and price visibility for adult collectors, compressing wholesale margins while securing artisan production slots in Osaka and Tokyo prefectures against competing Western licensors.
Pricing Analysis
Aftermarket resale premiums on authenticated limited editions drive lifetime value far beyond initial retail. Three-tier pricing structure across premium, standard, and economy levels separates hand-painted polystone statues from injection-molded vinyl figures and mass-market plush. Price differentiation rests on authentication infrastructure investment and serialized scarcity. Cost compression in budget-tier vinyl intensifies because crude oil-indexed PVC resin swings erode producer margins. Teen collectors exhibit highest price sensitivity, while Japanese adult collectors absorb premiums with minimal elasticity.
Supply Chain Analysis
Container availability on Asia-North America trade lanes constrains inbound logistics costs for resin statue shipments from Japanese ports. Manufacturing concentrates in Japan, China, and Vietnam. Premium cold-cast resin production draws from Osaka artisan clusters, while Guangdong and Zhejiang provinces anchor mass-market vinyl molding. Supply chain risk centers on single-source vulnerability for hand-painting talent in Tokyo prefectures. Distribution runs through brand-owned e-commerce portals and crowdfunding platforms, marginalizing traditional wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital-native collectibles and blockchain-verified in-game assets pose substitution threats that physical collectible incumbents must navigate through authentication infrastructure investment and hybrid digital-physical product development.
For Market Incumbents: Fortify artisan manufacturing relationships in Osaka and Tokyo through capacity reservation agreements that preempt competitor access to hand-painting talent. Deepen backward integration into polystone resin formulation to offset petroleum-derived input volatility. Channel control through direct-to-consumer pre-order platforms defends margin position against crowdfunding platform entrants.
For New Entrants and Emerging Players: Anchor in Indonesia, Vietnam, and Thailand where urban millennial demand for licensed anime merchandise outpaces local retail infrastructure. Gaming crossover formats with blockchain-verified in-game redemption codes represent the most penetrable white-space. Convention circuit exclusives and pop-up retail in Seoul's Gangnam district provide go-to-market velocity without legacy distributor relationships.
For Investors and Strategic Acquirers: Captive Japanese manufacturing specialists with METI-coordinated IP export frameworks command scarcity premiums in an increasingly authentication-driven market. Long-term viability hinges on digital provenance infrastructure ownership rather than pure production scale. Watch for inflection when NFC-embedded figure releases exceed paper certificate editions in secondary market liquidity.
| Strategic Initiative | Industry Significance |
|---|---|
| Authentication Infrastructure Deployment | NFC and blockchain integration elevates trust premiums for verified pieces across Japanese and US secondary markets. |
| Direct-to-Consumer Channel Expansion | Brand-owned e-commerce portals capture first-allocation rights previously held by brick-and-mortar hobby shops. |
| Artisan Capacity Reservation | Long-term sculptor contracts in Osaka prefectures preempt competitor access to hand-painting bottlenecks. |
| Gaming Crossover Format Development | Physical collectibles with blockchain-verified in-game assets attract hybrid digital-physical collectors from esports communities. |
| EU REACH Compliance Certification | Pre-submitted conformity documentation at Rotterdam and Hamburg ports captures shelf space from slower-adapting competitors. |
Methodological Framework
Operator-level perspectives from resin statue sculptors, vinyl mold production managers, IP licensing directors, and specialty retailer buyers anchored the qualitative base. Primary interviews combined with secondary validation from customs trade records, SEC filings of publicly traded toy manufacturers, METI export framework documentation, and EU REACH enforcement notices. Bottom-up demand modeling across product type, price tier, end user demographic, and sales channel dimensions triangulated against top-down market sizing.
Sensitivity analysis tested forecast robustness across petroleum price volatility scenarios and authentication technology adoption curves. The analytical framework segmented by product type, price tier, end user demographic, and sales channel across the analysis window. CAGRs derived from regression analysis against macroeconomic indicators and collector sentiment indices. Industry-specific inputs included PVC resin price trajectories and sculptor freelance rate inflation.
Material uncertainties — sculptor talent pipeline constraints, licensing agreement complexity delays, and digital collectible substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about authentication technology maturation and regional regulatory enforcement intensity. Recalibration cycles align with material shifts in crude oil markets and EU carbon border adjustment implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hobbies & Collectibles
Toys and Hobby Stores Market
Hobbies & Collectibles
Spiritual and Devotional Products Market
Hobbies & Collectibles
Sports Trading Card Market
Hobbies & Collectibles
Plastic Model Kit Market
Hobbies & Collectibles
Coin Collection Market
Hobbies & Collectibles
Foosball Table Market
Hobbies & Collectibles
Mannequins Market
Hobbies & Collectibles
Stamp Collecting Market