
 Online Fitness Market | 2026-2036
Online Fitness Market Size, Share, and Industry Trends Forecast 2026-2036
Online Fitness Market Analysis
Premium live-class tier differentiation is collapsing as commoditized on-demand libraries flood every price band. Peloton leverages its captive hardware-software ecosystem to sustain subscription stickiness. Zwift dominates cycling simulation with proprietary course rendering that anchors competitive user retention. WHOOP differentiates through recovery analytics that extend beyond basic activity tracking into sleep and strain scoring.
Online fitness denotes digitally delivered exercise instruction, biometric feedback integration, and performance analytics accessed through internet-connected screens or wearable sensors. Platforms encode video streams at adaptive bitrates to maintain real-time interactivity across variable bandwidth conditions, serving both individual consumers and employer wellness administrators. Live classes command higher monthly subscription pricing than on-demand libraries, while personalized coaching captures the steepest per-user revenue. Wearable device integration is maturing fastest as Apple Watch and Garmin APIs standardize heart-rate data exchange.
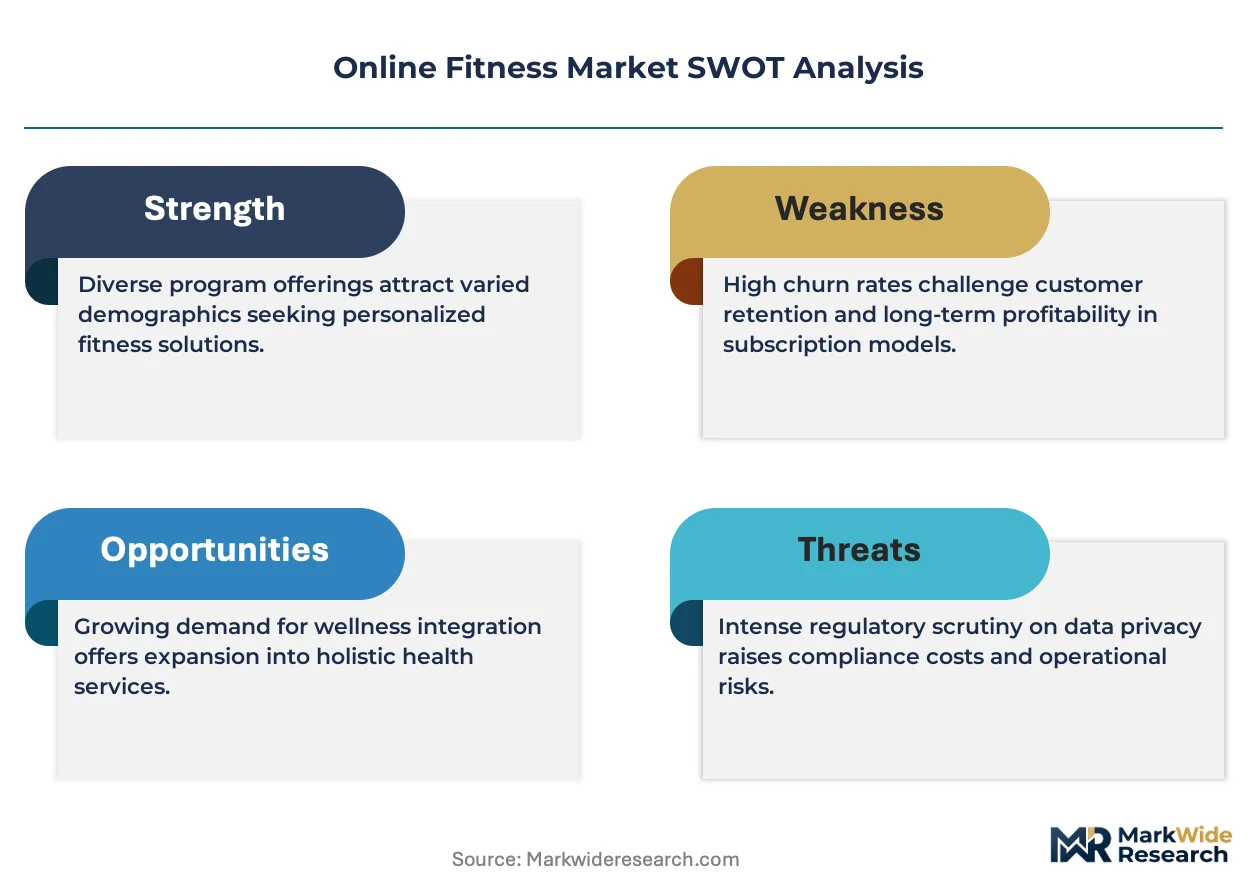
The FDA scrutinizes health claims tied to wearable-derived metrics that platforms display, while the FTC polishes subscription cancellation transparency following enforcement actions against deceptive billing practices. The EU AI Act will classify biometric inference tools used for workout personalization as high-risk systems, imposing conformity assessments before European market access. Stakeholders must decide whether to absorb compliance costs for biometric AI features or retreat to simpler motion-tracking offerings that evade regulatory thresholds.
Market Dynamics
The online fitness market faces commoditization pressure as on-demand video libraries proliferate across every subscription tier, eroding premium differentiation that once sustained higher pricing for live-streamed classes.
Growth Catalysts
- Employer wellness mandates:Corporate benefits administrators are expanding live-streamed platform subscriptions as tax-advantaged employee perks, particularly in dense urban labor markets where gym access remains inconvenient.
- Wearable API standardization:Apple Watch and Garmin heart-rate data exchange protocols are maturing, enabling real-time biometric feedback loops that increase workout personalization depth and platform switching costs.
- FDA regulatory clarity:The FDA's tightening scrutiny of wearable health claims is paradoxically advantaging compliant platforms that integrate validated metrics, creating a certification moat against unverified competitors.
Market Restraints
- Content production cost inflation:Studio-quality live-class production requires specialized lighting, audio engineering, and instructor talent that scales poorly across time zones.
- Bandwidth infrastructure inequality:Adaptive bitrate streaming depends on fiber and 5G penetration that concentrates in metropolitan corridors, excluding rural subscriber acquisition.
- EU AI Act compliance burden:Biometric inference tools for workout personalization face high-risk system classification, forcing conformity assessments that delay European market entry for AI-dependent features.
Strategic Opportunities
- Recovery analytics white space:Sleep and strain scoring beyond basic activity tracking remains underdeveloped, offering differentiation through WHOOP-style physiological monitoring integration.
- FTC billing transparency enforcement:Subscription cancellation clarity mandates create competitive advantage for platforms with frictionless churn processes that build trust against deceptive-practice competitors.
- Hardware-software bundling:Captive equipment ecosystems like connected bikes and rowing machines lock in subscription stickiness through proprietary data formats that resist platform switching.
Industry Challenges
- Biometric data engineering talent scarcity:Platforms struggle to hire machine learning specialists capable of translating heart-rate variability into actionable recovery recommendations without crossing medical-device regulatory lines.
- Cross-platform integration complexity:Legacy fitness devices with proprietary data formats resist API standardization, forcing expensive middleware development for unified dashboard experiences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Fitness Market |
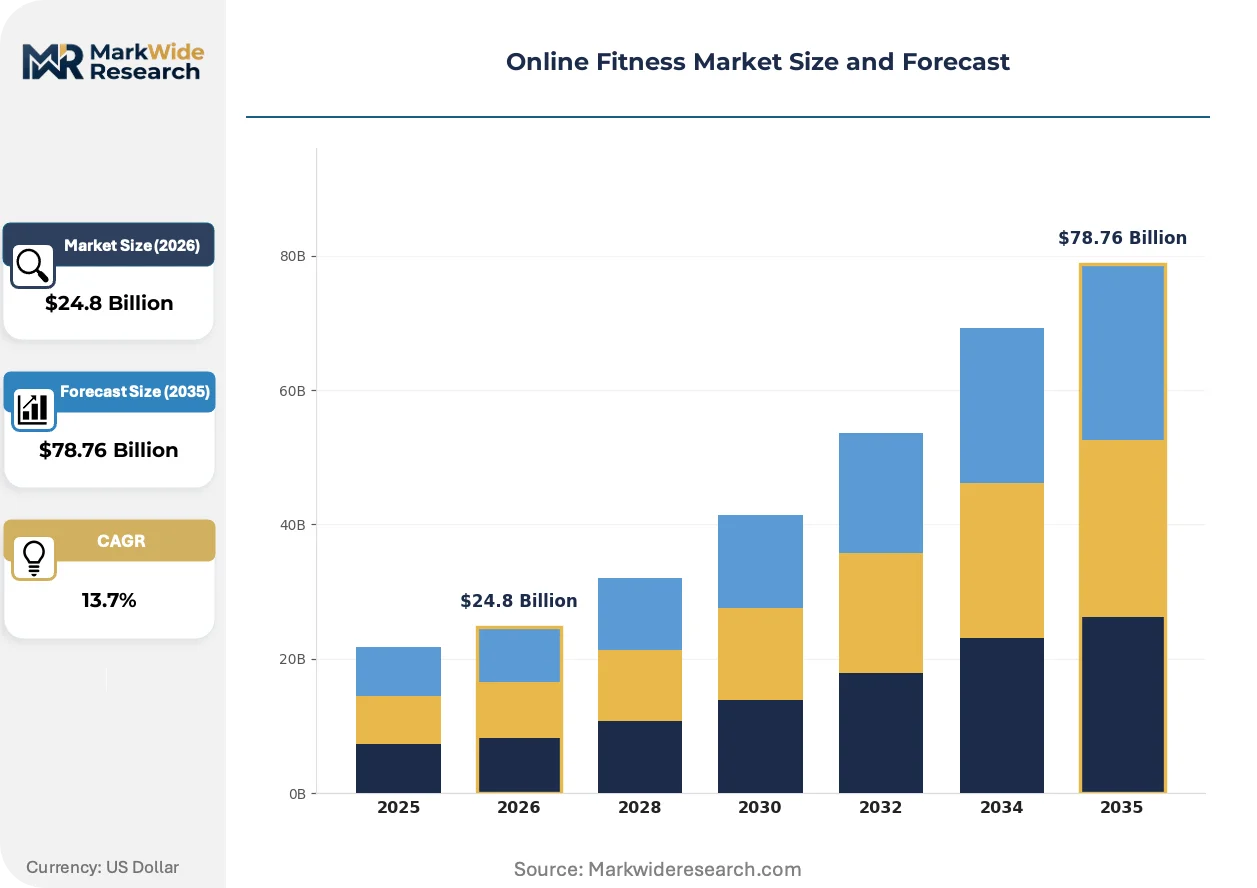
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $78.76 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Live Classes, On-Demand Videos, Personalized Coaching, Fitness Challenges Subscription Model: Monthly Subscription, Annual Membership, Pay-Per-Class, Freemium Target Audience: Beginner Fitness Enthusiasts, Advanced Athletes, Seniors, Busy Professionals Platform Type: Mobile Apps, Desktop Websites, Smart TVs, Wearable Devices |
| Companies Covered | WHOOP, Future, Peloton, MyFitnessPal, Strava, Nike, Noom, Zwift, Under Armour, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Fitness Market Emerging Trajectories
Real-time interactivity standards are compressing latency tolerances as competitive cycling simulation and multiplayer fitness gaming raise user expectations for synchronous performance.
AI-generated coaching cues are supplanting pre-recorded instructor scripts by dynamically adjusting verbal encouragement based on live heart-rate thresholds and movement pattern recognition. Boutique studio chains are adopting these adaptive audio systems to maintain perceived personalization without scaling human instructor headcount. The technology is compressing pricing power for static on-demand libraries that cannot match responsive feedback loops.
The EU AI Act's high-risk classification for biometric inference is forcing platforms to segregate European product roadmaps from AI-enhanced features deployed elsewhere. Developers must now maintain parallel codebases or strip personalization engines from EU releases. Cycling simulation and competitive leaderboard platforms face the steepest compliance costs given their reliance on physiological strain modeling.
Enterprise procurement of wellness benefits is consolidating vendor relationships as HR administrators demand single-dashboard reporting across multiple fitness modalities. Brokers and benefits platforms are displacing direct-to-employer sales by aggregating subscription purchasing power and standardizing implementation support. This concentration is most visible in United States metropolitan corridors where employer-sponsored fitness benefits have achieved highest penetration density.
Online Fitness Market Segmentation
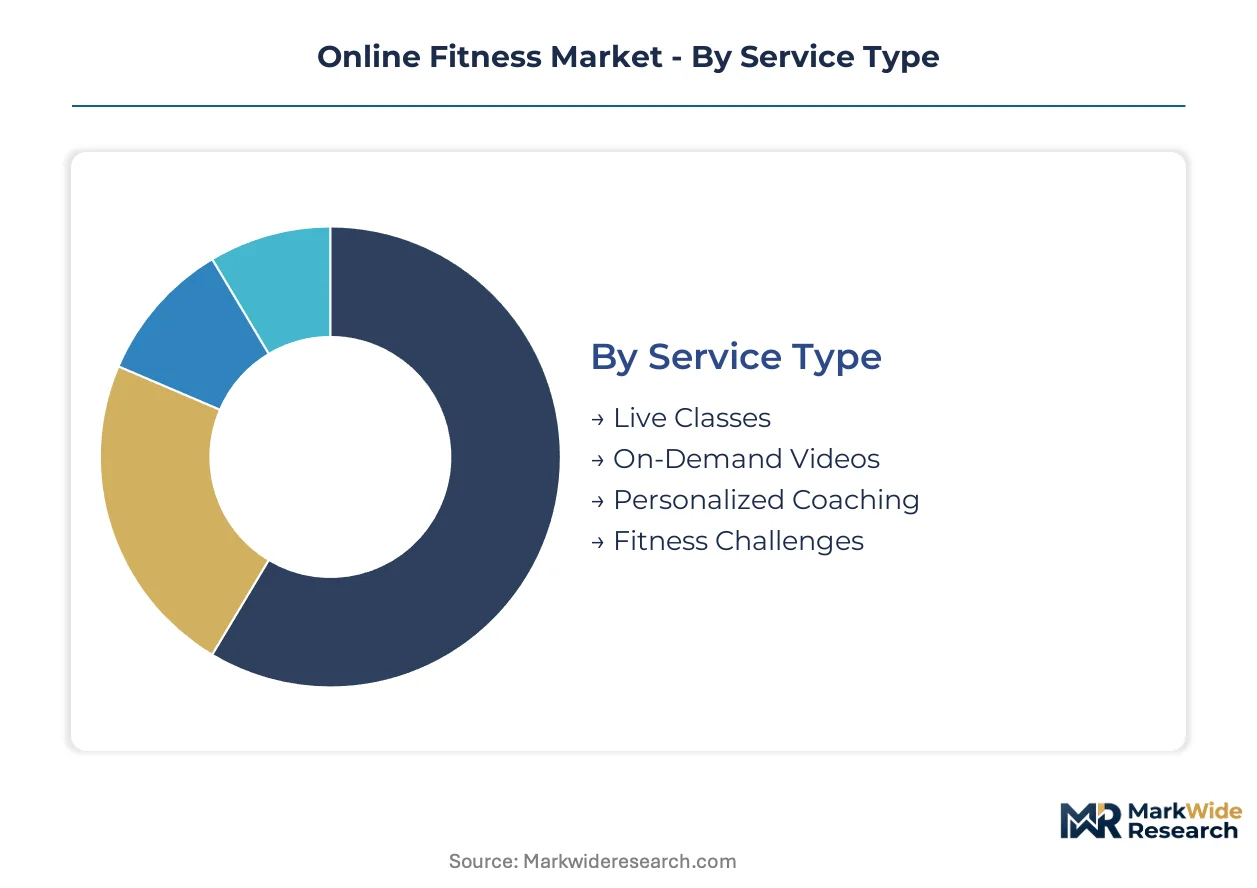
Segmentation in online fitness reveals how pricing power fragments across delivery modes and audience sophistication. Platforms must calibrate content depth, biometric integration, and subscription mechanics to match distinct willingness-to-pay profiles across user cohorts.
Service Type:
Margin pools concentrate in synchronous formats that command premium pricing through instructor scarcity and real-time accountability.
- Live Classes:Real-time video streams with two-way instructor interaction require specialized studio infrastructure and talent scheduling across time zones. Corporate wellness administrators in United States urban corridors purchase these at enterprise rates to replace gym memberships for distributed workforces.
- On-Demand Videos:Pre-recorded libraries with adaptive bitrate encoding serve bandwidth-constrained subscribers. Commoditization pressure from platform proliferation is collapsing differentiation that once sustained tiered pricing.
- Personalized Coaching:One-on-one video sessions with certified trainers capture steepest per-user revenue through bespoke programming.
- Fitness Challenges:Time-bound competitive events with leaderboard mechanics drive engagement spikes through social accountability.
Live Classes hold installed capacity. Personalized Coaching is rotating up the share rankings.
Subscription Model:
Revenue predictability varies sharply by commitment length and payment timing.
- Monthly Subscription:Recurring billing with cancellation flexibility dominates direct-to-consumer acquisition. FTC enforcement actions against deceptive churn practices are advantaging platforms with frictionless cancellation flows.
- Annual Membership:Upfront payment locks in twelve-month commitment at discounted effective monthly rates. Employer wellness benefits in United States metropolitan markets increasingly default to annual procurement cycles.
- Pay-Per-Class:Transactional access without recurring obligation serves intermittent users.
- Freemium:Limited content tiers with premium upgrade gates expand top-funnel acquisition.
Annual Membership anchors enterprise procurement. Monthly Subscription is climbing the fastest as cancellation transparency mandates reshape competitive positioning.
Target Audience:
Physiological monitoring intensity and coaching sophistication diverge across fitness maturity levels.
- Beginner Fitness Enthusiasts:Entry-level users requiring form correction and progressive overload guidance. Platform investment concentrates here due to largest addressable population and highest churn risk.
- Advanced Athletes:Performance-optimized users demanding power zone training and race simulation. WHOOP-style recovery analytics and strain scoring command premium attachment rates among this cohort.
- Seniors:Low-impact programming with fall-risk modifications and medication-aware coaching.
- Busy Professionals:Time-compressed workout formats integrated with calendar scheduling and travel-friendly equipment requirements.
Advanced Athletes drive per-user revenue expansion. Busy Professionals are gaining share fastest as hybrid work normalization sustains demand for flexible scheduling.
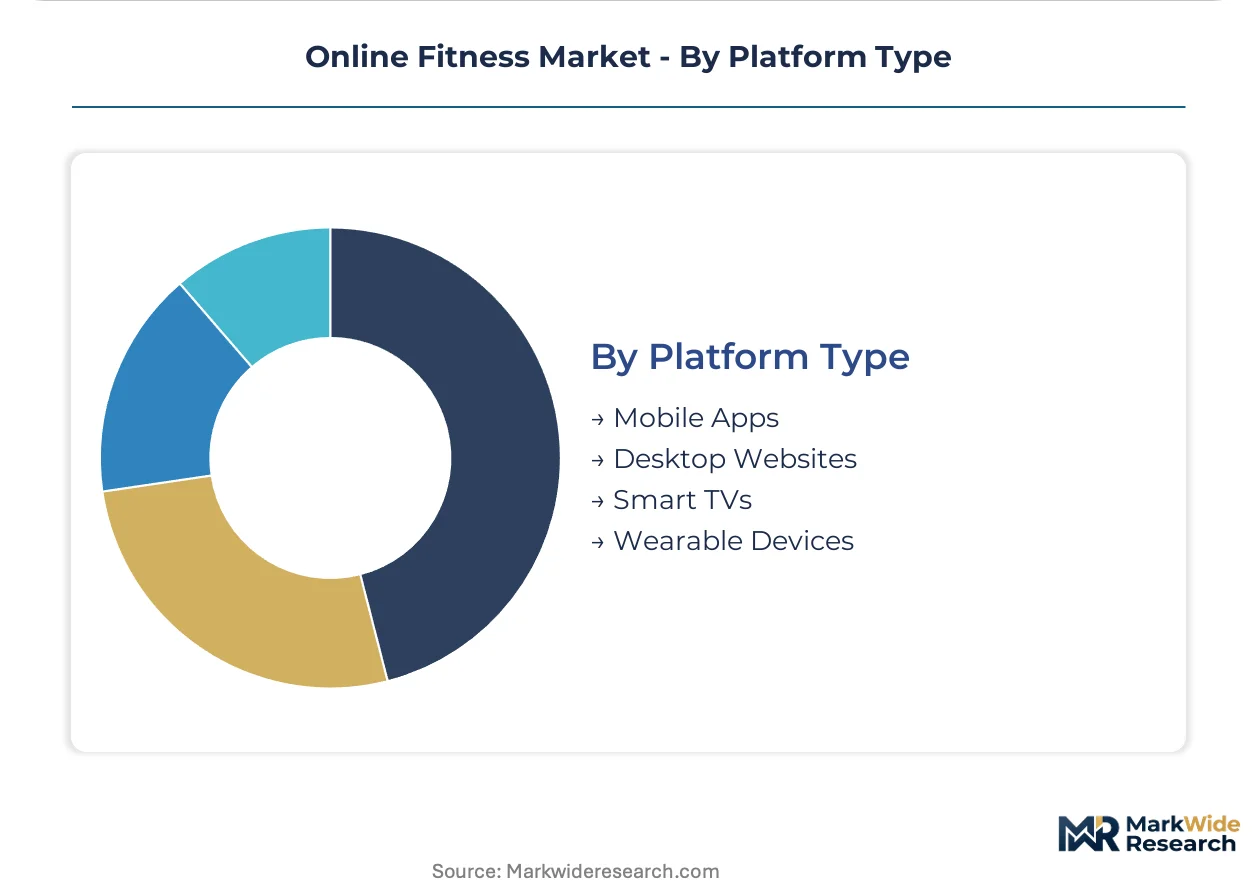
Platform Type:
Biometric data fidelity and interactivity depth depend on hardware-software integration tightness.
- Mobile Apps:Smartphone-native delivery with camera-based form tracking and GPS-enabled outdoor workouts. Apple Watch and Garmin API standardization is maturing heart-rate data exchange for real-time feedback loops.
- Desktop Websites:Larger-screen formats suited for strength training demonstrations and detailed performance analytics review.
- Smart TVs:Living-room immersive experience with casting protocols and family multi-user profiles.
- Wearable Devices:Native sensor integration with haptic coaching cues and always-on physiological monitoring.
Mobile Apps hold installed capacity. Wearable Devices is rotating up the share rankings as FDA scrutiny of health claims creates certification moats for compliant platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform development and subscription revenue cluster where employer wellness benefits intersect with dense metropolitan populations and robust digital infrastructure. The United States dominates installed capacity, while European markets face divergent regulatory treatment under the EU AI Act.
United States
Employer-sponsored fitness benefits and urban subscription density drive market concentration. The FTC enforces subscription cancellation transparency following enforcement actions against deceptive billing practices. New York and San Francisco corridors host the highest enterprise procurement rates for live-streamed corporate wellness platforms.
Germany
Corporate wellness mandates and statutory health insurance integration expand platform adoption. The EU AI Act classifies biometric inference tools as high-risk systems, imposing conformity assessments. Berlin and Munich clusters concentrate developer talent for wearable API standardization and heart-rate data exchange protocols.
United Kingdom
Hybrid work normalization sustains demand for flexible scheduling and home-based fitness solutions. The UK Information Commissioner's Office aligns with GDPR biometric data processing requirements. London's fintech and professional services sectors purchase enterprise subscriptions at premium rates for distributed workforces.
Japan
Aging demographics and preventive health awareness expand senior-focused platform segments. METI promotes digital health adoption through regulatory sandboxes for wearable-derived metrics. Tokyo and Osaka metropolitan areas concentrate subscription density among busy professionals seeking time-compressed workout formats.
Australia
Geographic dispersion and rural bandwidth constraints favor on-demand libraries over live-streamed classes. The Therapeutic Goods Administration scrutinizes health claims tied to wearable recovery analytics. Sydney and Melbourne anchor urban subscription growth, while regional markets lag in fiber and 5G penetration for real-time interactivity.
Online Fitness Market Vendor Landscape
Concentration sits with hardware-software ecosystem players that lock in subscription stickiness through proprietary data formats. The market structure spans three tiers: integrated equipment-platform bundlers, pure-play software platforms, and wearable-native analytics specialists. Dominant competitive moves include hardware-software bundling to raise switching costs and recovery analytics integration to differentiate beyond commoditized on-demand libraries.
Within the hardware-software ecosystem tier, Peloton and Zwift exemplify captive equipment strategies that resist platform switching through proprietary course rendering and performance data formats. WHOOP occupies a position among wearable-native specialists, anchoring recovery analytics differentiation through sleep and strain scoring that extends beyond basic activity tracking. These three companies represent the archetype spectrum from equipment-captive bundling to sensor-native physiological monitoring.
| Leading Market Players |
|---|
| WHOOP |
| Future |
| Peloton |
| MyFitnessPal |
| Strava |
| Nike |
| Noom |
| Zwift |
| Under Armour |
| Others |
Supply Flow & Price Mechanics
Forty-five-day content production cycles for live-class studio infrastructure compress margin recovery windows and tether pricing power to instructor talent scarcity across United States metropolitan corridors. This lead-time band concentrates cost inflation in premium synchronous formats while commoditized on-demand libraries collapse differentiation thresholds.
Pricing Analysis
FTC subscription cancellation transparency mandates dictate the pricing tier structure across monthly, annual, and enterprise procurement bands. Three-tier pricing structure across premium live-class, standard on-demand, and economy freemium levels separates corporate wellness administrators from individual subscribers. Price differentiation rests on biometric integration depth and hardware-software bundling intensity. Cost compression in the on-demand tier intensifies because adaptive bitrate encoding standardization erodes proprietary content moats. Beginner fitness enthusiasts exhibit highest price sensitivity; advanced athletes seeking WHOOP-style recovery analytics demonstrate lowest.
Supply Chain Analysis
The United States and Germany anchor live-class studio infrastructure and wearable API development respectively. Taiwan feeds semiconductor components for heart-rate sensors; South Korea supplies OLED display panels for connected equipment screens. Raw material dependencies draw from rare earth elements for sensor magnetometers, lithium-ion cells for device power management, and optical-grade glass for camera-based form tracking. Single-source vulnerability concentrates in proprietary course rendering engines for cycling simulation platforms. Distribution runs through direct-to-consumer subscription portals and employer benefits administrators as aggregated procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection hinges on Apple Watch and Garmin API standardization collapsing hardware switching costs while deepening biometric data liquidity across competing ecosystems.
For Market Incumbents: Fortify subscription stickiness through captive equipment ecosystems that encode performance data in proprietary formats resisting platform migration. Invest in FDA-compliant wearable health claims certification to create regulatory moats against unverified competitors. Defensive moves must counter pure-play software platforms eroding premium live-class differentiation through AI-generated coaching cues. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for recovery analytics algorithms offer entry into advanced athlete segments underserved by basic activity tracking. White-space targets concentrate in senior-focused low-impact programming with fall-risk modifications and employer wellness benefits procurement through benefits platform aggregators. Go-to-market execution should prioritize annual membership commitments from United States metropolitan HR administrators seeking single-dashboard reporting consolidation. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy fitness equipment manufacturers with dormant subscriber bases and undermonetized content libraries. Long-term viability over the coming decade frames hardware-software bundling as the dominant value-capture mechanism. Acquisition archetypes include wearable-native analytics specialists with sleep and strain scoring IP. Signal to monitor: EU AI Act conformity assessment completion rates as European market access discriminator.| Strategic Initiative | Industry Significance |
|---|---|
| Hardware-Software Bundling | Peloton-style captive equipment ecosystems lock in subscription revenue through proprietary data formats. |
| Biometric AI Compliance Investment | FDA validation of wearable-derived health claims creates certification moats against unverified platform competitors. |
| Enterprise Procurement Consolidation | Benefits platform aggregation displaces direct-to-employer sales in United States metropolitan corridors. |
| Recovery Analytics Integration | WHOOP-style sleep and strain scoring commands premium attachment rates among advanced athlete cohorts. |
| EU Regulatory Segregation | Parallel codebases for biometric inference tools manage EU AI Act high-risk system classification costs. |
Methodological Framework
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings. Primary fieldwork incorporated platform engineering leads, corporate wellness benefits administrators, wearable device product managers, and fitness content production directors. Secondary sources encompassed FDA enforcement action databases, EU AI Act implementation guidance, SEC subscription revenue disclosures, and employer benefits procurement records. Bottom-up subscriber segmentation triangulated against top-down market sizing from hardware shipment data and API call volume metrics.
Sensitivity analysis tested forecast robustness across bandwidth infrastructure penetration scenarios and regulatory compliance cost assumptions. The analytical framework modeled service type, subscription model, target audience sophistication, and platform type dimensions across the projection horizon. CAGRs derived from cohort retention curve analysis and enterprise procurement cycle timing. Industry-specific inputs included heart-rate variability algorithm adoption rates and live-class studio capacity utilization thresholds.
The analysis sits within stated boundaries; outcomes outside FDA regulatory clarity maintenance or EU AI Act enforcement intensity would require recalibration. Forecasts reflect documented assumptions regarding wearable API standardization velocity and employer wellness benefit tax treatment continuity. Recalibration cycles align with material shifts in FTC billing transparency enforcement and biometric data engineering talent availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO