
 Digital Fitness Market | 2026-2036
Digital Fitness Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Fitness Market Intelligence
Subscription unbundling is rebalancing buyer choice in digital fitness, as platforms separate live coaching, nutrition guidance, and community support into standalone purchases rather than forcing bundled annual commitments. Peloton leverages its hardware-software ecosystem to anchor premium subscriber retention. WHOOP specializes in recovery analytics to differentiate within the wearable devices segment. Apple Fitness extends its service reach through tight iOS integration, controlling distribution against standalone app competitors.
Digital fitness encompasses connected hardware, software applications, and streaming platforms that capture biometric data, deliver programmed workouts, and enable remote coaching through cloud-based infrastructure with real-time synchronization protocols. The primary commercial purpose is to replace or augment physical gym attendance with measurable, personalized training outcomes delivered through internet-connected devices. Wearable devices and fitness apps represent the most mature revenue pools, while live coaching services command premium pricing due to human capital intensity. Smart equipment manufacturers face margin pressure from commoditized sensor hardware, though streaming services benefit from low marginal distribution costs.
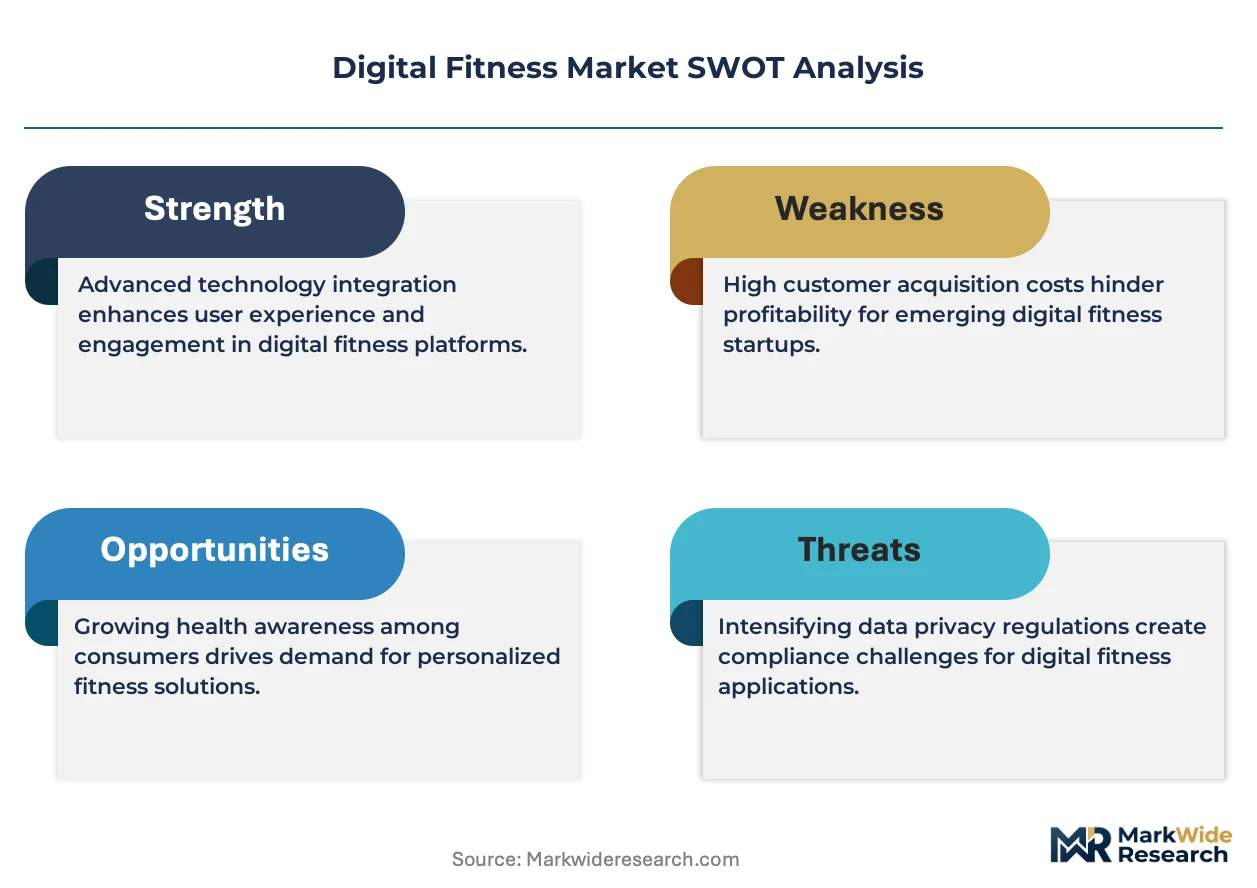
FDA scrutiny of health-related wearable claims and the EU AI Act's risk classification system for algorithmic coaching recommendations are elevating compliance costs for cross-platform operators. GDPR data portability rules and HIPAA-aligned employer wellness data handling in the United States further constrain how vendors collect, share, and monetize user biometric information. Stakeholders must weigh regulatory fragmentation against the scalability of unified platform architectures when prioritizing geographic expansion and partnership strategies.
Market Dynamics
Subscription unbundling is fragmenting the Digital Fitness Market's revenue architecture, forcing platforms to dismantle bundled annual commitments into modular live coaching, nutrition guidance, and community support purchases that shift pricing power toward selective consumers.
Growth Catalysts
- Employer wellness procurement:Corporate wellness programs in the United States are expanding digital fitness budgets as HIPAA-aligned data handling frameworks enable biometric tracking within occupational health initiatives.
- EU AI Act compliance:Algorithmic transparency mandates for health coaching recommendations are accelerating platform investment in explainable AI, creating competitive differentiation for compliant operators.
- Sensor miniaturization:Advances in photoplethysmography and accelerometer integration are reducing wearable production costs while expanding real-time recovery analytics capabilities.
Market Restraints
- FDA health claim scrutiny:Wearable manufacturers face elevated compliance costs as the FDA tightens oversight of diagnostic-adjacent marketing for heart rate variability and sleep disorder detection.
- Cloud infrastructure concentration:Real-time biometric synchronization depends on hyperscaler concentration in United States and European data centers, creating geopolitical exposure for cross-border operators.
- Human capital intensity:Live coaching services face margin compression from certified trainer scarcity and asynchronous content commoditization.
Strategic Opportunities
- Medicare Advantage integration:United States payers are piloting digital fitness benefits as supplemental coverage, opening B2B2C channels previously locked behind traditional gym reimbursement models.
- GDPR data portability:European users exercising biometric data export rights are creating interoperability demand that rewards open API architectures over walled garden ecosystems.
- Recovery analytics specialization:Convergence of strain-recovery balance algorithms with continuous glucose monitoring is absorbing adjacent health optimization spend from biohacking consumers.
Industry Challenges
- Algorithmic bias certification:Platforms deploying AI coaching must validate demographic equity across age, gender, and fitness baseline distributions before European market entry.
- Legacy gym network retaliation:Established fitness chains are lobbying for tax treatment parity and municipal zoning preferences that disadvantage virtual-only competitors.
- Biometric data breach exposure:HIPAA-aligned employer wellness programs create concentrated liability pools where single incidents trigger class-action exposure across covered employee populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Fitness Market |
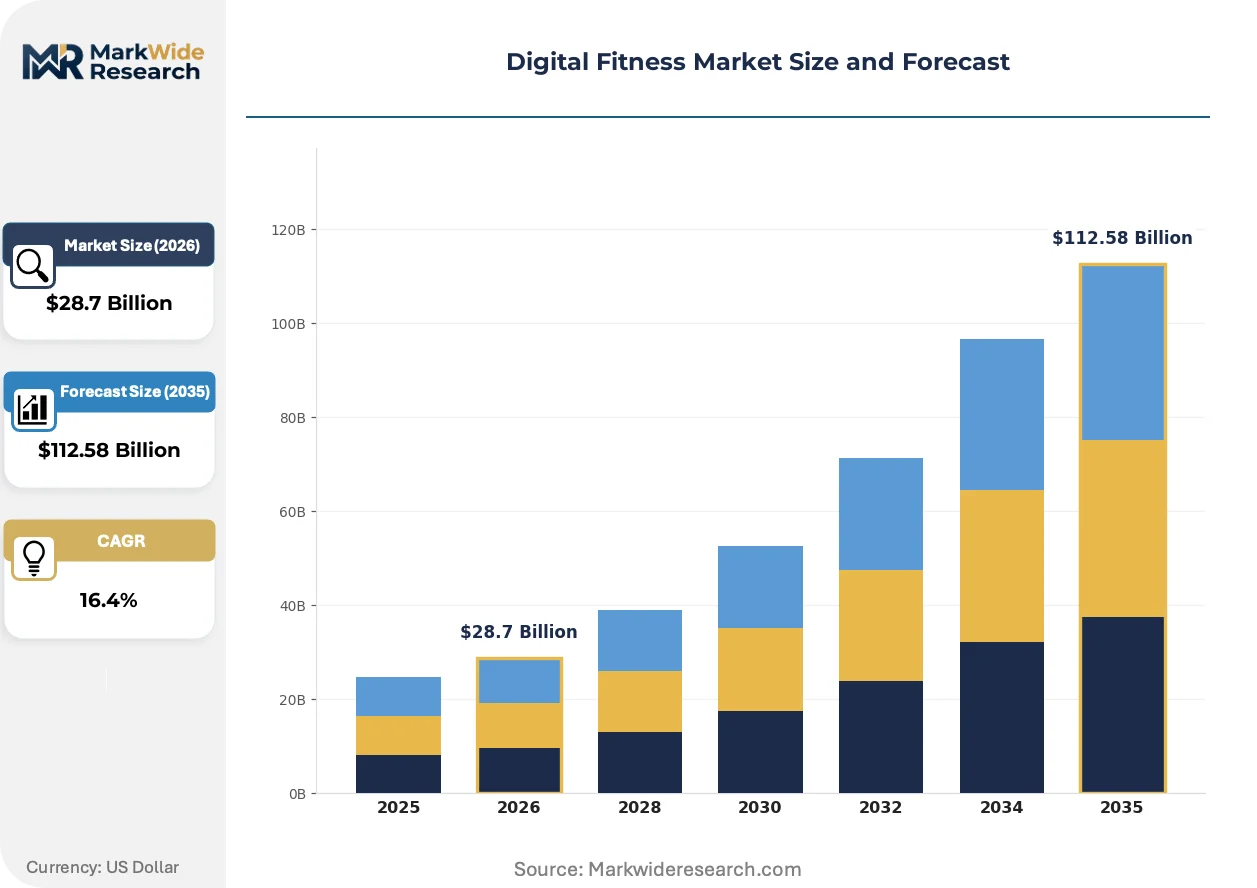
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $112.58 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Fitness Apps, Streaming Services, Smart Equipment End User: Individual Users, Gyms, Corporate Wellness Programs, Health Clubs Subscription Model: Free, Monthly, Annual, Pay-Per-Use Service Type: Live Coaching, On-Demand Workouts, Nutrition Guidance, Community Support |
| Companies Covered | Apple Fitness, Wildnet Edge, Peloton, Dogtown Media, MindSea, WHOOP, Fitbit, TechAhead, MyFitnessPal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Fitness Market Strategic Shifts & Innovations
Generative AI is compressing content production timelines for personalized workout programming while regulatory fragmentation forces architectural decisions that prioritize geographic compliance over platform uniformity.
Multimodal sensor fusion is absorbing standalone device categories into consolidated wearable form factors. Advanced signal processing now combines photoplethysmography, skin temperature, and accelerometer streams for recovery scoring that previously required multiple dedicated devices. Athlete and military end-users are adopting these consolidated platforms fastest, compressing addressable market space for single-function wearables.
The EU AI Act's risk classification system for algorithmic health recommendations is elevating documentation burdens for coaching platforms operating across European markets. High-risk system designations trigger conformity assessments and post-market monitoring obligations that favor larger operators with dedicated regulatory affairs functions. Wearable-software integrated ecosystems face particular exposure where biometric inputs feed directly into automated training prescriptions.
Employer-sponsored wellness budgets are rotating procurement authority from HR administrators to benefits consultants who demand outcome verification. United States corporations now require utilization metrics and engagement benchmarks that replace flat subscription fees with performance-contingent pricing. This shift concentrates vendor selection among platforms with established actuarial partnerships and validated health outcome datasets.
Digital Fitness Market Segmentation
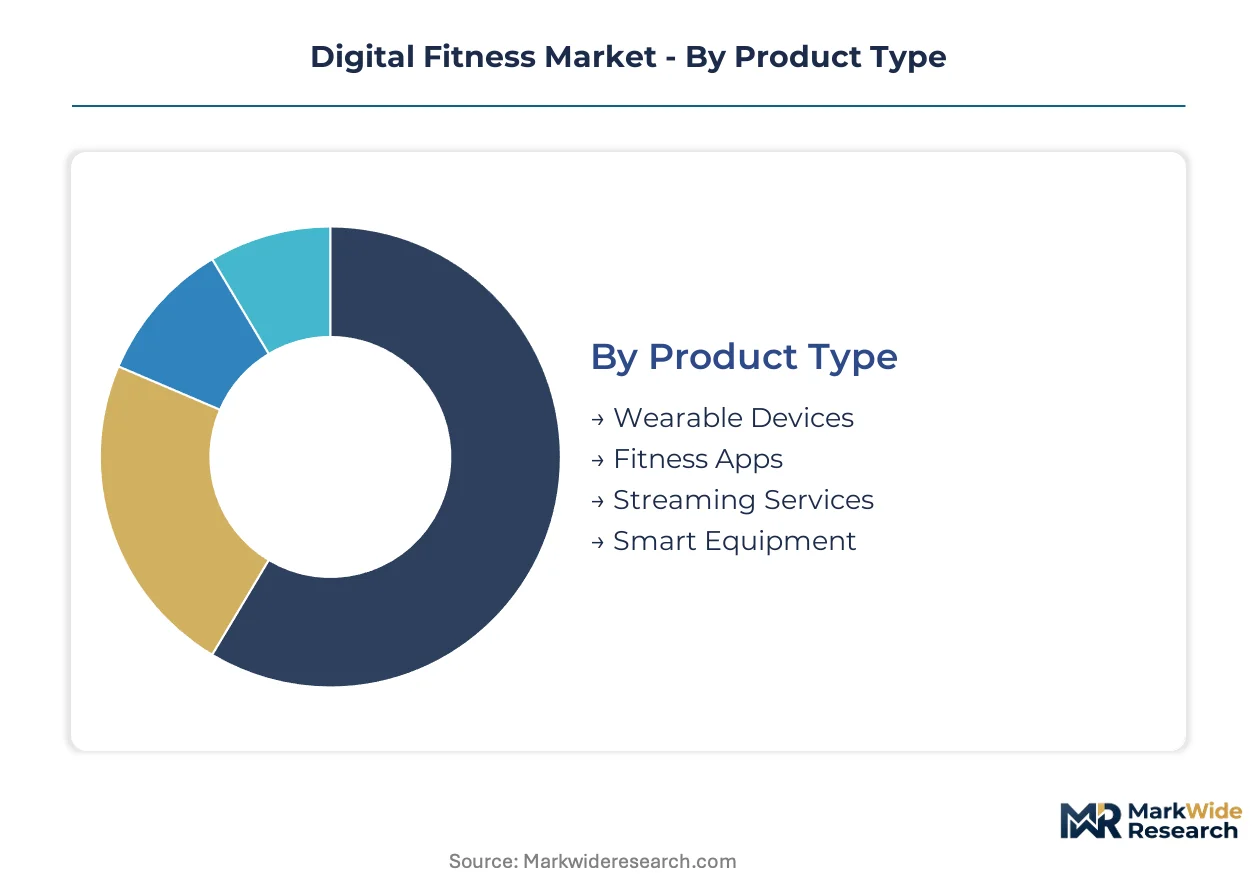
Segmentation in digital fitness reveals how capital deployment, user commitment patterns, and service delivery economics diverge across hardware, software, and human-capital-intensive offerings. Each dimension exposes distinct margin structures and regulatory exposure that shape vendor prioritization.
Product Type:
Capital intensity peaks in segments requiring manufacturing footprints and sensor R&D, while software-only offerings scale with minimal incremental infrastructure.
- Wearable Devices:Photoplethysmography and accelerometer integration demands semiconductor procurement and FDA-aligned validation for heart rate variability claims. Demand concentrates among United States employers seeking HIPAA-compliant biometric tracking for occupational wellness initiatives, though FDA diagnostic-adjacent scrutiny elevates compliance spend.
- Smart Equipment:Connected hardware with embedded touchscreens and real-time resistance calibration requires assembly facilities and logistics networks that rival traditional fitness OEMs. United States direct-to-consumer penetration remains deepest where premium subscription bundles justify upfront hardware subsidies.
- Fitness Apps:Low marginal distribution costs enable rapid geographic expansion, though iOS gatekeeping constrains standalone monetization against platform-integrated competitors.
- Streaming Services:Cloud infrastructure concentration in United States and European data centers creates geopolitical exposure for cross-border content synchronization.
Most installed capacity flows through Wearable Devices. Expansion is steepest in Smart Equipment as manufacturers absorb adjacent hardware categories into consolidated form factors.
End User:
Procurement authority varies sharply across direct consumers, institutional buyers, and intermediated corporate channels with diverging outcome verification demands.
- Corporate Wellness Programs:United States employers now rotate vendor selection to benefits consultants requiring utilization metrics and actuarially validated health outcomes, replacing flat subscription fees with performance-contingent pricing.
- Individual Users:Direct-to-consumer subscription penetration concentrates in the United States, where unbundling trends shift pricing power toward selective purchasers of modular live coaching and nutrition guidance.
- Health Clubs:Legacy gym networks lobby for tax treatment parity and municipal zoning preferences that disadvantage virtual-only competitors.
- Gyms:Hybrid operators deploy digital fitness as retention tools against pure-play streaming substitutes, though margin compression limits proprietary platform investment.
Revenue concentration tilts toward Corporate Wellness Programs where procurement scale justifies dedicated account management. Individual Users represent the most fragmented acquisition channel.
Subscription Model:
Pricing architecture shapes customer lifetime value and churn exposure, with commitment length directly correlating to retention economics and working capital requirements.
- Annual:Bundled commitments historically anchored platform revenue predictability, though unbundling trends now dismantle forced annual packages into modular component purchases.
- Monthly:Flexible terms attract price-sensitive users and reduce upfront friction, though higher churn demands continuous re-engagement marketing spend.
- Pay-Per-Use:Transactional access suits intermittent users and seasonal demand patterns, complicating capacity planning for live coaching services with human capital intensity.
- Free:Freemium tiers drive acquisition funnel volume but require conversion optimization or advertising monetization to sustain infrastructure costs.
Annual subscriptions retain the largest share of committed revenue. Monthly plans are gaining share fastest as unbundling empowers selective purchasing.
Service Type:
Human capital intensity and content production economics separate automated programming from live service delivery with diverging margin profiles.
- Live Coaching:Certified trainer scarcity and asynchronous content commoditization compress margins, though premium pricing persists for personalized programming and real-time form correction.
- On-Demand Workouts:Generative AI compresses content production timelines for personalized programming, enabling rapid library expansion with reduced production crew dependency.
- Nutrition Guidance:Registered dietitian oversight requirements vary by jurisdiction, with FDA and EFSA claim restrictions limiting automated meal planning recommendations in regulated markets.
- Community Support:Network effects drive retention but require moderation infrastructure and GDPR-aligned data handling for user-generated content and biometric sharing features.
On-Demand Workouts carry the largest content library investment. Live Coaching commands the highest per-session pricing despite scaling constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The digital fitness industry traces its commercial origins to Silicon Valley's hardware-software convergence in the early 2010s, where venture capital first scaled connected workout equipment and biometric tracking platforms into mass-market categories.
United States
Employer-sponsored wellness budgets and Medicare Advantage pilot programs drive procurement concentration. HIPAA-aligned data handling frameworks enable biometric tracking within occupational health initiatives, though FDA diagnostic-adjacent scrutiny elevates compliance costs for heart rate variability claims. San Francisco Bay Area and Austin clusters host platform engineering headquarters.
Germany
Corporate wellness adoption accelerates through worksite health promotion tax incentives. EU AI Act algorithmic transparency mandates trigger conformity assessments for coaching platforms using biometric inputs. Berlin and Munich host regulatory affairs functions serving cross-border European operations.
United Kingdom
Private health insurance integration creates B2B2C distribution channels for recovery analytics services. GDPR biometric data portability rules reward open API architectures over walled garden ecosystems. London's fintech infrastructure enables performance-contingent pricing models for employer contracts.
China
Domestic smartphone manufacturer ecosystem integration drives fitness app distribution against standalone competitors. NMPA medical device classification for diagnostic-adjacent wearables tightens marketing claims. Shenzhen hardware manufacturing clusters supply sensor components for global equipment brands.
Japan
Aging population wellness budgets expand through METI-subsidized workplace health programs. JIS standards for wearable device interoperability create certification barriers for imported platforms. Tokyo and Osaka metropolitan areas concentrate corporate procurement decision-making authority.
Digital Fitness Market Key Industry Players
The competitive structure tilts toward integrated hardware-software ecosystems over standalone application vendors. Platform operators fragment across three tiers: premium equipment-subscription bundles, specialized wearable analytics, and mass-market freemium applications. Strategic differentiation concentrates on sensor fusion capabilities, algorithmic coaching validation, and employer channel penetration. Consolidation pressure favors operators with dedicated regulatory affairs functions and actuarial outcome datasets.
Among integrated equipment-platform operators, Peloton and Apple Fitness exemplify the hardware-anchored subscription model. WHOOP occupies a specialist position within recovery analytics, differentiating through strain-recovery balance algorithms. These three companies represent divergent strategic archetypes: premium content bundling, ecosystem lock-in, and biometric specialization respectively.
| Leading Market Players |
|---|
| Apple Fitness |
| Wildnet Edge |
| Peloton |
| Dogtown Media |
| MindSea |
| WHOOP |
| Fitbit |
| TechAhead |
| MyFitnessPal |
| Others |
Cost & Logistics Intelligence
Sensor miniaturization and photoplethysmography integration are compressing wearable production costs while simultaneously concentrating semiconductor procurement leverage among United States and East Asian foundries, reshaping how hardware-software bundles capture margin across premium and mass-market tiers.
Pricing Analysis
Subscription unbundling into modular live coaching, nutrition guidance, and community support purchases is fragmenting historical annual-commitment pricing power. Price differentiation rests on FDA-aligned validation tiers for biometric claims and employer-sponsored wellness procurement scale. Cost compression in smart equipment manufacturing is intensifying because commoditized sensor hardware erodes hardware margins. Individual direct-to-consumer users exhibit highest price sensitivity, while corporate wellness programs with actuarial outcome requirements show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced semiconductor fabrication serving photoplethysmography chipsets. Raw material dependencies center on rare earth elements for sensor magnets, lithium-ion cells for wearable power, and optical-grade polymers for biosensing windows. Tariff exposure on cross-border cloud infrastructure concentration creates geopolitical risk for real-time biometric synchronization. Distribution runs through direct-to-consumer e-commerce channels and employer benefits consultant intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic transparency mandates and FDA diagnostic-adjacent scrutiny are compounding compliance spend into competitive moats, rewarding operators with dedicated regulatory affairs functions and validated health outcome datasets.
For Market Incumbents: To counter subscription unbundling and live coaching margin compression, anchor retention through hardware-software ecosystem lock-in and deepen backward integration into sensor semiconductor procurement. Prioritize actuarial partnerships that enable performance-contingent employer pricing. For New Entrants and Emerging Players: Capture white-space in recovery analytics specialization and Medicare Advantage B2B2C pilot programs where incumbent presence remains thin. Penetrate through open API architectures that satisfy GDPR biometric data portability demand in European markets. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone fitness app developers lacking hardware anchoring or employer channel penetration. Long-term viability favors integrated wearable-software ecosystems with FDA-aligned validation and cross-border regulatory affairs capacity. Watch for EU AI Act conformity assessment completion as inflection signal for European market entry readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Function Buildout | Dedicated EU AI Act and FDA compliance teams accelerate cross-border market access against resource-constrained competitors. |
| Actuarial Outcome Partnership | Performance-contingent employer pricing models replace flat subscriptions with validated health outcome datasets. |
| Sensor Fusion R&D Investment | Multimodal photoplethysmography and accelerometer integration compresses standalone device categories into consolidated wearables. |
| Open API Architecture Deployment | GDPR biometric data portability compliance rewards interoperability over walled garden ecosystem strategies. |
| Medicare Advantage Channel Pilot | B2B2C distribution through United States payer supplemental coverage opens previously locked gym reimbursement channels. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with platform engineering heads, benefits consultants, regulatory affairs leads, and wearable hardware procurement officers with secondary validation against FDA 510(k) filings, EU AI Act implementation guidance, HIPAA compliance documentation, and employer wellness program RFP databases. Bottom-up subscription revenue modeling and top-down employer procurement spend estimates were triangulated.
Historical reference periods anchored growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled included product type, end user procurement authority, subscription commitment length, and service delivery human capital intensity. CAGRs were derived from fitted trend extrapolation with adjustment for regulatory milestone impacts and sensor cost curve assumptions.
EU AI Act enforcement delays, FDA diagnostic claim reclassification actions, and employer wellness budget cyclicality are the dominant revision risks to forecast assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO