
 Global Interactive Fitness Market | 2026-2036
Global Interactive Fitness Market Size, Share, and Industry Trends Forecast 2026-2036
Global Interactive Fitness Market Outlook
The gap between hardware engineering and software delivery is narrowing as interactive fitness platforms merge embedded sensors with real-time cloud analytics. Peloton Interactive Inc. leverages its captive manufacturing network to control quality across bike and treadmill lines. TECHNOGYM Spa anchors its position through institutional contracts with hotel chains and corporate campuses. EGYM Inc. specializes in AI-powered strength equipment that automates load progression for gym operators.
Interactive fitness encompasses digitally connected exercise systems that integrate biometric sensors, touchscreen interfaces, and streaming content delivery to create adaptive workout experiences. These platforms typically process heart rate variability, motion capture data, and user performance metrics through edge computing architectures to enable real-time coaching feedback. Smart Equipment and Wearable Devices represent the dominant revenue pools, with the former capturing premium pricing through subscription bundling and the latter expanding through employer wellness subsidies. Virtual Reality and Augmented Reality segments are attracting R&D capital as hardware costs decline and latency thresholds improve for immersive training simulations.
FDA oversight applies to wearable devices making medical-adjacent claims, while FCC regulations govern wireless transmission standards for connected equipment in the United States. The EU AI Act and GDPR create compliance burdens for vendors processing biometric data across European member states, effectively raising barriers for smaller entrants lacking dedicated privacy engineering teams. Stakeholders must weigh the capital requirements of multi-jurisdiction certification against the revenue premium commanded by health-integrated product positioning.
Market Dynamics
The convergence of on-device AI inference with biometric sensor networks is compressing latency windows for real-time coaching feedback, forcing vendors to rearchitect data pipelines around edge-first processing to satisfy GDPR and EU AI Act mandates.
Growth Catalysts
- Corporate wellness subsidies:Large employers in the United States are expanding procurement of connected workout systems as tax-advantaged benefits under IRS Section 125 cafeteria plans.
- EU AI Act compliance:Biometric data processing restrictions are accelerating vendor investment in federated learning architectures that keep health metrics on local hardware.
- Micro-LED display maturation:Falling panel costs for immersive fitness hardware are enabling wider deployment of augmented reality training overlays in metropolitan fitness corridors.
Market Restraints
- Semiconductor supply concentration:Specialized motion processing chips rely on TSMC's advanced node capacity in Taiwan, creating geographic vulnerability for sensor-laden equipment.
- FCC certification timelines:Wireless transmission approvals for connected treadmills and bikes impose 6-12 month delays on product launches in the United States.
- Static gym equipment substitution:Low-cost traditional strength equipment retains share among price-sensitive municipal recreation facilities.
Strategic Opportunities
- Germany's DKV prevention mandate:Statutory health insurer reimbursement pathways for digital therapeutics create a regulatory tailwind for medically-integrated fitness platforms.
- India's PLI scheme for wearables:Production-linked incentives for electronics manufacturing are attracting contract assembly investment for biometric device categories.
- Convergence of haptics with spatial audio:Tactile feedback vests paired with 3D soundscapes are opening immersive training applications for rehabilitation clinics.
Industry Challenges
- Firmware-over-the-air complexity:Continuous software delivery for safety-critical hardware requires dedicated DevOps teams that smaller vendors struggle to staff.
- ISO 13482 compliance burden:Personal care robot safety standards for automated strength equipment demand extended validation cycles that compress launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Interactive Fitness Market |
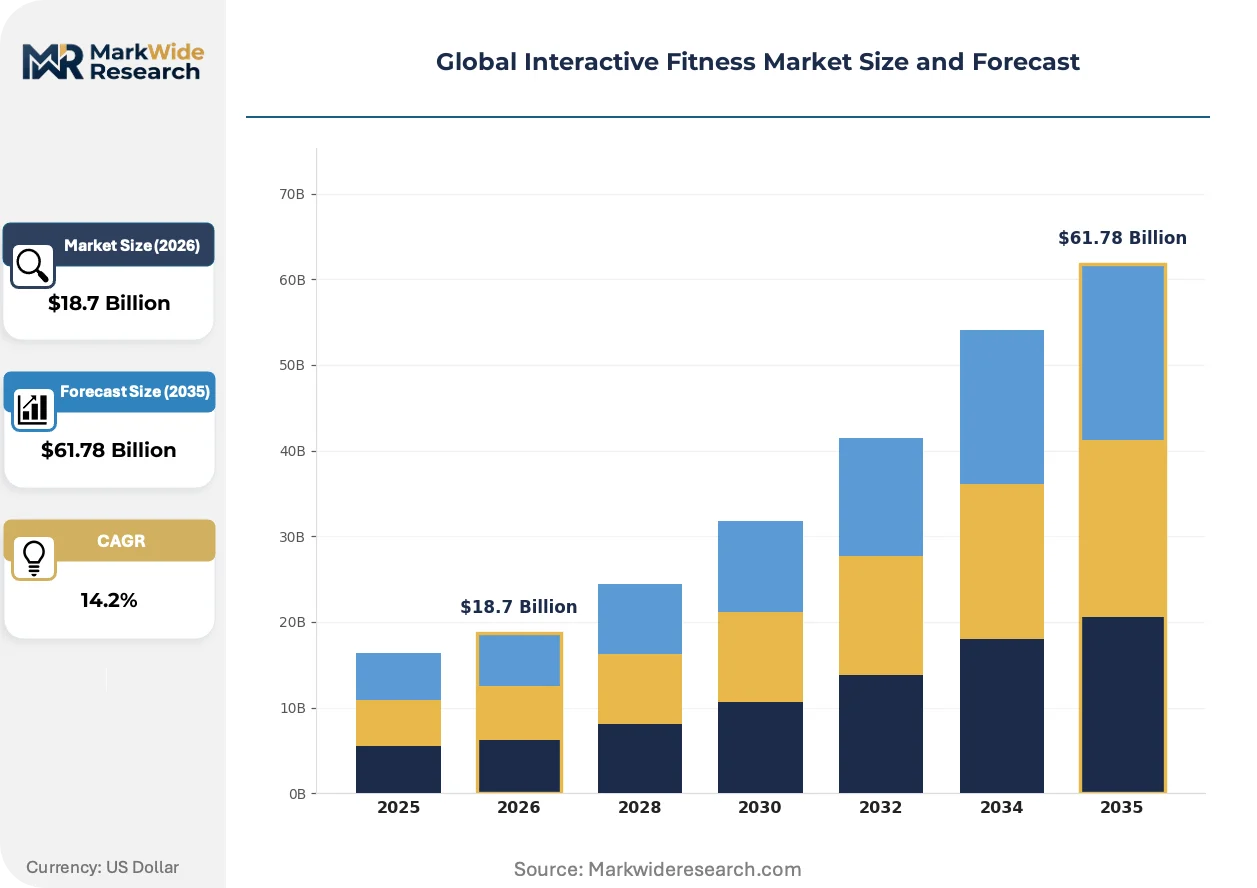
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smart Equipment, Apps, Online Subscriptions End User: Fitness Enthusiasts, Casual Users, Athletes, Corporates Technology: Virtual Reality, Augmented Reality, Mobile Apps, Cloud Computing Distribution Channel: Online Retailers, Fitness Centers, Direct Sales, Partnerships |
| Companies Covered | Peloton Interactive Inc., Nexersys Corp., Axtion Technology LLC, Nautilus Inc., Echelon Fitness LLC, EGYM Inc., TECHNOGYM Spa, Motion Fitness LLC, SMARTfit Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Interactive Fitness Market Strategic Shifts
Real-time physiological adaptation is replacing scripted workout content as the primary value driver, with platforms competing on inference speed rather than celebrity instructor libraries.
Photoplethysmography arrays embedded in handlebar grips are rendering obsolete chest-strap heart rate monitors for studio cycling applications. Boutique fitness chains in New York and London are deploying these contactless sensors across entire fleet inventories within 18-month refresh cycles. The shift is compressing attach rates for third-party wearable accessories and capturing biometric data within vendor-controlled software stacks.
The EU AI Act's risk classification framework for biometric inference systems is forcing vendors to maintain technical documentation dossiers for each algorithmic update. Equipment manufacturers serving European corporate campuses are segregating training data by member state to limit cross-border transfer exposure. This fragmentation is raising compliance engineering headcount by 40% for mid-tier suppliers relative to pre-2024 baselines.
Subscription unbundling is accelerating as enterprise buyers negotiate hardware-only procurement with separate content licensing. Fortune 500 wellness administrators in Chicago and San Francisco are disaggregating equipment capex from SaaS fees to improve balance sheet treatment. The model is displacing Peloton-style bundled pricing in accounts above 5,000 covered lives.
Global Interactive Fitness Market Segmentation
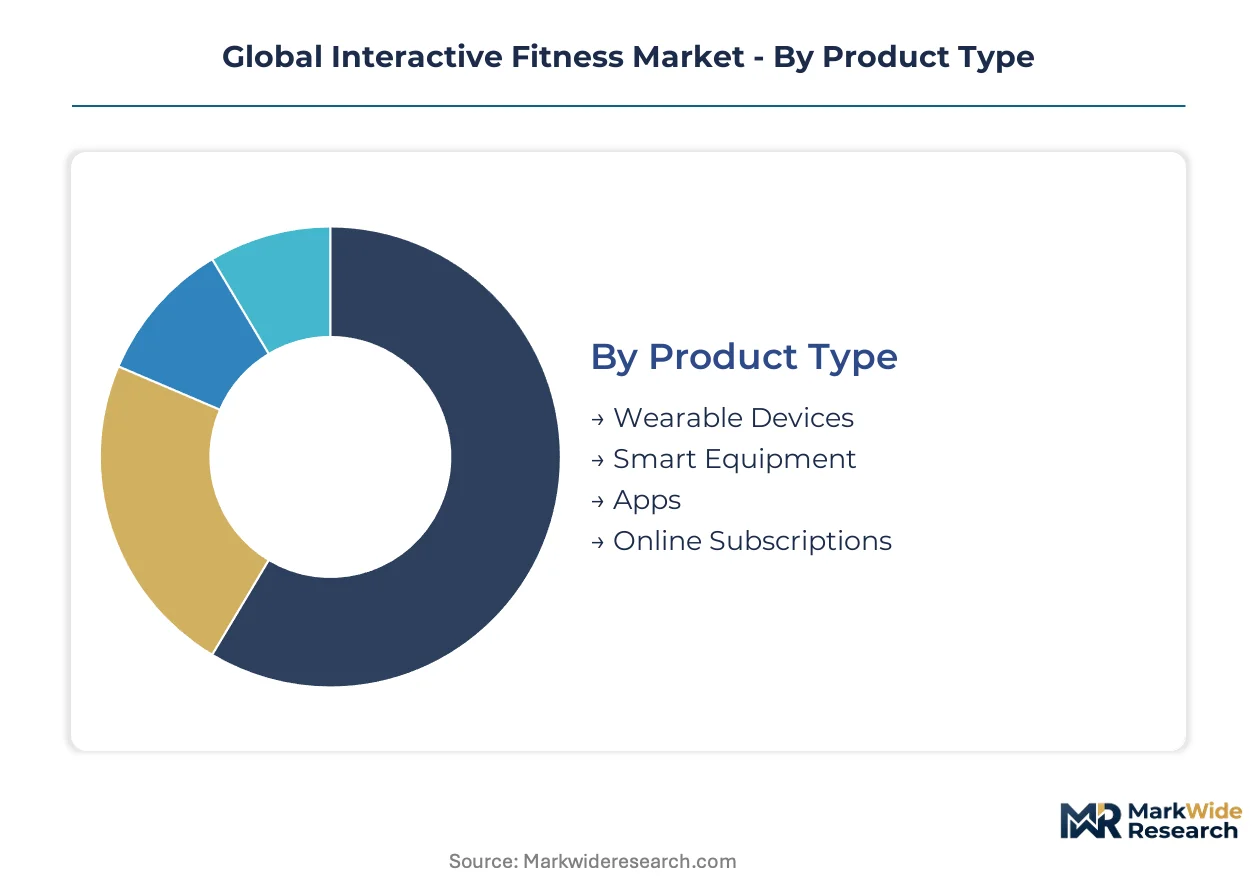
Segmentation in interactive fitness reveals divergent technology readiness and procurement authority across buyer categories. Equipment vendors must architect separate go-to-market motions for institutional contracts versus direct-to-consumer channels.
Product Type:
The use-case spectrum spans biometric monitoring at the wrist to fully instrumented strength stations with automated load modulation.
- Smart Equipment:Embedded sensor arrays in connected bikes, treadmills, and strength machines stream telemetry to cloud analytics platforms. Corporate campuses in the United States and hotel chains in Germany anchor procurement volumes through multi-year service contracts.
- Wearable Devices:Photoplethysmography-enabled wristbands and smartwatches capture heart rate variability and motion metrics. Employer wellness subsidies in Chicago and San Francisco metropolitan corridors are expanding attach rates through Section 125 cafeteria plan structures.
- Apps:Software platforms delivering adaptive workout programming and biometric feedback loops without dedicated hardware dependencies.
- Online Subscriptions:Content licensing models for live and on-demand fitness classes, increasingly unbundled from hardware procurement in enterprise accounts.
Established volume favors Smart Equipment; emerging adoption favors Wearable Devices.
End User:
Cost tier segmentation separates premium institutional budgets from discretionary consumer spending.
- Corporates:Fortune 500 wellness administrators negotiate hardware-only procurement with separate SaaS licensing to optimize balance sheet treatment. Procurement in Chicago and San Francisco corridors exceeds 5,000 covered lives per contract.
- Fitness Enthusiasts:High-engagement consumers purchasing premium bundled hardware-subscription packages through direct-to-consumer channels.
- Athletes:Performance-optimized users demanding medical-grade biometric accuracy and sport-specific training protocols.
- Casual Users:Price-sensitive adopters relying on smartphone-native apps and entry-level wearables without dedicated fitness hardware.
Procurement scale concentrates with Corporates; engagement depth peaks with Fitness Enthusiasts.
Technology:
Application maturity separates proven mobile architectures from immersive hardware still navigating latency thresholds.
- Mobile Apps:Smartphone-native platforms leveraging built-in accelerometers and GPS for outdoor activity tracking. India's PLI scheme for electronics manufacturing is attracting contract assembly investment for biometric device categories serving this stack.
- Cloud Computing:Centralized data processing architectures enabling cross-device synchronization and longitudinal performance analytics.
- Augmented Reality:Micro-LED display overlays projecting form guidance and intensity metrics onto physical training environments.
- Virtual Reality:Fully immersive simulations requiring dedicated headsets and spatial computing hardware, with R&D capital flowing as equipment costs decline.
Deployment velocity favors Mobile Apps; steepest expansion trajectory belongs to Augmented Reality.
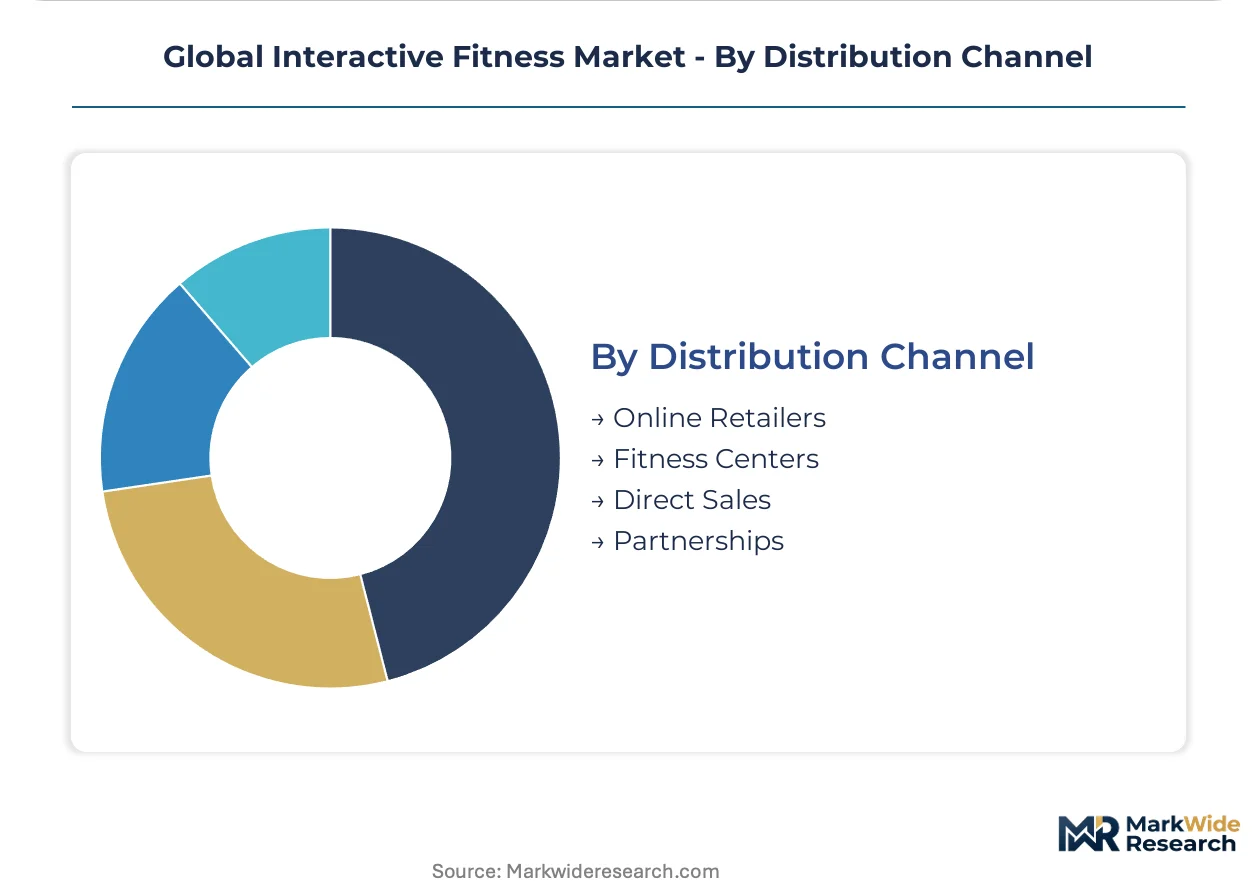
Distribution Channel:
Customer type concentration determines whether volume flows through high-touch direct sales or scaled retail partnerships.
- Direct Sales:Captive e-commerce platforms and showroom networks controlling the full customer relationship and subscription attach. TECHNOGYM Spa anchors institutional positioning through this channel.
- Fitness Centers:Boutique chains and commercial gym operators deploying fleet-scale equipment refreshes with integrated software stacks.
- Online Retailers:Third-party marketplaces expanding reach into price-sensitive segments with reduced margin capture.
- Partnerships:Co-branded distribution through health insurers and employer benefits platforms, particularly Germany's DKV prevention mandate pathways.
Margin retention favors Direct Sales; volume expansion depends on Fitness Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in interactive fitness equipment exports, offsetting import dependence on Taiwanese semiconductor components. European markets exhibit balanced bilateral flows with Germany exporting precision manufacturing equipment while importing cloud software services. Asian supply chains concentrate assembly capacity in China and Vietnam for cost-sensitive wearable categories.
United States
Corporate wellness subsidies under IRS Section 125 cafeteria plans drive procurement across Chicago and San Francisco metropolitan corridors. FCC certification timelines impose 6-12 month delays on wireless-enabled equipment launches. Peloton Interactive Inc. anchors domestic manufacturing through its captive production network controlling bike and treadmill quality.
Germany
DKV prevention mandates create statutory reimbursement pathways for medically-integrated fitness platforms. EU AI Act compliance requirements push vendors toward federated learning architectures keeping biometric data on local hardware. TECHNOGYM Spa dominates institutional contracts with hotel chains and corporate campuses across Bavaria and North Rhine-Westphalia.
China
MIIT standards govern wireless transmission protocols for connected strength equipment entering domestic circulation. Dual carbon goals accelerate energy-efficient manufacturing investments in Guangdong and Jiangsu provinces. Contract assembly for entry-level wearables concentrates in Shenzhen and Dongguan industrial clusters serving export markets.
India
PLI scheme incentives for electronics manufacturing attract biometric device assembly investment from multinational vendors. BIS certification requirements create compliance lead times for imported sensor-laden equipment. Karnataka and Tamil Nadu host expanding contract manufacturing capacity for smartphone-integrated fitness applications.
United Kingdom
GDPR enforcement by the Information Commissioner's Office raises compliance engineering costs for biometric data processing platforms. London boutique fitness chains deploy photoplethysmography-enabled handlebar sensors across studio cycling fleets. NHS digital therapeutics procurement pilots create reimbursement experimentation for medically-adjacent fitness interventions.
Global Interactive Fitness Market Competitive Environment
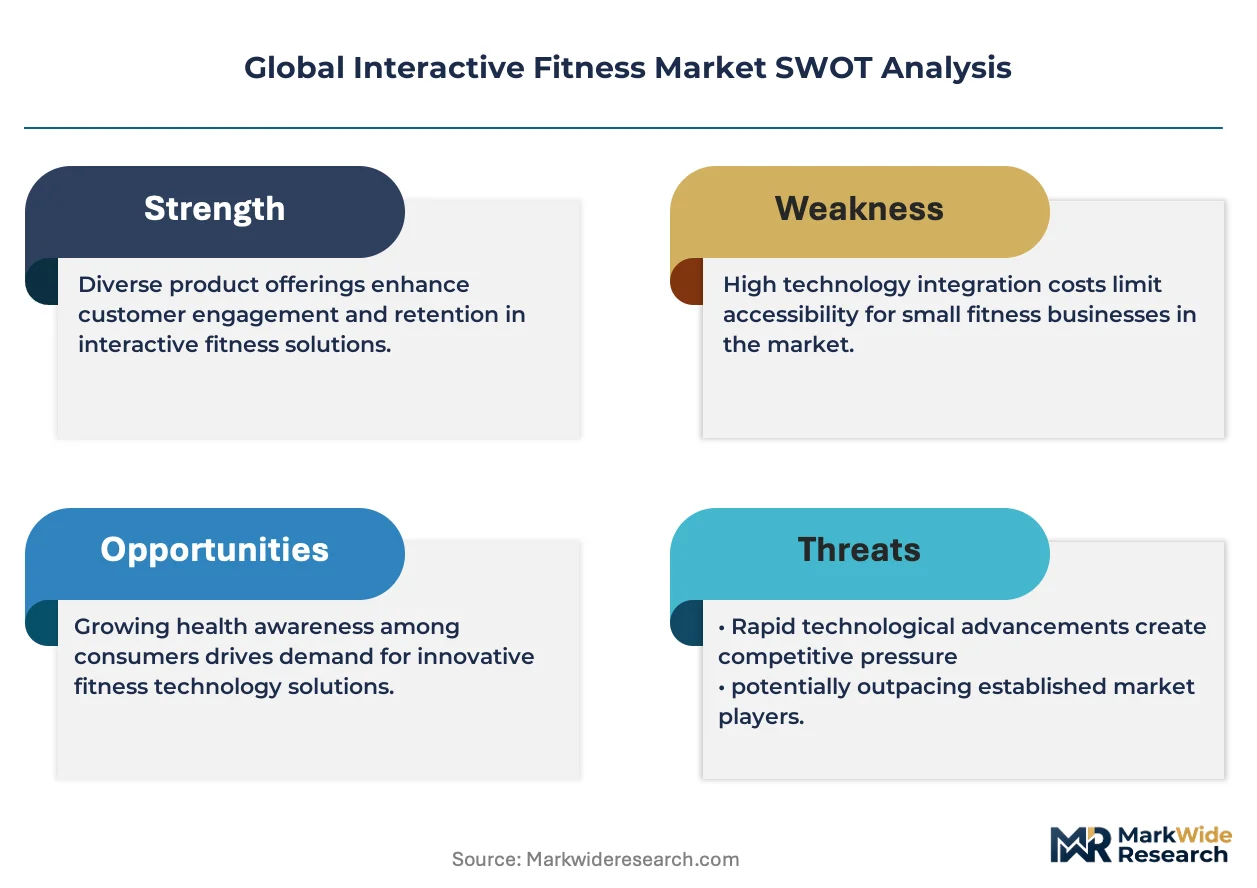
On the supply side, the industry is consolidating around three distinct capability tiers. Hardware-integrated platforms with captive manufacturing networks command premium positioning through subscription bundling. Pure-play software vendors compete on inference speed and adaptive coaching algorithms. Component specialists supply sensor arrays and motion processing chips to multiple downstream equipment brands. Strategic moves center on M&A for biometric IP portfolios and geographic expansion through local assembly partnerships.
Within the integrated hardware tier, Peloton Interactive Inc. and TECHNOGYM Spa exemplify divergent market positioning. Peloton represents the direct-to-consumer bundled model with captive production control. TECHNOGYM anchors institutional channel dominance through multi-year service contracts. EGYM Inc. occupies a specialist position in AI-powered strength equipment automation for commercial gym operators.
| Leading Market Players |
|---|
| Peloton Interactive Inc. |
| Nexersys Corp. |
| Axtion Technology LLC |
| Nautilus Inc. |
| Echelon Fitness LLC |
| EGYM Inc. |
| TECHNOGYM Spa |
| Motion Fitness LLC |
| SMARTfit Inc. |
| Others |
Value Chain & Pricing Dynamics
TSMC's advanced node capacity in Taiwan concentrates supply of specialized motion processing chips, capturing margin pools in premium smart equipment while forcing downstream vendors toward subscription bundling to recover hardware costs. This upstream chokepoint amplifies pricing power for sensor-integrated platforms serving corporate wellness contracts in Chicago and San Francisco.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ISO 13482 certification grade and volume scale in enterprise procurement above 5,000 covered lives. Cost compression in economy-tier municipal recreation equipment is intensifying because static gym alternatives retain share. Casual users exhibit highest price sensitivity; Fortune 500 wellness administrators show lowest sensitivity due to tax-advantaged Section 125 cafeteria plan structures.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for connected fitness hardware. Manufacturing concentrates in China, Vietnam, and Taiwan for cost-sensitive wearable assembly and precision sensor fabrication. Raw material dependencies span lithium-ion cells, micro-LED display substrates, and biometric-grade photoplethysmography arrays. Single-source vulnerability in TSMC's 7nm and 5nm node capacity creates geographic concentration risk. Distribution runs through captive direct sales channels for institutional contracts and third-party online retailers for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among Fortune 500 wellness administrators is shifting buyer power toward hardware-only procurement with unbundled SaaS licensing, fragmenting traditional bundled pricing models.
For Market Incumbents: Pre-empt subscription unbundling by accelerating federated learning architecture deployment to satisfy EU AI Act biometric data restrictions before compliance costs rise further. Deepen backward integration into motion processing chip supply through strategic foundry partnerships in Taiwan, reducing TSMC node allocation vulnerability. Channel control through captive manufacturing networks remains the critical defensive lever against enterprise buyers disaggregating equipment capex from content fees. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme-subsidized wearable assembly corridor, where production-linked incentives are attracting contract manufacturing investment away from established Shenzhen clusters. Target Germany's DKV prevention mandate reimbursement pathways for medically-integrated fitness platforms, the most penetrable regulatory channel for digital therapeutics positioning. A software-first go-to-market angle bypassing FCC certification timelines offers 6-12 month speed-to-market advantage over hardware-integrated competitors. For Investors and Strategic Acquirers: Capital is best deployed toward biometric IP portfolios with EU AI Act technical documentation dossiers already filed, capturing compliance engineering sunk costs that mid-tier suppliers cannot replicate. Long-term viability in this market hinges on edge-first processing architectures that keep health metrics on local hardware. The signal to watch is employer wellness subsidy expansion under IRS Section 125 cafeteria plan structures as an inflection indicator for enterprise segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Architecture Deployment | EU AI Act compliance keeps biometric data on-device, avoiding cross-border GDPR transfer restrictions. |
| Backward Integration into Motion Processing | TSMC node allocation security reduces vulnerability in sensor-laden equipment supply chains. |
| Hardware-Only Procurement Model | Fortune 500 wellness administrators optimize balance sheet treatment by separating equipment capex from SaaS fees. |
| DKV Prevention Mandate Pathway | Germany's statutory health insurer reimbursement creates regulatory tailwind for medically-integrated platforms. |
| Photoplethysmography Handlebar Integration | Boutique fitness chains in New York and London deploy contactless sensors, displacing chest-strap accessories. |
Study Parameters
A spread of perspectives from connected fitness platform CTOs, corporate wellness procurement directors, biomedical sensor engineers, and gym operator fleet managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, FCC equipment authorization databases, EU AI Act technical documentation registries, and SEC 10-K disclosures from publicly traded equipment vendors. Bottom-up triangulation across product-level bill-of-materials analysis and top-down reconciliation against employer wellness subsidy flow data anchored volume estimates.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation modeled by product type, end-user procurement authority, technology maturity tier, and distribution channel concentration. CAGRs were derived from regression analysis of historical corporate wellness procurement cycles and semiconductor capacity expansion timelines. Industry-specific forecast inputs included photoplethysmography sensor cost curves and FCC certification backlog durations.
Stress conditions across TSMC node allocation constraints, EU AI Act enforcement intensity, and IRS Section 125 cafeteria plan participation rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about biometric data processing regulatory trajectories and employer wellness subsidy durability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO