
 Global Snack Food Market | 2026-2036
Global Snack Food Market Size, Share, and Industry Trends Forecast 2026-2036
Global Snack Food Market Outlook
Southeast Asia is narrowing the cost gap with established snack manufacturing bases through automated extrusion lines and regional ingredient sourcing. PepsiCo Inc. leverages its direct-store-delivery network to control shelf placement in emerging markets. Mondelez International Inc. sustains premium positioning through dedicated cocoa sustainability programs. Mars Inc. anchors its snack portfolio with nut-based products that command higher per-unit margins.
Snack food encompasses ready-to-eat items formulated from cereals, pulses, tubers, or oilseeds through processes including extrusion, baking, frying, or air-popping, with moisture content typically below 10% to ensure shelf stability and portability for immediate consumption without preparation. The chips segment dominates value pools due to established brand loyalty and impulse purchase frequency in convenience channels. Granola bars represent the fastest-expanding category as protein fortification and clean-label positioning attract health-oriented consumers. Sweet flavor profiles command premium placement in supermarket end-cap displays, while savory variants maintain volume leadership across vending and foodservice channels.
The FDA governs nutrition labeling and allergen declarations for snack products sold in the United States, while the EU Green Deal and REACH framework restrict certain packaging substrates and chemical additives across European markets. EFSA guidelines on nutrient profiling shape permissible health claims and reformulation targets for sweet and savory categories. India's FSSAI enforces fortification standards and limits trans fat content in packaged snacks distributed through its domestic retail network. Stakeholders must monitor evolving extended producer responsibility mandates and front-of-pack labeling schemes that will determine competitive access and product architecture across priority markets.
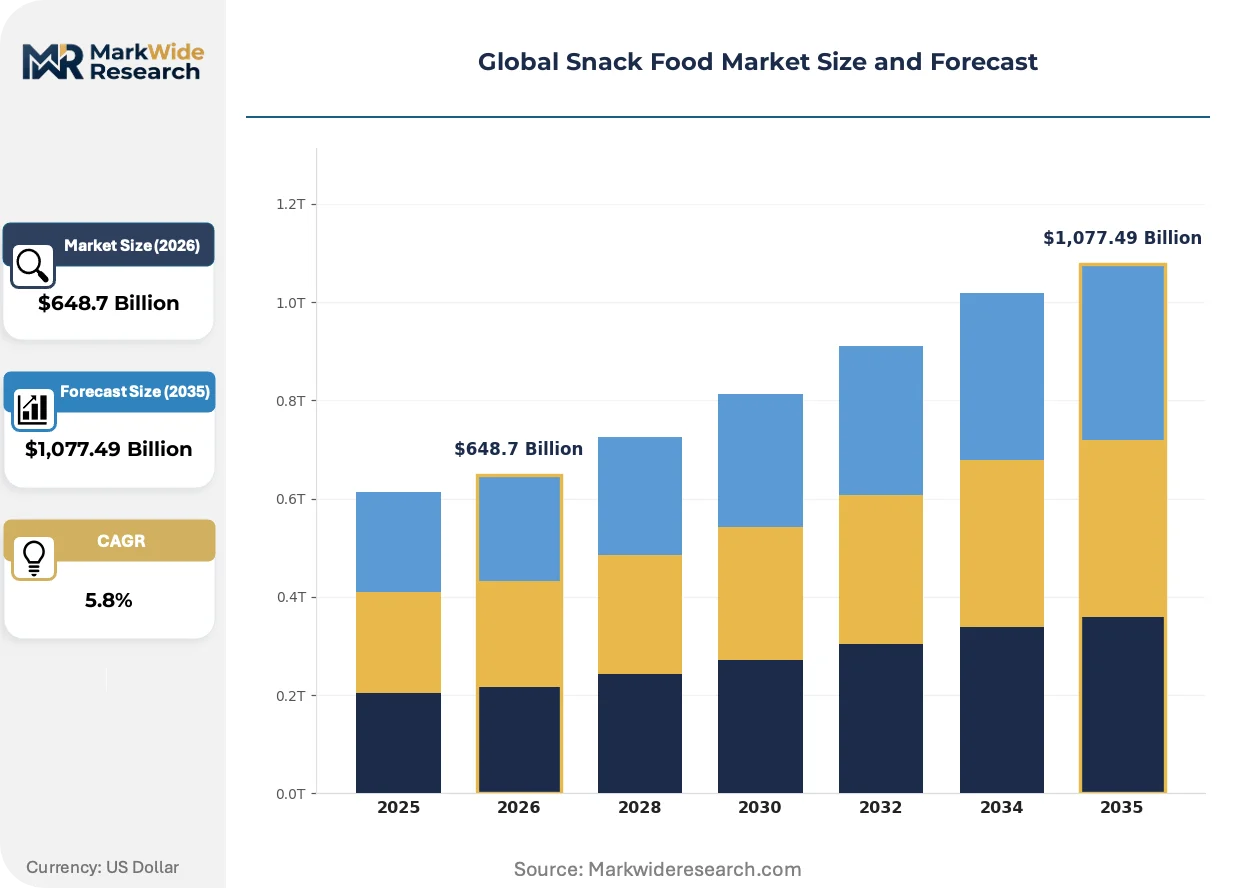
Market Dynamics
Extended producer responsibility mandates under the EU Green Deal are forcing snack manufacturers to redesign packaging architectures, while automated extrusion lines in Southeast Asia compress production economics and reshape competitive positioning.
Growth Catalysts
- Urbanization in India:FSSAI fortification standards and rising disposable incomes accelerate branded snack penetration as consumers shift from unpackaged street foods to packaged alternatives with guaranteed safety credentials.
- REACH framework compliance:European snack producers reformulating packaging substrates to eliminate restricted chemical additives gain preferential shelf access in EU retail channels and preempt regulatory displacement.
- Protein fortification technology:Enzymatic hydrolysis and plant-protein extrusion enable clean-label positioning in granola bars, attracting health-oriented consumers who previously avoided conventional snack categories.
Market Restraints
- Palm oil price volatility:Tropical supply concentration in Indonesia and Malaysia exposes frying-dependent chip manufacturers to input cost swings that compress margin stability.
- Single-serve packaging restrictions:EU Green Deal tightening of packaging waste rules for portion-controlled formats elevates compliance costs and limits format innovation in European markets.
- Moisture barrier limitations:Current biodegradable film technologies fail to match synthetic barrier performance, constraining shelf-life extension for reformulated sustainable products.
Strategic Opportunities
- Vietnam and Philippines expansion:Underpenetrated modern trade channels in these Southeast Asian markets offer first-mover advantages for brands establishing direct-store-delivery networks ahead of competitor saturation.
- Convenience store shelf-space expansion:On-the-go format prioritization by retailers creates white space for single-serve protein bars and air-popped alternatives in grab-and-go locations.
- Dual carbon alignment in China:MEE enforcement of carbon intensity targets for food processing incentivizes energy-efficient extrusion investments that qualify for preferential financing.
Industry Challenges
- Extrusion technician scarcity:Automated line operation demands specialized skill sets that outpace vocational training output in emerging manufacturing clusters.
- Legacy ERP integration:Traceability requirements for FSSAI and FDA compliance force costly middleware development to connect batch control systems with enterprise platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Snack Food Market |
| Market Size in 2026 | $648.7 Billion |
| Market Size in 2035 | $1,077.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Nuts, Popcorn, Granola Bars Flavor Profile: Sweet, Savory, Spicy, Sour Packaging Type: Bags, Boxes, Cans, Pouches Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores |
| Companies Covered | PepsiCo Inc., Mondelez International Inc., Mars Inc., Nestle S.A., The Kraft Heinz Company, Conagra Brands Inc., General Mills Inc., Grupo Bimbo S.A.B. de C.V., Calbee Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Snack Food Market Strategic Shifts
Digital twin technology is virtualizing production line optimization, while regulatory pressure on packaging substrates accelerates material science investment and clean-label positioning reshapes formulation priorities across sweet and savory categories.
Digital twin platforms are virtualizing extrusion and frying process optimization by creating real-time simulations of thermal profiles and moisture migration. Mid-sized manufacturers in Thailand and Vietnam adopt these tools to reduce trial-batch waste and accelerate new product scale-up. The technology is virtualizing quality assurance workflows, compressing the gap between pilot production and commercial deployment timelines.
The EU Green Deal's packaging waste directive is tightening substrate restrictions for single-serve formats, forcing migration from multi-layer laminates to mono-material or fiber-based alternatives. European snack producers face reformulation timelines that compress product development cycles and elevate R&D overhead. Sweet categories with premium end-cap placement absorb these costs most aggressively, while savory variants in vending channels lag in compliance investment.
Urban Indian consumers are rotating demand toward protein-fortified alternatives as FSSAI fortification standards elevate nutritional transparency expectations. Modern trade channels in Mumbai and Bangalore expand dedicated clean-label shelf sections, displacing conventional impulse placement for legacy brands. This behavioral pivot concentrates in metro markets where health-conscious millennials drive household purchasing decisions.
Global Snack Food Market Segmentation
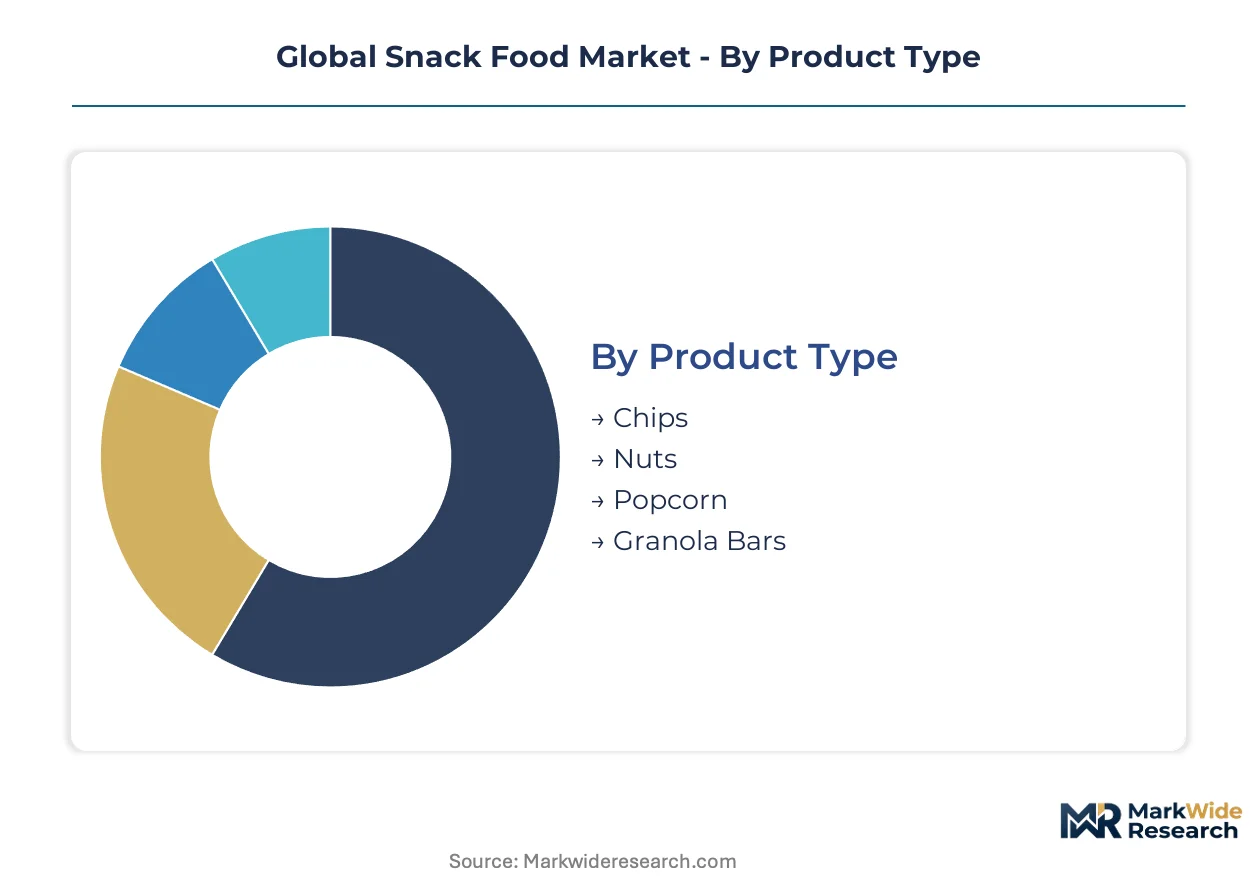
Segmentation in snack food markets reveals divergent margin structures and regulatory exposure across format, flavor, and channel dimensions. Each category carries distinct after-sales-service intensity, from shelf-life monitoring in perishable segments to packaging compliance in regulated markets.
Product Type:
After-sales-service intensity varies sharply across product categories, with moisture-sensitive formats demanding more intensive cold-chain and inventory-turn monitoring than shelf-stable alternatives.
- Chips:Thin-sliced tuber or extruded cereal bases fried or baked to sub-10% moisture content for extended shelf stability. Demand concentrates in US and European convenience channels where impulse purchase frequency and established brand loyalty sustain premium placement economics despite palm oil price volatility.
- Granola Bars:Compressed oat, nut, and dried fruit matrices with protein fortification via enzymatic hydrolysis or plant-protein extrusion. Health-oriented consumers in urban India and Southeast Asian metro markets are rotating demand toward these clean-label alternatives as FSSAI fortification standards elevate nutritional transparency expectations.
- Nuts:Roasted or raw tree nuts and legumes commanding higher per-unit margins through portion-controlled packaging.
- Popcorn:Air-popped or oil-popped whole grain with expanding grab-and-go format adoption in convenience retail.
Chips holds the largest share; momentum sits with granola bars.
Flavor Profile:
Cost tier stratification separates flavor categories, with premium-positioned profiles absorbing higher ingredient and compliance costs than mass-market variants.
- Sweet:Sugar, honey, or alternative sweetener-based coatings and inclusions commanding premium end-cap placement in supermarket channels. European producers face compressed reformulation timelines as EU Green Deal packaging restrictions elevate R&D overhead, with sweet categories absorbing compliance costs most aggressively.
- Savory:Salt, cheese, or umami-dense seasoning systems maintaining volume leadership across vending and foodservice channels where price sensitivity constrains premium migration.
- Spicy:Capsicum-derived heat profiles gaining traction in Southeast Asian and Latin American markets.
- Sour:Acidulated coatings targeting experimental flavor seekers in specialty retail channels.
Savory maintains volume dominance; sweet captures margin expansion.
Packaging Type:
Application-driven packaging selection balances barrier performance against EU Green Deal substrate restrictions and extended producer responsibility mandates.
- Bags:Flexible multi-layer or mono-material laminates dominating single-serve chip and popcorn formats. Migration from synthetic barriers to fiber-based alternatives is accelerating as European producers reformulate to preempt regulatory displacement, though biodegradable films currently fail to match moisture barrier performance for shelf-life extension.
- Pouches:Stand-up or flat flexible formats with reseal features for granola bars and nut mixes. Modern trade channels in Mumbai and Bangalore are expanding dedicated clean-label shelf sections utilizing pouch formats that signal premium positioning to health-conscious millennials.
- Boxes:Rigid paperboard for multi-serve assortments and gift-oriented presentations.
- Cans:Metal containers for premium nut assortments and export-oriented shelf-stable formats.
Bags holds the largest installed base; pouches are expanding most quickly.
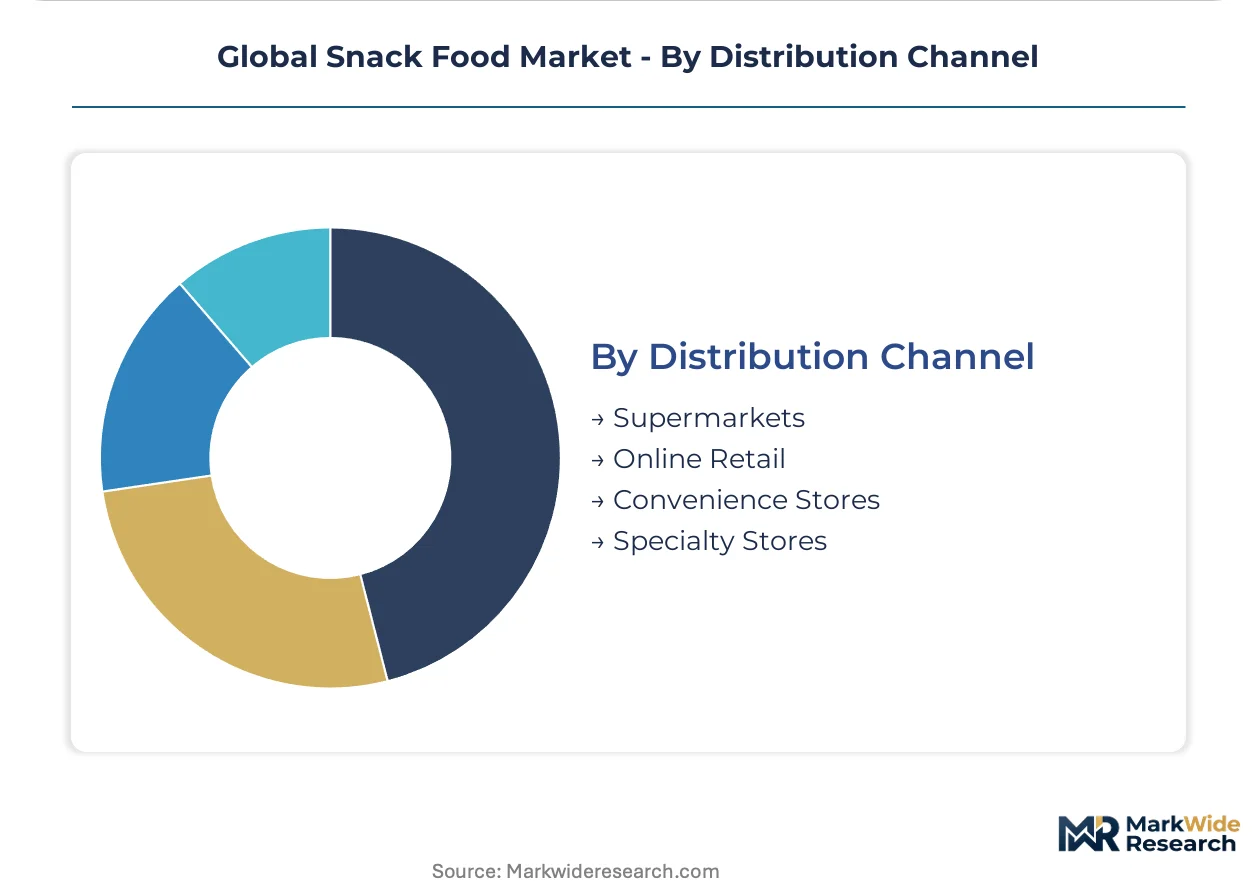
Distribution Channel:
Customer type fragmentation separates channel strategies, with direct-store-delivery networks commanding shelf placement control versus third-party logistics dependence.
- Convenience Stores:Grab-and-go oriented retailers expanding shelf space for on-the-go snack formats with high impulse purchase velocity. Underpenetrated modern trade channels in Vietnam and Philippines offer first-mover advantages for brands establishing direct-store-delivery networks ahead of competitor saturation.
- Supermarkets:Full-assortment retailers with end-cap premium placement and dedicated clean-label sections displacing conventional impulse placement for legacy brands in urban Indian metro markets.
- Online Retail:E-commerce platforms with subscription and bulk-format optimization for pantry stocking behavior.
- Specialty Stores:Curated assortments targeting experimental flavor and premium positioning seekers.
Supermarkets retains volume concentration; convenience stores are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Europe's snack import and redistribution capacity, while India's Jawaharlal Nehru Port anchors branded snack flows into South Asian markets.
United States
Impulse purchase velocity in convenience channels and direct-store-delivery network density drive snack penetration. FDA nutrition labeling and allergen declaration requirements shape product architecture for domestic distribution. Chicago and Dallas-Fort Worth metropolitan areas concentrate snack manufacturing and distribution facilities serving national retail networks.
Germany
Premium private-label demand in discount retail channels and clean-label rotation among health-conscious consumers expand addressable markets. EU Green Deal extended producer responsibility mandates force packaging substrate migration from multi-layer laminates. The Cologne-Düsseldorf industrial corridor hosts reformulation R&D facilities targeting mono-material compliance timelines.
China
Urban middle-class pantry stocking and e-commerce subscription formats accelerate category adoption in tier-one cities. MEE enforcement of dual carbon intensity targets for food processing incentivizes energy-efficient extrusion investments. The Yangtze River Delta manufacturing cluster around Shanghai scales automated production lines for both domestic consumption and export-oriented nut processing.
India
Urban consumer migration from unpackaged street foods to branded alternatives with FSSAI safety credentials concentrates demand in Mumbai and Bangalore. FSSAI fortification standards and trans fat limits drive reformulation of legacy snack portfolios. The Pune-Nashik industrial belt expands extrusion capacity to serve modern trade channels penetrating secondary cities.
Vietnam
Underpenetrated modern trade channels and rising disposable incomes create first-mover advantages for direct-store-delivery network establishment. ASEAN harmonization of food safety standards facilitates cross-border ingredient sourcing from Thailand and Indonesia. Ho Chi Minh City's manufacturing zones adopt automated extrusion lines to narrow cost gaps with established regional production bases.
Global Snack Food Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in ingredient and equipment supply. The snack food sector exhibits consolidated brand ownership alongside fragmented private-label manufacturing capacity. Three archetypes dominate: multinational platform owners with direct-store-delivery networks, regional specialists leveraging automated extrusion scale, and private-label converters serving retailer-owned brands. Competitive moves concentrate on packaging compliance investment ahead of EU Green Deal deadlines and backward integration into sustainable ingredient sourcing.
Among North American platform integrators, PepsiCo Inc. and Mondelez International Inc. occupy positions defined by distribution infrastructure depth and premium portfolio anchoring respectively. Mars Inc. represents the nut-based margin optimization archetype through portion-controlled format concentration. These three entities exemplify divergent strategic vectors: network control, sustainability-linked premium positioning, and per-unit margin architecture.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| Mondelez International Inc. |
| Mars Inc. |
| Nestle S.A. |
| The Kraft Heinz Company |
| Conagra Brands Inc. |
| General Mills Inc. |
| Grupo Bimbo S.A.B. de C.V. |
| Calbee Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Southeast Asian extrusion facilities is compressing supplier margins and forcing volume-discount tiering as manufacturers chase utilization targets. This utilization pressure feeds directly into pricing posture, with automated line operators accepting thinner margins to secure long-term offtake commitments from multinational brand owners.
Pricing Analysis
Volume-discount tiering separates enterprise-scale direct-store-delivery contracts from spot-market procurement by regional distributors. Pricing stratifies across premium clean-label positioning, standard fortified formulations, and economy-tier conventional snacks, with differentiation driven by FSSAI certification grade and palm oil sourcing transparency. Cost compression in the economy tier is intensifying because Indonesian and Malaysian feedstock volatility transmits directly into frying-dependent chip margins. Foodservice channel buyers exhibit highest price sensitivity, while modern trade supermarkets absorb premium positioning with lower elasticity.
Supply Chain Analysis
Contract-manufacturing concentration rests with PepsiCo's captive production network, Mondelez's integrated baking facilities, and third-party extrusion specialists in Thailand and Vietnam. Geographic supply concentration draws from Indonesia and Malaysia for palm oil, India for pulse and cereal inputs, and the Netherlands for reformulation R&D serving EU Green Deal compliance. Single-source vulnerability in tropical oilseed supply creates exposure to El Niño-driven harvest disruptions. Distribution runs through direct-store-delivery networks controlling convenience store shelf placement, supplemented by third-party logistics for e-commerce fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The snack food market functions as a defensive-moat story where direct-store-delivery network density creates regulatory entrenchment through shelf-placement control that new entrants cannot replicate without decade-long capital deployment.
For Market Incumbents: Pre-empt EU Green Deal packaging substrate displacement by accelerating mono-material migration ahead of compliance deadlines. Deepen backward integration into sustainable palm oil sourcing to insulate margin stability from Indonesian supply volatility. Channel control through direct-store-delivery expansion into Vietnam and Philippines represents the critical defensive lever against regional specialist challengers.
For New Entrants and Emerging Players: Underpenetrated modern trade channels in secondary Indian cities represent the most penetrable entry point for clean-label granola bar specialists. Protein-fortified formats in Mumbai and Bangalore supermarkets offer white-space positioning ahead of legacy brand reformulation. Go-to-market execution should anchor on FSSAI fortification certification as a credibility signal to health-conscious millennial purchasers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-store-delivery network operators with convenience channel lock-in. Long-term viability across the analysis window favors acquisition targets with extrusion capacity in ASEAN production clusters and established retailer relationships. The signal to watch is EU Green Deal packaging compliance timelines, which will force consolidation among non-compliant private-label converters.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Packaging Migration | EU Green Deal compliance deadlines force substrate reformulation ahead of regulatory displacement. |
| Direct-Store-Delivery Network Expansion | Vietnam and Philippines penetration captures shelf placement control before competitor saturation. |
| Protein Fortification Scale-Up | Enzymatic hydrolysis investment targets clean-label demand rotation in urban Indian metro markets. |
| Sustainable Palm Oil Backward Integration | Indonesian supply concentration creates margin vulnerability requiring captive sourcing. |
| Digital Twin Production Optimization | Thai and Vietnamese manufacturers reduce trial-batch waste through virtualized extrusion simulation. |
Study Parameters
Operator-level perspectives from plant managers at extrusion facilities, category buyers at convenience retail chains, FSSAI regulatory affairs specialists, and procurement leads at downstream brand owners anchored the qualitative base. Secondary validation drew from FDA nutrition labeling filings, EU Green Deal directive documentation, FSSAI fortification standards, and Nielsen retail audit data across convenience and modern trade channels. Bottom-up capacity assessments across ASEAN production clusters were triangulated against top-down demand modeling by distribution channel.
Scenario-bracketing framed the analytical approach with regulatory compliance timelines and palm oil price volatility bands as primary uncertainty drivers. Segmentation dimensions modeled include product type, flavor profile, packaging format, and distribution channel across the projection horizon. CAGRs were derived from elasticity-adjusted volume projections incorporating urbanization rates in India and modern trade penetration in Southeast Asia. Forecast inputs included extrusion capacity utilization rates and EU extended producer responsibility implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in Indian disposable income growth trajectories or Indonesian palm oil harvest yields would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement consistency and supply chain disruption frequency. Cross-checking against customs records for ASEAN ingredient flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Fat Crackers Market
Snacks
United Kingdom Energy Bar Market
Snacks
Edible Flakes Market
Snacks
Middle East and Africa Snack Pellets Market
Snacks
Oat-Based Snacks Market
Snacks
Global Protein Snack Market
Snacks
Popcorn Market
Snacks
Allergy-Free Snacks Market
Snacks
Spain Snack Bar Market
Snacks
Argentina Snack Bar Market
Snacks
Fruit and Vegetable Chips Market
Snacks
Low Calorie Crackers Market
Snacks
Better for You Snacks Market
Snacks
Baked Savoury Snacks Market
Snacks
Energy Balls Market
Snacks
US Potato Chips Market