
 Smart Building Market | 2026-2036
Smart Building Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Building Market Intelligence
Facility managers are redrawing procurement priorities away from traditional real estate developers as the dominant buyer archetype in smart building deployments. Johnson Controls leverages its vertical integration across HVAC and digital controls to capture recurring service revenue. Siemens anchors its position through deep specialization in building automation software that integrates with grid-edge applications.
Smart buildings integrate sensor networks, building management software, and automated control systems to optimize energy consumption, occupant comfort, and operational security across commercial and institutional assets. These systems typically operate through IP-based protocols such as BACnet or Modbus, enabling real-time data exchange between subsystems like lighting, climate control, and access management. Energy Management solutions command the widest deployment footprint as regulatory pressure intensifies, while Occupancy Analytics represents the fastest-expanding solution category as workplace utilization patterns shift permanently. Cloud-Based deployment is displacing On-Premises infrastructure among mid-market buyers seeking lower capital intensity and faster scalability.
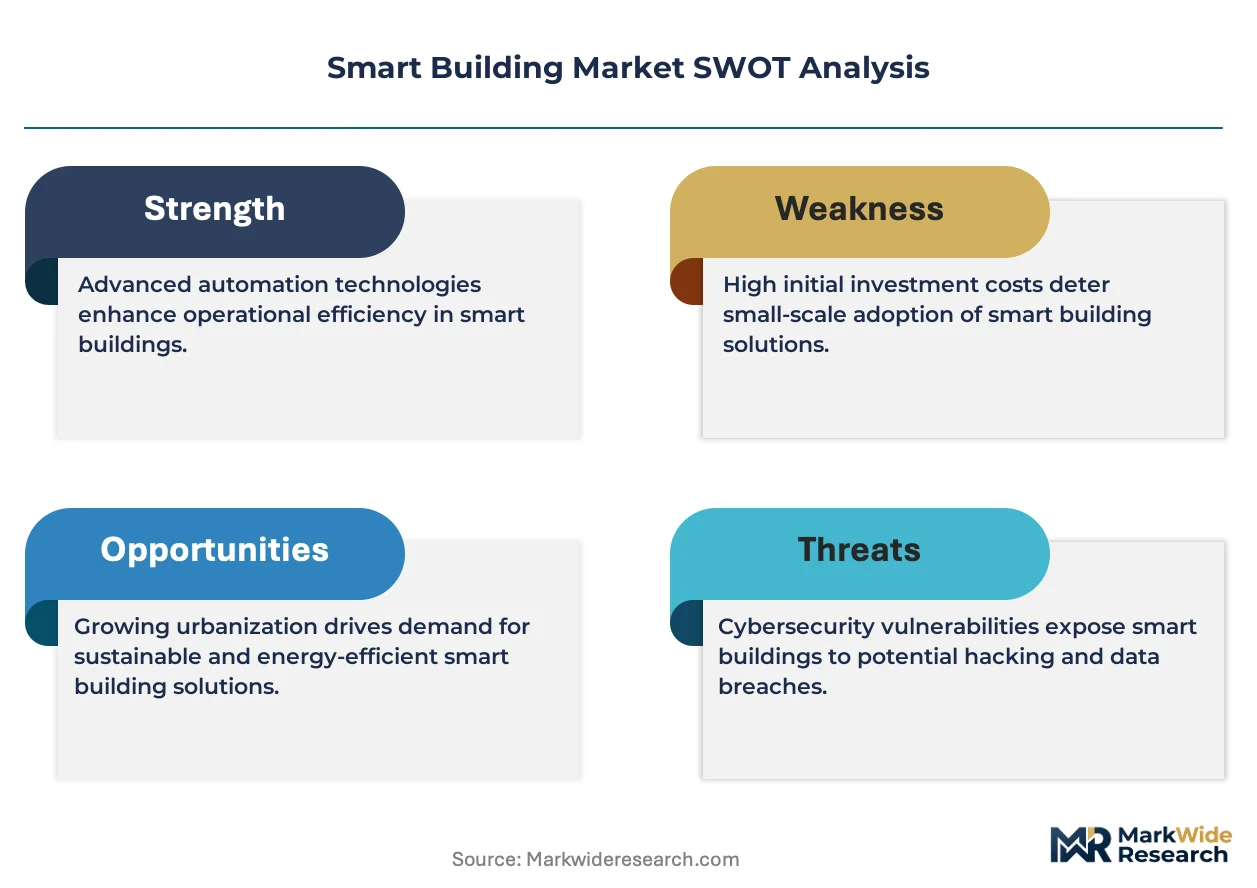
EPA energy benchmarking mandates and the EU Green Deal's building performance standards are forcing asset owners to justify automation investments against measurable carbon reduction targets. NIST cybersecurity frameworks and IEC 62443 standards are tightening product certification requirements for connected building systems, raising barriers for unqualified vendors. Stakeholders must weigh the trade-off between edge-computing latency advantages and cloud-based analytics depth when architecting system deployments.
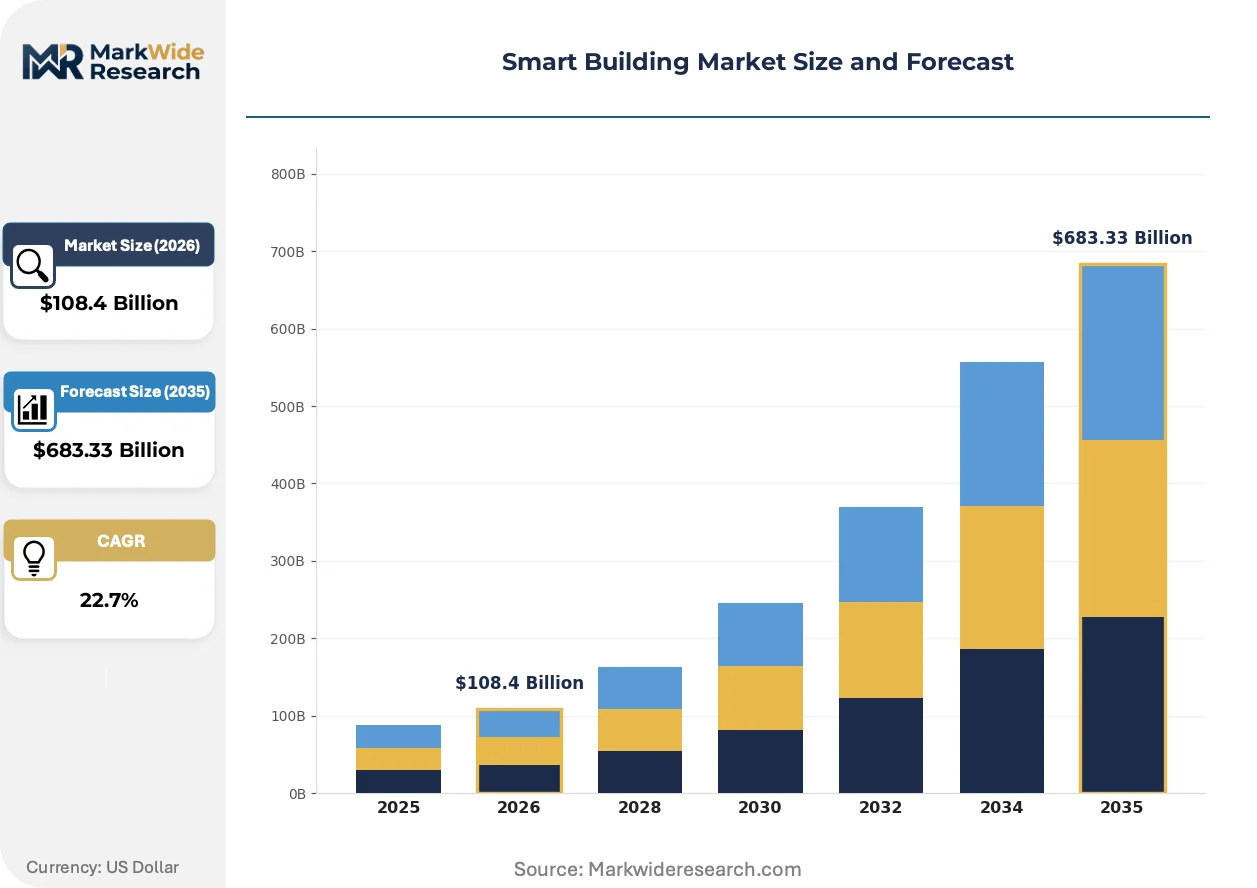
Market Dynamics
The EU Green Deal's building performance standards are forcing asset owners to automate energy systems ahead of decarbonization deadlines, compressing deployment timelines and reshaping vendor selection criteria.
Growth Catalysts
- EPA energy benchmarking mandates:US commercial real estate portfolios must install granular monitoring systems to comply with disclosure requirements, pulling demand for integrated sensor networks.
- Healthcare facilities:Hospital systems are accelerating investment in climate-controlled environments and occupancy analytics to support patient outcomes and staff efficiency.
- Edge computing architectures:Processing latency requirements for security and climate control applications are driving hybrid cloud-edge deployments across mid-market assets.
Market Restraints
- Semiconductor supply concentration:Sensor and controller chip fabrication concentrates in East Asian foundries, exposing automation projects to input volatility and extended lead times.
- Cyber certification friction:NIST cybersecurity frameworks and IEC 62443 standards impose multi-quarter product validation cycles that delay vendor market entry.
- Legacy protocol entrenchment:BACnet and Modbus infrastructure in existing buildings creates technical debt that slows IP-native system replacement.
Strategic Opportunities
- German commercial decarbonization:Stringent portfolio deadlines for commercial real estate create concentrated demand for deep automation retrofits in Europe's largest building stock.
- Grid-edge convergence:Building automation software integration with demand-response programs opens recurring revenue streams for controls vendors.
- Occupancy Analytics white space:Permanent shifts in workplace utilization patterns create unmet demand for space optimization tools beyond traditional energy management.
Industry Challenges
- OT-IT skill convergence:Facility management teams lack personnel capable of bridging operational technology maintenance with enterprise IT security protocols.
- Multi-system integration complexity:Coordinating lighting, HVAC, and access control vendors during retrofit projects extends commissioning timelines and escalates project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Building Market |
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $683.33 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Commercial Complexes, Educational Institutions, Healthcare Facilities, Data Centers, Hospitality Venues Solution Offering: Building Automation, Energy Management, Security & Surveillance, HVAC Control, Lighting Control, Occupancy Analytics Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing End User: Facility Managers, Real Estate Developers, Property Management Firms, Energy Service Companies |
| Companies Covered | Johnson Controls, IBM Corporation, Honeywell International Inc., Delta Electronics, Inc., Legrand SA, Siemens AG, ABB Ltd., Hitachi, Ltd., Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Building Market Strategic Shifts & Innovations
Cloud-based deployment models are rewriting capital allocation patterns across building automation procurement, while regulatory pressure and shifting workplace norms accelerate solution category rotation.
Digital twin platforms are supplanting static building information modeling systems as the reference architecture for predictive maintenance and scenario planning. Asset managers in institutional portfolios are adopting these tools to simulate retrofit outcomes before capital commitment. This technology is supplanting traditional energy audit workflows and compressing the vendor competitive set toward software-native providers.
The EU Green Deal's tightening energy performance standards are mandating automated fault detection and continuous commissioning across commercial assets above specified floor areas. Member state enforcement timelines vary, but the regulatory direction is hardening compliance baselines. Germany and France are responding fastest, with building codes now requiring interoperable data exchange protocols that favor open-standard vendors.
Facility managers are consolidating vendor relationships around integrated service platforms rather than procuring point solutions from specialized contractors. Traditional mechanical contractors are losing specification authority to controls vendors who bundle hardware, software, and remote monitoring. This concentration is most pronounced in US healthcare and German commercial office verticals, where single-source accountability reduces project coordination overhead.
Smart Building Market Segmentation
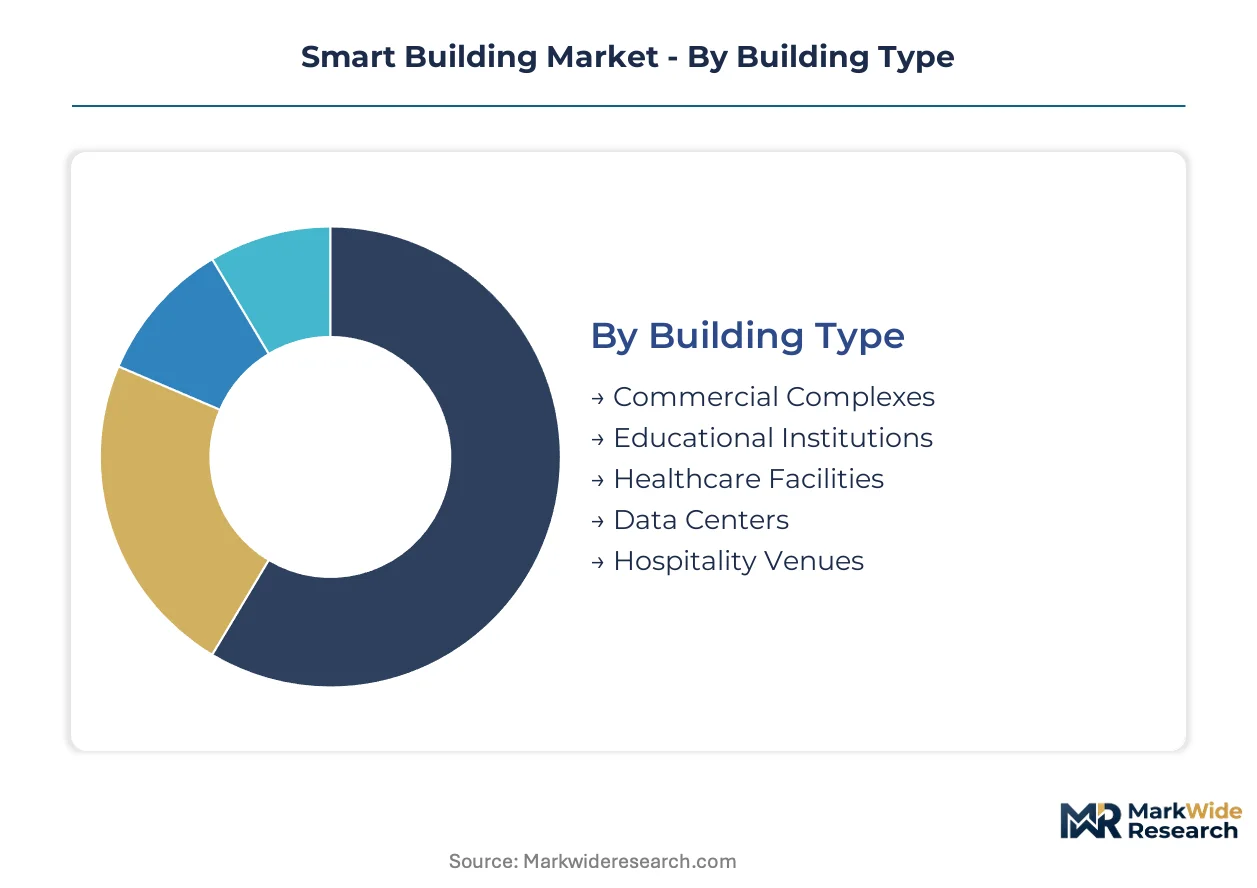
Smart building deployments fragment across asset types, solution stacks, infrastructure models, and buyer archetypes. Each segmentation axis carries distinct margin profiles and vendor competitive dynamics that shape procurement patterns.
Building Type:
Margin pools concentrate in mission-critical environments where downtime costs and regulatory scrutiny elevate solution pricing power.
- Healthcare Facilities:Climate-controlled patient environments and infection control protocols demand precision HVAC integration with real-time air quality monitoring. Hospital systems in Germany and the US are consolidating vendor relationships around single-source automation contracts to reduce commissioning complexity.
- Data Centers:Thermal load management and redundant power systems require edge-native control architectures with sub-second response latency. Operators prioritize predictive maintenance modules to minimize service interruptions that cascade into revenue loss.
- Commercial Complexes:Portfolio owners face EU Green Deal decarbonization deadlines driving deep retrofit automation across aging building stock.
- Educational Institutions:Public sector procurement cycles favor open-standard BACnet protocols that reduce vendor lock-in risk.
- Hospitality Venues:Guest experience differentiation pulls investment into occupancy-triggered environmental controls and seamless access management.
The dominant share belongs to Commercial Complexes, while Healthcare Facilities is closing the gap fastest.
Solution Offering:
Application intensity varies by regulatory pressure and operational pain point, with compliance-driven categories commanding premium pricing.
- Energy Management:Granular monitoring systems satisfy EPA benchmarking mandates and EU performance disclosure requirements. Asset owners in France and Germany treat these deployments as prerequisite infrastructure for decarbonization compliance.
- Occupancy Analytics:Post-pandemic workplace utilization patterns created unmet demand for space optimization beyond traditional energy dashboards. Sensor fusion and privacy-preserving computer vision are displacing badge-based counting systems in US and European office portfolios.
- Building Automation:Integrated control platforms consolidate lighting, HVAC, and access management under unified software layers.
- Security & Surveillance:Cyber-physical convergence drives hybrid cloud-edge architectures for video analytics and access control.
- HVAC Control:Fault detection algorithms and continuous commissioning modules address EU automated monitoring mandates.
- Lighting Control:Daylight harvesting and circadian rhythm programming gain traction in healthcare and educational verticals.
Energy Management holds the installed base lead, though Occupancy Analytics is expanding most quickly as workplace norms shift permanently.
Deployment:
Customer type determines infrastructure preference, with capital-constrained buyers favoring operational expenditure models.
- Cloud-Based:Subscription pricing and rapid scalability attract mid-market facility managers lacking dedicated IT infrastructure. German commercial portfolios and US healthcare systems are migrating monitoring workloads to reduce on-site hardware maintenance burdens.
- Edge Computing:Latency-sensitive climate and security applications require localized processing. Data centers and critical healthcare environments deploy edge nodes to maintain control independence during network interruptions.
- Hybrid:Tiered architectures balance real-time control at the edge with analytics depth in cloud environments.
- On-Premises:Air-gapped installations persist in defense and critical infrastructure facilities with stringent cybersecurity protocols.
Cloud-Based deployment is gaining share fastest among new installations, while Hybrid architectures dominate retrofit scenarios requiring legacy protocol bridging.
End User:
Procurement authority is shifting from traditional real estate developers toward operators with direct accountability for operational expenditure and compliance outcomes.
- Facility Managers:Direct operational accountability for energy costs and occupant complaints positions this group as specification authority in retrofit decisions. US healthcare systems and German commercial portfolios increasingly mandate integrated service platforms over point solutions.
- Energy Service Companies:Performance contracting models align vendor incentives with measured efficiency outcomes. ESCOs in France and the Netherlands are bundling automation hardware with guaranteed savings contracts that transfer technology risk.
- Property Management Firms:Multi-tenant assets drive demand for sub-metering and tenant billing integration.
- Real Estate Developers:New construction specifications increasingly treat smart systems as baseline amenity rather than premium upgrade.
Facility Managers command the dominant procurement role in retrofit markets, while Energy Service Companies are climbing fastest in greenfield performance-contracting segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea offshore grid interconnect underwrites Germany's commanding position in European smart building automation, while the Texas ERCOT grid and California ISO interconnection anchor US demand for climate-responsive building systems.
United States
EPA energy benchmarking mandates and IRA tax incentives pull investment into granular monitoring infrastructure across commercial portfolios. Hospital systems in Texas and California are consolidating vendor relationships around single-source automation contracts. The Greater Boston cluster concentrates demand-response integration expertise for grid-edge building systems.
Germany
Commercial real estate portfolios face EU Green Deal decarbonization deadlines compressing retrofit timelines. The Building Energy Act mandates interoperable data exchange protocols favoring open-standard vendors. The Rhine-Ruhr metropolitan region anchors deep automation retrofit activity across aging office stock.
France
Energy Service Companies bundle automation hardware with guaranteed savings contracts transferring technology risk to vendors. RE2020 building codes tighten energy performance requirements for new construction. The Paris-Saclay cluster concentrates digital twin platform development for predictive maintenance applications.
China
Dual carbon goals accelerate smart building deployment in commercial and institutional assets across tier-one cities. MIIT standards for building IoT interoperability raise certification barriers for foreign vendors. The Yangtze River Delta anchors manufacturing capacity for sensor and controller components.
United Kingdom
MEES regulations mandate minimum energy efficiency standards forcing automation retrofits in commercial lease renewals. NHS estate modernization programs drive climate-controlled environment investment. The London-Southeast corridor concentrates procurement authority for institutional portfolios.
Smart Building Market Key Industry Players
Concentration sits with diversified industrial conglomerates holding vertical integration across HVAC hardware and digital controls. The vendor base stratifies into three tiers: full-stack platform providers, specialized automation software vendors, and regional system integrators. Dominant competitive moves include portfolio diversification into grid-edge applications and strategic partnerships with energy utilities for demand-response program integration.
Within the full-stack platform tier, Johnson Controls and Siemens AG exemplify archetypes combining hardware manufacturing with recurring service revenue models. Honeywell International Inc. occupies a position bridging industrial controls with enterprise software integration. Schneider Electric SE represents the European vector for open-protocol building automation systems aligned with EU interoperability mandates.
| Leading Market Players |
|---|
| Johnson Controls |
| IBM Corporation |
| Honeywell International Inc. |
| Delta Electronics, Inc. |
| Legrand SA |
| Siemens AG |
| ABB Ltd. |
| Hitachi, Ltd. |
| Schneider Electric SE |
| Others |
Cost & Logistics Intelligence
Capacity utilization at East Asian foundry networks shapes both component availability floors and system integrator pricing power across automation hardware tiers. Scale concentration in semiconductor fabrication compresses margins for mid-market sensor vendors while elevating premiums for fault-tolerant controllers in critical infrastructure deployments.
Pricing Analysis
Volume-discount tiering structures separate enterprise-grade Building Automation Systems with bundled remote monitoring from entry-level sensor packages sold through distributor channels. Price differentiation centers on IEC 62443 certification tier and after-sales service bundling rather than raw hardware specifications. Cost compression in the mid-market segment is intensifying because facility managers are consolidating vendor relationships around integrated platforms. ESCOs and large healthcare systems exhibit the lowest price sensitivity due to performance-contracting models that transfer technology risk, while independent commercial property owners in fragmented European portfolios remain highly price-conscious.
Supply Chain Analysis
China and Taiwan anchor sensor and controller chip fabrication for building automation systems, while Germany and the United States concentrate precision HVAC hardware manufacturing. Raw material dependencies include rare earth elements for magnetic components in efficient motors, silicon carbide substrates for power electronics, and copper for wiring infrastructure. Single-source vulnerability in advanced semiconductor nodes exposes automation projects to input volatility and extended lead times. Distribution runs through authorized system integrators and mechanical contractors who maintain local commissioning capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart building market sits in early-cycle expansion as regulatory mandates force automation retrofits ahead of decarbonization deadlines across major commercial portfolios. EU Green Deal enforcement and EPA benchmarking requirements are accelerating penetration beyond early-adopter healthcare and data center verticals.
For Market Incumbents: Consolidate specification authority by acquiring specialized occupancy analytics vendors and deepening backward integration into edge-computing hardware. Siemens and Johnson Controls exemplify this path through captive supply of IP-native controllers that displace legacy BACnet infrastructure. Certification investment in NIST cybersecurity frameworks raises competitive barriers against unqualified entrants.
For New Entrants and Emerging Players: Lead with privacy-preserving computer vision solutions for occupancy analytics in US and German office portfolios, where post-pandemic utilization patterns have created unmet demand beyond traditional energy dashboards. The most penetrable segment is mid-market commercial complexes seeking cloud-based deployment to avoid capital intensity. A direct-to-facility-manager go-to-market model bypasses entrenched mechanical contractor channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among controls vendors who bundle hardware, software, and remote monitoring into subscription contracts. Long-term viability favors software-native providers with grid-edge integration capabilities rather than legacy hardware manufacturers. The signal to watch is consolidation velocity among German commercial portfolios facing 2025-2030 decarbonization deadlines.
| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Edge Integration Partnership | Building automation vendors capture recurring revenue streams through demand-response program participation with utilities. |
| Digital Twin Platform Development | Asset managers in institutional portfolios simulate retrofit outcomes before capital commitment, compressing vendor selection cycles. |
| Cybersecurity Certification Investment | NIST and IEC 62443 compliance accelerates market entry timelines and excludes unqualified competitors. |
| Cloud-Native Architecture Migration | Subscription pricing models attract capital-constrained mid-market facility managers seeking operational expenditure flexibility. |
| Occupancy Analytics Specialist Acquisition | Sensor fusion and computer vision capabilities address permanent shifts in workplace utilization patterns. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, industry association datasets, and vendor financial disclosures to validate market sizing and growth trajectory assumptions. Primary interviews engaged facility managers at US healthcare systems and German commercial portfolios, building automation software engineers, energy service company contracting officers, and grid-edge integration specialists. Secondary sources include EPA energy benchmarking databases, EU member state building code enforcement records, NIST cybersecurity framework documentation, and IEC standards publications. Bottom-up segment aggregation triangulates against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled span building type, solution offering, deployment architecture, and end-user archetype across the projection horizon. Building type captures mission-critical environments versus general commercial assets. Solution offering distinguishes compliance-driven energy management from emerging occupancy analytics. Deployment architecture separates cloud-based, edge-native, and hybrid infrastructure models. End-user archetype tracks procurement authority shifts from developers to facility managers and ESCOs. CAGRs derive from regression analysis of historical deployment velocity against regulatory enforcement timelines and technology cost curves, incorporating inputs from grid-edge convergence adoption rates and semiconductor supply availability.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement, stable semiconductor supply, or continued cloud infrastructure investment would require recalibration. Forecasts reflect assumptions regarding EU Green Deal implementation consistency, NIST framework adoption velocity, and facility management skill convergence timelines. Recalibration cycles align with material shifts in building performance standard enforcement, cybersecurity certification requirements, or workplace utilization pattern stabilization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Canada Residential Real Estate Market
Real Estate
Vietnam Real Estate & Mortgage Market
Real Estate
UAE Condominiums and Apartments Market
Real Estate
Asia Pacific Co-Working Office Spaces Market
Real Estate
Slovak Republic Facility Management Market
Real Estate
Global Unified Facility Management Market
Real Estate
Canada Hospitality Real Estate Market
Real Estate
China Residential Real Estate Market
Real Estate
Croatia Facility Management Market
Real Estate
Slovenia Facility Management Market
Real Estate
Warehousing Services Market
Real Estate
Brazil Commercial Real Estate Market
Real Estate
Block Former Market
Real Estate
Property Management Service Market
Real Estate
Asia-Pacific Affordable Housing Market
Real Estate
Vietnam Self-Storage Market