
 Global Music Streaming Service Market | 2026-2036
Global Music Streaming Service Market Size, Share, and Industry Trends Forecast 2026-2036
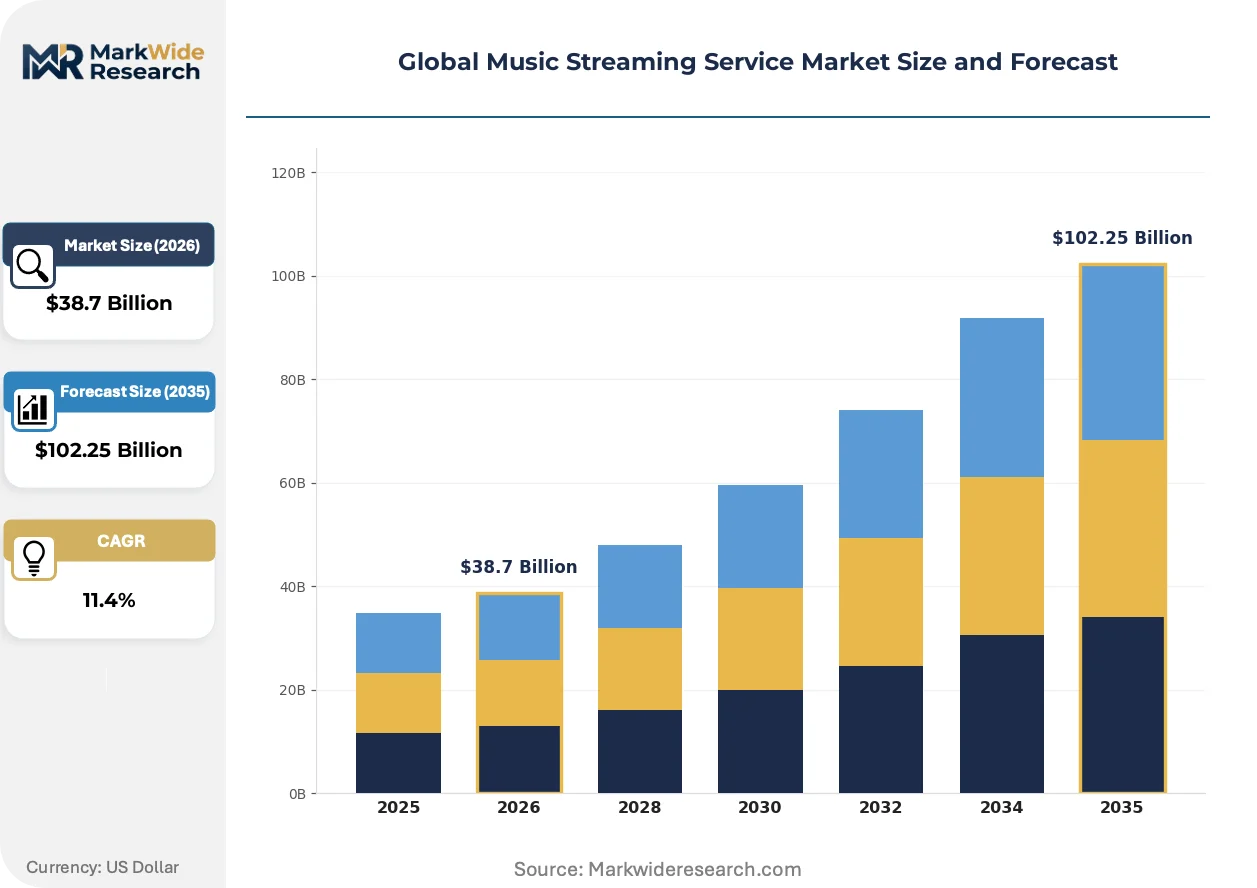
Global Music Streaming Service Market Outlook
Young adult individual subscribers is collapsing as the fastest-growing buyer archetype across developed and emerging markets. Spotify sustains its technology leadership in personalized recommendation engines and podcast integration. Tencent Music Entertainment Group dominates mainland China through its social entertainment features and karaoke functionality. Apple Music anchors premium subscriber pools with its hardware-ecosystem bundling and lossless audio catalog.
Music streaming services deliver digital audio content via internet protocol to connected devices, utilizing adaptive bitrate encoding that typically ranges from 96 kbps to 24-bit/192 kHz for high-resolution tiers, with primary commercial purpose being licensed access to recorded music catalogs without permanent ownership transfer. On-demand streaming captures the largest revenue pool as consumers prioritize playlist control and offline playback capabilities. Ad-supported models represent the fastest-expanding payment category in emerging markets where price sensitivity limits subscription conversion. Podcast services within content type segmentation are drawing fresh investment as platforms seek to diversify beyond music licensing costs.
FCC oversight of net neutrality principles shapes bandwidth prioritization rules affecting streaming quality and carrier zero-rating arrangements in the United States. GDPR and the EU AI Act impose algorithmic transparency and data minimization requirements on European operations. Stakeholders must monitor evolving royalty rate determinations by copyright tribunals across multiple jurisdictions and assess how generative AI training data licensing will reshape content acquisition economics.
Market Dynamics
Algorithmic personalization engines and adaptive bitrate streaming protocols are compressing content delivery costs while intensifying subscriber retention battles across licensed catalog platforms.
Growth Catalysts
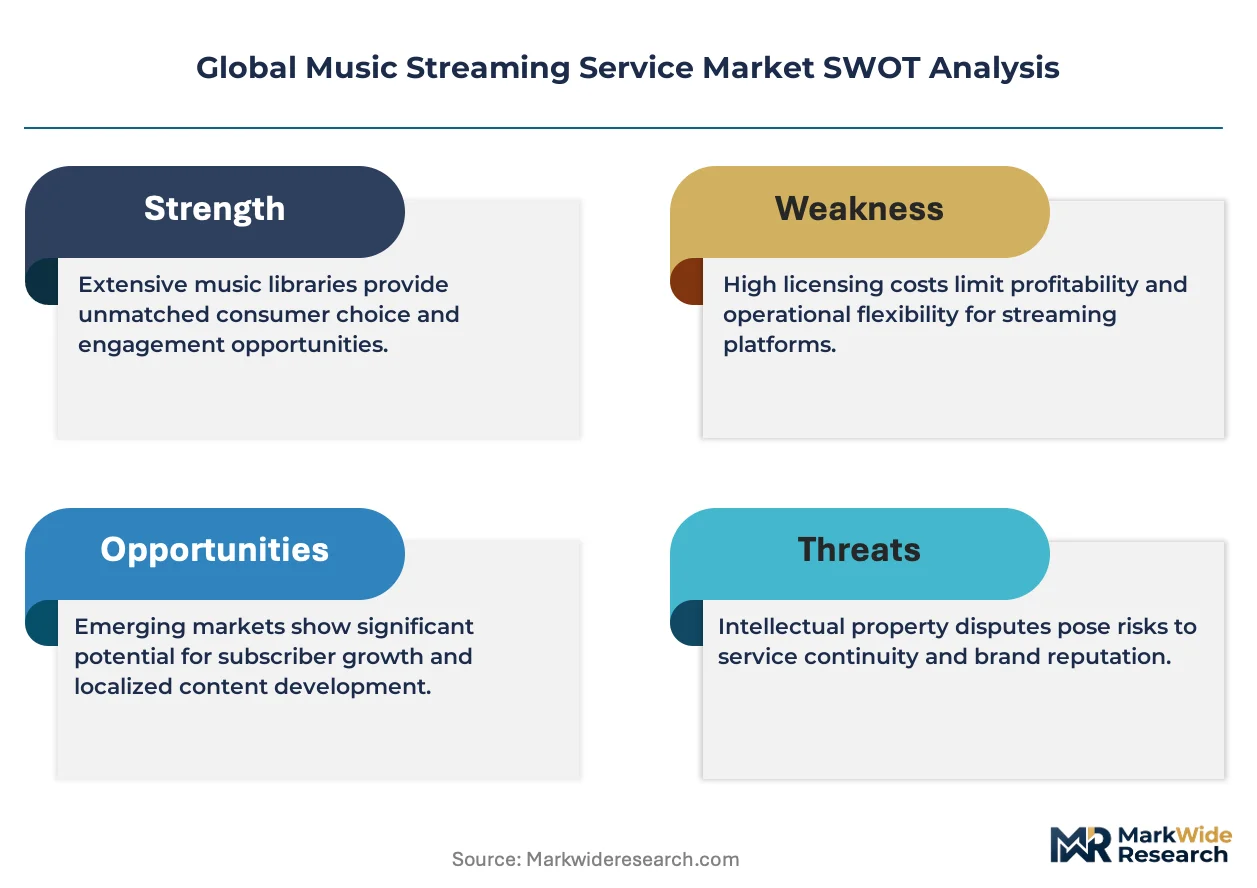
- EU AI Act compliance investments:European operators are upgrading recommendation transparency systems, creating competitive moats through audit-ready algorithmic governance that attracts privacy-conscious subscribers.
- Retail and hospitality licensing:Enterprise background music deployments in commercial environments are expanding recurring revenue pools beyond individual consumer subscriptions.
- Lossless audio codec adoption:High-resolution streaming tiers utilizing 24-bit/192 kHz encoding are capturing premium subscriber willingness to pay for hardware-matched fidelity.
Market Restraints
- Copyright royalty tribunal volatility:Rate-setting proceedings in multiple jurisdictions create unpredictable licensing cost structures that compress platform margins.
- Three-label catalog concentration:Major recorded music suppliers in the United States, United Kingdom, and Germany wield asymmetric negotiating power over streaming platforms.
- Generative AI training data uncertainty:Unresolved intellectual property frameworks around synthetic voice cloning and training set licensing threaten content acquisition economics.
Strategic Opportunities
- Brazil subscriber expansion:Price-optimized ad-supported tiers in Portuguese-language markets are converting mobile-first listeners at scale before premium upsell campaigns.
- Podcast-to-music cross-pollination:Spoken-word content integration is reducing per-stream licensing costs while extending session duration metrics.
- FCC net neutrality bandwidth rules:Zero-rating arrangements with United States carriers are enabling quality-of-service guarantees that differentiate platform delivery performance.
Industry Challenges
- Algorithmic audit talent scarcity:Machine learning interpretability specialists capable of documenting recommendation logic for GDPR and EU AI Act compliance command premium compensation.
- Legacy hardware codec fragmentation:Supporting adaptive bitrate ladders across aging device ecosystems strains engineering resources and degrades experience consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Music Streaming Service Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-Demand Streaming, Live Streaming, Radio Streaming, Podcast Services Payment Model: Subscription-Based, Ad-Supported, Freemium, Pay-Per-Use User Type: Individual Users, Family Plan Subscribers, Business Users, Students Content Type: Music Albums, Single Tracks, Audio Videos, Exclusive Content |
| Companies Covered | Amazon Music, NetEase Cloud Music, Spotify, SoundCloud, Deezer, Tencent Music Entertainment Group, YouTube Music, TIDAL, Apple Music, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Music Streaming Service Market Strategic Shifts
Generative AI voice synthesis and spatial audio rendering are redrawing content creation and consumption boundaries, while regulatory pressure on algorithmic transparency forces architectural redesigns.
Spatial audio formats with head-tracking capabilities are displacing stereo playback as the default expectation for premium tier subscribers. Young adult listeners in South Korea and Brazil are adopting Dolby Atmos-enabled hardware at accelerated replacement cycles. This displacement is compressing standard-definition catalog valuation while elevating remastering investment priorities for back-catalog assets.
GDPR algorithmic transparency mandates and the EU AI Act's risk-classification framework are forcing European operators to deploy explainable recommendation systems. Documentation of training data provenance and bias auditing protocols now consumes substantial compliance resources. French and German regulators are conducting active inspections, with platforms responding by segregating European recommendation engines from global models.
Consumption patterns are fragmenting across device-specific contexts rather than consolidating on single platforms. Automotive-integrated streaming in connected vehicles is capturing commute-time listening that previously defaulted to mobile apps. This rotation is most visible in the United States and Germany, where OEM infotainment partnerships are becoming exclusive distribution battlegrounds requiring substantial upfront integration investment.
Global Music Streaming Service Market Segmentation
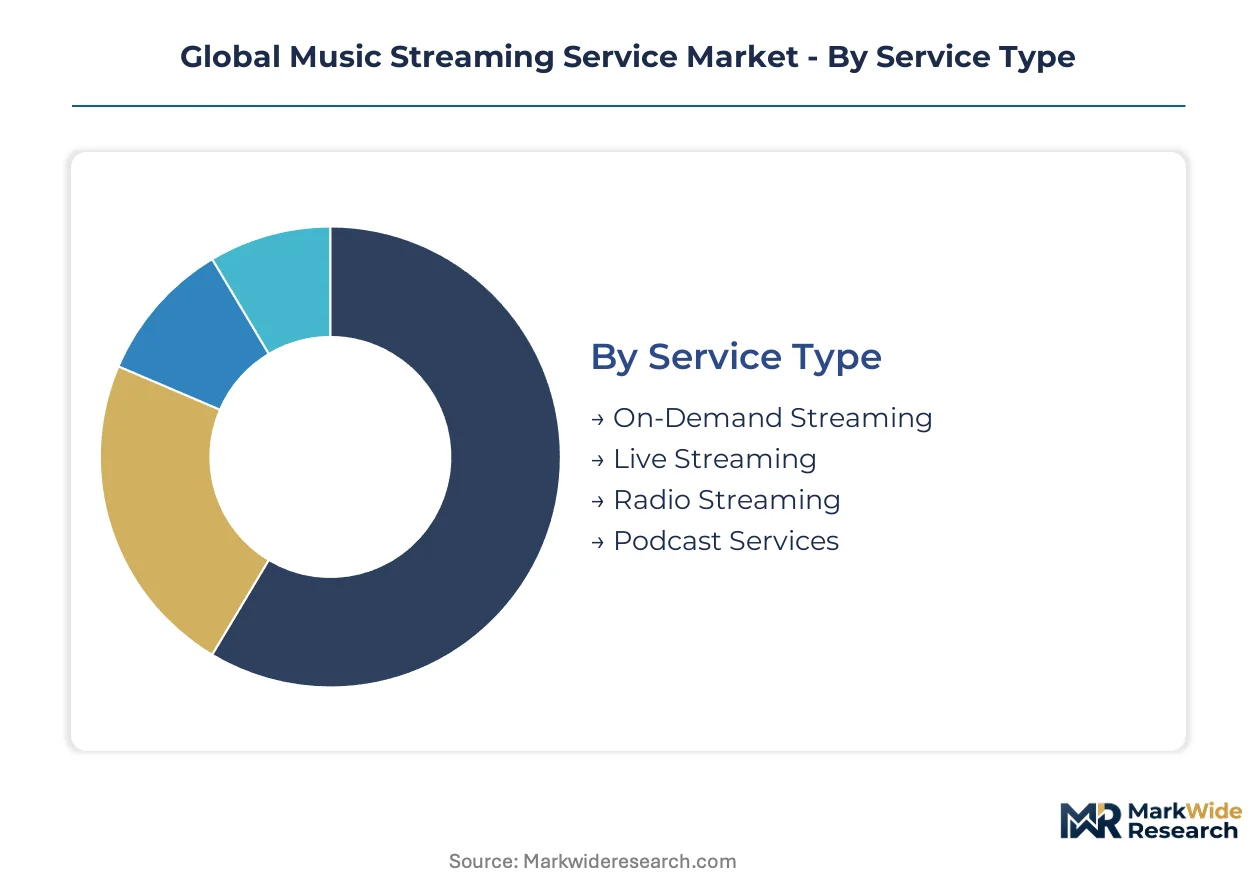
Segmentation in music streaming reveals how platform economics fragment across consumption contexts, payment willingness, and content licensing structures. Each dimension carries distinct margin profiles and regulatory exposure that shape competitive positioning.
Service Type:
Substitution pressure from short-form video platforms and social audio apps threatens live streaming and radio formats most acutely, while on-demand catalog access maintains defensive moats through exclusive licensing.
- On-Demand Streaming:Full catalog access with playlist control and offline playback capabilities anchors platform revenue. Demand concentrates in the United States and South Korea where subscriber density and premium tier conversion sustain per-user economics. FCC net neutrality bandwidth rules enable quality-of-service guarantees that differentiate delivery performance for high-bitrate tiers.
- Live Streaming:Real-time concert broadcasts and virtual event access utilize low-latency protocols. Brazil and South Korea drive adoption where K-pop live events and regional festival broadcasts command ticketed pricing. EU AI Act compliance costs for real-time content moderation compress margins relative to on-demand formats.
- Radio Streaming:Curated linear programming with limited skip functionality. Germany retains structural demand through broadcast heritage and automotive integration, though ad-load tolerance is declining among young adult demographics.
- Podcast Services:Spoken-word content with lower per-stream licensing costs than music. Investment is accelerating in the United States as platforms diversify beyond recorded music royalties.
On-Demand Streaming retains volume leadership; Podcast Services holds the steepest expansion curve.
Payment Model:
Cost tier stratification determines addressable market breadth, with ad-supported and freemium models capturing price-sensitive cohorts that subscription economics exclude.
- Subscription-Based:Recurring monthly fees for unlimited access with offline functionality. Family plan bundling in the United States and individual premium tiers in South Korea concentrate revenue. GDPR data minimization requirements increase customer acquisition costs for European subscriber bases.
- Ad-Supported:Free access funded by audio and display advertising. Brazil represents the largest expansion frontier where mobile-first listeners convert at scale before premium upsell campaigns. ANVISA advertising standards and LGPD privacy rules shape inventory valuation in Brazilian operations.
- Freemium:Tiered access with feature-gated upgrades. Student discounts and hardware bundling through OEM partnerships in Germany sustain conversion funnels.
- Pay-Per-Use:Transactional access for individual tracks or albums. Niche demand persists in Japan where physical-digital hybrid consumption patterns linger.
Subscription-Based dominates revenue contribution; Ad-Supported is climbing the fastest as emerging market penetration deepens.
User Type:
Customer type segmentation aligns pricing power with household structure and institutional procurement patterns.
- Individual Users:Single-account subscribers with personalized recommendation profiles. Young adult adoption in South Korea and the United States drives engagement metric optimization. EU AI Act algorithmic transparency mandates require segregated European recommendation engines.
- Family Plan Subscribers:Multi-profile household accounts with parental controls. United States market concentration reflects higher household discretionary spending and shared payment instrument adoption.
- Business Users:Enterprise licensing for retail, hospitality, and workplace background music. GDPR commercial use data processing agreements impose compliance overhead distinct from consumer subscriptions.
- Students:Verified educational discount tiers with eligibility documentation. Brazil and Germany show highest conversion retention post-graduation.
Individual Users retain volume leadership; Business Users hold the steepest expansion curve.
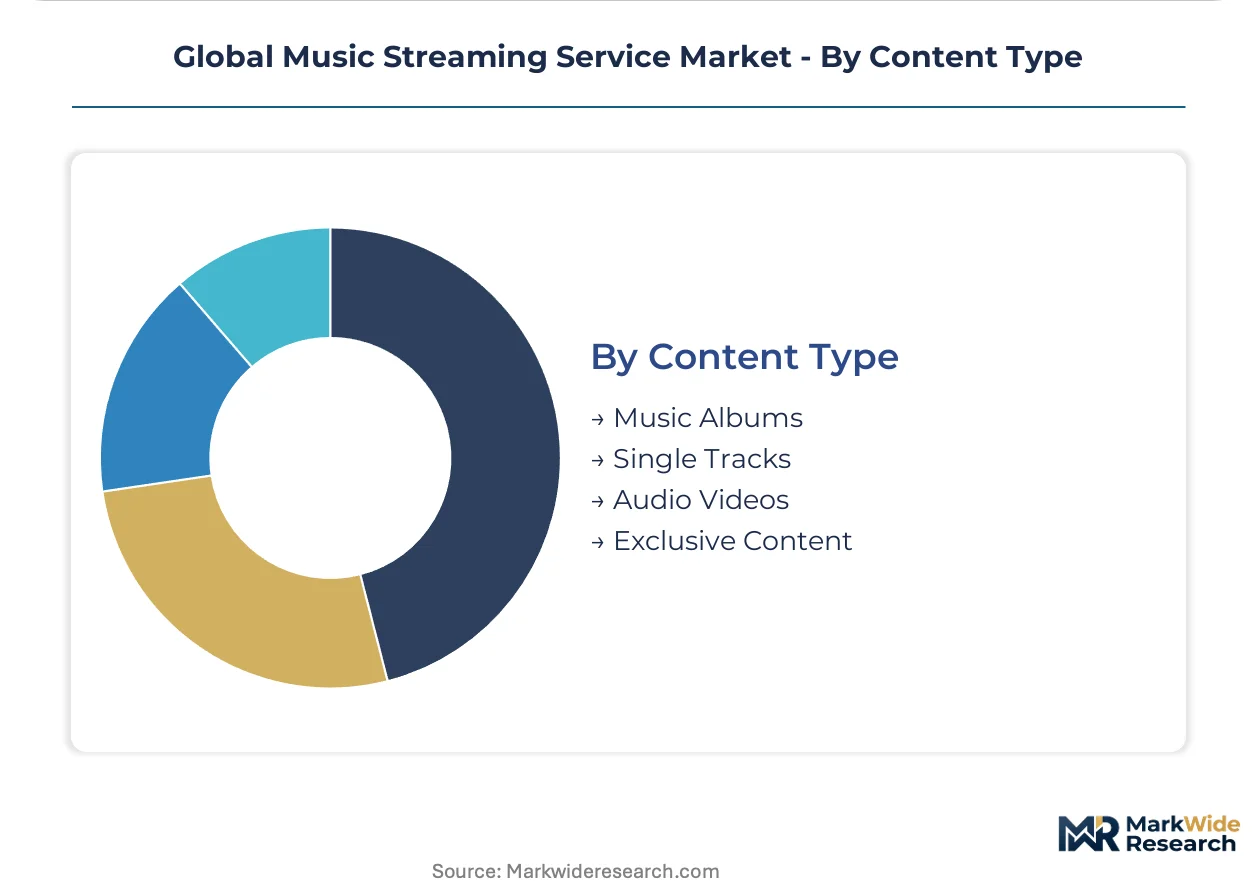
Content Type:
Supply concentration in three-label catalog structures elevates exclusive content and audio-video formats as differentiation vectors.
- Music Albums:Full-length releases with track sequencing intact. Catalog depth in the United States and United Kingdom sustains premium subscriber retention. Copyright royalty tribunal volatility in multiple jurisdictions creates unpredictable licensing cost structures.
- Single Tracks:Individual song access dominant in playlist-driven consumption. Brazil and South Korea show highest per-capita single-track streaming volume.
- Audio Videos:Visual content synchronized to audio streams. South Korea leads adoption through K-pop visual production value and YouTube Music integration.
- Exclusive Content:Platform-locked releases and early-window access. United States market concentration reflects artist deal economics and advance funding structures.
Music Albums retains volume leadership; Audio Videos holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean platform technology exports to Brazil and Southeast Asian markets are accelerating regional growth corridors. United States carriers negotiate zero-rating arrangements that shape bandwidth economics. European operators absorb GDPR and EU AI Act compliance costs that alter competitive positioning.
United States
Family plan bundling and automotive OEM infotainment partnerships drive subscriber density. FCC net neutrality proceedings determine carrier zero-rating eligibility for high-bitrate tiers. Los Angeles and Nashville anchor music industry licensing negotiations that set catalog rates.
Brazil
Mobile-first young adult adoption and ad-supported tier conversion expand addressable markets. ANVISA advertising standards and LGPD privacy rules govern inventory valuation. São Paulo concentrates platform operational investment and Portuguese-language content localization.
South Korea
K-pop global export demand and Dolby Atmos hardware replacement cycles sustain premium tier willingness to pay. MFDS oversight of biometric data in voice recognition features shapes product design. Seoul Capital Area hosts platform R&D clusters for spatial audio encoding.
Germany
Automotive integration heritage and broadcast-to-streaming migration sustain radio format demand. GDPR data minimization requirements increase customer acquisition costs for subscriber bases. Berlin and Hamburg concentrate podcast production investment and spoken-word content licensing.
France
EU AI Act algorithmic transparency mandates force segregated European recommendation engine deployment. CNIL conducts active inspections of training data provenance documentation. Paris anchors platform compliance headquarters and regulatory liaison functions.
Global Music Streaming Service Market Competitive Environment
Listed leaders compete with private specialists across catalog licensing and hardware ecosystem dimensions. The vendor base structures around three-label supplier dependence and platform-exclusive content funding. Strategic archetypes include hardware-integrated bundlers, social entertainment hybrids, and ad-supported mass-market operators. Competitive moves concentrate on podcast content acquisition and spatial audio codec differentiation.
Among Sweden-based listed entities, Spotify exemplifies the algorithmic personalization archetype. Tencent Music Entertainment Group occupies the social entertainment hybrid position in Chinese operations. Apple Inc.'s music division anchors the hardware-ecosystem bundler tier through device-integrated distribution.
| Leading Market Players |
|---|
| Amazon Music |
| NetEase Cloud Music |
| Spotify |
| SoundCloud |
| Deezer |
| Tencent Music Entertainment Group |
| YouTube Music |
| TIDAL |
| Apple Music |
| Others |
Value Chain & Pricing Dynamics
Ninety-day content licensing renegotiation cycles compress margin visibility while amplifying three-label supplier leverage across United States, United Kingdom, and German rights holders. This cadence ties pricing power directly to catalog concentration, forcing platforms to absorb royalty volatility or pass costs to subscribers.
Pricing Analysis
Standard-definition 96 kbps tiers, high-fidelity 320 kbps mid-tiers, and lossless 24-bit/192 kHz premium tiers stratify pricing across hardware-matched fidelity expectations. Three-tier pricing structure across premium, standard, and economy levels anchors subscription revenue, with Dolby Atmos spatial audio certification and exclusive windowing rights driving tier differentiation. Cost compression in ad-supported tiers is intensifying because Brazilian mobile-first listeners convert at scale before premium upsell, making this cohort most price-sensitive while South Korean audiophile subscribers show least elasticity.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes strains server hardware delivery for encoding infrastructure upgrades. Supply concentrates in Taiwan for semiconductor components, South Korea for display and audio hardware, and China for consumer electronics manufacturing. Raw material dependencies span rare earth elements for magnetic components, lithium for battery-backed edge servers, and high-purity silicon for data center processors. Single-source vulnerability in three-label catalog licensing creates asymmetric negotiating exposure. Distribution runs through hyperscaler cloud partnerships and carrier zero-rating arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story justified by subscriber data network effects that compound personalization accuracy and lock in switching costs.
For Market Incumbents: Shield catalog exclusivity through advance funding structures with United States and United Kingdom rights holders, while deepening vertical integration into podcast production to reduce per-stream licensing exposure. Spatial audio codec differentiation and EU AI Act compliance certification create regulatory entrenchment against algorithmic transparency mandates. For New Entrants and Emerging Players: Lead with enterprise background music licensing for Brazilian retail and hospitality verticals, where ANVISA advertising standards and LGPD privacy rules have slowed incumbent compliance adaptation. White-space concentration sits in Portuguese-language commercial deployments with hardware-agnostic API integration as the go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a subscription-retention compounding play because session duration metrics and family plan multipliers drive lifetime value expansion. Acquisition targets should exhibit podcast-to-music cross-pollination capabilities and Dolby Atmos remastering pipelines. Watch K-pop export volume and Brazilian ad-tier conversion rates as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Spatial Audio Codec Investment | Dolby Atmos remastering elevates premium tier willingness to pay in South Korean hardware replacement cycles. |
| Enterprise Licensing Expansion | Retail and hospitality deployments in Brazil diversify revenue beyond individual consumer subscriptions. |
| Podcast Content Acquisition | Spoken-word integration reduces per-stream costs while extending United States session duration metrics. |
| EU AI Act Compliance Architecture | Explainable recommendation systems create audit-ready moats attracting privacy-conscious European subscribers. |
| Carrier Zero-Rating Partnerships | FCC-enabled quality-of-service guarantees differentiate platform delivery performance for high-bitrate tiers. |
Study Parameters
A standing panel of platform licensing executives, music rights administrators, automotive infotainment procurement leads, and regulatory compliance officers provided ongoing calibration across primary fieldwork. Secondary validation drew from FCC net neutrality proceedings, EU AI Act implementation guidance, copyright tribunal rate determinations, and hyperscaler capex disclosures. Bottom-up subscriber modeling and top-down market sizing triangulated volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include service type, payment model, user archetype, content format, and regional regulatory cluster. CAGRs derived from cohort retention curves and pricing elasticity functions, with K-pop export velocity and Brazilian mobile data pricing serving as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FCC bandwidth governance, EU AI Act risk classification, and Brazilian LGPD enforcement; material policy shifts would require re-modeling. Generative AI training data litigation outcomes and copyright royalty tribunal volatility represent specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Media and Entertainment
Europe Inflight Entertainment and Connectivity Market
Media and Entertainment
Latin America Programmatic Advertising Market
Media and Entertainment
Global Exhibition Market
Media and Entertainment
Audio Mixing Console Market
Media and Entertainment
UK Arts Promoter Market
Media and Entertainment
Digital Rights Management in Media and Entertainment Market
Media and Entertainment
Digital Avatar Market
Media and Entertainment
Arcade Games Market
Media and Entertainment
Asia-Pacific Casino Gambling Market
Media and Entertainment
South Korea Subscription-Based Gaming Market
Media and Entertainment
Digital Newspapers and Magazines Market
Media and Entertainment
Radio Advertising Market
Media and Entertainment
Sports Broadcasting Technology Market
Media and Entertainment
Global ACGN Market
Media and Entertainment
Singapore Gaming Gadgets Market
Media and Entertainment
Global Advanced Cinema Projector Market