
 Boutique Fitness Market | 2026-2036
Boutique Fitness Market Size, Share, and Industry Trends Forecast 2026-2036
Boutique Fitness Market Analysis
Modular class-pack bundling is expanding consumer flexibility as studios unbundle traditional unlimited memberships into tiered credit systems. Xponential Fitness leverages its multi-brand portfolio to sustain geographic density across North American metros. Orangetheory Fitness anchors its growth in heart-rate-based training protocols that differentiate the brand from conventional gym offerings. F45 Training competes through franchise-standardized programming that controls quality across independent studio operators.
Boutique fitness denotes specialized, instructor-led physical training delivered in dedicated studios typically under 5,000 square feet, emphasizing community engagement and formatted exercise protocols rather than self-directed equipment use. The primary commercial purpose centers on capturing premium pricing through experiential differentiation and scheduled accountability structures that reduce member churn relative to traditional gyms. High-Intensity Interval Training and Pilates command the deepest margin pools due to equipment capital requirements and instructor certification barriers that limit competitive entry. Cycling studios occupy mature growth trajectories in coastal U.S. cities while yoga formats extend into corporate wellness contracts where employers subsidize membership as a taxable benefit.
OSHA workplace wellness guidelines and the EU Green Deal building performance standards shape studio design mandates, ventilation requirements, and energy efficiency thresholds that filter market access for new entrants. The U.S. IRS tax code Section 213(d) wellness benefit provisions and Australia's TGA-adjacent therapeutic claims oversight for fitness advertising create compliance complexity across multi-national operators. Stakeholders must monitor how municipal zoning boards classify boutique studios relative to traditional health clubs, as reclassification triggers divergent permitting costs and occupancy limits that alter unit economics.
Market Dynamics
The boutique fitness sector faces a structural compression between experiential premium positioning and operational cost inflation, as energy efficiency mandates and instructor wage pressures squeeze unit economics while consumer willingness to pay plateaus in saturated urban clusters.
Growth Catalysts
- Corporate wellness benefit expansion:Employer-sponsored fitness subsidies under U.S. IRS Section 213(d) provisions reduce net member acquisition costs while embedding studios into recurring enterprise contracts.
- EU Green Deal building retrofits:Energy performance standards for studio construction unlock public financing mechanisms that lower capex barriers for new market entrants in European metros.
- Heart-rate telemetry integration:Real-time biometric feedback systems deepen member engagement metrics and justify premium pricing tiers through quantified performance accountability.
Market Restraints
- Certified instructor supply bottlenecks:Specialized training protocols in Pilates and HIIT formats create 6-12 month qualification timelines that throttle expansion velocity.
- Lease cost concentration in tier-one cities:Prime urban retail rents in New York, London, and Sydney consume 25-35% of studio revenue, compressing operating margins.
- Substitute digital fitness platforms:Connected home equipment and on-demand streaming services capture price-sensitive consumers seeking convenience over community.
Strategic Opportunities
- Secondary city penetration:Underserved metropolitan clusters in Germany's Ruhr region and Australia's Queensland coast offer lower competitive density with comparable disposable income profiles.
- Medical fitness integration:Physician-referred exercise programs create reimbursement pathways through Australia's TGA-adjacent therapeutic claims framework.
- Modular micro-studio formats:Sub-2,000 square foot footprints reduce real estate exposure while enabling rapid geographic testing.
Industry Challenges
- Instructor retention and wage inflation:High turnover among certified trainers disrupts class consistency and drives recruitment costs upward.
- Municipal zoning reclassification risk:Local boards occasionally recategorize boutique studios as health clubs, triggering occupancy limit reductions and parking requirement increases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boutique Fitness Market |
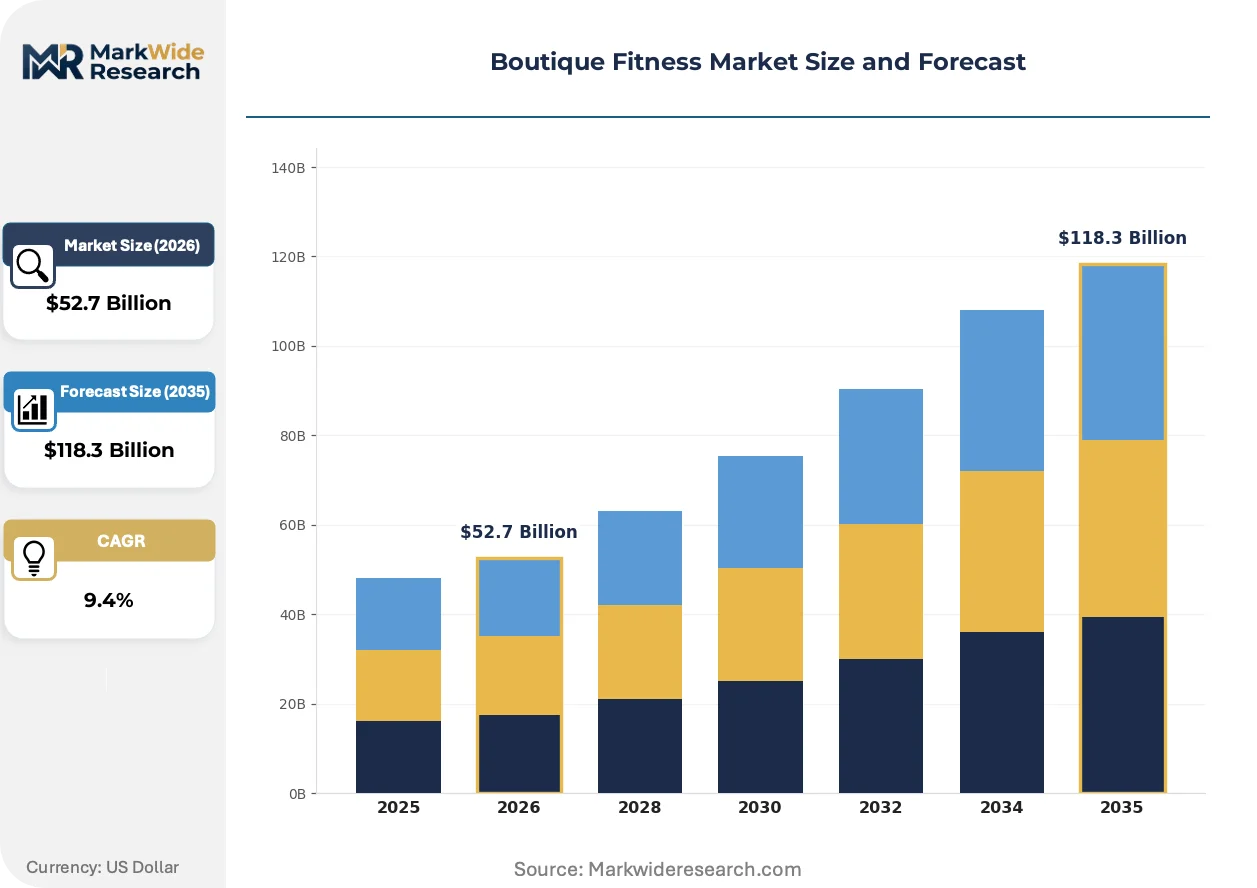
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $118.3 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Yoga, Cycling, Pilates, High-Intensity Interval Training Customer Type: Individuals, Corporate Clients, Wellness Retreats, Students Studio Size: Small Group, Large Group, Personal Training, Open Gym Membership Model: Monthly Subscription, Pay-Per-Class, Annual Membership, Punch Card |
| Companies Covered | Solidcore, Planet Fitness, Orangetheory Fitness, Anytime Fitness, LA Fitness (Fitness International), Xponential Fitness, Fitstop, Life Time, F45 Training, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boutique Fitness Market Emerging Trajectories
Technology-enabled personalization and regulatory energy mandates are restructuring how boutique studios design member experiences and physical infrastructure. These shifts favor operators who can integrate data systems while navigating compliance complexity.
AI-powered workout personalization is decentralizing programming authority from central franchise headquarters to individual studio locations. Operators in the United States and Australia deploy machine learning algorithms that adapt class difficulty based on aggregate member performance data. This compression of decision-making enables faster format iteration without corporate approval cycles.
The EU Green Deal's building energy performance standards mandate heat recovery ventilation and LED lighting retrofits for commercial fitness facilities. Studio operators face 18-24 month compliance timelines with phased efficiency thresholds. German and French markets exhibit the steepest adaptation curves as municipal enforcement intensifies.
Corporate procurement of fitness benefits is fragmenting from single-vendor contracts to multi-studio credit systems. Human resources departments in technology and professional services sectors now subsidize member-selected class packs rather than unlimited memberships. This consumption pattern shift concentrates in coastal U.S. cities where employer wellness budgets remain elevated.
Boutique Fitness Market Segmentation
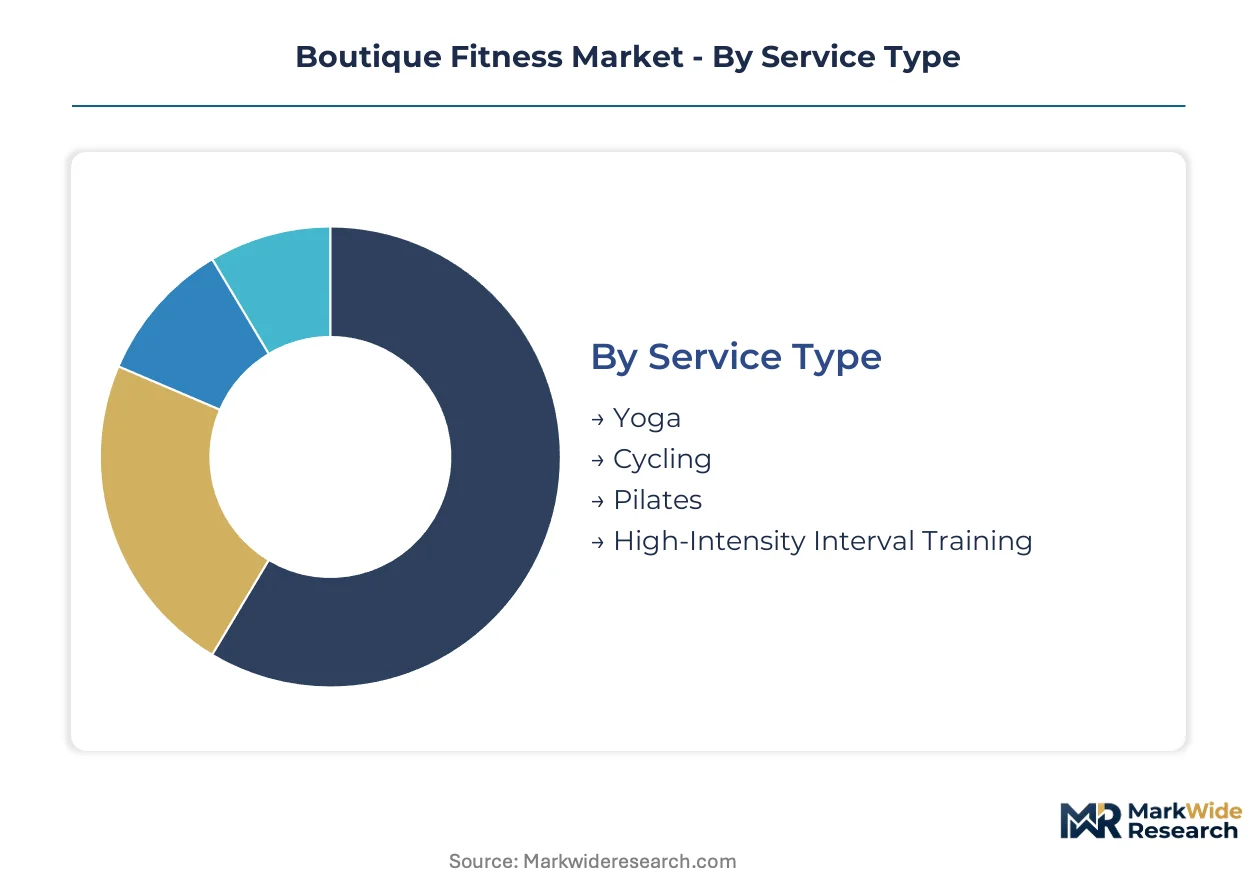
Boutique fitness operators configure their service mix, customer targeting, and real estate footprints to capture distinct margin pools. Segmentation discipline separates studios that sustain premium pricing from those competing on convenience.
Service Type:
Supply concentrates in formats where instructor certification barriers and equipment capital requirements filter competitive entry.
- High-Intensity Interval Training:Interval-based protocols demand minimal equipment but require certified coaches trained in metabolic conditioning. Demand clusters in urban United States metros where Orangetheory Fitness and F45 Training anchor geographic density through franchise-standardized programming.
- Pilates:Reformer apparatus and comprehensive certification timelines create 6-12 month instructor qualification bottlenecks. Studios in Germany's Ruhr region and Australia's Queensland coast exploit this scarcity to defend premium pricing against conventional gym competition.
- Yoga:Lower capital barriers enable rapid studio proliferation, though differentiation relies on instructor reputation and specialized formats like hot yoga or aerial variations.
- Cycling:Mature growth trajectories in coastal U.S. cities face compression from at-home connected equipment substitutes that capture convenience-seeking consumers.
Today's leader: High-Intensity Interval Training. Tomorrow's challenger: Pilates.
Customer Type:
Revenue stability depends on contract duration and subsidy mechanisms rather than discretionary individual spending.
- Corporate Clients:Employer-sponsored fitness benefits under U.S. IRS Section 213(d) provisions reduce net acquisition costs while embedding studios into recurring enterprise contracts with 12-24 month terms. Technology and professional services sectors in coastal U.S. cities concentrate procurement budgets here.
- Individuals:Direct-pay members exhibit highest lifetime value in Australia's metropolitan clusters where disposable income supports premium positioning, though churn rates exceed corporate-subsidized cohorts.
- Wellness Retreats:Seasonal demand spikes in Germany's Bavarian and Black Forest regions create capacity utilization challenges for studio operators without diversified revenue streams.
- Students:Price-sensitive segment concentrated near university towns in the United States and Australia, typically served through discounted class packs rather than unlimited memberships.
Corporate Clients anchor revenue predictability. Individuals deliver margin expansion.
Studio Size:
Real estate exposure and instructor labor intensity scale inversely across format configurations.
- Personal Training:One-to-one protocols command highest per-session pricing in Sydney and New York where affluent consumers prioritize accountability and customization over community dynamics.
- Small Group:8-15 participant formats balance instructor attention with revenue per square foot, dominating new studio openings in Germany's secondary cities where lease costs remain manageable.
- Large Group:Cycling and HIIT studios maximize throughput in prime urban retail locations, though occupancy limits under municipal zoning reclassification risk compress capacity.
- Open Gym:Minimal instructor dependency reduces labor costs but sacrifices the experiential differentiation and scheduled accountability that reduce churn relative to traditional gyms.
Small Group formats optimize unit economics. Personal Training captures price inelasticity.
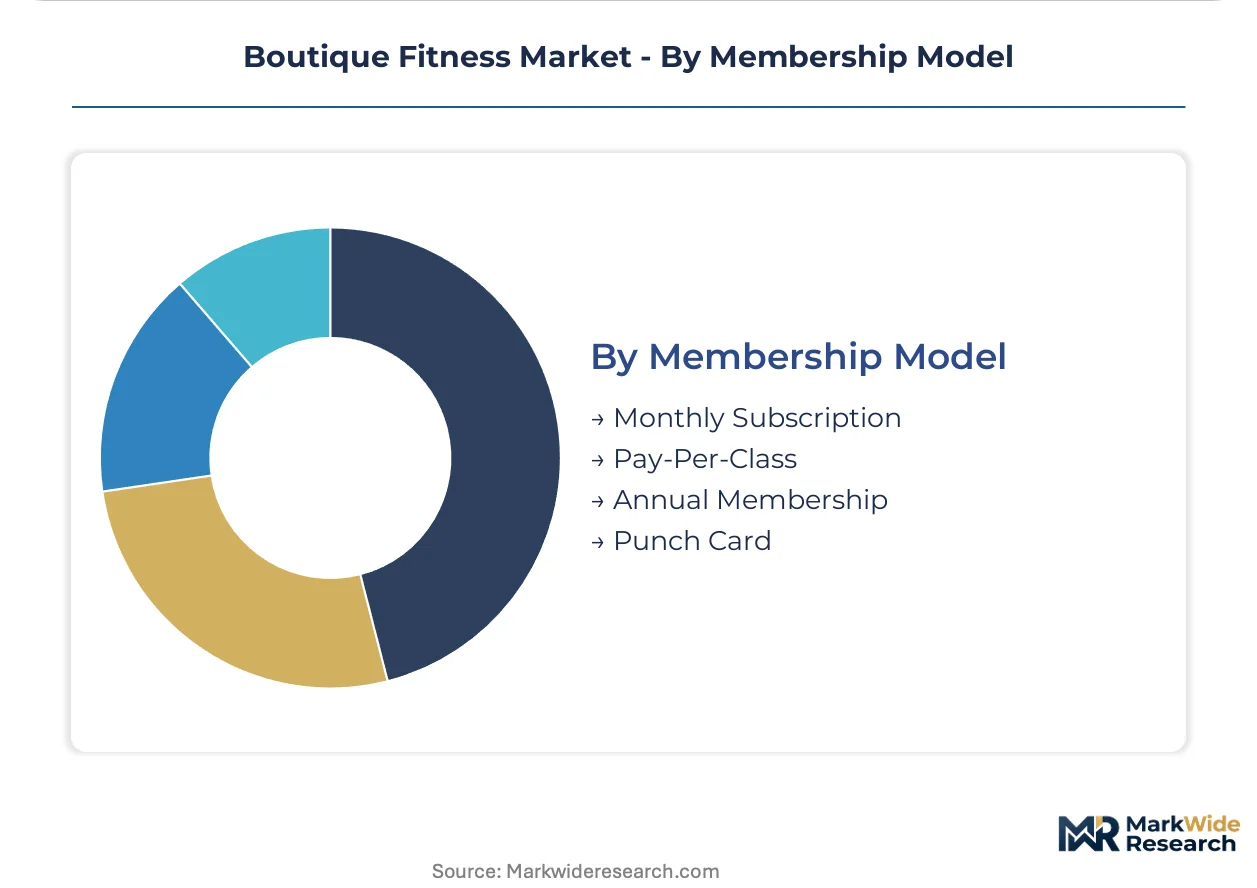
Membership Model:
Pricing architecture determines cash flow timing and member commitment depth.
- Monthly Subscription:Recurring revenue base sustains studio operations in the United States where consumer familiarity with subscription models supports predictable forecasting.
- Pay-Per-Class:Credit-based systems expand flexibility as studios unbundle unlimited memberships, concentrating adoption among corporate wellness programs that subsidize member-selected consumption.
- Annual Membership:Upfront payment improves working capital position for operators in Australia's competitive metros, though commitment depth varies with local economic conditions.
- Punch Card:Prepaid class packs appeal to intermittent users in Germany's secondary cities where fitness penetration remains below saturated urban benchmarks.
Monthly Subscription dominates volume. Pay-Per-Class gains share fastest among employer-sponsored segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boutique fitness studios originated in New York and Los Angeles during the early 2000s, spreading specialized formats like indoor cycling and barre before franchising models enabled continental expansion. Geographic diffusion now concentrates in metropolitan clusters with elevated disposable income and employer wellness infrastructure.
United States
Corporate wellness subsidies under IRS Section 213(d) provisions drive enterprise contract adoption across technology and professional services sectors. OSHA workplace wellness guidelines mandate ventilation and safety protocols that shape studio construction standards. New York and Los Angeles anchor premium pricing power, while secondary metros like Austin and Nashville attract modular micro-studio formats with lower lease exposure.
Germany
EU Green Deal building energy performance standards mandate heat recovery ventilation and LED retrofits for commercial fitness facilities. Municipal enforcement in Berlin and Hamburg intensifies compliance timelines to 18-24 months. The Ruhr region exhibits lower competitive density with comparable household income profiles, attracting Pilates and HIIT operators seeking expansion beyond saturated Berlin-Munich corridors.
Australia
TGA-adjacent therapeutic claims oversight governs fitness advertising and physician-referred exercise program reimbursements. Sydney and Melbourne command highest per-session pricing for personal training formats. Queensland coastal clusters present secondary city opportunities where studio penetration lags disposable income benchmarks established in southeastern metros.
United Kingdom
GDPR compliance requirements shape member data collection practices for biometric feedback systems and performance tracking apps. London concentrates cycling studio maturity with compressed growth trajectories from at-home equipment substitutes. Manchester and Birmingham emerge as small-group format testbeds where lease costs consume 15-20% less revenue than prime London retail.
Canada
Health Canada guidelines intersect with provincial workplace wellness tax incentives to subsidize employer-sponsored fitness benefits. Toronto anchors national pricing benchmarks while Vancouver's wellness-oriented demographics support premium yoga and Pilates positioning. Calgary and Edmonton present corporate contract opportunities tied to energy sector employee retention programs.
Boutique Fitness Market Vendor Landscape
Premium-margin players sit above commodity-margin players across experiential differentiation and instructor certification depth. The vendor base stratifies into three tiers: multi-brand portfolio operators sustaining geographic density, single-format franchise standardizers controlling quality across independent studios, and independent owner-operators competing on localized instructor reputation. Consolidation pressure intensifies as energy mandates and wage inflation squeeze unit economics. Dominant competitive moves include modular class-pack bundling and secondary city penetration through reduced-footprint formats.
Within the multi-brand portfolio tier, Xponential Fitness and Orangetheory Fitness exemplify archetypes leveraging franchise-standardized programming and heart-rate telemetry integration respectively. F45 Training occupies a position emphasizing workout protocol consistency across independent operators. Among traditional health club incumbents, Planet Fitness and LA Fitness represent commodity-margin competition through equipment-heavy, self-directed models that contrast with boutique experiential positioning.
| Leading Market Players |
|---|
| Solidcore |
| Planet Fitness |
| Orangetheory Fitness |
| Anytime Fitness |
| LA Fitness (Fitness International) |
| Xponential Fitness |
| Fitstop |
| Life Time |
| F45 Training |
| Others |
Supply Flow & Price Mechanics
EU Green Deal building energy performance standards gate qualified supply and premium-tier pricing access, as studios retrofitting heat recovery ventilation and LED systems capture public financing advantages that lower capex barriers while commanding membership premiums over non-compliant competitors.
Pricing Analysis
Credit-based class-pack systems separate unlimited memberships from tiered consumption bundles, with price differentiation driven by instructor certification depth and real estate footprint scale. Pricing pressure intensifies in saturated urban clusters as lease costs consume disproportionate revenue share. Corporate wellness subsidies reduce net price sensitivity among employer-sponsored members, while direct-pay individuals in secondary metros exhibit highest elasticity.
Supply Chain Analysis
Domestic-content mandates in Germany and France reshape equipment sourcing as EU Green Deal compliance requires locally certified HVAC and lighting contractors for studio retrofits. Reformers and cycling hardware concentrate manufacturing in China and Taiwan, with instructor certification programs anchored in the United States and Australia. Single-source vulnerability runs through specialized Pilates apparatus suppliers. Distribution feeds through franchise procurement networks and direct studio vendor relationships.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA workplace wellness guidelines compound demand generation by mandating employer fitness benefit infrastructure, creating regulatory tailwinds that embed studios into enterprise procurement cycles.
For Market Incumbents: Deepen heart-rate telemetry integration and biometric feedback systems to differentiate against connected home equipment substitutes. Expand modular micro-studio footprints in secondary metros to reduce lease exposure while maintaining geographic density. Invest in proprietary instructor certification pipelines to defend against wage inflation and retention disruption. For New Entrants and Emerging Players: IRS Section 213(d) provisions in the United States open a window for corporate contract penetration through employer-subsidized class-pack models. Target Australia's Queensland coastal clusters where studio penetration lags disposable income benchmarks. Pursue physician-referred exercise program positioning under TGA-adjacent therapeutic claims frameworks to access reimbursement pathways. For Investors and Strategic Acquirers: Roll-up economics work for multi-format portfolio operators because instructor scarcity and energy compliance costs favor scaled procurement and shared service infrastructure. Five-to-ten-year viability hinges on corporate wellness contract expansion and secondary city saturation. Monitor municipal zoning reclassification activity as an inflection signal for occupancy-constrained markets.| Strategic Initiative | Industry Significance |
|---|---|
| Heart-Rate Telemetry Integration | Real-time biometric feedback deepens member engagement metrics and justifies premium pricing tiers. |
| Modular Micro-Studio Expansion | Sub-2,000 square foot formats reduce real estate exposure while enabling rapid geographic testing. |
| Corporate Wellness Contract Penetration | Employer-sponsored subsidies under IRS Section 213(d) embed studios into recurring enterprise procurement. |
| EU Green Deal Compliance Retrofit | Energy performance standards unlock public financing mechanisms that lower capex barriers for new entrants. |
| Proprietary Instructor Certification Pipeline | Vertical control over training timelines defends against supply bottlenecks and wage inflation pressures. |
Methodological Framework
Coverage spans the United States, Germany, Australia, the United Kingdom, and Canada, with primary inputs from each market combining studio operators, franchise development executives, corporate wellness benefit administrators, and municipal zoning officials. Secondary validation draws from OSHA workplace wellness guidelines, EU Green Deal building performance standards, IRS Section 213(d) provisions, TGA therapeutic claims frameworks, and Health Canada wellness tax incentive documentation. Bottom-up studio count and membership data triangulate against top-down market sizing.
Granularity-level modeling disaggregates service type, customer contract structure, studio footprint scale, and membership pricing architecture across the projection horizon. CAGRs derive from segment-level growth trajectory analysis incorporating corporate wellness penetration rates, energy compliance cost curves, and instructor supply elasticity. Forecast inputs include municipal zoning reclassification risk exposure and secondary market disposable income benchmarking.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Green Deal enforcement timelines or sustained instructor wage inflation. Forecasts reflect assumptions regarding corporate benefit subsidy continuity and franchise expansion velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO