
 West Africa Alcoholic Beverages Market | 2026-2036
West Africa Alcoholic Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
West Africa Alcoholic Beverages Market Intelligence
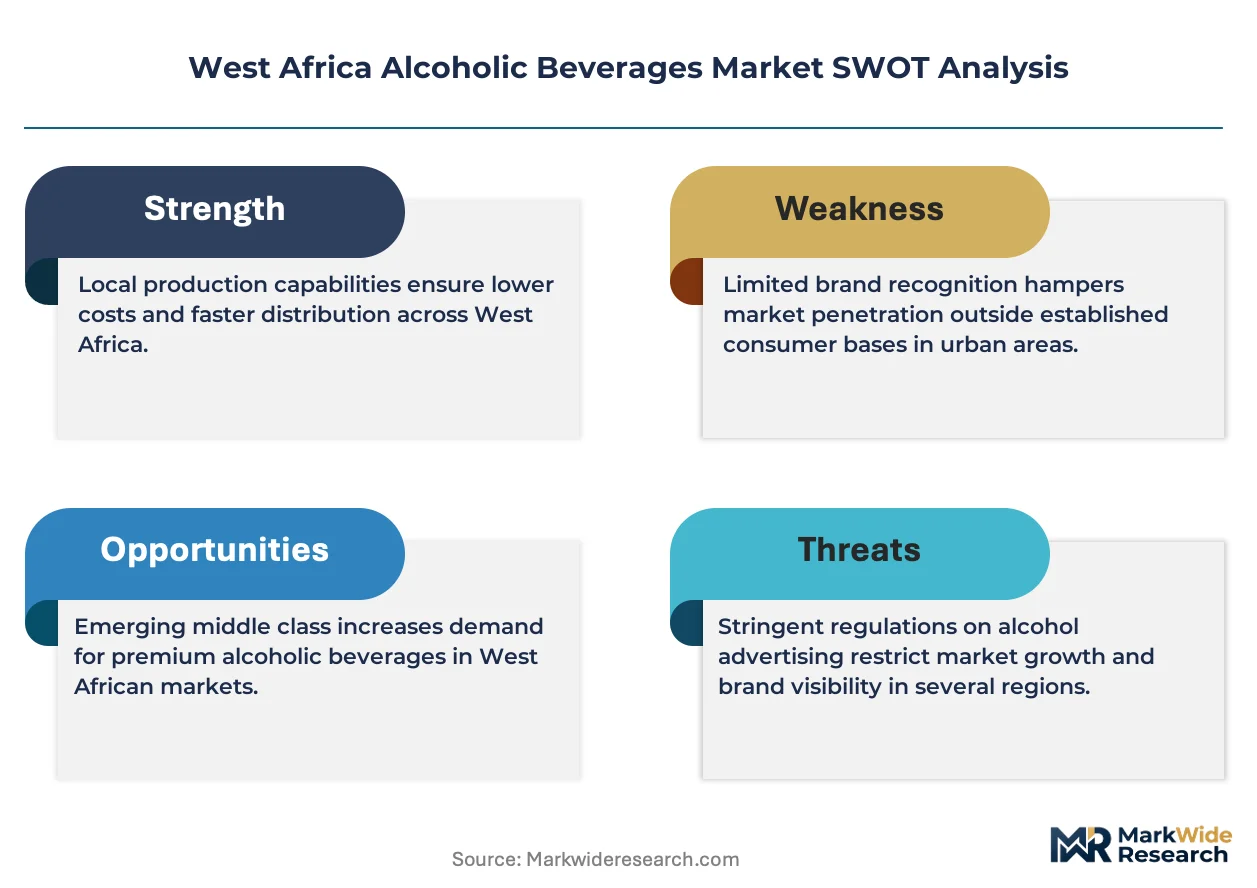
Premium lager specification tiers is collapsing the gap between mass-market and imported positioning across Lagos, Abidjan, and Accra. Nigerian Breweries leverages backward integration into sorghum and malt supply chains to protect margin structure. Guinness Nigeria anchors its stout franchise through decades-long brand equity in on-trade channels. Diageo Plc differentiates via spirits portfolio depth, particularly in whisky and ready-to-drink formulations.
West Africa alcoholic beverages encompass fermented and distilled products with ethanol content typically ranging from four percent to forty percent by volume, produced through brewing, distillation, or blending processes for social consumption and ceremonial use. Beer commands volume leadership due to affordability and localized production, while spirits capture disproportionate margin pools through premium taxation arbitrage. Online retail represents the fastest-growing distribution channel as urban millennials shift toward digital procurement, though liquor stores still dominate rural penetration. Bottles retain packaging dominance for brand visibility, yet cans gain traction in convenience-store formats.
Nigeria's NAFDAC enforces strict labeling and health-warning standards that elevate compliance costs for new entrants. Ghana's FDA and Côte d'Ivoire's national food safety authority impose parallel registration requirements that fragment market access protocols. The Economic Community of West African States (ECOWAS) common external tariff structure shapes cross-border sourcing economics for raw materials and finished goods. Stakeholders must monitor harmonization progress on excise tax bands and alcohol-content thresholds across the regional bloc.
Market Dynamics
Premium lager specification tiers is collapsing the gap between mass-market and imported positioning across Lagos, Abidjan, and Accra. Nigerian Breweries leverages backward integration into sorghum and malt supply chains to protect margin structure.
Growth Catalysts
- NAFDAC labeling mandates:Nigeria's tightening ingredient disclosure requirements are accelerating quality upgrades across domestic production facilities.
- Sorghum substitution protocols:Local grain sourcing is reducing import dependency for malted barley in Nigerian brewing operations.
- Urban hospitality corridor expansion:Ghana's Accra-Tema metropolitan zone is concentrating on-premise consumption venues and premium draft installations.
Market Restraints
- Malted barley price volatility:Currency fluctuation against euro-denominated European grain contracts compresses gross margins for Nigerian brewers.
- Excise tax band fragmentation:ECOWAS harmonization delays force parallel compliance systems across Côte d'Ivoire, Ghana, and Nigeria.
- Glass bottle supply concentration:Limited domestic container manufacturing capacity in West Africa creates import dependency on European and Asian suppliers.
Strategic Opportunities
- Ready-to-drink spirits formulations:Whisky-based premixes are capturing trial among urban millennials in Lagos nightlife districts.
- Digital retail channel penetration:E-commerce alcohol delivery platforms are bypassing traditional liquor store networks in Ghanaian cities.
- Sorghum farmer contract schemes:Nigerian Breweries' captive supply programs are securing agricultural input traceability for export qualification.
Industry Challenges
- Quality assurance laboratory capacity:NAFDAC testing backlog delays product registration timelines for new entrants into Nigeria.
- Cold chain infrastructure gaps:Inconsistent refrigeration standards across distributor networks compromise premium lager shelf stability in rural corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | West Africa Alcoholic Beverages Market |
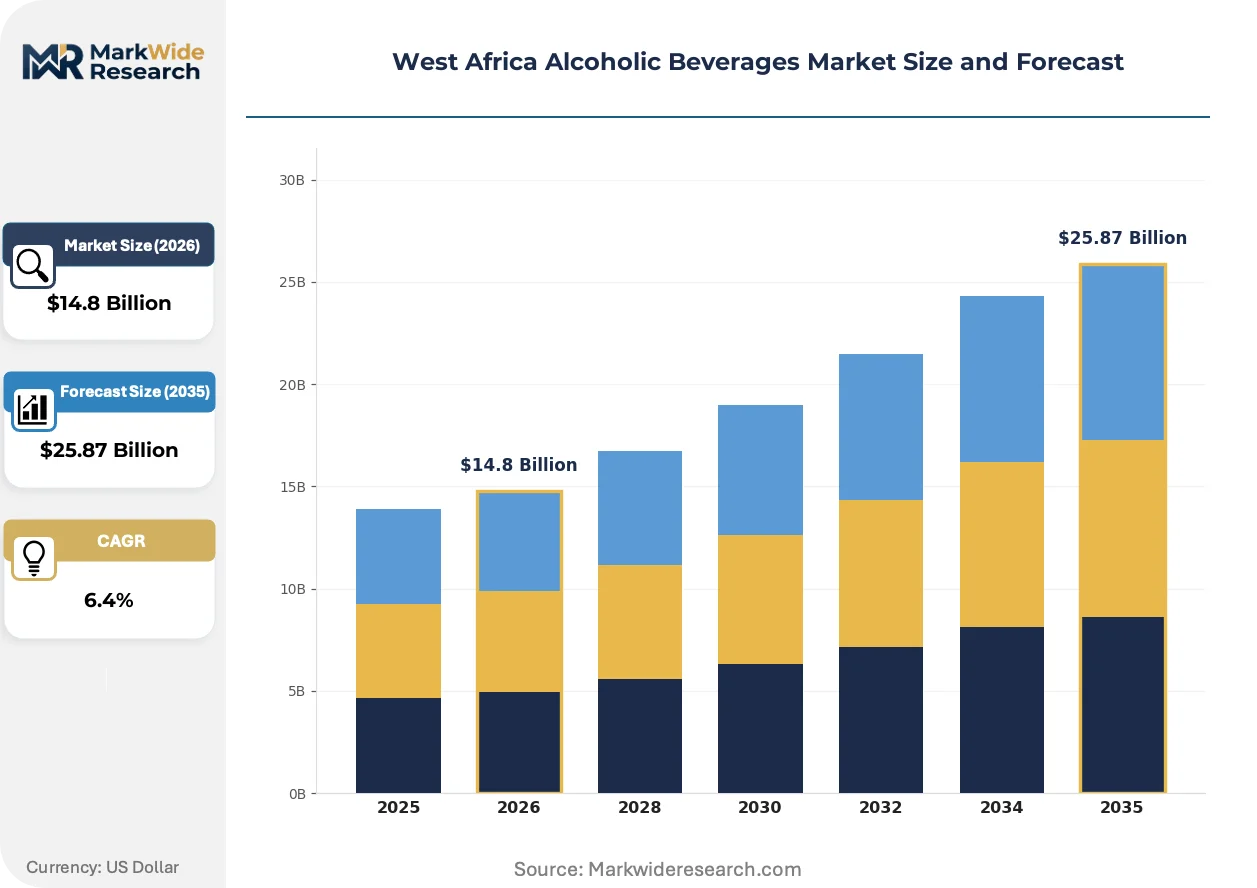
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beer, Spirits, Wine, Cider Distribution Channel: Supermarkets, Online Retail, Liquor Stores, Convenience Stores Customer Type: Millennials, Working Professionals, Tourists, Local Residents Packaging Type: Bottles, Cans, Kegs, Cartons |
| Companies Covered | Castel Group, Tambour Original, Diageo Plc, Guinness Nigeria, Nigerian Breweries, Heineken, Kasapreko Company Ltd, Pernod Ricard, AB InBev, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
West Africa Alcoholic Beverages Market Strategic Shifts & Innovations
Digital procurement platforms and localized ingredient sourcing are compressing traditional supply hierarchies across Nigerian and Ghanaian brewing operations. Regulatory disclosure requirements and consumer transparency demands are simultaneously reshaping production protocols.
Mobile-enabled direct-to-consumer ordering is fragmenting the three-tier distribution legacy in West African metropolitan markets. Lagos-based millennials are bypassing licensed liquor stores through app-based delivery services that aggregate inventory across multiple retailers. This channel disintermediation is forcing incumbent distributors to develop proprietary digital interfaces or cede urban volume to platform intermediaries.
NAFDAC's phased implementation of pictorial health warnings and ingredient transparency standards is elevating compliance infrastructure requirements for Nigerian producers. Domestic breweries are retrofitting labeling lines and reformulating additive profiles to meet disclosure thresholds. Smaller distillers without in-house regulatory affairs capacity are facing registration delays that favor established operators with dedicated compliance teams.
Consumption occasions are bifurcating between ceremonial bulk purchases and convenience-driven single-serve transactions. Urban professionals in Accra are shifting toward canned formats for informal gatherings, displacing returnable bottle rituals in informal settings. Ghana's hospitality sector is responding with modular serving sizes that match pay-as-you-go purchasing patterns prevalent in informal economy transactions.
West Africa Alcoholic Beverages Market Segmentation
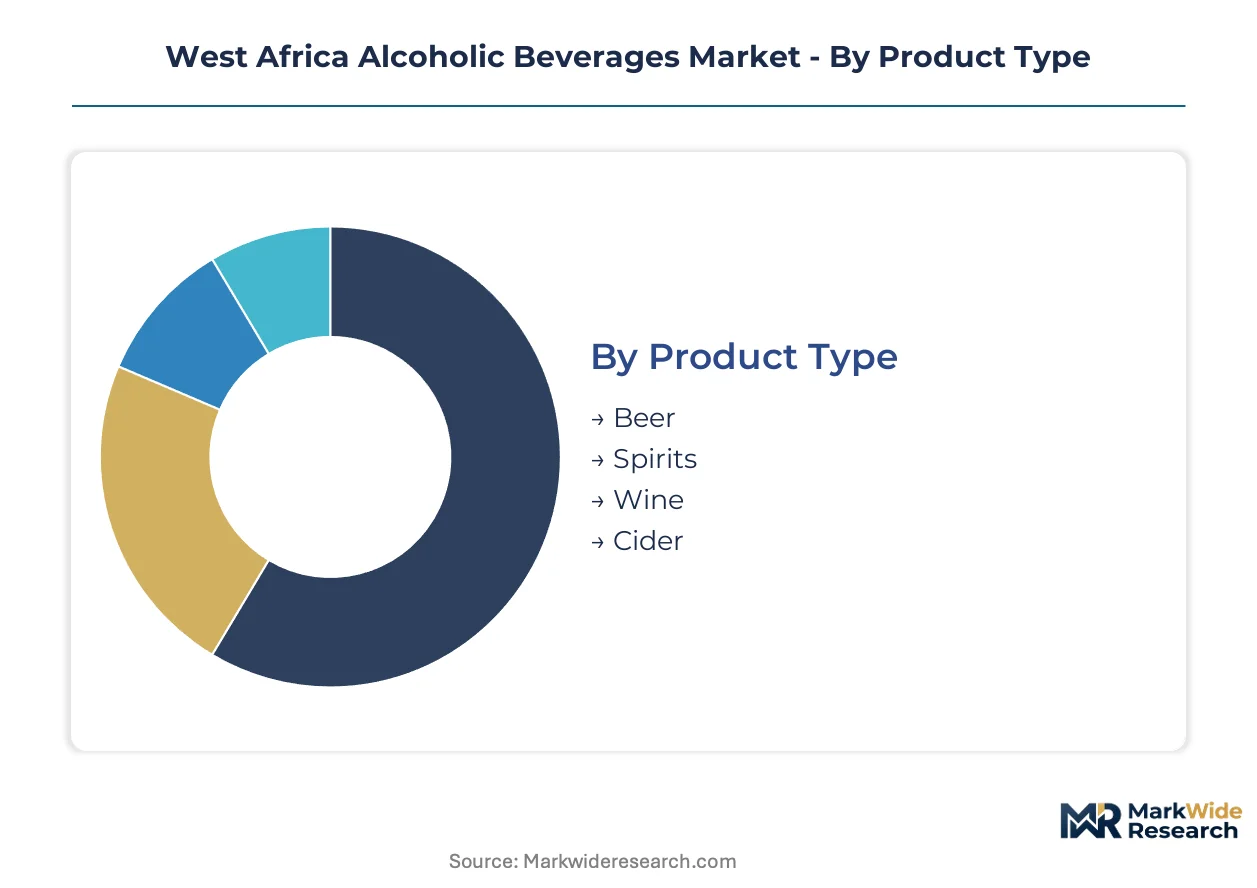
Segmentation in West Africa's alcoholic beverages market reveals how substitution pressures and channel fragmentation reshape competitive boundaries. Product type and packaging format decisions increasingly determine margin capture across Nigerian and Ghanaian consumption corridors.
Product Type:
Beer faces intensifying substitution from spirits-based ready-to-drink formulations, while wine and cider compete for ceremonial occasion budgets.
- Beer:Fermented grain beverages with four to six percent ABV dominate volume throughput across Nigerian and Ghanaian brewing facilities. Lagos and Accra working professionals drive premium lager adoption in urban on-trade venues, though sorghum-based formulations face raw material cost volatility from currency fluctuation against euro-denominated European malt contracts.
- Spirits:Distilled ethanol products ranging from twenty to forty percent ABV capture disproportionate margin pools through premium taxation arbitrage. Whisky and ready-to-drink premixes concentrate demand among urban millennials in Lagos nightlife districts, where digital procurement platforms accelerate trial adoption.
- Wine:Fermented grape products occupy ceremonial and hospitality consumption occasions, with import dependency shaping price positioning.
- Cider:Apple or pear-based fermented beverages target younger demographic trial in Ghanaian urban hospitality corridors.
Beer retains volume leadership; spirits holds the steepest expansion curve.
Distribution Channel:
Channel cost tiers determine market access economics, with digital intermediaries compressing traditional three-tier margins.
- Supermarkets:Organized retail formats with refrigerated shelving and standardized pricing serve bulk procurement needs across Nigerian metropolitan zones. Lagos-based chains anchor premium brand visibility, though cold chain infrastructure gaps compromise lager shelf stability in secondary locations.
- Online Retail:Mobile-enabled direct-to-consumer platforms aggregate inventory across multiple retailers for urban delivery. Ghanaian cities witness fastest adoption among millennials bypassing licensed liquor stores, forcing incumbent distributors toward proprietary digital interfaces.
- Liquor Stores:Traditional licensed outlets dominate rural penetration and informal economy transactions.
- Convenience Stores:Small-format neighborhood retailers emphasize single-serve canned formats for impulse purchase.
Liquor stores retain rural dominance; online retail gains share fastest in metropolitan corridors.
Customer Type:
Demographic application patterns segment procurement behavior between digital-native and occasion-driven consumption.
- Millennials:Digital-first consumers aged twenty-five to forty prioritize convenience and mobile-enabled ordering. Lagos-based cohorts drive ready-to-drink spirits trial through app-based delivery aggregation.
- Working Professionals:Salaried urban employees in Accra and Lagos concentrate premium lager demand in on-trade hospitality venues.
- Tourists:International visitors concentrate consumption in Ghana's Accra-Tema hospitality corridor and Nigerian business districts.
- Local Residents:Established community members sustain returnable bottle rituals and ceremonial bulk purchasing patterns.
Working professionals anchor premium pricing; millennials show the steepest digital adoption trajectory.
Packaging Type:
Volume and margin economics diverge sharply across format types, with supply concentration in glass manufacturing shaping strategic choices.
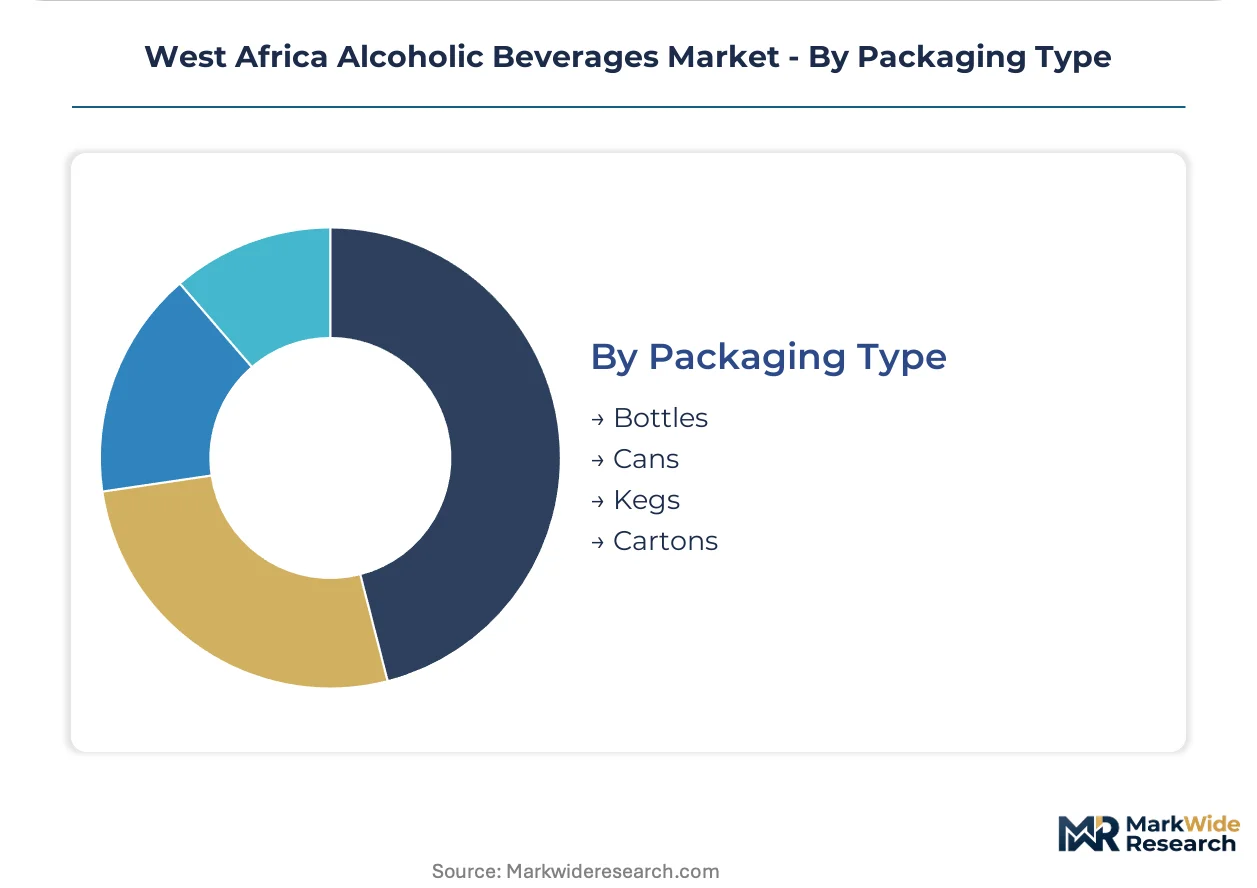
- Bottles:Returnable glass containers retain brand visibility dominance for premium positioning. European and Asian import dependency for container supply creates vulnerability to shipping cost fluctuation.
- Cans:Aluminum single-serve formats gain traction in convenience-store channels and informal gatherings. Accra professionals displace returnable bottle rituals with canned alternatives for pay-as-you-go purchasing flexibility.
- Kegs:Stainless steel draft containers serve on-premise hospitality volume in urban corridor venues.
- Cartons:Aseptic multi-serve packaging targets value-oriented bulk procurement in price-sensitive segments.
Bottles retain volume leadership; cans climb the fastest in urban convenience channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across West African markets, with Nigerian consumers exhibiting acute price sensitivity to sorghum-based lager fluctuations while Ghanaian urban professionals absorb premium positioning with minimal volume attrition.
Nigeria
Lagos and Abuja working professionals drive premium beer adoption in on-trade venues, though currency depreciation against euro-denominated malt contracts compresses margins for domestic brewers. NAFDAC enforces phased pictorial health warnings and ingredient transparency mandates that elevate compliance infrastructure requirements. The Ikeja industrial corridor concentrates brewing capacity where Nigerian Breweries and Guinness Nigeria retrofit labeling lines to meet disclosure thresholds.
Ghana
Accra-Tema metropolitan demand concentrates in hospitality venues with modular serving sizes matching pay-as-you-go purchasing patterns. Ghana's FDA imposes parallel registration requirements to Nigeria that fragment market access protocols for new entrants. The Osu and Labadi nightlife districts anchor premium draft installations where canned formats displace returnable bottle rituals among urban millennials.
Côte d'Ivoire
Abidjan's Plateau and Cocody districts sustain spirits-based ready-to-drink trial among younger demographics with disposable income growth. The national food safety authority maintains registration requirements distinct from ECOWAS neighbors, forcing parallel compliance systems. The Port of Abidjan logistics cluster handles European glass bottle imports that supply regional packaging needs.
Senegal
Dakar's coastal hospitality corridor exhibits moderate premium adoption concentrated in expatriate-facing venues and business districts. The country's national pharmaceutical and food safety regulator enforces labeling standards that lag Nigerian and Ghanaian stringency. The Pikine industrial zone hosts limited domestic brewing capacity dependent on regional supply chain integration.
Cameroon
Douala and Yaoundé urban centers sustain mass-market lager volume through price-sensitive consumption patterns with minimal premium tier penetration. The national standards agency applies food safety protocols that create registration friction for imported spirits categories. The Bonabéri industrial district concentrates beverage manufacturing with cross-border distribution reach into neighboring Central African markets.
West Africa Alcoholic Beverages Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across West Africa's alcoholic beverages sector. The market structure consolidates around multinational brewing conglomerates with captive supply chains and regional spirits distributors with portfolio depth. Three archetypes dominate: backward-integrated brewers controlling sorghum and malt sourcing, spirits specialists arbitraging premium taxation tiers, and platform intermediaries aggregating digital retail inventory. Competitive dynamics center on agricultural input traceability programs and proprietary e-commerce interface development.
Among multinational brewing conglomerates, Diageo Plc, Heineken, and AB InBev occupy positions exemplifying divergent strategic postures. Diageo Plc represents the spirits portfolio depth archetype with whisky and ready-to-drink formulation concentration. Heineken sits within the premium lager specification tier with regional production footprint expansion. AB InBev anchors the scale-driven mass-market positioning with brand portfolio breadth. Nigerian Breweries and Guinness Nigeria exemplify the backward-integrated brewer archetype with captive sorghum farmer contract schemes. Castel Group occupies a position bridging Francophone market access with brewing and distribution infrastructure.
| Leading Market Players |
|---|
| Castel Group |
| Tambour Original |
| Diageo Plc |
| Guinness Nigeria |
| Nigerian Breweries |
| Heineken |
| Kasapreko Company Ltd |
| Pernod Ricard |
| AB InBev |
| Others |
Cost & Logistics Intelligence
Long-term malted barley offtake agreements with European grain houses lock in Nigerian Breweries' input cost visibility while exposing margins to naira-euro exchange rate volatility. These contracts simultaneously secure brewing-grade barley access and transmit currency-driven pricing pressure downstream to wholesale distributors.
Pricing Analysis
NAFDAC's phased labeling mandates dictate the pricing tier structure by elevating compliance infrastructure costs that smaller distillers cannot absorb. Three-tier pricing structure across premium, standard, and economy levels stratifies around brand heritage depth and on-trade channel penetration. Cost compression in the standard tier is intensifying because sorghum substitution protocols reduce import dependency but introduce agricultural yield volatility. Working professionals in Lagos and Accra show lowest price sensitivity for premium lager, while rural local residents anchor economy-tier volume with acute sensitivity to naira depreciation.
Supply Chain Analysis
Nigeria and Ghana anchor West African brewing capacity with concentrated malting and packaging facilities serving regional demand. Manufacturing draws from European malted barley, Asian aluminum can sheet, and domestic sorghum from captive farmer contract schemes. Single-source vulnerability concentrates in European glass bottle imports where limited domestic container manufacturing creates shipping cost exposure. Distribution runs through three-tier legacy networks of licensed distributors, though digital intermediaries are fragmenting urban channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
West Africa's alcoholic beverages market is emerging from a cyclical trough driven by currency stabilization and premiumization tailwinds among urban professionals. The recovery trajectory hinges on NAFDAC compliance completion and ECOWAS excise harmonization progress.
For Market Incumbents: Fortify backward integration into sorghum supply chains to insulate margin structure from euro-denominated malt volatility. Deepen proprietary e-commerce interface development to counter platform intermediaries aggregating urban delivery volume. Channel control through captive digital infrastructure represents the critical defensive lever against disintermediation. For New Entrants and Emerging Players: Lead with ready-to-drink spirits formulations targeting Lagos nightlife districts where regulatory compliance backlogs delay established competitor registration. Ghana's Accra-Tema hospitality corridor offers the most penetrable white space for premium draft installations. A mobile-enabled direct-to-consumer launch bypasses traditional three-tier distributor gatekeeping. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among backward-integrated brewers with captive agricultural supply programs and established on-trade channel relationships. Long-term viability across the analysis window favors operators with NAFDAC-compliant labeling infrastructure and traceable sorghum sourcing. The signal to watch is ECOWAS excise tax band harmonization progress as inflection indicator for cross-border margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sorghum Supply | Captive farmer contracts reduce euro-denominated malt dependency for Nigerian Breweries. |
| Proprietary E-commerce Platform Launch | Direct digital interfaces counter platform intermediaries in Ghanaian urban delivery corridors. |
| Ready-to-Drink Spirits Formulation | Whisky-based premixes capture trial among Lagos millennials bypassing traditional distribution. |
| NAFDAC Compliance Infrastructure Investment | Labeling line retrofits accelerate product registration timelines against testing backlog. |
| Modular Serving Size Introduction | Pay-as-you-go formats match informal economy purchasing patterns in Accra hospitality venues. |
Research Approach
Operator-level perspectives from brewery supply chain managers, NAFDAC regulatory affairs leads, Ghana FDA registration specialists, and Lagos-based digital platform founders anchored the qualitative base. Primary interview findings triangulated against Nigerian customs import records, ECOWAS trade flow databases, NAFDAC product registration filings, and brewery annual disclosures. Bottom-up volume modeling from facility throughput data reconciled with top-down macroeconomic consumption indicators.
Sensitivity analysis tested forecast outputs against currency volatility scenarios and regulatory implementation delays across the analysis window. Segmentation dimensions modeled include product type, distribution channel, customer demographic, and packaging format with regional regulatory cluster overlays. CAGRs derived from historical volume trajectories adjusted for urbanization rates and disposable income elasticity. Sorghum substitution rates and digital channel penetration curves served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside NAFDAC labeling mandate adherence timelines or ECOWAS excise harmonization progress would require recalibration. Forecasts reflect documented assumptions around currency stability and agricultural yield consistency. Recalibration cycles align with material shifts in regulatory implementation schedules and cross-border tariff structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
UAE Alcohol E-Commerce Market
Alcoholic Beverages
Canada Wine Coolers Market
Alcoholic Beverages
Black Beer Market
Alcoholic Beverages
Home Beer Brewing Machine Market
Alcoholic Beverages
Hookah Charcoal Market
Alcoholic Beverages
India Gin Market
Alcoholic Beverages
Isoamyl Alcohol Market
Alcoholic Beverages
Cognac Market
Alcoholic Beverages
Global Spiced/Flavored Rum Market
Alcoholic Beverages
Ethyl Alcohol (Ethanol) Market
Alcoholic Beverages
Automated Brewing System Market
Alcoholic Beverages
Hard Kombucha Market
Alcoholic Beverages
Global Bars and Nightclubs Market
Alcoholic Beverages
Winetainer Market
Alcoholic Beverages
South America Wine Market
Alcoholic Beverages
Pisco Market