
 Virgin Leather Market | 2026-2036
Virgin Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Virgin Leather Market Analytics
Modular leather panel systems for automotive and furniture upholstery is consolidating buyer preferences around configurable, cut-to-specification supply contracts. Hermès International S.A. anchors its position through captive tannery operations in France that control raw hide selection. Kering S.A. leverages multi-brand leather sourcing across its portfolio to sustain margin visibility. LVMH Moët Hennessy Louis Vuitton SE dominates the ultra-premium segment through vertical integration from farm-level hide procurement to finished goods.
Virgin leather denotes hide material that has not undergone previous tanning, finishing, or commercial use, typically processed through chrome, vegetable, or synthetic tanning to achieve specified thickness, tensile strength, and grain consistency for industrial applications. The material serves as the structural substrate for luxury goods, automotive interiors, and high-durability upholstery where surface integrity and aging characteristics determine product lifespan. Genuine leather commands the largest value pool across product types due to its ubiquity in luxury footwear and accessories, while patent leather occupies a narrower but defensible niche in formal accessories where surface gloss constitutes a functional specification. Within quality grades, premium and luxury tiers capture disproportionate margin contribution despite representing smaller volume shares, as tanneries in Italian clusters command price premiums for certified origin and hand-finishing protocols.
REACH regulations in Europe and EPA discharge standards in the United States constrain wet-blue processing methods, compelling tanneries to invest in closed-loop water systems or alternative tanning chemistries. The EU Green Deal's product passport requirements will soon mandate traceability from slaughterhouse to finished article, reshaping procurement documentation burdens across the value chain. Stakeholders must monitor how evolving chemical restriction lists in multiple jurisdictions affect tanning process economics and supplier qualification thresholds.
Market Dynamics
REACH chemical restrictions are compressing wet-blue processing capacity across European tanneries, forcing a wholesale shift toward vegetable-tanning chemistries and closed-loop water systems that reshape cost structures and supplier qualification thresholds.
Growth Catalysts
- Automotive upholstery expansion:German and Italian vehicle manufacturers are scaling full-grain hide procurement for premium interior programs, pulling volume through certified tannery clusters.
- EU Green Deal product passports:The impending traceability mandate from slaughterhouse to finished article is accelerating investment in digital documentation infrastructure across the value chain.
- Vegetable-tanning process maturation:Advances in natural tanning agents are reducing processing time differentials versus chrome methods, enabling broader adoption by mid-tier producers.
Market Restraints
- Raw hide supply concentration:Farm-level procurement channels cluster in specific geographic belts, exposing processors to regional climate shocks and livestock disease cycles.
- Chromium discharge compliance costs:ECHA-enforced discharge limits at tanneries require capital-intensive effluent treatment upgrades that squeeze marginal operators.
- Synthetic leather substitution:Polyurethane and bio-based alternatives are capturing volume in price-sensitive automotive and furniture segments where surface aesthetics outweigh aging characteristics.
Strategic Opportunities
- Underpenetrated North American luxury furniture:Artisan upholstery workshops in the United States remain fragmented, creating consolidation potential for European tanneries with certified origin protocols.
- Blockchain-enabled provenance verification:Integration of distributed ledger technology with physical tagging is automating documentation workflows for EU Green Deal compliance.
- Biomaterial tanning agents:Convergence of enzymatic processing and agricultural waste-derived tannins opens pathways to carbon-negative leather production credentials.
Industry Challenges
- Master tanner skill scarcity:Traditional hand-finishing expertise concentrates in aging workforces across Italian clusters, constraining capacity expansion for luxury-grade output.
- Legacy chrome-tanning asset strandedness:Tanneries face write-down pressures on wet-blue infrastructure as regulatory timelines compress transition windows to alternative chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virgin Leather Market |
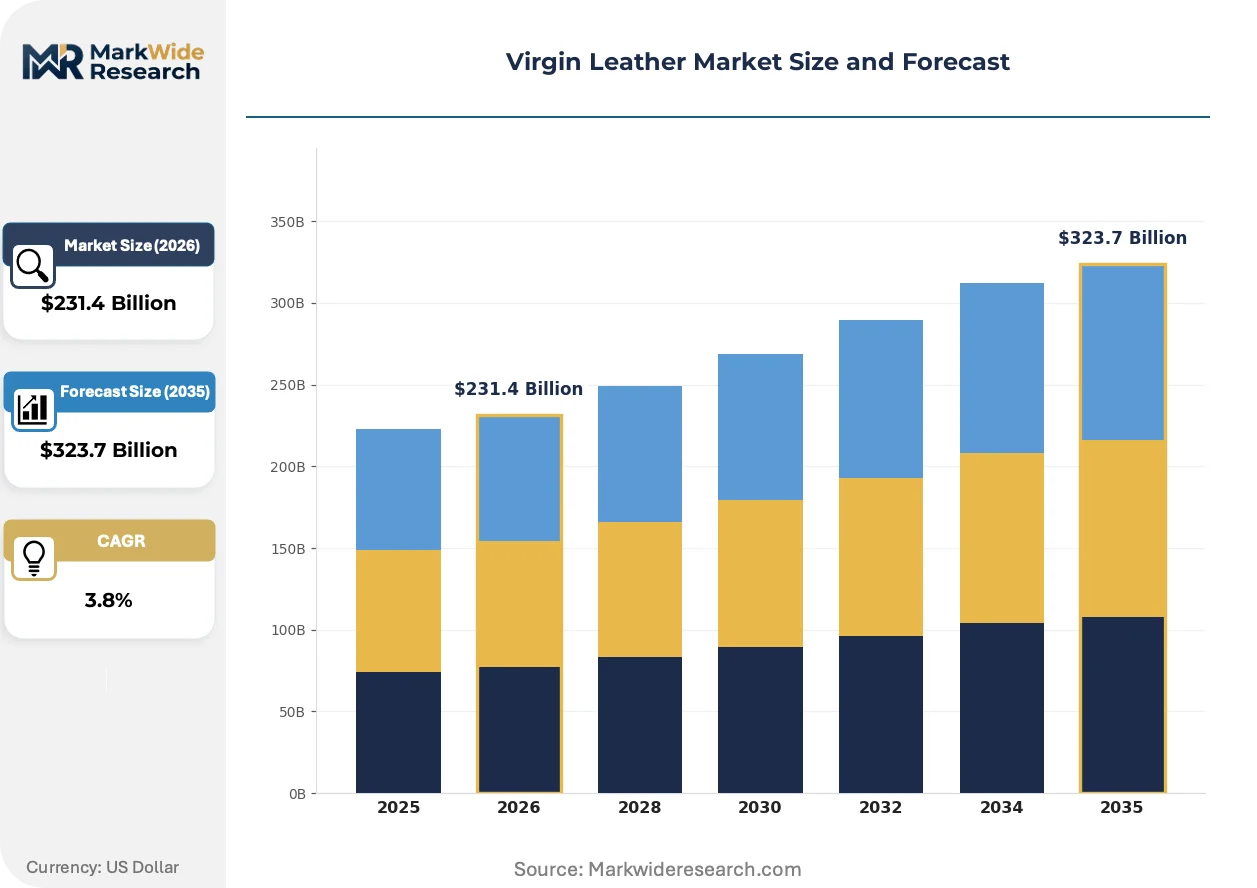
| Market Size in 2026 | $231.4 Billion |
| Market Size in 2035 | $323.7 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genuine Leather, Suede, Nubuck, Patent Leather Application: Footwear, Bags, Apparel, Upholstery Quality Grade: Premium, Mid-tier, Economy, Luxury Distribution Channel: Online Retail, Wholesalers, Direct Sales, Specialty Stores |
| Companies Covered | LVMH Moët Hennessy Louis Vuitton SE, Hermès International S.A., Kering S.A., Capri Holdings Limited, Prada S.p.A., Tapestry Inc., Adidas AG, American Leather Holdings LLC, Samsonite International S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virgin Leather Market Evolving Landscape
Processing automation and chemical substitution are converging to redefine tannery economics, while downstream buyers reconfigure procurement relationships around traceability and modular specification.
Computer-vision hide grading systems are automating quality assessment at slaughterhouse intake, reducing subjective classification errors that propagate through pricing. Automotive upholstery buyers in Germany are adopting these systems fastest, demanding digital grade certificates that compress inspection cycles. This technology is automating the elimination of manual sorting bottlenecks that previously constrained throughput scaling.
REACH Annex XVII chromium compound restrictions are tightening discharge limits for hexavalent chromium at tannery effluent points, compelling process chemistry overhauls. Italian producers around Arzignano are retrofitting closed-loop water recovery systems to maintain ECHA compliance without volume caps. Full-grain automotive programs face the steepest cost pass-through pressures as certification documentation burdens intensify.
Cut-to-specification supply contracts are displacing standard hide lot purchases among furniture upholstery manufacturers, transferring dimensional risk to tanneries. Modular panel systems enable just-in-sequence delivery to assembly lines, compressing buyer inventory positions. This pattern is most visible in Italian luxury furniture clusters where artisan workshops merge with industrial-scale upholstery operations.
Virgin Leather Market Segmentation
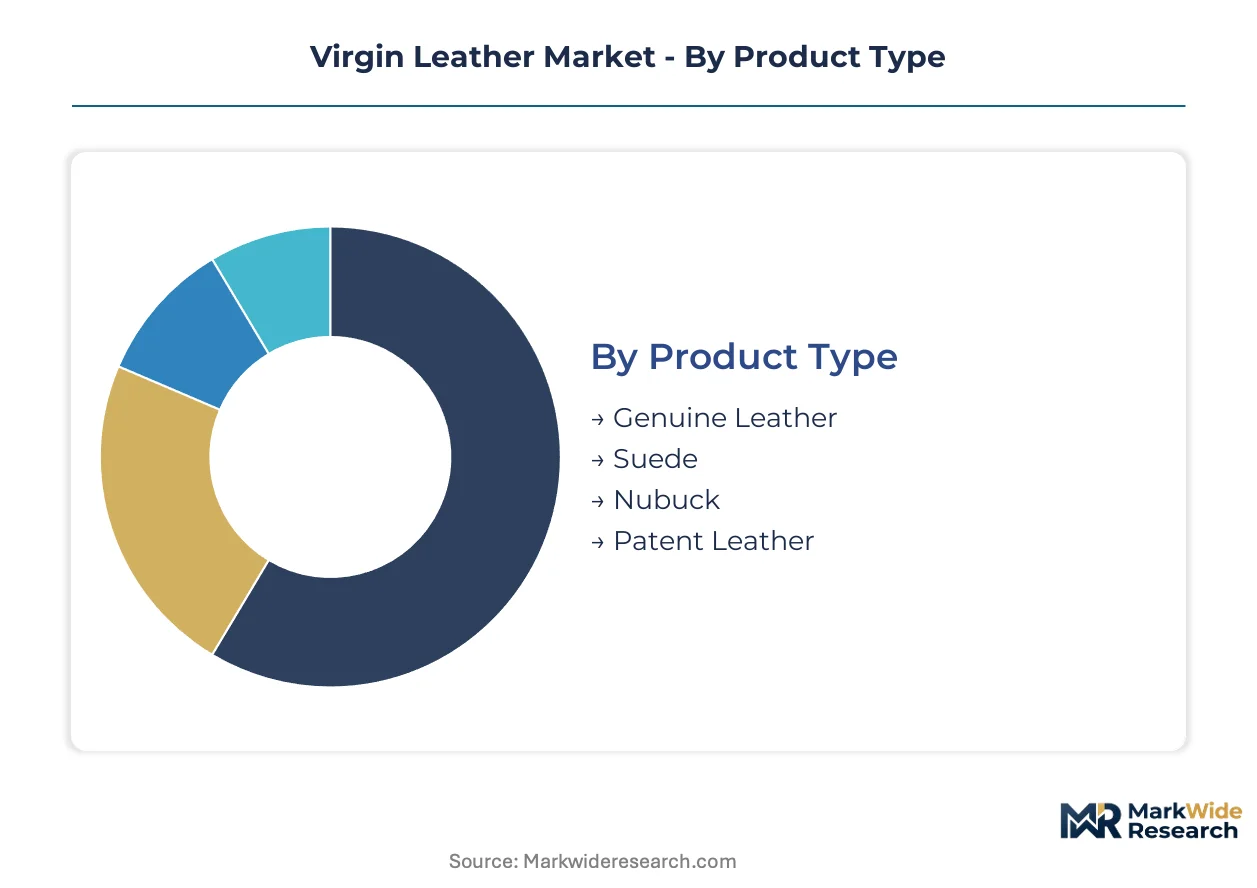
Segmentation in virgin leather markets tracks how processing methods and end-use specifications create divergent margin structures. Tanneries configure production lines around distinct quality certifications and customer documentation requirements.
Product Type:
Technology and surface finishing protocols differentiate material performance across durability, breathability, and aesthetic aging characteristics.
- Genuine Leather:Full-grain or top-grain hides retain natural fiber structure for structural applications. Automotive upholstery programs in Germany and Italy specify this grade for seat bolsters and steering wheel wraps where tensile strength thresholds exceed synthetic alternatives.
- Suede:Split hides with napped surface finish achieve soft hand-feel through buffing of flesh side. Luxury footwear houses in Italian clusters source this material for loafer linings and glove construction where pliability governs comfort ratings.
- Nubuck:Top-grain hides receive light sanding to create velvety nap while preserving surface integrity. Demand concentrates in premium furniture upholstery where abrasion resistance must coexist with tactile refinement.
- Patent Leather:High-gloss finish achieved through lacquer coating or synthetic resin impregnation serves formal accessories where surface reflectance constitutes functional specification.
Mature deployment sits with Genuine Leather across industrial volume applications. Newer deployment is concentrated in Patent Leather for evening accessories and ceremonial footwear segments.
Application:
End-use sectors impose divergent certification burdens and traceability documentation requirements that reshape tannery customer qualification protocols.
- Footwear:Largest volume sink across casual, formal, and athletic categories. Italian luxury houses source full-grain hides through captive tannery relationships that control raw hide selection from farm-level procurement.
- Bags:Structural leather goods require specific thickness tolerances and edge-finishing capabilities. Handbag manufacturers in France specify vegetable-tanned shoulders for handle attachments where load-bearing durability intersects with aging patina development.
- Apparel:Lightweight garment leathers prioritize drape and breathability over structural rigidity. Jacket producers specify chrome-tanned lamb and goat skins for motorcycle and fashion outerwear.
- Upholstery:Residential and commercial furniture demand fire-retardant finishing protocols. REACH-compliant tanneries in Arzignano supply certified full-grain for aviation and hospitality seating programs.
Volume concentration resides with Footwear. Margin expansion is climbing the fastest in Upholstery as automotive and aviation programs scale certified procurement.
Quality Grade:
Price-to-performance stratification aligns with hide origin documentation, hand-finishing labor intensity, and defect tolerance thresholds.
- Premium:Full-grain hides with minimal surface blemishing and certified origin documentation. Luxury automotive interiors specify this tier for dashboard and seat surfaces where visual consistency commands price premiums.
- Mid-tier:Corrected-grain or lightly finished hides with standardized thickness tolerances. Furniture manufacturers source this grade for residential upholstery where cost discipline competes with durability expectations.
- Economy:Split hides or heavily corrected surfaces with synthetic finishing overlays. Volume footwear producers specify this tier for price-sensitive casual segments.
- Luxury:Hand-selected hides with artisan finishing protocols and farm-level traceability. Hermès and comparable houses source through captive tannery operations that control raw material from slaughterhouse selection.
Margin capture concentrates in Luxury through vertical control of supply. Volume scaling is gaining share fastest in Mid-tier as certified tanneries expand capacity for furniture and automotive programs.
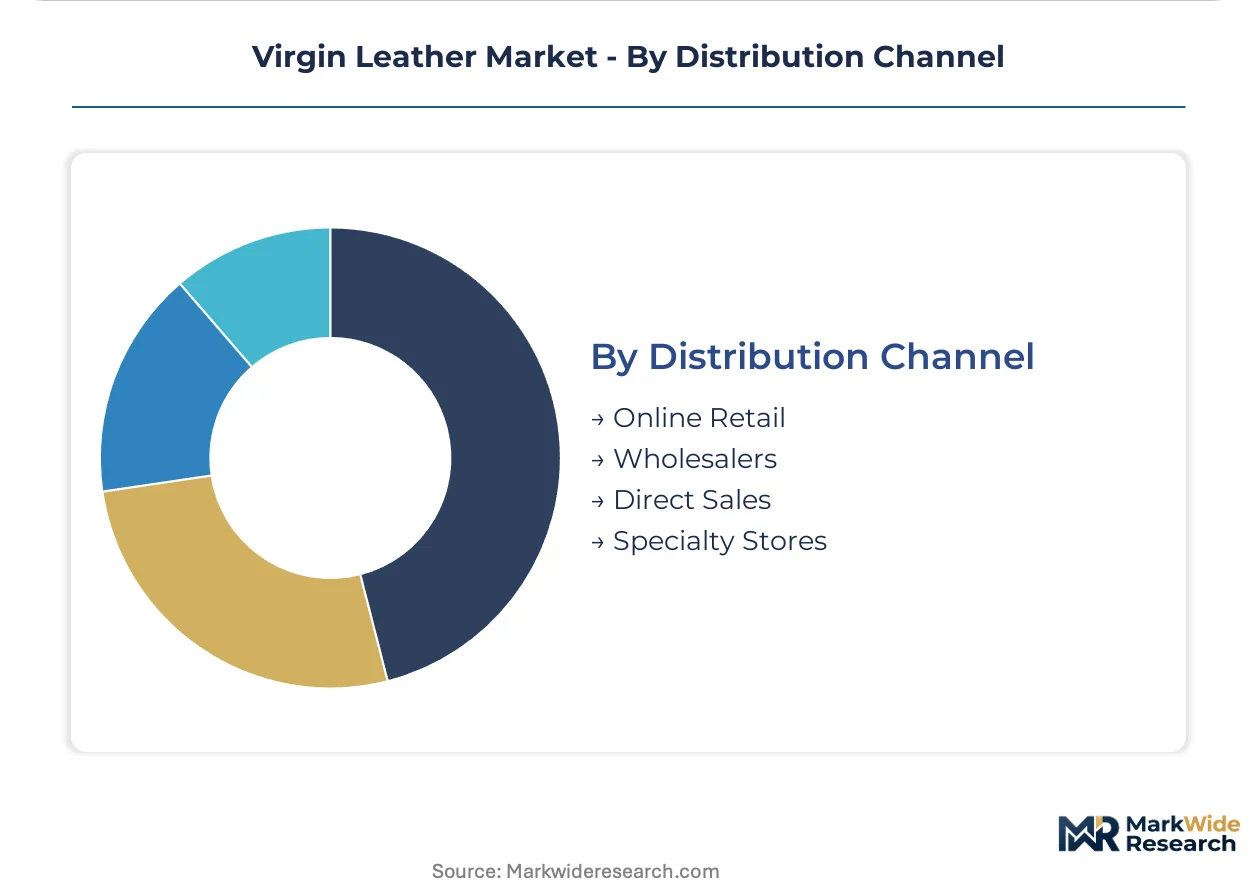
Distribution Channel:
Channel configuration determines documentation workflow automation and inventory risk allocation between tanneries and downstream buyers.
- Online Retail:Direct-to-consumer platforms for small-batch leather goods and custom accessories. Digital grade certificates from computer-vision hide grading systems enable remote procurement decisions.
- Wholesalers:Aggregated hide lots distributed to mid-tier manufacturers without direct tannery relationships. Inventory risk sits with distributors who manage grade standardization across multiple source tanneries.
- Direct Sales:Long-term supply contracts between tanneries and anchor customers in automotive and luxury goods. Cut-to-specification contracts transfer dimensional risk to tanneries while compressing buyer inventory positions.
- Specialty Stores:Artisan leatherworkers and bespoke furniture workshops sourcing hand-selected hides. Italian clusters around Solofra serve this channel with certified origin protocols and small-lot flexibility.
Relationship depth is strongest in Direct Sales. Channel expansion is expanding most quickly in Online Retail as digital documentation infrastructure matures for EU Green Deal compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in European tannery belts while consumption tilts toward Asian manufacturing centers and North American luxury retail. Italy and Germany anchor hide processing capacity through certified industrial clusters. China and Vietnam absorb intermediate leather volumes for finished goods assembly.
Italy
Arzignano and Solofra host dense concentrations of artisan and industrial tanneries supplying luxury automotive and fashion segments. ECHA-enforced REACH Annex XVII chromium discharge limits are accelerating closed-loop water system investments across Veneto and Campania facilities. Arzignano's Consorzio Vera Pelle Italiana Conciata al Vegetale certifies vegetable-tanned output for EU Green Deal product passport compliance.
Germany
BMW, Mercedes-Benz, and Volkswagen are scaling full-grain hide procurement for premium interior programs, pulling volume through Bavarian and Baden-Württemberg supply chains. KBA vehicle certification standards intersect with REACH chemical documentation requirements for automotive upholstery suppliers. Heilbronn and Reutlingen host specialized finishing operations serving OEM just-in-sequence delivery contracts.
France
Paris-based luxury houses anchor demand for hand-selected hides with farm-level traceability documentation. ANSM and CNIL oversight of chemical safety and data handling adds compliance layers to supply chain digitization. Normandy and Alsace maintain slaughterhouse-to-tannery linkages for captive raw material access by vertically integrated brands.
China
Wenzhou and Guangzhou leatherworking districts process intermediate hides into finished footwear and accessories for domestic and export markets. MEE discharge standards and dual carbon goals are tightening environmental enforcement at tanneries in Zhejiang and Guangdong provinces. Domestic brands are expanding vegetable-tanning capacity to meet EU import documentation requirements.
United States
Artisan upholstery workshops in North Carolina and Tennessee remain fragmented, creating consolidation opportunities for European tanneries with certified origin protocols. EPA effluent standards constrain wet-blue processing at remaining domestic facilities. Michigan and Ohio automotive suppliers are adopting cut-to-specification contracts for seat and interior panel programs.
Virgin Leather Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered quality segments. Market structure tilts toward consolidation at the luxury grade where captive tannery operations control raw hide selection from farm-level procurement. Three archetypes dominate: vertically integrated luxury houses with in-house tanning capacity, multi-brand portfolio companies leveraging pooled leather sourcing, and specialized tannery operators supplying third-party manufacturers. Competitive moves center on M&A for tannery asset acquisition and strategic partnerships for traceability technology deployment.
Within the luxury house tier, LVMH Moët Hennessy Louis Vuitton SE, Hermès International S.A., and Kering S.A. exemplify divergent sourcing architectures. LVMH represents full vertical integration from slaughterhouse procurement through finished goods. Hermès International S.A. anchors its position through captive French tannery operations controlling raw hide selection. Kering S.A. sits within a multi-brand pooling model that sustains margin visibility across portfolio leather demand.
| Leading Market Players |
|---|
| LVMH Moët Hennessy Louis Vuitton SE |
| Hermès International S.A. |
| Kering S.A. |
| Capri Holdings Limited |
| Prada S.p.A. |
| Tapestry Inc. |
| Adidas AG |
| American Leather Holdings LLC |
| Samsonite International S.A. |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between luxury and economy tiers manifests in divergent margin structures and procurement workflows across the value chain. Premium-grade full-grain hides command substantial markups through farm-level traceability documentation and hand-finishing protocols, while economy splits flow through standardized bulk contracts with minimal origin verification. This bifurcation reshapes both tannery investment priorities and buyer qualification thresholds.
Pricing Analysis
Margin tightening in mid-tier corrected-grain segments reflects REACH compliance cost pass-through and vegetable-tanning process premiums. Three-tier pricing structure across premium, standard, and economy levels tracks hide defect tolerance, certification depth, and finishing labor intensity. Pricing pressure stems from synthetic leather substitution in automotive upholstery programs. Furniture manufacturers exhibit highest price sensitivity, while luxury houses demonstrate inelastic demand for hand-selected farm-traceable hides.
Supply Chain Analysis
EU Green Deal domestic-content mandates for product passport traceability are reshaping sourcing toward European slaughterhouse-to-tannery linkages. Raw hide supply concentrates in France, Italy, and Germany, with intermediate processing in China and Vietnam. Wet-blue processing draws from chromium chemicals, vegetable tannins, and enzymatic agents. Single-source vulnerability sits with Italian master tanner skill scarcity. Distribution runs through direct long-term contracts for automotive and luxury segments, with wholesale aggregation serving mid-tier manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The virgin leather market functions as a vertical-integration race where control over farm-level hide selection and captive tanning capacity determines margin capture. Players are pursuing upstream control over raw material provenance as the decisive competitive lever.
For Market Incumbents: Deploy blockchain-enabled provenance verification systems to automate EU Green Deal documentation workflows and defend against synthetic leather substitution in automotive programs. Secure captive tannery capacity in Italian clusters before master tanner skill scarcity constrains luxury-grade output expansion. Reinforce position through closed-loop water system investments that maintain ECHA compliance without volume caps. For New Entrants and Emerging Players: The premium-to-economy price-point gap in North American artisan furniture upholstery offers white-space entry with certified European origin protocols. Target fragmented upholstery workshops in Tennessee and North Carolina with cut-to-specification modular panel supply. Pursue digital-first go-to-market positioning leveraging computer-vision hide grading certificates for remote procurement decisions. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier tanneries completing vegetable-tanning transitions given REACH Annex XVII chromium restriction timelines. Long-term viability favors operators with demonstrated ECHA compliance and automotive OEM qualification. Watch for inflection in EU Green Deal product passport enforcement intensity as digital documentation infrastructure deployment accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm-Level Procurement | Hermès-style captive tannery operations control raw hide selection from slaughterhouse intake. |
| Vegetable-Tanning Process Transition | Arzignano cluster investments in closed-loop systems maintain ECHA compliance without volume restrictions. |
| Blockchain Provenance Verification Deployment | Digital ledger integration automates EU Green Deal product passport documentation workflows. |
| Cut-to-Specification Contract Expansion | Modular panel systems transfer dimensional risk to tanneries while compressing buyer inventory positions. |
| North American Upholstery Market Entry | European certified-origin protocols create consolidation opportunities in fragmented Tennessee workshops. |
Research Methodology
Trade databases, tannery association publications, and customs records formed the secondary backbone for this analysis. Primary interviews with tannery operations managers, automotive upholstery procurement leads at German OEMs, luxury goods supply chain directors, and Italian cluster trade association representatives combined with secondary validation. Bottom-up hide volume modeling and top-down value chain triangulation anchored the analytical framework.
Historical trendline analysis of tanning capacity expansion, hide price indices, and regulatory compliance cost trajectories informed projection construction across the analysis window. Segmentation dimensions modeled include product type, quality grade, application sector, and distribution channel complexity. CAGRs derived from trend extrapolation adjusted for REACH regulatory phase-in schedules and automotive program ramp timelines.
Underlying measurement precision varies by segment; luxury-grade volume estimates carry tighter precision than fragmented artisan workshop data. Forecasts reflect assumptions around ECHA enforcement intensity and EU Green Deal product passport implementation pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Drain Cleaners Market
Consumer Goods
Saudi Arabia Microwave Ovens Market
Consumer Goods
Heated Razor Starter Kit Market
Consumer Goods
Germany Vegan Cosmetics Market
Consumer Goods
Diaper Bag Market
Consumer Goods
Maternity Products Market
Consumer Goods
South Korea Kitchen Appliances Market
Consumer Goods
Spain Do-It-Yourself (DIY) Home Improvement Retailing Market
Consumer Goods
Wearable Computing Devices Market
Consumer Goods
Malaysia Pet Food Market
Consumer Goods
Botanical Skin Care Ingredients Market
Consumer Goods
Germany Digital Showers Market
Consumer Goods
Phone Tripod Market
Consumer Goods
China Cookware Market
Consumer Goods
Pet Beds Market
Consumer Goods
Mountain Bike Footwear and Socks Market