
 Uzbekistan Container Glass Market | 2026-2036
Uzbekistan Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Uzbekistan Container Glass Market Insights
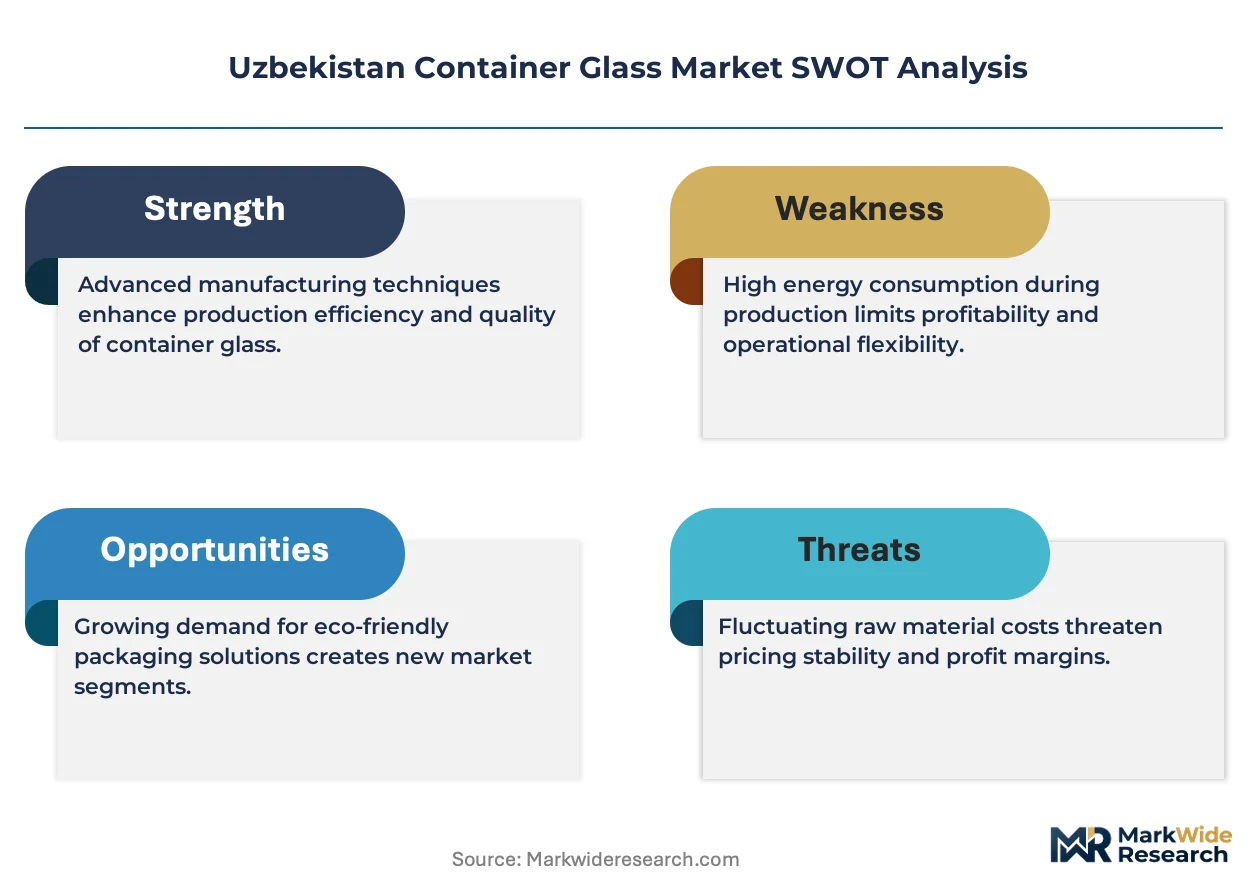
Project finance tied to industrial zone development is reconfiguring competitive entry in Uzbekistan's container glass sector, allowing mid-scale operators to secure furnace capacity without full capital ownership. Sirdaryo Universal Oyna leverages its Sirdaryo region location to anchor supply for beverage clients across Central Asia. Mingyuan Silu competes through technology leadership in lightweight bottle production. Kvarts Aksiyadorlik Jamiyati controls distribution networks linking Tashkent manufacturers to Fergana Valley processors.
Container glass comprises soda-lime silica formed through blow-and-blow or press-and-blow molding, with wall thickness typically ranging from 2.5mm to 4.5mm depending on internal pressure requirements and thermal shock specifications; its primary purpose is to store, protect, and extend shelf life of consumable and chemical products while permitting repeated sterilization and reuse. Bottles occupy the dominant volume position within product type segments, serving Uzbekistan's expanding wine and spirits bottling activity. Pharmaceutical vials represent the fastest-expanding end-use category, driven by domestic drug packaging mandates and import substitution programs for medical glass. Jars sustain stable demand from preserved food processors in Samarkand and Bukhara regions.
O'zstandart enforces GB-harmonized food-contact glass standards that dictate permissible heavy metal migration limits, while the State Committee for Ecology and Environmental Protection regulates furnace emissions and cullet recovery quotas. Compliance with these frameworks determines market access for new furnace investments and shapes product specifications for export-oriented bottlers. Stakeholders must monitor forthcoming technical regulations on pharmaceutical glass hydrolytic resistance classes and evaluate furnace rebuild cycles against evolving emission thresholds.
Market Dynamics
Project finance mechanisms tied to Uzbekistan's industrial zone development are reconfiguring furnace ownership structures, allowing mid-scale operators to secure melting capacity without full capital burden while O'zstandart's tightened food-contact rules push converters toward certified soda-lime silica formulations.
Growth Catalysts
- Domestic pharmaceutical packaging mandates:State-driven import substitution programs for medical glass are accelerating vial demand from Tashkent drug manufacturers expanding sterile fill-finish operations.
- O'zstandart GB-harmonized standards:Tighter heavy metal migration limits for food-contact materials are forcing technical upgrades that differentiate certified suppliers from informal competitors.
- Returnable bottle economics:Beverage bottlers in the Fergana Valley are scaling refillable glass orders as deposit-return infrastructure spreads across Central Asian distribution networks.
Market Restraints
- Natural gas price volatility:Furnace operations depend on Uzbekneftegas supply contracts with indexed pricing that compress margin predictability for continuous melting cycles.
- Cullet recovery infrastructure gaps:Limited formal collection systems in Samarkand and Bukhara regions constrain closed-loop raw material access for cost-competitive batch formulations.
- Hydrolytic resistance certification timelines:Pending O'zstandart technical regulations on pharmaceutical glass classes are delaying product qualification for domestic drug exporters.
Strategic Opportunities
- Karakalpakstan logistics corridor:Underdeveloped western regions offer first-mover positioning for furnace capacity serving Kazakhstan-bound beverage exports via rail links.
- Lightweight bottle technology convergence:Combining thin-wall forming with surface coating treatments enables material reduction for premium spirits packaging without strength loss.
- Industrial zone captive power:Sirdaryo region development incentives include subsidized electricity allocations that offset furnace energy intensity for qualifying investments.
Industry Challenges
- Specialized furnace engineering talent:Shortage of experienced glass technologists familiar with oxy-fuel conversion and electric boosting retrofit designs limits operational optimization.
- Emission threshold compliance capex:State Committee for Ecology mandates on particulate and NOx limits require rebuild cycles that strain mid-scale operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uzbekistan Container Glass Market |
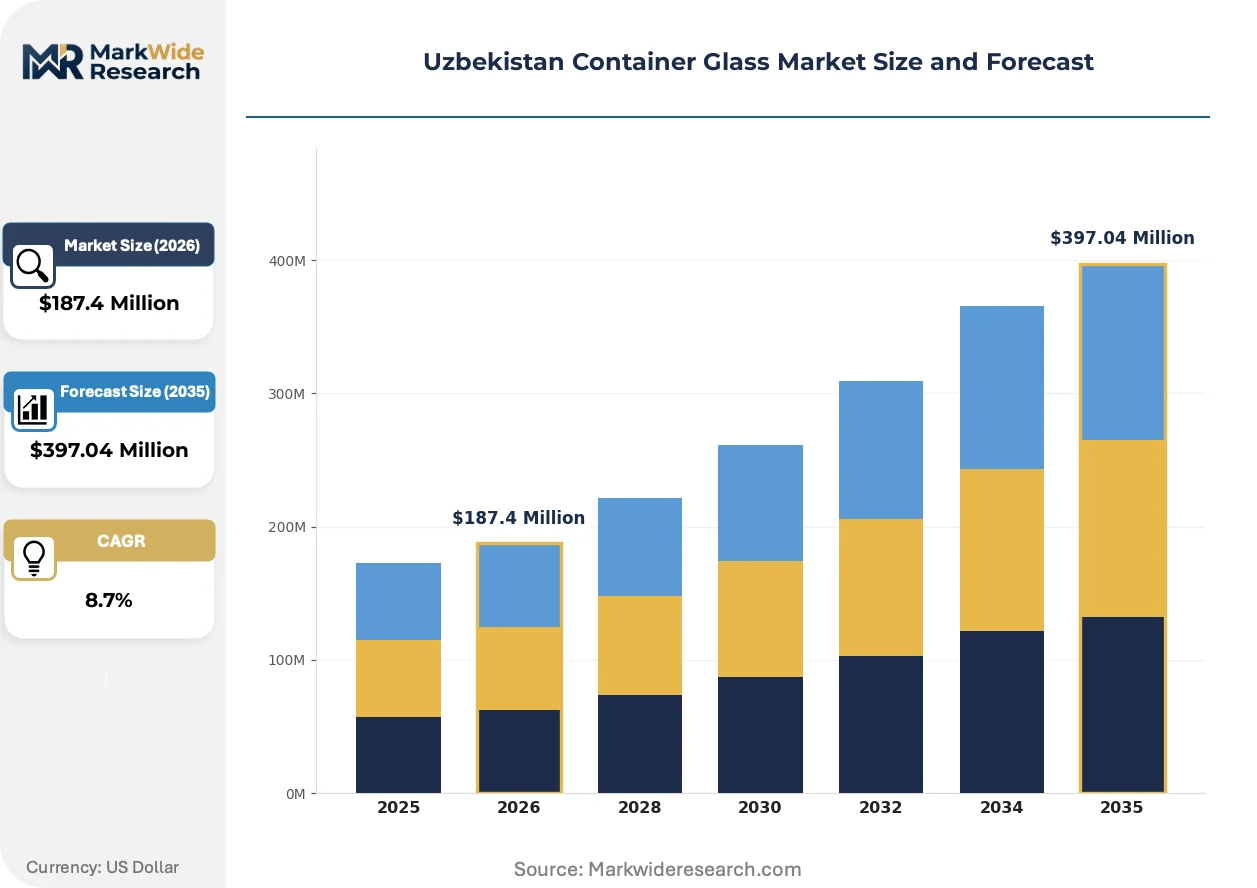
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End Use Industry: Food & Beverage, Cosmetics, Pharmaceuticals, Chemicals Capacity: 50ml, 100ml, 500ml, 1L Shape: Cylindrical, Square, Rectangular, Custom |
| Companies Covered | Sirdaryo Universal Oyna, Mingyuan Silu, ASL OYNA LLC, Campalia, Asl Oyna, IP Campalia LLC, Exclusive Glass Bottles LLC, Kvartz, Kvarts Aksiyadorlik Jamiyati, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uzbekistan Container Glass Market Trends and Innovations
Blow-and-blow forming controls, regulatory pressure on material purity, and buyer consolidation among beverage bottlers are compressing technical requirements and procurement timelines across Uzbekistan's container glass value chain.
Advanced furnace control systems using real-time temperature profiling and automated gob weight feedback are digitizing melting and forming operations. Tashkent-area pharmaceutical vial producers are adopting these platforms fastest, driven by batch consistency requirements for hydrolytic resistance certification. The technology is digitizing quality assurance workflows that previously relied on manual sampling, reducing deviation-related reject rates and accelerating O'zstandart compliance documentation.
O'zstandart's forthcoming technical regulations on pharmaceutical glass hydrolytic resistance classes are mandating upgraded material specifications. Domestic drug manufacturers must now source vials meeting USP Type I or equivalent standards to maintain export registration, forcing converters to reformulate batch compositions and extend annealing protocols. The vial segment is responding by locking in long-term supply agreements with furnace operators committing to dedicated pharmaceutical-grade production lines.
Beverage bottlers in the Fergana Valley are consolidating procurement under central purchasing agreements that specify returnable bottle technical standards and minimum order commitments. This aggregation is displacing fragmented spot-market sourcing that characterized the 2010s, compressing supplier margins while guaranteeing volume offtake for furnace operators with certified lightweight designs. The shift is most visible in wine and spirits packaging, where Tashkent-based brand owners now mandate 18-month rolling forecasts from glass partners.
Uzbekistan Container Glass Market Segmentation
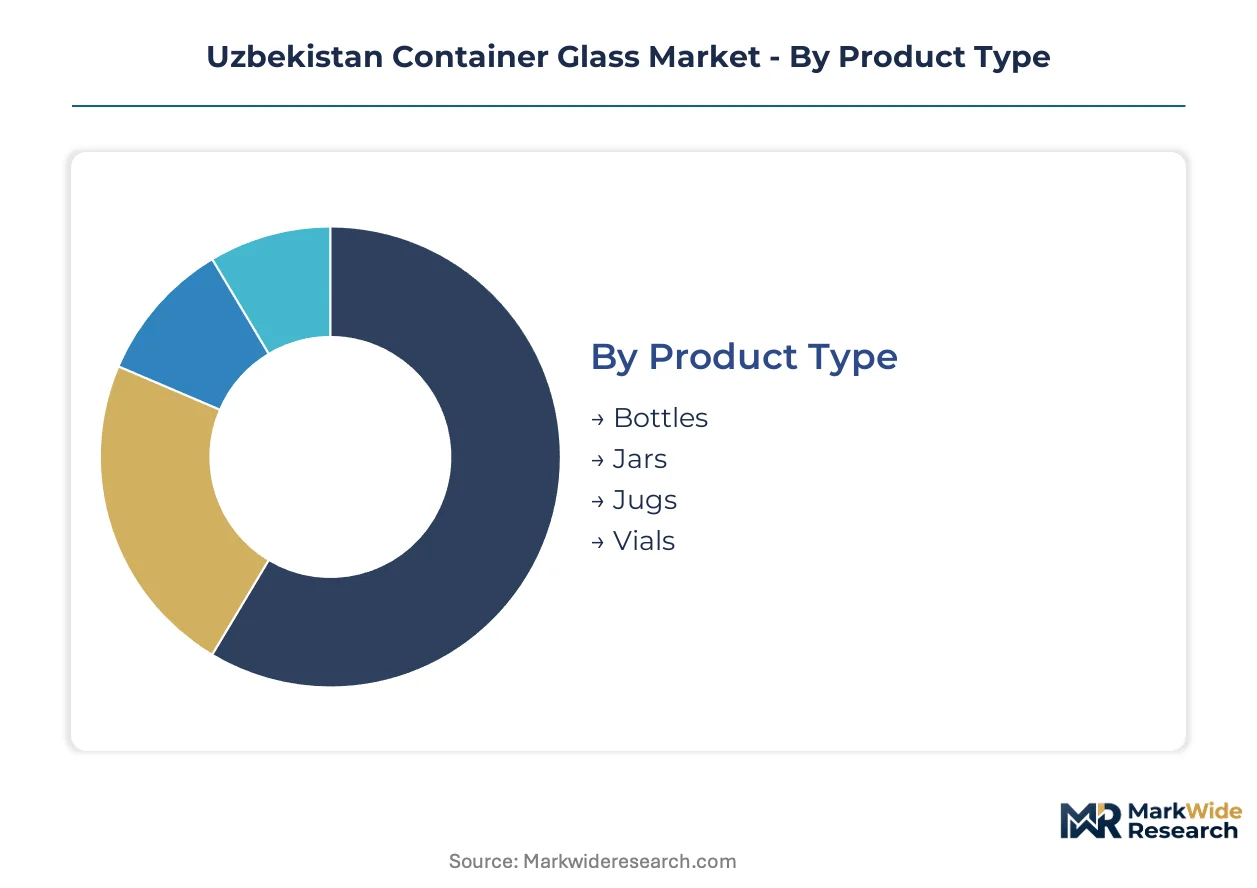
Segmentation in Uzbekistan's container glass market reveals how furnace operators allocate melting capacity across divergent technical requirements. O'zstandart certification pressures and pharmaceutical export mandates are compressing the viable supplier base for premium grades while standard beverage packaging tolerates broader sourcing.
Product Type:
Maturity varies sharply across this category, with centuries-old bottle formats contrasting against precision-engineered vial segments governed by recent pharmacopeial standards.
- Bottles:Soda-lime silica vessels formed through blow-and-blow or press-and-blow molding, with wall thickness calibrated to internal pressure and thermal shock specifications. Demand concentrates in Tashkent and Fergana Valley beverage bottling operations where returnable formats are displacing single-use alternatives under deposit-return infrastructure expansion.
- Vials:Small-volume containers requiring hydrolytic resistance certification under pending O'zstandart technical regulations aligned with USP Type I standards. Domestic drug manufacturers in Tashkent expanding sterile fill-finish capacity are locking in dedicated pharmaceutical-grade production lines through long-term supply agreements.
- Jars:Wide-mouth containers serving preserved food processors in Samarkand and Bukhara regions with stable, non-cyclical demand patterns.
- Jugs:Large-format vessels for bulk liquid storage with limited domestic furnace specialization, often imported from Kazakh or Russian suppliers.
Bottles retain volume leadership; vials hold the steepest expansion curve.
End Use Industry:
Application-driven cost tiers separate commodity beverage contracts from premium pharmaceutical supply relationships with divergent margin structures.
- Food & Beverage:The foundational demand pool encompassing wine, spirits, and non-alcoholic bottling across Central Asian distribution networks. Fergana Valley beverage producers are consolidating procurement under central purchasing agreements that mandate 18-month rolling forecasts and certified lightweight designs.
- Pharmaceuticals:Medical glass governed by import substitution programs and export registration requirements. State-driven mandates for domestic drug packaging are accelerating vial demand as manufacturers must source USP-equivalent materials to maintain market access.
- Cosmetics:Premium fragrance and skincare packaging requiring aesthetic surface finishes and precise dimensional tolerances.
- Chemicals:Industrial containers for reagents and solvents with specialized resistance requirements outside standard soda-lime formulations.
Food & Beverage commands the largest furnace allocation; Pharmaceuticals is climbing the fastest.
Capacity:
Volume scale determines batch economics and furnace scheduling efficiency, with mid-range formats offering optimal melting cost absorption.
- 500ml:The workhorse format for beverage bottling across wine and spirits categories, balancing material efficiency with handling practicality. Fergana Valley producers favor this capacity for returnable bottle programs where washing and refill cycles maximize packaging economics.
- 1L:Standard large-format for bulk beverage and food service applications with stable demand from regional distributors.
- 100ml:Compact format for single-serve beverages and cosmetic samples with growing adoption in premium positioning strategies.
- 50ml:Miniature vessels for pharmaceutical dosing and travel-size cosmetics requiring precision forming controls.
500ml maintains production dominance; 100ml is gaining share fastest.
Shape:
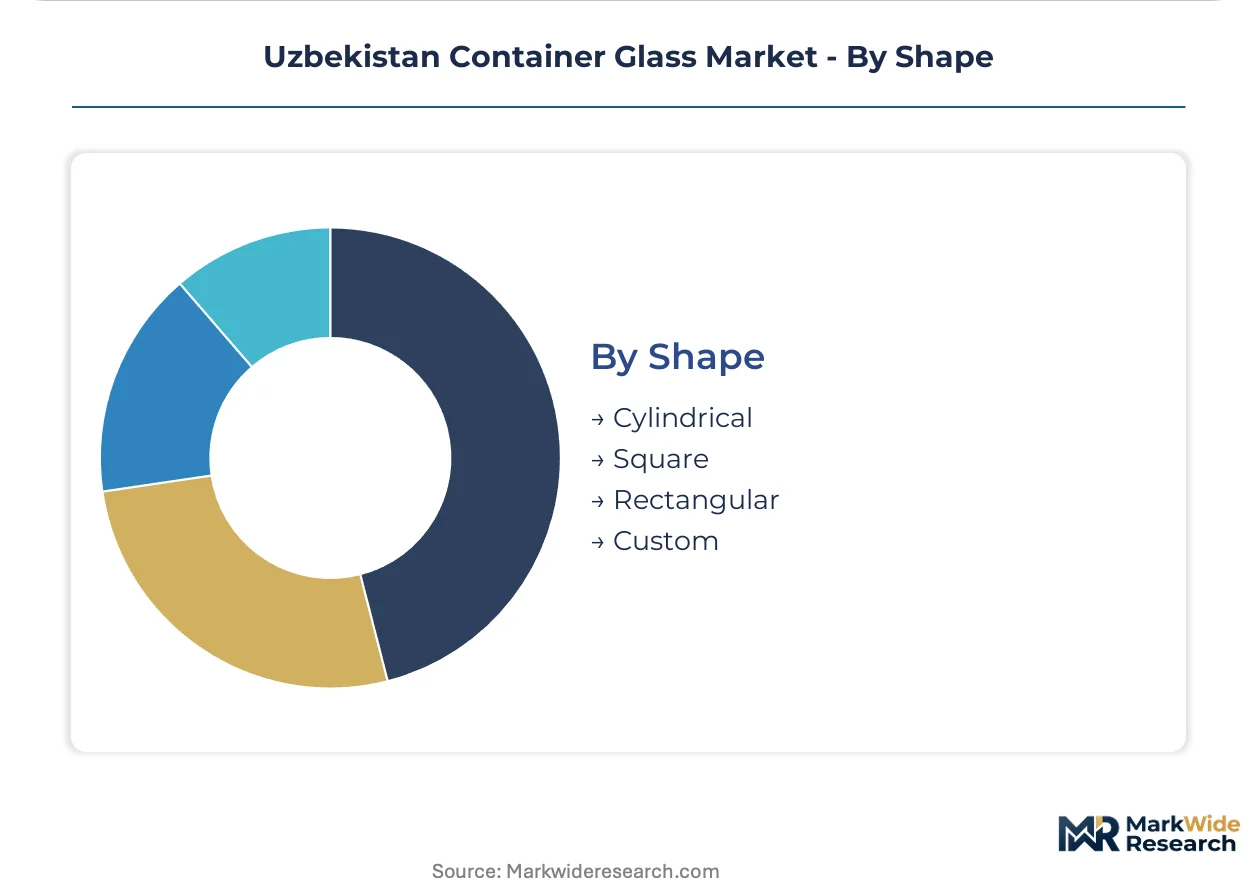
Supply concentration favors cylindrical geometries where tooling amortization and forming efficiency maximize furnace throughput.
- Cylindrical:The default geometry for high-volume beverage and pharmaceutical production, optimized for uniform wall distribution and label adhesion. Tashkent-area furnaces dedicate continuous production lines to this format given its compatibility with automated inspection and filling systems.
- Square:Space-efficient stacking format for warehousing and retail shelf density, common in spirits and chemical applications.
- Rectangular:Specialized containers for preserved foods and cosmetics where flat panel surfaces accommodate decorative treatments.
- Custom:Proprietary molds for brand differentiation in premium spirits and gift packaging with longer lead times and higher tooling investment.
Cylindrical retains volume leadership; Custom holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Uzbekistan's container glass trade flows are tilting toward net export positioning as Sirdaryo-region furnace capacity expands to serve Kazakhstan and Kyrgyzstan beverage bottlers. Import dependency persists only for specialized pharmaceutical-grade vials and premium cosmetic containers.
Tashkent Region
Pharmaceutical vial demand from domestic drug manufacturers expanding sterile fill-finish operations anchors melting capacity allocation. O'zstandart's pending hydrolytic resistance regulations are accelerating technical upgrades among Tashkent-area converters. The capital's industrial zones concentrate furnace investments tied to project finance mechanisms that reduce capital barriers for mid-scale operators.
Fergana Valley
Beverage bottlers across Namangan and Fergana provinces are scaling returnable glass orders under deposit-return infrastructure expansion. Central purchasing agreements now mandate 18-month rolling forecasts and certified lightweight designs from glass partners. Sirdaryo Universal Oyna leverages rail connectivity to anchor supply contracts across this eastern cluster.
Sirdaryo Region
Industrial zone development incentives include subsidized electricity allocations that offset furnace energy intensity for qualifying investments. Natural gas supply contracts with Uzbekneftegas underpin continuous melting operations, though indexed pricing compresses margin predictability. Captive power arrangements are attracting furnace operators seeking cost-competitive batch economics.
Samarkand and Bukhara
Preserved food processors sustain stable jar demand with non-cyclical procurement patterns. Cullet recovery infrastructure gaps constrain closed-loop raw material access, forcing reliance on virgin batch formulations. Regional distribution networks link these southern processors to Tashkent-based furnace operators.
Karakalpakstan
Underdeveloped western regions offer first-mover positioning for furnace capacity serving Kazakhstan-bound beverage exports via rail links. Limited existing glass infrastructure creates greenfield opportunities for operators securing industrial zone concessions. Logistics corridor development is prioritizing cross-border rail connectivity to Aktobe and Atyrau markets.
Uzbekistan Container Glass Market Competitive Landscape
On the supply side, the industry is consolidating around furnace operators with certified pharmaceutical-grade production lines and industrial zone project finance access. Mid-scale converters without O'zstandart food-contact certification face displacement as beverage bottlers centralize procurement. Three archetypes dominate: regionally anchored furnace operators with logistics advantages, technology-focused lightweight bottle specialists, and distribution-network controllers linking production clusters. Competitive moves center on long-term supply agreement lock-ins with pharmaceutical manufacturers and industrial zone capacity expansion leveraging subsidized power allocations.
Among Uzbekistan-based furnace operators, Sirdaryo Universal Oyna exemplifies the regionally anchored archetype through its Sirdaryo location and cross-border supply positioning. Mingyuan Silu occupies the technology-focused tier, representing lightweight bottle production capabilities. Kvarts Aksiyadorlik Jamiyati anchors the distribution-network controller archetype, linking Tashkent manufacturers to Fergana Valley processors through established logistics relationships. These three operators illustrate how competitive positioning stratifies across geographic anchoring, technical specialization, and supply chain control.
| Leading Market Players |
|---|
| Sirdaryo Universal Oyna |
| Mingyuan Silu |
| ASL OYNA LLC |
| Campalia |
| Asl Oyna |
| IP Campalia LLC |
| Exclusive Glass Bottles LLC |
| Kvartz |
| Kvarts Aksiyadorlik Jamiyati |
| Others |
Pricing and Supply Chain Analysis
Uzbekneftegas natural gas contracts with indexed pricing anchor furnace operating costs, concentrating margin pools with converters securing subsidized electricity allocations through Sirdaryo industrial zone concessions. Beverage bottlers in the Fergana Valley extract volume discounts through central purchasing agreements while pharmaceutical manufacturers absorb premium pricing for hydrolytic resistance-certified vials.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate Uzbekistan's container glass procurement. Price differentiation separates USP Type I pharmaceutical-grade vials from standard beverage bottles, with certification tier and volume scale as primary drivers. Cost compression in standard beverage packaging intensifies as Fergana Valley bottlers consolidate procurement under 18-month rolling forecasts. Small-scale preserved food processors in Samarkand exhibit highest price sensitivity, while Tashkent drug manufacturers expanding sterile fill-finish operations show lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Silica sand deposits in Kazakhstan and Uzbekistan, combined with soda ash from Russia, feed furnace batch formulations across the region. Raw material dependencies center on natural gas from Uzbekneftegas, imported boron compounds for thermal shock resistance, and virgin cullet where formal collection systems remain underdeveloped. Single-source vulnerability in pharmaceutical-grade tubing imports constrains domestic vial production expansion. Distribution runs through rail-linked industrial zones serving Kazakhstan-bound beverage exports and regional trucking networks linking Tashkent furnaces to Fergana Valley bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in furnace rebuild engineering and O'zstandart compliance consulting expand faster than base container sales, as emission threshold upgrades and hydrolytic resistance certification create recurring technical advisory demand.
For Market Incumbents: Entrench market position by locking dedicated pharmaceutical-grade production lines through long-term supply agreements with Tashkent drug manufacturers facing USP-equivalent export mandates. Secure backward integration into captive cullet recovery infrastructure to offset virgin batch cost volatility from Uzbekneftegas indexed contracts. Oxy-fuel conversion engineering capabilities represent the critical defensive lever against mid-scale competitors accessing project finance mechanisms. For New Entrants and Emerging Players: Karakalpakstan's underdeveloped western corridor represents the most penetrable entry point for furnace capacity serving Kazakhstan-bound beverage exports via cross-border rail links to Aktobe and Atyrau markets. Lightweight bottle technology specialization offers differentiation against established Sirdaryo-region operators. Go-to-market execution should leverage industrial zone subsidized electricity allocations to undercut incumbent batch economics. For Investors and Strategic Acquirers: Capital is best deployed toward furnace operators with certified pharmaceutical-grade production lines and established O'zstandart compliance documentation, positioned for import substitution program tailwinds. Long-term viability hinges on exposure to domestic drug packaging mandates rather than commodity beverage contract exposure. Watch for O'zstandart finalization of hydrolytic resistance technical regulations as inflection signal accelerating vial demand qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks dedicated pharmaceutical-grade capacity with Tashkent drug manufacturers expanding sterile operations. |
| Backward Integration | Cullet recovery infrastructure in Samarkand reduces virgin batch dependence and Uzbekneftegas price exposure. |
| Capacity Expansion | Sirdaryo industrial zone furnace additions capture subsidized electricity and Kazakhstan export demand. |
| Technology Licensing | Lightweight bottle forming transfers from Mingyuan Silu to regional converters seeking Fergana contracts. |
| Joint Venture | Karakalpakstan greenfield partnerships with Kazakh distributors secure cross-border rail corridor access. |
Research Methodology
Cross-validation between primary interviews with furnace operators, beverage procurement directors, and pharmaceutical packaging managers and secondary validation through O'zstandart technical regulation drafts, Uzbekneftegas supply contract structures, and industrial zone development disclosures anchors the qualitative findings. Bottom-up and top-down triangulation reconciles furnace capacity utilization rates with end-use demand aggregation across Tashkent pharmaceutical clusters and Fergana Valley bottling operations.
Calibration against historical furnace investment cycles and natural gas price volatility patterns shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, capacity format, and regional production cluster. CAGRs derive from melt tonnage growth trajectories, batch cost inflation assumptions, and export penetration scenarios for Kazakhstan-bound beverage packaging.
Practitioners should monitor O'zstandart regulatory finalization timelines and Uzbekneftegas contract renegotiation windows for early signals of forecast revision. Quarterly review of furnace rebuild completion rates and pharmaceutical vial qualification backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Angola Container Glass Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
United States Glass Packaging Market
Glass Packaging
Egypt Container Glass Market
Glass Packaging
Spain Container Glass Market
Glass Packaging
Mexico Container Glass Market
Glass Packaging
United Kingdom Container Glass Market
Glass Packaging
Russia Glass Packaging Market
Glass Packaging
Asia Pacific Glass Packaging Market
Glass Packaging
Guatemala Container Glass Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
Bangladesh Container Glass Market
Glass Packaging
Colombia Container Glass Market
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
Mason Jars Market
Glass Packaging
Thailand Container Glass Market