
 US Sustainable Mattress Market | 2026-2036
US Sustainable Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
US Sustainable Mattress Market Insights
EPA regulations on volatile organic compound emissions from polyurethane foams is expanding the compliance burden for conventional mattress manufacturers. Tempur Sealy International, Inc. anchors its competitive stance through in-house visco-elastic foam production facilities in the Southeast. Avocado Mattress differentiates via GOTS-certified organic supply chains that bypass petrochemical inputs entirely. Naturepedic specializes in pediatric and medical-grade organic mattresses, commanding premium positioning through third-party chemical-free certifications.
A sustainable mattress combines certified organic or recycled inputs—such as GOTS-verified cotton, natural latex harvested from Hevea brasiliensis plantations, or soy-based polyurethane alternatives—with manufacturing processes that eliminate toxic adhesives and flame retardants. Its primary commercial purpose is to reduce indoor air contaminants while meeting durability standards for residential and institutional sleep environments. Latex Foam and Hybrid categories lead current production volume, with Hybrid configurations capturing margin pools by blending coil support systems with organic comfort layers. The Direct-to-Consumer channel sustains the fastest expansion, compressing traditional retail markups while enabling transparent material sourcing narratives.
The Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1633, pushing manufacturers toward wool and cellulose barrier technologies that satisfy open-flame tests without halogenated chemicals. USDA BioPreferred labeling and FTC Green Guides further shape marketing claims and federal procurement preferences for biobased content. Stakeholders must monitor state-level extended producer responsibility legislation in California, Oregon, and Washington that could mandate mattress recycling infrastructure and alter end-of-life cost structures.
Market Dynamics
The EPA's emerging framework on volatile organic compound emissions from polyurethane foams is forcing immediate reformulation across domestic manufacturing. This regulatory pressure is compressing the viability window for petrochemical-based comfort layers while accelerating plant-based alternative adoption.
Growth Catalysts
- California hospitality procurement mandates:Chains in the Pacific Northwest are expanding certified organic sleep surface requirements into standard RFP templates.
- 16 CFR Part 1633 compliance pathways:The CPSC flammability standard is pushing manufacturers toward wool and cellulose barrier technologies that satisfy open-flame tests without halogenated chemicals.
- Texas green building integration:New residential construction in metropolitan corridors is embedding sustainable mattress specifications into LEED and similar certification workflows.
Market Restraints
- Natural latex supply concentration:Hevea brasiliensis plantation output concentrates in Southeast Asian geographies exposed to climate volatility and logistics disruption.
- GOTS certification cost structure:Third-party organic verification imposes multi-year compliance timelines and recurring audit expenses that disadvantage smaller domestic manufacturers.
- Soy-based polyurethane technical limitations:Current biopolymer formulations exhibit durability gaps versus conventional visco-elastic foams in high-humidity sleep environments.
Strategic Opportunities
- Pediatric medical-grade expansion:Third-party chemical-free certifications for infant sleep surfaces command substantial premium positioning in hospital and childcare procurement.
- Extended producer responsibility tailwinds:California, Oregon, and Washington are advancing mattress recycling infrastructure mandates that favor domestic producers with established take-back capabilities.
- Direct-to-consumer channel innovation:Compressed-ship mattress platforms are collapsing traditional retail markups while enabling transparent material sourcing narratives for millennial and Gen Z buyers.
Industry Challenges
- Reformulation capex intensity:Plant-based foam R&D and production line retooling demands substantial capital deployment during a compressed regulatory compliance window.
- Multi-certification timeline compression:Simultaneous pursuit of GOTS, USDA BioPreferred, and state-level green procurement qualifications strains quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Sustainable Mattress Market |
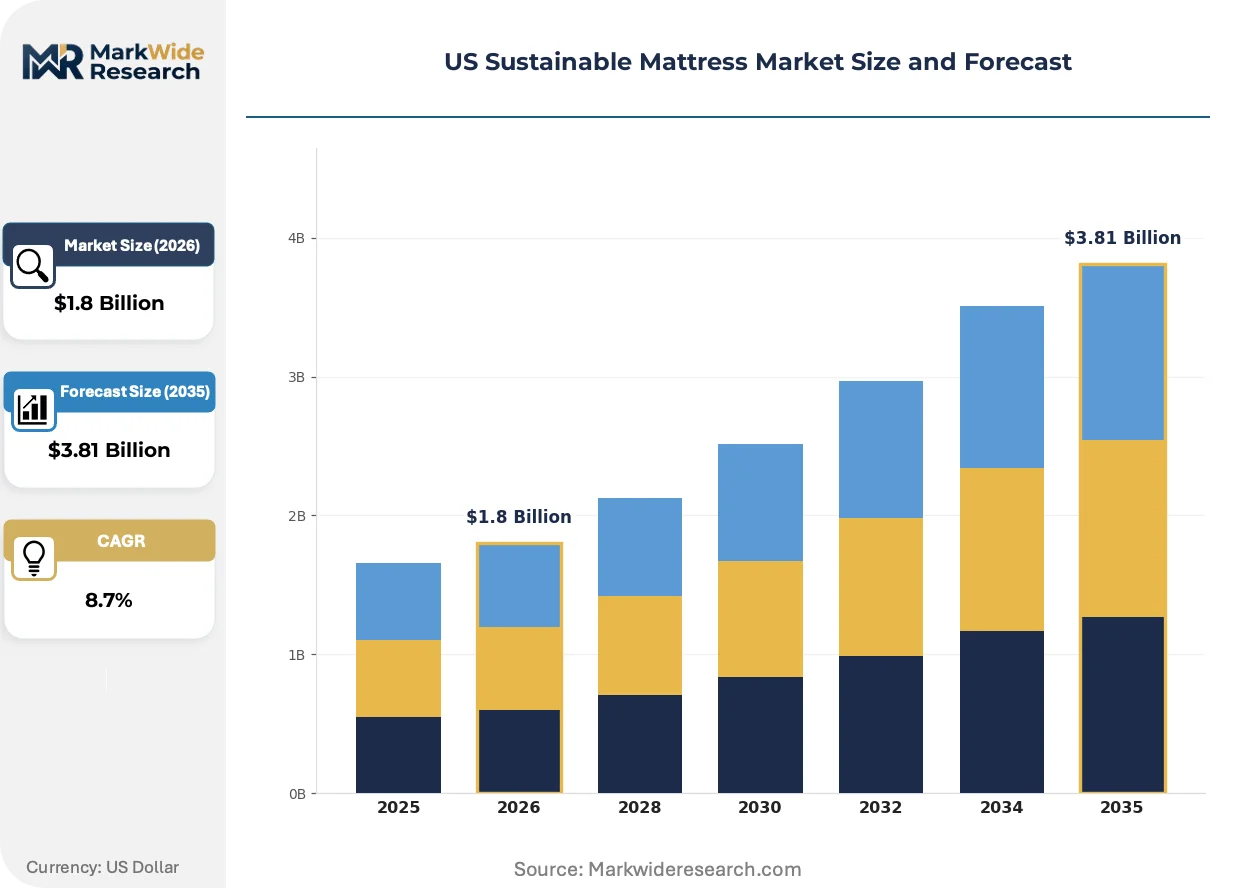
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Cotton, Latex Foam, Memory Foam, Hybrid End User: Residential, Hotels, Health Facilities, Educational Institutions Distribution Channel: Online Retail, Furniture Stores, Specialty Stores, Direct-to-Consumer Manufacturing Stage: Raw Material Sourcing, Production, Quality Testing, Packaging |
| Companies Covered | Serta Simmons Bedding, LLC, Tempur Sealy International, Inc., Sleep Number Corporation, The Natural Sleep Store, Kingsdown, Inc., Avocado Mattress, Naturepedic, Magnolia Organics, Helix Sleep, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Sustainable Mattress Market Trends and Innovations
Reformulation chemistry is actively displacing incumbent petrochemical inputs across the domestic mattress supply base. Three distinct vectors are compressing traditional manufacturing economics while opening premium positioning pathways.
Hybrid coil-organic comfort layer configurations are integrating natural latex harvested from certified plantations with recycled steel support systems. Hospitality buyers in California and the Pacific Northwest are specifying these configurations at accelerating rates. This architecture is integrating premium margin capture with compliance pre-positioning against forthcoming EPA volatile organic compound restrictions.
The EPA's developing polyurethane foam emissions framework is compressing reformulation timelines for domestic manufacturers. Industrial consequence includes accelerated pilot programs for soy-based and algae-derived polyol alternatives. Texas and California production facilities are most affected, with larger operators absorbing compliance costs through captive R&D while smaller competitors face outsourcing or exit pressures.
Certification-driven preference rotation is restructuring residential purchase journeys. Buyers now initiate searches with GOTS or OEKO-TEX queries rather than brand or price parameters. Direct-to-consumer platforms are capturing this traffic through searchable certification filters and material traceability tools, compressing traditional retail intermediary roles most visibly in Austin, Dallas, and Seattle metropolitan markets.
US Sustainable Mattress Market Segmentation
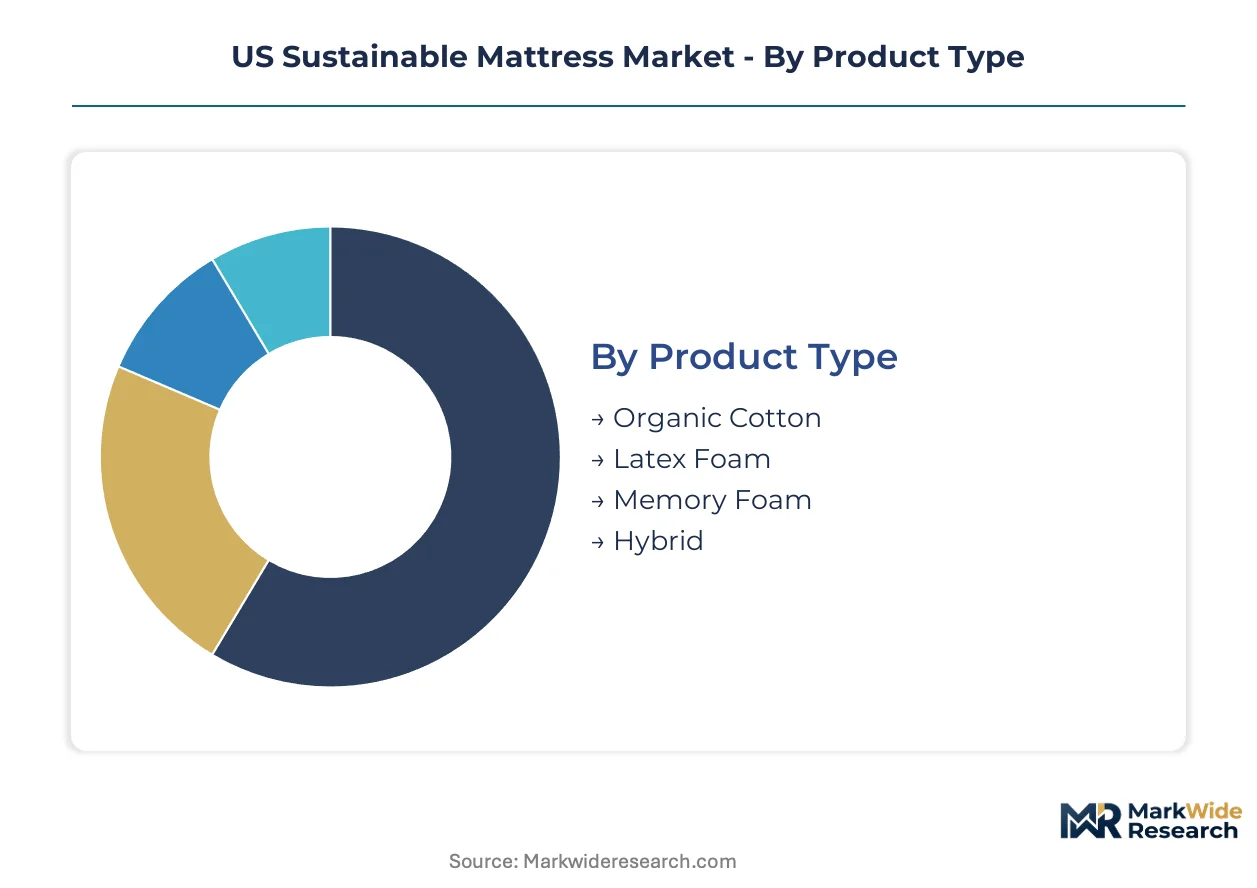
Segmentation in the US sustainable mattress market reveals how certification requirements, procurement channels, and manufacturing complexity create distinct competitive arenas. Each dimension carries different margin structures and regulatory exposure.
Product Type:
Volume concentrates in plant-based comfort layers while premium capture shifts toward certified organic configurations with traceable supply chains.
- Latex Foam:Harvested from Hevea brasiliensis plantations and processed into Dunlop or Talalay configurations. Texas and California hospitality procurement specifies this category for durability in high-occupancy environments, though Southeast Asian supply concentration exposes buyers to climate volatility.
- Hybrid:Integrates recycled steel coil support systems with organic cotton, wool, or natural latex comfort layers. California and Pacific Northwest hotel chains are expanding RFP requirements for this architecture to satisfy green building standards while maintaining pressure relief performance.
- Organic Cotton:GOTS-certified fiber fills gaining traction in pediatric and budget-conscious residential segments.
- Memory Foam:Plant-based polyol alternatives displacing petrochemical formulations under EPA emissions pressure.
Today's leader: Hybrid. Tomorrow's challenger: Latex Foam.
End User:
Procurement authority separates fragmented residential decision-making from institutional buyers with mandated sustainability criteria.
- Residential:Individual purchasers navigating certification complexity through direct-to-consumer platforms with searchable GOTS filters. Austin, Dallas, and Seattle metropolitan corridors show concentrated demand for transparent material sourcing.
- Hotels:California hospitality chains embedding certified organic sleep surface requirements into standard procurement templates, with Pacific Northwest properties following.
- Health Facilities:Pediatric and medical-grade specifications commanding premium positioning through third-party chemical-free certifications.
- Educational Institutions:University housing procurement increasingly referencing LEED and similar green building workflows for dormitory furnishings.
Institutional buyers currently dominate volume; residential channels are expanding most quickly through compressed-ship platforms.
Distribution Channel:
Margin compression and transparency demands are restructuring how buyers access certified products.
- Direct-to-Consumer:Compressed-ship mattress platforms collapsing traditional retail markups while enabling material traceability tools for millennial and Gen Z purchasers.
- Online Retail:Third-party marketplaces capturing certification-driven search traffic with filterable organic and recycled content parameters.
- Specialty Stores:Brick-and-mortar showrooms emphasizing tactile evaluation of natural latex and organic cotton configurations.
- Furniture Stores:Generalist retailers adding sustainable SKUs to capture ancillary mattress purchases.
Direct-to-Consumer holds current growth leadership; Specialty Stores retain premium positioning power.
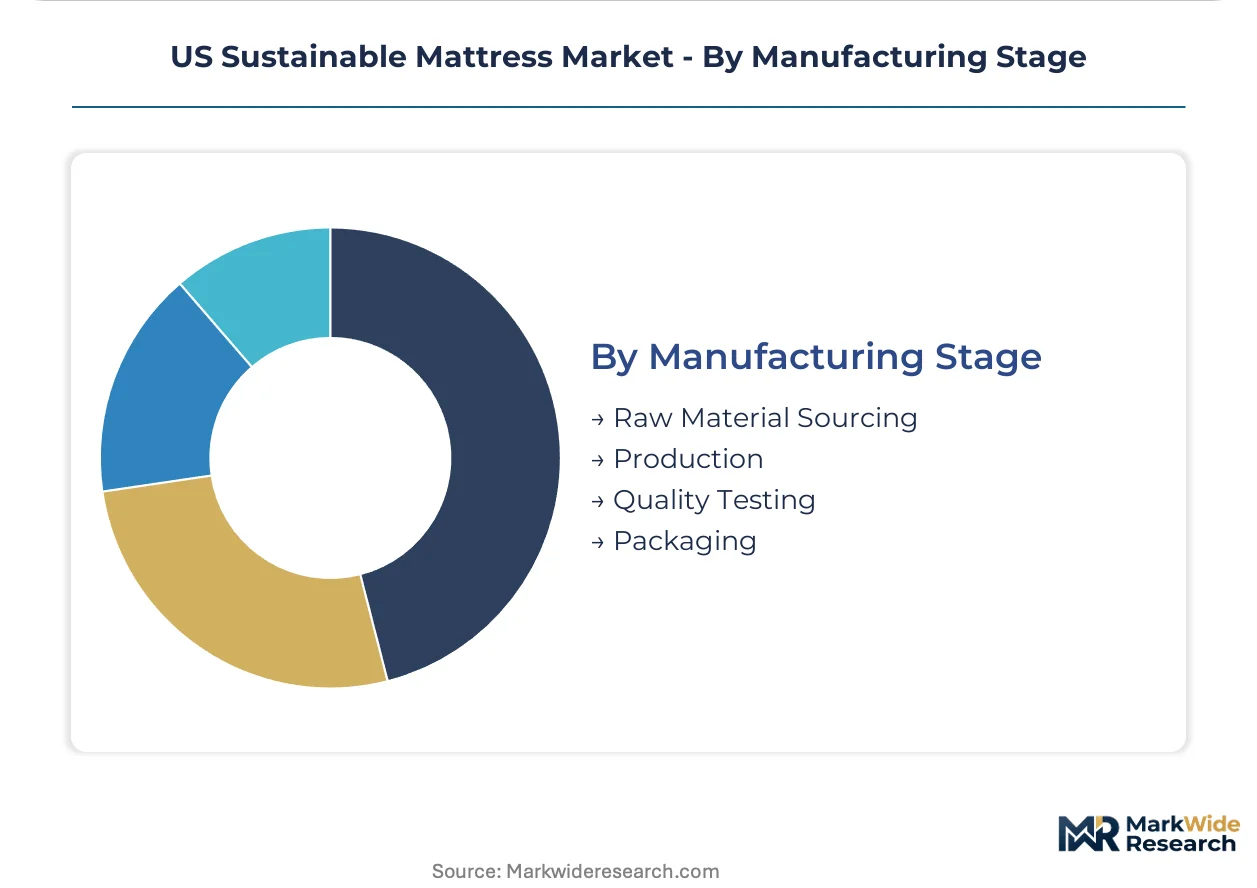
Manufacturing Stage:
Regulatory pressure concentrates competitive advantage in upstream control over certified inputs and reformulation capabilities.
- Raw Material Sourcing:GOTS-certified organic cotton and FSC-certified latex plantations require multi-year supplier relationships and audit compliance.
- Production:Plant-based foam R&D and retooling demands substantial capital deployment during compressed EPA compliance windows.
- Quality Testing:16 CFR Part 1633 flammability validation using wool and cellulose barriers without halogenated chemicals.
- Packaging:Compressed-roll logistics enabling direct-to-consumer fulfillment while reducing shipping emissions.
Raw Material Sourcing determines current margin capture; Production capabilities represent the steepest expansion trajectory as reformulation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized manufacturing talent clusters across domestic production zones anchor sustainable mattress capacity expansion. Regional regulatory divergence and procurement mandates are fragmenting competitive positioning across state boundaries.
California
Los Angeles and San Francisco hospitality procurement teams mandate GOTS-certified organic sleep surfaces in standard RFP templates. The California Department of Public Health enforces Proposition 65 disclosure requirements for chemical flame retardants. San Diego manufacturing facilities pilot algae-derived polyol alternatives under compressed EPA compliance timelines.
Texas
Austin and Dallas metropolitan corridors embed sustainable mattress specifications into LEED-certified residential construction workflows. The Texas Commission on Environmental Quality monitors volatile organic compound emissions from polyurethane foam production. Houston-area manufacturing plants absorb reformulation capex through captive R&D investments.
Pacific Northwest
Seattle and Portland hospitality chains extend California-style organic procurement requirements into Pacific Northwest properties. Oregon and Washington extended producer responsibility legislation advances mattress recycling infrastructure mandates. Portland production facilities develop take-back logistics capabilities for anticipated regulatory compliance.
Southeast
Atlanta and Charlotte distribution hubs serve compressed-ship direct-to-consumer platforms targeting millennial buyers. Georgia and North Carolina environmental regulators align with emerging federal volatile organic compound frameworks. North Carolina manufacturing clusters leverage in-house visco-elastic foam production for reformulation flexibility.
Mountain West
Denver and Phoenix residential markets concentrate demand for transparent material sourcing through online certification filters. Colorado and Arizona green building codes reference sustainable mattress specifications in multi-family housing standards. Denver specialty retail showrooms emphasize tactile evaluation of natural latex configurations.
US Sustainable Mattress Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: legacy bedding conglomerates with captive foam production, certified organic specialists with GOTS-verified supply chains, and direct-to-consumer platforms with compressed-ship logistics. Dominant competitive moves include strategic partnerships for raw material security and portfolio diversification into pediatric medical-grade segments.
Among legacy bedding conglomerates, Serta Simmons Bedding, LLC and Tempur Sealy International, Inc. occupy positions anchored by in-house manufacturing scale and reformulation R&D capacity. Avocado Mattress and Naturepedic exemplify the certified organic specialist archetype, bypassing petrochemical inputs through third-party verified supply chains. These companies represent alternative competitive vectors as EPA emissions frameworks compress conventional manufacturing viability windows.
| Leading Market Players |
|---|
| Serta Simmons Bedding, LLC |
| Tempur Sealy International, Inc. |
| Sleep Number Corporation |
| The Natural Sleep Store |
| Kingsdown, Inc. |
| Avocado Mattress |
| Naturepedic |
| Magnolia Organics |
| Helix Sleep |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up mattress specialists anchor supply discipline through centralized procurement consortia while enforcing pricing floors across branded portfolios. This ownership pattern compresses cost pass-through flexibility for independent domestic manufacturers facing simultaneous reformulation capex demands and GOTS certification timelines.
Pricing Analysis
Bundled white-glove delivery and installation services separate premium hybrid configurations from compressed-ship direct-to-consumer alternatives that unbox at residential endpoints. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and natural latex content percentage. Pricing pressure stems from EPA-mandated foam reformulation capex absorbing margin pools at mid-market manufacturers. Residential buyers in Texas metropolitan corridors exhibit highest price sensitivity through searchable certification filters, while California hospitality procurement shows lowest sensitivity due to mandated organic RFP requirements.
Supply Chain Analysis
Natural latex supply rests on Hevea brasiliensis plantation output concentrated in Thailand, Indonesia, and Vietnam. Domestic manufacturers draw from Southeast Asian latex processors, GOTS-certified organic cotton suppliers in India and Turkey, and soy-based polyol feedstock from Midwestern agricultural processors. Single-source vulnerability concentrates in Talalay latex production where three Malaysian facilities supply North American hybrid manufacturers. Distribution runs through compressed-roll logistics networks anchored in Atlanta and Charlotte distribution hubs serving direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US sustainable mattress market compounds steadily as regulatory compliance mandates permanently expand addressable demand beyond voluntary green purchasing. EPA emissions frameworks and state-level extended producer responsibility legislation create durable tailwinds institutionalizing sustainable procurement.
For Market Incumbents: To counter margin compression from simultaneous reformulation capex and multi-certification timelines, Serta Simmons and Tempur Sealy should deepen backward integration into captive visco-elastic foam production while accelerating GOTS pre-certification of Southeast Asian latex supplier networks. Vertical control over plant-based polyol R&D preserves pricing power as smaller competitors face outsourcing or exit pressures. For New Entrants and Emerging Players: Enter via pediatric medical-grade segments where third-party chemical-free certifications command substantial premium positioning in hospital and childcare procurement. White-space concentrates in Pacific Northwest hospitality properties extending California-style organic mandates, with compressed-ship logistics enabling transparent material sourcing narratives for millennial buyers seeking searchable GOTS filters. For Investors and Strategic Acquirers: Bedding conglomerates with captive manufacturing and established take-back logistics represent the most active acquirer category in this space. Long-term viability favors targets with demonstrated EPA reformulation execution and California recycling infrastructure pre-positioning. The signal to watch is Oregon and Washington extended producer responsibility implementation timelines as inflection indicators for domestic consolidation activity.| Strategic Initiative | Industry Significance |
|---|---|
| GOTS Certification Acceleration | Third-party organic verification opens California hospitality procurement and federal BioPreferred channels. |
| Plant-Based Foam Reformulation | EPA emissions compliance preserves manufacturing licensure while displacing petrochemical input costs. |
| Take-Back Logistics Development | California, Oregon, and Washington EPR mandates favor producers with established mattress recycling infrastructure. |
| Pediatric Medical-Grade Expansion | Hospital and childcare procurement specifications command premium positioning through chemical-free certifications. |
| Compressed-Ship Platform Scale | Direct-to-consumer logistics collapse traditional retail markups while enabling transparent material sourcing narratives. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with mattress manufacturing executives, hospitality procurement directors, sustainability certification auditors, and direct-to-consumer platform operators with secondary validation. Secondary sources included EPA regulatory filings, CPSC flammability standard documentation, GOTS certification databases, and state-level extended producer responsibility legislative records. Bottom-up demand modeling across residential, hospitality, and institutional segments triangulated against top-down supply capacity assessments.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling across product architecture, end-user procurement authority, and distribution channel economics. CAGRs derived from regression analysis of certified organic input cost trajectories, green building standard adoption curves, and compressed-ship logistics penetration rates. Forecast inputs incorporated EPA reformulation timeline assumptions and state-level mattress recycling mandate implementation schedules.
The model holds under sustained regulatory enforcement of volatile organic compound emissions frameworks; deviation in EPA rulemaking delays or GOTS certification backlog expansion would shift manufacturer compliance cost profiles. Forecasts reflect assumptions regarding Southeast Asian latex supply stability and Midwestern soy-based polyol scale-up execution. A small set of named triggers—California hospitality mandate expansion, Oregon EPR implementation acceleration, and natural latex climate volatility—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Shoe Shine Machine Market
Consumer Goods
Duck Boots Market
Consumer Goods
Reusable Sanitary Pads Market
Consumer Goods
Charcoal Bristle Toothbrush Market
Consumer Goods
Global Pet Companion Robots Market
Consumer Goods
USA Bird Food Market
Consumer Goods
Europe Cigarette Vending Machine Market
Consumer Goods
Baby Care and Mother Care Market
Consumer Goods
Saudi Arabia Microwave Ovens Market
Consumer Goods
Baby Bottle Holder Market
Consumer Goods
Smart/AI Toys Market
Consumer Goods
Australia Washing Machine Market
Consumer Goods
Trolley Bags Market
Consumer Goods
Israel Home Needs Appliances Market
Consumer Goods
Mosquito Repellent Candles Market
Consumer Goods
Sports Apparel Market