
 US Real Estate Software Market | 2026-2036
US Real Estate Software Market Size, Share, and Industry Trends Forecast 2026-2036
US Real Estate Software Market Insights
SOC 2 Type II certification is collapsing as a meaningful barrier between mid-tier vendors and enterprise property managers. Yardi Systems sustains dominance through captive development of vertically integrated accounting and maintenance modules. RealPage competes aggressively on pricing for student housing and affordable property segments. CoStar Group leverages its data monopoly in commercial listings to cross-sell analytics subscriptions.
US real estate software encompasses cloud-native and on-premises platforms that automate property operations, financial reporting, tenant communications, and regulatory compliance through API-connected databases and workflow engines. These systems process rent rolls, lease abstracts, and capital improvement schedules into actionable dashboards for asset-level decision-making. Property management software anchors the largest revenue pool, while CRM solutions for agent lead routing represent the fastest-expanding segment as brokerages consolidate. Cloud-based deployment now dominates new implementations, though hybrid architectures persist among owners managing legacy on-site server investments across scattered-site affordable portfolios.
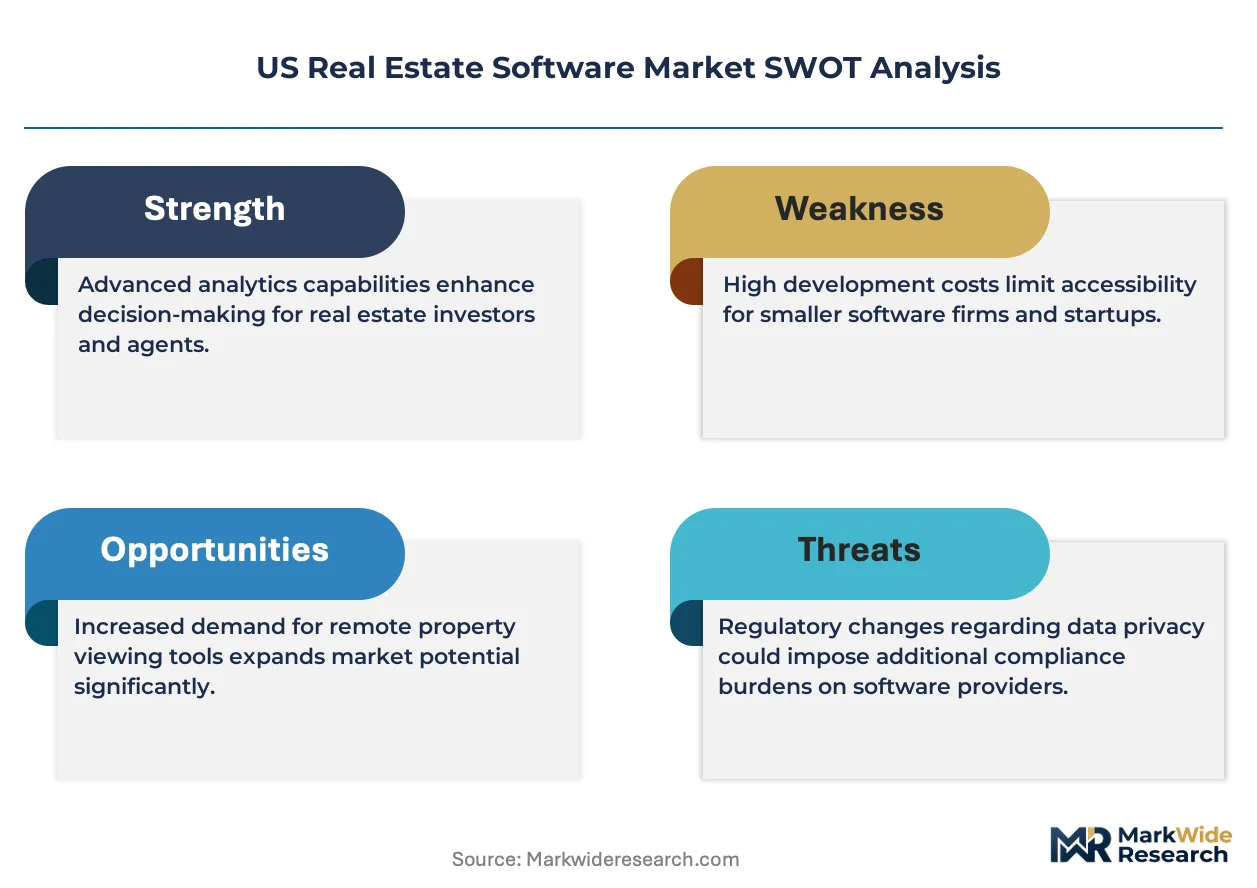
FCC broadband mapping requirements intersect with HUD digital equity mandates to shape software procurement criteria for federally subsidized properties. The SEC's investment adviser custody rules and state-level real estate commission data standards collectively force platform vendors to maintain audit trails and encrypted record retention. Stakeholders must weigh the trade-off between best-of-breed point solutions and consolidated suites as interest rate volatility compresses operating margins across the multifamily and commercial sectors.
Market Dynamics
Interest rate volatility compresses operating margins across multifamily and commercial portfolios, forcing asset managers to consolidate software spend into unified platforms rather than tolerate fragmented point solutions. This margin pressure is accelerating vendor consolidation and reshaping procurement criteria toward demonstrable ROI compression.
Growth Catalysts
- FCC Broadband Mapping Mandates:Federally subsidized properties must document connectivity infrastructure, creating procurement pull for integrated compliance modules that automate data collection and reporting workflows.
- Texas and Florida Construction Activity:Elevated institutional investor presence in these states concentrates demand for cloud-native property management platforms capable of scaling across dispersed asset portfolios.
- API-Connected Workflow Engines:Real-time synchronization between rent rolls, maintenance ticketing, and capital planning systems reduces administrative overhead for operators managing thousands of units.
Market Restraints
- Legacy On-Site Server Investments:Affordable housing owners with scattered-site portfolios face sunk-cost barriers when evaluating full cloud migration, perpetuating hybrid architecture complexity.
- SOC 2 Type II Certification Saturation:Mid-tier vendors have achieved parity with enterprise incumbents on security credentials, collapsing this former differentiator into table stakes and intensifying price competition.
- State Real Estate Commission Data Standards:Fragmented licensing requirements across jurisdictions force vendors to maintain multiple audit trail formats, elevating compliance engineering costs.
Strategic Opportunities
- SEC Climate Disclosure Rules:Real estate investment trusts face new reporting obligations for carbon emissions and physical risk exposure, opening white space for integrated ESG analytics modules.
- Student Housing Segment:Purpose-built student accommodation operators seek specialized lease-cycle management tools that handle academic-calendar turnover and guarantor workflows distinct from conventional multifamily.
- Convergence of IoT Sensors and Predictive Maintenance:Smart building infrastructure generates operational data streams that software platforms can monetize through premium tiering for automated work order generation.
Industry Challenges
- Interoperability with Legacy Accounting Systems:Property managers running decades-old general ledger platforms encounter data mapping failures during API integration, requiring expensive custom middleware development.
- Talent Scarcity in Real Estate Technology Implementation:Brokerages and owner-operators struggle to hire analysts capable of configuring advanced reporting dashboards without vendor professional services dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Real Estate Software Market |
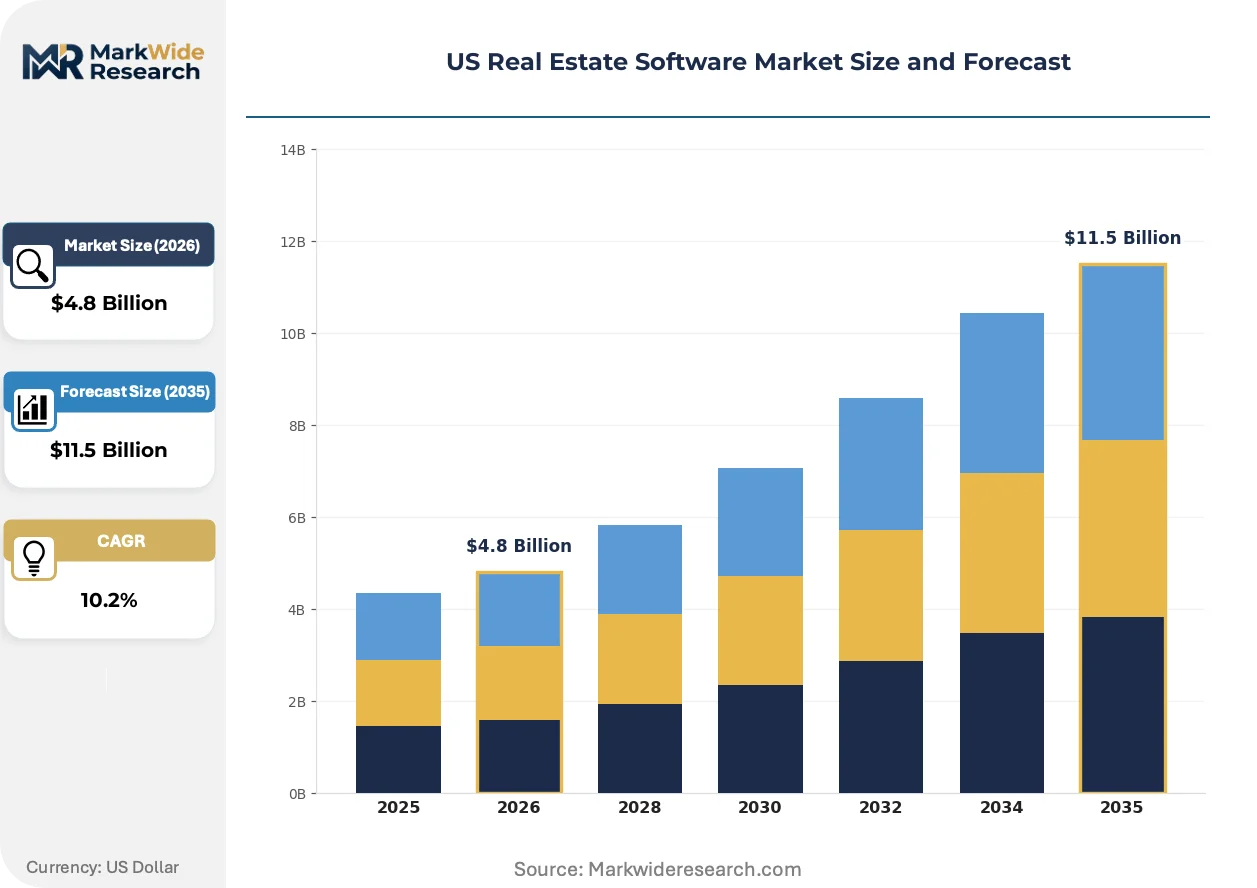
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 10.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Property Management, Transaction Management, CRM Solutions, Listing Software Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Real Estate Agents, Property Managers, Developers, Investors Solution: Market Analysis, Compliance Management, Asset Tracking, Valuation Tools |
| Companies Covered | Yardi Systems, Inc., RealPage, Inc., MRI Software LLC, AppFolio, Inc., CoStar Group, Inc., Entrata, CoreLogic, Inc., Zillow Group, Inc., Black Knight, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Real Estate Software Market Trends and Innovations
Cloud-native architectures are actively displacing on-premises deployments across the property management stack, while regulatory mandates force embedded compliance functionality. These shifts favor vendors with captive data infrastructure over pure workflow plays.
Embedded AI lease abstraction is supplanting manual document review workflows in institutional multifamily operations. Asset managers at REITs and pension fund advisors deploy natural language processing tools to extract critical dates, renewal options, and expense escalation clauses from scanned agreements. This compression of due diligence timelines is collapsing the competitive advantage of incumbent vendors lacking native document intelligence.
SEC investment adviser custody rules now mandate encrypted record retention and immutable audit trails for client assets including real estate holdings. Platform vendors must architect database layers with write-once-read-many integrity guarantees to serve registered investment advisers. The commercial property management segment bears the heaviest compliance burden, driving procurement toward vendors with existing financial services regulatory pedigree.
Subscription unbundling disrupts traditional all-in-one pricing for property management software. Mid-market operators in the Sun Belt increasingly procure core accounting from established vendors while sourcing tenant-facing mobile applications from specialized challengers. This preference for modular procurement is most visible among build-to-rent developers in Florida and Texas seeking rapid deployment without enterprise implementation cycles.
US Real Estate Software Market Segmentation
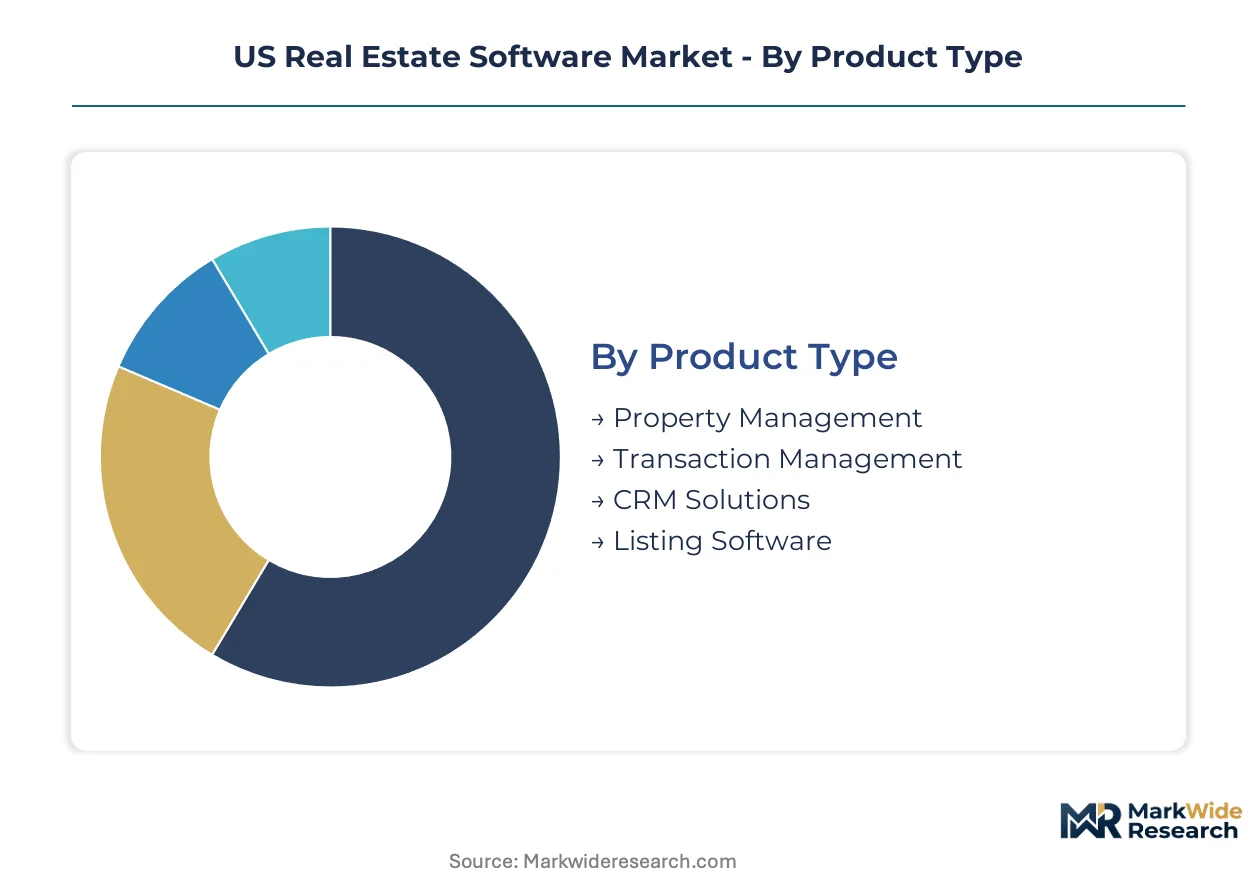
Segmentation in US real estate software reveals how procurement criteria diverge between institutional REITs and independent operators. Understanding these fault lines exposes where vendor consolidation will accelerate versus where point solutions retain defensible positions.
Product Type:
Property management platforms face the most acute substitution pressure from adjacent ERP vendors expanding into real estate verticals, while specialized transaction tools maintain stronger moats through regulatory integration.
- Property Management:Core platforms automate rent collection, maintenance ticketing, and lease administration through unified databases. Demand concentrates among Texas and Florida multifamily operators scaling past 5,000 units, where margin compression from interest rate volatility forces consolidation onto single-vendor stacks rather than fragmented point solutions.
- Transaction Management:Workflow engines coordinate document signatures, escrow tracking, and closing timelines across distributed deal teams. Institutional investors in commercial assets drive adoption here, seeking audit trails that satisfy SEC investment adviser custody rules for encrypted record retention.
- CRM Solutions:Lead routing and client relationship platforms tailored for agent-centric brokerages.
- Listing Software:Syndication and marketing tools connecting inventory to consumer search portals and MLS feeds.
Property management anchors the volume base while CRM solutions gain share at the steepest rate as brokerages consolidate and demand centralized lead intelligence.
Deployment:
Cost tier stratification separates enterprise-grade cloud migrations from budget-constrained hybrid implementations, with SaaS emerging as the default procurement mode for new market entrants.
- On-Premises:Legacy server installations retaining sensitive financial data behind operator-controlled firewalls. Affordable housing owners with scattered-site portfolios across rural counties maintain these deployments due to sunk-cost barriers and unreliable broadband infrastructure, perpetuating hybrid complexity.
- Cloud-Based:Fully hosted architectures eliminating local hardware maintenance and enabling remote access for distributed property teams. Sun Belt build-to-rent developers in Florida and Texas favor these for rapid deployment without enterprise implementation cycles.
- Hybrid:Mixed environments preserving on-site accounting servers while connecting tenant-facing applications to cloud infrastructure.
- SaaS:Subscription-native delivery with automatic updates and usage-based pricing tiers.
Cloud-based deployment captures the majority of new implementations while SaaS exhibits the most rapid expansion trajectory among venture-backed property technology entrants.
End User:
Customer type determines feature prioritization, with institutional investors demanding compliance depth that individual agents trade for usability and mobile accessibility.
- Real Estate Agents:Independent practitioners and brokerage-affiliated licensees requiring lightweight mobile tools for showing schedules, contract signatures, and commission tracking. This segment shows strongest preference for unbundled procurement, sourcing core accounting from established vendors while adopting specialized mobile applications from challengers.
- Property Managers:Professional operators overseeing multifamily, commercial, or single-family rental portfolios at scale. FCC broadband mapping mandates intersecting with HUD digital equity requirements shape their procurement criteria for federally subsidized properties, pulling demand toward integrated compliance modules.
- Developers:Ground-up construction and conversion project sponsors tracking pre-leasing, capital draws, and unit delivery timelines.
- Investors:Asset owners and fund managers monitoring portfolio performance, distributions, and investor reporting obligations.
Property managers represent the largest addressable spend pool while investors are expanding most quickly as institutional capital concentrates in build-to-rent and single-family rental aggregation strategies.
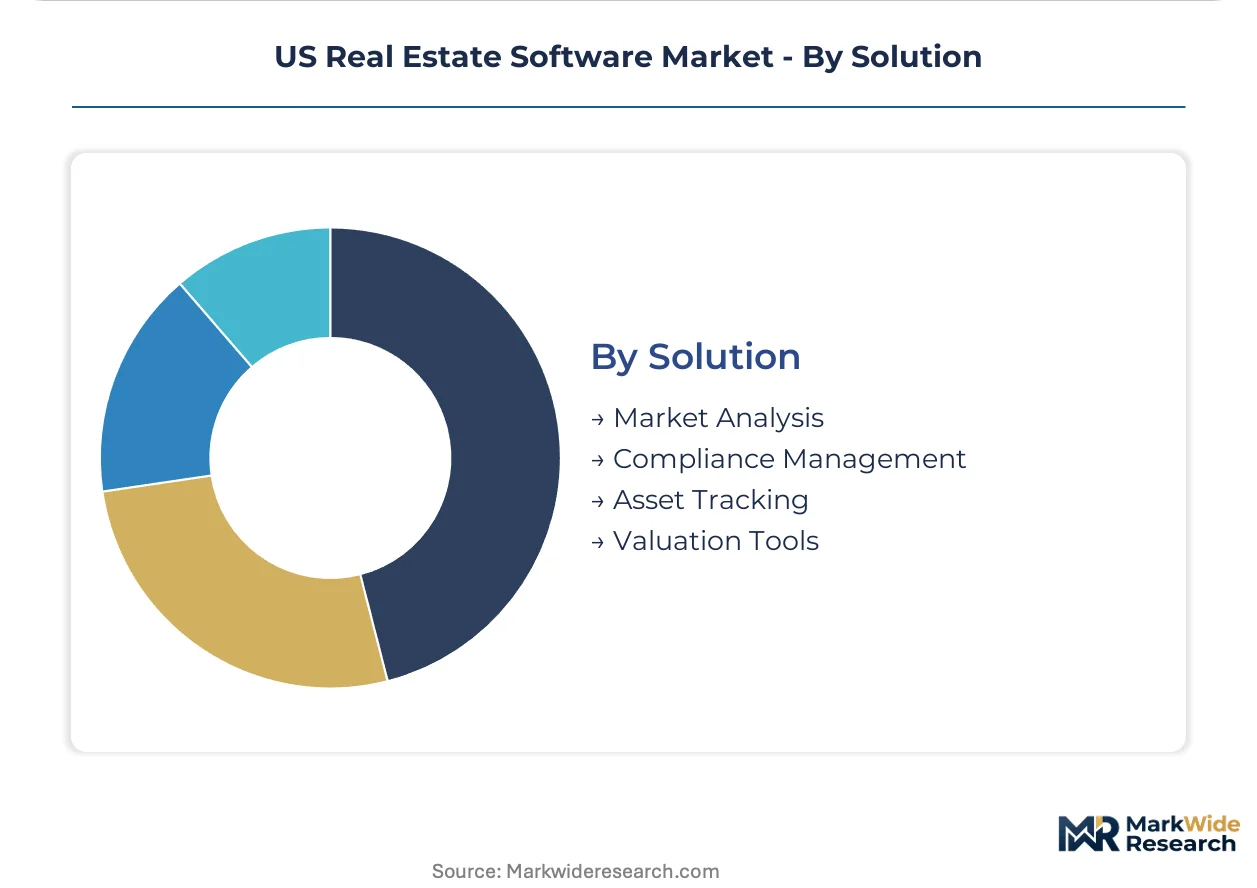
Solution:
Application maturity varies sharply, with valuation tools approaching commodity status while compliance management retains premium pricing power through regulatory complexity.
- Market Analysis:Data aggregation and visualization platforms synthesizing rent comps, absorption rates, and demographic trends into investment decision support. CoStar Group leverages its commercial listings data monopoly to cross-sell these analytics subscriptions, creating high switching costs for institutional users.
- Compliance Management:Automated reporting engines addressing SEC climate disclosure rules for REIT carbon emissions, state real estate commission data standards, and FCC broadband documentation requirements. The SEC's investment adviser custody rules mandate encrypted record retention and immutable audit trails, elevating procurement toward vendors with financial services regulatory pedigree.
- Asset Tracking:Capital improvement scheduling, warranty management, and depreciation calculation systems.
- Valuation Tools:Automated valuation models and appraisal workflow platforms for underwriting and refinancing.
Market analysis commands the deepest enterprise penetration while compliance management is climbing the fastest as regulatory disclosure obligations proliferate across federal and state jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC broadband mapping mandates intersecting with HUD digital equity requirements are pulling procurement toward integrated compliance modules across federally subsidized properties. Texas and Florida construction activity concentrates demand for cloud-native platforms capable of scaling dispersed portfolios.
Southeast
Florida build-to-rent developers favor rapid-deployment SaaS architectures over enterprise implementation cycles. State-level real estate commission data standards force vendors to maintain jurisdiction-specific audit trail formats. Miami-Dade and Tampa Bay institutional investor presence elevates demand for transaction management tools with SEC-compliant encrypted record retention.
Southwest
Texas multifamily operators scaling past 5,000 units consolidate onto single-vendor stacks amid interest rate margin compression. FCC broadband documentation requirements shape procurement criteria for rural scattered-site affordable housing. Dallas-Fort Worth and Houston construction pipelines drive cloud-native property management platform adoption.
West Coast
California REITs deploy embedded AI lease abstraction to compress due diligence timelines for institutional acquisitions. SEC climate disclosure rules for carbon emissions and physical risk exposure open white space for integrated ESG analytics modules. Los Angeles and San Francisco asset managers prioritize compliance management solutions with financial services regulatory pedigree.
Northeast
New York Metro brokerages consolidate CRM investments as commission compression forces centralized lead intelligence. State real estate commission data standards elevate compliance engineering costs for multi-jurisdiction operators. Boston and Washington DC pension fund advisors seek natural language processing tools for lease document review workflows.
Mountain West
Denver and Phoenix purpose-built student accommodation operators seek specialized lease-cycle management tools handling academic-calendar turnover. Hybrid architectures persist among affordable housing owners with legacy on-site server investments across rural counties. HUD digital equity mandates intersect with unreliable broadband infrastructure to perpetuate mixed deployment environments.
US Real Estate Software Market Competitive Landscape
Player mix skews toward vertically integrated incumbents with captive accounting modules and specialized challengers attacking narrow workflow segments. The competitive structure concentrates around three archetypes: full-suite platform vendors, point-solution specialists, and data-monopoly analytics providers. Dominant competitive moves include M&A-driven portfolio consolidation and API partnership networks that embed workflow tools into broader enterprise stacks.
Within the full-suite tier, Yardi Systems, RealPage, and CoStar Group occupy positions representing distinct strategic emphases. Yardi exemplifies vertical integration through captive development of accounting and maintenance modules. RealPage sits within the aggressive pricing vector for student housing and affordable property segments. CoStar anchors the data-monopoly archetype, leveraging commercial listings concentration to cross-sell analytics subscriptions with high switching costs for institutional users.
| Leading Market Players |
|---|
| Yardi Systems, Inc. |
| RealPage, Inc. |
| MRI Software LLC |
| AppFolio, Inc. |
| CoStar Group, Inc. |
| Entrata |
| CoreLogic, Inc. |
| Zillow Group, Inc. |
| Black Knight, Inc. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day implementation cycles for enterprise property management platforms concentrate pricing power among vendors with captive accounting modules, while compressed margins from interest rate volatility force buyers toward consolidated suites over fragmented point solutions. Procurement patterns in Texas and Florida construction markets favor rapid-deployment SaaS architectures that trade customization depth for speed-to-value.
Pricing Analysis
Certification level (SOC 2 Type II) creates the primary spread between mid-tier challengers and enterprise incumbents, though this credential has collapsed into table stakes. Subscription-based SaaS tiers dominate, with pricing stratifying across premium, standard, and economy levels based on integration complexity and after-sales support depth. Cost compression in the affordable housing segment intensifies because scattered-site operators face sunk-cost barriers to cloud migration. Independent brokerages show highest price sensitivity, while institutional REITs prioritize compliance depth over unit economics.
Supply Chain Analysis
Cloud infrastructure provisioning through hyperscale data centers in Virginia, Oregon, and Ohio underwrites delivery reliability for property management platforms serving dispersed portfolios. Software development draws from domestic engineering talent pools in Austin, Denver, and Seattle, with API integration specialists concentrated in San Francisco and New York. Single-source vulnerability sits with legacy accounting system vendors whose decades-old general ledger platforms require expensive custom middleware. Distribution runs through direct enterprise sales teams and channel partnerships with real estate consulting firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US real estate software sits in early-cycle expansion as SEC climate disclosure rules and FCC broadband mandates pull adoption forward among federally subsidized properties and institutional investors. Cloud-native architectures are displacing on-premises deployments faster than prior technology transitions in the sector.
For Market Incumbents: Secure dominance in student housing and affordable segments through aggressive pricing that exploits SOC 2 Type II parity among mid-tier rivals. Deepen vertical integration into IoT sensor networks for predictive maintenance, creating switching costs that API-only challengers cannot replicate. Prioritize captive development of ESG analytics modules before regulatory deadlines compress procurement windows. For New Entrants and Emerging Players: Lead with specialized lease-cycle tools for purpose-built student accommodation operators in Denver and Phoenix, where academic-calendar workflows remain underserved by generic multifamily platforms. Target the Mountain West affordable housing corridor, where hybrid architecture complexity and unreliable broadband infrastructure perpetuate gaps in cloud-native coverage. Pursue channel partnerships with regional property management associations rather than direct enterprise sales. For Investors and Strategic Acquirers: Carve-out targets emerge from private equity-owned software rollups seeking liquidity after multiple add-on acquisitions. Long-term viability hinges on regulatory pedigree depth, with financial services compliance expertise becoming the scarcest capability across the analysis window. Monitor SEC enforcement patterns around investment adviser custody rules as the signal for which vendors will capture commercial property management procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies rent rolls, maintenance ticketing, and capital planning into single-vendor stacks for Texas operators scaling past 5,000 units. |
| Acquisition of Specialist Firm | Captures AI lease abstraction capabilities that compress due diligence timelines for California REITs executing institutional acquisitions. |
| Strategic Partnership | Embeds compliance modules into broader enterprise stacks serving federally subsidized properties under FCC broadband mandates. |
| Product Launch | Introduces ESG analytics modules addressing SEC climate disclosure rules for carbon emissions and physical risk exposure reporting. |
| Geographic Expansion | Establishes presence in Florida build-to-rent corridors where rapid-deployment SaaS architectures outcompete enterprise implementation cycles. |
Research Methodology
The analysis maps property management platforms, transaction management tools, CRM solutions, and compliance management modules, each validated through primary interviews with CTOs at multifamily operators, IT procurement officers at REITs, platform engineers at software vendors, and integration specialists at consulting firms. Secondary validation draws from SEC filings, App Annie mobile analytics, hyperscaler capex disclosures, and HUD program documentation. Bottom-up unit economics triangulate against top-down market sizing across deployment models and end-user segments.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models segmentation by deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern. CAGRs derive from regression analysis of historical penetration rates and forward-looking regulatory obligation timelines, with inputs including interest rate volatility assumptions and construction pipeline data from Texas and Florida markets.
The analysis sits within stated boundaries; outcomes outside sustained institutional capital concentration in build-to-rent and single-family rental aggregation would require recalibration. Forecasts reflect assumptions around regulatory enforcement intensity and cloud infrastructure cost curves. Practitioners should keep alternative scenarios live as SEC disclosure rule implementation and FCC broadband mapping deadlines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Middle East and Africa Hard Facility Management Market
Real Estate
India Office Real Estate Market
Real Estate
US Property Management Software Market
Real Estate
Global Office Space Market
Real Estate
Office Real Estate Market
Real Estate
China Facility Management Market
Real Estate
Mexico Facility Management Market
Real Estate
Vietnam Self-Storage Market
Real Estate
GCC REIT Market
Real Estate
Japan Office Real Estate Market
Real Estate
Egypt Residential Real Estate Market
Real Estate
Switzerland Luxury Residential Real Estate Market
Real Estate
Africa Facility Management Market
Real Estate
Argentina Facility Management Market
Real Estate
Smart Building Market
Real Estate
Residential Real Estate Market