
 US Pet Insurance Market | 2026-2036
US Pet Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
US Pet Insurance Market Outlook
Veterinary actuarial talent scarcity is reorganizing how carriers price risk and structure underwriting teams. Trupanion leverages direct-to-consumer platforms to sustain its position in illness and injury coverage. Nationwide Mutual Insurance Company anchors its competitive stance through embedded distribution within existing property and casualty relationships. Healthy Paws differentiates via unlimited lifetime benefits without per-incident caps.
Pet insurance constitutes a property and casualty contract that indemnifies policyholders against veterinary medical expenses, typically structured with annual deductibles, reimbursement percentages between 70% and 90%, and varying annual benefit limits. Comprehensive policies dominate premium volume by covering accidents, illnesses, and hereditary conditions under single contracts. Accident-only plans occupy a shrinking but price-sensitive niche. Direct sales channels are capturing share from traditional broker networks as digital-native pet owners research and bind coverage online.
State insurance commissioners enforce solvency and rate-filing requirements, while the National Association of Insurance Commissioners develops model laws for pet insurance standardization. The USDA and FDA regulate veterinary pharmaceuticals and biologics that directly influence claim costs and policy exclusions. Stakeholders must monitor how state-by-state regulatory fragmentation affects product portability and national scaling strategies.
Market Dynamics
State insurance commissioner oversight and evolving NAIC model laws are reorganizing product standardization across the US pet insurance landscape. Carriers must now navigate fifty distinct regulatory frameworks while building scalable national platforms.
Growth Catalysts
- NAIC Model Law Harmonization:Standardized disclosure requirements are reducing compliance fragmentation and enabling carriers to launch products across multiple states with fewer regulatory rewrites.
- Veterinary Cost Inflation:Advanced diagnostic imaging and specialty surgery pricing in urban California and Texas markets is pushing pet owners toward comprehensive indemnity products.
- Embedded Distribution Partnerships:Property and casualty carriers are integrating pet coverage into existing homeowner and renter policy ecosystems, lowering customer acquisition costs.
Market Restraints
- Actuarial Talent Scarcity:The limited pool of veterinary actuaries concentrated in coastal metropolitan areas is constraining carrier pricing sophistication and slowing product development cycles.
- State-by-State Rate Filing Friction:California, Florida, and New York maintain distinct prior-approval requirements that extend time-to-market by six to eighteen months compared to file-and-use states.
- Claim Cost Volatility:Unpredictable veterinary pharmaceutical pricing, particularly for biologics regulated by the FDA, complicates loss ratio forecasting and reserve adequacy.
Strategic Opportunities
- Midwest and Mountain State Penetration:Ohio, Michigan, and Colorado exhibit pet ownership rates comparable to coastal leaders but carry significantly lower policy penetration, offering whitespace for direct-to-consumer expansion.
- Wellness and Preventive Care Bundling:USDA-regulated veterinary biologics and routine care services present opportunities for subscription-based hybrid products beyond traditional indemnity structures.
- Telemedicine Integration:Convergence of remote veterinary consultation platforms with policy administration systems is enabling real-time claim pre-authorization and cost containment.
Industry Challenges
- Veterinary Data Standardization:Inconsistent medical record formats across the 30,000+ independent US veterinary practices complicate automated claims adjudication and fraud detection.
- Legacy System Integration:Established carriers face technical debt when connecting modern pet-specific policy engines to decades-old property and casualty core systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pet Insurance Market |
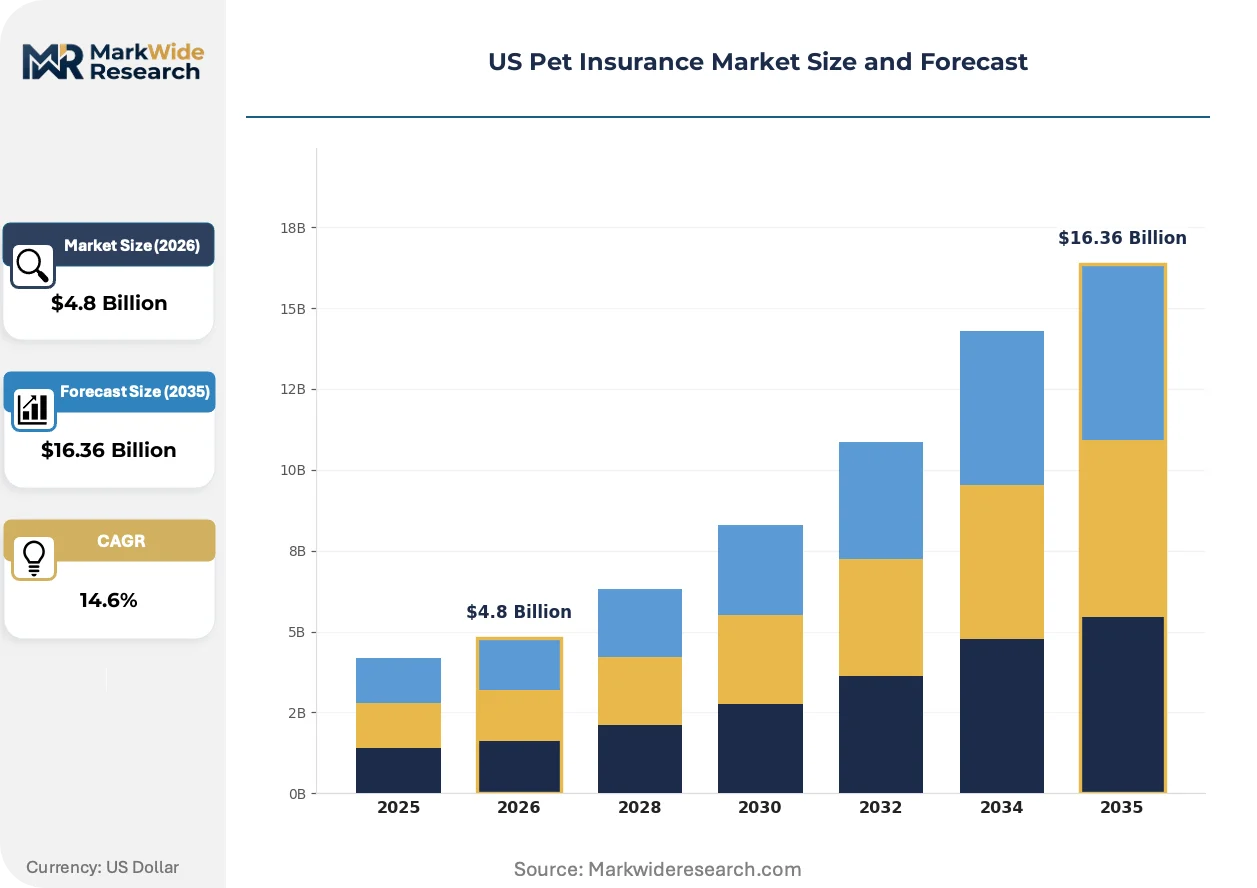
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Accident Only, Comprehensive, Wellness, Lifetime Animal Species: Dogs, Cats, Birds, Exotic Pets Premium Range: Low, Medium, High, Variable Sales Channel: Direct, Brokers, Aggregators, Affiliates |
| Companies Covered | Trupanion, Nationwide Mutual Insurance Company, Embrace Pet Insurance Agency, Fetch Pet Insurance, Healthy Paws, Pets Best Insurance Services, ASPCA Pet Insurance, Figo Pet Insurance, Pumpkin Insurance Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pet Insurance Market Strategic Shifts
Digital-native pet owners are compressing research-to-purchase cycles and demanding seamless mobile-first experiences. Carriers are responding with AI-enabled underwriting and real-time claims processing.
Telematics-enabled wearable devices for companion animals are miniaturizing rapidly. Millennial pet owners in Texas and Florida are adopting collar-mounted health monitors at accelerating rates. This sensor technology is miniaturizing the data collection infrastructure, enabling predictive underwriting models that price risk at the individual pet level rather than breed-based tables.
The NAIC Pet Insurance Model Law is mandating standardized policy language and mandatory waiting period disclosures across adopting states. This regulatory push is forcing carriers to redesign policy documents and refile products in 23 states that have adopted or adapted the framework. Small regional carriers without dedicated compliance infrastructure are struggling to meet the 2024-2025 refiling deadlines.
Subscription-based wellness plans are displacing traditional fee-for-service veterinary relationships. Younger pet owners in California and New York are prioritizing predictable monthly budgeting over episodic large veterinary expenditures. This behavioral shift is most visible in urban markets where veterinary practice consolidation has concentrated pricing power among corporate clinic chains.
US Pet Insurance Market Segmentation
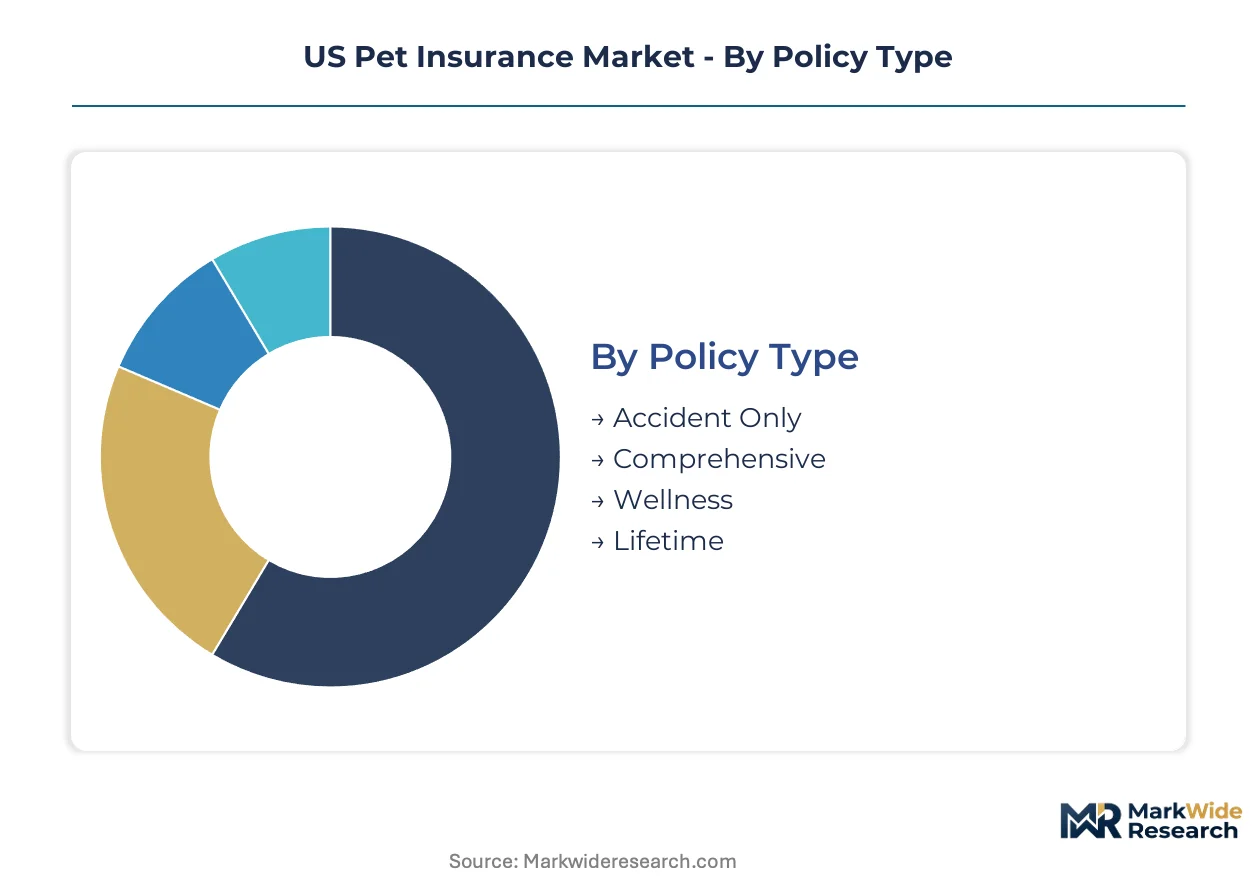
Segmentation in the US pet insurance market determines how carriers align product architectures with distinct risk pools and purchasing behaviors. Regulatory filing requirements vary by policy structure, while species-specific actuarial data drives pricing sophistication across state lines.
Policy Type:
FDA-regulated veterinary biologics and USDA animal health standards create divergent coverage mandates across policy structures, with state insurance commissioners scrutinizing each variant's reserve adequacy differently.
- Comprehensive:Single-contract coverage spanning accidents, illnesses, and hereditary conditions with annual deductibles and 70-90% reimbursement tiers. California, Texas, and Florida concentrate demand here as specialty veterinary costs in urban markets push owners toward full indemnity protection against diagnostic imaging and surgical interventions.
- Accident Only:Narrow indemnity limited to traumatic injury events, excluding illness coverage entirely. Price-sensitive segments in Midwest states maintain residual demand for this stripped-down structure despite shrinking overall share as comprehensive plans penetrate downward.
- Wellness:Routine care bundling covering vaccinations, dental cleanings, and preventive screenings under subscription-style arrangements. USDA-regulated biologics and annual exam protocols define the covered service menu.
- Lifetime:Unlimited benefit structures without per-incident or annual caps, typically commanding premium positioning. Healthy Paws and specialty carriers anchor product portfolios around this segment for high-attachment-rate pet owners.
Comprehensive handles the majority of throughput; Wellness is expanding most quickly as younger owners prioritize predictable monthly budgeting over episodic expenditures.
Animal Species:
Actuarial data availability and veterinary cost structures concentrate carrier investment around species with standardized medical record formats and established treatment protocols.
- Dogs:Dominant premium volume segment with breed-specific pricing tables and hereditary condition riders. Large breed orthopedic risks and brachycephalic respiratory conditions drive differential pricing across state markets.
- Cats:Lower average claim severity but higher frequency of chronic renal and thyroid conditions in aging populations. Indoor-outdoor lifestyle factors create rating territory variations.
- Birds:Avian veterinary specialists command premium pricing in coastal metropolitan areas, constraining carrier appetite for this segment.
- Exotic Pets:Reptile, small mammal, and pocket pet coverage remains niche with limited actuarial data and restricted veterinary specialist networks.
Dogs anchors absolute premium volume; Cats is gaining share fastest as urban apartment-dwelling patterns accelerate feline ownership in New York and California markets.
Premium Range:
Three-tier pricing structure across premium, standard, and economy levels aligns with deductible selection, reimbursement percentage, and annual benefit cap configurations.
- High:Unlimited lifetime benefits with low deductibles and 90% reimbursement, targeting specialty-coverage-seeking owners in high-cost veterinary markets.
- Medium:Balanced deductible-reimbursement tradeoffs with defined annual caps, capturing the core middle-market expansion.
- Low:High-deductible, lower-reimbursement entry points for first-time buyers and price-sensitive segments in lower-penetration states.
- Variable:Usage-based and telematics-linked pricing emerging from wearable device data collection, with Texas and Florida Millennial adoption leading experimental rollout.
Medium tier carries the bulk of policy count; Variable pricing is climbing the fastest as sensor technology enables individual pet risk rating.
Sales Channel:
Distribution concentration reflects customer acquisition cost economics and state-level broker licensing requirements that fragment national platform scalability.
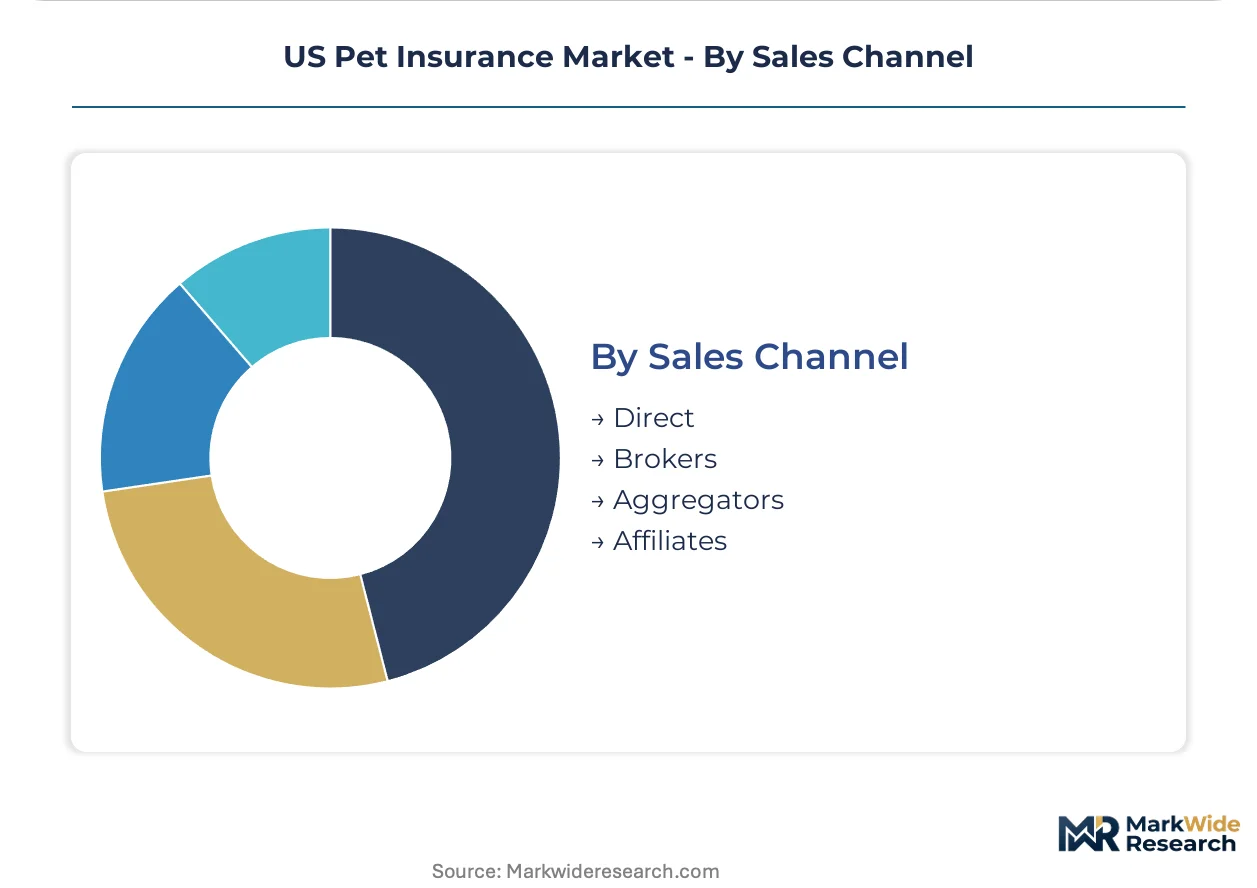
- Direct:Carrier-owned digital platforms and call centers capturing share from traditional intermediaries as Millennial and Gen Z owners research and bind coverage online. Trupanion sustains positioning through direct-to-consumer infrastructure.
- Brokers:Licensed intermediaries with state-specific appointments, maintaining relevance in complex multi-pet and commercial kennel coverage scenarios.
- Aggregators:Comparison platforms generating quote volume with state disclosure requirements creating compliance overhead for participating carriers.
- Affiliates:Embedded distribution through veterinary practice partnerships, pet retailer relationships, and property-casualty carrier ecosystems. Nationwide Mutual Insurance Company leverages existing homeowner policy relationships for this channel.
Direct channels process the majority of new policy volume; Affiliates is expanding fastest through embedded property-casualty partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The California Department of Insurance anchors the most active regulatory environment for pet coverage, with state-level rate filings and consumer protection mandates shaping carrier behavior nationwide. State insurance commissioners across the US enforce divergent prior-approval requirements that fragment product portability.
California
Veterinary specialty costs in Los Angeles and San Francisco drive comprehensive policy uptake among Millennial pet owners. The California Department of Insurance mandates prior approval for all rate changes, extending carrier time-to-market by twelve to eighteen months. Silicon Valley telematics startups are piloting wearable-enabled risk pricing with select carrier partners.
Texas
Houston and Dallas-Fort Worth veterinary practice consolidation concentrates pricing power among corporate clinic chains. The Texas Department of Insurance operates under file-and-use protocols that accelerate product launches compared to coastal jurisdictions. Austin-based insurtech platforms are capturing direct-to-consumer market share through mobile-first binding.
Florida
Miami and Tampa Bay pet ownership rates exceed national averages while specialty veterinary infrastructure lags demand. The Florida Office of Insurance Regulation maintains strict solvency oversight with detailed reserve adequacy reviews. Orlando carriers are experimenting with embedded distribution through property-casualty agency networks.
New York
New York City apartment-dwelling patterns accelerate feline ownership and wellness-plan subscriptions. The New York State Department of Financial Services enforces comprehensive disclosure requirements for policy waiting periods. Upstate veterinary deserts create telemedicine integration opportunities for remote claim pre-authorization.
Ohio
Cleveland and Columbus exhibit pet ownership rates comparable to coastal leaders with significantly lower policy penetration. The Ohio Department of Insurance offers streamlined rate-filing pathways for innovative product structures. Cincinnati carriers are targeting price-sensitive segments through high-deductible economy-tier offerings.
US Pet Insurance Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with property-casualty incumbents leveraging embedded distribution against pure-play pet carriers. The market structure rewards scale in actuarial data accumulation and regulatory compliance infrastructure. Two strategic archetypes dominate: direct-to-consumer specialists with digital-native platforms, and diversified carriers integrating pet coverage into existing policy ecosystems. Competitive moves concentrate on M&A for veterinary data assets and strategic partnerships with telematics hardware providers.
Among direct-to-consumer specialists, Trupanion and Healthy Paws exemplify the illness-and-injury coverage archetype with unlimited benefit structures. Nationwide Mutual Insurance Company represents the embedded distribution model, anchoring competitive positioning through property-casualty policyholder relationships. These three carriers illustrate the fundamental strategic divergence between standalone pet expertise and cross-sell ecosystem leverage.
| Leading Market Players |
|---|
| Trupanion |
| Nationwide Mutual Insurance Company |
| Embrace Pet Insurance Agency |
| Fetch Pet Insurance |
| Healthy Paws |
| Pets Best Insurance Services |
| ASPCA Pet Insurance |
| Figo Pet Insurance |
| Pumpkin Insurance Services |
| Others |
Value Chain & Pricing Dynamics
Ninety-day rate-filing delays in prior-approval states compress carrier pricing agility while concentrating actuarial talent procurement in coastal metropolitan corridors, feeding premium tier stratification that separates unlimited lifetime benefit structures from high-deductible economy entry points.
Pricing Analysis
Coastal-to-Midwest premium spreads of forty to sixty percent reflect differential veterinary specialty costs and state regulatory burden. Three-tier pricing structure across premium, standard, and economy levels anchors product architecture, with unlimited lifetime benefits commanding positioning against high-deductible entry tiers. Pricing pressure stems from veterinary pharmaceutical cost volatility and FDA-regulated biologic pricing unpredictability. First-time buyers in Ohio and Michigan exhibit highest price sensitivity; specialty-coverage-seeking owners in California and Texas show lowest.
Supply Chain Analysis
Claims adjudication latency averaging fourteen to twenty-one days reflects dependency on fragmented veterinary practice management systems across thirty thousand independent US clinics. Carrier policy administration draws from proprietary actuarial data repositories, NAIC compliance infrastructure, and telematics hardware partnerships. Single-source vulnerability concentrates in veterinary actuarial talent pools anchored in Seattle, Boston, and New York corridors. Distribution runs through direct-to-consumer digital platforms, embedded property-casualty agency networks, and veterinary practice point-of-sale partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in Midwest and Mountain state whitespace where pet ownership rates match coastal leaders at half the policy penetration, as Millennial and Gen Z demand for comprehensive coverage creates tier-specific niches.
For Market Incumbents: Secure proprietary veterinary data assets through strategic partnerships with practice management software providers to defend against insurtech entrants. Deepen actuarial talent pipelines via university veterinary school alliances and remote-work infrastructure that unlocks non-coastal hiring pools. Channel control through embedded property-casualty distribution anchors retention against direct-to-consumer disintermediation.
For New Entrants and Emerging Players: NAIC model law compliance fast-track enables multi-state product launches with single regulatory rewrite rather than fifty distinct filings. Midwest state penetration offers lowest competitive density against established coastal concentration. Mobile-first binding platforms with real-time claims visualization capture Millennial research-to-purchase compression.
For Investors and Strategic Acquirers: Carve-out targets emerge from regional property-casualty carriers with dormant pet insurance books requiring actuarial infrastructure investment. Long-term viability hinges on telematics-enabled individual pet risk rating displacing breed-based tables. Watch FDA veterinary biologic pricing announcements as inflection indicator for loss ratio volatility.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Wearable Partnership | Sensor-enabled individual pet risk rating displaces legacy breed-based pricing tables in Texas and Florida. |
| NAIC Model Law Compliance Infrastructure | Standardized disclosure capabilities unlock multi-state product launches without regulatory rewrite overhead. |
| Veterinary Practice Management Integration | Direct claims data feeds from Vetter and eVetPractice compress adjudication latency and fraud exposure. |
| Midwest Direct-to-Consumer Expansion | Ohio and Colorado whitespace capture leverages lower customer acquisition costs against saturated coastal markets. |
| Wellness Subscription Product Development | USDA-regulated preventive care bundling addresses Millennial preference for predictable monthly budgeting. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of state insurance commissioner rate filings, NAIC model law adoption tracking, and veterinary practice consolidation databases. Primary interviews engaged pet insurance product executives, veterinary actuarial directors, state regulatory affairs leads, and embedded distribution channel managers at property-casualty carriers. Secondary validation drew from SEC carrier filings, state department of insurance bulletins, and American Veterinary Medical Association demographic surveys. Bottom-up policy count estimation triangulates against top-down premium volume analysis across the analysis window.
Segmentation dimensions modeled include policy type architecture, animal species actuarial pools, premium tier configuration, and sales channel concentration. CAGRs derive from regression analysis of historical premium growth against veterinary cost inflation indices and pet ownership demographic shifts. Forecast inputs incorporate FDA veterinary biologic pricing trajectories and NAIC model law adoption velocity across state jurisdictions throughout the forecast period.
Decision-makers should treat outputs as directional under assumptions of continued veterinary specialty cost inflation and stable NAIC harmonization progress; material deviation in either would warrant model refresh. Specific risk factors include state-by-state regulatory fragmentation persistence and unpredictable claim cost volatility from novel veterinary treatments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Investment Analysis and Financial Strategies
South Korea Real Time Payments Market
Investment Analysis and Financial Strategies
Online Trading Platform Market
Investment Analysis and Financial Strategies
India Student Loan Market
Investment Analysis and Financial Strategies
Bill Splitting Apps Market
Investment Analysis and Financial Strategies
Canada Payment Gateway Market
Investment Analysis and Financial Strategies
Financial Forecasting Software Market
Investment Analysis and Financial Strategies
China Prepaid Cards Market
Investment Analysis and Financial Strategies
Europe Digital Asset Management Market
Investment Analysis and Financial Strategies
US Long-Term Care Private Insurance Market
Investment Analysis and Financial Strategies
Spain Real Time Payments Market
Investment Analysis and Financial Strategies
Commercial Cyber Insurance Market
Investment Analysis and Financial Strategies
Asia Pacific Capital Exchange Ecosystem Market
Investment Analysis and Financial Strategies
Bulgaria POS Terminals Market
Investment Analysis and Financial Strategies
Europe Entertainment Insurance Market
Investment Analysis and Financial Strategies
China Mobile Payments Market
Investment Analysis and Financial Strategies
Mobile Wallet Market