
 Uruguay Life and Non-Life Insurance Market | 2026-2036
Uruguay Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Uruguay Life and Non-Life Insurance Market Analytics
Retirement annuity product revenue is rewriting profitability equations across Uruguay's insurance sector. Banco de Seguros del Estado leverages its state-backed position to dominate public-sector group policies. Seguros SURA anchors its competitive stance through specialized agricultural risk offerings. Mapfre competes on digital platform investments that streamline underwriting workflows.
Uruguay life and non-life insurance encompasses risk-pooling contracts covering mortality, morbidity, property damage, and liability exposures, with capital reserves regulated under risk-based solvency frameworks and technical provisions calculated through actuarial mortality tables and catastrophe loss modeling. Health insurance leads product type segmentation as private medical coverage supplements gaps in the national public health system, while auto insurance maintains steady premium flows tied to mandatory liability requirements. Bancassurance channels capture margin concentration through embedded product distribution within retail banking relationships.
Uruguay's central bank, Banco Central del Uruguay, enforces solvency standards and reserve requirements that shape insurer capital allocation and product pricing structures, while the country's pension regulator supervises annuity product design linked to retirement system reforms. Stakeholders must monitor regulatory harmonization pressures from Mercosur integration initiatives and evolving digital authentication standards for remote policy issuance.
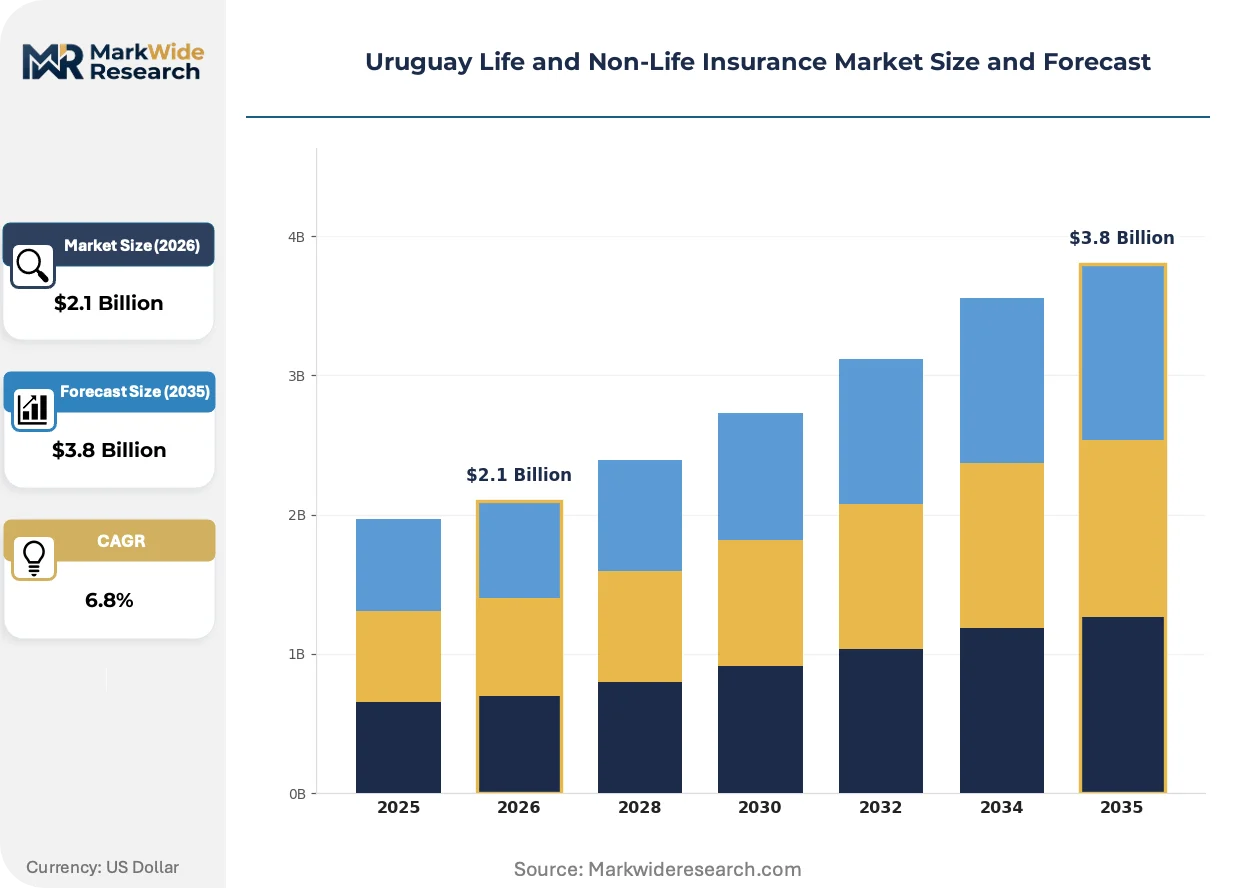
Market Dynamics
Digital distribution platforms are concentrating policy issuance in Montevideo's financial district while Banco Central del Uruguay modernizes solvency frameworks. This structural shift compresses traditional agency networks and rewards insurers with integrated banking partnerships.
Growth Catalysts
- Mercosur regulatory harmonization:Cross-border policy recognition protocols are expanding addressable markets for Uruguayan carriers into Argentina and Brazil.
- Agribusiness expansion:Soy and cattle operations in Paysandú and Río Negro departments are driving specialized crop and livestock coverage demand.
- Pension system reform:Mandatory retirement savings conversion to annuity products is creating predictable premium flows for life insurers.
Market Restraints
- Reinsurance capacity concentration:Catastrophe coverage for flood and windstorm exposures depends on Lloyd's and Miami-based treaty markets, creating pricing volatility.
- Actuarial talent scarcity:Montevideo's Universidad de la República produces fewer than fifteen qualified actuaries annually, constraining product development velocity.
- Mandatory auto tariff compression:Banco Central del Uruguay's reference pricing for compulsory third-party liability limits premium growth in the largest non-life line.
Strategic Opportunities
- Digital authentication standards:Remote biometric verification protocols under central bank supervision enable fully digital policy issuance without physical presence.
- Coastal property underpenetration:Maldonado and Rocha departments show sub-40% coverage rates for vacation residence exposures.
- Parametric index products:Satellite-triggered drought and rainfall coverage eliminates claims adjustment costs for agricultural portfolios.
Industry Challenges
- Core system modernization:Legacy policy administration platforms from the 1990s require multimillion-dollar replacement to support real-time digital distribution.
- Cyber risk modeling:Sparse local claims history complicates pricing for commercial cyber liability products targeting Montevideo's fintech sector.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uruguay Life and Non-Life Insurance Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Health Insurance, Property Insurance, Life Insurance, Auto Insurance Customer Type: Individual Clients, Corporates, SMEs, Government Entities Coverage Type: Comprehensive Coverage, Third Party Liability, Basic Coverage, Accidental Death Distribution Channel: Agency Channel, Direct Sales, Online Platform, Bancassurance |
| Companies Covered | Banco de Seguros del Estado, Seguros SURA, Mapfre, Porto Seguros, SBI Seguros, Surco Seguros, Sancor Seguros, Zurich Santander, Berkley Uruguay Seguros, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uruguay Life and Non-Life Insurance Market Evolving Landscape
Technology investment patterns in Uruguay's insurance sector are pivoting from back-office efficiency toward front-end distribution capture. Insurers are racing to embed products within digital banking workflows before channel concentration solidifies.
Telematics-enabled usage-based auto coverage is migrating from pilot deployments to mainstream commercial fleet offerings. Transport operators in Canelones and San José departments are adopting GPS-linked premium calculations to reduce exposure-based costs. This migration from traditional annual rating to real-time behavioral pricing compresses risk selection cycles and rewards safer operators with immediate tariff reductions.
Banco Central del Uruguay's risk-based solvency framework is tightening capital reserve requirements for catastrophe-exposed property lines. Insurers must hold additional technical provisions against earthquake and flood scenarios modeled at 200-year return periods. Agricultural and coastal property segments face the steepest capital charges, pushing carriers toward reinsurance-heavy structures or selective geographic withdrawal.
Small and medium enterprises are consolidating insurance purchasing through banking relationships rather than independent brokers. Bancassurance channels now originate over half of new commercial policies in Montevideo and surrounding departments. This concentration is most pronounced among manufacturing and professional services firms with existing credit facilities, where embedded coverage offers streamlined administration and consolidated billing.
Uruguay Life and Non-Life Insurance Market Segmentation
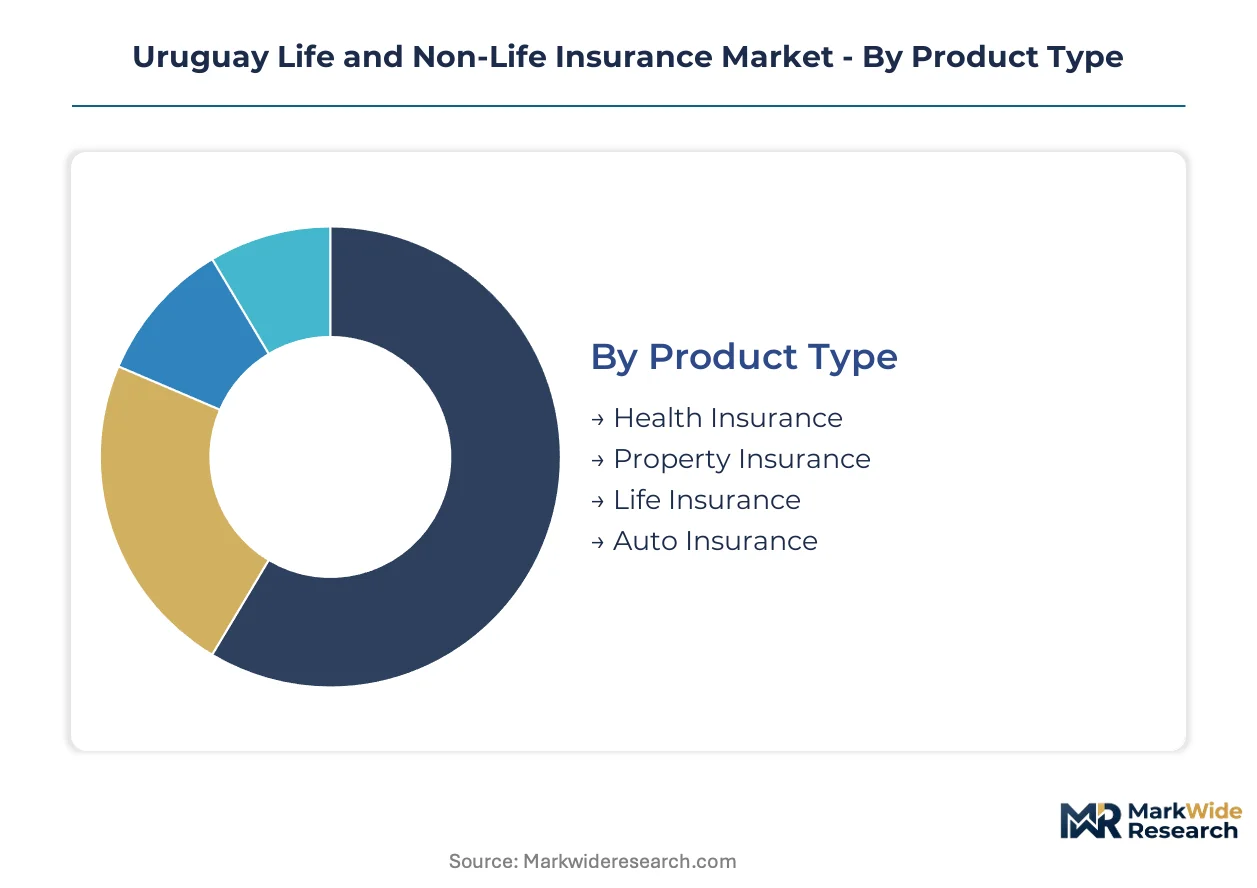
Segmentation in Uruguay's insurance sector reveals how capital reserves, regulatory capital charges, and distribution economics concentrate profitability within specific product-customer-channel combinations. Understanding these partitions exposes where Banco Central del Uruguay's solvency frameworks create structural advantages for certain business models over others.
Product Type:
Cost tier differentiation across Uruguay's insurance products reflects varying capital intensity under risk-based solvency rules, with medical and mortality exposures demanding distinct technical provision calculations.
- Health Insurance:Private medical coverage contracts supplement gaps in Uruguay's national public health system, with premium flows concentrating among Montevideo-based employer group policies. Banco Central del Uruguay's reserve requirements for morbidity risk exceed those for standard property lines, compressing margins unless scaled through corporate accounts.
- Property Insurance:Residential and commercial building coverage carries catastrophe capital charges at 200-year return periods for earthquake and flood scenarios. Coastal exposures in Maldonado and Rocha departments face steepest reserve requirements, pushing carriers toward selective underwriting or reinsurance-heavy structures.
- Life Insurance:Mortality-based contracts include term, whole life, and endowment structures with technical provisions calculated through actuarial mortality tables. Pension reform linkages are converting mandatory retirement savings into predictable annuity premium flows.
- Auto Insurance:Compulsory third-party liability maintains steady premium volumes tied to mandatory coverage requirements, though Banco Central del Uruguay's reference pricing limits tariff growth in this largest non-life line.
Health Insurance holds installed capacity. Property Insurance is rotating up the share rankings.
Customer Type:
Application patterns across customer categories show how embedded distribution through banking relationships is consolidating purchasing power away from traditional broker channels.
- Individual Clients:Personal lines coverage including auto, home, and supplemental health products. Demand concentrates through direct digital platforms and agency networks, with biometric authentication enabling remote policy issuance without physical presence.
- Corporates:Large enterprise risk programs spanning property, liability, and group life benefits. These accounts anchor reinsurance treaty structures and command preferential pricing through volume concentration.
- SMEs:Small and medium enterprises are consolidating insurance purchasing through existing banking relationships rather than independent intermediaries. Manufacturing and professional services firms in Montevideo and surrounding departments drive bancassurance channel concentration.
- Government Entities:Public-sector group policies leverage state-backed procurement processes, with Banco de Seguros del Estado dominating this segment through its sovereign guarantee position.
Corporates anchor reinsurance capacity. SMEs are climbing the fastest through bancassurance migration.
Coverage Type:
Volume distribution across coverage tiers reflects how regulatory mandates and risk appetite stratify the addressable market into compulsory minimums versus discretionary enhancement layers.
- Comprehensive Coverage:All-risk policies covering multiple peril categories under single contracts. Commercial property and fleet auto programs in Canelones and San José departments favor this structure for administrative efficiency.
- Third Party Liability:Compulsory auto coverage and professional indemnity contracts. Mandatory requirements sustain baseline premium flows regardless of economic cycles.
- Basic Coverage:Named-peril policies with explicit exclusions and lower premium points. Individual health supplemental plans and residential property coverage often utilize this tier.
- Accidental Death:Rider benefits attached to life policies or standalone travel and occupational coverage. Lower technical provision requirements support rapid digital distribution.
Third Party Liability holds regulatory-mandated volume. Comprehensive Coverage is rotating up the share rankings.
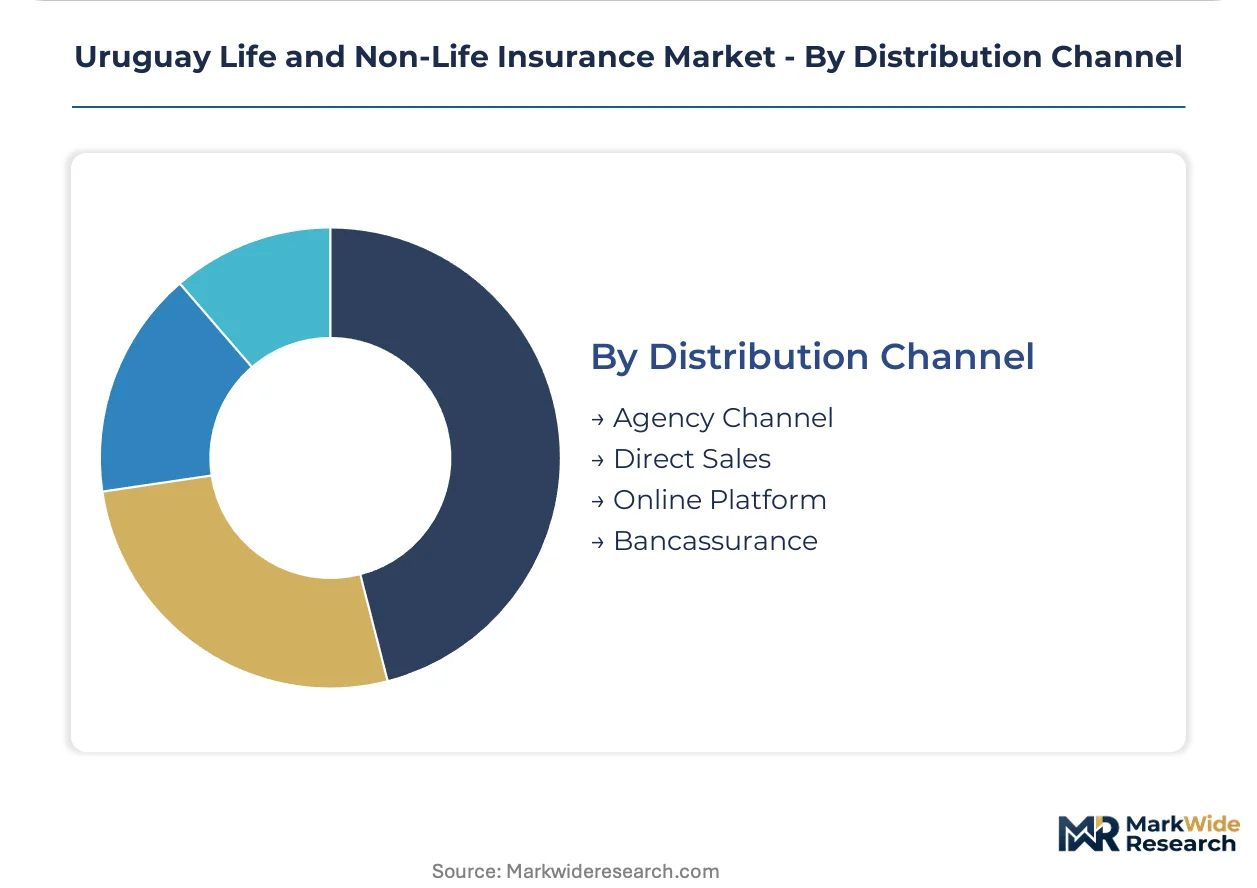
Distribution Channel:
Customer type concentration is reshaping channel economics, with banking integration capturing commercial accounts while digital platforms penetrate individual lines.
- Agency Channel:Traditional intermediary networks with physical presence across Montevideo and departmental capitals. Commission structures face compression as digital alternatives reduce acquisition costs.
- Direct Sales:Insurer-employed representatives targeting large corporate accounts and specialized agricultural risks in Paysandú and Río Negro departments.
- Online Platform:Digital-first distribution with biometric authentication enabling remote policy issuance. Telematics-enabled auto coverage migrates through this channel.
- Bancassurance:Embedded product distribution within retail banking relationships now originates over half of new commercial policies. Credit facility bundling streamlines administration for SMEs.
Bancassurance holds relationship-based capacity. Online Platform is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Uruguay's sub-regions. Montevideo's corporate buyers negotiate aggressively on commercial premiums, while coastal property owners in Maldonado absorb higher rates for catastrophe coverage. Rural agricultural operators in the interior balance cost against parametric payout reliability.
Montevideo
Montevideo concentrates bancassurance channel dominance and digital platform deployment. Banco Central del Uruguay's solvency frameworks tighten capital requirements for insurers headquartered in the capital. The Ciudad Vieja financial district hosts consolidated policy issuance infrastructure serving national corporate accounts.
Maldonado
Maldonado's vacation residence market drives coastal property underwriting concentration. Sub-40% coverage penetration leaves expansion headroom for specialized catastrophe products. Punta del Este's high-value real estate cluster demands reinsurance-heavy structures under 200-year return period capital charges.
Paysandú
Paysandú's soy and cattle operations anchor agricultural risk demand. Satellite-triggered parametric coverage eliminates claims adjustment costs for drought-exposed portfolios. The department's grain belt concentration supports index-based product scaling absent traditional loss verification.
Río Negro
Río Negro's livestock and cropping systems generate specialized coverage requirements. Rural broker networks face compression as direct sales channels penetrate agricultural portfolios. Young's agribusiness cluster experiments with GPS-linked telematics for fleet auto programs.
Canelones
Canelones' manufacturing and logistics sectors consolidate SME purchasing through banking relationships. Transport operators adopt usage-based auto coverage with real-time premium calculations. The department's industrial corridor feeds bancassurance channel growth for commercial property lines.
Uruguay Life and Non-Life Insurance Market Competitive Landscape
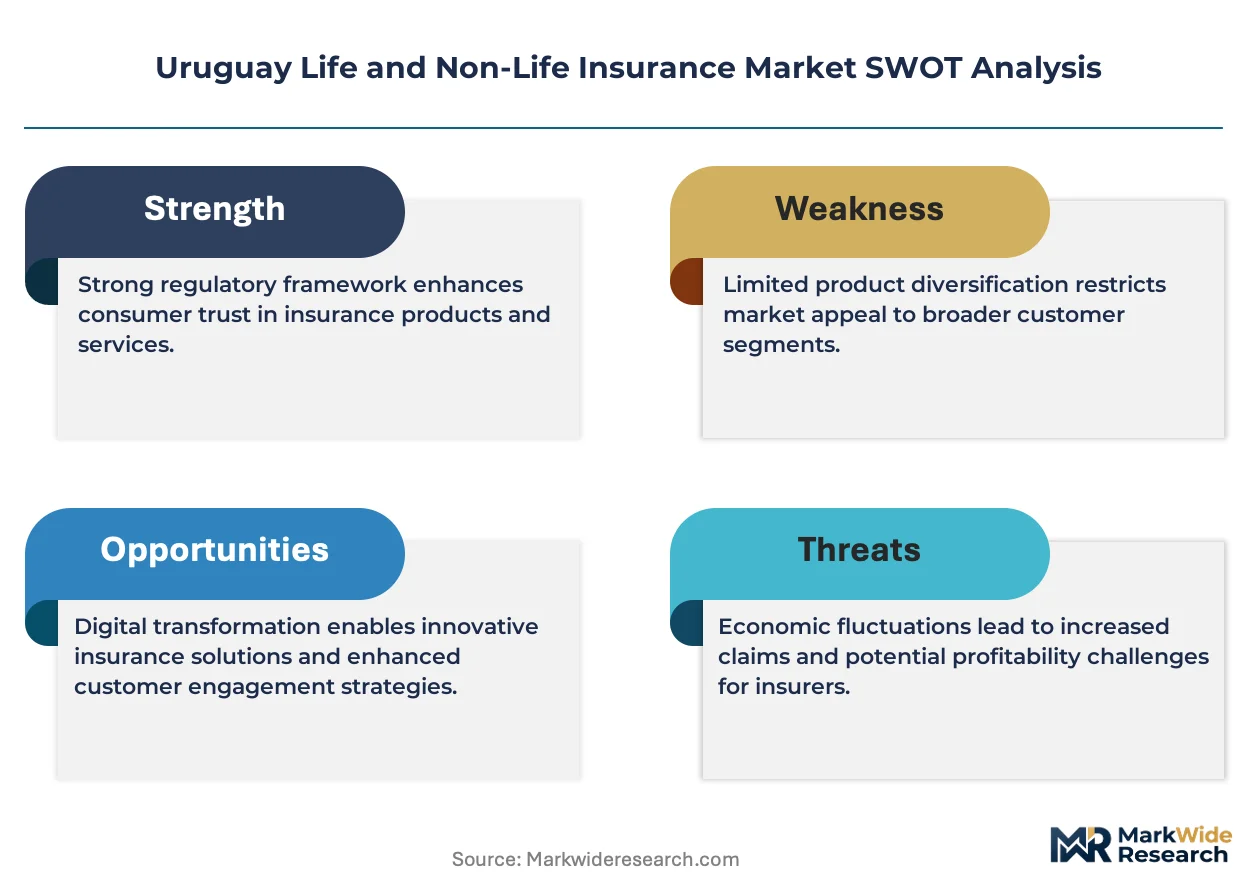
Capability concentration sits with state-backed incumbents; scale advantage sits with diversified regional carriers. The market structures around three tiers: sovereign-guaranteed domestic players, Latin American regional specialists, and global reinsurance-dependent underwriters. Two strategic archetypes dominate—bancassurance-integrated distributors and agricultural risk specialists. Competitive moves center on embedded banking partnerships and parametric product development.
Within the state-backed tier, Banco de Seguros del Estado occupies a sovereign-guaranteed position anchoring public-sector group policy procurement. Seguros SURA and Mapfre exemplify regional specialists competing through agricultural risk expertise and digital platform investments respectively. These three represent distinct competitive vectors: sovereign procurement access, rural underwriting specialization, and technology-enabled distribution capture.
| Leading Market Players |
|---|
| Banco de Seguros del Estado |
| Seguros SURA |
| Mapfre |
| Porto Seguros |
| SBI Seguros |
| Surco Seguros |
| Sancor Seguros |
| Zurich Santander |
| Berkley Uruguay Seguros |
| Others |
Value Network & Pricing Analysis
Reinsurance capacity concentration in Lloyd's and Miami treaty markets determines both premium tier spreads and supply chain configuration for Uruguayan carriers. Catastrophe-exposed property lines face 200-year return period capital charges that compress margins on standard tiers while elevating premium pricing for coastal and agricultural risks.
Pricing Analysis
After-sales revenue from policy renewals and rider attachments drives lifetime value across Uruguay's insurance sector. Three-tier pricing structure across premium, standard, and economy levels stratifies by risk selection intensity and claims service levels. Pricing pressure stems from Banco Central del Uruguay's reference pricing mandates for compulsory auto coverage. Individual retail buyers exhibit highest price sensitivity, while corporate accounts with embedded banking relationships absorb premium tiers for administrative consolidation.
Supply Chain Analysis
Export-control regimes on satellite data and parametric index technology restrict flows of drought-modeling capabilities to Uruguayan agricultural underwriters. Risk modeling software and catastrophe data feeds draw from United States, United Kingdom, and Bermuda. Reinsurance treaty capacity, actuarial talent, and core system platforms anchor the supply base. Single-source vulnerability concentrates in legacy policy administration systems from the 1990s. Distribution runs through bancassurance partnerships with Montevideo-based retail banks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through SME consolidation into banking-embedded purchasing, fragmenting traditional broker intermediation and compressing acquisition economics for standalone distributors.
For Market Incumbents: Harden catastrophe risk selection through selective geographic withdrawal from Maldonado and Rocha coastal zones where 200-year return period capital charges erode returns. Deepen backward integration into parametric index product development to capture agricultural risk margins without reinsurance-heavy structures. Threat vector: fintech-enabled digital distributors capturing individual lines through biometric authentication protocols. For New Entrants and Emerging Players: Build out white-space positions in cyber liability coverage for Montevideo's fintech sector, where sparse local claims history has deterred incumbent pricing confidence. Target underpenetrated vacation residence markets in coastal departments with satellite-triggered catastrophe products. Go-to-market angle: direct digital issuance bypassing compressed agency commission structures. For Investors and Strategic Acquirers: The market sits at a regulatory modernization phase that favors technology-enabled distributors with embedded banking partnerships over legacy agency networks. Long-term viability centers on bancassurance channel control and parametric product IP. Acquisition archetype: mid-tier carriers with agricultural risk expertise and SURA-compatible underwriting platforms. Signal to watch: Banco Central del Uruguay's digital authentication standard finalization as channel inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Satellite-triggered drought coverage eliminates claims adjustment costs for Paysandú soy operations. |
| Bancassurance Partnership Expansion | Embedded distribution within retail banking relationships captures over half of new SME commercial policies. |
| Core System Modernization | Replacement of 1990s policy administration platforms enables real-time digital distribution capture. |
| Cyber Risk Modeling Investment | Local claims history development supports pricing for Montevideo fintech sector liability products. |
| Reinsurance Treaty Restructuring | Alternative capital sources reduce dependency on Lloyd's and Miami markets for catastrophe capacity. |
Research Methodology
Initial hypotheses were tested against primary input from insurance product managers, actuarial directors, bancassurance channel heads, and central bank supervisory staff and refined through secondary validation. Stakeholder interviews combined with regulatory filings from Banco Central del Uruguay, Mercosur integration protocols, and reinsurance treaty market reports. Bottom-up policy issuance data triangulated against top-down premium flow estimates across the analysis window.
Demand-supply balance framing anchored the forecast framework across product type, customer segment, distribution channel, and departmental geography dimensions. CAGRs derived from historical premium trajectory analysis adjusted for pension reform linkage effects and digital platform penetration curves. Modeled inputs included actuarial mortality table revisions, catastrophe loss modeling updates, and bancassurance channel share migration patterns.
Sensitivities concentrate around Mercosur regulatory harmonization timing, central bank solvency framework revisions, and reinsurance capacity pricing volatility. Forecasts reflect documented assumptions on pension system conversion rates and digital authentication adoption curves. Material shifts in Banco Central del Uruguay's catastrophe capital charge calculations or biometric verification protocol mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Norway Life and Non-Life Insurance Market
Life and Non Life Insurance
Czech Republic Life & Non-Life Insurance Market
Life and Non Life Insurance
Teenager Life Insurance Market
Life and Non Life Insurance
Life Reinsurance Market
Life and Non Life Insurance
Children Life Insurance Market
Life and Non Life Insurance
Indonesia Life and Non-Life Insurance Market
Life and Non Life Insurance
Greece Life and Non-Life Insurance Market
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market
Life and Non Life Insurance
Japan Life and Non-Life Insurance Market
Life and Non Life Insurance
Finland Life and Non-Life Insurance Market
Life and Non Life Insurance
Argentina Life and Non-Life Insurance Market
Life and Non Life Insurance
South Korea Life & Non-Life Insurance Market
Life and Non Life Insurance
Denmark Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia Pacific Life & Non-Life Insurance Market
Life and Non Life Insurance
Colombia Life and Non-Life Insurance Market