
 University Management System Market | 2026-2036
University Management System Market Size, Share, and Industry Trends Forecast 2026-2036
University Management System Market Insights
Market Overview
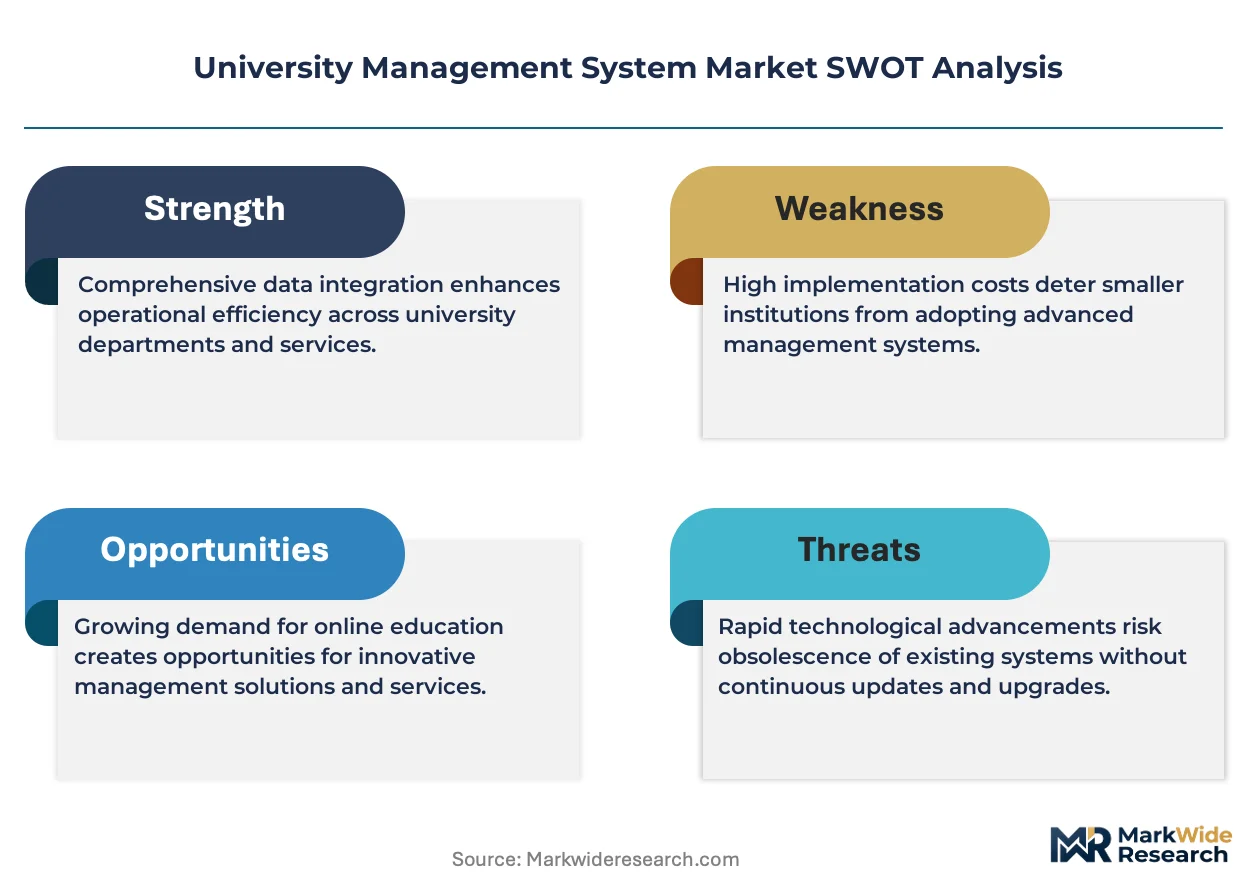
Modular platform bundling is pivoting how procurement committees evaluate vendor proposals across higher education institutions. Oracle leverages its database heritage to anchor multi-module contracts with large state university systems. Workday sustains competitive pressure through cloud-native financial and human capital integration that appeals to research-intensive campuses.
A university management system constitutes an integrated software architecture that orchestrates student lifecycle operations, academic scheduling, financial aid processing, and institutional compliance reporting through centralized data repositories and API-connected modules. Its primary commercial purpose is to replace fragmented legacy databases with unified platforms that reduce administrative overhead and satisfy accreditation data requirements. Cloud-based deployment now leads segment preference as campuses prioritize remote accessibility and reduced IT staffing burdens, while student management functionality captures the deepest margin pools due to recurring enrollment-cycle dependencies. Course management tools represent the fastest-expanding service category as hybrid instruction models permanently alter faculty workflow expectations.
FERPA privacy mandates from the US Department of Education shape product development priorities for any vendor seeking American institutional contracts, while GDPR compliance requirements from European data protection authorities constrain cross-border hosting architectures for international campus networks. ISO 27001 certification has become a non-negotiable procurement filter across OECD education markets. Stakeholders must monitor how artificial intelligence grading and admissions tools trigger emerging algorithmic accountability regulations before embedding automated decision systems into core platforms.
Market Dynamics
Cloud migration mandates from education technology regulators are forcing public research universities to replace fragmented legacy databases with unified platforms that reduce administrative overhead and satisfy accreditation data requirements.
Growth Catalysts
- FERPA compliance pressure:The US Department of Education's privacy mandates compel American institutions to upgrade student data management systems, creating procurement urgency for vendors with certified architectures.
- Hybrid instruction permanence:Faculty workflow expectations have permanently shifted toward blended learning models, accelerating demand for course management modules that synchronize in-person and remote scheduling.
- API-connected modular bundling:Procurement committees now evaluate vendor proposals on interoperability standards, favoring platforms that integrate financial aid processing with human capital systems through standardized interfaces.
Market Restraints
- ISO 27001 certification bottleneck:The certification timeline and audit costs create barriers for smaller vendors seeking OECD education market access, concentrating supply among established enterprise software providers.
- Legacy system lock-in:Decades of institutional data trapped in proprietary formats raise switching costs for universities, delaying replacement cycles despite regulatory pressure.
- Cross-border hosting complexity:GDPR constraints on European data residency conflict with cloud cost optimization strategies, forcing international campus networks into fragmented architectural decisions.
Strategic Opportunities
- Algorithmic accountability preparation:Vendors embedding artificial intelligence grading and admissions tools can capture first-mover advantage before emerging regulations formalize compliance requirements.
- Research-intensive campus specialization:Cloud-native financial and human capital integration tailored to grant administration workflows addresses unmet needs in the R1 university segment.
- Federal student aid workflow automation:Platforms that streamline Title IV compliance reporting reduce administrative burden during enrollment cycles, creating recurring dependency.
Industry Challenges
- Interoperability skill scarcity:Campus IT departments lack sufficient API architecture expertise to manage multi-module integrations, forcing reliance on vendor professional services.
- Data migration complexity:Centralized repository transitions from siloed departmental databases require extensive cleansing and mapping, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | University Management System Market |
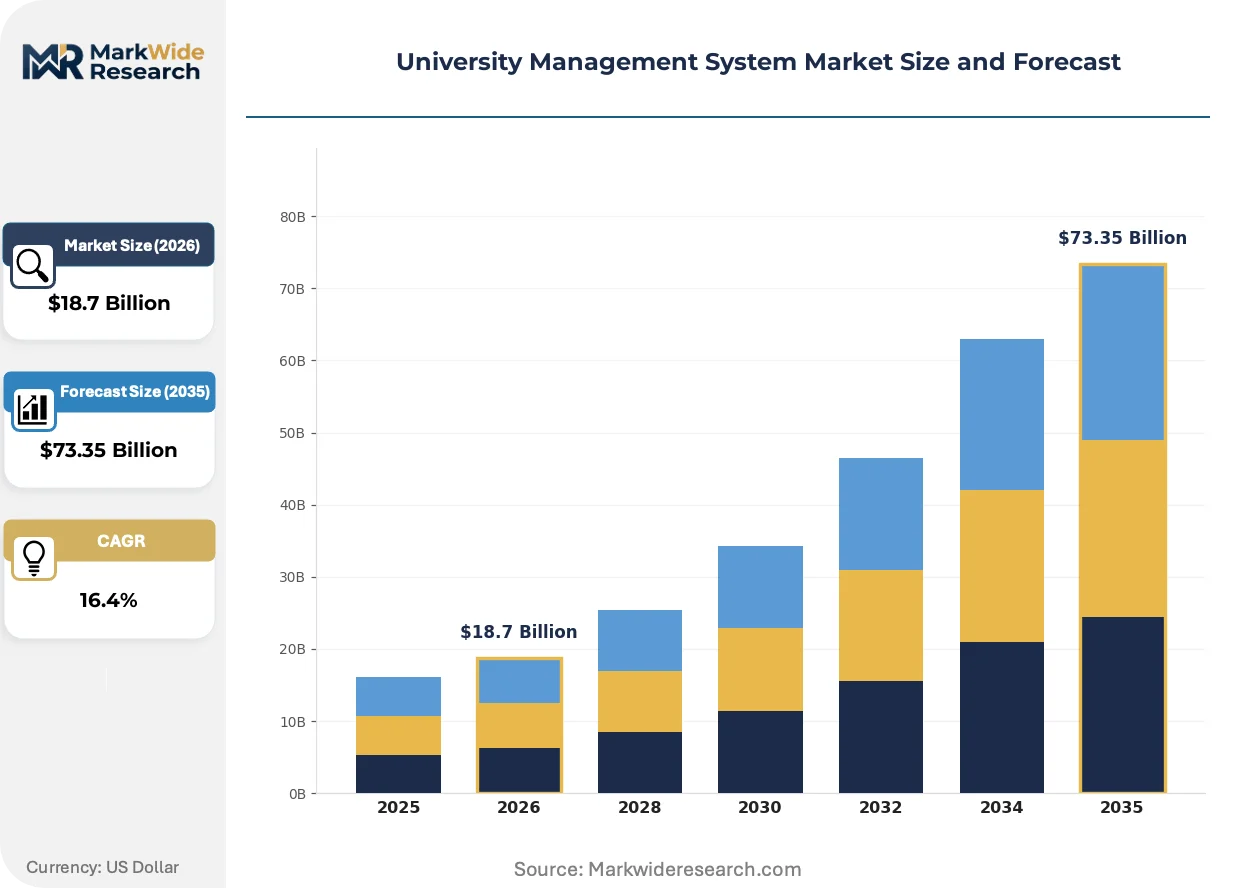
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Service Type: Student Management, Course Management, Financial Management, Library Management End User: Universities, Colleges, Online Education Providers, Vocational Institutes Feature: Registration System, Grading System, Attendance Tracking, Communication Tools |
| Companies Covered | Ellucian Company L.P., Oracle, Workday, SAP, Blackbaud, Jenzabar, Foradian Technologies, MeritTrac Services Pvt Ltd, Libsys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
University Management System Market Trends and Innovations
Artificial intelligence capabilities are embedding into core administrative workflows, reshaping how platforms handle admissions screening, academic advising, and predictive retention analytics.
Machine learning algorithms are integrating into enrollment management systems to forecast student persistence risk and automate intervention triggers. Large state university systems are adopting these tools fastest, driven by retention rate accountability metrics tied to state funding formulas. This capability compression is reducing reliance on third-party analytics vendors and shifting margin capture toward platform providers.
The EU AI Act's risk classification framework is imposing algorithmic transparency requirements on automated decision systems used in admissions. Vendors must now document training data provenance and decision logic for high-risk applications. European campus networks are responding by demanding explainability features that American institutions have not yet prioritized.
Subscription-based platform access is displacing perpetual license models as procurement committees prioritize operational expenditure flexibility. Research-intensive campuses in the United States are leading this transition, negotiating multi-year enterprise agreements that bundle implementation services. This financing rotation reduces upfront capital requirements but increases long-term vendor dependency.
University Management System Market Segmentation
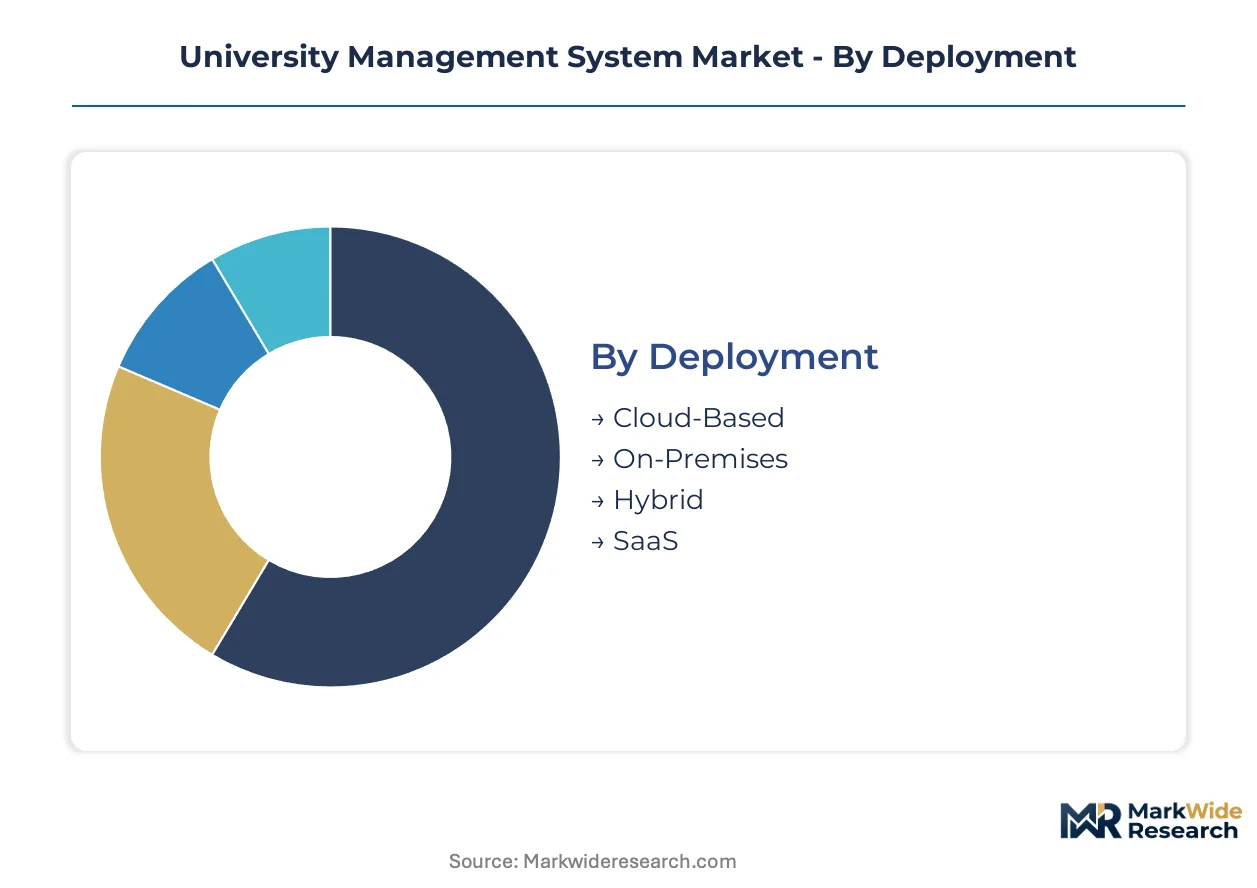
Segmentation in the university management system market reveals how procurement priorities diverge across institutional archetypes. Deployment preferences separate cost-conscious community colleges from research universities with dedicated IT infrastructure. Service type selection maps directly to regulatory exposure and enrollment complexity.
Deployment:
Buyers in this category separate by internal technical capacity and risk tolerance for data sovereignty.
- Cloud-Based:Multi-tenant architectures with vendor-managed infrastructure eliminate capital expenditure for server procurement. State university systems in the United States concentrate procurement here, driven by federal student aid compliance deadlines that demand rapid system deployment without on-site hardware provisioning.
- SaaS:Subscription licensing with automatic feature updates reduces version fragmentation across campus departments. Online education providers represent the densest demand cluster, as their distributed faculty models require instant remote accessibility without VPN dependencies.
- On-Premises:Self-hosted installations retain full data custody within institutional firewalls.
- Hybrid:Split architectures isolate sensitive records locally while pushing routine operations to cloud tiers.
Volume sits with Cloud-Based; growth tilts toward SaaS.
Service Type:
Commercial margin pools track regulatory touch frequency and enrollment cycle recurrence.
- Student Management:Lifecycle orchestration spanning admissions through alumni relations, with FERPA-compliant data handling at every transaction point. Public research universities anchor procurement volume, as Title IV federal aid workflows create recurring dependency on enrollment verification modules.
- Course Management:Scheduling engines synchronizing in-person and remote instruction with learning management system interoperability. Hybrid instruction permanence across North American campuses accelerates replacement cycles for legacy scheduling tools.
- Financial Management:Grant administration and tuition billing with audit trail preservation.
- Library Management:Digital asset cataloging and interlibrary loan coordination.
Revenue concentrates in Student Management; expansion accelerates most quickly in Course Management.
End User:
Institutional scale and funding structure determine module bundling depth and implementation timeline.
- Universities:Comprehensive platform deployments integrating financial aid, human capital, and research administration. Large state systems in the United States drive enterprise contract values, with procurement committees evaluating interoperability standards across multi-campus networks.
- Colleges:Streamlined configurations prioritizing student information systems and basic course scheduling. Regional accreditation requirements shape vendor selection criteria.
- Online Education Providers:Scalable architectures supporting asynchronous enrollment spikes and distributed faculty.
- Vocational Institutes:Competency-based tracking aligned to workforce certification pathways.
Contract value peaks with Universities; deployment velocity favors Online Education Providers.
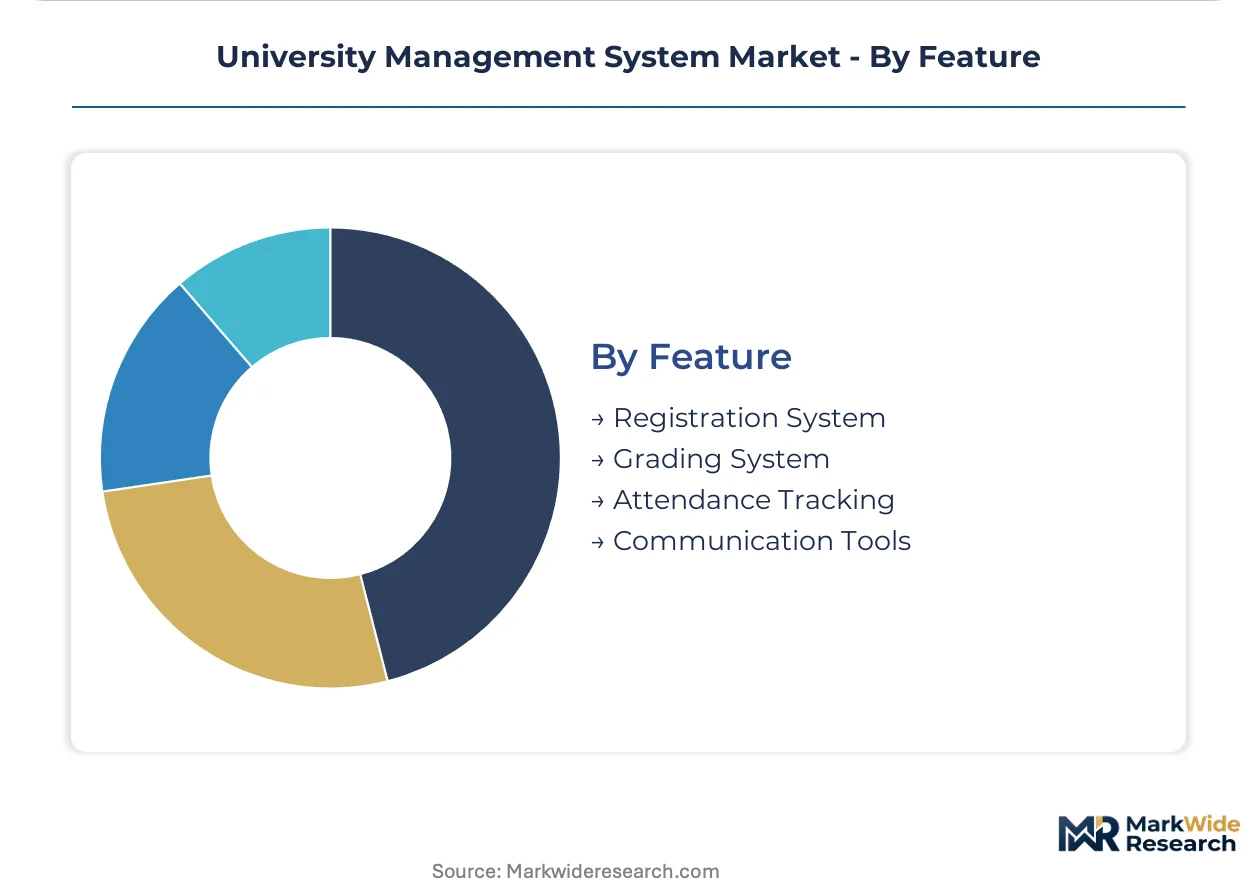
Feature:
Functional priority reflects staff automation pressure and student experience investment levels.
- Registration System:Enrollment bottleneck management with prerequisite validation and waitlist automation. Peak load engineering determines vendor suitability for large public institutions.
- Grading System:Transcript integrity with audit trails satisfying accreditation review.
- Attendance Tracking:Biometric and geolocation verification for financial aid eligibility documentation.
- Communication Tools:Integrated messaging replacing fragmented email and portal announcements.
Implementation priority runs through Registration System; feature development investment flows toward Communication Tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform development concentrates in the United States while procurement demand distributes across OECD education markets. Consumption patterns diverge sharply between federal compliance-driven American institutions and GDPR-constrained European networks.
United States
Large state university systems drive enterprise contract volumes through Title IV federal aid workflow mandates. FERPA compliance deadlines from the US Department of Education force rapid system replacements. California's public university clusters anchor west coast procurement, with multi-campus networks negotiating interoperability standards for research administration.
Germany
Research-intensive technical universities prioritize grant administration modules aligned to DFG funding structures. The EU AI Act's risk classification framework imposes algorithmic transparency requirements on admissions automation. Bavaria's Munich-anchored campus networks lead adoption of explainable AI features for high-stakes student decisions.
United Kingdom
Russell Group institutions concentrate procurement in cloud-native financial and human capital integration. GDPR constraints from the Information Commissioner's Office shape data residency architectures for international student populations. London's dense higher education cluster drives premium-tier platform demand for research collaboration tools.
India
Central universities under UGC oversight expand digital campus infrastructure through national education policy mandates. The National Academic Depository creates interoperability requirements for transcript verification systems. Karnataka's Bangalore-centered technical institutes anchor south Indian procurement for scalable enrollment management.
Australia
Group of Eight universities prioritize international student lifecycle management amid enrollment volatility. The Tertiary Education Quality and Standards Agency imposes audit trail requirements for compliance reporting. New South Wales' Sydney-centered research campuses lead adoption of predictive retention analytics for government funding accountability.
University Management System Market Competitive Landscape
The competitive structure tilts toward database heritage providers anchoring multi-module contracts with state university systems. Enterprise software incumbents leverage existing institutional relationships to bundle student information systems with financial and human capital modules. Strategic archetypes separate into cloud-native challengers, legacy platform modernizers, and specialized research administration vendors. Dominant competitive moves include API interoperability investments and subscription licensing transitions displacing perpetual models.
Among database-centric incumbents, Oracle and SAP occupy positions anchoring enterprise procurement through infrastructure integration advantages. Workday represents the cloud-native archetype competing on financial-human capital unification for research-intensive campuses. Ellucian Company L.P. exemplifies the education-specialized tier with concentrated presence in North American public institutions. These three anchors illustrate how vendor selection maps to institutional scale and existing technology stack commitments.
| Leading Market Players |
|---|
| Ellucian Company L.P. |
| Oracle |
| Workday |
| SAP |
| Blackbaud |
| Jenzabar |
| Foradian Technologies |
| MeritTrac Services Pvt Ltd |
| Libsys |
| Others |
Pricing and Supply Chain Analysis
ISO 27001 certification requirements from education technology regulators gate qualified supply and premium-tier pricing access for university management system vendors, concentrating procurement among established providers with audit-proven architectures while excluding smaller competitors from enterprise contract contention.
Pricing Analysis
Margin tightening in cloud-native tiers reflects the shift from perpetual licensing to subscription SaaS models across North American public universities. Three-tier pricing structure across premium, standard, and economy levels separates Oracle's database-anchored enterprise bundles from Workday's financial-human capital unification and Jenzabar's mid-market configurations. Price differentiation hinges on FERPA compliance certification depth and API interoperability breadth. Pricing pressure stems from federal student aid workflow automation demands compressing implementation timelines. Community colleges exhibit highest price sensitivity due to capital expenditure constraints, while large state university systems prioritize total cost of ownership over upfront licensing.
Supply Chain Analysis
Returns and refurbishment flows for on-premises hardware legacy systems create reverse-logistics complexity as campuses migrate to cloud-native architectures, with data migration services and decommissioning support becoming margin-capture opportunities for incumbent vendors. Software development concentrates in the United States, India, and Germany, with Bangalore-centered technical institutes feeding engineering talent into platform R&D. Raw material dependencies span cloud infrastructure from AWS, Azure, and Google Cloud, alongside specialized API middleware and cybersecurity audit services. Single-source vulnerability concentrates in hyperscaler hosting agreements, where vendor lock-in risks complicate multi-cloud strategies. Distribution runs through direct enterprise sales teams and certified implementation partners serving regional campus clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race where vendors pursue downstream control over professional services and data migration capabilities to capture implementation margin and deepen institutional dependency.
For Market Incumbents: Deploy API interoperability investments as the primary defensive lever against cloud-native challengers. Deepen vertical integration into data migration and cleansing services to capture implementation margin and extend contract duration. Counter Workday's financial-human capital unification threat by bundling research administration modules with existing student information system relationships. Fortify position against algorithmic accountability regulations by pre-building explainable AI documentation for admissions automation. For New Entrants and Emerging Players: The EU AI Act's risk classification framework in Germany and France opens a window for explainable AI specialization targeting European research-intensive universities. White-space opportunity concentrates in vocational institute competency-based tracking aligned to workforce certification pathways, where incumbent presence remains thin. Penetrate India's central university segment through National Academic Depository interoperability compliance as a go-to-market wedge. Target Australia's Group of Eight international student lifecycle management volatility with predictive retention analytics as entry point. For Investors and Strategic Acquirers: Oracle's multi-module contract expansion with California public university clusters is the leading indicator that database heritage providers are successfully defending against cloud-native displacement. Long-term viability favors vendors with ISO 27001 certification and FERPA audit history, suggesting acquisition targets among education-specialized firms with compliance-proven architectures. Monitor EU AI Act enforcement actions against non-compliant admissions automation as inflection signal for explainable AI feature demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Investment | Standardized interfaces enable Ellucian and Oracle to bundle financial aid with human capital modules across multi-campus networks. |
| Subscription Licensing Transition | SaaS pricing models reduce upfront capital barriers for community colleges while increasing long-term vendor dependency and recurring revenue. |
| Algorithmic Accountability Preparation | Explainable AI documentation for admissions automation addresses EU AI Act transparency mandates before formal compliance deadlines. |
| Research Administration Specialization | Grant administration workflow integration targets R1 universities with DFG-aligned modules in Germany and NSF reporting in the United States. |
| Data Migration Service Expansion | Professional services for legacy system transitions capture implementation margin and extend contract duration with institutional clients. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with university CIOs, education technology procurement officers, platform integration specialists, and federal student aid compliance directors with secondary validation from EDUCAUSE reports, US Department of Education FERPA guidance documents, and OECD education technology policy briefs. Bottom-up campus deployment tracking and top-down vendor revenue triangulation reconciled volume estimates across the analysis window.
Data-stream reconciliation across deployment model, institutional scale, service type bundling, and regional regulatory framework dimensions shaped the forecast framework. CAGRs derived from enrollment cycle recurrence patterns, cloud migration mandate timelines, and replacement cycle compression factors. Federal student aid compliance deadline schedules and EU AI Act implementation phases served as industry-specific forecast inputs throughout the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for hybrid cloud architectures would alter the outlook if GDPR data residency constraints force fragmented deployments. Forecasts reflect assumptions about regulatory enforcement consistency and campus IT staffing capacity. Practitioners should monitor EU AI Act algorithmic transparency rulings and US Department of Education FERPA audit frequency changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
VR Education Market
Education & Training
Talent As a Service Market
Education & Training
Asia-Pacific Corporate Training Market
Education & Training
United States Soft Skills Training Market
Education & Training
IT Training Market
Education & Training
Asia Big Data Analytics in Education Market
Education & Training
Higher Education Technology Market
Education & Training
Homeschooling Market
Education & Training
Braille Book Market
Education & Training
Executive Coaching and Leadership Development Market
Education & Training
GCC E-Learning Market
Education & Training
GCC Massive Open Online Course (MOOC) Market
Education & Training
Digital Marketing Courses Market
Education & Training
Cognitive Assessment and Training Market
Education & Training
Cloud-Based Training Software Market
Education & Training
Europe K12 Education Market