
 United States Private Equity Market | 2026-2036
United States Private Equity Market Size, Share, and Industry Trends Forecast 2026-2036
United States Private Equity Market Analytics
Institutional-grade fund structures is rotating toward longer-duration vehicles with enhanced LP governance provisions. Blackstone leverages its scale across credit, real estate, and private equity to sustain multi-strategy capital deployment. KKR anchors its position through infrastructure and insurance-linked permanent capital vehicles. Apollo Global Management differentiates via integrated asset services and yield-oriented strategies that compete directly with traditional fixed income.
Private equity denotes pooled capital investment in non-publicly traded companies, employing leveraged buyouts, growth capital, and distressed restructuring to generate returns through operational improvement and financial engineering rather than public market multiples. Buyout-focused limited partnerships dominate capital flows and fee generation, while technology and healthcare verticals attract premium entry multiples due to recurring revenue profiles and regulatory moats. Early-stage venture funds occupy a narrower but strategically significant lane for LP portfolio construction.
SEC registration requirements, ERISA fiduciary standards, and the Investment Advisers Act shape capital formation, fee transparency, and LP access to retail channels. The SEC's private fund adviser rules mandate quarterly statements and audited financials, tightening operational compliance for managers. Stakeholders must monitor evolving accredited investor definitions and state-level fund formation incentives as structural determinants of competitive positioning.
Market Dynamics
The SEC's private fund adviser rules are compressing fee opacity and mandating quarterly statement disclosures, forcing general partners to restructure carry arrangements and operational workflows.
Growth Catalysts
- Texas and Florida fund formation:State tax regimes and population inflows concentrate capital deployment in these jurisdictions, drawing general partner headquarters and portfolio company relocations.
- Hospital system operational partnerships:Healthcare buyout activity deepens as hospital systems seek private equity partners for cost restructuring and clinical network optimization.
- ERISA fiduciary channel expansion:Defined benefit pension allocations to alternative assets sustain limited partner commitment levels despite public market volatility.
Market Restraints
- SEC disclosure compliance costs:The Investment Advisers Act mandates audited financials and fee transparency, elevating back-office expenditures for emerging managers.
- Accredited investor definition constraints:Regulatory thresholds limit retail capital participation, capping fund formation scale for strategies targeting mass-affluent segments.
- Leverage availability cyclicality:Federal Reserve rate policy compresses debt financing capacity for buyout transactions, elevating equity contribution requirements.
Strategic Opportunities
- Insurance-linked permanent capital vehicles:KKR and competitors anchor strategies through balance sheet integration, reducing redemption risk and fee sensitivity.
- Distressed restructuring specialization:Credit cycle positioning enables operational turnaround expertise deployment across healthcare and energy verticals.
- State-level fund formation incentives:Delaware and Nevada regulatory frameworks attract master-feeder structures and blocker corporation domiciliation.
Industry Challenges
- Operational due diligence talent scarcity:Value creation teams with sector-specific expertise command premium compensation, compressing net returns.
- Portfolio company integration complexity:Multi-platform rollups require ERP harmonization and culture alignment across acquired entities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Private Equity Market |
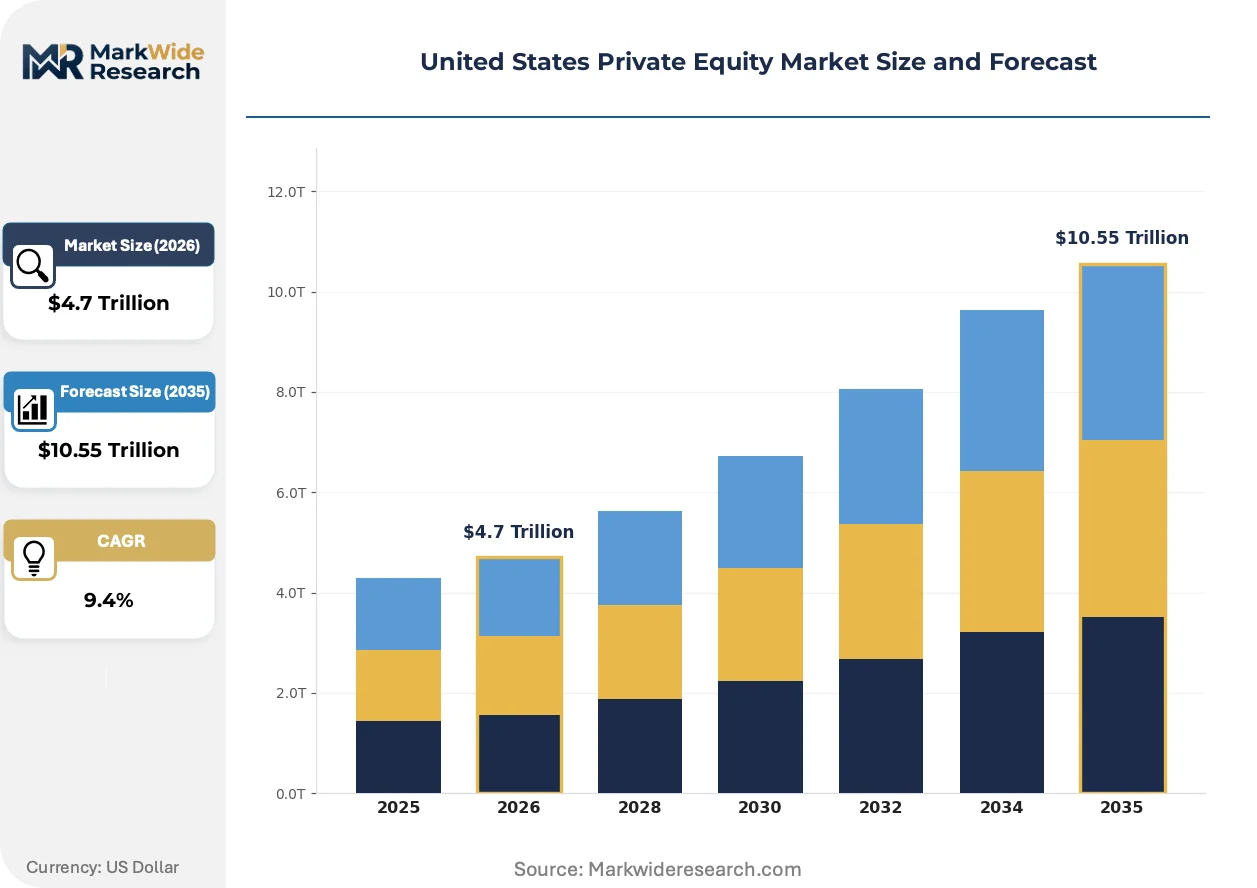
| Market Size in 2026 | $4.7 Trillion |
| Market Size in 2035 | $10.55 Trillion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Early Stage, Growth Stage, Buyout, Mezzanine Industry Vertical: Healthcare, Technology, Consumer Goods, Manufacturing Fund Structure: Closed-End Fund, Open-End Fund, Limited Partnership, Venture Fund Investor Type: Institutional Investors, High-Net-Worth Individuals, Family Offices, Endowments |
| Companies Covered | TPG, Clayton, Dubilier & Rice, KKR, Apollo Global Management, Carlyle Group, Blackstone, Hellman & Friedman, Bain Capital, Thoma Bravo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Private Equity Market Evolving Landscape
Capital formation is rotating toward longer-duration vehicles with enhanced limited partner governance, while technology-enabled sourcing and data analytics reshape origination efficiency.
Artificial intelligence-driven due diligence platforms are supplanting traditional manual financial analysis in sponsor screening processes. Mid-market buyout firms deploy natural language processing for management team assessment and customer contract review. This compression of evaluation timelines is narrowing exclusivity periods and elevating auction competitiveness.
The SEC's private fund adviser rules mandate quarterly statements and audited financials, tightening operational compliance across registered investment advisers. General partners restructure administrative workflows and engage third-party fund administrators to satisfy documentation requirements. Emerging managers face disproportionate cost burdens relative to assets under management.
Institutional limited partners increasingly unbundle advisory relationships from capital commitments, engaging independent consultants for manager selection. Pension funds and endowments negotiate direct fee arrangements rather than accepting bundled placement agent structures. This disintermediation concentrates in California and New York public pension systems with scale to justify internal due diligence capabilities.
United States Private Equity Market Segmentation
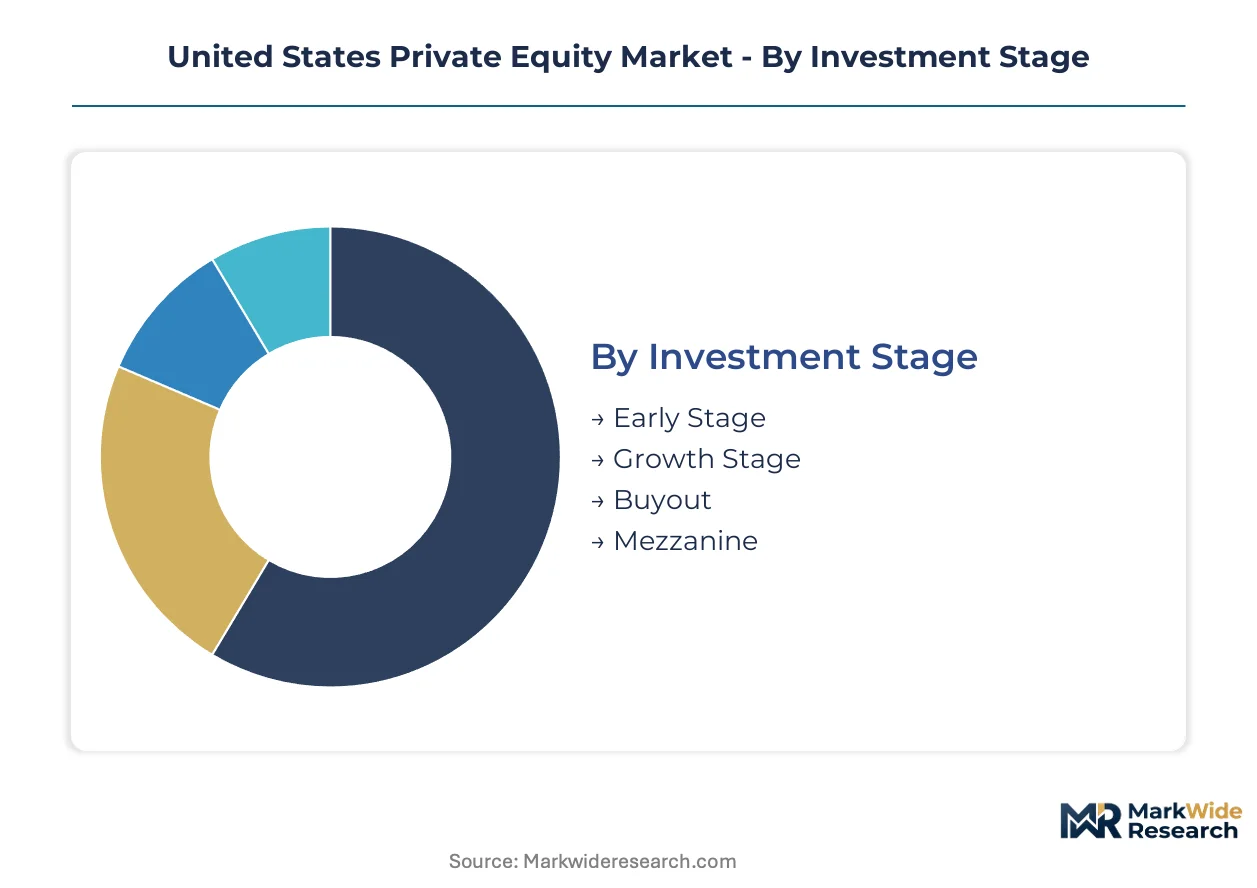
Segmentation in the United States private equity market reveals how capital flows concentrate across risk-return profiles and regulatory constraints. Fund managers structure vehicles to match liability durations of specific investor classes while optimizing for fee generation and governance flexibility.
Investment Stage:
Buyout and growth-stage deployments capture the deepest margin pools through management fees on committed capital and performance-based carried interest.
- Early Stage:Seed and Series A commitments target pre-revenue enterprises with high technical risk. California and Massachusetts concentrate venture formation activity, where technology transfer from research institutions feeds deal pipeline density.
- Growth Stage:Expansion capital injections finance revenue-scaling without ownership dilution. Healthcare and enterprise software verticals in Texas and Florida attract premium entry multiples due to recurring revenue predictability and state tax advantages.
- Buyout:Majority-control transactions employ leverage to amplify equity returns through operational restructuring.
- Mezzanine:Subordinated debt with equity participation rights fills capital structure gaps in middle-market acquisitions.
Buyout holds installed capacity. Growth Stage is rotating up the share rankings.
Industry Vertical:
Healthcare commands the steepest valuation multiples while technology delivers the fastest deployment velocity.
- Healthcare:Hospital systems and physician practice management attract buyout capital for cost consolidation. Texas, Florida, and Arizona concentrate ambulatory surgery center rollups where Medicare reimbursement shifts incentivize outpatient migration.
- Technology:Software-as-a-service platforms with net revenue retention above 120% justify premium entry prices. San Francisco Bay Area and Seattle maintain origination dominance despite distributed workforce trends.
- Consumer Goods:Direct-to-consumer brands and specialty retail chains target middle-market consolidation.
- Manufacturing:Industrial automation and precision components attract operational improvement specialists.
Healthcare holds installed capacity. Technology is rotating up the share rankings.
Fund Structure:
Closed-end limited partnerships dominate fee generation while open-end vehicles reduce capital deployment friction.
- Closed-End Fund:Fixed-life vehicles with 10-12 year terms lock in committed capital through J-curve periods. Delaware domiciliation concentrates here due to established case law on fiduciary duties and fee litigation.
- Open-End Fund:Evergreen structures permit periodic subscriptions and redemptions, aligning with insurance company balance sheet requirements. KKR and competitors anchor permanent capital vehicles through this format.
- Limited Partnership:The standard GP-LP governance framework allocates investment discretion to general partners.
- Venture Fund:Early-stage vehicles with higher risk tolerances and longer capital lockups.
Closed-End Fund holds installed capacity. Open-End Fund is rotating up the share rankings.
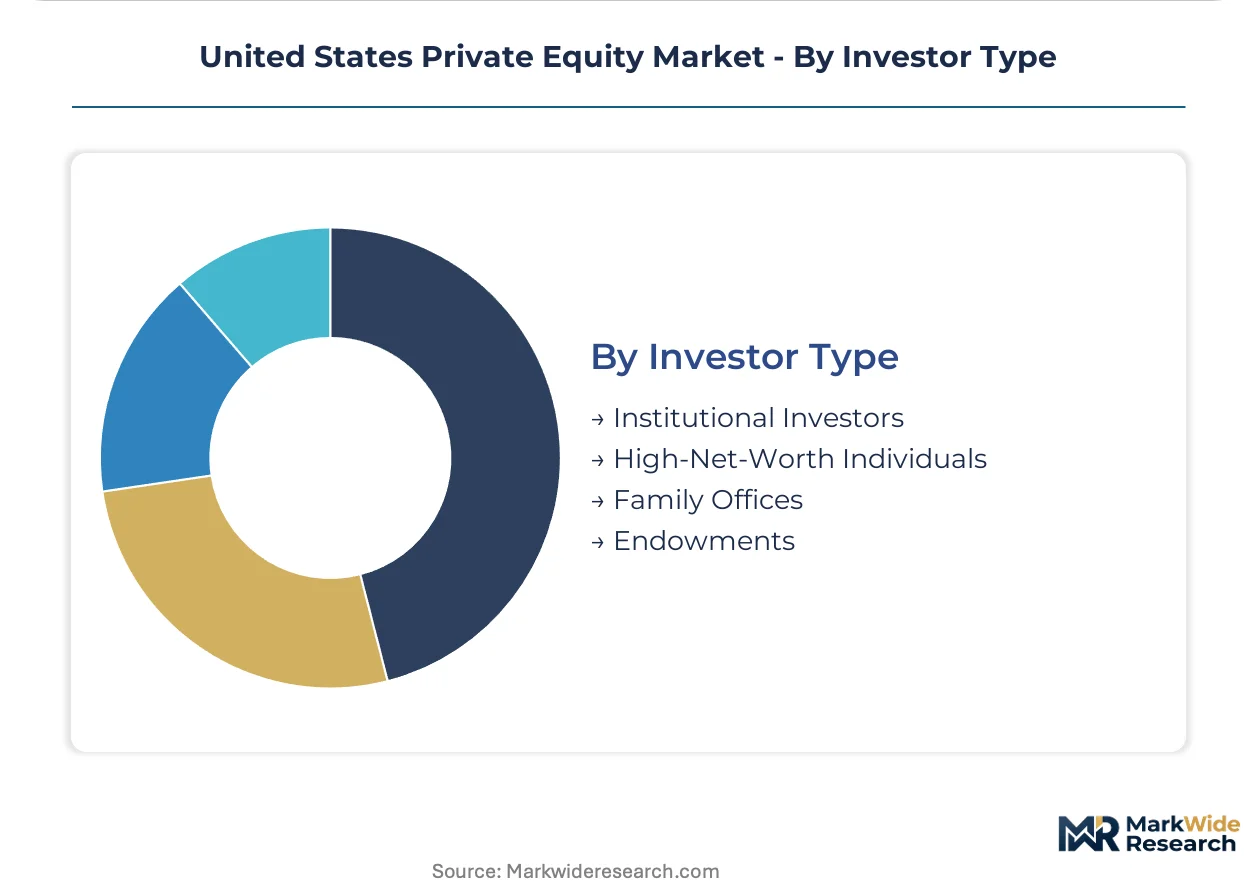
Investor Type:
Institutional capital supplies the deepest commitment pools while family offices offer the fastest decision timelines.
- Institutional Investors:Public pension funds and insurance companies allocate 15-25% of portfolios to alternatives. California Public Employees' Retirement System and New York State Common Retirement Fund negotiate direct fee arrangements, bypassing placement agent intermediaries.
- High-Net-Worth Individuals:Accredited investor thresholds limit retail participation to those with $200,000 annual income or $1 million net worth. SEC registration requirements under the Investment Advisers Act constrain marketing to this segment.
- Family Offices:Single-family and multi-family vehicles deploy patient capital with concentrated position tolerance.
- Endowments:University and foundation investment offices pioneered the Yale Model allocation to illiquid alternatives.
Institutional Investors hold installed capacity. Family Offices is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fund formation concentrates in jurisdictions offering favorable tax treatment and regulatory clarity. General partner headquarters cluster where state policy and capital access align.
Texas
Energy transition capital and healthcare system consolidation drive deployment velocity. The Texas Business Organizations Code enables flexible limited partnership structures. Dallas and Houston anchor buyout firm headquarters migration from high-tax jurisdictions.
Florida
Wealth migration from the Northeast sustains family office formation and direct investment activity. The absence of state income tax attracts fund manager relocation. Miami emerges as a Latin America-focused capital raising hub with growing venture debt presence.
California
Venture formation dominates early-stage deployment despite operational cost pressures. SEC registration requirements under the Investment Advisers Act shape marketing constraints to accredited investors. San Francisco Bay Area maintains technology buyout origination density.
New York
Credit and distressed strategies concentrate where bankruptcy court expertise and lender relationships concentrate. ERISA fiduciary standards shape pension fund allocation negotiations. Manhattan retains secondary transaction and fund-of-funds advisory clustering.
Delaware
Master-feeder structures and blocker corporation domiciliation exploit established case law on fiduciary duties. The Court of Chancery's specialized commercial docket reduces litigation uncertainty. Wilmington serves as the legal infrastructure backbone for national fund formation.
United States Private Equity Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United States private equity market. Scale-driven multi-strategy platforms deploy integrated asset services while specialized boutiques concentrate sector-specific operational expertise. The competitive landscape segments into mega-cap diversified sponsors, mid-market vertical specialists, and permanent capital vehicles. Consolidation through fund mergers and strategic talent acquisition reshapes tier boundaries.
Within the mega-cap diversified tier, Blackstone, KKR, and Apollo Global Management exemplify scale-driven platform architecture. These firms anchor competitive positioning through balance sheet integration and cross-asset class capital deployment capabilities.
| Leading Market Players |
|---|
| TPG |
| Clayton, Dubilier & Rice |
| KKR |
| Apollo Global Management |
| Carlyle Group |
| Blackstone |
| Hellman & Friedman |
| Bain Capital |
| Thoma Bravo |
| Others |
Value Network & Pricing Analysis
SEC registration requirements under the Investment Advisers Act gate both fund manager qualification and fee structure differentiation simultaneously, compressing pricing opacity while elevating compliance costs that feed into management fee loadings. General partners with scale absorb these fixed costs across larger asset bases, while emerging managers face disproportionate pressure that reshapes competitive positioning.
Pricing Analysis
The Investment Advisers Act dictates the pricing tier structure across the United States private equity landscape, mandating fee transparency that stratifies offerings across premium, standard, and economy levels. Price differentiation rests on fund size scale and operational track record depth, with mega-cap sponsors commanding premium carry multiples while mid-market firms compete on lower fee breakpoints. Pricing pressure stems from limited partner disintermediation and direct fee negotiation, particularly among California and New York public pension systems. Family offices exhibit the least price sensitivity due to concentrated position tolerance, while high-net-worth retail channels face the greatest fee compression given regulatory constraints on mass-affluent marketing.
Supply Chain Analysis
Delaware corporate law expertise anchors fund formation chokepoints, with the Court of Chancery's specialized docket underwrites legal infrastructure concentration for master-feeder structures nationwide. Supply draws from Delaware legal services, Texas energy transition capital, and Florida wealth migration corridors for investor sourcing. Raw material dependencies include regulatory filing capacity, audit firm bandwidth, and third-party administrator talent. Single-source vulnerability concentrates in Delaware domiciliation for fiduciary duty precedent, while distribution runs through institutional consultant channels and direct pension fund relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects across the United States private equity market as multi-strategy architectures displace single-asset-class specialization, with ecosystem interoperability between credit, real estate, and private equity units determining capital retention and cross-selling velocity.
For Market Incumbents: Fortify competitive positioning through balance sheet integration and permanent capital vehicle expansion, reducing redemption risk that emerging open-end structures exploit. Vertical integration into insurance-linked strategies and infrastructure platforms deepens fee durability against disintermediation threats from limited partner direct investment capabilities. Scale-driven operational leverage in back-office compliance absorbs SEC disclosure mandates that compress emerging manager margins. For New Entrants and Emerging Players: Operational due diligence talent scarcity in healthcare and energy verticals opens white-space targets where sector-specific expertise commands premium placement. Mid-market buyout firms penetrate fastest through technology-enabled sourcing and natural language processing deployment for accelerated due diligence. Direct family office relationships in Florida bypass institutional consultant gatekeeping that concentrates California and New York pension access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across permanent capital vehicles as balance sheet integration reduces fund formation frequency and associated placement costs. Long-term viability favors sponsors with diversified asset class platforms and insurance-linked capital structures over single-strategy buyout firms. Acquisition target archetypes concentrate in distressed restructuring specialists with healthcare operational expertise. The signal to watch is Federal Reserve rate policy trajectory and its compression of leverage availability for traditional buyout transactions.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Capital Vehicle Expansion | KKR and competitors anchor strategies through insurance balance sheet integration, reducing redemption sensitivity. |
| Technology-Enabled Due Diligence | Artificial intelligence platforms compress evaluation timelines and elevate auction competitiveness for mid-market sponsors. |
| State-Level Fund Formation Migration | Texas and Florida tax regimes attract general partner headquarters relocation from high-cost jurisdictions. |
| Healthcare Operational Partnership | Hospital systems seek private equity partners for cost restructuring and clinical network optimization. |
| Fee Structure Disintermediation | California and New York public pension systems negotiate direct arrangements, bypassing placement agent intermediaries. |
Research Methodology
Initial hypotheses were tested against primary input from fund formation attorneys, limited partner portfolio managers, fund administrators, and SEC compliance officers and refined through secondary validation. Primary fieldwork drew from general partners across Texas, Florida, California, and New York, combined with institutional investor interviews at public pension funds and insurance companies. Secondary sources encompassed SEC regulatory filings, Delaware Court of Chancery case records, ERISA fiduciary guidance documents, and state-level fund formation statutes. Bottom-up triangulation across sponsor-reported metrics and top-down validation through committed capital flow analysis anchored quantitative outputs.
Variance decomposition across the projection horizon isolates drivers by investment stage, industry vertical, fund structure, and investor type dimensions. Growth trajectories incorporate healthcare buyout velocity, technology deployment multiples, and permanent capital vehicle formation rates. CAGRs derive from historical capital commitment patterns and forward-looking allocation surveys across institutional limited partners. Model inputs include Federal Reserve policy trajectory, state tax regime competitiveness indices, and regulatory compliance cost curves.
Underlying assumptions cover sustained institutional allocation to alternatives, SEC rule stability, and leverage availability normalization, with deviation risk concentrated in accredited investor definition changes and state-level tax policy shifts. Forecasts reflect these conditions without scenario weighting. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Investment Analysis and Financial Strategies
Indonesia Life and Non-Life Insurance Market
Investment Analysis and Financial Strategies
Austria Property and Casualty Insurance Market
Investment Analysis and Financial Strategies
Global Wealth Management Platform Market
Investment Analysis and Financial Strategies
Autonomous Finance Market
Investment Analysis and Financial Strategies
Banking ERP Software Market
Investment Analysis and Financial Strategies
LAMEA Crypto Payment Gateway Market
Investment Analysis and Financial Strategies
White Glove Services Market
Investment Analysis and Financial Strategies
Video Banking Service Market
Investment Analysis and Financial Strategies
NPL Management Market
Investment Analysis and Financial Strategies
Takaful Insurance Market
Investment Analysis and Financial Strategies
Liquidation Service Market
Investment Analysis and Financial Strategies
Investment Banking Market
Investment Analysis and Financial Strategies
APAC Mutual Fund Market
Investment Analysis and Financial Strategies
Loan Origination Software Market
Investment Analysis and Financial Strategies
Norway Mobile Payments Market
Investment Analysis and Financial Strategies
Malaysia Fintech Market