
 United States of America Arts Promoter Market | 2026-2036
United States of America Arts Promoter Market Size, Share, and Industry Trends Forecast 2026-2036
United States of America Arts Promoter Market Insights
Market Context
Digital ticketing infrastructure is hardening as the core material layer replacing paper-based legacy systems across the promoter stack. Live Nation Entertainment leverages its Ticketmaster integration to control primary and secondary distribution channels nationwide. AEG Presents anchors its position through the Coachella and Stagecoach festival properties in California. The Madison Square Garden Company sustains venue-level dominance through its New York and Las Vegas real estate portfolio.
Technical Definition and Segment Structure
Arts promotion encompasses the commercial coordination of live performances, exhibitions, and cultural events, spanning talent procurement, venue logistics, audience development, and revenue optimization through dynamic pricing algorithms and sponsorship packaging. The service type dimension shows event management capturing the largest revenue pool while production services yields the highest per-project margins due to equipment and labor specialization. Within client type, corporations and cultural institutions generate the steadiest retainer-based revenue, whereas individual artists increasingly drive on-demand project volume.
Regulatory Environment
The Federal Trade Commission scrutinizes ticketing transparency under its 2016 enforcement policy statement on drip pricing, while state-level legislation in California, New York, and Illinois mandates all-in pricing disclosures. The National Endowment for the Arts and state arts agencies shape subsidy flows that reduce risk capital requirements for nonprofit-leaning promoters. Stakeholders must monitor how pending Federal legislation on ticket resale restrictions alters secondary market economics and primary pricing power.
Market Dynamics
Digital ticketing infrastructure is consolidating control over primary and secondary distribution channels, compressing margins for independent promoters while amplifying pricing power for vertically integrated platforms across live music and theatrical production.
Growth Catalysts
- Section 181 Tax Deduction:The Internal Revenue Service's provision for live theatrical productions incentivizes domestic capital deployment, reducing after-tax production costs for qualifying stage works.
- Live Music Festivals:Multi-day outdoor events generate ancillary revenue streams through sponsorship packaging, hospitality tiers, and on-site merchandise that exceed per-capita yields from single-night arena shows.
- Dynamic Pricing Algorithms:Real-time demand-responsive ticketing systems capture consumer surplus at peak interest moments, optimizing yield per seat across venue configurations.
Market Restraints
- Talent Roster Concentration:A limited pool of bankable headliners drives guarantee inflation, forcing smaller promoters into unfavorable revenue splits or cancellation exposure.
- Venue Real Estate Scarcity:Established rooms in California, New York, and Tennessee command premium rent structures that absorb 25-40% of gross event revenue before marketing spend.
- FTC Drip Pricing Scrutiny:Federal Trade Commission enforcement against fee obfuscation mandates all-in price disclosure, compressing the fee-stacking revenue that platforms previously extracted at checkout.
Strategic Opportunities
- Secondary Market Legislation:Pending federal restrictions on ticket resale bots and speculative listing create openings for primary sellers to reclaim price arbitrage currently captured by scalpers.
- Immersive Exhibition Formats:Non-traditional venue types—warehouses, botanical gardens, historic sites—expand addressable inventory beyond purpose-built theaters and arenas.
- Corporate Retainer Relationships:Cultural institutions and Fortune 500 entities seek multi-year programming partnerships that smooth revenue seasonality and reduce per-event acquisition costs.
Industry Challenges
- Technical Production Labor Shortage:Rigging, lighting, and audio engineering specializations face generational attrition, extending load-in timelines and inflating crew rates.
- Legacy System Integration:Mid-tier promoters operate on fragmented CRM, accounting, and access control platforms that resist API connectivity with dominant ticketing ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States of America Arts Promoter Market |
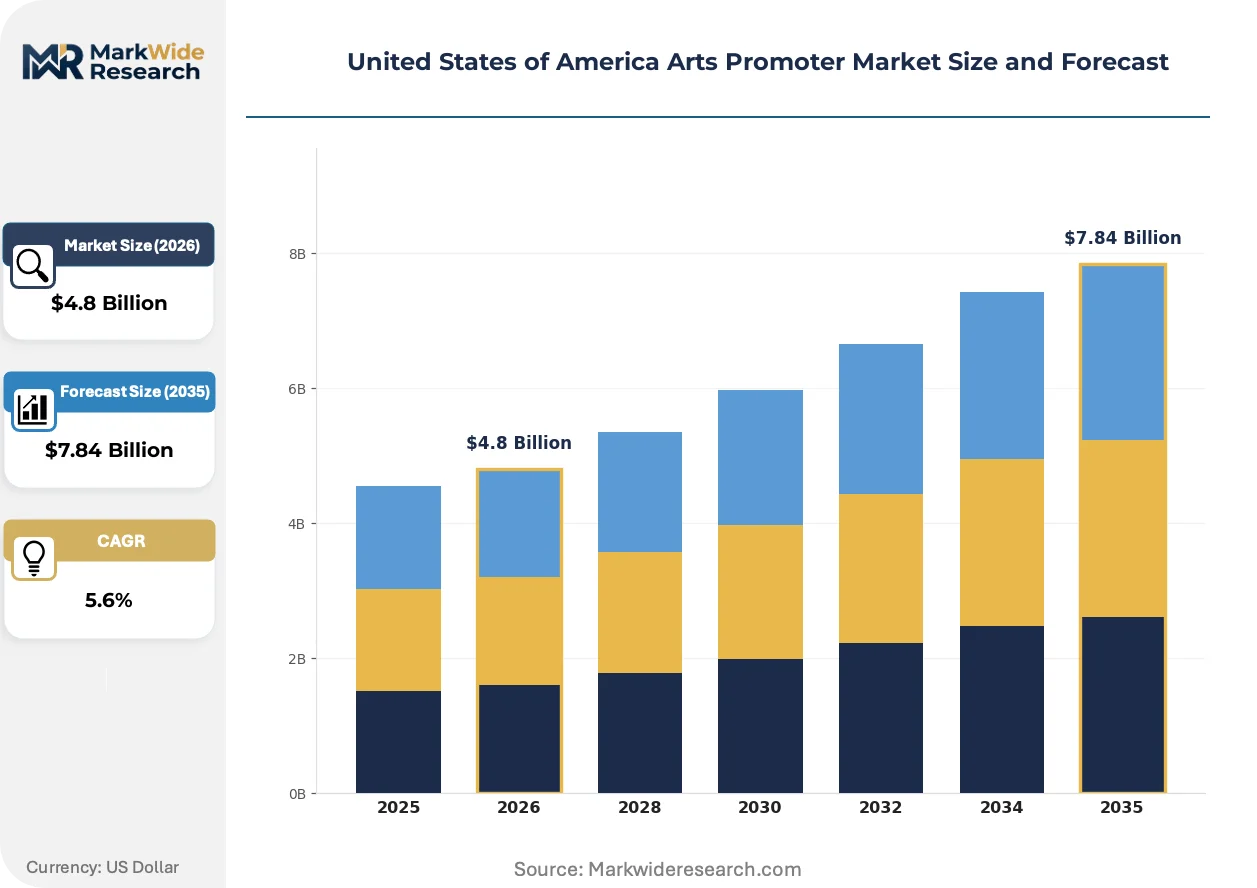
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Event Management, Artist Representation, Production Services, Marketing Strategies Client Type: Corporations, Nonprofits, Individual Artists, Cultural Institutions Industry Vertical: Performing Arts, Visual Arts, Literature, Music Events Engagement Model: Consulting, On-Demand Services, Retainer, Project-Based |
| Companies Covered | The Madison Square Garden Company, Comcast Corporation, Live Nation Entertainment, Goldenvoice, C3 Presents, The Walt Disney Company, Paramount Global, The Shubert Organization, AEG Presents, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States of America Arts Promoter Market Trends and Innovations
Live event production is absorbing mobile-first audience engagement tools that reshape how promoters build demand curves and monetize attention before, during, and after performances.
RFID-enabled credentialing is absorbing cashless commerce and access control functions across festival environments. Live Nation Entertainment deploys this technology at Bonnaroo and Lollapalooza properties, capturing granular spending data that informs real-time inventory decisions for food, beverage, and merchandise vendors. The structural consequence is that promoter-owned data assets are displacing third-party payment processor relationships.
California's all-in pricing mandate and Illinois disclosure requirements are forcing fee restructuring across multi-state tours. Promoters operating national routing must either adopt the strictest state standard universally or maintain jurisdiction-specific checkout flows. The mid-market touring segment bears the highest compliance cost burden from this regulatory fragmentation.
Subscription-based membership programs are replacing single-ticket purchases for core audience segments. AEG Presents and independent promoters in Nashville test annual passes that guarantee early access and fixed pricing, trading per-show margin for predictable recurring revenue and reduced marketing spend per transaction. This behavioral shift concentrates most visibly in secondary markets where venue scarcity creates FOMO-driven commitment.
United States of America Arts Promoter Market Segmentation
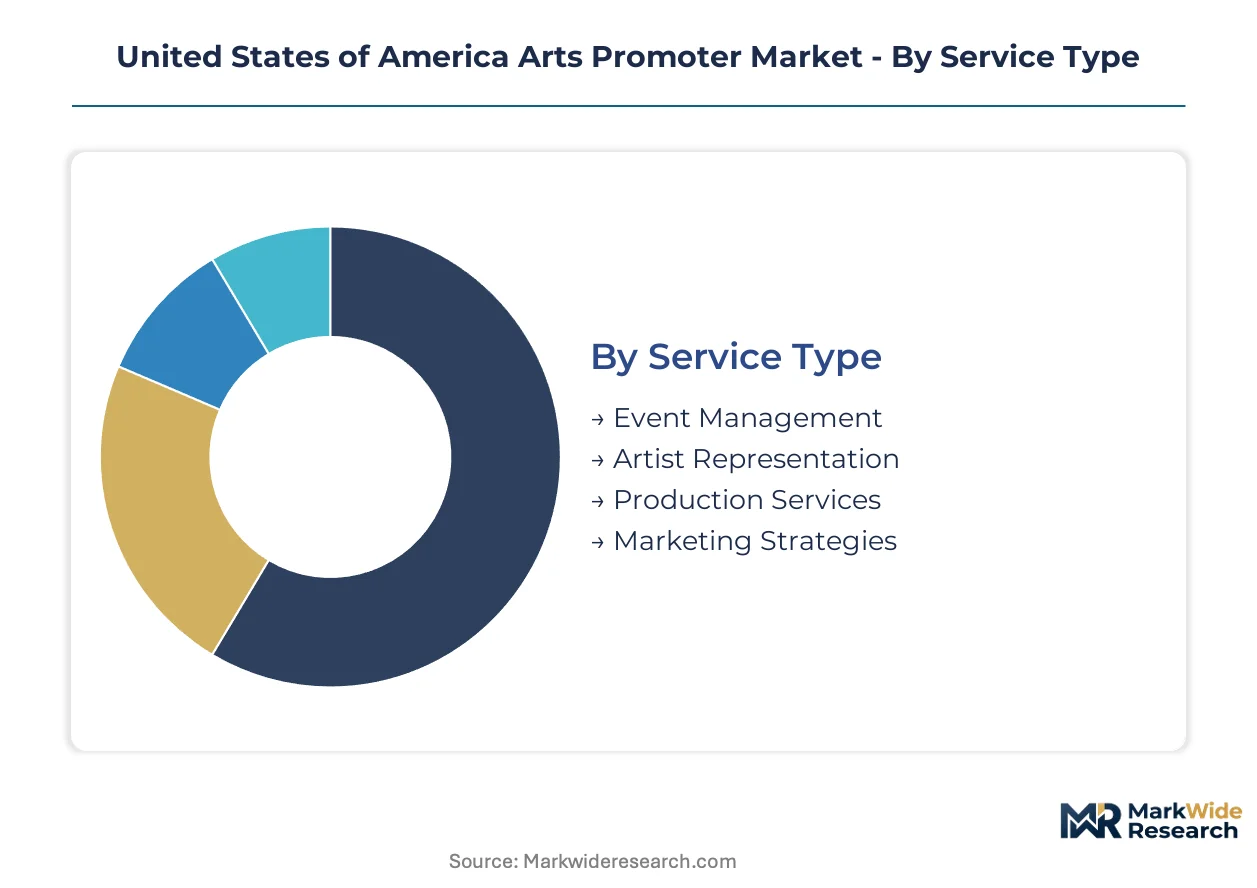
Arts promotion segmentation reveals how service specialization, client risk profiles, and engagement economics create distinct competitive arenas. Promoters configure operations around these dimensions to match capital intensity with revenue predictability.
Service Type:
Customization intensity varies sharply across this spectrum, from templated event logistics to bespoke production design requiring specialized labor and equipment pools.
- Event Management:Logistics coordination spanning venue procurement, permitting, and on-site operations. Demand concentrates in California and Tennessee festival circuits where multi-day outdoor events require complex infrastructure orchestration and weather contingency protocols.
- Production Services:Technical execution including lighting, sound, and staging systems with specialized crew deployment. High per-project margins reflect equipment amortization schedules and union labor rates that smaller promoters cannot replicate.
- Artist Representation:Talent procurement and contract negotiation services. Retainer structures dominate in Nashville and Los Angeles where roster depth determines competitive position.
- Marketing Strategies:Audience development through digital channels and sponsorship packaging. Dynamic pricing algorithm deployment separates premium-tier operators from commodity social-media management.
Most installed capacity flows through Event Management. Expansion is steepest in Production Services.
Client Type:
Revenue stability inversely correlates with client sophistication, from Fortune 500 retainer relationships to volatile individual artist project flows.
- Corporations:Brand activation and employee engagement programming with multi-year contracts. Steady retainer revenue from technology and financial services sectors in New York and California reduces seasonal cash flow volatility.
- Cultural Institutions:Museums, orchestras, and theater companies seeking subscriber acquisition and donor cultivation support. Public funding cycles in Massachusetts and Illinois create predictable procurement calendars.
- Nonprofits:Mission-driven programming with grant-dependent budgets. Fee sensitivity limits service scope to volunteer-staffed events in secondary markets.
- Individual Artists:On-demand tour support and single-project launches. Volume is climbing fastest in Nashville and Austin where independent musician density outpaces institutional infrastructure.
Corporations anchor revenue stability. Individual Artists are gaining share fastest.
Industry Vertical:
Production complexity and audience monetization depth separate verticals with ancillary revenue potential from those dependent on single-ticket economics.
- Music Events:Festival and touring formats generating sponsorship, hospitality, and merchandise layers beyond admission. Live Nation and AEG control primary distribution in this vertical through venue ownership and ticketing integration.
- Performing Arts:Theater, dance, and opera presenting with subscription-based audience development. Section 181 tax incentives for live theatrical productions in New York and Chicago reduce capital risk for nonprofit-leaning promoters.
- Visual Arts:Exhibition curation and gallery programming with corporate sponsorship reliance. Pop-up formats in non-traditional venues are expanding addressable inventory beyond purpose-built museum space.
- Literature:Author tours, festival programming, and spoken-word events. Smallest revenue pool with highest per-capita marketing spend due to dispersed audience geography.
Music Events concentrate the largest revenue base. Performing Arts show the steepest expansion trajectory.
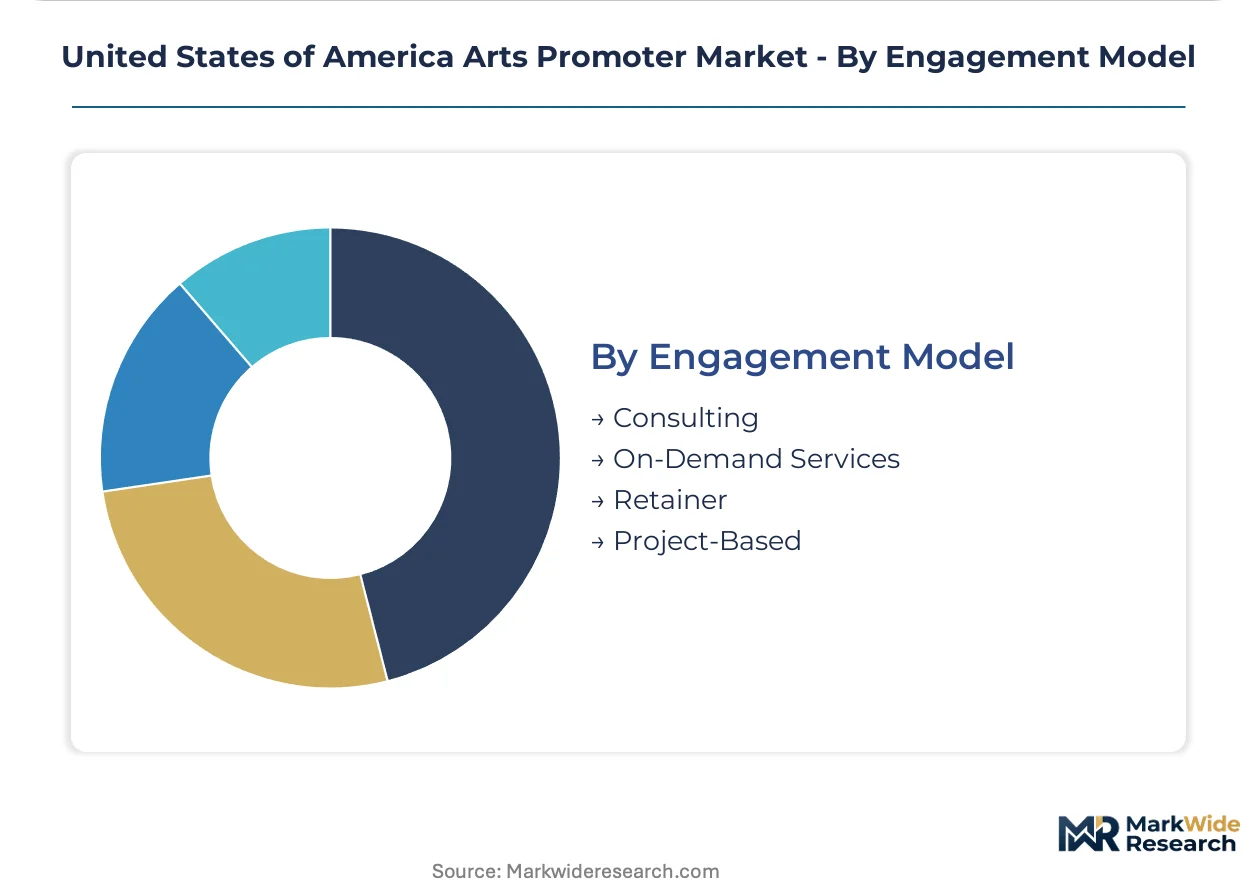
Engagement Model:
Margin structure and client acquisition cost vary by commitment duration, from high-touch consulting relationships to transactional on-demand fulfillment.
- Retainer:Multi-year agreements with fixed monthly fees and defined service tiers. Cultural institutions and corporations in Washington DC and Boston favor this model for budget predictability.
- Project-Based:Scoped deliverables with milestone payments and completion risk. Dominant format for festival production where single-event economics require discrete capital deployment.
- Consulting:Advisory services without operational execution, priced hourly or by deliverable. Strategy-heavy engagements for new market entry and digital transformation.
- On-Demand Services:Rapid-response support for artist emergencies and last-minute routing changes. Premium pricing reflects availability guarantees and cancellation flexibility.
Retainer relationships dominate revenue stability. Project-Based engagements are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's entertainment corridor anchors national arts promotion capacity, with venue density and talent concentration creating self-reinforcing cluster effects that draw touring infrastructure investment from across the country.
California
Live music festivals and immersive exhibition formats drive demand in Los Angeles and San Francisco metro areas. The California Department of Tax and Fee Administration enforces all-in pricing mandates that reshape checkout flows for multi-state tours. Goldenvoice's Indio festival properties exemplify how desert-adjacent real estate enables multi-day event scaling unavailable in dense urban cores.
New York
Theater subscription programming and corporate brand activations sustain retainer-based revenue stability in Manhattan and Brooklyn. The New York State Department of Financial Services oversees charitable solicitation regulations affecting nonprofit-leaning promoters. The Madison Square Garden Company's venue portfolio in Midtown anchors Broadway-adjacent production economics.
Tennessee
Country music touring circuits and songwriter showcase formats concentrate demand in Nashville and Memphis. The Tennessee Department of Revenue administers sales tax collection on ticketed events with specific exemptions for certain cultural programming. AEG Presents maintains festival properties in Manchester that draw national routing decisions toward the mid-South.
Texas
Arena touring and corporate event programming expand addressable inventory in Dallas-Fort Worth and Austin. The Texas Comptroller of Public Accounts regulates mixed beverage taxes affecting hospitality revenue streams at promoted events. C3 Presents operates Austin-based festival properties that anchor South-by-Southwest adjacent programming year-round.
Illinois
Performing arts subscriptions and museum exhibition curation sustain institutional client relationships in Chicago. The Illinois Attorney General enforces consumer protection statutes on ticket resale transparency that exceed federal baseline requirements. The Shubert Organization's theatrical portfolio in the Loop district concentrates Broadway touring circuit decision-making.
United States of America Arts Promoter Market Competitive Landscape
Vertical integration dominates the current landscape, with control over ticketing infrastructure and venue real estate separating scalable platforms from project-based independents. The market structure concentrates around three to five vertically integrated holdings that own primary distribution channels, while mid-tier promoters operate on fragmented technology stacks with limited pricing power. Two strategic archetypes predominate: venue-owning conglomerates that capture rent and ticket fees, and festival-focused operators that monetize multi-day hospitality packaging. Competitive moves center on exclusive talent roster lockups and geographic expansion into secondary markets with underserved venue inventory.
Within the venue-owning conglomerate tier, Live Nation Entertainment and AEG Presents exemplify scale-driven positioning through integrated ticketing and real estate control, while The Madison Square Garden Company anchors premium-tier theatrical and arena economics in dense urban markets. These entities occupy positions that independent promoters cannot replicate due to capital requirements for venue acquisition and technology infrastructure. The competitive dynamic forces mid-market operators toward niche specialization in immersive formats or corporate retainer relationships where personal networks substitute for platform scale.
| Leading Market Players |
|---|
| The Madison Square Garden Company |
| Comcast Corporation |
| Live Nation Entertainment |
| Goldenvoice |
| C3 Presents |
| The Walt Disney Company |
| Paramount Global |
| The Shubert Organization |
| AEG Presents |
| Others |
Pricing and Supply Chain Analysis
California's all-in pricing mandate gates qualified supply access and premium-tier pricing power for promoters operating multi-state tours, forcing compliance investments that smaller operators cannot absorb while rewarding scaled platforms with jurisdiction-spanning infrastructure.
Pricing Analysis
Input-cost pass-through from venue real estate and technical labor pools shapes promoter margin structures across service tiers. Three-tier pricing structure across premium hospitality, standard admission, and economy general access separates AEG Presents and Live Nation Entertainment from independent competitors lacking bundled inventory control. Price differentiation rests on venue ownership depth and dynamic pricing algorithm deployment. Pricing pressure stems from FTC drip pricing enforcement eliminating fee-stacking revenue at checkout. Nonprofit-leaning promoters show highest price sensitivity due to grant-dependent budgets, while corporate clients accept premium rates for guaranteed access and brand alignment.
Supply Chain Analysis
Warehouse-distribution layer consolidation in Los Angeles, Nashville, and New York anchors equipment and labor deployment for national touring circuits. Supply concentrates in these three metropolitan clusters where rigging, lighting, and audio engineering specializations pool. Raw material dependencies span aluminum truss systems, LED display panels, and diesel generator sets. Supply chain risk centers on technical production labor shortage extending load-in timelines and inflating crew rates. Distribution runs through hub-and-spoke patterns radiating from owned venue properties and regional equipment depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as audience demand shifts toward immersive exhibition formats and multi-day festival experiences commanding premium pricing over single-night arena economics.
For Market Incumbents: Anchor defensive positioning through exclusive talent roster lockups and venue real estate acquisition in secondary markets with underserved inventory. Consolidate control over RFID-enabled credentialing infrastructure to capture ancillary spending data currently flowing through third-party payment processors. Threat substitution from immersive digital entertainment platforms demands counterinvestment in physical experience differentiation.
For New Entrants and Emerging Players: The price-point gap between premium hospitality tiers and economy general admission creates entry space for mid-market promoters specializing in corporate retainer relationships and cultural institution partnerships. Target white-space opportunities in immersive exhibition formats utilizing non-traditional venues—warehouses, botanical gardens, historic sites—where purpose-built theater scarcity limits incumbent platform deployment. Go-to-market leverage rests on multi-year programming contracts smoothing revenue seasonality.
For Investors and Strategic Acquirers: Roll-up economics work for venue-owning regional promoters because fragmented technology stacks and limited pricing power create acquisition targets at discounted multiples. Long-term viability favors scaled platforms with ticketing integration and real estate control over project-based independents. Signal to monitor: federal ticket resale legislation altering secondary market economics and primary seller pricing power recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Dynamic Pricing Algorithm Deployment | Live Nation Entertainment captures consumer surplus at peak demand moments through real-time yield optimization. |
| Venue Real Estate Acquisition | AEG Presents expands addressable inventory through desert-adjacent properties enabling multi-day festival scaling. |
| RFID Credentialing Integration | Goldenvoice displaces third-party payment relationships through promoter-owned cashless commerce data capture. |
| Corporate Retainer Program Development | Madison Square Garden Company secures multi-year brand activation contracts reducing per-event acquisition costs. |
| Immersive Format Expansion | Independent promoters access non-traditional venue inventory beyond purpose-built theater and arena constraints. |
Research Methodology
Bottom-up live event volume modeling reconciled against top-down promoter revenue tracking forms the analytical core of this study. Primary interviews with festival production directors, venue operations managers, talent agency executives, and corporate event procurement officers combined with secondary validation from SEC filings, state tax authority enforcement records, and National Endowment for Arts appropriation data. Triangulation across these sources calibrated segment-level estimates.
Historical trendline analysis of ticketing revenue, sponsorship packaging, and ancillary spending established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include service type specialization, client risk profile, industry vertical production complexity, and engagement model commitment duration. CAGRs derived from curve-fitting observed expansion rates against capacity constraints and regulatory compliance cost trajectories. Forecast inputs incorporated Section 181 tax incentive utilization rates and state-level pricing disclosure mandate adoption timelines.
The model assumes a particular technology adoption path for RFID-enabled credentialing and dynamic pricing systems; alternative pathways for mobile-first audience engagement tools would alter the outlook. Forecasts reflect assumptions about labor pool replenishment and venue construction permitting velocity that external shocks could revise. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Media and Entertainment
Social Media Content Creation Market
Media and Entertainment
Streaming Services Market
Media and Entertainment
India Event and Exhibition Market
Media and Entertainment
Podcast Advertising Market
Media and Entertainment
Global Gaming Market
Media and Entertainment
Gaming Chair Market
Media and Entertainment
United States Live Music Market
Media and Entertainment
Music Fountain Market
Media and Entertainment
Movie Tickets Market
Media and Entertainment
Global Esports and Traditional Sports Betting Market
Media and Entertainment
Professional Dubbing Services Market
Media and Entertainment
Asia-Pacific and Germany Digital Out of Home (DOOH) Advertising Market
Media and Entertainment
Digital Content Locker Market
Media and Entertainment
Europe User Generated Content Platform Market
Media and Entertainment
Indonesia Digital Advertising Market
Media and Entertainment
Global Online Simulation Games Market