
 United States Occupational Health Market | 2026-2036
United States Occupational Health Market Size, Share, and Industry Trends Forecast 2026-2036
United States Occupational Health Market Analytics
Texas is reshaping occupational health service capacity through expanded clinic networks serving the Permian Basin energy corridor and Gulf Coast petrochemical complexes. Concentra leverages its national footprint of employer-focused medical centers to sustain same-day injury care and regulatory compliance testing. Examinetics differentiates through mobile health screening units that reach remote construction and logistics sites. WorkCare anchors its position in travel medicine and pandemic response protocols for multinational employers.
United States occupational health encompasses medical surveillance, injury prevention, and regulatory compliance services designed to maintain workforce fitness and reduce employer liability under federal and state labor laws. Clinical protocols integrate spirometry testing, audiometric screening, and functional capacity evaluations performed by board-certified occupational medicine physicians. Screening services dominate current revenue flows, while telemedicine adoption accelerates fastest among SMEs seeking cost-effective access to specialist consultations. Wearable device integration represents an emerging margin pool, with biometric monitoring contracts commanding premium pricing from large enterprises in high-hazard industries.
OSHA mandates drive baseline demand through standards for bloodborne pathogens, hazard communication, and personal protective equipment fit testing. EPA coordination on chemical exposure limits and NIOSH research priorities further shape service specifications and clinician training requirements. Stakeholders must monitor how state-level workers compensation reforms and emerging silica enforcement actions recalibrate provider reimbursement and employer compliance spending.
Market Dynamics
OSHA's intensified silica enforcement and respirable crystalline silica standard revisions are compressing compliance timelines for construction and manufacturing employers, forcing accelerated investment in medical surveillance infrastructure and on-site screening capacity.
Growth Catalysts
- Respiratory Protection Standards:OSHA's updated fit testing mandates for tight-fitting respirators are expanding employer demand for quantitative fit testing services and pulmonary function screening programs.
- Permian Basin Energy Expansion:West Texas shale operations require continuous medical surveillance for hydrogen sulfide exposure and heat stress management across dispersed drilling sites.
- Wearable Biometric Monitoring:Real-time physiological tracking devices are embedding heart rate variability and core temperature sensors into standard PPE for high-hazard industrial assignments.
Market Restraints
- Clinical Workforce Scarcity:Board-certified occupational medicine physicians concentrate in Houston, Los Angeles, and Chicago, leaving rural manufacturing corridors underserved for specialized surveillance.
- Reimbursement Compression:State workers compensation fee schedules in Texas and California cap reimbursement rates for functional capacity evaluations and impairment ratings.
- Equipment Capital Intensity:Mobile audiometric testing vans and spirometry calibration systems require six-figure capital outlays that constrain independent clinic expansion.
Strategic Opportunities
- Gulf Coast Petrochemical Corridor:Louisiana and Texas chemical processing facilities face benzene and 1,3-butadiene monitoring mandates that exceed current local clinic capacity.
- Telemedicine-Enabled Specialist Access:Rural construction and agriculture employers in the Mountain West lack proximity to occupational medicine physicians for complex case management.
- Heat Illness Prevention Mandates:California's outdoor heat illness prevention standard and emerging federal heat stress rules are creating demand for acclimatization protocols and physiological monitoring services.
Industry Challenges
- Certified Industrial Hygienist Shortage:Complex exposure assessment protocols for mixed chemical environments require credentialed professionals whose training pipeline operates on multi-year cycles.
- Electronic Health Record Fragmentation:Employer clinics, third-party administrators, and workers compensation carriers maintain incompatible data systems that obstruct longitudinal health surveillance.
- Mobile Unit Deployment Logistics:Remote construction sites and offshore platforms demand specialized equipment transport and clinician rotation schedules that compress margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Occupational Health Market |
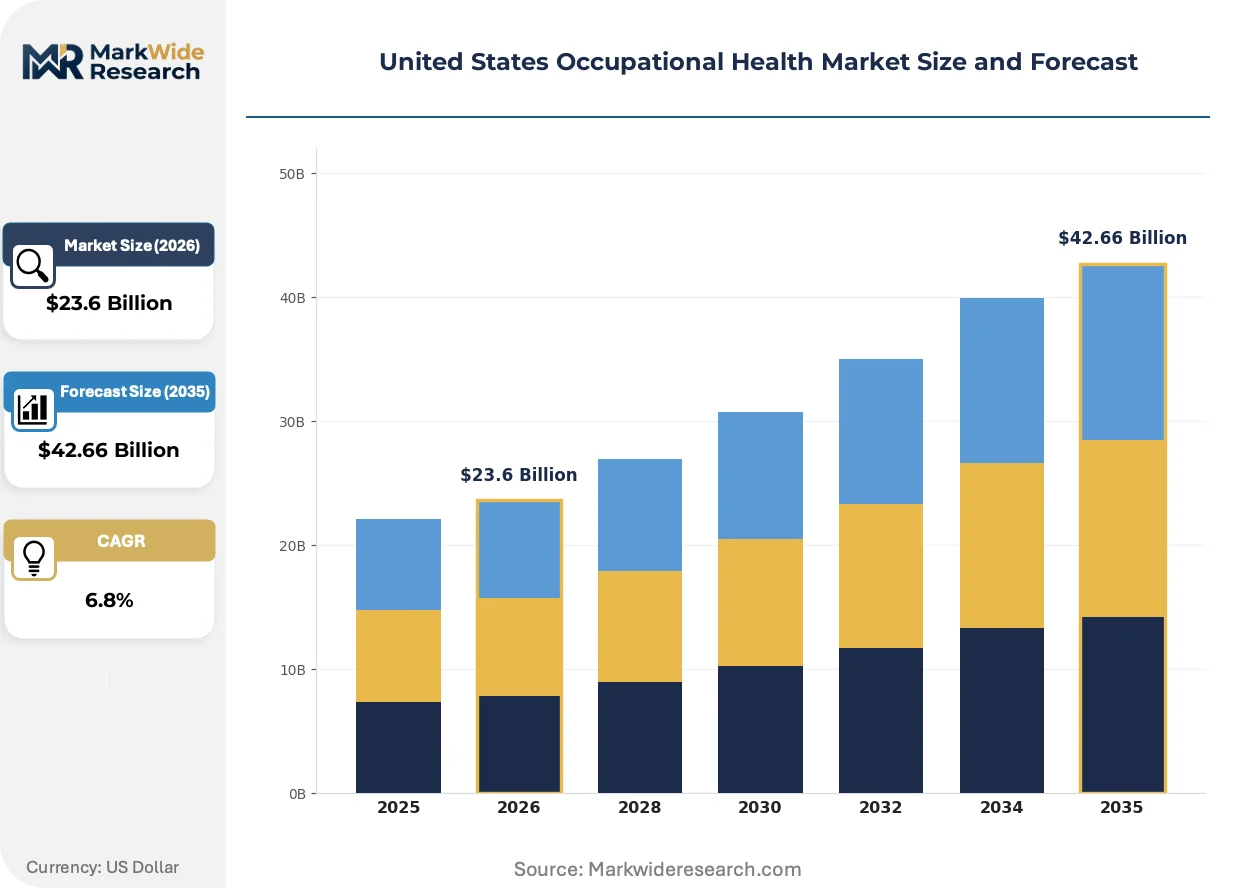
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $42.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consultation, Screening, Wellness Programs, Risk Assessment End User: Large Enterprises, SMEs, Government Agencies, Nonprofits Technology: Telemedicine, Wearable Devices, Health Analytics, Mobile Apps Application: Employee Assistance Programs, Injury Management, Occupational Therapy, Fitness Testing |
| Companies Covered | U.S. HealthWorks, Examinetics, Premise Health, OccuCare International, Workwell Occupational Medicine, Concentra, WorkCare, Axiom Medical, Nova Medical Centers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Occupational Health Market Evolving Landscape
Digital health infrastructure is collapsing the distance between remote worksites and specialist diagnostic capabilities, while regulatory pressure on chemical exposure monitoring accelerates investment in continuous sensing technologies.
Artificial intelligence-assisted audiometric interpretation is digitizing the detection of occupational hearing loss patterns that human technicians miss during high-volume screening events. Mining and heavy manufacturing employers in Appalachia and the Upper Midwest are piloting these systems to reduce false-negative rates in baseline and annual testing programs. The technology is digitizing quality assurance workflows that previously required manual review by certified audiometric technicians.
OSHA's national emphasis program on heat-related hazards is compelling employers across the Sun Belt to implement acclimatization protocols and physiological monitoring for outdoor workers. The enforcement priority is expanding demand for wet-bulb globe temperature monitoring and work-rest cycle management in construction, agriculture, and warehouse distribution operations. California's existing heat illness prevention standard provides the compliance template that federal inspectors are applying nationwide.
Self-insured employers in the logistics and e-commerce sectors are consolidating occupational health vendor relationships to capture integrated medical surveillance, injury care, and return-to-work coordination under single-source contracts. Third-party administrators are responding by bundling clinic networks, telemedicine triage, and nurse case management into unified service platforms. The consolidation is most visible in the Inland Empire warehouse corridor east of Los Angeles, where Amazon, Walmart, and Target operate dense fulfillment networks.
United States Occupational Health Market Segmentation
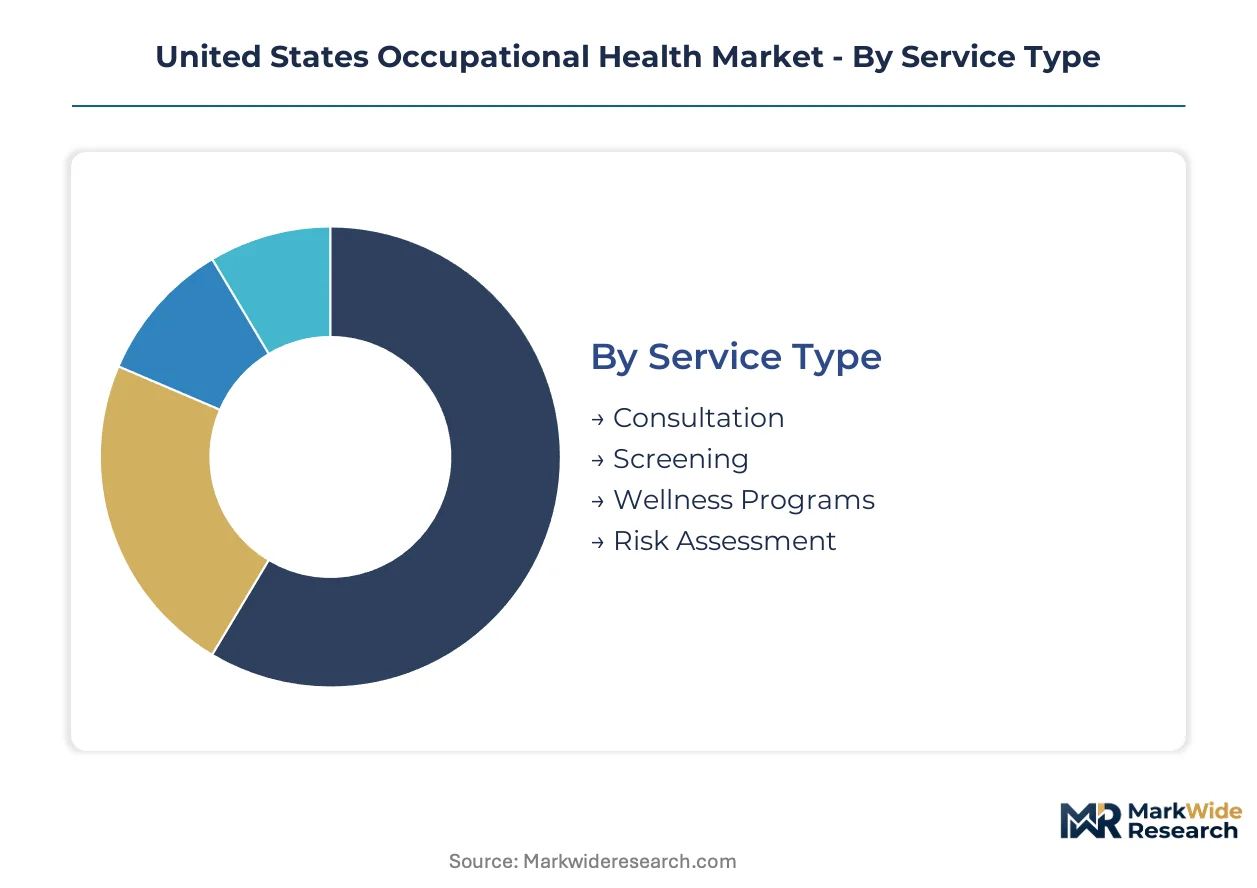
Occupational health service delivery fragments across four structural dimensions that determine pricing power, capital requirements, and regulatory exposure. Each segmentation axis reveals distinct competitive dynamics between clinic-based incumbents and technology-enabled challengers reshaping workforce health management.
Service Type:
Mature compliance-driven services anchor revenue stability while emerging preventive offerings reshape margin structures through recurring subscription models.
- Screening:Pulmonary function testing, audiometric evaluation, and bloodborne pathogen surveillance constitute the procedural backbone of OSHA-mandated medical surveillance. Manufacturing employers in Houston and Los Angeles drive volume concentration for these services due to dense industrial clustering and enforcement visibility.
- Consultation:Board-certified occupational medicine physicians deliver case management for complex exposures and fitness-for-duty determinations. Demand concentrates among Permian Basin energy operators and Gulf Coast petrochemical facilities requiring specialized expertise for hydrogen sulfide and benzene monitoring protocols.
- Wellness Programs:Corporate fitness initiatives and mental health support services expand employer value propositions beyond regulatory minimums. Large self-insured employers in logistics and e-commerce sectors bundle these programs with medical surveillance contracts.
- Risk Assessment:Industrial hygiene surveys and ergonomic evaluations identify hazards before OSHA citations materialize. Construction and agriculture employers in rural Mountain West corridors utilize these services to preempt enforcement actions.
Screening retains volume leadership; Consultation holds the steepest expansion curve.
End User:
Customer scale determines procurement sophistication, with enterprise buyers demanding integrated platforms and smaller employers prioritizing transactional service access.
- Large Enterprises:Self-insured manufacturers and energy operators with 1,000-plus employees negotiate multi-year contracts bundling on-site clinics, mobile screening units, and telemedicine triage. Amazon, Walmart, and Target operate dense fulfillment networks in California's Inland Empire that command dedicated occupational health infrastructure.
- SMEs:Mid-sized construction firms and regional manufacturers rely on third-party administrator networks and shared clinic access for sporadic compliance testing. Telemedicine adoption accelerates fastest among this cohort seeking cost-effective specialist access without proximity to occupational medicine physicians.
- Government Agencies:Federal facilities and state-level departments of transportation maintain internal occupational health units for uniformed and hazardous duty personnel. Procurement follows federal supply schedule protocols with emphasis on veteran-owned and small business set-asides.
- Nonprofits:Healthcare systems and social service organizations operate occupational health programs for volunteer corps and field deployment staff. Workers compensation exposure remains elevated due to manual handling tasks in community-based service delivery.
Large Enterprises dominate contract value concentration; SMEs are expanding most quickly through telemedicine-enabled access.
Technology:
Digital infrastructure investment separates capital-intensive hardware deployments from software-enabled service extensions that scale without proportional labor expansion.
- Telemedicine:Video-based specialist consultation and asynchronous case review collapse geographic barriers between remote worksites and board-certified occupational medicine physicians. Rural construction and agriculture employers in the Mountain West represent the addressable demand concentration for this modality.
- Wearable Devices:Biometric sensors embedded in standard PPE deliver real-time heart rate variability and core temperature monitoring for heat stress prevention. Mining and heavy manufacturing employers in Appalachia pilot these systems to reduce heat-related illness incidence.
- Health Analytics:Population-level surveillance dashboards aggregate screening results across employer portfolios to identify exposure trends and predict impairment risk. Third-party administrators leverage these platforms to demonstrate return-on-investment for self-insured clients.
- Mobile Apps:Worker-facing applications deliver acclimatization protocols, symptom checkers, and emergency response guidance for dispersed field personnel. Oilfield service contractors in West Texas shale operations deploy these tools across rotating crews with limited clinic access.
Wearable Devices capture premium pricing from high-hazard industries; Telemedicine is gaining share fastest among geographically dispersed workforces.
Application:
Functional use cases span reactive injury management through proactive fitness optimization, with regulatory pressure strongest in post-incident protocols.
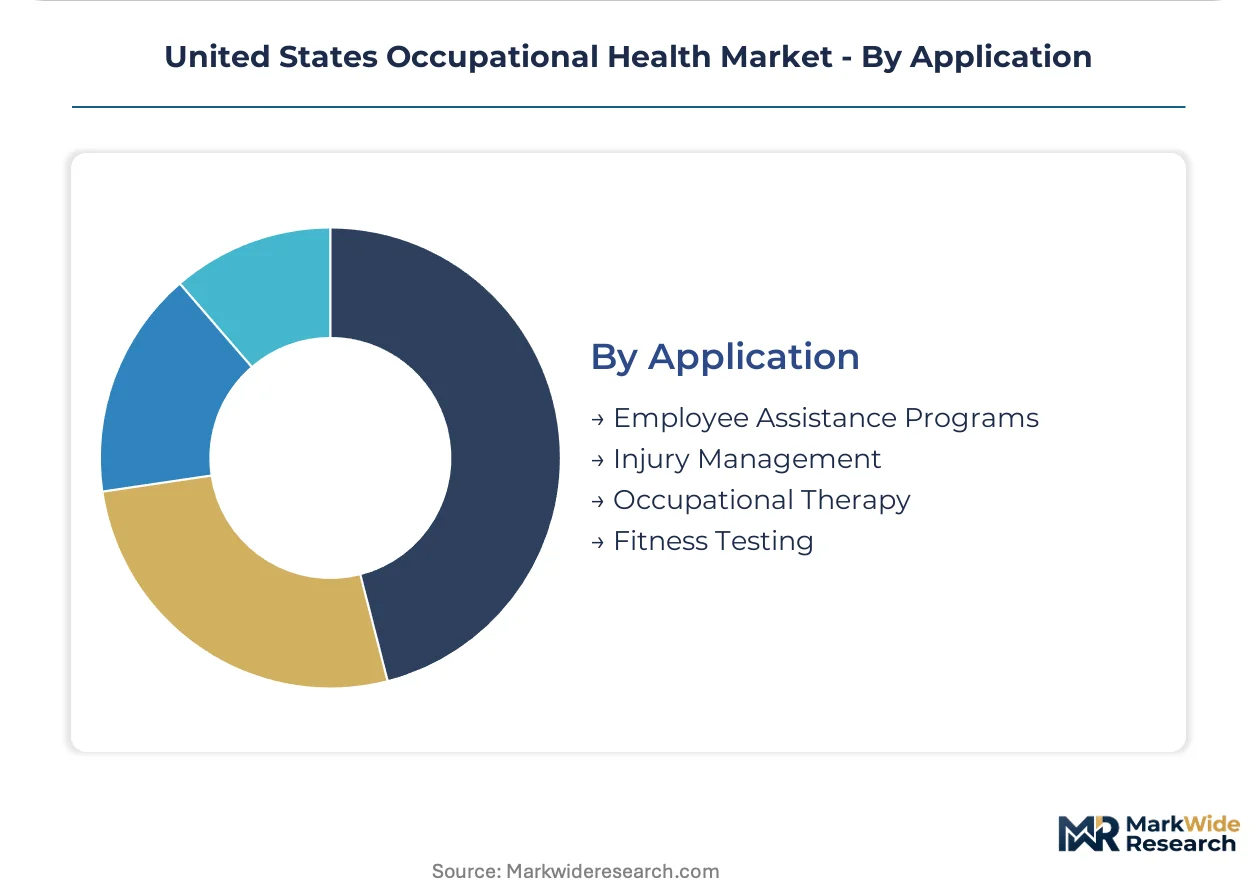
- Injury Management:Same-day acute care, specialist referral coordination, and return-to-work planning reduce workers compensation claim duration and indemnity costs. Concentra's national clinic network anchors service delivery for this application through employer-focused medical centers.
- Employee Assistance Programs:Confidential counseling and crisis intervention services address behavioral health factors that compound physical injury risk. Logistics employers in warehouse distribution corridors integrate EAP access with occupational health contracts to manage turnover and absenteeism.
- Occupational Therapy:Functional capacity evaluations and work hardening programs restore injured workers to pre-injury duty status. Texas and California workers compensation fee schedules cap reimbursement rates for these services, compressing provider margins.
- Fitness Testing:Pre-placement physicals and periodic fitness assessments validate capability for safety-sensitive positions. Fire departments, law enforcement agencies, and commercial drivers represent concentrated demand for standardized testing protocols.
Injury Management retains volume leadership; Employee Assistance Programs hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA enforcement intensity varies sharply across U.S. states, creating divergent compliance investment patterns and service demand concentrations that reshape provider network deployment strategies.
Texas
Permian Basin shale operations and Gulf Coast petrochemical complexes drive hydrogen sulfide exposure monitoring and heat stress management demand. The state's workers compensation fee schedule caps reimbursement for functional capacity evaluations. Houston anchors the densest concentration of occupational medicine clinics serving energy sector employers.
California
Silica enforcement actions and outdoor heat illness prevention standards compress compliance timelines for construction and agriculture employers. Cal/OSHA maintains stricter exposure limits than federal counterparts for multiple chemical agents. The Inland Empire warehouse corridor commands dedicated occupational health infrastructure from major logistics operators.
Appalachia
Coal mining and heavy manufacturing employers pilot AI-assisted audiometric interpretation systems to reduce false-negative rates in hearing conservation programs. MSHA coordination with OSHA shapes dual regulatory exposure for surface and underground operations. West Virginia and Kentucky clinics face equipment capital intensity barriers to mobile screening expansion.
Mountain West
Rural construction and agriculture employers lack proximity to board-certified occupational medicine physicians for complex case management. Telemedicine adoption accelerates fastest in this corridor as SMEs seek specialist access without travel burden. Denver and Salt Lake City host the only regional concentrations of certified industrial hygienists.
Louisiana
Gulf Coast chemical processing facilities face benzene and 1,3-butadiene monitoring mandates that exceed current local clinic capacity. EPA coordination with OSHA on refinery sector enforcement drives medical surveillance infrastructure investment. Baton Rouge and Lake Charles petrochemical complexes anchor service demand concentration.
United States Occupational Health Market Competitive Landscape
National clinic networks and specialized service providers split the market between scale-driven compliance testing and premium consulting engagements. The structure rewards geographic footprint density in industrial corridors while penalizing capital-light entrants lacking mobile unit deployment capability. Two archetypes dominate: employer-focused medical center operators and mobile health screening specialists. Consolidation through multi-year enterprise contracts and technology-enabled service extensions represent the primary competitive vectors reshaping market share distribution.
Within the national clinic network tier, Concentra leverages its employer-focused medical center footprint to sustain same-day injury care and regulatory compliance testing. Examinetics occupies a position exemplifying mobile health screening specialization through units that reach remote construction and logistics sites. WorkCare anchors the travel medicine and pandemic response protocol segment for multinational employers. These three represent distinct strategic postures that competitors must match or circumvent to secure contract renewals in enterprise accounts.
| Leading Market Players |
|---|
| U.S. HealthWorks |
| Examinetics |
| Premise Health |
| OccuCare International |
| Workwell Occupational Medicine |
| Concentra |
| WorkCare |
| Axiom Medical |
| Nova Medical Centers |
| Others |
Value Network & Pricing Analysis
I-10 corridor freight costs from Houston to Los Angeles directly shape clinic network expansion economics and downstream price differentiation for mobile screening services. Supply concentration in Texas and California metro areas creates tiered access costs that remote Mountain West employers absorb through telemedicine premiums or travel surcharges.
Pricing Analysis
Metropolitan-rural price spreads of 40-60% separate Houston clinic rates from Permian Basin mobile unit deployments, with fuel and clinician travel time as primary drivers. Three-tier pricing structure across premium concierge, standard clinic-based, and economy telemedicine levels dominates contract structures. Price differentiation rests on certification level (board-certified occupational medicine physician vs. nurse practitioner) and geographic delivery cost. Pricing pressure stems from Texas workers compensation fee schedule compression for functional capacity evaluations. SMEs exhibit highest price sensitivity, while self-insured logistics operators in California's Inland Empire accept premium rates for integrated platforms.
Supply Chain Analysis
Export-control restrictions on advanced audiometric calibration equipment and AI-assisted diagnostic software limit vendor options for domestic clinic operators. Geographic supply concentration centers on German and Japanese manufacturers for precision spirometry systems, with domestic assembly for mobile unit chassis. Raw material dependencies include medical-grade sensors, specialized vehicle upfitting components, and cloud infrastructure for telemedicine platforms. Single-source vulnerability runs through certified industrial hygienist training pipelines operating on multi-year cycles. Distribution runs through third-party administrator networks that bundle clinic access, telemedicine triage, and nurse case management for enterprise clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across rural-urban access divides creates niche opportunities for technology-enabled challengers. Telemedicine adoption among SMEs is accelerating fastest where board-certified occupational medicine physician proximity is lowest.
For Market Incumbents: Insulate market position by deepening vertical integration into wearable biometric monitoring hardware and securing exclusive Gulf Coast petrochemical clinic network contracts. Threat from AI-assisted diagnostic platforms that reduce false-negative rates in audiometric screening demands counterinvestment in quality assurance automation. Certification investment in Cal/OSHA heat illness prevention protocols represents a critical lever for California market retention. For New Entrants and Emerging Players: Rural Mountain West construction and agriculture corridors offer the most penetrable white-space for telemedicine-enabled specialist access platforms. Louisiana benzene and 1,3-butadiene monitoring mandates exceed current local clinic capacity, creating entry opportunity for mobile screening specialists. Go-to-market angle should target third-party administrator bundling partnerships rather than direct employer sales. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform consolidators with telemedicine infrastructure and wearable device integration capabilities. Long-term viability hinges on recurring revenue share from biometric monitoring subscriptions rather than transactional screening volumes. Acquisition target archetype: regional clinic networks with dense Houston or Los Angeles footprints and underutilized mobile unit capacity. Signal to watch: OSHA heat stress rule finalization triggering enterprise physiological monitoring contract acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Unit Fleet Expansion | Permian Basin energy operators require hydrogen sulfide exposure screening across dispersed drilling sites. |
| Telemedicine Platform Integration | Mountain West SMEs lack proximity to board-certified occupational medicine physicians for complex case management. |
| Wearable Device Partnership | California heat illness prevention standards drive demand for real-time core temperature monitoring in warehouse operations. |
| AI-Assisted Diagnostic Deployment | Appalachia mining employers pilot automated audiometric interpretation to reduce false-negative detection rates. |
| Gulf Coast Clinic Network Acquisition | Louisiana petrochemical facilities face benzene monitoring mandates exceeding current local provider capacity. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with occupational medicine physicians, clinic operations directors, third-party administrator executives, and self-insured employer benefits managers; and secondary validation through OSHA enforcement databases, state workers compensation fee schedules, FDA medical device filings, and hospital procurement records. Bottom-up triangulation across service type volumes and top-down macroeconomic calibration ensured cross-verification of market sizing assumptions.
Forecast inputs considered service type segmentation, end user scale tiers, technology deployment models, and application use cases across the analysis window. CAGRs derived from regression analysis against OSHA regulatory action timelines, industrial employment projections, and healthcare labor supply constraints. Industry-specific inputs included silica enforcement intensity indices and heat stress rule development trajectories.
Practitioners should monitor OSHA national emphasis program shifts and state-level workers compensation reforms for early signals of demand recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and clinical workforce pipeline stability. Material shifts in federal heat stress rule finalization or certified industrial hygienist graduation rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety & Security
Global Biometric Card Market
Safety & Security
Europe Baggage and Parcel Screening Market
Safety & Security
Security Camera Software Market
Safety & Security
Europe Safety Connection Devices Market
Safety & Security
Bullet Proof Jackets Market
Safety & Security
Global Integration Security Services Market
Safety & Security
Integrated Video Surveillance Systems Market
Safety & Security
Global Biometric Identification Market
Safety & Security
Global Public Safety Analytics Market
Safety & Security
N95 Mask Market
Safety & Security
Global Biometric-As-A-Service Market
Safety & Security
Blast Resistant and Bulletproof Buildings Market
Safety & Security
Fireproof Insulation Market
Safety & Security
Access Control Market
Safety & Security
Scuba Gloves Market
Safety & Security
Fire Protection Systems Market