
 UAE Life and Annuity Insurance Market | 2026-2036
UAE Life and Annuity Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Life and Annuity Insurance Market Analytics
Corporate group coverage among construction and logistics employers is realigning the buyer base away from purely individual retail channels. Emirates Insurance Company leverages its sovereign-linked distribution to dominate public-sector employee schemes. Sukoon Insurance sustains competitive positioning through Shariah-compliant product specialization. Abu Dhabi National Insurance Company anchors its portfolio in high-net-worth endowment structures tailored to Emirati family offices.
Life and annuity insurance encompasses contractual risk transfer instruments where insurers pool mortality and longevity exposures through actuarially priced premium schedules, with reserves held against future liability run-off. These products function primarily as financial stabilization mechanisms, converting uncertain life-event risks into predictable cash flow obligations for households and pension sponsors. Investment-linked products are capturing margin pools as policyholders shift from traditional guaranteed returns toward unit-linked structures with equity participation. Term life coverage competes aggressively on price through direct online platforms, while whole life persists among legacy bank-assurance channels. Broker distribution still controls the SME segment where complex multi-life arrangements require intermediary structuring.
UAE Central Bank regulations govern solvency ratios and product filing standards, while SAMA-aligned frameworks from neighboring Saudi Arabia influence regional best practices for takaful capital requirements. MOHAP health benefit mandates indirectly steer employer-sponsored life coverage bundling. Stakeholders must monitor how IFRS 17 implementation reshapes reserve disclosure and whether digital sandbox licensing opens direct-to-consumer channels beyond traditional agent networks.
Market Dynamics
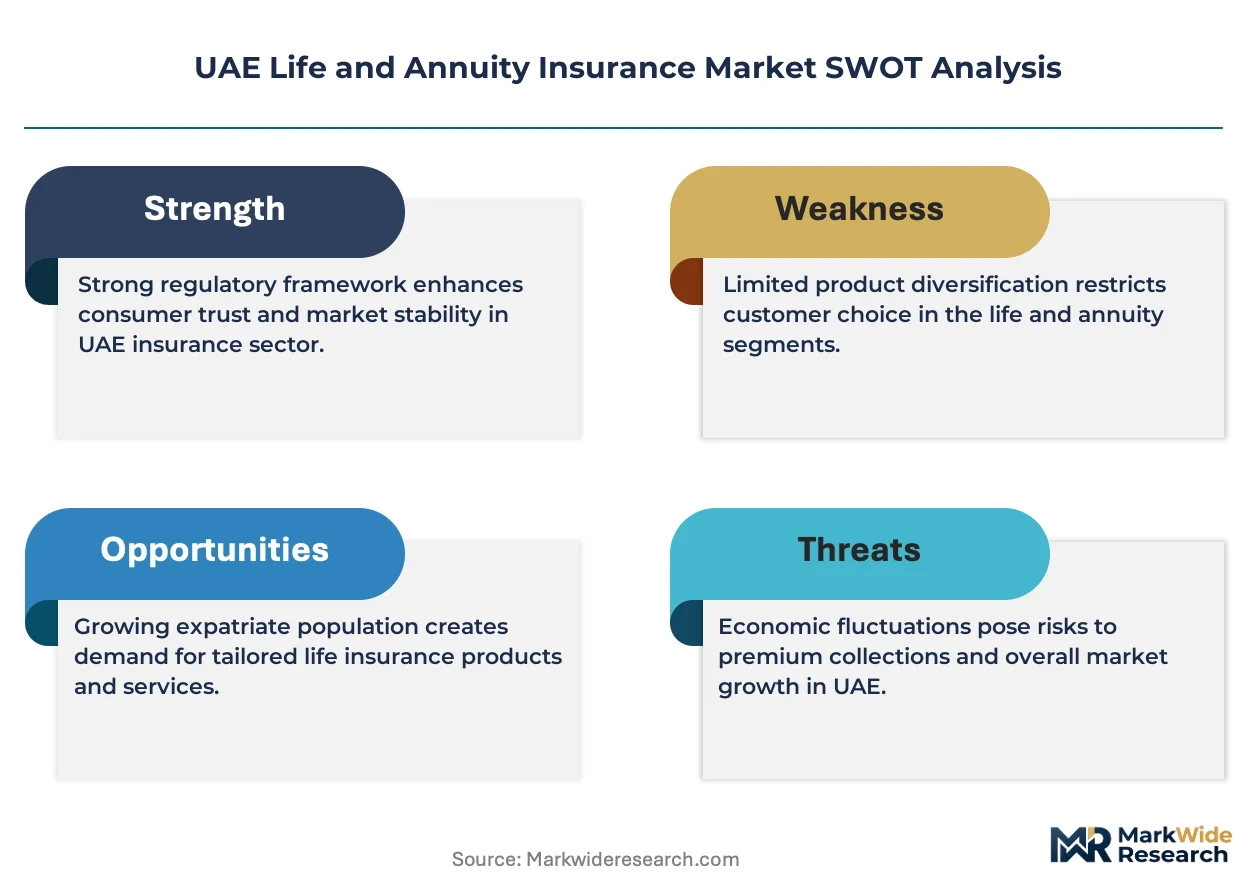
UAE Central Bank capital adequacy tightening is compressing product reserve margins and forcing insurers into unit-linked structures that transfer investment risk to policyholders.
Growth Catalysts
- Expatriate workforce expansion:Corporate group schemes among construction and logistics employers are deepening policy uptake beyond traditional retail channels.
- IFRS 17 implementation:Enhanced reserve disclosure standards are driving demand for actuarial advisory services and modernized policy administration systems.
- Shariah-compliant product specialization:Takaful frameworks aligned with SAMA regional standards are capturing underserved segments in Abu Dhabi's sovereign wealth-adjacent corridors.
Market Restraints
- Central bank solvency friction:UAE Central Bank reserve requirements are elevating capital lock-up costs and constraining product innovation cycles.
- Interest rate volatility:Guaranteed return liabilities face margin compression when benchmark rates diverge from pricing assumptions.
- Direct platform substitution:Online term life aggregators are eroding traditional bank-assurance commission structures in Dubai's financial free zones.
Strategic Opportunities
- Digital sandbox licensing:UAE Central Bank regulatory sandboxes are opening direct-to-consumer channels beyond traditional agent networks.
- Endowment-wealth management convergence:High-net-worth structures tailored to Emirati family offices are capturing margin pools from conventional deposit products.
- MOHAP mandate bundling:Employer-sponsored life coverage packaged with health benefits is penetrating SME segments previously served by standalone policies.
Industry Challenges
- Actuarial talent scarcity:IFRS 17 technical expertise shortages are delaying implementation timelines for mid-tier insurers.
- Legacy system integration:Policy administration platforms require capex-intensive upgrades to support real-time reserve reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Life and Annuity Insurance Market |
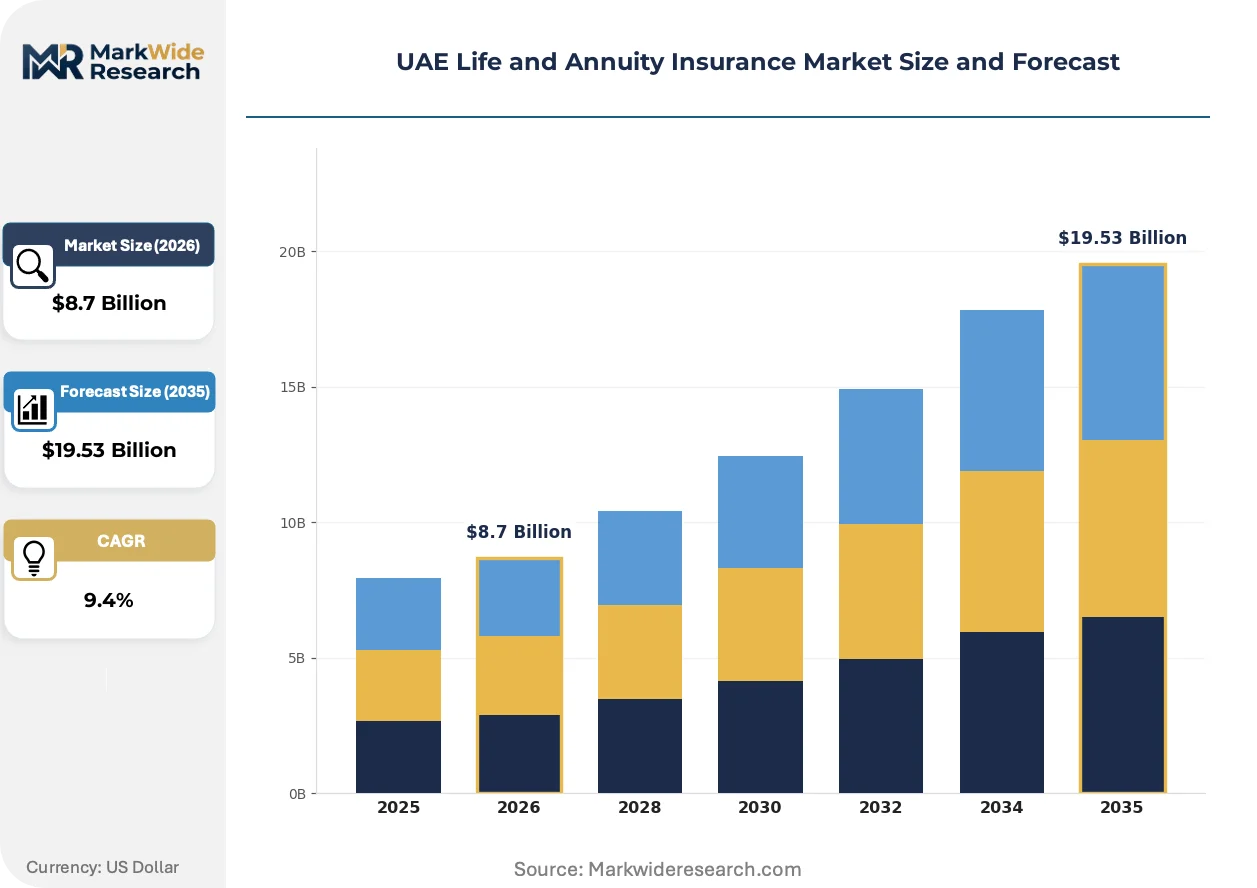
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Life, Term Life, Endowment, Investment-Linked Distribution Channel: Direct Sales, Insurance Agents, Brokers, Online Platforms Customer Type: Individuals, Corporates, High-Net-Worth Individuals, SMEs Payment Mode: Monthly, Quarterly, Annually, Single Premium |
| Companies Covered | Emirates Insurance Company, Sukoon Insurance, Abu Dhabi National Insurance Company, Emirates NBD, RAK Bank, Orient Insurance, Al Ain Ahlia Insurance, Oman Insurance, SALAMA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Life and Annuity Insurance Market Evolving Landscape
Technology and regulatory frameworks are converging to reshape how mortality and longevity risks are priced, distributed, and serviced across the Emirates.
Embedded insurance APIs are expanding into payroll and HR management platforms, enabling real-time enrollment for corporate group schemes. Construction and logistics employers in Dubai's free zones are adopting these integrations to automate beneficiary updates. The technology is expanding into SME segments previously excluded from streamlined underwriting.
UAE Central Bank digital sandbox frameworks are permitting algorithmic underwriting models that compress policy issuance from weeks to hours. Insurers must demonstrate model governance to the regulator before full licensing. The framework most affects direct online term life platforms competing on price transparency.
Wealth management advisors are unbundling life coverage from traditional deposit products, creating standalone advisory relationships with Emirati family offices. Private banks in Abu Dhabi are displacing legacy bank-assurance channels with fee-based insurance structuring. This behavioral shift concentrates in sovereign wealth-adjacent corridors where endowment products dominate.
UAE Life and Annuity Insurance Market Segmentation
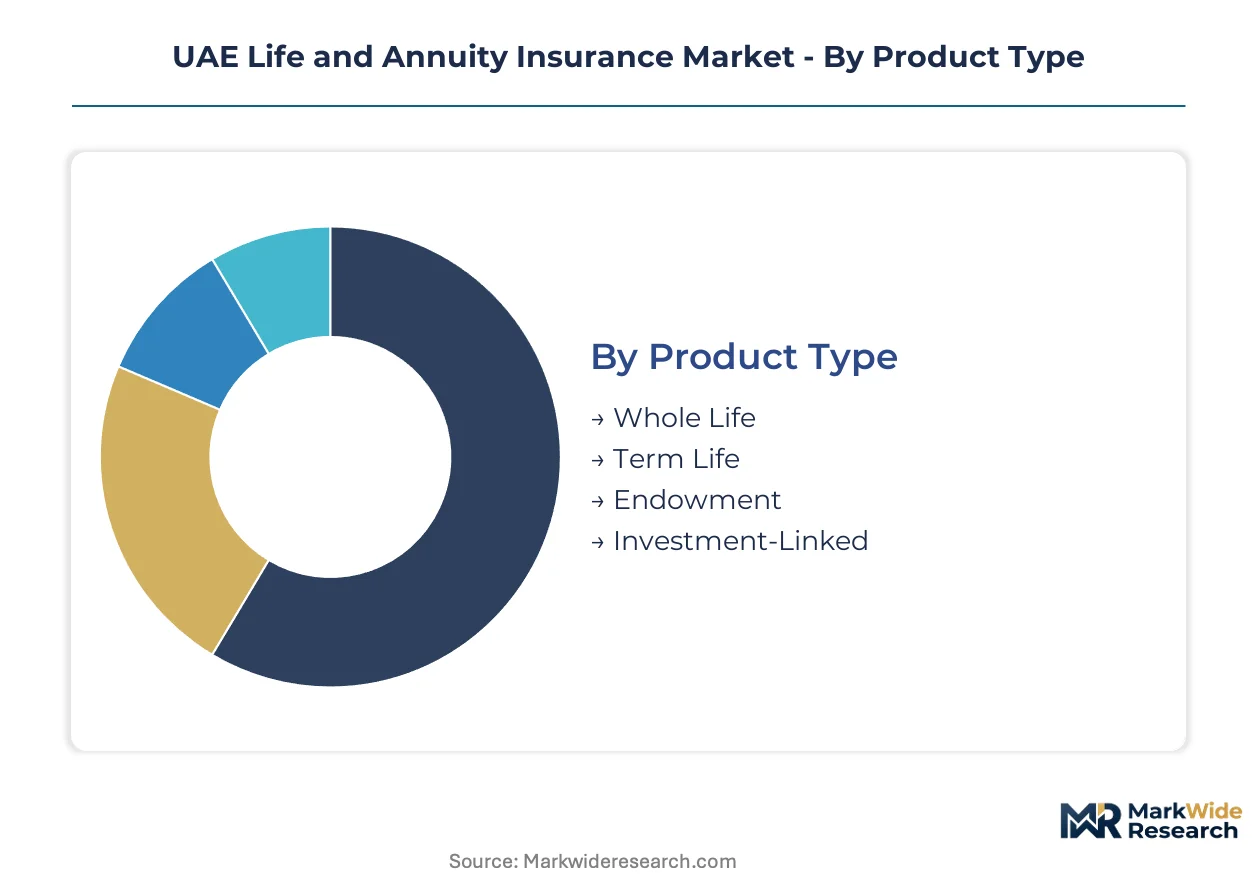
Product architecture and distribution economics segment the UAE life and annuity insurance market into distinct competitive arenas. Buyer sophistication varies sharply between corporate group purchasers and individual retail clients, creating tiered pricing and service models across channels.
Product Type:
Buyer risk appetite determines product selection, with investment-linked offerings displacing guaranteed-return structures among affluent segments.
- Whole Life:Permanent coverage combines mortality protection with cash value accumulation through insurer-managed reserves. Demand concentrates in Abu Dhabi's sovereign wealth-adjacent corridors where Emirati family offices seek estate preservation instruments.
- Term Life:Pure mortality coverage without cash value component, priced on age-rated renewable schedules. Dubai's financial free zones drive volume through expatriate workforce schemes requiring temporary protection aligned with employment contracts.
- Endowment:Savings-cum-protection contracts with defined maturity benefits and participating profit shares. Sukoon Insurance and ADNIC target this structure for Shariah-compliant wealth accumulation.
- Investment-Linked:Unit-linked policies where policyholders bear investment risk through segregated fund selections. UAE Central Bank capital adequacy tightening accelerates carrier migration toward this risk-transfer format.
Volume sits with Term Life; growth tilts toward Investment-Linked.
Distribution Channel:
Channel economics reflect customer acquisition costs and policy complexity, with intermediaries dominating multi-life arrangements.
- Insurance Agents:Captive or independent representatives earning commission on first-year premiums and renewals. Individual retail penetration in Dubai's residential corridors depends on agent face-to-face underwriting for medical disclosures.
- Brokers:Independent intermediaries structuring complex corporate group schemes and SME multi-life arrangements. Construction and logistics employers in Jebel Ali Free Zone rely on broker expertise for beneficiary administration.
- Direct Sales:Carrier-employed advisors targeting public-sector employee schemes through sovereign-linked relationships. Emirates Insurance Company leverages this channel for government workforce coverage.
- Online Platforms:Algorithmic underwriting portals compressing issuance timelines for standardized term products. UAE Central Bank digital sandbox licensing enables direct-to-consumer expansion beyond traditional networks.
Brokers capture the highest policy values; online platforms are expanding most quickly.
Customer Type:
Customer scale determines product customization depth and servicing intensity across the Emirates.
- Corporates:Large employers sponsoring group life schemes with automatic enrollment and master policy administration. Construction sector concentration in Dubai South generates bulk policy uptake through payroll deduction structures.
- High-Net-Worth Individuals:Affluent clients requiring bespoke endowment and universal life structures with premium financing. Private banks in Abu Dhabi Global Market displace legacy channels with fee-based insurance advisory.
- Individuals:Retail purchasers of standalone protection products through bank-assurance or direct channels. Term life dominates this segment on price-competitive positioning.
- SMEs:Small and mid-sized enterprises with simplified underwriting requirements and lower coverage multiples. MOHAP health benefit mandates indirectly drive bundled life coverage adoption.
Corporates anchor premium volume; SMEs show the steepest expansion trajectory.
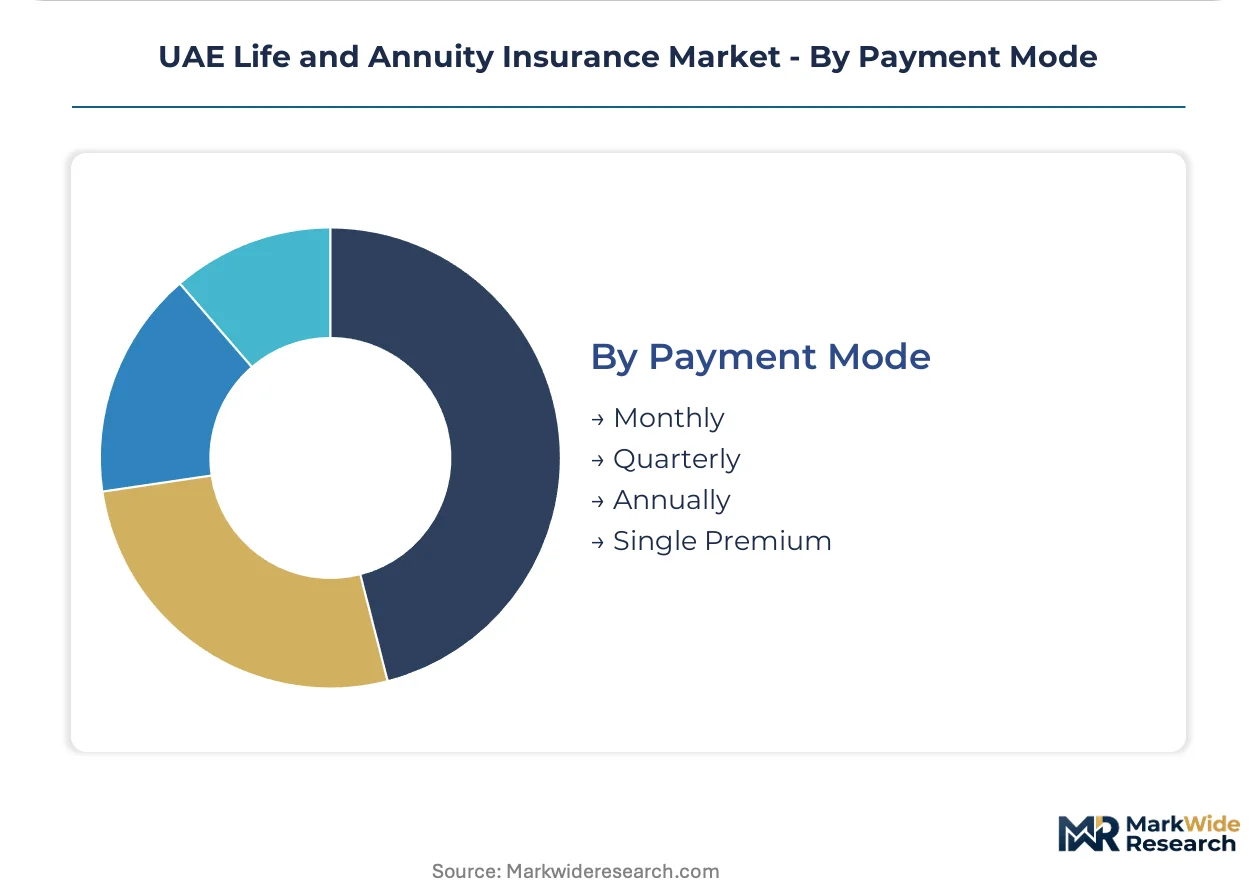
Payment Mode:
Cash flow timing preferences segment buyers by liquidity position and premium financing access.
- Single Premium:Lump-sum payment eliminating future obligation uncertainty and reducing lapse risk. High-net-worth endowment purchasers in Abu Dhabi favor this mode for immediate policy collateralization.
- Annually:Yearly premium schedules with modal discount incentives versus more frequent payments. Corporate group schemes default to annual billing for administrative simplicity.
- Monthly:Payroll-deducted premiums aligning with expatriate employment cycles in Dubai's free zones. This mode expands accessibility for lower-income retail segments.
- Quarterly:Intermediate frequency balancing cash flow management with modal cost efficiency. Limited uptake relative to monthly and annual alternatives.
Annual payment dominates persistency; monthly modes are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Abu Dhabi Global Market and Dubai International Financial Centre anchor insurance concentration through tax-efficient structuring and regulatory sandbox access. UAE Central Bank licensing frameworks in these zones compress capital adequacy compliance costs for takaful and conventional carriers alike. Expatriate workforce density in these corridors drives group scheme penetration beyond national averages.
Dubai
Construction and logistics employers in Jebel Ali Free Zone and Dubai South generate bulk policy uptake through payroll-deducted group life arrangements. UAE Central Bank digital sandbox licensing enables algorithmic underwriting platforms to compress term life issuance timelines. Dubai International Financial Centre clusters wealth management advisors unbundling coverage from traditional deposit products for high-net-worth expatriates.
Abu Dhabi
Sovereign wealth-adjacent family offices in Al Maryah Island and Yas Island drive demand for bespoke endowment structures with premium financing features. MOHAP health benefit mandates indirectly steer employer-sponsored life coverage bundling among public-sector entities. Abu Dhabi Global Market regulatory frameworks permit Shariah-compliant takaful specialization aligned with SAMA regional standards.
Sharjah
Mid-market retail penetration concentrates in residential corridors where bank-assurance channels dominate standalone protection product distribution. The emirate's manufacturing base generates SME group scheme demand through broker-structured multi-life arrangements. Sharjah Islamic Bank partnerships sustain takaful product accessibility for cost-conscious retail segments.
Northern Emirates
Fujairah and Ras Al Khaimah present underpenetrated corridors where direct online platforms expand accessibility beyond traditional agent networks. Lower expatriate income profiles favor monthly premium modes aligned with employment cycles. Local insurer branches compete on simplified underwriting for standardized term products.
UAE Life and Annuity Insurance Market Competitive Landscape
Top-tier vendors anchor public-sector and sovereign-linked distribution, while mid-tier specialists compete through Shariah-compliant product differentiation and digital channel expansion. The market structure consolidates around state-affiliated carriers with privileged access to government workforce schemes, alongside takaful operators capturing underserved segments. Strategic archetypes include sovereign-linked incumbents, Shariah-compliant specialists, and digital-first direct platforms. Competitive moves center on regulatory sandbox licensing for algorithmic underwriting and wealth management advisory unbundling from legacy bank-assurance structures.
Among UAE-based carriers, Emirates Insurance Company and Abu Dhabi National Insurance Company occupy positions within the sovereign-linked tier, leveraging public-sector relationships for group scheme dominance. Sukoon Insurance exemplifies the Shariah-compliant specialist archetype, sustaining competitive positioning through takaful capital structures aligned with regional SAMA frameworks. These three entities represent distinct strategic vectors: state-affiliated distribution access, religious compliance specialization, and hybrid conventional-takaful product architecture.
| Leading Market Players |
|---|
| Emirates Insurance Company |
| Sukoon Insurance |
| Abu Dhabi National Insurance Company |
| Emirates NBD |
| RAK Bank |
| Orient Insurance |
| Al Ain Ahlia Insurance |
| Oman Insurance |
| SALAMA |
| Others |
Value Network & Pricing Analysis
Captive distribution through bank-assurance partnerships anchors both the supply position and pricing power for legacy carriers, while direct online platforms erode this integration through disintermediated term life offerings. UAE Central Bank capital adequacy requirements compress guaranteed-return product margins, forcing carriers toward unit-linked structures that transfer investment risk.
Pricing Analysis
Short lead-time issuance commands premium pricing in Dubai's financial free zones, where algorithmic underwriting platforms compress policy delivery from weeks to hours. Three-tier pricing structure across premium, standard, and economy levels segments buyers by underwriting complexity and service bundling. Cost compression in term life channels is intensifying because direct online aggregators bypass traditional commission structures. Corporate group schemes show lowest price sensitivity due to payroll-deducted administrative convenience, while individual retail segments compete aggressively on premium transparency.
Supply Chain Analysis
Regional distribution centers in Dubai International Financial Centre and Abu Dhabi Global Market anchor hub-and-spoke patterns for policy administration and claims servicing. Reinsurance capacity concentrates in London, Bermuda, and Singapore, with UAE carriers ceding mortality risk to international markets. Raw material dependencies include actuarial talent pools, legacy system infrastructure, and regulatory compliance technology. Single-source vulnerability sits with concentrated reinsurer relationships during peak issuance periods. Distribution runs through broker networks for SME multi-life arrangements and direct platforms for standardized term products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE life insurance sector occupies a technology-transition phase, with embedded insurance APIs and algorithmic underwriting displacing legacy agent-driven enrollment and paper-based policy administration.
For Market Incumbents: To counter direct platform substitution in term life, Emirates Insurance Company and ADNIC should deepen bank-assurance channel control through exclusive product partnerships, while accelerating captive actuarial talent acquisition to compress IFRS 17 implementation timelines. For New Entrants and Emerging Players: Capture white-space opportunity in Sharjah and Northern Emirates retail corridors where traditional agent networks underpenetrate cost-conscious segments. Algorithmic underwriting platforms targeting monthly premium modes through mobile-first distribution represent the most penetrable entry vector. For Investors and Strategic Acquirers: Exit pathways concentrate in takaful specialization and digital sandbox licensing acquisitions. Long-term viability favors carriers with hybrid conventional-takaful architecture and real-time reserve reporting capability. Monitor UAE Central Bank digital sandbox full licensing approvals as the critical inflection signal for direct-to-consumer channel viability.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Underwriting Platform Deployment | UAE Central Bank sandbox licensing enables hour-level policy issuance versus legacy week-long timelines. |
| Takaful Product Architecture Expansion | SAMA-aligned capital structures capture underserved segments in Abu Dhabi's sovereign wealth corridors. |
| Embedded Insurance API Integration | Payroll and HR platform partnerships automate enrollment for construction sector group schemes. |
| Actuarial Talent Acquisition Program | IFRS 17 technical expertise shortages threaten implementation timelines for mid-tier carriers. |
| Wealth Management Advisory Unbundling | Fee-based insurance structuring displaces legacy bank-assurance channels for high-net-worth Emirati clients. |
Research Methodology
Independent corroboration across UAE Central Bank regulatory filings, SAMA takaful framework documentation, and MOHAP employer mandate circulars underwrites the qualitative findings. Primary interviews with chief actuaries, distribution channel heads, and digital transformation officers at tier-one and tier-two insurers combined with secondary validation from policy administration system vendors and reinsurance brokers. Bottom-up policy issuance data and top-down premium pool estimates triangulate market sizing.
Rate-of-change decomposition across product type, distribution channel, customer segment, and payment mode dimensions structures the analytical framework. CAGRs derive from fitted growth curves against historical issuance trajectories and projected expatriate workforce expansion. Mortality assumption updates, reserve discount rate movements, and digital channel penetration curves constitute key forecast inputs throughout the projection horizon.
The model holds under stable UAE Central Bank solvency requirements and continued expatriate employment growth; deviation in interest rate volatility or regulatory sandbox suspension would shift carrier product mix assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Greece Life and Non-Life Insurance Market
Life and Non Life Insurance
Teenager Life Insurance Market
Life and Non Life Insurance
Uruguay Life and Non-Life Insurance Market
Life and Non Life Insurance
Malaysia Life Insurance Market
Life and Non Life Insurance
US Burial Insurance Market
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market
Life and Non Life Insurance
Asia Pacific Life & Non-Life Insurance Market
Life and Non Life Insurance
Sweden Life and Non-Life Insurance Market
Life and Non Life Insurance
Austria Life and Non-Life Insurance Market
Life and Non Life Insurance
Germany Life and Non-Life Insurance Market
Life and Non Life Insurance
UAE Life & Non-Life Insurance Market
Life and Non Life Insurance
Burial Insurance Market
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market
Life and Non Life Insurance
Denmark Life and Non-Life Insurance Market
Life and Non Life Insurance
Global Life and Non-Life Insurance Market
Life and Non Life Insurance
China Life and Non-Life Insurance Market