
 Toilet Care Products Market | 2026-2036
Toilet Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Toilet Care Products Market Outlook
Consolidation among hotel chains and facility management companies is repositioning procurement power toward large-scale contract buyers. Henkel leverages its European manufacturing footprint to serve these consolidated accounts with customized dispensing systems. Reckitt Benckiser Group competes through concentrated formula technologies that reduce logistics costs for bulk purchasers. Procter & Gamble anchors its position via brand equity in North American retail channels while extending professional-grade lines into commercial contracts.
Toilet care products encompass chemically formulated cleaning agents, disinfectants, and deodorizing systems designed for ceramic sanitation fixtures, typically containing surfactants, quaternary ammonium compounds, or organic acids at pH ranges optimized for mineral deposit removal and bacterial control. Their primary purpose is maintaining hygienic conditions in enclosed restroom environments while preventing surface degradation. Liquid cleaners dominate value contribution due to formulation flexibility and established consumer habits, while gel cleaners represent the fastest-expanding format as viscosity engineering improves cling time and reduces application frequency. The residential application segment sustains volume leadership, though institutional procurement generates superior margin pools through specification-driven compliance requirements.
EPA registration mandates under FIFRA govern antimicrobial claims in the United States, while REACH and the EU Detergents Regulation restrict surfactant biodegradability thresholds across Europe, collectively elevating R&D expenditure for multi-market compliance. India's BIS certification and FSSAI-adjacent state-level sanitation directives create additional formulation adaptation requirements for entrants targeting municipal tenders. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as pending EPA hazard designations and corresponding state-level prohibitions threaten legacy protective-coating chemistries and demand substitute validation investments.
Market Dynamics
Hotel chain consolidation and facility management outsourcing are compressing procurement cycles while elevating specification complexity, forcing suppliers to embed compliance documentation directly into dispensing hardware and concentrate formulation portfolios around multi-jurisdictional registrations.
Growth Catalysts
- REACH Detergents Regulation:Biodegradability mandates across Europe are filtering supplier bases toward specialized surfactant manufacturers with validated environmental fate data, accelerating premium tier uptake.
- Municipal sanitation upgrades in India:State-level tender volumes for institutional-grade disinfectants are expanding as urban local bodies modernize public restroom infrastructure in tier-1 and tier-2 cities.
- Viscosity engineering:Thixotropic gel formulations with extended cling times are reducing application frequency for commercial cleaners, creating labor cost savings that justify higher per-unit pricing.
Market Restraints
- Quaternary ammonium compound supply concentration:Production of benzalkonium chloride and related biocides clusters in Chinese chemical manufacturing hubs, exposing formulators to shipping cost volatility and customs processing delays.
- EPA FIFRA registration timelines:Antimicrobial claim validation requires 18-36 month review cycles with no guaranteed approval, freezing formulation pipelines and elevating working capital requirements for pending submissions.
- Per- and polyfluoroalkyl substance restrictions:Pending EPA hazard designations and state-level prohibitions in New York and Maine threaten legacy protective-coating chemistries, demanding substitute validation investments with uncertain performance parity.
Strategic Opportunities
- Underpenetrated institutional segments in Brazil:ANVISA regulatory harmonization with OECD test guidelines is reducing registration friction for European and North American suppliers targeting hospital and airport concession contracts.
- Smart dispensing convergence:Integration of IoT-enabled usage tracking with concentrated cartridge systems is unifying facility management software with consumables procurement, creating subscription revenue streams.
- EU Green Deal procurement mandates:Public sector ecolabel requirements under the EU GPP criteria are tilting tender awards toward bio-based acid formulations and refillable packaging architectures.
Industry Challenges
- Multi-jurisdictional registration portfolio management:Maintaining concurrent EPA, REACH, and BIS dossiers requires specialized regulatory affairs capacity that mid-size formulators struggle to staff, creating compliance gaps during renewal windows.
- Legacy dispensing infrastructure incompatibility:Concentrated and ultra-concentrated chemistries often require hardware modifications incompatible with installed bases of dilution-control equipment, slowing adoption in retrofit-heavy commercial accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toilet Care Products Market |
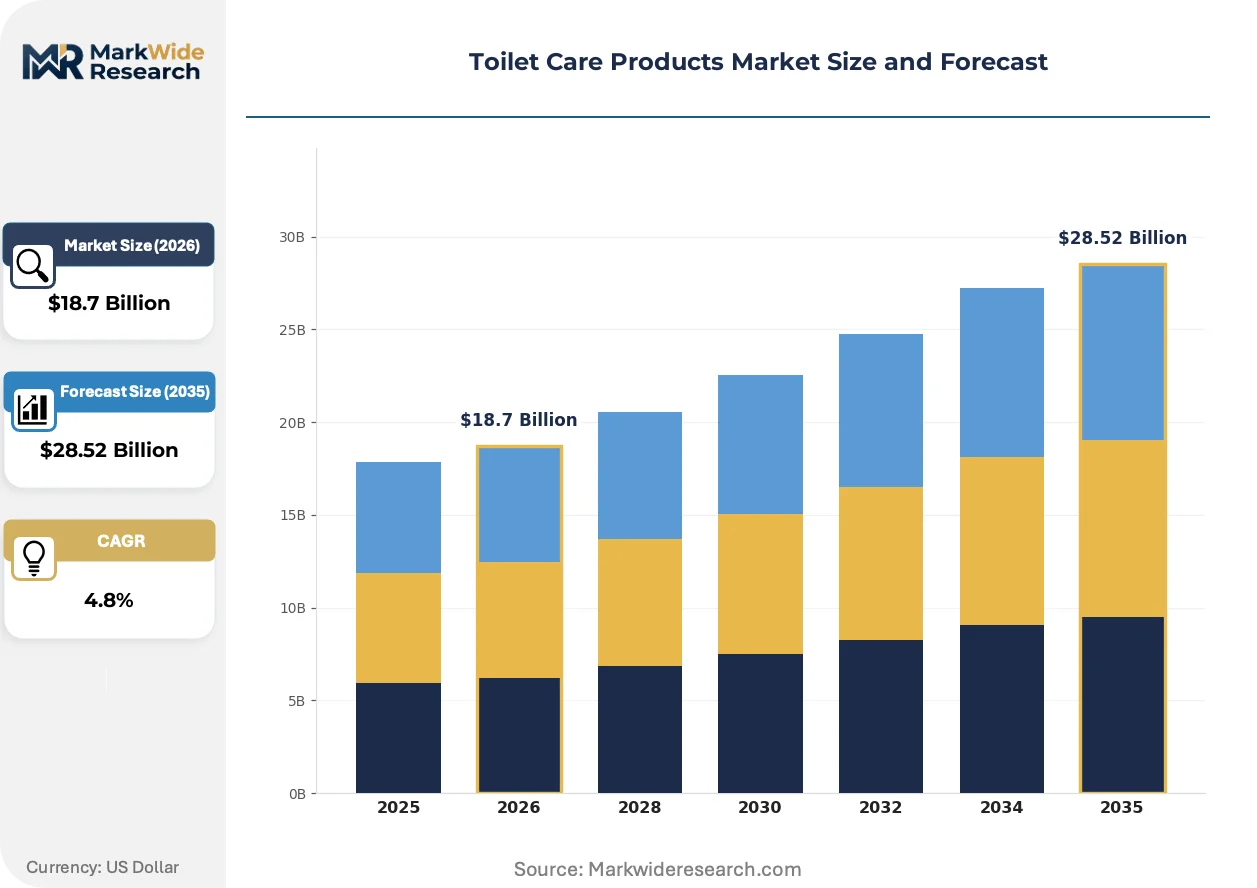
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cleaners, Toilet Tablets, Gel Cleaners, Disinfectant Wipes Application: Residential, Commercial, Industrial, Institutional Packaging Type: Bottles, Sachets, Jars, Pouches Distribution Channel: Online Retail, Supermarkets, Hypermarkets, Specialty Stores |
| Companies Covered | Henkel, Clorox Company, Reckitt Benckiser Group, Kao Corporation, Church & Dwight, Procter & Gamble, SC Johnson, S.C. Johnson & Son, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toilet Care Products Market Strategic Shifts
Formulation chemistry and delivery hardware are converging into integrated systems that embed compliance, traceability, and labor efficiency into single procurement decisions, compressing the traditional separation between product and service.
Enzymatic cleaning technologies incorporating protease and amylase blends are unifying organic stain removal with biofilm disruption in a single application step. Healthcare facility managers in Germany and the Netherlands are specifying these systems for overnight cleaning protocols. The technology is unifying previously separate product categories—general cleaners and disinfectants—into dual-claim formulations that reduce SKUs and storage footprint.
REACH restrictions on microplastic-containing leave-on products are extending to rinse-off toilet care formulations, compelling suppliers to reformulate abrasive suspensions and visual indicator beads. ECHA guidance on polymer registration thresholds is forcing disclosure of synthetic fragrance encapsulation technologies. European private-label manufacturers are responding by accelerating partnerships with natural abrasive suppliers processing crushed walnut shell and mineral silica alternatives.
Facility management companies are consolidating vendor panels and demanding consolidated reporting on chemical usage, safety incidents, and sustainability metrics. Tier-1 contract cleaners in the United Kingdom are replacing fragmented spot-purchasing with framework agreements bundling dispensing hardware, formulation supply, and compliance documentation. This concentration is most visible in airport and railway station concessions, where single-source accountability reduces audit complexity across distributed restroom networks.
Toilet Care Products Market Segmentation
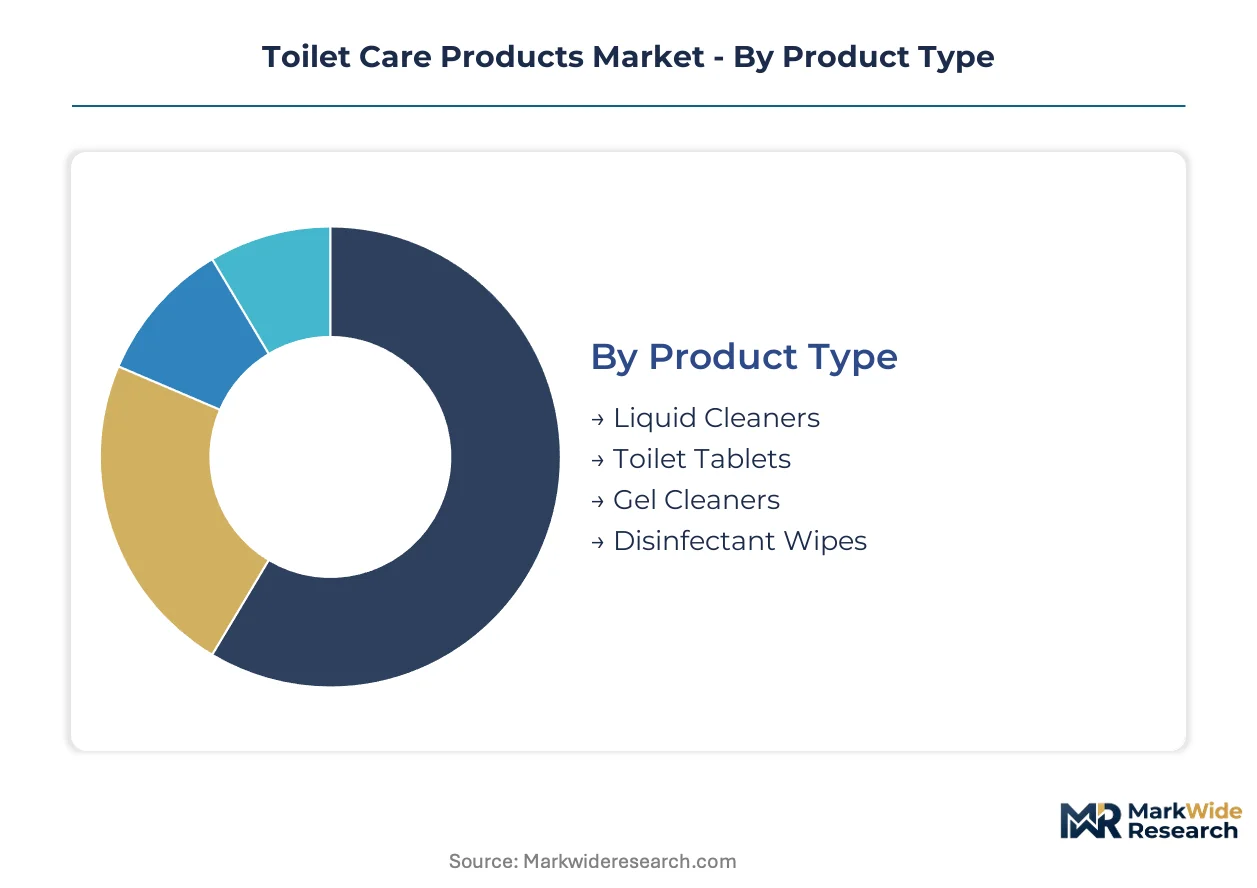
Segmentation in toilet care products separates volume-driven retail formats from specification-heavy institutional procurement, each demanding distinct formulation portfolios, compliance documentation, and margin structures. Understanding these divides clarifies where capital deployment yields sustainable returns versus commodity exposure.
Product Type:
Capital intensity peaks in gel manufacturing, where viscosity engineering and precision dispensing systems require specialized mixing equipment and quality control infrastructure.
- Liquid Cleaners:Surfactant-based formulations with adjustable pH chemistry dominate manufacturing throughput due to flexible batch processing and established raw material supply chains. Demand concentrates in North American retail channels where spray-dispense ergonomics and familiar usage rituals sustain repeat purchase loyalty despite gel alternatives.
- Gel Cleaners:Thixotropic formulations engineered for extended cling time on vertical ceramic surfaces command premium positioning through reduced application frequency. Procurement volumes are climbing fastest in German and Dutch healthcare facilities where overnight cleaning protocols favor single-application efficiency.
- Toilet Tablets:Slow-release chlorine and surfactant matrices for tank-dispensed maintenance.
- Disinfectant Wipes:Pre-saturated cellulose substrates with quaternary ammonium or hydrogen peroxide chemistries for touchpoint sanitation.
Most installed capacity flows through Liquid Cleaners. Expansion is steepest in Gel Cleaners.
Application:
Margin capture varies sharply by compliance burden, with institutional accounts demanding multi-jurisdictional registration portfolios that filter out smaller formulators.
- Residential:Brand equity and shelf placement drive purchase decisions in mass retail environments where fragrance profiles and packaging aesthetics outweigh technical specifications. India's urban centers are absorbing volume growth as municipal sanitation upgrades and middle-class expansion normalize category penetration.
- Institutional:Specification-driven procurement for hospitals, airports, and municipal facilities requires EPA FIFRA or REACH-compliant documentation bundled with dispensing hardware and usage reporting. Tender awards in tier-1 and tier-2 Indian cities are accelerating as urban local bodies modernize public restroom infrastructure.
- Commercial:Office buildings, retail spaces, and hospitality venues with outsourced facility management.
- Industrial:Manufacturing facilities and logistics hubs with heavy-duty soil loads and shift-based cleaning schedules.
Revenue concentration sits with Institutional applications. Volume leadership remains with Residential.
Packaging Type:
Packaging selection tracks distribution economics, with refillable formats gaining traction where concentrated chemistries reduce logistics cost per active dose.
- Bottles:Standard HDPE and PET containers with trigger sprayers or flip-cap dispensing dominate retail shelf presence.
- Sachets:Single-use laminated film packets for emerging market price-sensitive consumers and travel segments.
- Jars:Wide-mouth containers for paste and abrasive formulations requiring scoop application.
- Pouches:Flexible refill formats compatible with concentrated chemistries and closed-loop dispensing systems.
Bottles carry the heaviest polymer cost exposure. Pouches are gaining fastest in European contract cleaning frameworks.
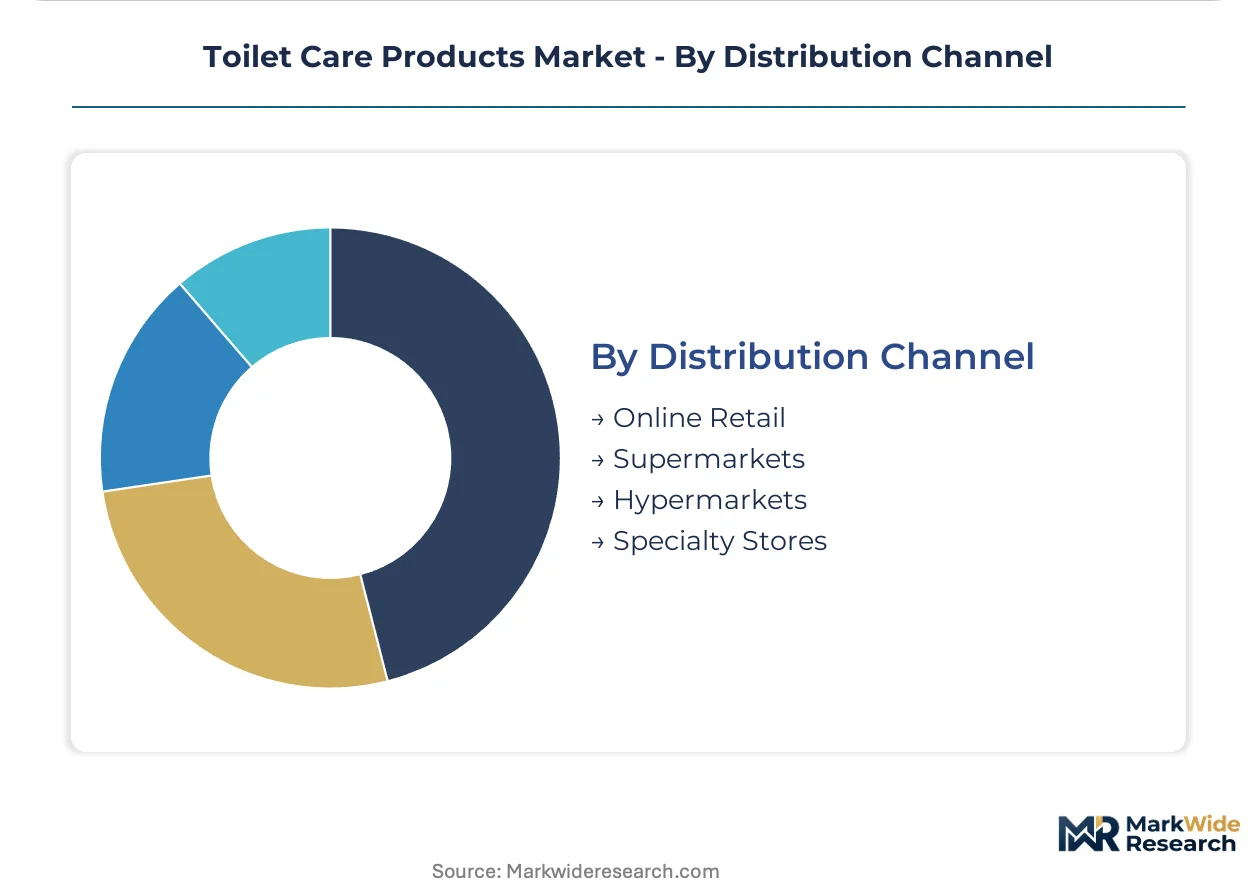
Distribution Channel:
Channel strategy determines working capital intensity, with retail requiring inventory float against slotting fees while direct institutional contracts stretch payment terms.
- Supermarkets:High-frequency replenishment environments where private-label competition and promotional pricing pressure branded margins.
- Online Retail:Subscription models and bulk purchasing platforms capturing pantry-loading behavior and reducing brand switching.
- Hypermarkets:Large-format retail with expanded SKU counts and cross-category merchandising opportunities.
- Specialty Stores:Janitorial supply and professional cleaning distributors serving commercial account specification requirements.
Supermarkets anchor volume throughput. Online Retail is expanding most quickly in subscription-format household replenishment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists and regulatory compliance officers cluster in Germany, the United States, India, Japan, and Brazil, anchoring regional innovation capacity for toilet care products.
United States
Commercial facility management outsourcing and hotel chain consolidation drive institutional procurement volumes. EPA FIFRA registration mandates govern antimicrobial claims and stretch validation timelines to 18-36 months. Formulation R&D concentrates in New Jersey and North Carolina chemical corridors where compliance documentation capabilities support multi-jurisdictional dossier management.
Germany
Healthcare facility managers specify enzymatic cleaning systems for overnight protocols in hospitals and elder care centers. REACH Detergents Regulation and ECHA microplastic restrictions filter supplier bases toward validated surfactant manufacturers. Industrial chemists in the Rhine-Ruhr cluster engineer thixotropic gel formulations with extended cling times for vertical ceramic surfaces.
India
Municipal sanitation upgrades in Mumbai, Delhi, and Bangalore expand tender volumes for institutional-grade disinfectants. BIS certification and state-level sanitation directives create formulation adaptation requirements for public restroom infrastructure modernization. Procurement officers in tier-1 and tier-2 cities award contracts bundling dispensing hardware with compliance documentation.
Japan
Compact urban dwellings and aging demographics sustain demand for low-odor, quick-drying formulations in residential channels. METI chemical safety guidelines and JIS standards elevate product performance thresholds for mineral deposit removal. Osaka-based formulators supply concentrated chemistries optimized for automated dispensing systems in high-traffic commercial venues.
Brazil
Hospital and airport concession contracts attract European and North American suppliers seeking growth beyond saturated home markets. ANVISA regulatory harmonization with OECD test guidelines reduces registration friction for antimicrobial formulations. São Paulo industrial parks host contract manufacturers adapting imported concentrate technologies for Latin American water hardness conditions.
Toilet Care Products Market Competitive Environment
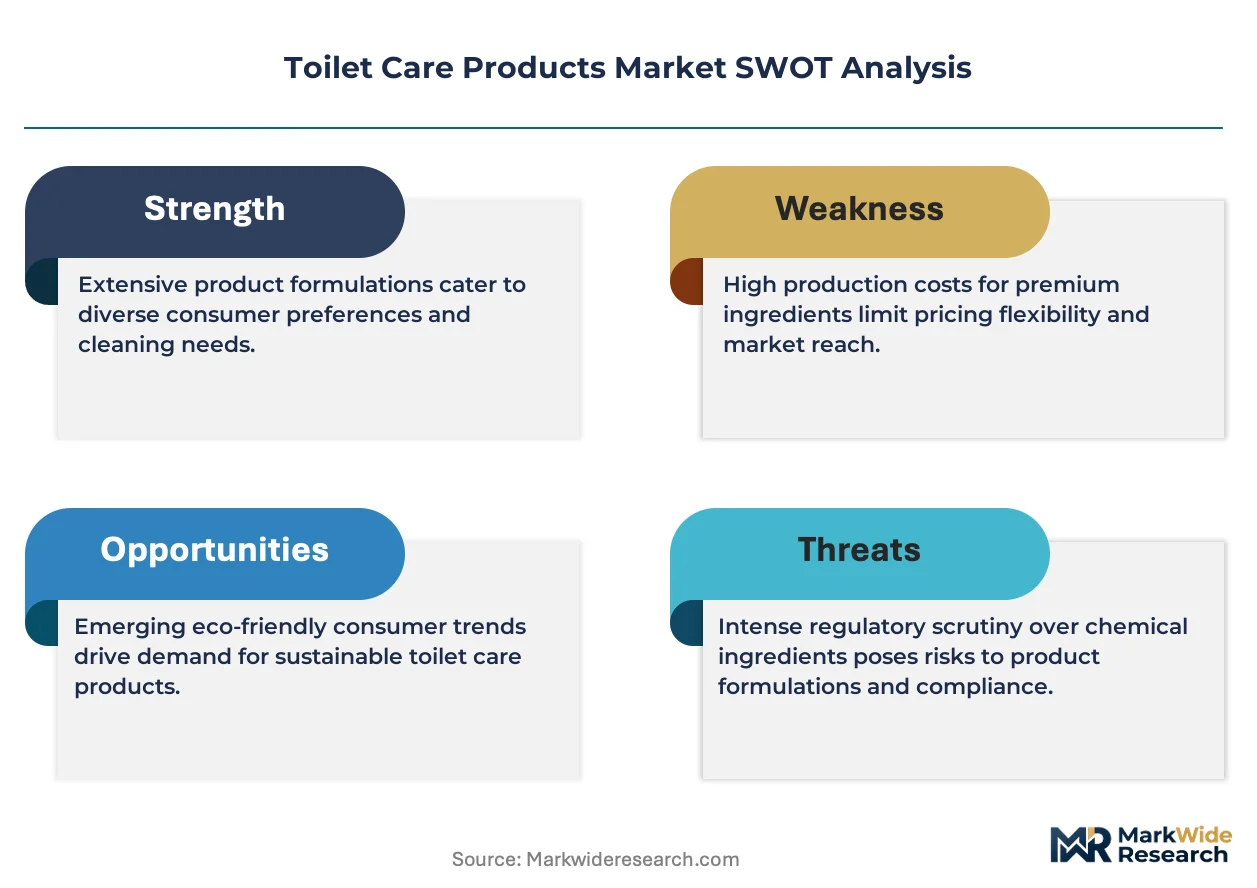
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation among facility management companies and hotel chains compresses procurement cycles while elevating specification complexity. Three archetypes dominate: European manufacturers with integrated dispensing hardware capabilities, North American consumer goods giants extending professional-grade lines, and Asian chemical specialists supplying surfactant intermediates. Competitive moves center on M&A to capture institutional contract relationships and strategic partnerships to embed IoT-enabled usage tracking into dispensing systems.
Within the diversified multinational tier, Henkel AG & Co. KGaA and Reckitt Benckiser Group plc occupy positions shaped by European manufacturing footprints and concentrated formula technologies. Procter & Gamble anchors the North American retail-to-commercial extension vector. These three exemplify how scale enables concurrent maintenance of EPA, REACH, and BIS registration portfolios that filter out mid-size competitors during tender renewal windows.
| Leading Market Players |
|---|
| Henkel |
| Clorox Company |
| Reckitt Benckiser Group |
| Kao Corporation |
| Church & Dwight |
| Procter & Gamble |
| SC Johnson |
| S.C. Johnson & Son |
| Unilever |
| Others |
Value Chain & Pricing Dynamics
Captive surfactant manufacturing in the Rhine-Ruhr chemical corridor anchors Henkel's supply position while enabling premium pricing power through REACH-compliant documentation bundled with dispensing hardware. This backward integration into quaternary ammonium compound synthesis insulates margin structures from Chinese benzalkonium chloride volatility that compresses pure-play formulators.
Pricing Analysis
Capacity additions in India's chemical manufacturing zones are reshaping price floors for standard-grade liquid formulations as domestic surfactant output expands. Three-tier pricing structure across premium, standard, and economy levels separates EPA-registered institutional disinfectants from retail shelf products, with certification tier and volume scale as primary differentiation drivers. Pricing pressure stems from consolidated procurement at hotel chains and facility management companies squeezing per-unit margins. Residential retail channels exhibit highest price sensitivity, while institutional buyers prioritize compliance documentation over unit cost.
Supply Chain Analysis
Refillable pouch return flows through European closed-loop dispensing systems are creating reverse logistics infrastructure that concentrated cartridge suppliers exploit for customer lock-in. Manufacturing gravity centers on Germany, China, and India, with surfactant intermediates, quaternary ammonium biocides, and thixotropic gel polymers as critical input dependencies. Single-source vulnerability concentrates in Chinese benzalkonium chloride production hubs exposed to shipping cost volatility. Distribution runs through janitorial supply distributors serving commercial specification requirements alongside mass retail channels for residential volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Toilet care products function as a regulatory compounder where REACH Detergents Regulation biodegradability mandates and EPA FIFRA registration timelines continuously elevate compliance investment thresholds that filter marginal competitors from tender participation.
For Market Incumbents: Anchor market position through concurrent maintenance of EPA, REACH, and BIS registration portfolios that mid-size formulators cannot staff during renewal windows. Defend against enzymatic cleaning technology displacement by accelerating dual-claim formulation R&D that unifies disinfectant and general cleaner categories. Prioritize backward integration into surfactant manufacturing to capture margin pool compression from Chinese supply volatility. For New Entrants and Emerging Players: The price-point gap between premium gel formulations and economy liquid cleaners creates entry space for mid-tier concentrated cartridge systems targeting Brazilian hospital and airport concession contracts. Municipal sanitation upgrades in India's tier-2 cities offer the most penetrable geography where ANVISA-harmonized suppliers face reduced registration friction. Pursue smart dispensing convergence partnerships with facility management software platforms to embed IoT-enabled usage tracking into procurement workflows. For Investors and Strategic Acquirers: Roll-up economics work for mid-size European formulators with validated environmental fate data because REACH compliance gaps during renewal windows create distressed acquisition opportunities. Target specialists with concentrated chemistry capabilities and installed dispensing hardware relationships. Monitor EPA per- and polyfluoroalkyl substance hazard designations as inflection signal for substitute validation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Manufacturing | Captive benzalkonium chloride production insulates margin structures from Chinese supply volatility. |
| Smart Dispensing IoT Convergence | Usage tracking integration with facility management software creates subscription revenue streams. |
| Multi-Jurisdictional Registration Portfolio Expansion | Concurrent EPA, REACH, and BIS dossiers filter competitors from institutional tender renewals. |
| Enzymatic Dual-Claim Formulation Development | Protease-amylase blends unify cleaner-disinfectant categories, reducing SKU counts for healthcare accounts. |
| Bio-Based Acid Formulation Repositioning | EU Green Deal procurement mandates tilt public sector awards toward refillable packaging architectures. |
Study Parameters
Direct dialogue with formulation chemists, regulatory affairs officers at multi-jurisdictional suppliers, facility management procurement directors, and janitorial supply distributors grounded qualitative insights in operational reality. Secondary validation drew from EPA FIFRA registration databases, ECHA REACH dossier filings, Indian BIS certification records, customs trade data on surfactant imports, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up and top-down triangulation cross-checked volume assumptions against tender award data and retail channel audit information.
Top-down macroeconomic modeling anchored regional demand projections while bottom-up segmentation analysis across product type, application, packaging format, and distribution channel generated granular growth trajectories. Modeled dimensions included liquid versus gel formulation chemistry, residential versus institutional procurement patterns, refillable versus single-use packaging economics, and regional regulatory cluster alignment. CAGRs were derived from installed base penetration rates and replacement cycle dynamics rather than extrapolated trend lines, with thixotropic gel viscosity engineering adoption curves and municipal sanitation upgrade tender pipelines as industry-specific forecast inputs across the projection horizon.
Caveats apply where EPA per- and polyfluoroalkyl substance hazard designations, REACH microplastic restriction extensions, or Indian state-level sanitation directive modifications could materially shift the outlook for legacy formulation portfolios. Forecasts reflect assumptions about registration timeline continuity and concentrated chemistry hardware compatibility that regulatory enforcement variability may disrupt. Practitioners should monitor ECHA polymer registration threshold guidance and facility management vendor panel consolidation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Ironing Beads Market
Consumer Goods
Dog Crate Furniture Market
Consumer Goods
Landscaping Products Market
Consumer Goods
Pet Tag Market
Consumer Goods
North America Electric Fireplace Market
Consumer Goods
UK Lifestyle Sneakers Market
Consumer Goods
United States Electric Kettle Market
Consumer Goods
Asia-Pacific E Cigarettes Market
Consumer Goods
Middle East and Africa Leather Goods Market
Consumer Goods
Cosmetic Oil Market
Consumer Goods
India Consumer Speaker Market
Consumer Goods
North America Cigarette Market
Consumer Goods
Letter Opener Market
Consumer Goods
Face Makeup Market
Consumer Goods
Asia-Pacific Washing Machine Market
Consumer Goods
Stress Ball Market