
 Toddler Shoes Market | 2026-2036
Toddler Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Toddler Shoes Market Outlook
Recycled polyester is expanding its share in toddler shoe uppers, displacing conventional virgin synthetics in mid-tier production. Nike leverages its FlyEase closure technology to dominate adaptive toddler footwear, while Stride Rite sustains its pediatric podiatry heritage through biomechanical design specialization. Crocs anchors the molded-foam category with proprietary Croslite chemistry that controls unit economics at scale.
Toddler shoes are engineered footwear designed for children aged one to four years, typically featuring flexible outsoles below 4mm thickness, breathable linings, and anatomically shaped lasts that accommodate developing metatarsal structures. The primary commercial purpose centers on supporting early gait development while meeting parental safety and durability expectations. Sneakers occupy the largest volume position across product types due to year-round versatility and school-dress compatibility, while Velcro closure systems lead functional preferences by reducing caregiver dressing time. Leather materials command premium positioning through natural breathability claims, though synthetic alternatives capture cost-sensitive segments with improved water resistance.
The US Consumer Product Safety Commission enforces stringent small-parts and phthalate limits that dictate material selection and component design for toddler footwear sold domestically. The EU's REACH regulation and associated CE marking requirements restrict hazardous substances in children's products, creating compliance barriers for non-certified imports. China's GB standards for children's footwear, administered by SAMR, mandate formaldehyde limits and sole slip-resistance testing that shape manufacturing specifications for export-oriented suppliers. Stakeholders must monitor evolving chemical restriction schedules and regional certification reciprocity to optimize sourcing footprints and avoid market access disruptions.
Market Dynamics
Biomechanical engineering requirements are restructuring manufacturing priorities across toddler footwear, as parental demand for gait-development support collides with tightening chemical safety mandates from Brussels and Beijing.
Growth Catalysts
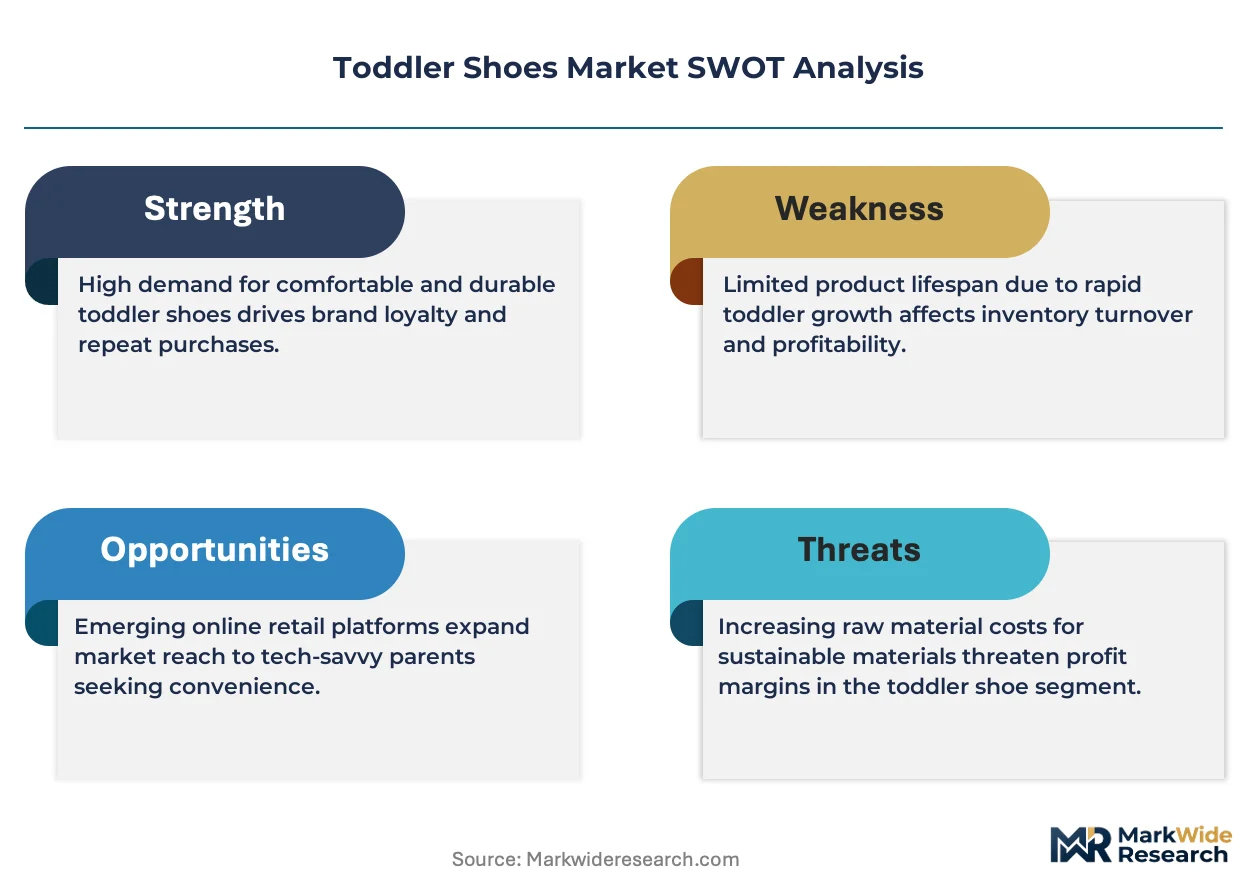
- REACH chemical restrictions:The EU's expanding hazardous substance lists are accelerating certified material sourcing, creating competitive separation for compliant suppliers in export markets.
- Recycled polyester uptake:Mid-tier manufacturers are displacing virgin synthetics in uppers, driven by cost parity and retailer sustainability procurement mandates.
- China's middle-income expansion:Household spending concentration in tier-one and tier-two cities is pulling premium children's apparel volumes upward.
Market Restraints
- Petrochemical feedstock volatility:EVA and TPU input costs for molded-foam soles fluctuate with crude oil indices, compressing margin predictability.
- Single-source adhesive dependency:Water-based polyurethane bonding agents concentrate production in Zhejiang and Guangdong provinces, exposing supply chains to regional disruption.
- Small-parts testing bottlenecks:US CPSC laboratory capacity constraints extend certification timelines for seasonal product launches.
Strategic Opportunities
- Adaptive closure technology:Magnetic and elastic fastening systems are opening positioning space between Velcro convenience and lace-up performance segments.
- Specialty retail channel expansion:Pediatric podiatry clinics and biomechanical assessment services are creating direct-to-caregiver distribution pathways outside mass retail.
- SAMR formaldehyde enforcement:Stricter GB standard administration is forcing supplier consolidation, creating acquisition targets for quality-certified manufacturers.
Industry Challenges
- Biomechanical engineering talent scarcity:Pediatric last design and gait-analysis expertise concentrates in legacy orthopedic footwear centers, limiting new entrant capability building.
- Multi-jurisdiction certification overlap:Simultaneous CPSC, REACH, and GB compliance testing creates redundant cost burdens without mutual recognition agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toddler Shoes Market |
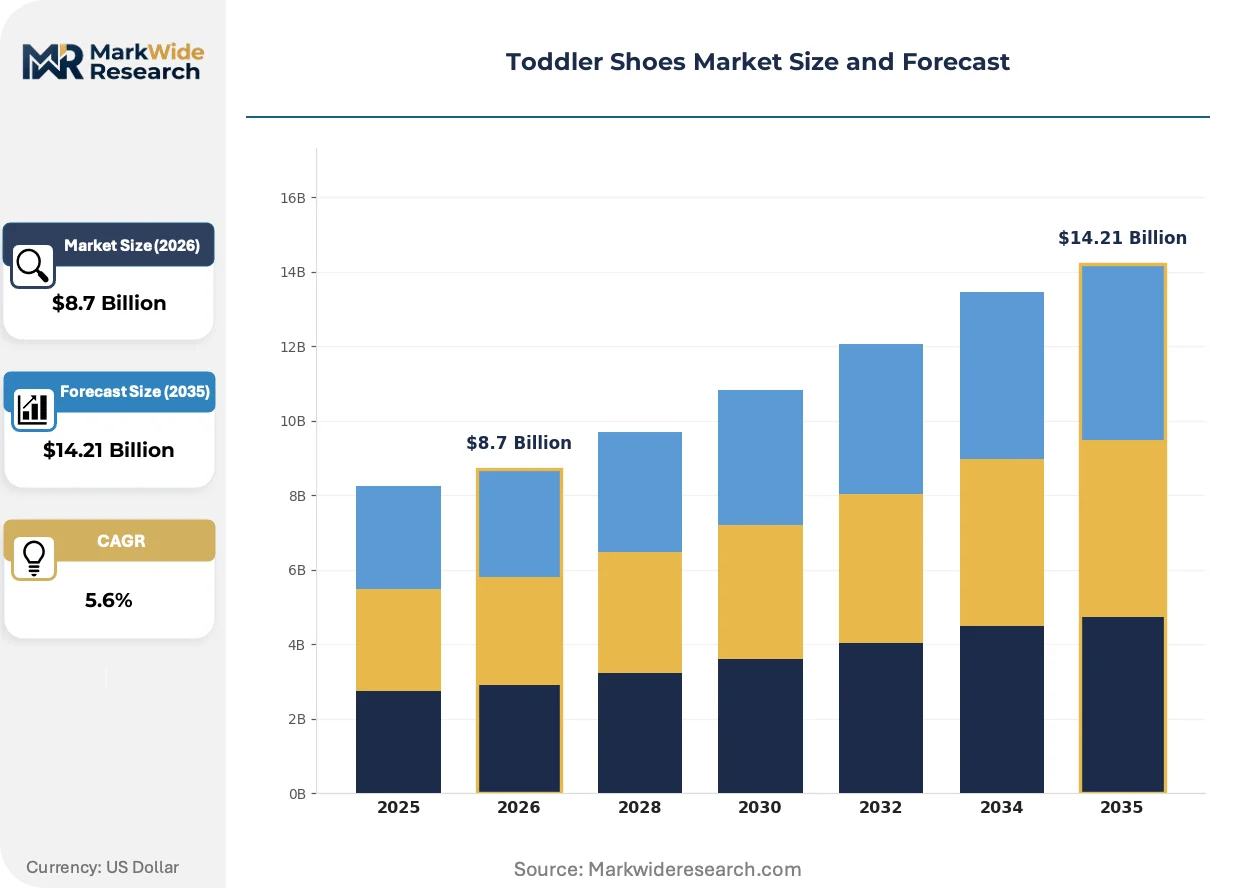
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casual Shoes, Sneakers, Sandals, Boots Material: Leather, Canvas, Synthetic, Rubber Closure Type: Velcro, Laces, Slip-On, Buckle Age Group: Infants, Toddlers, Pre-Schoolers, Beginners |
| Companies Covered | Nike, Adidas, Crocs, New Balance, SKECHERS USA, Puma SE, ASICS, Stride Rite, DR.KONG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toddler Shoes Market Strategic Shifts
Material science convergence with digital manufacturing is collapsing traditional development cycles, while regulatory fragmentation forces parallel compliance architectures.
3D-knitted uppers constructed from engineered textile structures are electrifying production economics by eliminating cutting waste and enabling single-piece construction. Specialty children's retailers in Germany and the Netherlands are piloting made-to-measure programs with two-week delivery windows. This compression is forcing conventional cut-and-sew suppliers to retool or retreat to commodity positioning.
ECHA's 2025 restriction proposal on microplastic release from synthetic textiles is tightening filtration requirements for manufacturing wastewater. Italian and Portuguese finishing houses are investing in closed-loop dyeing systems to maintain CE marking eligibility. The directive hits colored synthetic uppers hardest, accelerating natural fiber blends in premium positioning.
Caregiver purchasing through biomechanical assessment referrals is displacing impulse buying in big-box environments. Pediatric physical therapy networks in Australia and South Korea are embedding certified footwear recommendations into treatment protocols. This channel shift rewards technical documentation and clinical validation over marketing expenditure.
Toddler Shoes Market Segmentation
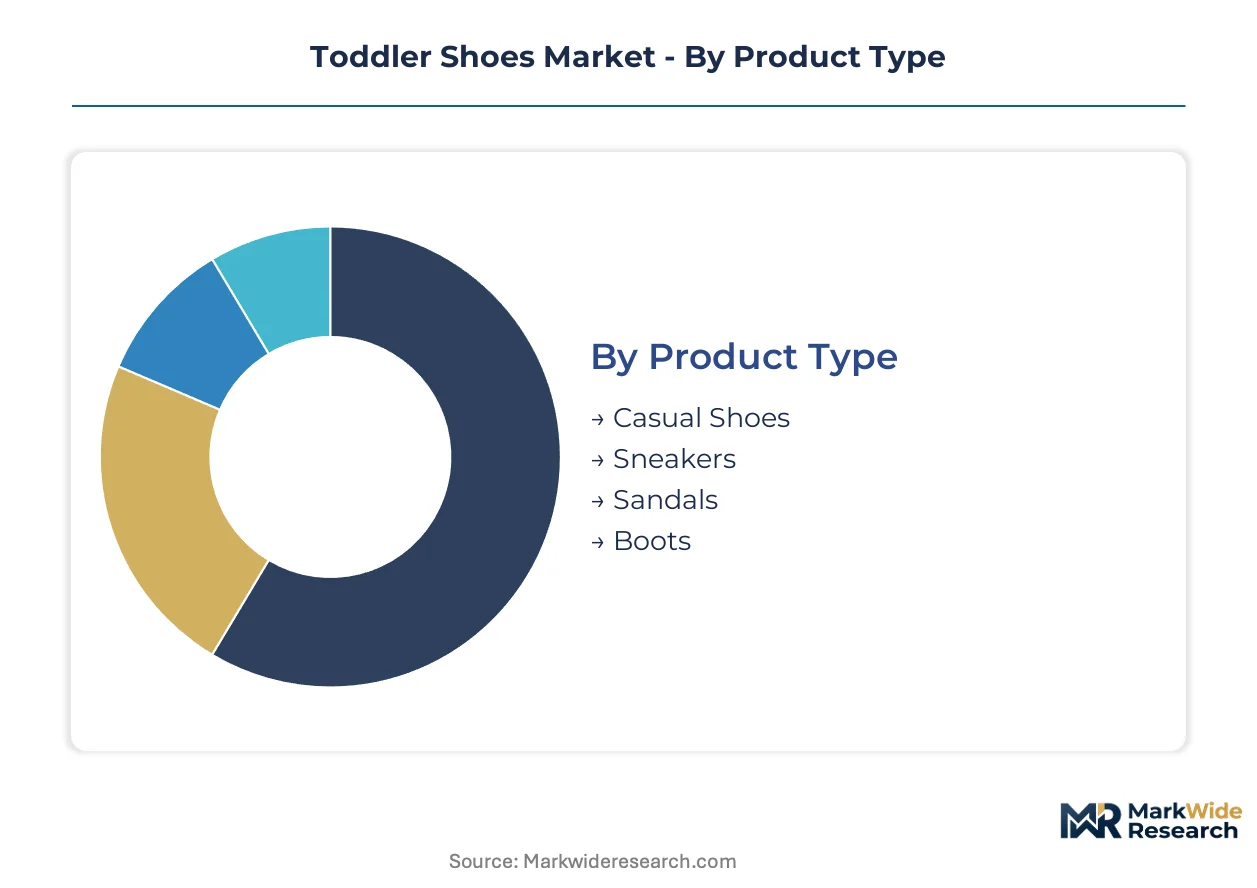
Toddler footwear segmentation tracks distinct biomechanical requirements across developmental stages, material safety thresholds, and caregiver convenience preferences. Each axis shapes manufacturing specifications, retail positioning, and regulatory compliance pathways differently.
Product Type:
Engineering specifications vary sharply by intended activity intensity and seasonal wear patterns.
- Sneakers:Flexible outsoles below 4mm thickness accommodate developing metatarsal structures while breathable mesh uppers manage thermoregulation during extended wear. Demand concentrates in China's tier-one cities where school-dress codes mandate closed-toe footwear year-round, pulling premium volumes from mid-tier synthetic suppliers.
- Casual Shoes:Anatomically shaped lasts with wider toe boxes support natural toe splay during early gait development. European specialty retailers prioritize REACH-certified leather constructions, creating competitive separation for Portuguese and Italian finishing houses with closed-loop dyeing capabilities.
- Sandals:Open-toe designs with protective bumpers address summer thermoregulation needs while meeting CPSC small-parts thresholds for strap hardware.
- Boots:Weather-resistant constructions with thermal linings target cold-climate caregivers, though thicker outsoles challenge flexibility requirements for pre-walkers.
Mature deployment sits with Sneakers. Newer deployment is concentrated in Boots as climate-adaptive features penetrate mid-tier production.
Material:
Cost-to-performance ratios and chemical compliance burdens restructure sourcing priorities across price tiers.
- Synthetic:Recycled polyester uppers displace virgin petroleum-based constructions in mid-tier manufacturing, achieving cost parity while satisfying retailer sustainability procurement mandates. Zhejiang and Guangdong province suppliers dominate water-based polyurethane bonding capacity, exposing brands to single-source adhesive concentration risk.
- Leather:Natural breathability claims command premium positioning through tanneries with SAMR formaldehyde compliance and ECHA REACH certification. Italian and Portuguese finishing houses invest in closed-loop systems to maintain CE marking eligibility as microplastic restrictions tighten.
- Canvas:Cotton-based constructions with reinforced toe caps serve economy positioning, though moisture retention limits extended wear applications.
- Rubber:Molded-foam chemistry controls unit economics at scale for waterproof categories, with EVA and TPU input costs fluctuating with crude oil indices.
Volume leadership belongs to Synthetic materials. Steepest expansion trajectory is occurring in Leather as certified supply consolidates.
Closure Type:
Caregiver time constraints and child motor-skill development stages dictate functional design priorities.
- Velcro:Hook-and-loop fastening systems reduce dressing time for caregivers managing multiple children, dominating mass retail distribution. Pediatric physical therapy networks in Australia embed Velcro-equipped footwear into treatment protocols for adaptive mobility support.
- Slip-On:Elasticized collars and heel pulls enable independent dressing as toddlers develop fine motor control, gaining share in pre-school transition segments.
- Laces:Traditional closure systems persist in performance-oriented constructions where fit precision matters, though caregiver preference limits volume penetration below age three.
- Buckle:Adjustable strap hardware with safety-release mechanisms addresses sandal categories, requiring CPSC small-parts testing that extends certification timelines.
Mass-market dominance rests with Velcro. Technical differentiation is emerging in Buckle systems for adaptive footwear applications.
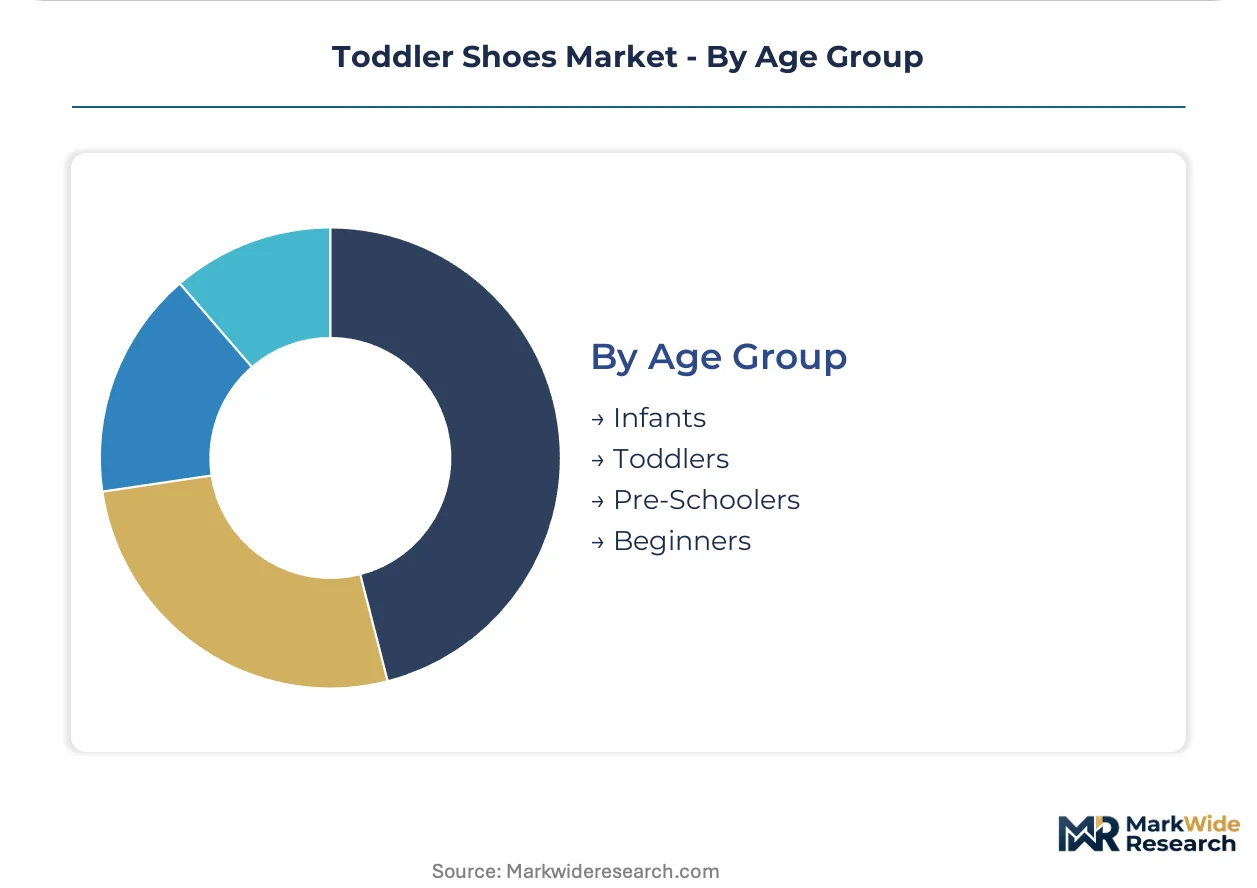
Age Group:
Biomechanical engineering requirements intensify as gait patterns mature and activity duration extends.
- Toddlers:Footwear for children aged one to four years requires flexible outsole construction below 4mm thickness and anatomically shaped lasts accommodating developing metatarsal structures. China's middle-income household expansion in tier-one and tier-two cities pulls premium volumes toward biomechanically validated constructions.
- Infants:Pre-walking soft soles prioritize proprioceptive feedback over structural support, with minimal retail markup limiting manufacturer investment.
- Pre-Schoolers:Extended wear durations and playground activity intensity demand reinforced toe protection and moisture-wicking linings.
- Beginners:First independent walkers require hybrid flexibility-stability engineering that bridges infant soft soles and toddler structured support.
Revenue concentration aligns with Toddlers. Fastest volume expansion is occurring in Pre-Schoolers as school-entry ages extend footwear replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's middle-income household expansion in tier-one and tier-two cities pulls premium toddler footwear volumes upward, while regulatory tightening across Brussels and Washington reshapes material sourcing priorities for export-oriented suppliers.
United States
Pediatric physical therapy networks embed certified footwear recommendations into treatment protocols, shifting caregiver purchasing away from impulse buying. The US Consumer Product Safety Commission enforces stringent small-parts and phthalate limits that dictate material selection. Massachusetts and California concentrate specialty retail channels serving biomechanical assessment referrals.
China
School-dress codes mandate closed-toe footwear year-round in urban centers, pulling premium volumes from mid-tier synthetic suppliers. SAMR administers GB standards with formaldehyde limits and sole slip-resistance testing. Zhejiang and Guangdong provinces dominate water-based polyurethane bonding capacity for molded-foam production.
Germany
Specialty children's retailers pilot made-to-measure programs with compressed delivery windows, forcing conventional suppliers to retool. ECHA's REACH regulation restricts hazardous substances and tightens filtration requirements for manufacturing wastewater. Bavaria and Baden-Württemberg host finishing houses investing in closed-loop dyeing systems.
Italy
Premium positioning through natural breathability claims concentrates demand for certified leather constructions. ECHA's 2025 microplastic restriction proposal accelerates natural fiber blends in colored synthetic uppers. Tuscany and Veneto tanneries maintain CE marking eligibility through closed-loop system investments.
Australia
Biomechanical assessment referrals displace traditional retail purchasing as pediatric networks embed footwear guidance into protocols. The Therapeutic Goods Administration framework shapes clinical validation requirements for adaptive products. Melbourne and Sydney concentrate specialty distribution channels serving caregiver education segments.
Toddler Shoes Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbents extend closure technology and material science capabilities across price tiers. The vendor base separates into three distinct strata: multinational sportswear houses with adaptive R&D platforms, heritage pediatric specialists with clinical validation networks, and molded-foam commoditizers controlling unit economics at scale. M&A activity targets certified material suppliers and biomechanical engineering talent, while geographic expansion into China's tier-two cities accelerates through joint venture structures.
Among sportswear-based diversified manufacturers, Nike and Adidas exemplify technology-licensing archetypes that leverage adaptive closure platforms across age segments. Heritage specialists occupy positions anchored by clinical validation, with Stride Rite representing pediatric podiatry heritage through biomechanical design concentration. At the molded-foam commoditization end, Crocs sits within the chemistry-control archetype that manages proprietary material economics.
| Leading Market Players |
|---|
| Nike |
| Adidas |
| Crocs |
| New Balance |
| SKECHERS USA |
| Puma SE |
| ASICS |
| Stride Rite |
| DR.KONG |
| Others |
Value Chain & Pricing Dynamics
Mass retail buyers concentrating in China's tier-one cities and US big-box channels command volume-based procurement terms that compress margins for mid-tier synthetic suppliers while rewarding certified leather manufacturers with premium positioning power.
Pricing Analysis
Volume leadership in synthetic constructions runs on thin margins, while leather and adaptive technology tiers capture value through certification premiums. Price differentiation hinges on REACH compliance status and pediatric podiatry validation, with certified suppliers commanding separation from commodity players. Pricing pressure stems from petrochemical feedstock volatility affecting EVA and TPU input costs for molded-foam soles. Economy synthetic segments show highest price sensitivity, while biomechanical assessment-referred purchases in specialty channels demonstrate inelastic demand.
Supply Chain Analysis
Direct-to-specialty-retail channels serve caregiver education segments in Germany and Australia, while mass retail distribution runs through consolidated buying offices in China and the United States. Manufacturing concentrates in China, Vietnam, and Indonesia for cut-and-sew assembly, with Italian and Portuguese tanneries anchoring premium leather finishing. Raw material flows draw from petroleum-based EVA and TPU suppliers, recycled polyester fiber producers, and water-based polyurethane adhesive manufacturers in Zhejiang and Guangdong provinces. Single-source adhesive dependency creates regional disruption exposure. Finished goods move through pediatric podiatry clinic networks, specialty children's retailers, and mass-market big-box channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The toddler footwear market functions as a cost-of-compliance arena where ECHA's REACH chemical restrictions and SAMR's formaldehyde enforcement create regulatory moats that favor incumbents with certified material sourcing and multi-jurisdiction testing capabilities.
For Market Incumbents:Cement defensible positioning through backward integration into water-based polyurethane adhesive production in Zhejiang province, eliminating single-source concentration risk. Deepen clinical validation networks with pediatric physical therapy chains in Australia and South Korea to lock in referral-driven channel control. Counter recycled polyester commoditization by investing in closed-loop dyeing systems that preserve CE marking eligibility under tightening microplastic restrictions.
For New Entrants and Emerging Players:Begin with adaptive closure technology white space between Velcro convenience and lace-up performance segments, targeting magnetic and elastic fastening systems for caregivers of children with mobility challenges. Penetrate China's tier-two cities through joint venture structures that navigate SAMR GB standard compliance without building captive testing infrastructure. Anchor go-to-market strategy through biomechanical assessment partnerships rather than mass retail slotting fee competition.
For Investors and Strategic Acquirers:The window for entry favors quality-certified manufacturers facing forced consolidation from SAMR formaldehyde enforcement tightening. Long-term viability rests on acquiring targets with existing REACH, CPSC, and GB certification portfolios that eliminate redundant multi-jurisdiction testing costs. Watch ECHA's 2025 microplastic restriction implementation as inflection signal for natural fiber blend acceleration and colored synthetic upper displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Production | Captive water-based polyurethane supply eliminates Zhejiang-Guangdong concentration risk for molded-foam sole bonding. |
| Pediatric Podiatry Clinic Partnership | Biomechanical assessment referral networks in Australia embed certified footwear into treatment protocols. |
| Closed-Loop Dyeing System Investment | Italian and Portuguese finishing houses maintain CE marking eligibility under ECHA wastewater filtration tightening. |
| Adaptive Closure Technology Development | Magnetic and elastic fastening systems open positioning between Velcro convenience and lace-up performance tiers. |
| Recycled Polyester Uppers Transition | Mid-tier manufacturers displace virgin synthetics to satisfy retailer sustainability procurement mandates. |
Study Parameters
Independent corroboration across brand managers at multinational sportswear houses, category buyers at specialty children's retailers, procurement leads at Zhejiang and Guangdong manufacturing clusters, and regulatory affairs specialists at EU and US compliance consultancies underwrites the qualitative findings. Primary interviews with pediatric podiatrists, physical therapy network administrators, and tannery technical directors combined with secondary validation from ECHA restriction proposals, SAMR GB standard publications, US CPSC small-parts testing guidelines, and customs trade data for footwear imports. Bottom-up volume modeling and top-down value triangulation anchored segment-level outputs.
Comparable historical periods spanning pre-pandemic baseline, supply chain disruption peak, and normalization phases anchored the forecast window across the analysis window. The analytical framework modeled segmentation dimensions including product type, material composition, closure mechanism, age group, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating parental income expansion in China's tier-one and tier-two cities, school-dress code enforcement intensity, and seasonal replacement cycle compression. Industry-specific inputs included petrochemical feedstock price indices and laboratory certification capacity constraints.
Underlying measurement precision varies by segment; sneakers and synthetic materials carry tighter precision than sandals and canvas constructions due to trade data granularity. Forecasts reflect assumptions around REACH chemical restriction implementation schedules and SAMR enforcement intensity that could revise trajectories if regulatory timelines accelerate or reciprocity agreements emerge. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO