
 Test Paper Market | 2026-2036
Test Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Test Paper Market Analytics
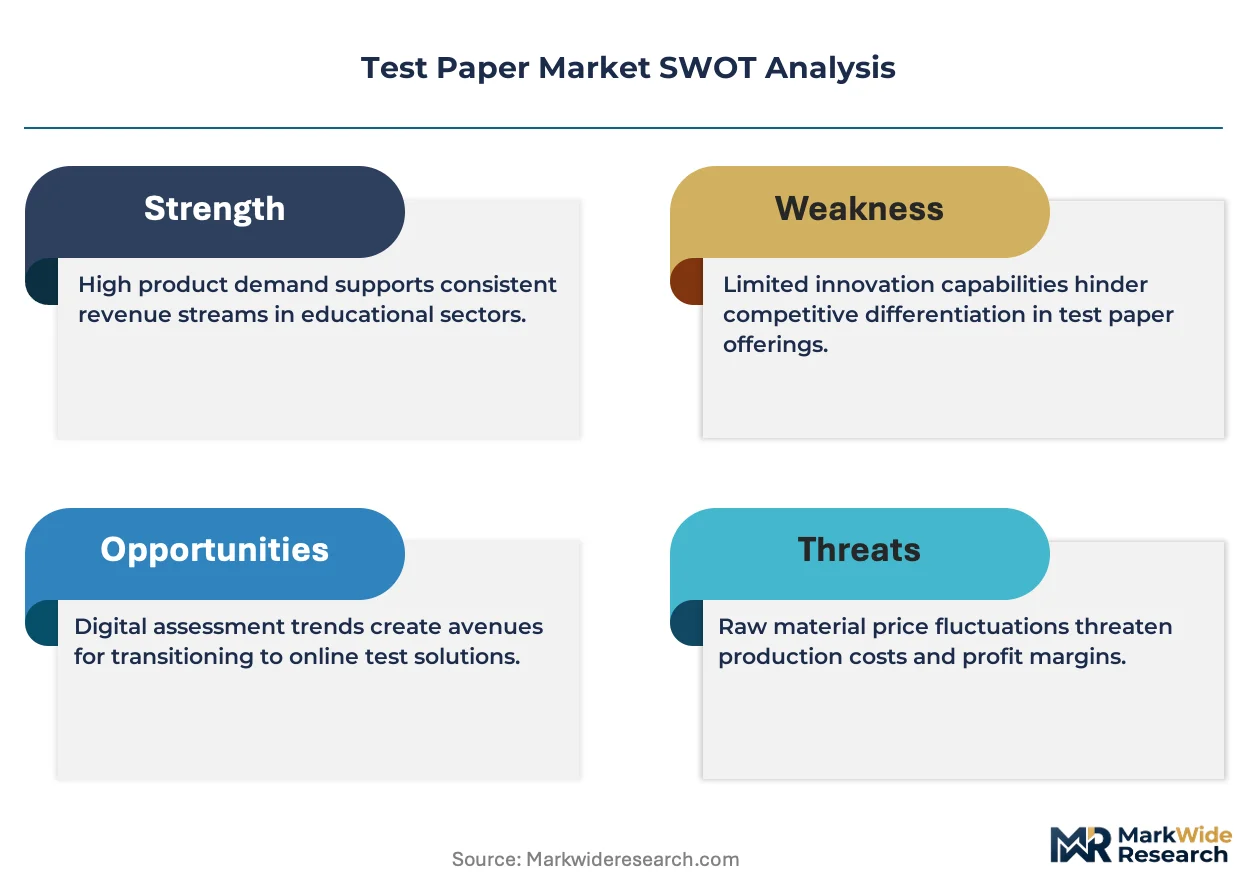
Multi-source procurement is restructuring how educational publishers and certification bodies secure test paper supply chains. AMETEK leverages its instrumentation heritage to supply precision-calibrated testing substrates for high-stakes examination environments. Thwing-Albert Instrument Company sustains competitive position through specialized tensile and tear-testing equipment that validates paper durability for standardized formats. Techlab Systems anchors its presence in European markets with quality-control systems tailored to ISO-compliant test paper production.
Test papers are specialized cellulose or synthetic substrates impregnated with chemical indicators, optical recognition markers, or conductive coatings, manufactured through controlled wet-laid or cast-coating processes to achieve uniform porosity and surface reactivity for accurate signal detection or machine-readable response capture. Diagnostic tests represent the fastest-expanding product type as healthcare systems shift toward decentralized screening protocols that demand shelf-stable, colorimetric indicator papers. Printed papers retain dominant share among format categories due to entrenched infrastructure for optical mark recognition in large-scale examination administration, though scannable sheets are gaining traction where institutions seek faster digitization of handwritten responses.
ISO 9001 quality management standards and the EU Green Deal's sustainable product requirements shape material sourcing and coating chemistry decisions across European test paper manufacturing. The US EPA regulates chemical indicator disposal pathways for diagnostic test papers used in clinical settings, while India's BIS certification mandates dimensional stability thresholds for examination papers deployed in national eligibility tests. Stakeholders must monitor how regulatory tightening on per- and polyfluoroalkyl substances affects coating formulations and whether digital assessment mandates in major education systems alter physical test paper procurement trajectories.
Market Dynamics
Diagnostic test paper procurement is accelerating as healthcare systems decentralize screening protocols, while educational examination boards in Germany and India consolidate supplier relationships to secure standardized formats for high-stakes testing environments.
Growth Catalysts
- EU F-Gas Regulation:Chemical indicator coating reformulation toward lower-emission substrates is creating compliant product lines that qualify for public procurement tenders across European healthcare systems.
- Point-of-care diagnostic expansion:Decentralized screening protocols in clinical settings are driving shelf-stable colorimetric indicator paper volumes for rapid-result testing outside centralized laboratories.
- Germany's vocational certification concentration:Centralized examination boards in Baden-Württemberg and Bavaria generate bulk orders for standardized optical-mark-recognition formats with precise dimensional tolerances.
Market Restraints
- Cellulose pulp cost volatility:Specialty-grade pulp inputs for controlled-porosity substrates face price instability from Nordic supply concentration and energy-intensive refining processes.
- Coating chemistry regulatory friction:Per- and polyfluoroalkyl substance restrictions under REACH and emerging state-level US prohibitions are forcing costly reformulation cycles before patent-protected alternatives mature.
- Digital assessment substitution:Computer-based testing mandates in tertiary education segments are compressing physical test paper procurement trajectories in markets with robust broadband infrastructure.
Strategic Opportunities
- India's national eligibility test expansion:BIS-certified examination paper procurement for NEET and JEE examinations offers volume growth as test-taker populations expand and security-feature requirements tighten.
- Biodegradable synthetic substrate development:Convergence of wet-laid cellulose processing with polylactic acid coating technologies opens compostable alternatives for single-use diagnostic applications.
- Direct-to-institution distribution channels:Bypassing traditional educational supply distributors through ISO 9001-certified manufacturer portals reduces procurement cycle times for large certification bodies.
Industry Challenges
- Colorimetric indicator stability certification:Shelf-life validation protocols for diagnostic test papers require extended accelerated-aging studies that compress product launch timelines against competitor regulatory submissions.
- Optical recognition marker integration:Legacy scanning infrastructure in examination administration systems demands backward-compatible reflective coating formulations that constrain next-generation security feature adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Test Paper Market |
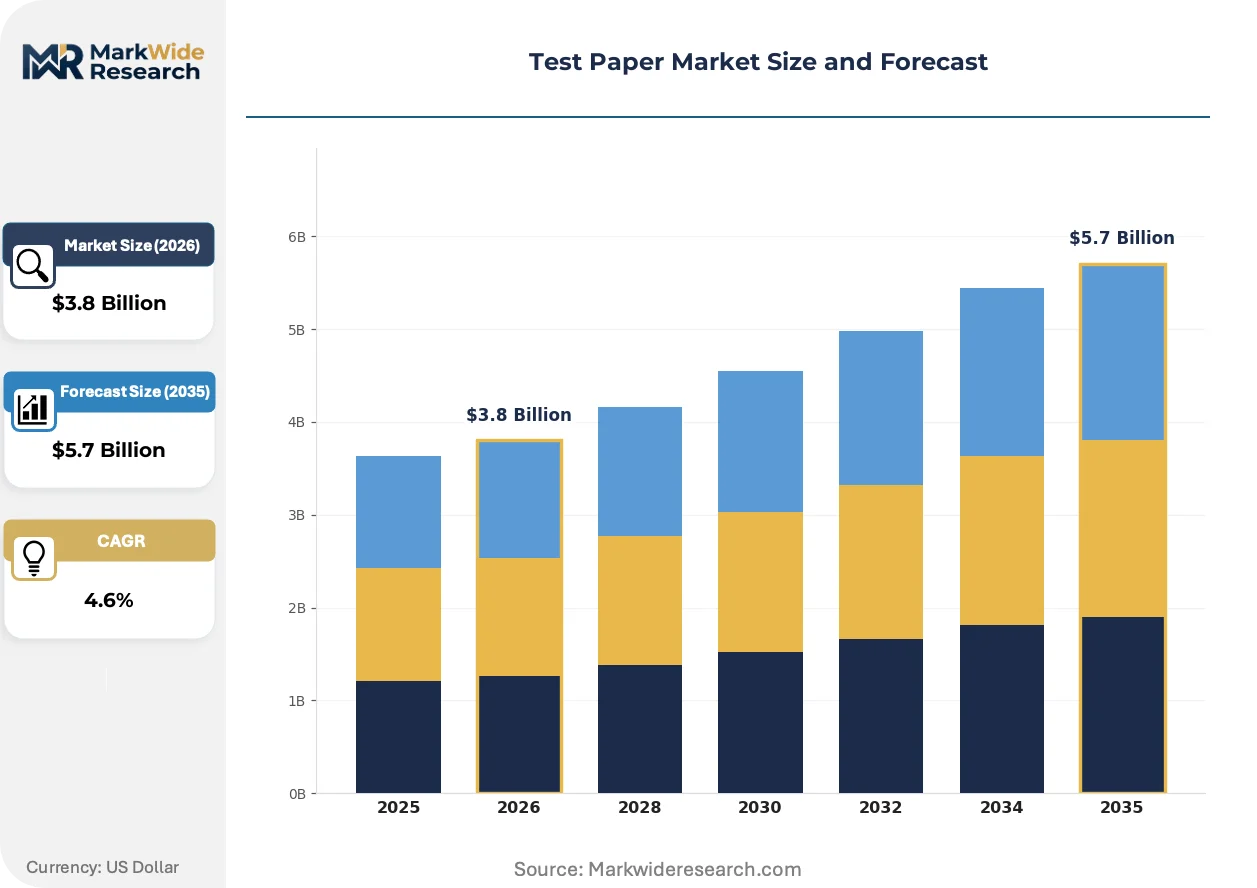
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standardized Tests, Diagnostic Tests, Practice Tests, Certification Tests End User: Schools, Universities, Training Centers, Corporates Distribution Channel: Online Stores, Retail Outlets, Direct Sales, Educational Institutions Format: Printed Papers, Digital Papers, Scannable Sheets, Interactive Tests |
| Companies Covered | Testing Machines, AMETEK, Thwing-Albert Instrument Company, Techlab Systems, ABB Ltd, Gurley Precision Instruments, AML Instruments, Gester Instruments, IDM Instruments Pty Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Test Paper Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are reshaping how test paper manufacturers balance signal accuracy, environmental compliance, and machine-readability in next-generation substrates.
Cast-coating processes with nano-scale porosity control are expanding into high-stakes examination formats where uniform ink absorption prevents optical mark recognition errors. German certification bodies and Indian national testing agencies are adopting these substrates for million-unit examination deployments. The technology is expanding into security-feature integration by enabling micro-encapsulated indicator zones that resist tampering without compromising scanning compatibility.
EU F-Gas Regulation phase-down schedules are forcing coating chemistry transitions away from fluorinated surfactants traditionally used for moisture-barrier properties in diagnostic test papers. Manufacturers must reformulate toward silicone-based or bio-derived alternatives while maintaining colorimetric sensitivity thresholds. Clinical point-of-care segments in France and the Netherlands are experiencing procurement delays as suppliers validate replacement coatings against ISO 15197 glucose monitoring standards.
Consolidated tendering by multi-state examination boards is compressing supplier qualification cycles and favoring manufacturers with integrated quality-control systems. India's National Testing Agency and Germany's Kultusministerkonferenz now require single-source accountability for dimensional stability, optical density, and lot-traceability documentation. This concentration is most visible in Bavaria and Karnataka, where state-level procurement offices have eliminated secondary distributors from high-volume standardized test contracts.
Test Paper Market Segmentation
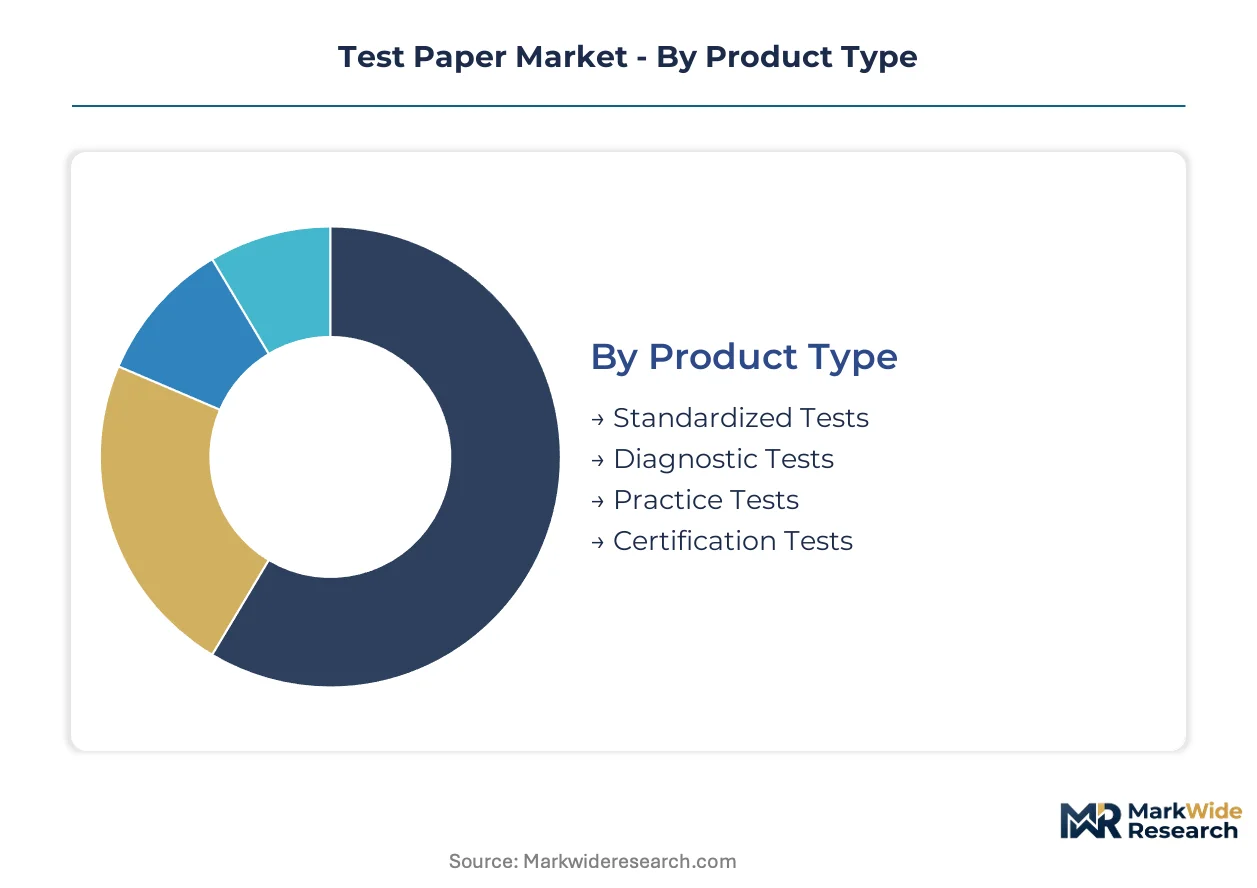
Test paper procurement splits across four dimensions that determine manufacturing specifications, coating chemistry, and distribution economics. Each category carries distinct technical requirements and regulatory exposure that reshape supplier positioning.
Product Type:
Supply concentration clusters around formats with the tightest dimensional tolerances and longest qualification cycles.
- Standardized Tests:Optical-mark-recognition substrates with calibrated porosity for uniform ink absorption. Germany's Kultusministerkonferenz and India's National Testing Agency drive bulk procurement of security-featured formats with lot-traceability documentation.
- Diagnostic Tests:Colorimetric indicator papers manufactured through controlled wet-laid processes for shelf-stable clinical screening. Point-of-care expansion in France and the Netherlands accelerates volumes despite EU F-Gas Regulation coating reformulation delays.
- Practice Tests:Lower-specification substrates for preparatory examination materials.
- Certification Tests:Vocational credentialing formats with ISO 9001-certified production requirements.
Standardized tests absorb the bulk of installed capacity; diagnostic tests are expanding most quickly.
End User:
Customer procurement scale determines whether supply flows through distributor networks or direct manufacturer relationships.
- Schools:Regional education authorities in Karnataka and Bavaria consolidate tenders for million-unit examination deployments with single-source accountability requirements.
- Universities:Tertiary institutions with computer-based testing mandates compress physical paper procurement in broadband-served markets.
- Training Centers:Vocational facilities requiring BIS-certified or ISO-compliant formats for credentialing examinations.
- Corporates:Internal certification programs with shorter runs and faster turnaround requirements.
Universities show the steepest procurement compression; schools retain the largest absolute volumes.
Distribution Channel:
Channel selection reflects procurement cycle urgency and quality-control documentation needs.
- Online Stores:Digital procurement portals reducing cycle times for standardized test replenishment.
- Retail Outlets:Regional distributors serving fragmented school and training center demand.
- Direct Sales:Manufacturer portals bypassing intermediaries for large certification bodies with ISO 9001 audit requirements.
- Educational Institutions:Consolidated tendering offices in Baden-Württemberg and Karnataka eliminating secondary distributors from high-volume contracts.
Direct sales channels are gaining share fastest; retail outlets still handle the greatest transaction count.
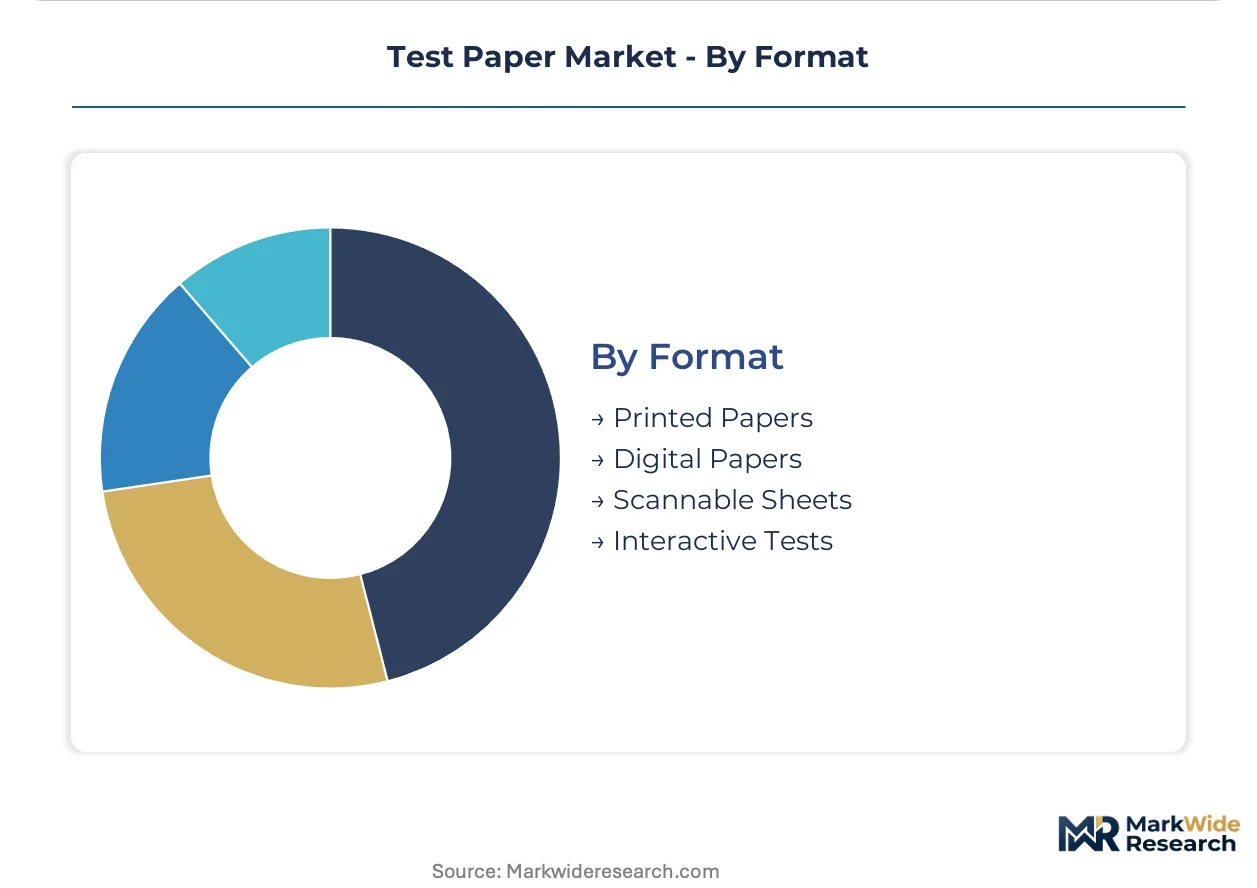
Format:
Format choice constrains coating chemistry and security feature integration possibilities.
- Printed Papers:Dominant share among legacy optical mark recognition infrastructure in large-scale examination administration.
- Digital Papers:Screen-readable formats for hybrid assessment environments.
- Scannable Sheets:Reflective coating formulations compatible with legacy scanning infrastructure while enabling faster digitization of handwritten responses.
- Interactive Tests:Emerging formats with micro-encapsulated indicator zones for tamper resistance without scanning compatibility loss.
Printed papers retain the largest installed base; scannable sheets are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nordic specialty cellulose pulp suppliers anchor substrate quality for controlled-porosity test papers, while manufacturing concentration clusters in Germany, India, France, and the United States where examination and diagnostic procurement volumes sustain dedicated production lines.
Germany
Baden-Württemberg and Bavaria host centralized examination boards generating million-unit standardized test orders with precise optical-mark-recognition tolerances. The Kultusministerkonferenz consolidates tenders requiring single-source accountability for dimensional stability and lot-traceability documentation. Stuttgart and Munich industrial zones concentrate wet-laid processing capacity serving vocational certification bodies across federal states.
India
Karnataka and Maharashtra drive BIS-certified examination paper procurement for NEET and JEE national eligibility tests with expanding test-taker populations. The National Testing Agency mandates security-feature integration and dimensional stability thresholds under central government examination reform programs. Bengaluru and Mumbai supply corridors concentrate ISO-compliant manufacturing for state-level education authorities eliminating secondary distributors.
France
Clinical point-of-care diagnostic procurement accelerates in Île-de-France and Provence-Alpes-Côte d'Azur despite EU F-Gas Regulation coating reformulation delays. ANSM oversight shapes shelf-stable colorimetric indicator paper validation protocols for decentralized screening outside centralized laboratories. Paris and Lyon metropolitan clusters anchor quality-control system integration for ISO 15197 glucose monitoring standard compliance.
United States
EPA chemical indicator disposal pathways regulate diagnostic test paper end-of-life management in clinical settings across California and Texas healthcare systems. Tertiary education computer-based testing mandates compress physical procurement in broadband-served coastal markets while standardized K-12 assessment sustains volume in interior states. Boston and Austin examination technology corridors concentrate optical recognition infrastructure serving multi-state certification bodies.
Netherlands
Diagnostic test paper procurement experiences validation delays as manufacturers substitute silicone-based coatings for fluorinated surfactants under EU F-Gas Regulation phase-down schedules. Healthcare procurement offices in Randstad cities prioritize ISO 15197-compliant substrates for point-of-care glucose monitoring applications. Eindhoven quality-control technology providers support regional coating chemistry transition programs.
Test Paper Market Competitive Landscape
Global majors compete with regional champions across instrumentation heritage and precision-calibration capabilities. Market structure tilts toward consolidated supply relationships where multi-year qualification cycles favor incumbents with integrated quality-control systems and ISO 9001-certified production documentation. Three archetypes dominate: instrumentation conglomerates leveraging measurement precision into substrate supply, specialized testing equipment fabricators validating paper durability, and regional quality-control system providers serving geography-specific regulatory compliance. Competitive moves concentrate on direct-to-institution distribution channel development and coating chemistry reformulation partnerships responding to per- and polyfluoroalkyl substance restrictions.
Among instrumentation heritage conglomerates, AMETEK occupies a position exemplifying precision-calibrated substrate supply for high-stakes examination environments. Specialized equipment fabricators include Thwing-Albert Instrument Company representing tensile and tear-testing validation capabilities, and Techlab Systems anchoring European market presence through ISO-compliant production quality-control systems. These three entities collectively illustrate how competitive positioning depends on regulatory documentation depth and direct institutional relationship scale rather than manufacturing capacity alone.
| Leading Market Players |
|---|
| Testing Machines |
| AMETEK |
| Thwing-Albert Instrument Company |
| Techlab Systems |
| ABB Ltd |
| Gurley Precision Instruments |
| AML Instruments |
| Gester Instruments |
| IDM Instruments Pty Ltd |
| Others |
Value Network & Pricing Analysis
ISO 9001 certification-grade divergence separates premium test paper supply from commodity-grade alternatives, with this bifurcation manifesting in bundled quality-assurance service packages for high-stakes examination formats while diagnostic applications face unbundled coating chemistry costs under EU F-Gas Regulation compliance timelines.
Pricing Analysis
Extended lot-traceability documentation and accelerated-aging validation services are bundled into per-unit pricing for German Kultusministerkonferenz and Indian National Testing Agency contracts, while diagnostic test paper procurement in France and the Netherlands sees coating reformulation costs passed through as separate line items. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with BIS-certified formats commanding premium positioning against practice-test commodities. Pricing pressure stems from cellulose pulp cost volatility in Nordic supply corridors, compressing margins for mid-tier suppliers. Schools and vocational training centers exhibit highest price sensitivity, whereas centralized examination boards prioritize dimensional stability guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing qualification mandates from India's National Testing Agency and Germany's state procurement offices require manufacturers to maintain validated secondary coating chemistry suppliers for F-Gas Regulation compliance. Supply concentration clusters in Germany, India, and France, with wet-laid processing capacity anchored in Stuttgart, Bengaluru, and Lyon industrial zones. Specialty-grade cellulose pulp inputs draw from Nordic refining operations, while silicone-based coating alternatives rest on Dutch and German chemical supplier networks. Single-source vulnerability in fluorinated surfactant substitution creates procurement delays for point-of-care diagnostic segments. Distribution runs through direct-to-institution portals for consolidated tenders, with regional distributors serving fragmented training center demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Test paper manufacturing is becoming a vertical-integration race as players pursue captive control over coating chemistry formulation to secure F-Gas Regulation compliance timelines and bypass raw material volatility.
For Market Incumbents: Hedge against REACH and emerging US state-level per- and polyfluoroalkyl substance restrictions by securing backward integration into silicone-based coating precursor supply. Lock in multi-year cellulose pulp offtake agreements with Nordic suppliers to defend margin position against energy-intensive refining cost spikes. Prioritize ISO 15197 validation capacity expansion for diagnostic test paper segments facing procurement delays. For New Entrants and Emerging Players: Nano-scale porosity control technology offers entry into high-stakes examination formats where German and Indian procurement offices are consolidating supplier relationships. Target biodegradable synthetic substrate development for single-use diagnostic applications, where polylactic acid coating convergence creates white-space opportunity. Pursue direct-to-institution distribution channel partnerships with state-level education authorities eliminating secondary distributors. For Investors and Strategic Acquirers: Re-rating potential sits with ISO 9001-certified manufacturers with integrated quality-control systems given consolidation of multi-state examination board tenders toward single-source accountability. Long-term viability hinges on coating chemistry reformulation capabilities aligned with EU Green Deal sustainable product requirements. Monitor ANSM and EPA regulatory submission timelines as inflection indicators for diagnostic test paper supplier valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Chemistry | Captive silicone-based formulation supply secures F-Gas Regulation compliance for EU healthcare procurement. |
| ISO 15197 Validation Capacity Expansion | Accelerated-aging certification infrastructure addresses point-of-care diagnostic procurement delays in France and Netherlands. |
| Direct-to-Institution Distribution Portal | Manufacturer portals bypass intermediaries for Karnataka and Bavaria consolidated tender requirements. |
| Biodegradable Synthetic Substrate Development | Polylactic acid coating convergence opens compostable alternatives for single-use clinical screening applications. |
| Multi-Year Pulp Offtake Agreements | Nordic specialty cellulose supply locks anchor controlled-porosity substrate quality for standardized test formats. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with test paper manufacturing plant managers, procurement leads at German Kultusministerkonferenz and Indian National Testing Agency, coating chemistry R&D directors, and educational supply distributors. Bottom-up segmentation modeling triangulated against top-down examination administration volume data from state-level education authorities and point-of-care diagnostic deployment statistics from ANSM and EPA oversight jurisdictions.
Data-stream reconciliation across product type, end user, distribution channel, and format dimensions generated volume and value outputs across the analysis window. Segmentation incorporated standardized test, diagnostic test, practice test, and certification test categories alongside printed paper, digital paper, scannable sheet, and interactive test format tiers. CAGRs derived from regression analysis of procurement volume trajectories, with coating chemistry reformulation cycle timelines and digital assessment substitution rates as key forecast inputs.
Several conditions sit outside the modeled scope, including patent-protected alternative coating maturation timelines and broadband infrastructure expansion rates affecting computer-based testing penetration. Forecasts reflect documented assumptions regarding EU F-Gas Regulation phase-down adherence and BIS certification enforcement consistency. Deviation in REACH per- and polyfluoroalkyl substance restriction scope or India's national eligibility test expansion pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Middle East and Africa Management Consulting Services Market
Education & Training
Test Preparation Market
Education & Training
Global Smart Classroom Market
Education & Training
Smart Education System Market
Education & Training
HSE Consulting Training Services Market
Education & Training
GCC E-Learning Market
Education & Training
Corporate eLearning Market
Education & Training
Flipped Classroom Market
Education & Training
GCC Massive Open Online Course (MOOC) Market
Education & Training
Europe Executive Search (Headhunting) Market
Education & Training
Kindergarten Books Market
Education & Training
Research Publication Support Service Market
Education & Training
Europe MOOC Market
Education & Training
Smart Education and Learning Market
Education & Training
Corporate Learning Management System Market
Education & Training
Competency-Based Education Spending Market