
 Temporary Power Market | 2026-2036
Temporary Power Market Size, Share, and Industry Trends Forecast 2026-2036
Temporary Power Market Intelligence
Market Context
Remote monitoring and predictive maintenance subscriptions is realigning how temporary power providers monetize uptime rather than equipment alone. Aggreko leverages its digital fleet management platform to anchor long-term utility partnerships across Africa and Latin America. Cummins Inc. sustains technology leadership in natural gas generator sets through in-house engine development. Caterpillar Inc. dominates heavy-duty diesel rental fleets for mining and construction applications.
Technical Definition and Segments
Temporary power encompasses modular electricity generation and distribution equipment deployed for finite durations, typically rated from 10 kW to 100 MW, designed for rapid installation and decommissioning without permanent infrastructure commitment. Diesel generator sets retain the largest installed base due to fuel availability and load-following capability, though natural gas and hybrid systems are capturing share in emissions-regulated jurisdictions. Generator sets command the deepest margin pools because OEMs bundle fuel management software and load-optimization controls. Mobile units and hybrid systems represent the fastest-expanding deployment modes as event management and telecommunications providers prioritize rapid relocation and noise reduction.
Regulatory Outlook
EPA Tier 4 Final and CARB standards in the United States, combined with EU Stage V non-road engine regulations, are phasing out legacy diesel fleets and redirecting capital toward natural gas and hydrogen-ready assets. India's CEA grid connectivity codes and state-level industrial backup mandates compel manufacturing zones to maintain temporary power redundancy. Stakeholders must evaluate fuel pathway flexibility and emissions certification portability across jurisdictions before committing to multi-year fleet investments.
Market Dynamics
Fleet turnover toward lower-emission assets is compressing capital deployment timelines across the temporary power sector. Rental providers face simultaneous pressure from EPA Tier 4 Final mandates in the United States and equivalent MEE regulations in China, forcing accelerated obsolescence of legacy diesel generator sets.
Growth Catalysts
- Grid instability in industrial corridors:State-level mandates for uninterrupted power supply to manufacturing zones in India sustain procurement of temporary grid integration solutions for textile and automotive clusters.
- EPA Tier 4 Final compliance deadlines:Emissions standards in the United States are redirecting capital expenditure toward natural gas and hybrid-ready rental fleets ahead of enforcement dates.
- Hybrid system maturation:Battery-generator hybrid architectures are capturing share in noise-sensitive deployments including urban construction and outdoor event management.
Market Restraints
- Diesel engine supply concentration:Core powertrain sourcing remains concentrated among a limited set of European and Japanese engine manufacturers, exposing rental fleets to allocation risk.
- Natural gas infrastructure gaps:Pipeline availability constraints in sub-Saharan Africa and Southeast Asia limit fuel pathway flexibility for cleaner-burning temporary power assets.
- MEE certification portability:Chinese emissions certification lacks mutual recognition with EPA or EU Stage V standards, fragmenting fleet standardization for multinational operators.
Strategic Opportunities
- Telecommunications backup in rural India:Tower infrastructure operators seek diesel-reduction pathways through solar-hybrid rental contracts in grid-deficient states.
- EU Green Deal alignment:Hydrogen-ready generator set specifications are creating first-mover positioning for rental providers serving German and Dutch industrial zones.
- Remote monitoring convergence:Integration of IoT telemetry with predictive maintenance software is enabling subscription-based uptime monetization distinct from equipment rental.
Industry Challenges
- Certification timeline compression:Multi-jurisdiction emissions compliance requires simultaneous EPA, EU Stage V, and MEE homologation, straining technical documentation resources.
- Technician specialization gaps:Natural gas and hybrid system maintenance demands competencies distinct from legacy diesel repair, limiting field service scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temporary Power Market |
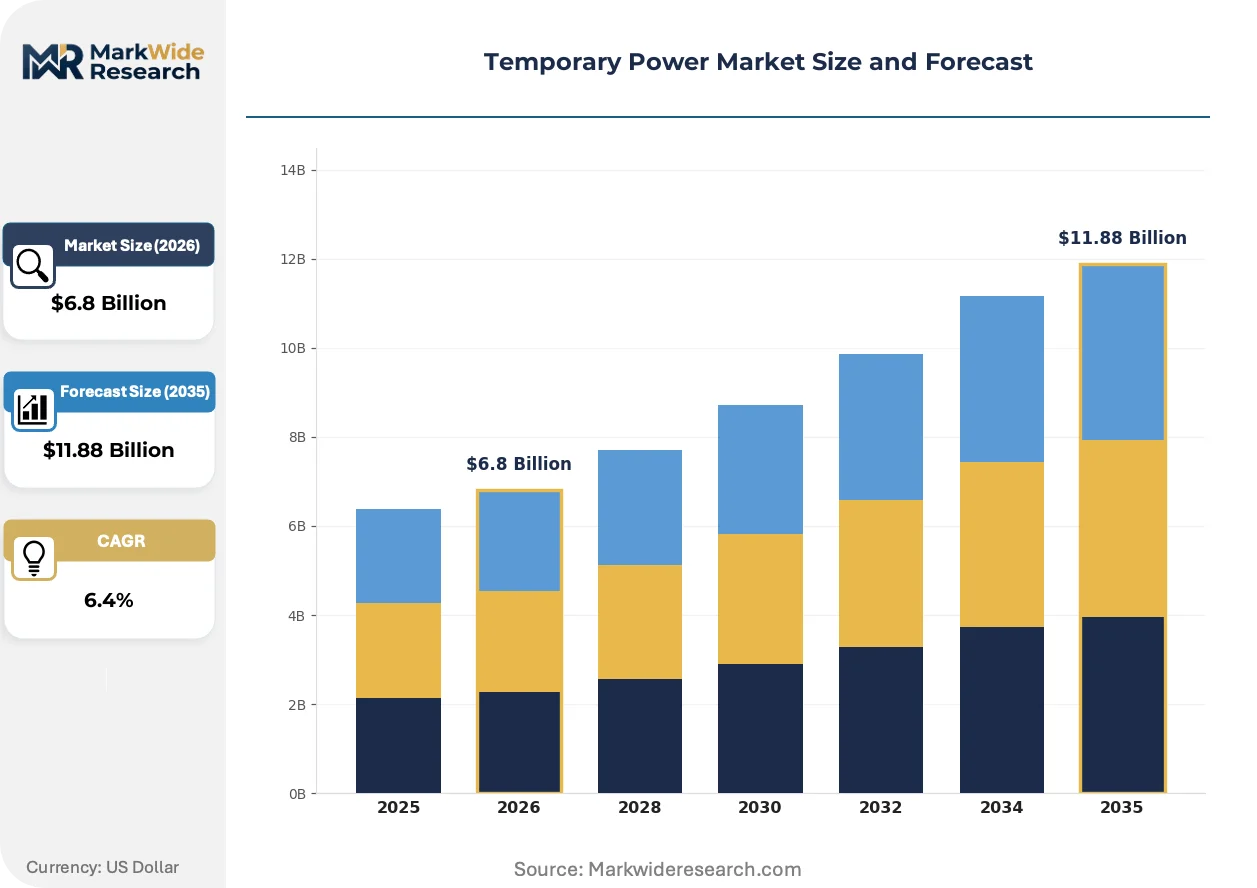
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
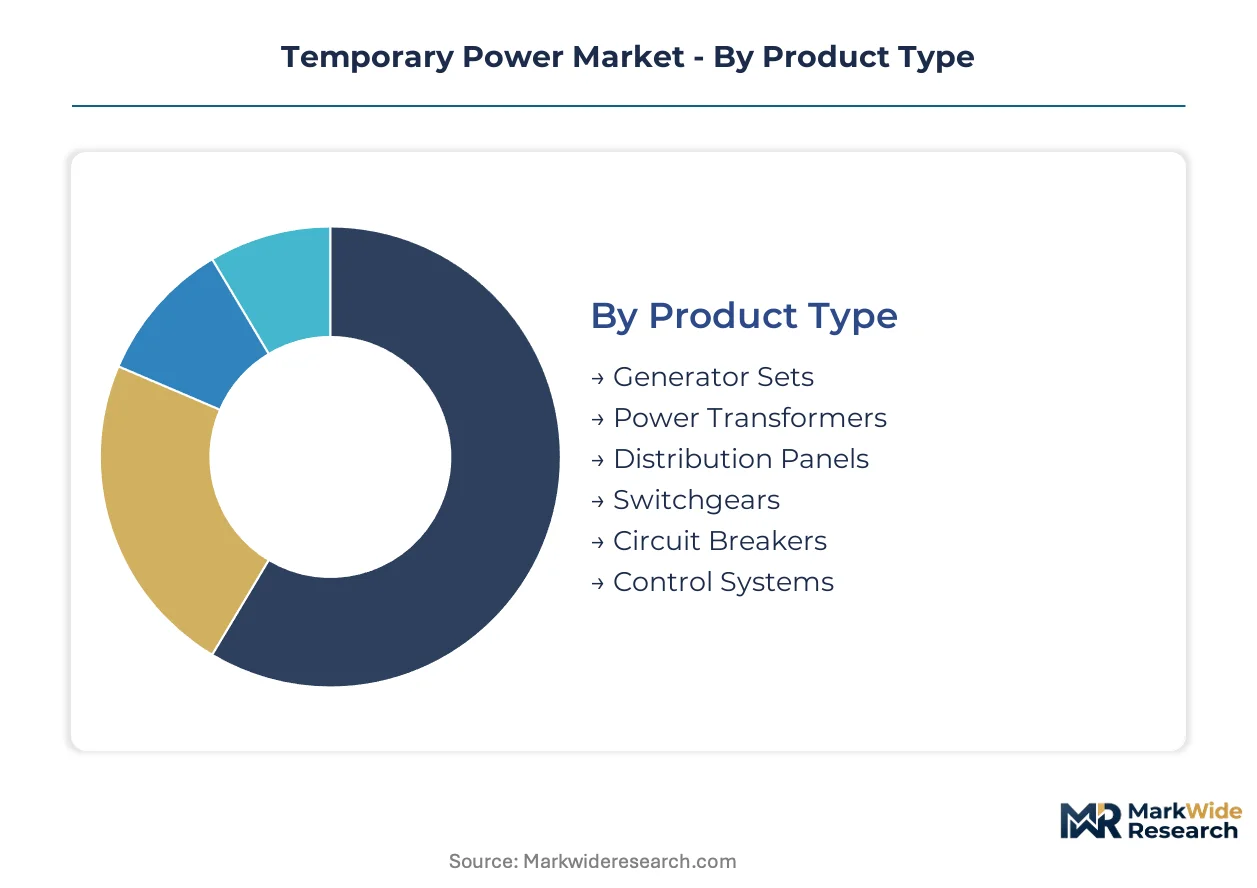
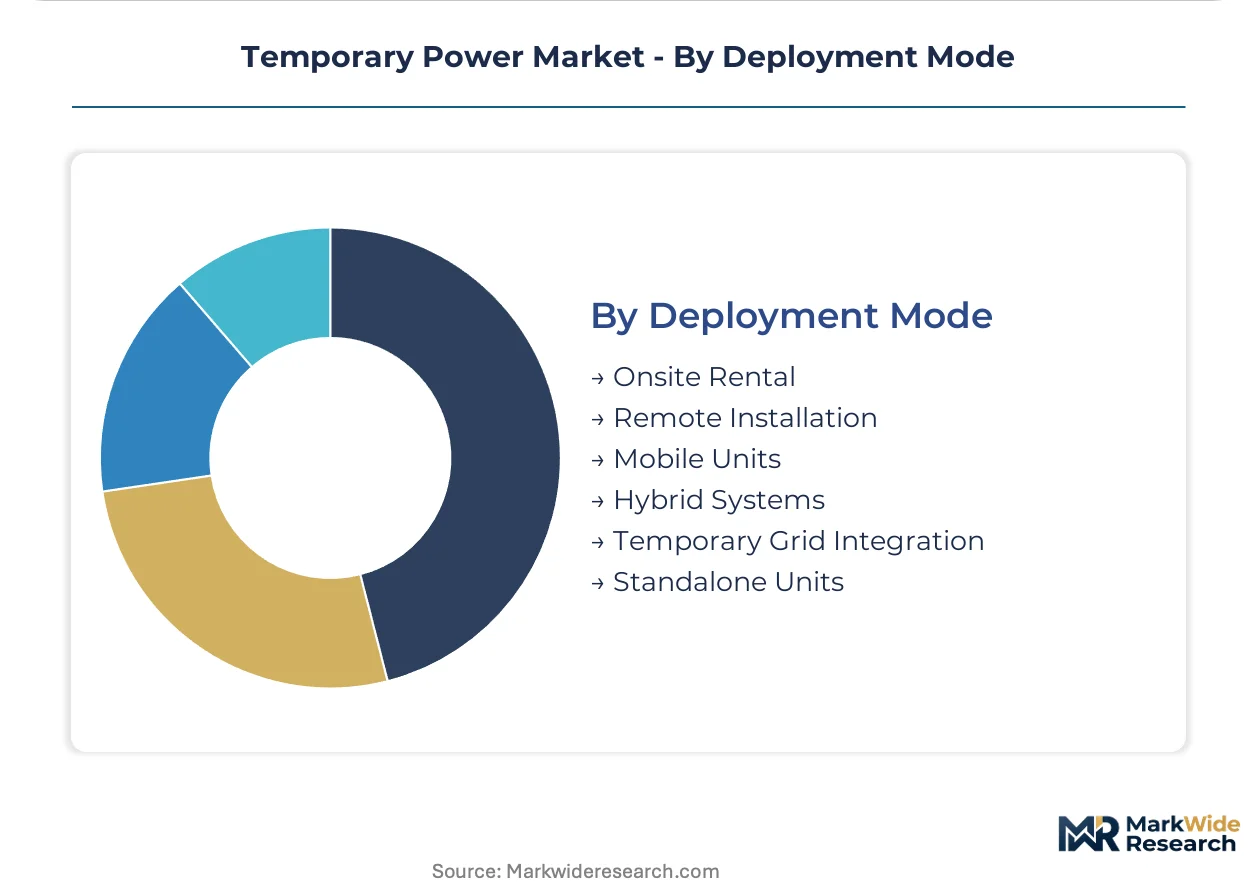
| Segmentation | Product Type: Generator Sets, Power Transformers, Distribution Panels, Switchgears, Circuit Breakers, Control Systems End User Industry: Construction Firms, Event Management, Mining Operations, Telecommunications Providers, Emergency Services, Film Production Units Fuel Type: Diesel, Natural Gas, Propane, Petrol, Biogas, Hydrogen Deployment Mode: Onsite Rental, Remote Installation, Mobile Units, Hybrid Systems, Temporary Grid Integration, Standalone Units |
| Companies Covered | APR Energy, Atlas Copco, Aggreko, Ashtead Group, Kohler, Caterpillar Inc., Cummins Inc., Generac Holdings, United Rentals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temporary Power Market Strategic Shifts & Innovations
Digitalization of fleet management is repositioning temporary power from commodity equipment rental toward outcome-based energy service contracts. Predictive analytics and remote diagnostics are compressing response times while enabling new pricing architectures.
Hybrid battery-diesel architectures are absorbing capital allocation previously directed toward pure diesel generator sets. Mining operators in Australia and Chile are piloting these systems for load-following applications where fuel reduction targets intersect with remote deployment requirements. The technology is absorbing margin pressure from emissions compliance costs by extending maintenance intervals and reducing fuel logistics burden.
EU Stage V non-road engine regulations are eliminating legacy diesel fleets from European rental pools. Equipment providers must now source powertrains meeting particulate and NOx limits that add cost and complexity to sub-300 kW units. Construction rental firms in Germany and France are responding through accelerated natural gas pilot programs and selective geographic fleet specialization.
Energy-as-a-service contracting is displacing traditional equipment rental in utility and industrial applications. Buyers in Brazil and South Africa now specify guaranteed availability metrics rather than generator set specifications, transferring operational risk to rental providers. This shift concentrates procurement authority among buyers with sophisticated load profiling capabilities and long-term site control.
Temporary Power Market Segmentation
Temporary power procurement decisions hinge on matching equipment specifications to site constraints, fuel availability, and duration requirements. Segmentation reveals where rental providers can capture premium pricing through specialized configurations versus competing on fleet scale.
Product Type:
Standardization dominates high-volume categories while engineered solutions command customization premiums across specialized applications.
- Generator Sets:Modular internal combustion or turbine-based units rated from 10 kW to 100 MW with rapid deployment skids. Mining operators in Australia and Chile absorb the largest rental volumes for remote extraction sites where grid extension proves uneconomical.
- Power Transformers:Oil-immersed or dry-type voltage conversion equipment stepping temporary generation to distribution levels. Indian industrial corridors sustain concentrated demand from textile and automotive clusters facing state-mandated backup power requirements.
- Distribution Panels:Enclosed busbar assemblies with circuit protection for secondary power distribution.
- Switchgears:Metal-clad assemblies housing disconnect switches, fuses, and circuit breakers for load isolation.
- Circuit Breakers:Automatic protection devices interrupting fault currents in temporary distribution networks.
- Control Systems:Programmable logic controllers and SCADA interfaces enabling remote monitoring and load optimization.
Leading the category by volume: Generator Sets. Expanding most quickly: Control Systems.
End User Industry:
Customer sophistication varies sharply — infrastructure operators prioritize uptime guarantees while event managers optimize for rapid mobilization.
- Construction Firms:General contractors and specialty trades requiring phased power for site development, vertical construction, and commissioning. Emerging economy builders in India and Brazil increasingly rely on rental fleets to avoid capital tie-up in owned equipment.
- Event Management:Concert promoters, sporting event organizers, and festival operators demanding noise-compliant, aesthetically neutral power solutions. Outdoor entertainment in European urban centers drives hybrid system adoption where diesel restrictions apply.
- Mining Operations:Surface and underground extraction companies with multi-year remote power requirements.
- Telecommunications Providers:Tower infrastructure operators seeking backup and off-grid solutions for rural coverage expansion.
- Emergency Services:Disaster response agencies requiring immediate deployment following grid failure.
- Film Production Units:Location shooting crews with mobile, quiet power for lighting and equipment.
Construction Firms anchor category revenue. Event Management climbs fastest on hybrid system penetration.
Fuel Type:
Emissions compliance timelines are fragmenting fuel choice across jurisdictions with divergent regulatory stringency.
- Diesel:Distillate fuel oil burned in compression-ignition engines with established logistics infrastructure. Legacy fleets retain dominance in sub-Saharan Africa and Southeast Asia where pipeline networks remain underdeveloped.
- Natural Gas:Methane-rich pipeline or compressed gas fueling spark-ignition or dual-fuel engines. US rental providers redirect capital toward gas-capable units ahead of EPA Tier 4 Final enforcement deadlines.
- Propane:Liquefied petroleum gas stored in portable cylinders for remote deployment.
- Petrol:Gasoline fueling smaller portable units below 50 kW output.
- Biogas:Anaerobic digestion-derived methane from agricultural or wastewater sources.
- Hydrogen:Fuel cell or combustion-based zero-carbon generation for pilot deployments.
Diesel retains installed base leadership. Natural Gas gains share fastest on regulatory pressure.
Deployment Mode:
Asset mobility requirements determine whether providers optimize for transport efficiency or integration depth.
- Onsite Rental:Equipment positioned at customer facilities for defined contract periods with full service inclusion. Brazilian and South African utilities now specify availability guarantees rather than equipment specifications, transferring operational risk to rental operators.
- Remote Installation:Hardwired temporary infrastructure requiring civil works and grid interconnection.
- Mobile Units:Trailer or skid-mounted equipment relocatable within hours. Australian mining contractors pilot battery-diesel hybrids for load-following where fuel reduction targets intersect with remote logistics constraints.
- Hybrid Systems:Battery-generator combinations reducing fuel consumption and noise emissions.
- Temporary Grid Integration:Synchronized parallel operation with utility infrastructure for peak shaving or backup.
- Standalone Units:Islanded operation without utility interconnection for complete grid independence.
Onsite Rental dominates contract value. Hybrid Systems steepen fastest on emissions compliance cost absorption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing concentrates in Germany, the United States, and Japan, while deployment demand clusters in India's industrial corridors, Australia's mining regions, and Brazil's utility markets. This production-consumption divide shapes fleet logistics and regional service capabilities.
United States
Utility-scale renewable integration and data center construction sustain demand for grid-stabilizing temporary power. EPA Tier 4 Final deadlines are forcing rental providers to retire legacy diesel fleets ahead of enforcement dates. Texas and California industrial zones absorb the largest rental volumes for oilfield services and technology campus development.
India
State-level mandates for uninterrupted power supply to manufacturing zones drive procurement across textile and automotive clusters. Central Electricity Authority grid connectivity codes compel backup redundancy in designated industrial areas. Gujarat and Maharashtra industrial corridors sustain concentrated demand for temporary grid integration solutions.
Germany
EU Stage V non-road engine regulations are eliminating legacy diesel equipment from rental pools. EU Green Deal alignment is creating first-mover positioning for hydrogen-ready generator specifications. The Ruhr industrial region and Bavarian manufacturing zones are piloting natural gas and hybrid systems for construction and event applications.
Australia
Remote mining operations with multi-year power requirements anchor demand for mobile and hybrid deployment modes. Load-following battery-diesel architectures are capturing share where fuel reduction targets intersect with remote logistics constraints. Western Australian and Queensland mining belts sustain the deepest rental contract values.
Brazil
Utility and industrial buyers now specify guaranteed availability metrics rather than equipment specifications, transferring operational risk to rental providers. Grid instability in southeastern industrial states sustains procurement for manufacturing backup. São Paulo state utilities are advancing energy-as-a-service contracting models.
Temporary Power Market Key Industry Players
Top-tier vendors anchor multinational fleet scale, while regional specialists compete on local service density and fuel pathway flexibility. The market structures around three tiers: integrated equipment manufacturers with captive rental arms, independent rental specialists with digital fleet platforms, and regional contractors serving single-country markets. Dominant competitive moves include portfolio diversification into hybrid systems and strategic partnerships with telecommunications and mining operators for long-term site contracts.
Among integrated equipment manufacturers, Caterpillar Inc. and Cummins Inc. exemplify the captive technology-development archetype, while Aggreko represents the independent rental specialist model with digital fleet management capabilities. These three companies occupy distinct competitive positions: equipment manufacturers leverage in-house engine development and manufacturing scale, while rental specialists monetize uptime through predictive maintenance subscriptions and utility partnerships.
| Leading Market Players |
|---|
| APR Energy |
| Atlas Copco |
| Aggreko |
| Ashtead Group |
| Kohler |
| Caterpillar Inc. |
| Cummins Inc. |
| Generac Holdings |
| United Rentals |
| Others |
Cost & Logistics Intelligence
Hybrid system maturation across temporary power fleets is simultaneously compressing equipment cost curves and concentrating procurement leverage among integrated manufacturers with captive battery supply. This dual shift rewards rental providers that secured long-term cell supply agreements ahead of EPA Tier 4 Final enforcement deadlines.
Pricing Analysis
Margin tightening in diesel generator rental traces to Tier 4 Final compliance costs and accelerated fleet obsolescence timelines. Three-tier pricing structure across premium hybrid, standard gas-capable, and economy diesel tiers differentiates on emissions certification grade and remote monitoring bundling. Cost compression in the diesel tier intensifies because Chinese engine manufacturers are capturing share with MEE-certified units priced below European equivalents. Construction firms in emerging economies exhibit highest price sensitivity, while mining operators in Australia absorb premium hybrid rates for fuel logistics savings.
Supply Chain Analysis
Technician specialization gaps in natural gas and hybrid system maintenance are constraining service network expansion in Germany, the United States, and Japan where manufacturing concentrates. Core powertrain sourcing draws from Cummins, Caterpillar, and a limited set of European and Japanese engine specialists, exposing fleets to allocation risk during emissions transition surges. Single-source vulnerability sits with lithium-ion cell supply for hybrid architectures, which feeds from concentrated Asian production. Distribution runs through regional rental hubs with OEM-direct service contracts for mining and utility accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Temporary power markets are supply-constrained by certified technician availability, which props pricing for hybrid and natural gas service contracts above historical diesel-equipment rates.
For Market Incumbents: Acquire specialized natural gas and hybrid service capabilities through technician training partnerships or regional service firm purchases. Consolidate backward integration into battery energy storage systems to secure cell allocation ahead of competing rental providers. Defensive positioning against emerging digital-native fleet platforms requires anchoring long-term utility partnerships with guaranteed availability metrics rather than equipment specifications alone.
For New Entrants and Emerging Players: Telecommunications tower operators in rural India represent the most penetrable white-space target, with diesel-reduction mandates creating procurement urgency for solar-hybrid rental contracts. Solar EPC contractors seeking downstream revenue expansion offer established channel access for temporary power-as-a-service positioning. A narrow geographic focus on grid-deficient Indian states with state-level industrial backup mandates enables faster service network amortization than fragmented national expansion.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated equipment manufacturers seeking digital fleet management capabilities and utility contract books. Long-term viability across the projection horizon favors rental specialists with hydrogen-ready generator specifications aligned to EU Green Deal trajectories. The signal to watch is German and Dutch industrial zone pilot program conversion rates from natural gas to hydrogen combustion, which would trigger accelerated capital reallocation across European rental fleets.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Fleet Conversion | Absorbs EPA Tier 4 Final compliance costs while extending maintenance intervals for mining operators in remote Australian basins. |
| Natural Gas Capacity Expansion | Positions rental providers ahead of US enforcement deadlines with pipeline-connected assets in Texas and California industrial zones. |
| Predictive Maintenance Platform Deployment | Enables subscription-based uptime monetization distinct from equipment rental through Aggreko-style utility partnerships. |
| Hydrogen-Ready Generator Specification | Creates first-mover positioning for EU Green Deal alignment in German and Dutch industrial corridor pilots. |
| Telecommunications Tower Service Contracts | Captures diesel-reduction procurement from tower operators expanding rural coverage across grid-deficient Indian states. |
Research Approach
Document review covered SEC filings from Caterpillar and Cummins, EIA power market data, and EU Stage V regulatory documentation, complemented by interviews with fleet managers at Aggreko and regional rental specialists. Primary fieldwork engaged utility planning officers, mining procurement directors, telecommunications infrastructure operators, and construction project managers across India, Brazil, and Australia. Secondary validation drew from customs trade data on generator set imports, FERC interconnection queue filings, and CEA grid connectivity code notifications. Bottom-up equipment deployment estimates triangulated against top-down market sizing from energy service contract disclosures.
Cross-referencing historical fleet turnover patterns with panel input from rental provider executives anchored the analytical framework across the projection horizon. Segmentation modeling incorporated fuel type, deployment mode, end-user industry, and regional regulatory cluster dimensions. CAGRs were derived from equipment replacement cycle compression and emissions compliance deadline impacts rather than extrapolated trend lines. Industry-specific forecast inputs included state-level industrial backup mandate expansion rates in India and EU Green Deal hydrogen pilot program commitments.
Caveats apply where MEE certification portability failures or lithium-ion supply disruptions could materially shift the outlook for hybrid system penetration. Forecasts reflect assumptions about technician training pipeline expansion and natural gas infrastructure buildout in sub-Saharan Africa. A small set of triggers—EPA enforcement delay, EU hydrogen combustion standard revision, and Indian state mandate expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy & Power
Single-Phase Microinverter Market
Energy & Power
Box Solar Cookers Market
Energy & Power
North America Oil and Gas Electric Submersible Pump Market
Energy & Power
Hybrid Valve Market
Energy & Power
Middle-East Solar Power Market
Energy & Power
Oil and Gas Pipe Market
Energy & Power
Surge Tank Market
Energy & Power
Wind Turbine Alternator Market
Energy & Power
Fuel Cells for Marine Vessels Market
Energy & Power
Process Gas Compressors Market
Energy & Power
Ocean Thermal Energy Conversion Plant Market
Energy & Power
EV Batteries Market
Energy & Power
Hybrid Solar Wind System Market
Energy & Power
South America LNG Bunkering Market
Energy & Power
PV Water Heater Market
Energy & Power
North America Coiled Tubing Services Market